
 Shop Shelving Market | 2026-2036
Shop Shelving Market Size, Share, and Industry Trends Forecast 2026-2036
Shop Shelving Market Analytics
The gap between premium and commodity shop shelving is shifting from simple material grade to integrated digital capability and custom configurability. Lozier leverages its manufacturing scale to dominate North American big-box retail fixtures with high-volume steel systems. Madix differentiates through specialized wire shelving and security product lines that anchor its position in loss-prevention segments.
Shop shelving comprises freestanding or wall-mounted storage structures fabricated from steel, aluminum, wood composites, or engineered polymers, typically rated for load capacities between 200 and 2,000 pounds per shelf level depending on gauge and reinforcement. These systems serve the primary commercial purpose of merchandise display, inventory organization, and spatial optimization across retail and logistics environments. Metal shelving leads in absolute volume due to durability requirements in supermarkets and distribution centers, while modular design is gaining fastest as retailers demand rapid reconfiguration for seasonal layouts. Wire shelving commands premium positioning in food retail applications where ventilation and sanitation standards elevate product specifications.
FDA food-contact surface regulations and OSHA workplace safety standards shape material selection and load-rating certifications for shelving deployed in US grocery and warehouse environments. The EU's RoHS directives and REACH chemical restrictions constrain coating and finish options for products entering European retail supply chains. Stakeholders must monitor evolving building codes and sustainability disclosure requirements as jurisdictions tighten embodied-carbon tracking for commercial fixtures.
Market Dynamics
Modular shelving systems are displacing fixed fixtures as retailers prioritize rapid reconfiguration for seasonal layouts and omnichannel fulfillment integration.
Growth Catalysts
- EU Green Deal material standards:These mandates accelerate demand for low-carbon steel and recyclable aluminum shelving systems across European retail supply chains.
- China retail infrastructure modernization:Tier-one and tier-two cities are deploying high-density shelving to optimize floor space in expanding supermarket networks.
- Wire shelving ventilation properties:FDA food-contact surface regulations elevate specifications for food retail applications where sanitation standards drive premium product adoption.
Market Restraints
- Steel tariff volatility:United States tariff adjustments create input cost uncertainty for domestic manufacturers dependent on imported raw materials.
- REACH chemical restrictions:These EU directives constrain coating and finish options, limiting supplier flexibility for products entering European markets.
- Engineered polymer substitution:Lightweight composite materials threaten metal shelving dominance in low-load retail environments.
Strategic Opportunities
- India retail formalization:Organized retail expansion in secondary cities creates demand for standardized shelving systems as modern trade penetrates beyond metros.
- OSHA workplace safety standards:Stricter load-rating certification requirements in US warehouse environments open premium positioning for certified heavy-duty systems.
- Digital inventory integration:Convergence of RFID tagging and modular shelving enables real-time stock tracking for omnichannel retailers.
Industry Challenges
- Embodied-carbon certification timelines:Evolving sustainability disclosure requirements across jurisdictions complicate product qualification and market entry.
- Welding automation skill gaps:Steel shelving manufacturers face shortages of technicians capable of operating precision fabrication equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shop Shelving Market |
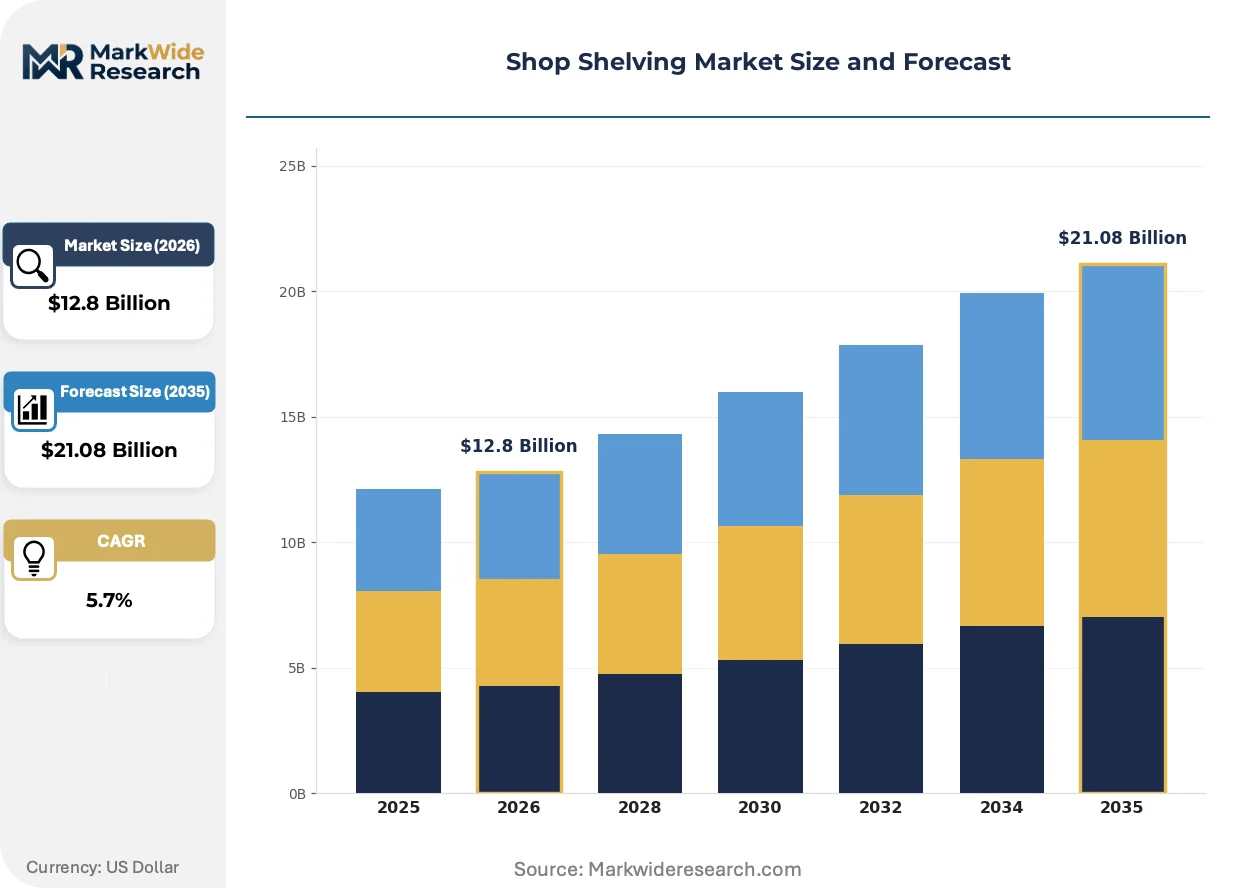
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Shelving, Wood Shelving, Plastic Shelving, Wire Shelving Application: Retail Stores, Supermarkets, Warehouses, Showrooms End User: Small Retailers, Large Retailers, E-commerce Businesses, Distribution Centers Design: Modular, Fixed, Mobile, Floating |
| Companies Covered | Lozier, Madix, Artitalia Group, Streater, Trion Industries, LA Darling, Gondella, CAEM, Storflex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shop Shelving Market Evolving Landscape
Retail fixture design is pivoting from static storage to adaptive infrastructure that supports rapid layout transformation and data-driven merchandising.
Light-gauge cold-rolled steel with powder-coated finishes is rewriting durability expectations for mid-market supermarket shelving. Mass merchandisers in the United States are specifying these systems for five-year replacement cycles rather than traditional ten-year horizons. This compression is enabling faster technology refresh and reducing total cost of ownership calculations.
REACH compliance deadlines are forcing coating suppliers to eliminate hexavalent chromium and specific phthalates from pretreatment processes. European shelving manufacturers are reformulating surface treatments to maintain corrosion resistance under stricter chemical restrictions. Food retail segments in Germany and France are accelerating qualification of compliant systems ahead of enforcement phases.
Buyer concentration among omnichannel grocery operators is compressing specification cycles and demanding vendor-managed inventory programs. Traditional distributor networks are losing share to direct procurement relationships with national retail chains. This consolidation is most visible in US and UK markets where top-five grocers control expanding shelf space allocation authority.
Shop Shelving Market Segmentation
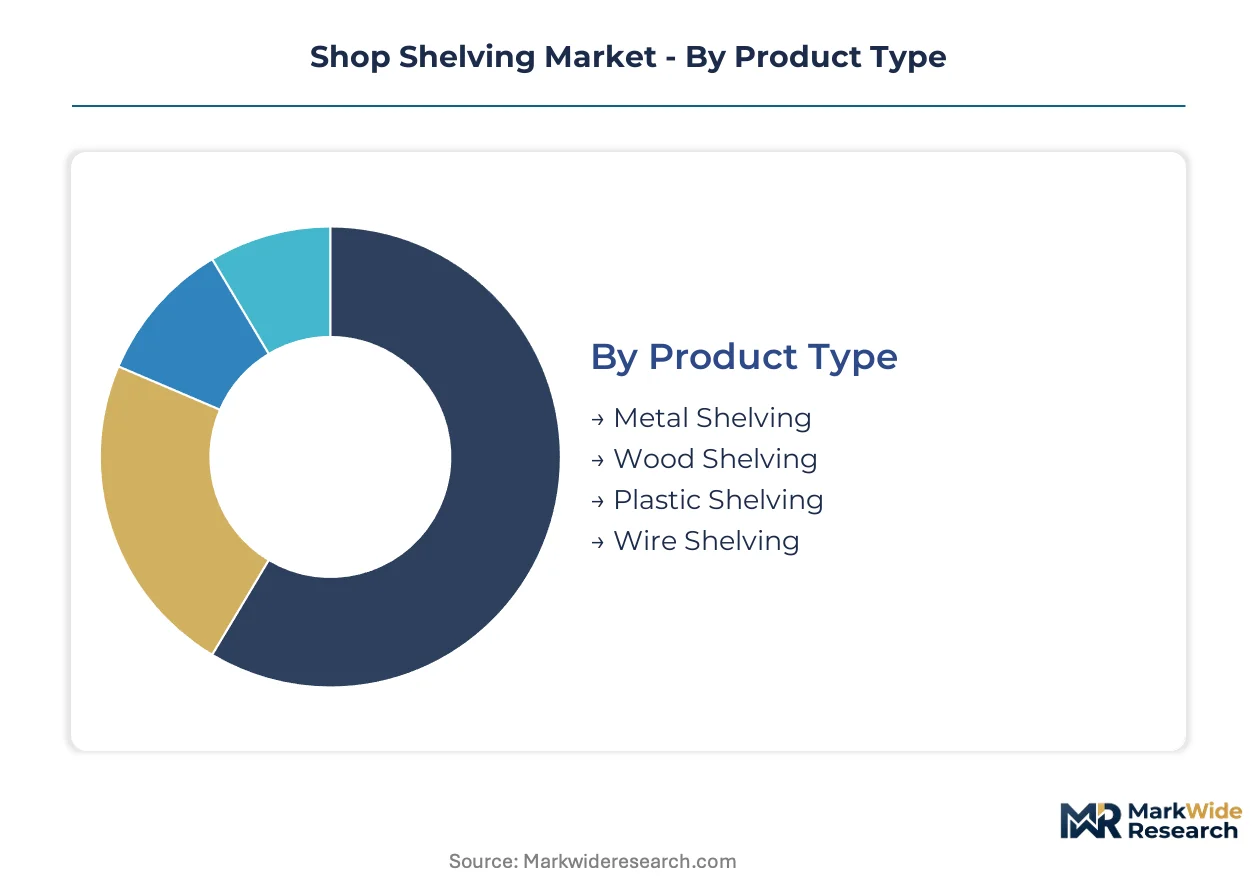
Segmentation in shop shelving reveals divergent capital requirements and margin profiles across materials, applications, and design architectures. Retailers prioritize load capacity, reconfiguration speed, and compliance certifications when matching shelving systems to operational environments.
Product Type:
Capital intensity varies sharply by raw material processing and fabrication complexity, with metal systems demanding the heaviest upfront tooling investment.
- Metal Shelving:Cold-rolled steel and aluminum structures rated for 500-2,000 pound loads per shelf level dominate supermarket and warehouse deployments. Chinese steel mills supply the bulk of raw stock for global fabrication networks, though EU Green Deal carbon-border adjustments are reshaping sourcing economics for European-bound finished goods.
- Wire Shelving:Chromium-plated or epoxy-coated steel wire configurations offer ventilation and drainage properties critical for FDA food-contact compliance in grocery cold storage. Premium positioning in North American food retail reflects sanitation-driven specification upgrades and loss-prevention integration.
- Wood Shelving:Engineered composites and solid hardwood systems serve boutique retail and showroom aesthetics where visual warmth overrides durability metrics. Lower capital barriers enable regional craft producers to compete against scaled metal fabricators.
- Plastic Shelving:Injection-molded polypropylene and high-density polyethylene units target light-load environments with corrosion resistance and color customization. E-commerce fulfillment centers specify these for rapid deployment in climate-controlled zones.
Metal shelving absorbs the bulk of installed capacity; wire shelving is expanding most quickly.
Application:
Volume concentration tracks the square footage expansion of organized retail and logistics infrastructure across development corridors.
- Supermarkets:High-density gondola and wall systems optimize product facings per linear foot in grocery environments. Tier-one and tier-two Chinese cities are deploying standardized fixtures as domestic retail chains consolidate store formats.
- Warehouses:Pallet-rack and cantilever configurations support bulk storage and pick-and-pack fulfillment operations. OSHA load-rating certification requirements in US distribution centers are elevating specification thresholds for heavy-duty systems.
- Retail Stores:Freestanding and perimeter fixtures balance merchandise density with traffic flow in general merchandise and specialty formats. Modular designs enable seasonal reconfiguration without full fixture replacement.
- Showrooms:Custom architectural systems emphasize brand presentation over inventory density in automotive, furniture, and luxury goods environments. Project-based procurement cycles differ sharply from standard retail replenishment patterns.
Supermarket applications command the largest share of current deployment; warehouse specifications are climbing the fastest.
End User:
Procurement sophistication scales with operational scale, creating tiered vendor relationships between mass retailers and fragmented small-format operators.
- Large Retailers:National chains leverage direct manufacturer relationships and vendor-managed inventory programs to compress specification cycles. Buyer concentration among top-five US and UK grocers is consolidating shelf space allocation authority.
- Distribution Centers:Third-party logistics operators specify standardized racking systems across multi-tenant facilities to maximize flexibility. Real-time inventory tracking integration is becoming a baseline requirement.
- E-commerce Businesses:Pure-play online retailers prioritize rapid-deployment modular systems in fulfillment nodes. Last-mile proximity requirements are driving shelving investment into secondary logistics corridors.
- Small Retailers:Independent operators rely on distributor networks for lower-volume procurement with higher per-unit costs. Financing constraints limit access to premium certified systems.
Large retailers absorb the bulk of installed capacity; e-commerce businesses are gaining share fastest.
Design:
Engineering trade-offs between stability, adaptability, and mobility define competitive positioning across design architectures.
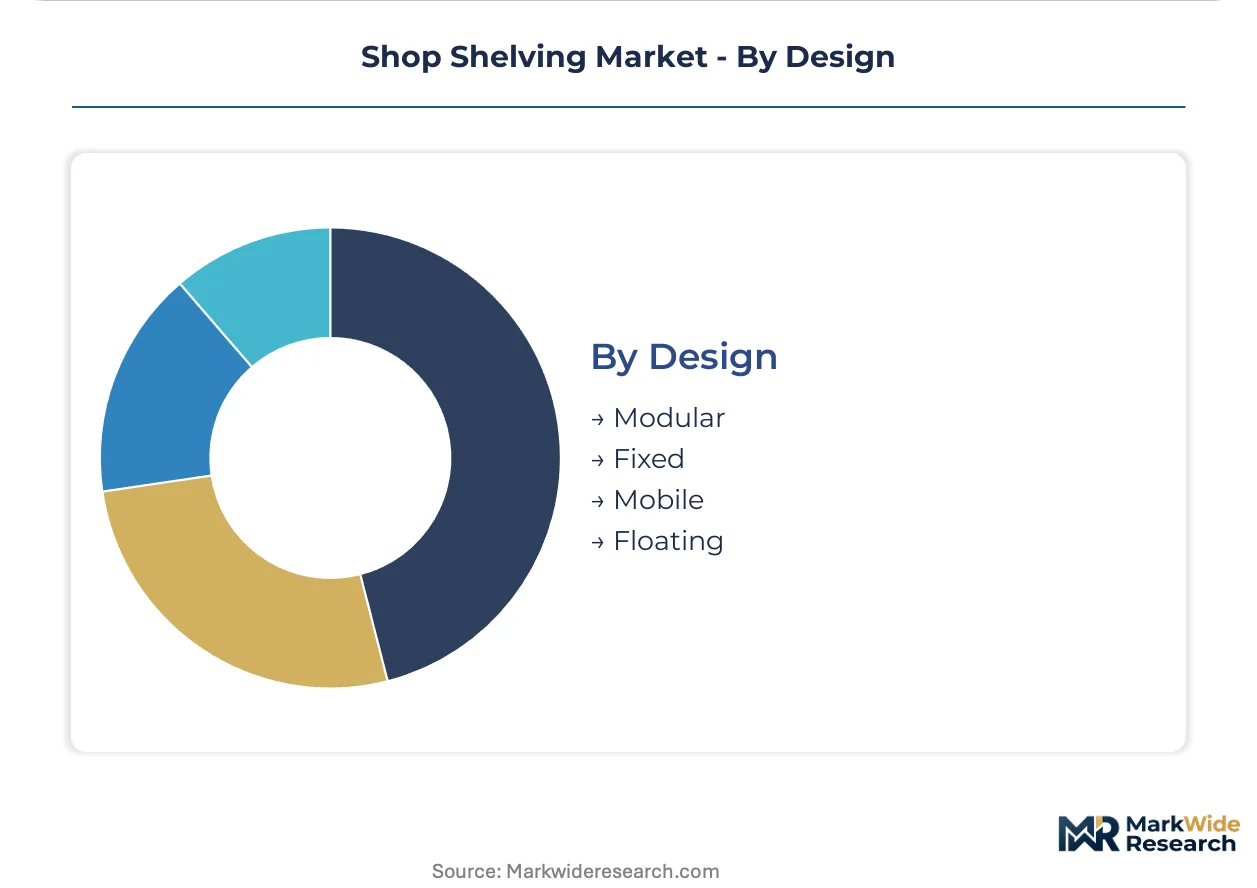
- Modular:Boltless or clip-together components enable tool-free reconfiguration for seasonal layouts and category resets. Mass merchandisers in the United States are specifying five-year replacement cycles to accelerate technology refresh.
- Fixed:Permanently anchored systems maximize load capacity and seismic stability in high-bay warehouse environments. Longer depreciation horizons suit capital-constrained operators with predictable inventory profiles.
- Mobile:Track-mounted or caster-equipped units optimize space utilization in back-of-house storage and temporary retail installations. Compact footprints serve urban store formats with premium square footage costs.
- Floating:Wall-anchored cantilever designs create visual levitation effects in showroom and boutique applications. Structural engineering requirements limit load ratings compared to floor-supported alternatives.
Modular designs absorb the bulk of installed capacity; mobile configurations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors the world's largest shop shelving procurement volume as Chinese supermarket chains execute format standardization across tier-one and tier-two cities. Domestic steel fabrication clusters in Jiangsu and Zhejiang provinces feed regional distribution networks with compressed lead times.
United States
Big-box retailers in the Midwest and Southeast are consolidating vendor relationships for gondola and pallet-rack systems. OSHA workplace safety standards elevate specification thresholds for warehouse shelving in distribution corridors. Chicago and Dallas-Fort Worth logistics hubs drive demand for heavy-duty certified systems supporting e-commerce fulfillment density.
Germany
Food retailers across Bavaria and North Rhine-Westphalia are accelerating REACH-compliant coating qualifications ahead of enforcement deadlines. EU Green Deal carbon-border adjustments reshape sourcing economics for steel-intensive fixtures. Stuttgart's automotive showroom cluster sustains demand for custom architectural floating systems.
India
Organized retail expansion in Maharashtra and Gujarat creates demand for standardized modular shelving as modern trade penetrates secondary cities. BIS certification requirements constrain import channels for foreign manufacturers. Mumbai-Pune industrial corridor hosts emerging domestic fabrication capacity serving western India supermarket networks.
Japan
Convenience store operators in Kanto and Kansai regions specify compact mobile shelving for urban formats with premium square footage costs. METI energy efficiency guidelines influence material selection for climate-controlled retail environments. Osaka-based logistics real estate developers are deploying high-density racking in automated fulfillment nodes.
Shop Shelving Market Competitive Landscape
Premium-margin players sit above commodity-margin players across digital integration and custom configurability capabilities. The market structures around three tiers: multinational fixture conglomerates with direct retail relationships, regional metal fabricators serving distributor networks, and specialized wire shelving producers targeting loss-prevention segments. Consolidation pressure concentrates among mid-scale manufacturers as buyer power aggregates at national grocery chains. Dominant competitive moves include vendor-managed inventory program adoption and five-year replacement cycle contracting to accelerate technology refresh.
Within the scale-driven tier, Lozier and Madix exemplify divergent specialization strategies. Lozier occupies a position among North American big-box retail fixture suppliers leveraging high-volume steel system production. Madix represents the wire shelving specialist archetype with positioning in food retail ventilation and security product lines. Artitalia Group sits within the European custom architectural segment serving showroom and boutique environments where visual presentation overrides inventory density metrics.
| Leading Market Players |
|---|
| Lozier |
| Madix |
| Artitalia Group |
| Streater |
| Trion Industries |
| LA Darling |
| Gondella |
| CAEM |
| Storflex |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up metal fabrication specialists have consolidated tier-two and tier-three producers across the US Midwest and Jiangsu province, tightening supply discipline while compressing margin pools for undifferentiated commodity shelving. This ownership concentration enables coordinated capacity management but exposes pricing power to raw material tariff volatility and carbon-border adjustment timelines.
Pricing Analysis
Outcome-based pricing anchored to load-capacity certification and OSHA compliance tier dominates heavy-duty warehouse segments, with three-tier pricing structure across premium, standard, and economy levels separating certified systems from uncertified imports. Price differentiation rests on steel gauge grade and powder-coat finish durability, with FDA food-contact compliance commanding 15-25% premiums in grocery applications. Cost compression in standard-grade gondola systems is intensifying because Chinese mill oversupply and US tariff uncertainty squeeze fabricator margins. Small independent retailers exhibit highest price sensitivity due to financing constraints, while national grocery chains leverage volume scale for vendor-managed inventory discounts.
Supply Chain Analysis
Direct-to-retail procurement channels handle hyperscale buyer demand from top-five US and UK grocers, bypassing traditional distributor markups. Raw material supply draws from Chinese steel mills in Hebei and Jiangsu provinces, Indian flat-rolled steel producers in Maharashtra, and EU-based low-carbon aluminum smelters in Norway and Iceland. Cold-rolled steel coil, zinc-aluminum coating substrates, and REACH-compliant epoxy powder constitute critical input dependencies. Single-source vulnerability concentrates in Chinese steel supply for global fabrication networks, with EU carbon-border adjustments threatening cost pass-through capabilities. Distribution runs through regional metal service centers for mid-market buyers and direct mill relationships for volume purchasers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a consolidation play driven by buyer concentration among national grocery chains forcing sub-scale fabricators into distressed exits or acquisition targets.
For Market Incumbents: Lock in five-year replacement cycle contracts with top-tier grocers to accelerate technology refresh and foreclose competitor access. Pursue backward integration into cold-rolled steel coil processing to neutralize tariff exposure and secure margin control. Threats include engineered polymer substitution in light-load environments and REACH compliance cost escalation for coating suppliers. For New Entrants and Emerging Players: Launch via specialized wire shelving for food retail ventilation segments where FDA compliance barriers deter commodity competitors. Target India's secondary cities where BIS certification requirements constrain import channels and domestic fabrication capacity remains underdeveloped. White-space opportunities sit in RFID-integrated modular systems for omnichannel fulfillment and mobile shelving for Japan's compact urban convenience formats. For Investors and Strategic Acquirers: Distressed-cycle entries favor EU-based coating specialists with REACH-compliant formulation capabilities ahead of enforcement deadlines. Long-term viability favors vertically integrated producers with captive steel supply and direct retail relationships over distributor-dependent mid-caps. Monitor EU carbon-border adjustment implementation timelines as inflection indicator for sourcing economics restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Coil Processing | Captive supply from Hebei or Jiangsu mills neutralizes US tariff volatility and secures margin control. |
| REACH-Compliant Coating Certification | ECHA-compliant surface treatments unlock German and French food retail procurement ahead of enforcement. |
| RFID-Enabled Modular System Launch | Real-time inventory tracking integration addresses omnichannel grocer requirements in US distribution corridors. |
| Vendor-Managed Inventory Program Adoption | Direct relationships with national chains compress specification cycles and displace distributor networks. |
| India Domestic Fabrication Capacity Buildout | Mumbai-Pune corridor proximity serves western India supermarket expansion under BIS certification constraints. |
Research Methodology
Document review covered customs and trade flow databases, EU ECHA regulatory filings, and SEC 10-K disclosures from listed retail fixture suppliers, complemented by interviews with supermarket procurement directors, warehouse operations managers, metal fabrication plant engineers, and coating supplier technical leads. Primary fieldwork across tier-one Chinese cities, US Midwest distribution corridors, and German food retail clusters validated secondary estimates. Bottom-up unit economics triangulated against top-down retail construction spending models.
Market sizing and growth projections incorporate product type, application environment, end-user scale tier, and design architecture segmentation across the analysis window. CAGRs derive from regression analysis of historical retail floor space expansion, steel price elasticity coefficients, and regulatory compliance cost trajectories. Forecast inputs include supermarket format standardization rates in China, OSHA certification adoption curves in US warehousing, and EU carbon-border adjustment phase-in schedules.
Steel tariff volatility, REACH enforcement timeline shifts, and engineered polymer substitution acceleration are the dominant revision risks to base-case projections. Forecasts reflect documented assumptions regarding retail construction cycles and regulatory implementation schedules. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Storage and Organization
Toy Storage Market
Home Storage and Organization
Kitchen Storage Market
Home Storage and Organization
Display Cabinets Market
Home Storage and Organization
Flush Mount Photo Album Market
Home Storage and Organization
Shoe Storage and Organizers Market
Home Storage and Organization
Hong Kong Self-Storage Market
Home Storage and Organization
Smart Shoe Cabinet Market
Home Storage and Organization
Shoe Rack Market
Home Storage and Organization
Collapsible Wardrobe Market
Home Storage and Organization
Jewelry Organizer Market
Home Storage and Organization
United States Home Organizers and Storage Market
Home Storage and Organization
Europe Home Organizers and Storage Market
Home Storage and Organization
Regency Shelving Market
Home Storage and Organization
Small Space Furniture Market
Home Storage and Organization
Flatware Holders and Organizers Market
Home Storage and Organization
Kitchen Storage Organization Market