
 Shoe Storage and Organizers Market | 2026-2036
Shoe Storage and Organizers Market Size, Share, and Industry Trends Forecast 2026-2036
Shoe Storage and Organizers Market Analytics
Premium-grade modular systems is reorganizing how consumers allocate closet renovation budgets. The Container Store leverages its specialty retail footprint to control high-margin custom installations. IKEA anchors mass-market penetration through flat-pack logistics and in-store room displays. SONGMICS competes aggressively online with direct-to-consumer pricing on fabric and plastic organizers.
Shoe storage and organizers comprise engineered enclosures, vertical racks, and compartmentalized containers designed to protect footwear from deformation, moisture, and dust while maximizing spatial efficiency. Manufacturing employs injection-molded polypropylene for stackable bins, powder-coated steel for multi-tiered frames, and FSC-certified particleboard for finished shelving units, with load ratings typically spanning fifteen to fifty pounds per shelf. The primary commercial purpose centers on inventory management for retail backrooms and residential space reclamation in square-footage-constrained dwellings. Racks and organizers command the largest revenue share due to repeat purchase frequency and cross-selling potential, while wall-mounted designs represent the fastest-expanding margin pool as contractors integrate storage into new construction specifications. Plastic dominates unit volume for entry-level price points, though metal fabrication captures superior per-unit economics in commercial and premium residential channels.
EPA guidelines on formaldehyde emissions in composite wood products shape material sourcing decisions for domestic manufacturers, while ISO 9001 quality management standards govern production consistency among export-oriented suppliers. The EU's REACH regulation restricts certain phthalates in plastic formulations, directly affecting polymer selection for boxes and bins sold in European markets. California's Proposition 65 labeling requirements create compliance friction for imported goods lacking transparent supply chain documentation. Stakeholders must monitor evolving extended producer responsibility frameworks for furniture and homeware, as these programs threaten to add end-of-life collection costs to current pricing models.
Market Dynamics
California's Title 24 building efficiency standards are compressing installation timelines for space-optimized storage systems in new multi-family construction, forcing manufacturers to pre-certify wall-mounted configurations before project bidding.
Growth Catalysts
- REACH phthalate restrictions:The EU's chemical safety framework is accelerating polymer reformulation toward bio-based alternatives, opening premium positioning for compliant manufacturers.
- Injection-molded polypropylene advances:Stackable bin production now achieves 40% faster cycle times through automated tooling, reducing per-unit labor content for mass-market SKUs.
- China tier-one city density:Shanghai and Beijing apartment dwellers under 45 square meters are driving wall-mounted system adoption as primary footwear display infrastructure.
Market Restraints
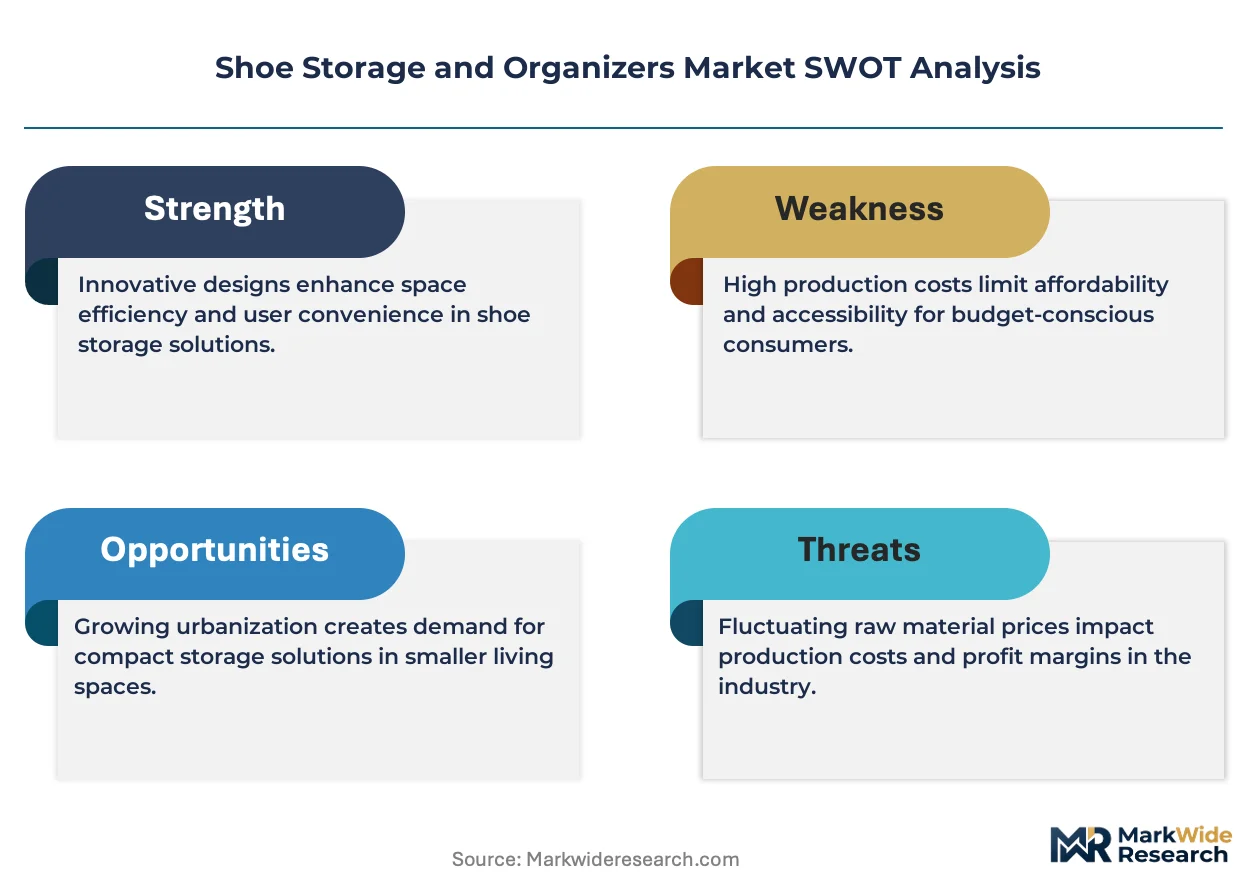
- FSC-certified particleboard cost volatility:Sustained pressure on certified wood fiber supplies from Baltic and Southeast Asian sources is squeezing margin on finished shelving units.
- Proposition 65 documentation gaps:California's labeling requirements create customs hold risks for Asian imports lacking transparent supply chain disclosure, particularly for composite wood adhesives.
- Steel tariff exposure:Powder-coated multi-tiered frames face input cost instability from Section 232 and 301 trade measures affecting coil steel sourcing.
Strategic Opportunities
- Extended producer responsibility frameworks:Emerging EU and state-level furniture take-back mandates will favor domestic producers with established reverse logistics infrastructure.
- Smart home integration:RFID-enabled inventory tracking and humidity-sensing enclosures represent convergence between IoT sensor platforms and traditional storage hardware.
- India urban housing stock:Metro rail expansion corridors in Mumbai and Delhi are generating new-construction shoe storage specifications for compact footprint apartments.
Industry Challenges
- ISO 9001 audit compression:Export-oriented suppliers face shortened certification renewal cycles as European buyers demand current quality management documentation.
- Legacy ERP integration:Mid-tier manufacturers struggle to synchronize production scheduling with real-time inventory visibility demanded by large-format retail EDI protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shoe Storage and Organizers Market |
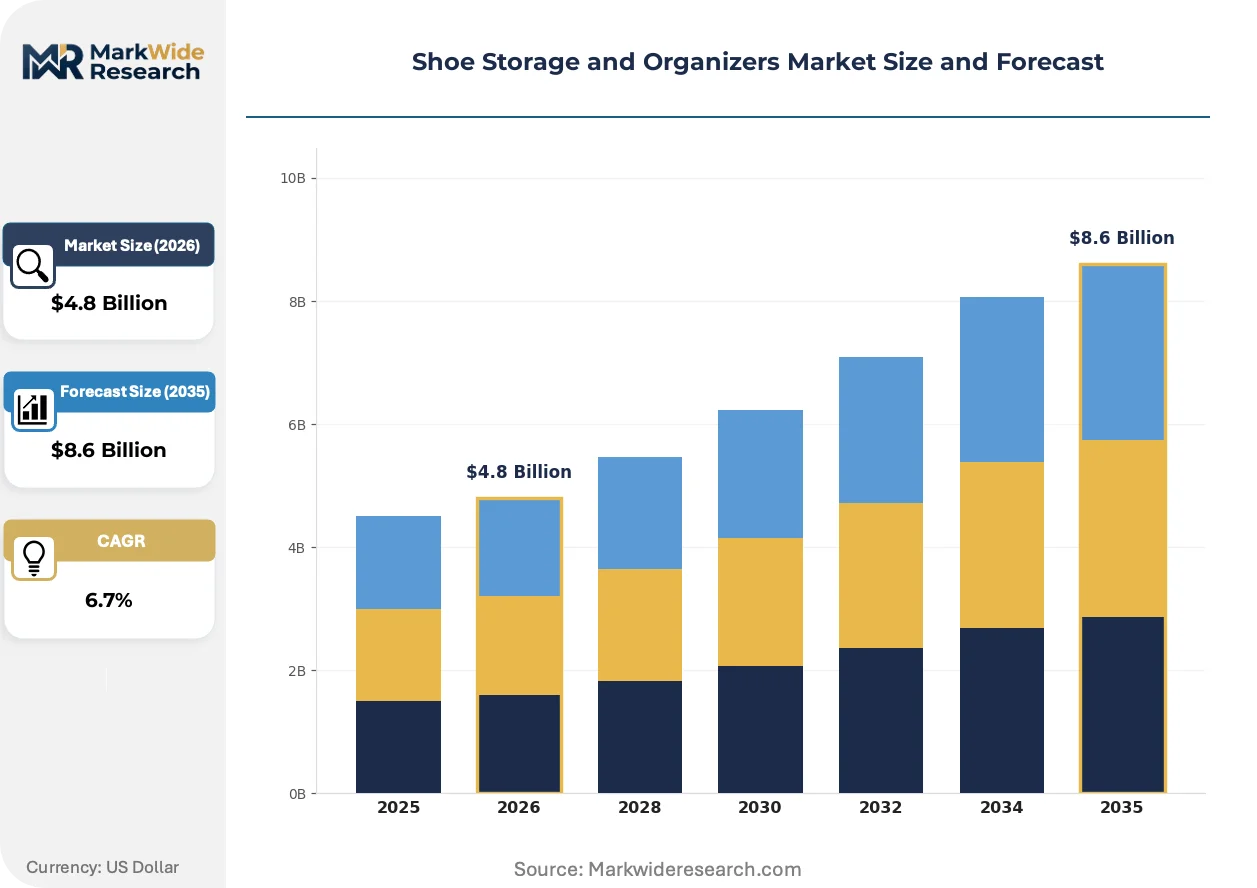
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Racks, Boxes, Shelves, Organizers Material: Plastic, Wood, Metal, Fabric Design Type: Stackable, Portable, Wall-mounted, Multi-tiered End User: Residential, Commercial, Retail, Online Consumers |
| Companies Covered | The Container Store, SONGMICS, IKEA, Prepac Manufacturing, Rubbermaid Commercial Products, Whitmor, Seville Classics, Honey-Can-Do, ClosetMaid, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shoe Storage and Organizers Market Evolving Landscape
Active material science breakthroughs and regulatory compliance automation are compressing product development cycles while fragmenting traditional price-performance tradeoffs across residential and commercial channels.
Magnetic mounting hardware paired with ultra-light aluminum extrusions is miniaturizing wall-mounted system profiles to under two inches of projection depth. Urban apartment renovators in Tokyo and Seoul are specifying these configurations for entryway corridors under three feet wide. The technology is compressing the distinction between permanent fixture and removable furniture, enabling rental-friendly installations that previously required landlord approval.
EPA formaldehyde emission standards for composite wood products are tightening testing protocols for particleboard shelving substrates. Domestic manufacturers must now maintain third-party certification through quarterly mill audits rather than annual self-reporting. Kitchen and closet renovation contractors in the US Northeast are shifting specification preference toward CARB Phase 2 compliant imports to avoid project delay risks.
Direct-to-consumer configurators now dominate replacement purchasing for fabric and plastic organizers, displacing in-store assortment browsing. SONGMICS and equivalent platforms capture search-intent traffic through room-dimension matching algorithms, while traditional retailers rely on remnant foot traffic for impulse accessories. This channel rotation is most pronounced among 25-34 year-old renters in China's tier-one cities, where same-day delivery expectations have normalized.
Shoe Storage and Organizers Market Segmentation
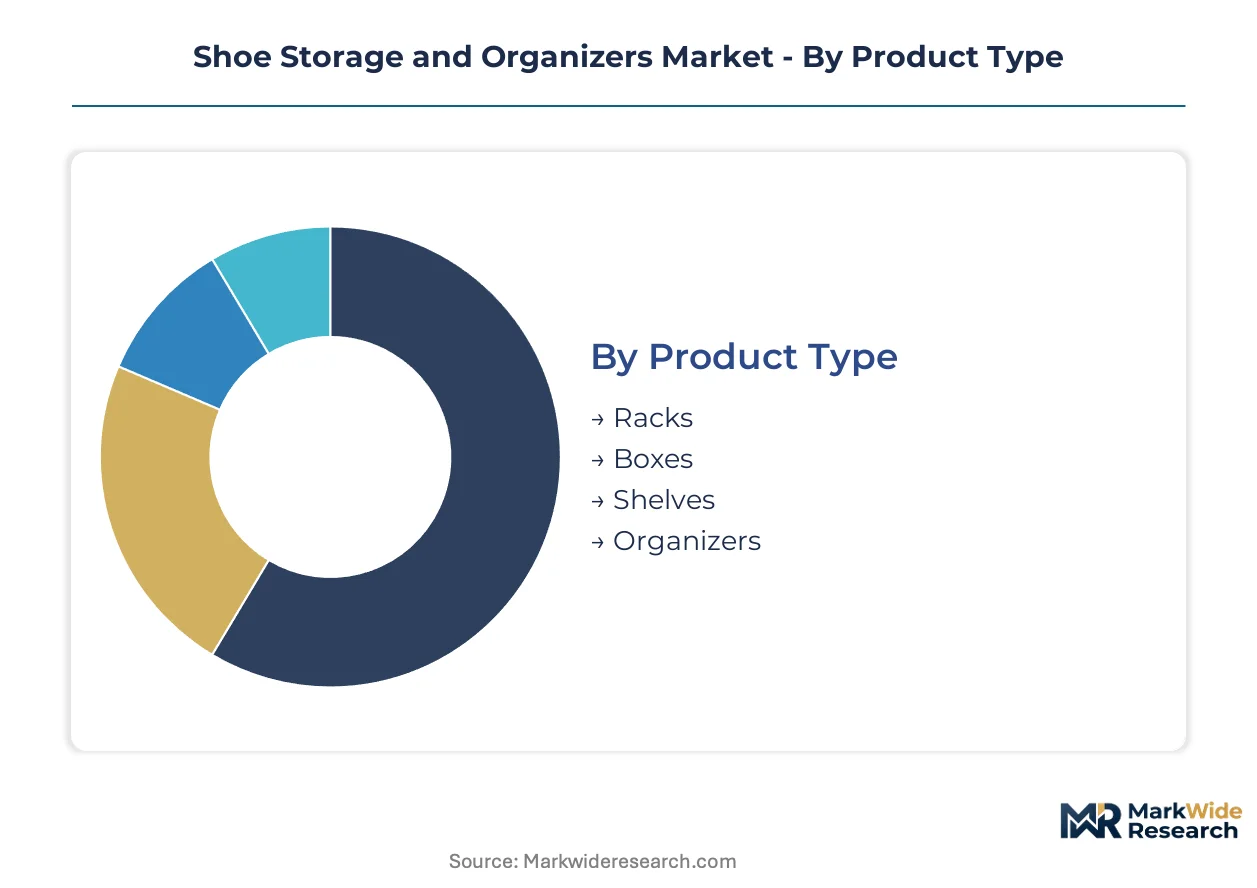
Segmentation in shoe storage and organizers reveals how material costs, installation constraints, and channel economics fragment purchasing behavior across residential and commercial buyers. Understanding these divides exposes where margin pools concentrate versus where volume commoditization accelerates.
Product Type:
Domestic manufacturers dominate racks and shelving through custom installation partnerships, while boxes and organizers flow through export-heavy direct-to-consumer channels.
- Racks:Powder-coated steel or aluminum frames engineered for fifteen to fifty pound load ratings per tier. Demand concentrates in California multi-family construction where Title 24 efficiency standards mandate space-optimized storage specifications. Contractors pre-certify wall-mounted configurations to compress bidding timelines.
- Boxes:Injection-molded polypropylene or fabric constructions with snap-fit lids. Compact apartment dwellers in Shanghai and Beijing under forty-five square meters drive repeat purchase frequency for under-bed and closet-floor configurations. SONGMICS captures this segment through room-dimension matching algorithms.
- Shelves:FSC-certified particleboard or engineered wood substrates with CARB Phase 2 compliance for US Northeast renovation contractors.
- Organizers:Modular compartment systems spanning hanging, over-door, and drawer-insert configurations.
Racks hold the largest share; momentum sits with boxes as direct-to-consumer configurators displace in-store browsing.
Material:
Cost tier stratification separates premium metal fabrication from mass-market plastic volumes, with wood and fabric occupying intermediate positioning.
- Plastic:Polypropylene homopolymer formulations processed through automated injection molding achieving forty percent faster cycle times. REACH phthalate restrictions are accelerating polymer reformulation toward bio-based alternatives among EU-exporting suppliers.
- Metal:Powder-coated cold-rolled steel or aluminum extrusions for commercial-grade durability. Retail backrooms and premium residential channels absorb tariff-exposed input costs from Section 232 and 301 trade measures affecting coil steel sourcing.
- Wood:CARB Phase 2 compliant particleboard or solid hardwood substrates for finished shelving aesthetics.
- Fabric:Non-woven polypropylene or canvas constructions with collapsible frames for portable deployment.
Plastic commands unit volume leadership; metal fabrication captures superior per-unit economics in commercial channels.
Design Type:
Installation permanence divides rental-friendly portable solutions from fixture-integrated wall-mounted systems in new construction.
- Wall-mounted:Magnetic mounting hardware paired with ultra-light aluminum extrusions achieving under two inches projection depth. Tokyo and Seoul apartment renovators specify these for entryway corridors under three feet wide, compressing the distinction between permanent fixture and removable furniture.
- Stackable:Interlocking polypropylene bins with nesting geometry for vertical space reclamation. Tier-one Chinese city density drives adoption as primary footwear display infrastructure in sub-forty-five square meter dwellings.
- Portable:Collapsible fabric or lightweight plastic constructions for seasonal rotation and relocation.
- Multi-tiered:Freestanding vertical frames with adjustable shelf spacing for boot and athletic shoe accommodation.
Wall-mounted designs are expanding most quickly as contractors integrate storage into new construction specifications; stackable systems anchor replacement volume.
End User:
Channel concentration separates commercial procurement through renovation contractors from residential direct purchasing via e-commerce platforms.
- Residential:Individual homeowners and apartment renters executing closet renovations or space reclamation projects. The Container Store controls high-margin custom installations through specialty retail footprint while IKEA anchors mass-market penetration via flat-pack logistics.
- Commercial:Retail backrooms, hospitality housekeeping, and corporate facilities requiring inventory management infrastructure. ISO 9001 quality management standards govern production consistency among export-oriented suppliers serving this segment.
- Retail:Brick-and-mortar footwear and apparel stores requiring display-forward storage with brand visibility.
- Online Consumers:Search-intent purchasers aged twenty-five to thirty-four in China's tier-one cities where same-day delivery expectations have normalized.
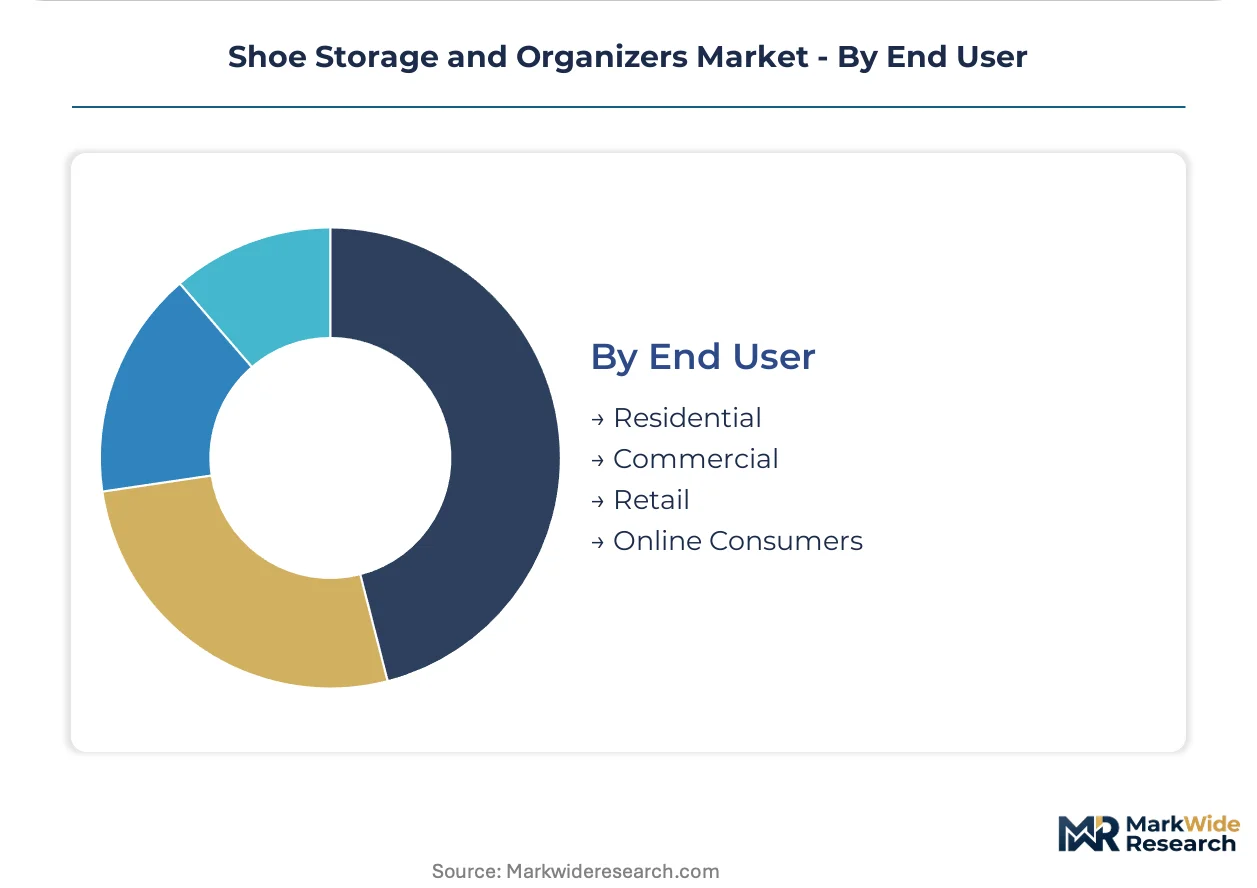
Residential absorbs the largest revenue pool; online consumers are gaining share fastest as channel rotation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import flows from Asian manufacturing clusters dominate supply chains serving Western residential renovation markets, while domestic fabrication retains share in premium commercial channels. Export-oriented suppliers in China and Vietnam face documentation friction from California's Proposition 65 and the EU's REACH compliance requirements. Regional demand patterns diverge sharply between dense urban centers prioritizing wall-mounted systems and suburban markets favoring freestanding storage furniture.
United States
California's Title 24 building efficiency standards mandate space-optimized storage in new multi-family construction, compressing bidding timelines for pre-certified wall-mounted configurations. EPA formaldehyde emission rules and CARB Phase 2 compliance requirements govern particleboard sourcing for shelving substrates. The Northeast corridor from Boston to Washington DC concentrates renovation contractor demand for compliant imports.
China
Shanghai and Beijing apartment dwellers in sub-forty-five square meter units drive wall-mounted system adoption as primary footwear display infrastructure. The country's national standards administration oversees quality certification for export-bound production. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta supply injection-molded polypropylene bins to global e-commerce channels.
Germany
REACH phthalate restrictions accelerate polymer reformulation toward bio-based alternatives among domestic fabricators serving EU markets. The country's federal environmental agency enforces extended producer responsibility frameworks threatening to add end-of-life collection costs to current pricing models. Industrial concentration in North Rhine-Westphalia and Bavaria supports precision metal fabrication for commercial-grade rack systems.
Japan
Tokyo apartment renovators specify magnetic mounting hardware with under-two-inch projection depth for entryway corridors under three feet wide. METI oversees industrial standards for furniture and homeware quality management. The Kanto region around Tokyo anchors specification-driven demand for rental-friendly installations.
India
Mumbai and Delhi metro rail expansion corridors generate new-construction shoe storage specifications for compact footprint apartments. The Bureau of Indian Standards governs material safety certification for domestic and imported products. Manufacturing activity in Maharashtra and Gujarat supplies fabric and plastic organizers to emerging urban housing stock.
Shoe Storage and Organizers Market Competitive Landscape
Listed leaders compete with private specialists across channel access and margin capture, creating a tiered structure where scale-driven retailers face off against configuration-focused direct-to-consumer platforms. Specialty retail footprints control high-margin custom installation workflows, while mass-market penetration flows through flat-pack logistics and automated warehousing. Three archetypes dominate: vertically integrated specialty retailers, direct-to-consumer configurators, and commercial-grade fabricators. Competitive moves concentrate on geographic licensing partnerships and portfolio diversification into adjacent storage categories.
Among North American-based retailers, The Container Store exemplifies the specialty retail archetype through controlled custom installation workflows. SONGMICS occupies a position within the direct-to-consumer tier, leveraging room-dimension matching algorithms to capture search-intent traffic. IKEA anchors the mass-market vector through flat-pack logistics and in-store room displays that reduce customer acquisition costs.
| Leading Market Players |
|---|
| The Container Store |
| SONGMICS |
| IKEA |
| Prepac Manufacturing |
| Rubbermaid Commercial Products |
| Whitmor |
| Seville Classics |
| Honey-Can-Do |
| ClosetMaid |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between injection-molded polypropylene suppliers and mass-market retailers lock in both resin access and price visibility across volatile polymer markets. California's Title 24 pre-certification requirements compress bidding timelines for wall-mounted systems, forcing contractors to secure capacity reservations before project awards.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in commercial-grade metal fabrication. Price differentiation rests on FSC certification grade and CARB Phase 2 compliance status for particleboard substrates. Cost compression in entry-level plastic bins is intensifying because automated tooling achieves forty percent faster cycle times. Renovation contractors in the US Northeast demonstrate least price sensitivity due to project delay risks, while direct-to-consumer purchasers aged twenty-five to thirty-four in China's tier-one cities exhibit highest sensitivity.
Supply Chain Analysis
Port congestion on the Shanghai-Los Angeles trade lane elevates inbound logistics costs for injection-molded polypropylene bins and fabric organizers. Manufacturing concentrates in China, Vietnam, and Malaysia, drawing from cold-rolled steel coil, FSC-certified wood fiber, and polymer resin feedstocks. Steel tariff exposure from Section 232 and 301 trade measures creates structural risk for powder-coated frame production. Distribution runs through flat-pack logistics networks for mass-market penetration and custom installation partnerships for premium residential channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against magnetic mounting hardware and ultra-light aluminum extrusions that compress the distinction between permanent fixture and removable furniture.
For Market Incumbents: Fortify custom installation workflows through controlled specialty retail footprints to defend against direct-to-consumer configurators. Secure backward integration into FSC-certified particleboard supply to mitigate Baltic and Southeast Asian fiber cost volatility. Prioritize CARB Phase 2 compliance investment to avoid customs hold risks under California's Proposition 65. For New Entrants and Emerging Players: Lead with wall-mounted system specifications for India's Mumbai and Delhi metro rail expansion corridors, where compact footprint apartments generate new-construction demand. Target underpenetrated commercial backroom inventory management with ISO 9001-certified production. Deploy room-dimension matching algorithms to capture search-intent traffic from twenty-five to thirty-four-year-old renters. For Investors and Strategic Acquirers: Fabricators with established reverse logistics infrastructure represent the priority acquisition archetype as extended producer responsibility frameworks threaten end-of-life collection cost additions. Long-term viability hinges on smart home integration convergence between RFID-enabled inventory tracking and traditional storage hardware. Monitor EU REACH phthalate restriction enforcement as inflection indicator for bio-based polymer premium positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Home Integration | RFID-enabled inventory tracking converges with IoT sensor platforms for premium positioning. |
| Bio-based Polymer Transition | REACH-compliant reformulation opens margin expansion in EU-exporting supply chains. |
| Reverse Logistics Buildout | Extended producer responsibility mandates favor domestic producers with take-back infrastructure. |
| Direct-to-Consumer Configurator | Room-dimension matching algorithms displace in-store browsing among urban renters. |
| Title 24 Pre-certification | California multi-family construction mandates compress bidding timelines for wall-mounted systems. |
Research Methodology
Operator-level perspectives from closet renovation contractors, retail category buyers, injection molding plant managers, and e-commerce platform supply planners anchored the qualitative base. Primary interviews combined with secondary validation from customs records, EPA formaldehyde emission filings, CARB certification databases, and ISO 9001 audit registries. Bottom-up shipment analysis and top-down construction spending data provided triangulation across the analysis window.
Sensitivity analysis tested forecast outputs against steel tariff exposure scenarios and REACH compliance cost pass-through assumptions. Segmentation dimensions modeled include product type, material grade, design configuration, and end-user channel across the projection horizon. CAGRs derived from polynomial trend fitting to historical shipment data, with inputs from residential construction permits and multi-family housing starts.
The analysis sits within stated boundaries; outcomes outside sustained urban density trends in tier-one Chinese cities and continued California Title 24 enforcement would require recalibration. Forecasts reflect assumptions regarding polymer feedstock availability and FSC-certified fiber supply stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Storage and Organization
Shoe Rack Market
Home Storage and Organization
Asia-Pacific Digital Home Locker Market
Home Storage and Organization
Closet Organizers Market
Home Storage and Organization
Kitchen Storage Organization Market
Home Storage and Organization
Shop Shelving Market
Home Storage and Organization
United States Home Organizers and Storage Market
Home Storage and Organization
Regency Shelving Market
Home Storage and Organization
Clothes Closets Market
Home Storage and Organization
Smart Shoe Cabinet Market
Home Storage and Organization
Europe Home Organizers and Storage Market
Home Storage and Organization
Kitchen Storage Market
Home Storage and Organization
Sheds and Outdoor Storage Market
Home Storage and Organization
Small Space Furniture Market
Home Storage and Organization
United Kingdom Home Decor Market
Home Storage and Organization
Wardrobe Boxes Market
Home Storage and Organization
Cabinet & Furniture Drawer Slides Market