
 Russia Office Furniture Market | 2026-2036
Russia Office Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Office Furniture Market Analytics
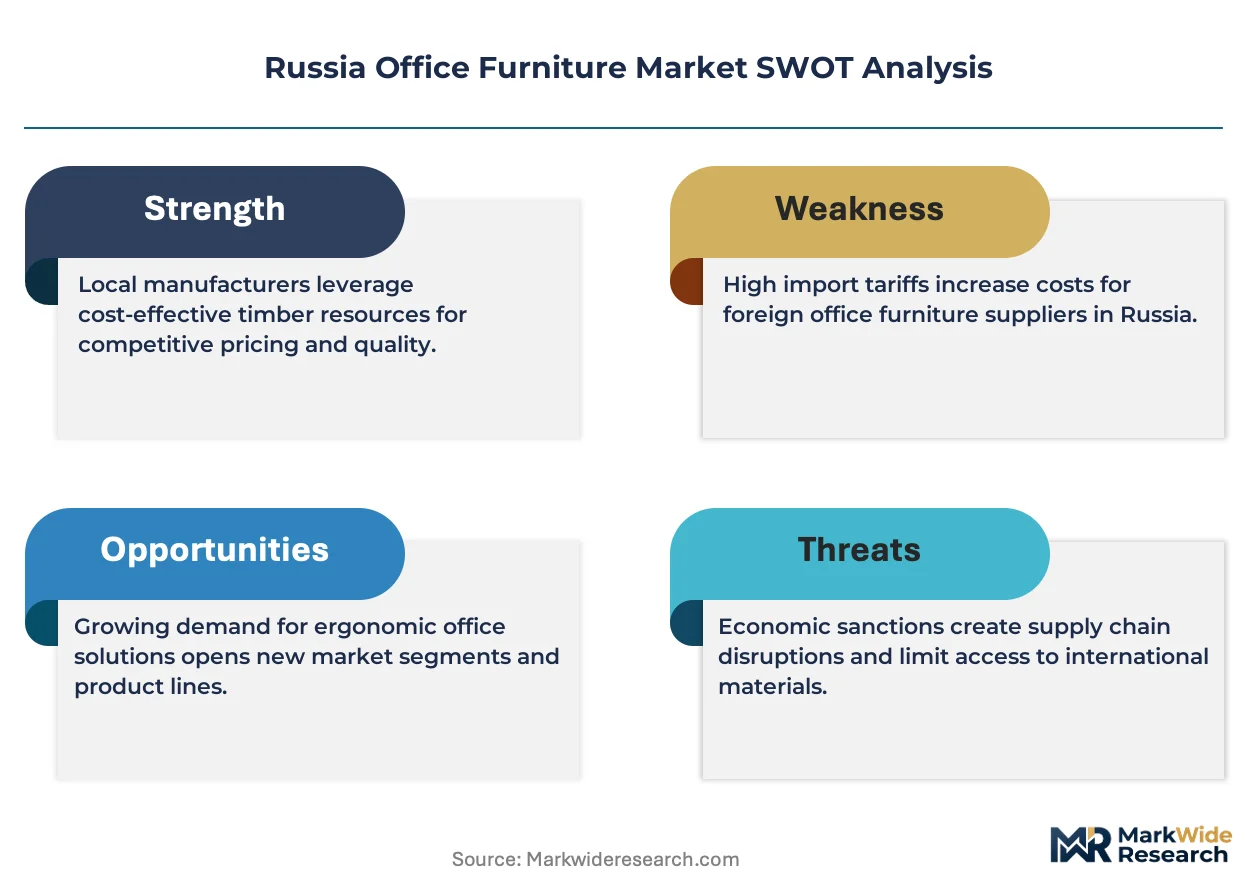
Ergonomic specification tiers is reorganizing competitive dynamics across the Russia office furniture sector. Narbutas leverages its Baltic manufacturing footprint to supply height-adjustable desking systems to Russian corporate clients. ARTU Factory anchors its position through captive metalworking capabilities that reduce lead times for government tenders. Metta Company competes on upholstered seating specialization, drawing demand from co-working operators in Moscow.
Office furniture encompasses workstations, seating, and storage systems engineered for commercial productivity environments, typically fabricated from engineered wood substrates, cold-rolled steel frames, and high-density polyurethane cushioning with fire-retardant fabric treatments. The primary purpose centers on supporting occupant health, spatial efficiency, and organizational workflow in professional settings. Wood-based desks and storage units retain the largest revenue pool, though metal-framed ergonomic seating captures the fastest expansion as corporations retrofit for employee retention. Co-working spaces and educational institutions represent ascending demand channels, while traditional government procurement maintains volume stability through centralized purchasing protocols.
Russia's Federal Agency on Technical Regulating and Metrology (Rosstandart) enforces GOST-R certification for furniture flammability and structural safety, creating compliance barriers for unverified imports. The Eurasian Economic Union's technical regulations (TR CU 025/2012) harmonize sanitary-epidemiological requirements across member states, shaping cross-border sourcing decisions for manufacturers operating in Belarus and Kazakhstan. Domestic producers must monitor pending amendments to construction norms that mandate accessibility standards in public administration buildings.
Market Dynamics
Import substitution mandates are restructuring procurement flows across Russia's office furniture sector, redirecting volume from Baltic and Asian suppliers toward domestic manufacturers with verified GOST-R certification.
Growth Catalysts
- Import substitution framework:Federal procurement protocols now prioritize domestic suppliers, creating captive demand for Russian manufacturers.
- Ergonomic retrofit cycles:Corporate employers are replacing static workstations with height-adjustable configurations to reduce musculoskeletal claims.
- Co-working expansion:Flexible workspace operators in Moscow and Saint Petersburg are scaling furniture procurement for multi-location rollouts.
Market Restraints
- Engineered wood substrate volatility:Birch plywood and particleboard input costs fluctuate with forestry export restrictions.
- Metal component concentration:Cold-rolled steel frame supply clusters in Belarus, exposing procurement to cross-border logistics friction.
- TR CU 025/2012 compliance burden:Eurasian Economic Union sanitary-epidemiological testing extends product launch timelines for upholstered seating.
Strategic Opportunities
- Secondary city penetration:Kazan and Novosibirsk office stock is modernizing without established furniture supplier relationships.
- Leasing-as-service models:Furniture-as-a-service contracts allow manufacturers to capture recurring revenue from SME tenants.
- Accessibility mandate preparation:Pending amendments to Russian construction norms will require adjustable-height workstations in public administration buildings.
Industry Challenges
- Certification timeline compression:Rosstandart GOST-R testing queues create inventory holding costs ahead of tender deadlines.
- Legacy ERP integration:Domestic manufacturers lack real-time production planning systems to match just-in-time delivery expectations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Office Furniture Market |
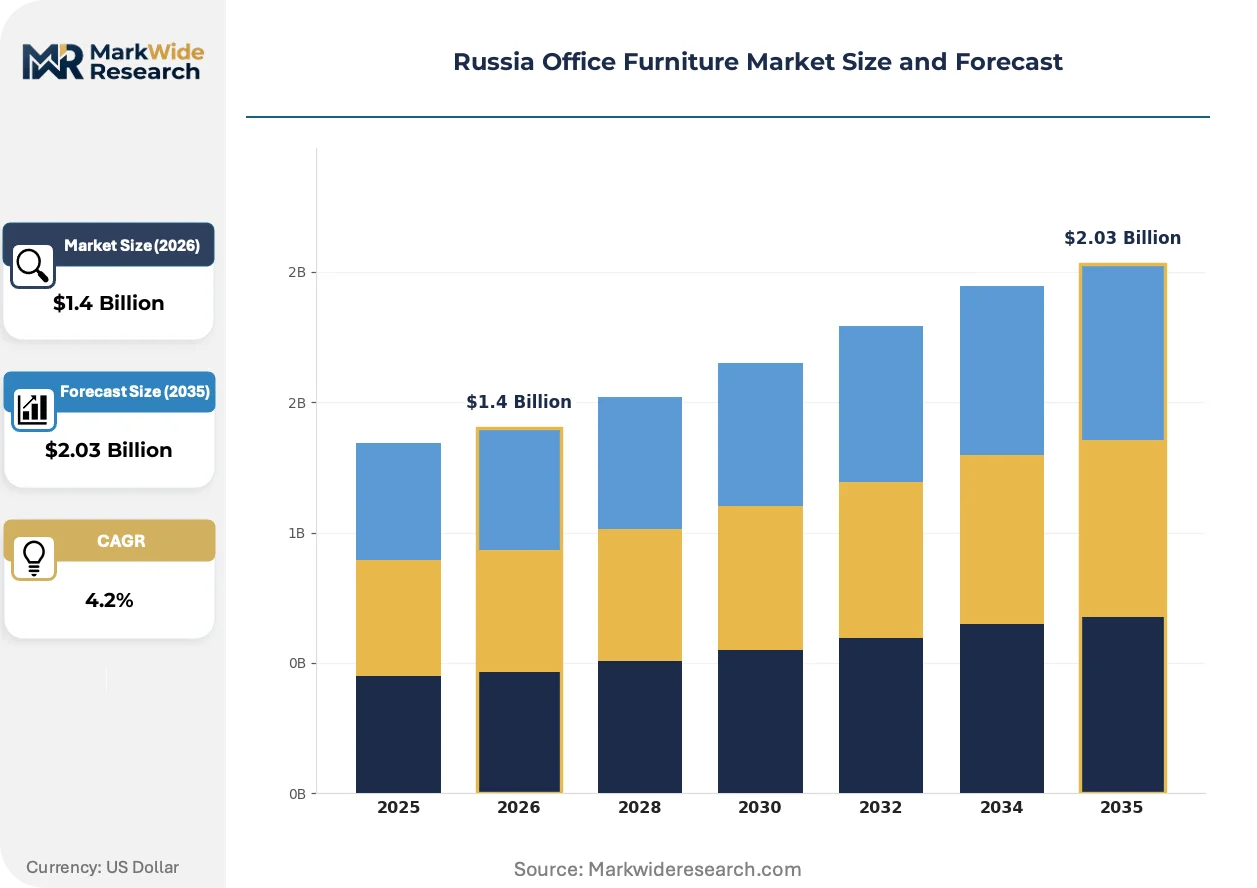
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.03 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desks, Chairs, Storage Units, Workstations Material: Wood, Metal, Plastic, Glass End User: Corporations, Educational Institutions, Government Offices, Co-working Spaces Style: Modern, Traditional, Ergonomic, Contemporary |
| Companies Covered | Narbutas, ARTU Factory, Metta Company, KSBuro, Tabula Sense, IKEA, DiKom, Bene Rus LLC, FELIX Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Office Furniture Market Evolving Landscape
Digital specification tools and modular assembly systems are compressing design-to-delivery cycles across Russia's office furniture value chain.
Sensor-integrated height-adjustable desking is supplanting manual crank mechanisms in premium commercial developments. Corporate real estate managers in Moscow are specifying these units for new build-outs. The technology is compressing price differentiation between mid-tier and premium workstation categories.
Rosstandart is tightening GOST-R flammability testing protocols for upholstered components. Manufacturers must now submit expanded documentation for foam cushioning and fabric treatments. Seating specialists are responding by consolidating supply relationships with certified textile mills in Tula and Ryazan regions.
Direct-to-developer contracting is displacing traditional distributor intermediaries for large-format projects. Real estate developers are engaging manufacturers for turnkey furniture packages during construction phases. This pattern concentrates in Saint Petersburg's commercial pipeline where developer-led fit-outs dominate.
Russia Office Furniture Market Segmentation
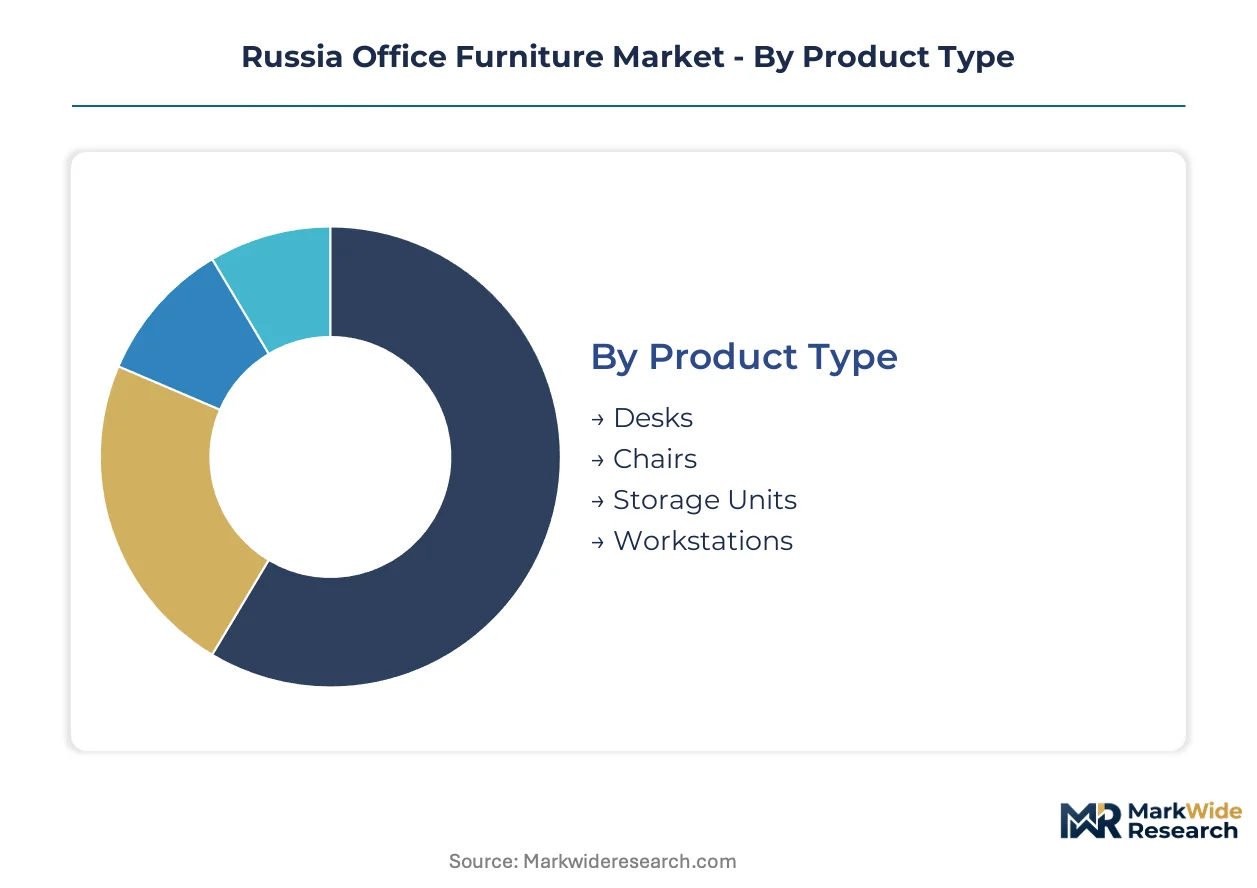
Russia's office furniture procurement flows through distinct regulatory and functional channels that reshape competitive positioning. GOST-R certification requirements and import substitution mandates create tiered market access that varies sharply by product category and end-use specification.
Product Type:
Rosstandart applies differentiated flammability and structural load testing protocols across furniture categories, with upholstered seating facing the most intensive documentation requirements.
- Desks:Engineered wood substrates with cold-rolled steel leg assemblies dominate corporate specifications. Height-adjustable configurations are gaining traction in Moscow premium developments as employers retrofit for ergonomic compliance.
- Chairs:High-density polyurethane cushioning with fire-retardant fabric treatments requires expanded TR CU 025/2012 documentation. Government tenders in Saint Petersburg specify certified seating from domestic producers with verified supply chain traceability.
- Storage Units:Modular filing systems fabricated from birch plywood and particleboard serve public administration buildings. Lead times compress when manufacturers maintain captive metalworking for hardware components.
- Workstations:Integrated desk-screen-storage configurations are specified by co-working operators for rapid deployment. Panel system modularity allows reconfiguration between open-plan and cellular layouts.
Desks handle the majority of throughput; workstations are expanding most quickly on share.
Material:
Input cost volatility and cross-border logistics exposure determine material selection priorities for Russian manufacturers.
- Wood:Birch plywood and particleboard from domestic forestry operations anchor government procurement. Export restriction volatility on raw timber creates margin pressure for engineered wood producers.
- Metal:Cold-rolled steel frames concentrate supply relationships with Belarusian mills, exposing procurement to Eurasian Economic Union border friction. ARTU Factory mitigates this through captive metalworking capabilities.
- Plastic:Polypropylene and ABS components serve budget seating tiers and accessory lines. Injection molding capacity clusters in Tula and Ryazan regions near certified textile suppliers.
- Glass:Tempered glass surfaces appear in executive desking and conference table specifications. Weight and fragility limit application to premium installations with white-glove delivery capability.
Wood commands the volume base; metal is climbing the fastest on specification intensity.
End User:
Federal procurement protocols and facility modernization cycles create divergent demand profiles across customer categories.
- Corporations:Ergonomic retrofit programs in Moscow and Saint Petersburg drive replacement demand for height-adjustable workstations. Real estate managers specify sensor-integrated desking for new build-outs.
- Educational Institutions:Furniture procurement follows centralized acquisition schedules with durability specifications exceeding commercial standards. Secondary cities lack established supplier relationships.
- Government Offices:Rosstandart GOST-R certification is mandatory for tender participation. Import substitution mandates prioritize domestic manufacturers with verified compliance documentation.
- Co-working Spaces:Flexible workspace operators require rapid-scaling procurement for multi-location rollouts. Leasing-as-service models appeal to capital-constrained SME tenants.
Corporations anchor demand volume; co-working spaces are gaining share fastest on expansion velocity.
Style:
Aesthetic positioning intersects with functional specification tiers across price-sensitive and premium market layers.
- Modern:Clean lines and minimal hardware characterize developer-led fit-outs in Saint Petersburg commercial pipeline. Direct-to-developer contracting concentrates procurement for large-format projects.
- Traditional:Veneered wood surfaces and ornamental metalwork serve public administration buildings with heritage preservation requirements. Lead times extend for custom finishing.
- Ergonomic:Biomechanically optimized seating and height-adjustable desking reduce employer musculoskeletal claims. Specification penetration is deepest in Moscow corporate headquarters.
- Contemporary:Hybrid aesthetics blending modern proportion with traditional materiality appeal to professional services firms. Price positioning sits between economy and premium tiers.
Modern styling handles the majority of new construction specification; ergonomic is the fastest mover on retrofit demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Russia's office furniture trade balance has inverted since import substitution policies took effect, with domestic producers capturing procurement volume previously sourced from Baltic and Asian suppliers. Federal mandates now require GOST-R certification for government tenders, redirecting demand toward verified local manufacturers.
Moscow
Corporate headquarters and co-working operators in Moscow drive specification for sensor-integrated height-adjustable desking. Rosstandart enforces tightened flammability testing protocols that extend product launch timelines for upholstered seating. The Moscow-Central cluster concentrates developer-led fit-outs where direct-to-manufacturer contracting displaces traditional distribution channels.
Saint Petersburg
Commercial real estate developers in Saint Petersburg specify turnkey furniture packages during construction phases, compressing traditional procurement cycles. Import substitution mandates prioritize domestic suppliers with verified compliance documentation for public administration tenders. The city's commercial pipeline favors modern styling with minimal hardware for large-format office developments.
Kazan
Educational institutions and emerging corporate tenants in Kazan modernize office stock without established supplier relationships, creating first-mover opportunities. Federal procurement protocols apply standardized durability specifications exceeding commercial norms for university and administrative buildings. The Volga Federal District hub lacks incumbent furniture vendors, lowering competitive barriers for certified domestic entrants.
Novosibirsk
Siberian corporate expansion and public sector modernization in Novosibirsk generate demand for ergonomic workstation configurations. TR CU 025/2012 harmonizes sanitary-epidemiological requirements across Eurasian Economic Union member states, shaping cross-border sourcing from Belarusian and Kazakh suppliers. The Siberian Federal District's industrial base supports captive metalworking capabilities that reduce lead times for regional tenders.
Yekaterinburg
Ural region mining and industrial conglomerates in Yekaterinburg retrofit administrative facilities with ergonomic seating to reduce occupational health claims. Pending amendments to Russian construction norms mandate accessibility standards in public buildings, requiring adjustable-height workstations. The Ural Federal District's manufacturing heritage supports integrated supply chains for steel-frame components and engineered wood substrates.
Russia Office Furniture Market Competitive Landscape
Concentration sits with domestic manufacturers possessing captive certification capabilities and verified GOST-R documentation. The vendor base segments across three tiers: integrated producers with metalworking and upholstery capabilities, specialized seating fabricators, and modular workstation assemblers sourcing components from Eurasian Economic Union partners. Two competitive moves dominate: backward integration into cold-rolled steel frame production to mitigate Belarusian supply friction, and direct contracting with real estate developers to bypass distributor margins.
Within the domestic integrated tier, ARTU Factory and Metta Company exemplify archetypes competing on divergent capabilities. ARTU Factory anchors its positioning through captive metalworking that compresses lead times for government tenders requiring rapid turnaround. Metta Company occupies the upholstered seating specialization vector, drawing procurement from co-working operators and corporate retrofit programs in Moscow. Narbutas represents the cross-border Baltic supplier archetype, leveraging proximity manufacturing to serve Russian corporate clients despite import substitution headwinds.
| Leading Market Players |
|---|
| Narbutas |
| ARTU Factory |
| Metta Company |
| KSBuro |
| Tabula Sense |
| IKEA |
| DiKom |
| Bene Rus LLC |
| FELIX Company |
| Others |
Value Network & Pricing Analysis
Forty-five to sixty-day Rosstandart GOST-R certification queues compress pricing power for domestic manufacturers while elevating premium capture for pre-certified incumbents with inventory buffers. This lead-time asymmetry rewards Baltic suppliers like Narbutas with established documentation pipelines, forcing Russian assemblers to absorb holding costs or forfeit tender participation.
Pricing Analysis
Government procurement offices anchor contract-based long-term pricing through centralized tender frameworks that prioritize GOST-R certification over unit cost. Price differentiation separates certified domestic producers from uncertified imports on compliance grade, with volume-scale discounts concentrated in multi-location co-working rollouts. Cost compression in mid-tier engineered wood desking intensifies as Belarusian birch plywood export restrictions elevate substrate expenses. SME tenants exhibit highest price sensitivity, while federal administrators accept premium positioning for verified supply chain traceability.
Supply Chain Analysis
Container availability constraints on Baltic Sea routes elevate inbound logistics costs for Lithuanian and Polish component suppliers serving Russian distributors. Manufacturing concentration clusters in Belarus for cold-rolled steel frames, Tula and Ryazan for injection-molded plastics, and domestic forestry regions for birch plywood. Raw material dependencies rest on Belarusian metallurgical output, certified textile treatments from Central Russian mills, and polyurethane foam from Eurasian Economic Union partners. Single-source vulnerability concentrates in cross-border steel procurement exposed to EAEU customs friction. Distribution runs through direct-to-developer contracting for large-format projects alongside traditional distributor networks serving secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Furniture-as-a-service leasing contracts expand faster than hardware sales as capital-constrained co-working operators and SME tenants prioritize operational expenditure over capital deployment. This recurring-revenue layer rewards manufacturers with integrated maintenance and reconfiguration capabilities.
For Market Incumbents: Compound certification advantages by expanding GOST-R documentation pipelines into pending accessibility-mandate categories before regulatory amendments take effect. Captive metalworking capabilities defend against Belarusian supply friction while direct-to-developer contracting locks out distributor intermediaries in Saint Petersburg's commercial pipeline. Threat concentration sits with Baltic suppliers leveraging proximity logistics to bypass import substitution headwinds.
For New Entrants and Emerging Players: Aftermarket reconfiguration and maintenance services represent an under-served layer where incumbents lack real-time production planning systems for just-in-time delivery. Secondary cities Kazan and Novosibirsk offer penetrable procurement channels without established supplier relationships. Leasing-as-service models provide capital-efficient go-to-market positioning against hardware-centric domestic producers.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because GOST-R certification barriers compound with each Rosstandart protocol amendment, entrenching verified domestic producers. Acquisition targets center on upholstered seating specialists with consolidated textile mill relationships and modular workstation assemblers with sensor-integration capabilities. Watch for inflection in federal accessibility-mandate implementation timelines affecting adjustable-height workstation specifications.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cold-Rolled Steel | Captive frame production mitigates Belarusian border friction and compresses government tender lead times. |
| Direct-to-Developer Contracting | Turnkey furniture packages during construction phases displace distributor margins in Saint Petersburg pipeline. |
| Sensor-Integrated Workstation Launch | Biometric height-adjustable desking captures Moscow corporate retrofit demand and elevates specification tier. |
| Certified Textile Mill Consolidation | Vertical control over Tula and Ryazan fabric suppliers streamlines TR CU 025/2012 compliance for seating lines. |
| Furniture-as-a-Service Platform | Recurring revenue contracts align with co-working operator capital constraints and SME tenant preference for OPEX. |
Research Methodology
A standing panel of procurement directors at federal agencies, real estate development managers, co-working space operators, and Rosstandart compliance officers provided ongoing calibration across the research cycle. Primary interviews with furniture manufacturing executives and distributor channel heads combined with secondary validation from Eurasian Economic Union trade databases, GOST-R certification registries, and Russian construction norm amendment drafts. Bottom-up production capacity assessments triangulated against top-down procurement flow analysis.
Consistency checks validated volume and value outputs against external benchmarks including regional commercial real estate development pipelines and federal tender award disclosures. The analytical framework modeled demand across product type, material composition, end-user category, and style specification throughout the projection horizon. CAGRs derived from segmented growth trajectory analysis incorporating ergonomic retrofit cycle timing, import substitution policy implementation pace, and co-working space expansion velocity.
Material uncertainties — forestry export restriction volatility, EAEU border policy shifts, and Rosstandart protocol amendment timing — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding certification timeline compression and developer-led procurement adoption rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Furniture
France Office Furniture Market
Office Furniture
Office Furniture Market
Office Furniture
UAE Office Furniture Market
Office Furniture
Europe Office Furniture Market
Office Furniture
Australia Office Furniture Market
Office Furniture
Furniture and Home Furnishings Market
Office Furniture
Home Office Spending Market
Office Furniture
Japan Office Furniture Market
Office Furniture
United States Furniture Market
Office Furniture
South Korea Office Furniture Market
Office Furniture
Home Office Furniture Market
Office Furniture
United States Home Office Furniture Market
Office Furniture
Office Furniture Edgebands Market
Office Furniture
Europe Home Office Furniture Market
Office Furniture
United Kingdom Office Furniture Market
Office Furniture
Home Office Desk Market