
 Sheds and Outdoor Storage Market | 2026-2036
Sheds and Outdoor Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Sheds and Outdoor Storage Market Analytics
Asset-light leasing models for commercial-grade outdoor storage is narrowing the competitive field for capital-constrained entrants. Lifetime Products leverages vertical integration across resin compounding and rotational molding to sustain margin control. Keter competes through geographic dominance in European distribution while extending its North American retail presence. Tuff Shed anchors its position via manufactured-to-order wooden structures with in-house installation crews.
Sheds and outdoor storage encompass freestanding enclosed structures fabricated from steel, timber, engineered polymers, or resin composites, typically spanning 50 to 2,000 square feet and designed to protect equipment, vehicles, or inventory from weather degradation. Metal sheds command the largest installed base due to lower per-unit cost and minimal maintenance requirements, though resin storage represents the fastest-expanding category as UV-stabilized polyethylene formulations improve impact resistance and color retention. The residential end user segment generates the deepest margin pools, particularly in large and extra-large configurations where customization and foundation work inflate project value. Distribution through home improvement stores captures the highest volume throughput, while online retail channels are gaining share among small-format, DIY-assembly products.
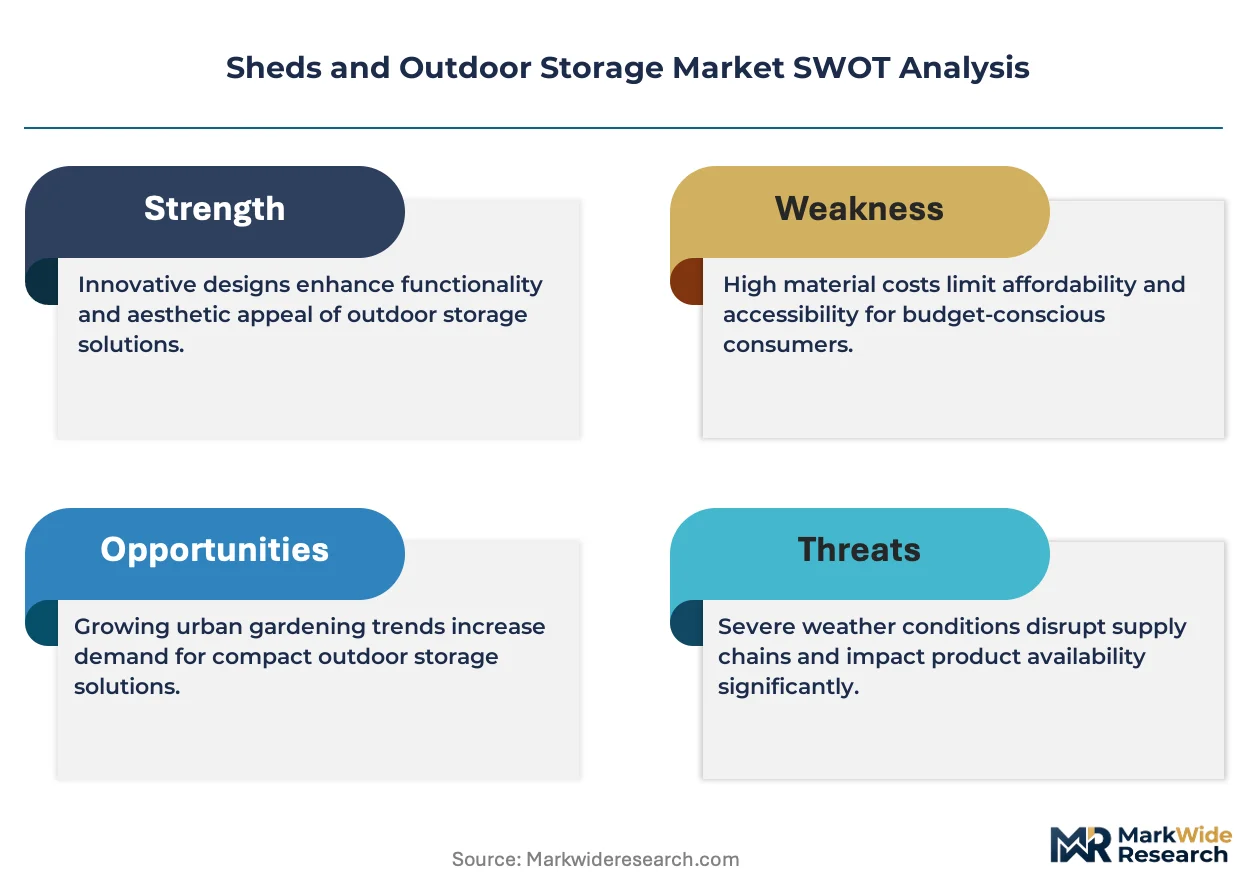
EPA regulations governing pressure-treated lumber emissions shape product availability and material sourcing decisions for wooden shed manufacturers. State-level building codes, particularly in California and Florida, mandate wind-load and seismic resistance standards that elevate engineering costs for permanent structures. Stakeholders must monitor evolving municipal zoning restrictions on accessory building footprints, as these local ordinances increasingly determine addressable market density in high-growth suburban corridors.
Market Dynamics
Residential homeowners across Sun Belt states are expanding outdoor living spaces, creating sustained pull for large-format storage structures that require engineered foundations and custom installation services.
Growth Catalysts
- EPA-treated lumber standards:Federal emissions regulations are accelerating manufacturer migration toward alternative materials including resin composites and galvanized steel.
- California Title 24 building codes:Seismic and wind-load mandates for permanent accessory structures are elevating engineering specifications and project values statewide.
- Suburban corridor zoning liberalization:Municipal ordinances in Texas, Florida, and Arizona are relaxing footprint restrictions for detached structures, expanding addressable lot coverage.
Market Restraints
- Lumber price volatility:Pressure-treated southern yellow pine and engineered wood product costs fluctuate with housing construction cycles, compressing margin predictability for wooden shed producers.
- Resin feedstock concentration:UV-stabilized polyethylene compounding depends on Gulf Coast petrochemical infrastructure, creating geographic supply vulnerability.
- Foundation engineering costs:Permanent structure codes in seismic zones require site-specific soil analysis and engineered slab specifications, elevating total project costs beyond DIY budgets.
Strategic Opportunities
- Modular flat-pack distribution:Containerized shipping of unassembled steel and resin components enables direct-to-consumer channels bypassing home improvement retail markups.
- Vehicle electrification infrastructure:Residential battery storage and EV charging equipment protection is creating demand for climate-controlled, ventilated structures with electrical rough-in.
- Home office ancillary structures:Remote work permanence is driving specifications for insulated, finished-interior sheds serving as dedicated workspace outside primary dwellings.
Industry Challenges
- Installation labor scarcity:Manufactured-to-order wooden structures require skilled crews for on-site assembly and foundation work, constraining throughput for regional producers.
- Permit timeline variability:Municipal plan review and inspection backlogs in high-growth counties extend project completion windows, compressing seasonal selling seasons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sheds and Outdoor Storage Market |
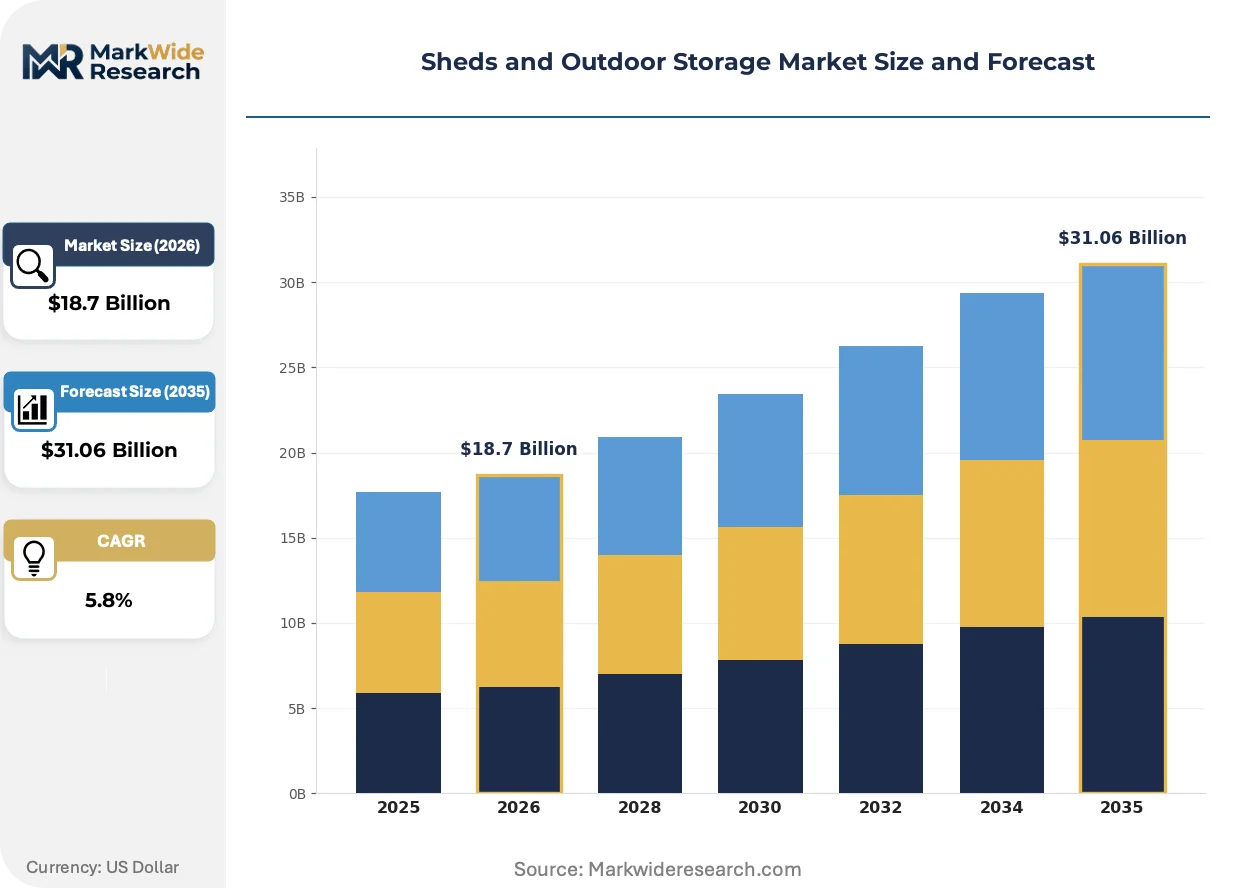
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Sheds, Wooden Sheds, PVC Sheds, Resin Storage End User: Residential, Commercial, Industrial, Agricultural Size: Small, Medium, Large, Extra Large Distribution Channel: Online Retail, Home Improvement Stores, Specialty Outlets, Direct Sales |
| Companies Covered | Lifetime Products, Suncast Corporation, Keter, Rubbermaid, ShelterLogic Group, Tuff Shed, Palram Applications, Arrow Storage Products, DuraMax Building Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sheds and Outdoor Storage Market Evolving Landscape
Material science advances and regulatory pressure are converging to reshape product specifications, manufacturing processes, and distribution economics across the sheds and outdoor storage sector.
UV-stabilized polyethylene rotational molding is virtualizing traditional wooden construction in small and medium format categories. Homeowners seeking zero-maintenance solutions are adopting resin storage at rates exceeding metal alternatives. This material transition is virtualizing the installed base of wooden structures in coastal and humid climates where rot and insect damage accelerate replacement cycles.
California's CALGreen building standards and Florida's wind-borne debris requirements are mandating impact-resistant construction methods for permanent accessory structures. Manufacturers must engineer metal connectors, anchor systems, and wall sheathing to meet jurisdiction-specific load calculations. Producers serving these states have retooled product lines around code-compliant pre-engineered systems, creating regional product fragmentation.
Home improvement retail consolidation is concentrating volume through fewer national chains, altering supplier negotiation leverage and promotional calendar dependencies. Independent shed builders and regional manufacturers are responding by developing proprietary installation networks and direct sales capabilities. This channel tension is most visible in Texas and southeastern states where local builders retain significant market presence against national retail distribution.
Sheds and Outdoor Storage Market Segmentation
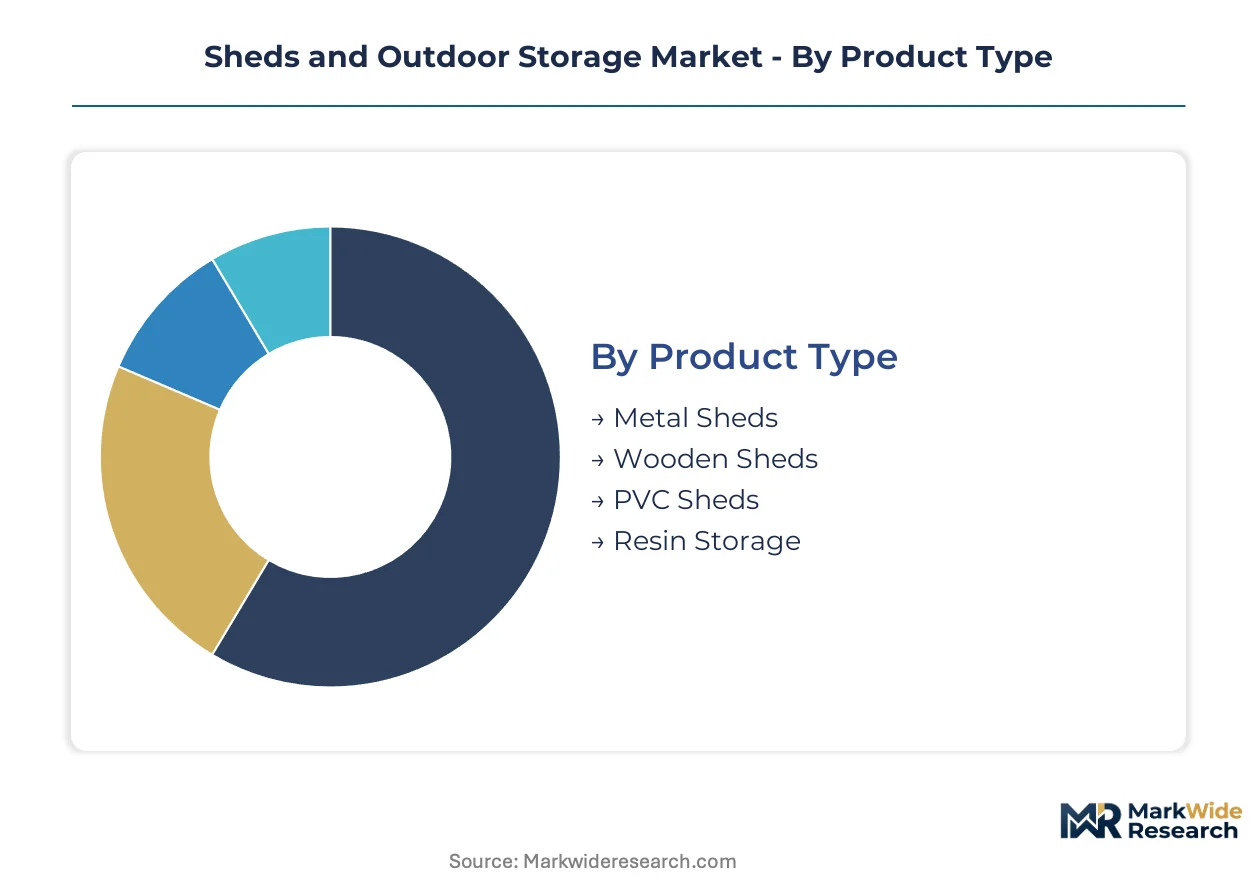
Sheds and outdoor storage manufacturers align product portfolios against distinct usage cycles, from rapid-turnover resin units to engineered wooden structures with decade-long replacement horizons. Segment-level profitability varies dramatically by material chemistry, installation complexity, and channel markup structure.
Product Type:
Metal sheds turn inventory fastest through standardized manufacturing and minimal customization, while wooden structures stretch production-to-delivery cycles through site-specific engineering and foundation coordination.
- Metal Sheds:Galvanized steel construction with ribbed panel architecture dominates the installed base across suburban developments in Texas and Florida. Demand concentrates among homeowners seeking cost-effective vehicle and equipment protection with minimal maintenance obligations.
- Resin Storage:UV-stabilized polyethylene rotational molding delivers zero-maintenance durability against coastal humidity and insect pressure. Sun Belt residential markets are adopting resin formats fastest as color retention and impact resistance formulations improve.
- Wooden Sheds:Pressure-treated southern yellow pine structures with manufactured-to-order specifications serve homeowners requiring aesthetic integration with primary residences. EPA emissions regulations and lumber price volatility compress margin predictability.
- PVC Sheds:Vinyl-clad engineered frames offer intermediate durability between metal and resin with modular expansion capability. Agricultural and light commercial end users favor PVC for chemical resistance and washdown compatibility.
Metal sheds dominate installed base. Resin storage is where expansion concentrates.
End User:
Margin structure inverts across customer types, with residential commanding premium pricing for customization while agricultural buyers extract volume discounts through fleet purchasing.
- Residential:Single-family homeowners drive demand for large and extra-large configurations with finished interiors, electrical rough-in, and climate control. California Title 24 seismic compliance elevates project values for permanent accessory structures.
- Commercial:Property management firms and small businesses require standardized dimensions for equipment staging and inventory overflow. Asset-light leasing models are narrowing the competitive field for capital-constrained entrants.
- Industrial:Manufacturing facilities and logistics operations specify heavy-gauge steel with reinforced anchoring for high-wind zones. Municipal zoning restrictions on accessory building footprints constrain addressable density.
- Agricultural:Farm and ranch operations prioritize equipment protection and feed storage with wide-span clearances. Demand clusters in Midwest and Great Plains states with established distribution through co-op networks.
Residential generates the deepest margin pools. Commercial leasing is climbing the fastest.
Size:
Foundation engineering requirements scale non-linearly with footprint, compressing DIY viability above threshold dimensions and forcing channel migration toward professional installation.
- Large:Configurations spanning 200-600 square feet require engineered slab specifications and permit compliance in seismic zones. Sun Belt suburban developments are expanding lot coverage allowances for detached structures.
- Extra Large:Structures exceeding 600 square feet incorporate finished interiors, insulation, and HVAC rough-in for home office conversion. Remote work permanence is elevating specifications for dedicated workspace outside primary dwellings.
- Medium:Standardized dimensions suit equipment storage and hobby workshops with minimal site preparation. Home improvement retail channels capture highest volume throughput in this bracket.
- Small:Compact formats under 100 square feet ship flat-pack for DIY assembly and online retail distribution. Containerized shipping of unassembled components enables direct-to-consumer channels bypassing retail markups.
Large formats anchor manufacturer revenue. Extra large is gaining share fastest.
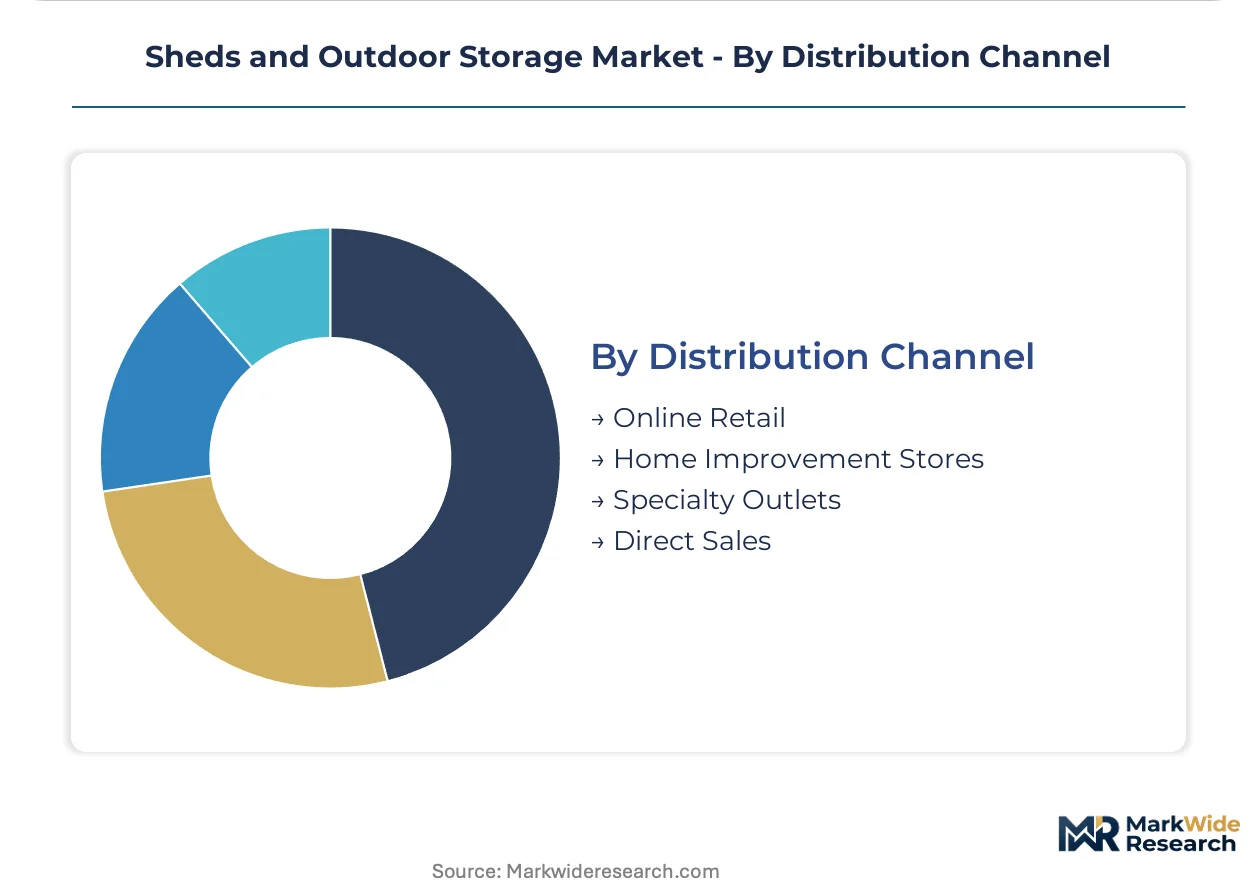
Distribution Channel:
Channel economics diverge sharply on inventory carrying costs, with retail consolidation concentrating volume leverage against supplier pricing while direct models capture margin through installation services.
- Home Improvement Stores:National chains dominate volume throughput with seasonal promotional calendars and co-located installation services. Supplier negotiation leverage is altering promotional dependencies for branded shed lines.
- Direct Sales:Manufacturer-controlled channels capture full project value through manufactured-to-order production and captive installation crews. Regional producers in Texas and southeastern states defend market position via proprietary networks.
- Online Retail:E-commerce platforms gain share among small-format, DIY-assembly products with compressed delivery timelines. Modular flat-pack distribution enables geographic expansion without physical retail presence.
- Specialty Outlets:Independent dealers and farm supply retailers serve agricultural and commercial segments with application-specific expertise. Local builders retain significant presence against national distribution in fragmented markets.
Home improvement stores dominate volume throughput. Direct sales is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from Chinese resin compounders and US timber suppliers balance against import demand from European distributors and Australian retailers. Trade patterns concentrate around containerized flat-pack formats that minimize shipping cube and customs complexity. Regional regulatory divergence on pressure-treated lumber emissions and seismic engineering standards fragments product specifications across destination markets.
United States
Sun Belt suburban expansion in Texas, Florida, and Arizona generates sustained demand for large-format detached structures with engineered foundations. EPA emissions regulations on pressure-treated lumber accelerate manufacturer migration toward resin composites and galvanized steel alternatives. Dallas-Fort Worth and Houston metropolitan clusters anchor distribution networks for manufactured-to-order wooden structures with captive installation crews.
Germany
Home office conversion demand and garden equipment protection sustain residential pull for medium and large configurations with finished interiors. ECHA REACH compliance requirements for chemical emissions shape material sourcing decisions for wooden and resin product lines. Industrial concentration in North Rhine-Westphalia and Bavaria supports precision metal fabrication for modular steel shed components serving export markets.
China
Domestic demand for agricultural equipment protection and rural property improvement expands addressable volume beyond export manufacturing. GB standards for structural steel and plastic product safety establish baseline specifications for rotational-molded resin and corrugated metal formats. Yangtze River Delta manufacturing clusters in Zhejiang and Jiangsu provinces concentrate rotational molding capacity for UV-stabilized polyethylene storage units.
Australia
Bushfire-prone regions and coastal humidity drive specification shifts toward metal and resin alternatives over traditional timber construction. State-level building codes in New South Wales and Victoria mandate wind-load resistance and fire-safety ratings for permanent accessory structures. Sydney and Melbourne metropolitan corridors concentrate retail distribution through home improvement chains and direct-to-consumer online channels.
United Kingdom
Garden room conversions and remote work permanence elevate demand for insulated, electrified structures with HVAC rough-in capabilities. Planning permission requirements for outbuildings exceeding specified footprints create regulatory friction that favors modular, sub-threshold formats. Southeast England and Greater Manchester serve as logistics hubs for flat-pack distribution to both domestic consumers and European export channels.
Sheds and Outdoor Storage Market Competitive Landscape
On the supply side, the industry is bifurcated between mass-market resin and metal producers operating at scale and regional wooden structure fabricators with captive installation capabilities. Consolidation pressure concentrates volume leverage through home improvement retail channels, while fragmentation persists among local builders defending geographic territories. Two strategic archetypes dominate: vertically integrated resin compounders with rotational molding operations, and manufactured-to-order wooden specialists with proprietary crew networks. Competitive moves center on direct-to-consumer channel development and modular flat-pack distribution systems that bypass traditional retail markups.
Among US-based manufacturers, Lifetime Products exemplifies the integrated resin compounder archetype through upstream control over polyethylene formulation and molding operations. Tuff Shed anchors the manufactured-to-order wooden segment with regional production facilities and captive installation infrastructure. Keter, with European origins visible in its corporate structure, occupies a transatlantic position bridging resin manufacturing scale with retail distribution density across multiple continents.
| Leading Market Players |
|---|
| Lifetime Products |
| Suncast Corporation |
| Keter |
| Rubbermaid |
| ShelterLogic Group |
| Tuff Shed |
| Palram Applications |
| Arrow Storage Products |
| DuraMax Building Products |
| Others |
Value Network & Pricing Analysis
Lumber price volatility tethered to housing construction cycles compresses margin predictability for wooden shed producers while simultaneously widening pricing spreads between pressure-treated timber and resin composite alternatives. This input cost instability forces manufacturers to engineer supply chain flexibility through dual-sourcing strategies that balance Gulf Coast petrochemical feedstock access against domestic timber procurement networks.
Pricing Analysis
Residential homeowners anchor a three-tier pricing structure across premium, standard, and economy levels in the sheds and outdoor storage market. Price differentiation separates engineered wooden structures with site-specific foundation work from flat-pack resin units and galvanized steel alternatives. Cost compression in the economy tier is intensifying because resin rotational molding achieves manufacturing scale that wooden fabrication cannot match. Agricultural fleet buyers exhibit the highest price sensitivity, while residential customers seeking home office conversions demonstrate the lowest.
Supply Chain Analysis
UV-stabilized polyethylene compounding draws from Gulf Coast petrochemical infrastructure, while pressure-treated lumber sourcing centers on southern yellow pine mills across the southeastern United States and engineered wood product manufacturers in the Pacific Northwest. Raw material dependencies include polyethylene resin, galvanized steel coil, and EPA-compliant lumber treatments. Single-source vulnerability concentrates in rotational molding equipment supply, where European and Asian machinery builders dominate. Distribution runs through home improvement retail consolidation, with direct-to-consumer flat-pack channels gaining incremental share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward national home improvement chains as retail consolidation concentrates volume leverage, fragmenting supplier pricing autonomy and promotional calendar control across the sheds and outdoor storage sector.
For Market Incumbents: Pre-empt resin composite displacement by securing captive polyethylene compounding capacity or long-term offtake agreements with Gulf Coast petrochemical producers. Anchor position in California and Florida through Title 24 and wind-borne debris pre-engineering investments that create regulatory moats against unqualified entrants. Vertical integration into installation crew networks defends margin capture against retail channel disintermediation. For New Entrants and Emerging Players: Pursue modular flat-pack distribution as the most penetrable entry vector, targeting online retail channels for small-format DIY assembly products that bypass established retail markups. Geographic white space concentrates in Texas and Arizona suburban corridors where municipal zoning liberalization expands addressable lot coverage. Direct-to-consumer digital acquisition with containerized shipping economics enables geographic expansion without physical retail presence. For Investors and Strategic Acquirers: EPA-treated lumber emissions standards reshape the acquisition landscape by devaluing wooden structure fabricators without resin composite transition capabilities. Long-term viability favors vertically integrated compounders with rotational molding operations over regional wooden shed builders exposed to lumber price volatility. The signal to watch is municipal zoning ordinance velocity in Sun Belt states, as footprint restriction relaxations directly expand addressable market density.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Lifetime Products demonstrates how captive polyethylene formulation secures margin control against Gulf Coast feedstock volatility. |
| Pre-Engineered Code Compliance Investment | California Title 24 seismic and Florida wind-borne debris mandates create regulatory barriers that qualified producers exploit. |
| Modular Flat-Pack Distribution Development | Containerized shipping of unassembled components enables direct-to-consumer channels that bypass home improvement retail markups. |
| Captive Installation Crew Networks | Tuff Shed's proprietary on-site assembly infrastructure defends project value capture against channel disintermediation pressures. |
| EV Charging Infrastructure Adaptation | Climate-controlled structures with electrical rough-in specifications capture residential battery storage and vehicle electrification demand. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with residential contractors, home improvement retail category managers, municipal planning officials, and rotational molding plant engineers. Secondary validation drew from EPA emissions compliance filings, state-level building code amendments, customs trade data on polyethylene resin imports, and SEC disclosures from publicly held building products manufacturers. Bottom-up volume modeling across product type, end user, size, and distribution channel segments was triangulated against top-down macroeconomic indicators including housing starts and suburban development permit issuance.
Calibration across the analysis window employed regression-based demand elasticity modeling that incorporated lumber price index volatility, resin feedstock cost movements, and zoning ordinance liberalization velocity as independent variables. Segmentation dimensions modeled included material chemistry, installation complexity tier, geographic regulatory cluster, and channel markup structure. CAGRs were derived from iterative convergence of production capacity expansion announcements, retail square footage allocation trends, and permit pipeline data across Sun Belt metropolitan corridors.
Sensitivities concentrate around lumber price volatility, resin supply disruption from Gulf Coast weather events, and municipal zoning reversals in high-growth suburban counties. Cross-checking against Census Bureau housing starts data and American Housing Survey outdoor structure ownership rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Storage and Organization
Collapsible Wardrobe Market
Home Storage and Organization
Wardrobe Boxes Market
Home Storage and Organization
Hong Kong Self-Storage Market
Home Storage and Organization
United States Home Organizers and Storage Market
Home Storage and Organization
Closet Organizers Market
Home Storage and Organization
Flatware Holders and Organizers Market
Home Storage and Organization
United Kingdom Home Decor Market
Home Storage and Organization
Shoe Storage and Organizers Market
Home Storage and Organization
Display Cabinets Market
Home Storage and Organization
Flush Mount Photo Album Market
Home Storage and Organization
Slipcases Market
Home Storage and Organization
Tool Chest Market
Home Storage and Organization
Jewelry Organizer Market
Home Storage and Organization
Clothes Closets Market
Home Storage and Organization
Small Space Furniture Market
Home Storage and Organization
Scandinavia Self-Storage Market