
 Home Improvement Market | 2026-2036
Home Improvement Market Size, Share, and Industry Trends Forecast 2026-2036
Home Improvement Market Analysis
Market Context
North American residential construction capacity is reshaping supplier strategies across the home improvement value chain. The Home Depot leverages its last-mile delivery infrastructure to dominate pro-contractor segments in major metropolitan corridors. Lowe's Companies anchors its competitive stance through rural and suburban store density that competitors struggle to replicate. Floor & Decor Holdings specializes in hard-surface flooring assortment depth, carving defensible positioning against generalist retailers.
Technical Definition and Segment Structure
Home improvement encompasses the alteration, repair, modernization, and aesthetic enhancement of residential structures through materials such as low-VOC paint formulations, engineered hardwood flooring, LED luminaires with color-temperature adjustability, and water-efficient plumbing fixtures. These products and services preserve structural integrity, elevate energy performance, and extend functional lifespan of dwelling units. The product type dimension shows paint and flooring commanding the largest revenue pools due to repeat purchase frequency, while lighting benefits from electrification trends and smart-home integration. The service type dimension reveals installation and remodeling as margin-rich segments where labor scarcity protects pricing power, whereas repair maintains volume stability through weather-related damage cycles.
Regulatory Framework and Outlook
The EPA enforces lead-safe certification requirements under RRP rules that dictate contractor training and work-site containment protocols, directly shaping market access for painting and renovation professionals. OSHA standards govern residential construction site safety, influencing liability insurance costs and subcontractor qualification thresholds. The DOE's appliance efficiency regulations drive fixture replacement demand through minimum performance mandates. Stakeholders must monitor how building code adoption timelines across municipal jurisdictions create asynchronous demand windows for compliance-driven upgrades.
Market Dynamics
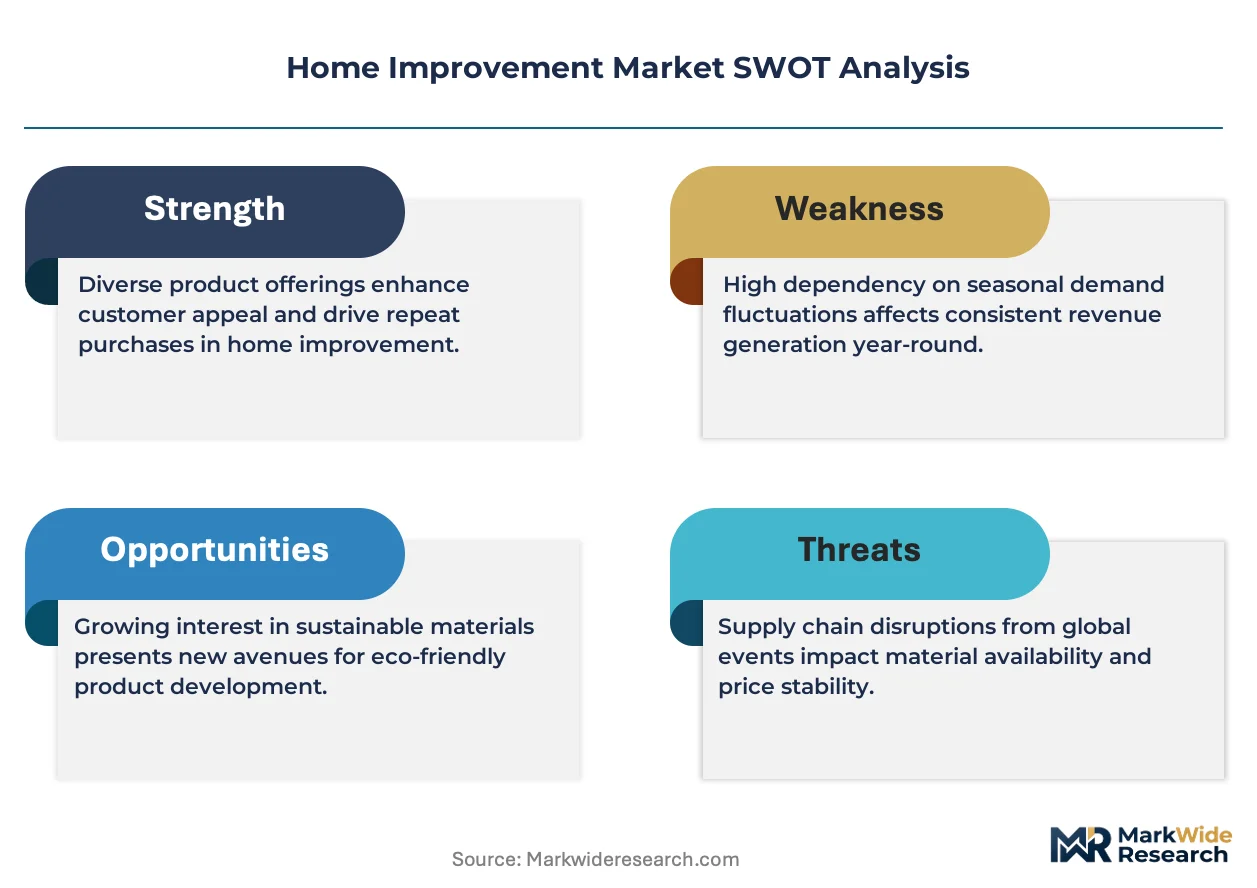
DIY adoption is accelerating as digital platforms compress skill acquisition curves and e-commerce infrastructure collapses distribution lead times for specialized materials.
Growth Catalysts
- EPA RRP Certification Mandate:Lead-safe work practices now required for pre-1978 housing renovations expand contractor training demand and certified service premiums.
- Electrification Retrofits:Heat pump installations and panel upgrades accelerate as utilities phase out natural gas hookups in new construction corridors.
- Aging Housing Stock:The median US home age exceeds 40 years, concentrating replacement demand for roofing, plumbing, and electrical systems.
Market Restraints
- Lumber Price Volatility:Softwood futures swings disrupt project budgeting and contractor margin stability across framing and decking segments.
- Adhesive Supply Concentration:Specialty construction adhesive production clusters in Gulf Coast petrochemical corridors, exposing availability to hurricane disruption cycles.
- Skilled Labor Scarcity:Electrician and plumber apprenticeship completion rates lag retirement outflows, extending project timelines and inflating wage costs.
Strategic Opportunities
- IRA Tax Credits:Residential clean energy credits up to 30% for efficiency upgrades and renewable installations unlock financing-constrained demand segments.
- Pro-Contractor Digital Platforms:B2B marketplaces integrating material procurement, project management, and payment processing capture wallet share from fragmented distributor networks.
- Water-Stressed Southwest:Xeriscaping and drought-tolerant irrigation system demand concentrates in Arizona, Nevada, and Colorado municipalities with usage restrictions.
Industry Challenges
- OSHA Silica Compliance:Respirable crystalline silica exposure limits impose dust suppression capital requirements on countertop fabrication and masonry contractors.
- Permit Approval Delays:Municipal building department backlogs extend project starts by 6-14 weeks in high-growth metropolitan jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Improvement Market |
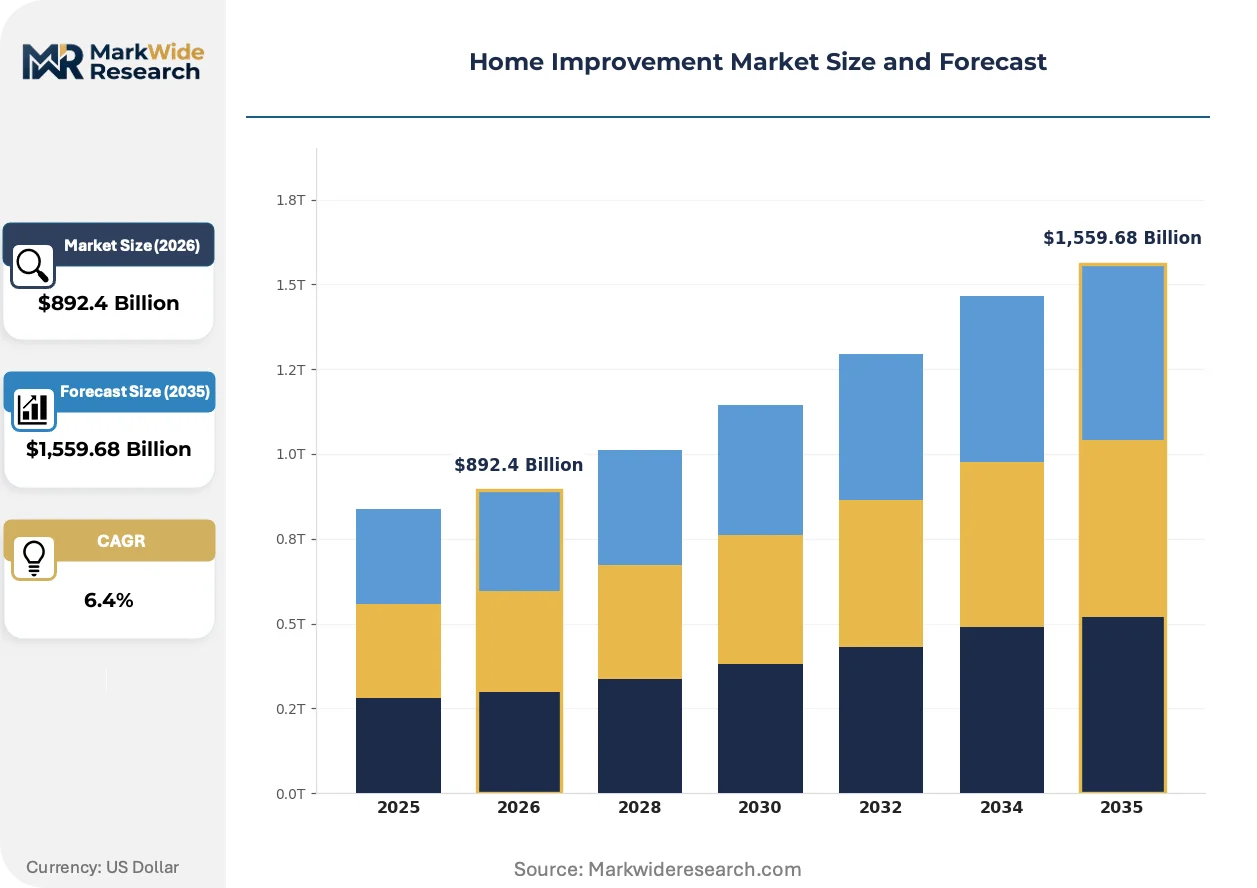
| Market Size in 2026 | $892.4 Billion |
| Market Size in 2035 | $1,559.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paint, Flooring, Lighting, Fixtures End User: Homeowners, Contractors, Property Managers, DIY Enthusiasts Service Type: Installation, Remodeling, Repair, Consultation Distribution Channel: Online, Retail Stores, Wholesale, Direct Sales |
| Companies Covered | BELFOR Holdings, Great Day Improvements, The Home Depot, DaBella, Power Home Remodeling, Lowe's Companies, Leaf Home, West Shore Home, Floor & Decor Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Improvement Market Emerging Trajectories
Material science advances and connected-device integration are compressing installation complexity while elevating performance expectations across residential renovation categories.
Cross-laminated timber (CLT) is migrating from commercial pilot projects to residential load-bearing applications as fire-rated assemblies gain code approval. Custom home builders in Pacific Northwest markets specify CLT for floor and roof systems to reduce on-site labor hours. This shift is compressing traditional stick-framing dominance in premium single-family segments.
DOE appliance efficiency standards phase in minimum performance thresholds for water heaters, HVAC equipment, and lighting fixtures through 2029. Manufacturers must redesign supply chains to eliminate non-compliant inventory ahead of effective dates. The replacement cycle concentrates in states with accelerated adoption timelines like California and New York.
Homeowners increasingly initiate projects through visualization tools that generate material takeoffs and labor estimates from smartphone-captured room dimensions. Big-box retailers and independent contractors compete to own this discovery-to-purchase funnel. The behavior shift is most pronounced in millennial first-time buyers renovating entry-level housing stock.
Home Improvement Market Segmentation
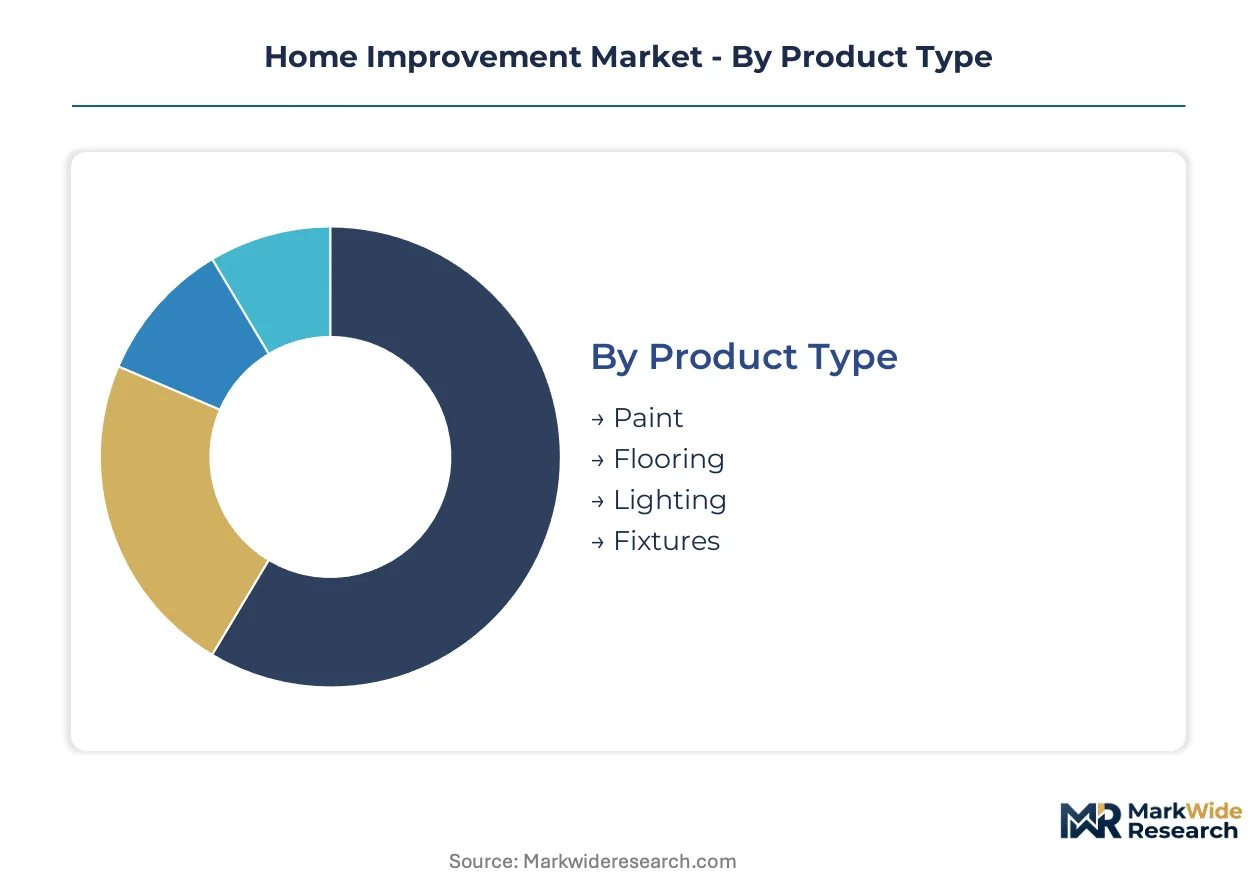
Segmentation in home improvement reveals how purchasing authority, project complexity, and channel preferences split value capture across the value chain. Understanding these divides allows suppliers to align inventory depth, service bundling, and pricing architecture with actual buyer behavior rather than assumed homogeneity.
Product Type:
Mature coatings and surfacing materials dominate revenue pools, while emerging smart-enabled categories reshape specification patterns in premium renovations.
- Paint:Low-VOC and zero-VOC formulations now command specification preference in pre-1978 housing renovations subject to EPA RRP lead-safe requirements. Repeat purchase frequency and color-refresh cycles sustain volume stability across residential repaint activity, with contractor-grade lines capturing pro-segment loyalty through bulk pricing and tint-matching reliability.
- Flooring:Engineered hardwood and luxury vinyl plank displace solid hardwood in moisture-prone applications, compressing installation skill requirements while extending product lifespan. Demand concentrates in aging housing stock replacement cycles across the United States, where subfloor condition issues favor floating installations over nail-down methods.
- Lighting:LED retrofits with color-temperature adjustability penetrate residential replacement markets as utility rebate programs and IRA tax credits offset upfront cost premiums.
- Fixtures:Water-efficient plumbing products face DOE efficiency mandates that accelerate replacement timelines in states with accelerated code adoption.
Paint handles the majority of throughput; lighting is gaining share fastest on electrification tailwinds.
End User:
Cost tier stratification separates professional-specified projects from self-directed renovations, with distinct service expectations and price sensitivity profiles.
- Homeowners:Owner-occupiers drive discretionary aesthetic upgrades and code-mandated repairs, with financing access determining project scope and material grade selection.
- Contractors:General and specialty contractors aggregate purchasing volume across multiple projects, demanding consistent availability, pro-grade durability, and streamlined logistics that support compressed construction schedules.
- Property Managers:Multi-unit portfolio operators prioritize total cost of ownership and warranty coverage over upfront material cost, specifying commercial-grade products for rental turnover durability.
- DIY Enthusiasts:Digital-native homeowners leverage tutorial platforms and e-commerce to bypass labor costs, concentrating demand in pre-finished materials and tool-rental adjacent categories.
Contractors absorb the largest share of material volume; DIY enthusiasts are expanding most quickly on digital enablement.
Service Type:
Application complexity determines margin architecture, with labor-intensive segments protecting pricing power through skilled trade scarcity.
- Installation:Professional fitting of flooring, fixtures, and lighting requires trade-licensed execution, with electrician and plumber availability constraints extending lead times and inflating wage rates in high-growth metropolitan corridors.
- Remodeling:Whole-room and whole-home renovations combine design services, material procurement, and multi-trade coordination, capturing premium margins through project management value-add.
- Repair:Weather-damage and system-failure response work maintains steady demand regardless of economic cycles, with insurance claim processing determining contractor selection in catastrophe-affected regions.
- Consultation:Design and energy-audit advisory services increasingly integrate with material sales, with big-box retailers and independent contractors competing to own the discovery-to-purchase funnel.
Installation commands the deepest margin pool; consultation is climbing the fastest as retailers bundle advisory with product sales.
Distribution Channel:
Geography and customer type determine channel preference, with density economics favoring distinct formats for urban versus rural access patterns.
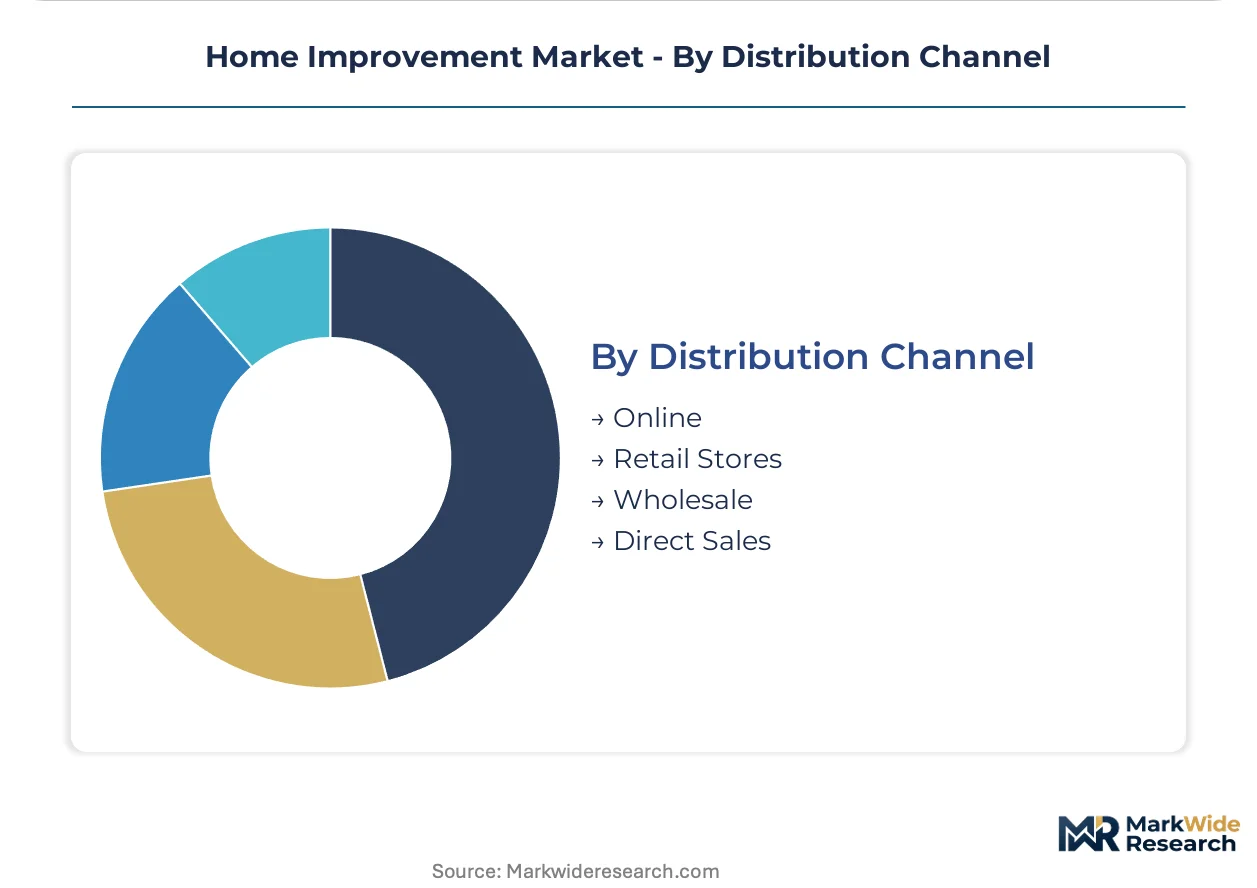
- Online:E-commerce platforms collapse distribution lead times for specialized materials, with visualization tools and material takeoff generators capturing millennial first-time buyer renovation demand.
- Retail Stores:Big-box and specialty retailers anchor last-mile availability for time-sensitive projects, with pro-desk services and bulk pickup options defending contractor loyalty against digital entrants.
- Wholesale:Distributor networks serve multi-location contractors and property management portfolios with credit terms and jobsite delivery that retail channels rarely match.
- Direct Sales:Manufacturer-direct and contractor-direct models bypass margin stacking in premium custom applications, with made-to-order flooring and fixture lines utilizing this channel for specification control.
Retail stores maintain the highest transaction velocity; online is expanding most quickly on digital-native buyer cohort maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA enforcement of lead-safe certification under RRP rules anchors contractor compliance requirements in the United States, where aging housing stock and hurricane reconstruction sustain continuous renovation activity across residential markets.
United States
Hurricane-driven reconstruction in Florida and Gulf Coast states sustains roofing and window replacement demand, while the EPA's Lead Renovation, Repair and Painting Rule mandates certified contractor training for pre-1978 housing work. The Inflation Reduction Act residential clean energy credits accelerate heat pump installations and panel upgrades in California and New York metropolitan corridors.
Germany
Building energy efficiency regulations under the EU Green Deal drive facade insulation and window replacement cycles in older housing stock, with the Federal Ministry for Economic Affairs and Climate Action administering renovation subsidy programs. Industrial clusters in North Rhine-Westphalia concentrate engineered wood product manufacturing serving cross-laminated timber residential applications.
China
Urban renewal programs in tier-one cities accelerate aging residential district modernization, with the Ministry of Housing and Urban-Rural Development setting green building standards for renovation projects. Manufacturing concentration in the Pearl River Delta supplies LED lighting and water-efficient fixtures for domestic replacement markets and export channels.
Japan
Seismic retrofit mandates for pre-1981 housing stock sustain structural reinforcement demand, with the Ministry of Land, Infrastructure, Transport and Tourism administering subsidy programs for earthquake-resistant upgrades. The Kanto region around Tokyo anchors specialized contractor networks for whole-home renovation and energy efficiency consulting services.
United Kingdom
Energy Performance Certificate upgrade requirements for rental properties drive insulation and heating system replacements, with the Department for Energy Security and Net Zero phasing out gas boiler installations in new construction. Greater London concentrates design-build firms integrating visualization tools with material procurement for residential renovation projects.
Home Improvement Market Vendor Landscape
Capability concentration sits with specialty retailers and installation service networks; scale advantage sits with big-box operators with last-mile infrastructure. The vendor base spans three tiers: national big-box retailers with pro-desk services, regional specialty retailers with category depth, and direct-to-consumer installation platforms with project management integration. Dominant competitive moves include geographic densification through small-format stores and backward integration into captive installation labor pools.
Within the big-box tier, The Home Depot and Lowe's Companies occupy positions defined by metropolitan corridor penetration and rural store density respectively. Floor & Decor Holdings exemplifies specialty depth strategy in hard-surface flooring assortment. Among installation-focused operators, BELFOR Holdings and Power Home Remodeling sit within the insurance restoration and whole-home renovation segments where project management capabilities defend margin structures.
| Leading Market Players |
|---|
| BELFOR Holdings |
| Great Day Improvements |
| The Home Depot |
| DaBella |
| Power Home Remodeling |
| Lowe's Companies |
| Leaf Home |
| West Shore Home |
| Floor & Decor Holdings |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Gulf Coast petrochemical corridors drives adhesive suppliers toward allocation-based pricing and extended lead times for specialty construction formulations, compressing contractor margins while elevating procurement urgency across residential renovation projects.
Pricing Analysis
Geographic price spreads between coastal metropolitan markets and inland secondary cities reflect last-mile delivery cost differentials and contractor density premiums. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and volume commitment, with EPA RRP-certified pro-grade lines commanding 15-25% premiums over consumer equivalents. Pricing pressure stems from lumber futures volatility disrupting project budgeting certainty. DIY enthusiasts exhibit highest price sensitivity, while multi-location contractors absorb premiums for inventory reliability.
Supply Chain Analysis
Contract manufacturing concentration sits with regional coating formulators in Ohio and Texas, engineered flooring producers in Southeast Asia, and LED assembly operations in Guangdong province. Raw material flows draw from Canadian softwood, Chinese rare earth phosphors, and German pigment chemistry. Single-source vulnerability concentrates in specialty adhesive feedstocks tethered to Gulf Coast petrochemical infrastructure. Distribution runs through big-box retail pro-desks and wholesale distributor networks with jobsite delivery capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated pro-contractor networks aggregating volume across multiple projects, fragmenting pricing leverage previously held by dispersed independent operators.
For Market Incumbents: Pre-empt margin erosion from digital-native procurement platforms by anchoring contractor loyalty through captive installation labor pools and exclusive pro-grade product lines. Backward integration into water-efficient fixture manufacturing defends specification control against private-label encroachment. Prioritize EPA RRP certification infrastructure as a competitive moat. For New Entrants and Emerging Players: Build out digital-first consultation services bundling visualization tools with material takeoff generation, targeting millennial first-time buyers in aging housing stock corridors. Xeriscaping and drought-tolerant irrigation systems in water-stressed Southwest municipalities represent the most penetrable white-space segment. Partner with utility rebate programs for go-to-market acceleration. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across smart-enabled lighting and fixture categories as Asian manufacturing scales. Long-term viability favors platforms integrating material procurement with project management software rather than pure retail plays. Target regional installation service networks with multi-trade coordination capabilities. Monitor IRA tax credit utilization rates as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Pro-Contractor Digital Platform Launch | Captures wallet share from fragmented distributor networks through integrated procurement and payment processing. |
| Backward Integration into Fixture Manufacturing | Secures margin control over water-efficient product lines facing DOE efficiency mandate acceleration. |
| Certified Installation Labor Pool Expansion | Defends pricing power in electrician- and plumber-constrained metropolitan corridors. |
| Utility Rebate Program Partnership | Unlocks financing-constrained demand segments for LED retrofits and heat pump installations. |
| Xeriscaping Service Line Introduction | Positions for drought-driven demand concentration in Arizona, Nevada, and Colorado municipalities. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with home improvement retailers, pro-contractor purchasing managers, and EPA RRP training providers; and secondary validation through customs trade records, SEC 10-K filings, and DOE appliance efficiency standard dockets. Bottom-up and top-down triangulation cross-checked material volume flows against end-use demand segmentation.
Forecast inputs span product type evolution, service type margin architecture, and channel shift dynamics across the projection horizon. Segmentation dimensions modeled include product category, end-user archetype, service complexity tier, and distribution channel. CAGRs derive from regression analysis against housing stock age, electrification policy intensity, and skilled labor availability indices.
Stress conditions across lumber price volatility, adhesive supply disruption, and permit approval delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of IRA tax credit utilization rates, EPA enforcement intensity, and municipal building department backlog indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Improvement and Renovation
Australia Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
Vietnam DIY Home Improvement Market
Home Improvement and Renovation
Residential Interior Wood Doors Market
Home Improvement and Renovation
External Blinds Market
Home Improvement and Renovation
Interior Doors Market
Home Improvement and Renovation
DIY Furnitures Market
Home Improvement and Renovation
Vietnam Home Improvement Market
Home Improvement and Renovation
Italy Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
DIY Home Decor Market
Home Improvement and Renovation
Home Improvement Services Market
Home Improvement and Renovation
Global DIY Home Improvement Market
Home Improvement and Renovation
Melamine Door Market
Home Improvement and Renovation
Bays and Bows Window Market
Home Improvement and Renovation
South Africa Do-It-Yourself (DIY) Home Improvement Retailing Market
Home Improvement and Renovation
US Home Remodeling Market
Home Improvement and Renovation
Automatic Curtain Market