
 Middle East and Africa Kitchen Storage Market | 2026-2036
Middle East and Africa Kitchen Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Kitchen Storage Market Foresight
Engineered bamboo and recycled polymer composites is rebalancing cost-performance trade-offs for cabinet carcasses across the Middle East and Africa. Hettich Holding GmbH & Co. oHG leverages its hardware systems expertise to anchor premium sliding mechanism demand in Saudi Arabian developments. nobilia sustains manufacturing scale advantages through its European production base serving African distributor networks. Inter IKEA Systems B.V. competes on flat-pack logistics efficiency, reducing landed costs in price-sensitive North African markets.
Kitchen storage encompasses modular and fixed systems designed to organize cookware, utensils, pantry goods, and cleaning supplies within food preparation environments, typically constructed from moisture-resistant particleboard with melamine facing, powder-coated steel, or injection-molded polypropylene rated for sustained load bearing. Cabinets dominate value capture given their structural role in kitchen fit-outs and higher per-unit pricing relative to baskets or racks. Metal segments show fastest volume expansion as Gulf hospitality projects specify stainless steel for durability under intensive use, while wood retains residential preference in Moroccan and Lebanese markets where artisanal finishing commands aesthetic premiums.
South Africa's National Regulator for Compulsory Specifications and the UAE's Emirates Authority for Standardization and Metrology enforce divergent testing protocols for load-bearing hardware and food-contact surfaces, fragmenting compliance costs for pan-regional suppliers. The EU Green Deal's extraterritorial REACH chemical restrictions affect imported European components, compelling Middle Eastern assemblers to verify coating and adhesive certifications. Stakeholders must monitor evolving Gulf standardization harmonization talks and decide whether to maintain dual certification systems or consolidate around stricter UAE benchmarks.
Market Dynamics
Hospitality-led demand across the Gulf Cooperation Council is compressing product lifecycles as operators trade up to stainless steel systems ahead of tourism capacity expansion. This procurement surge is reshaping supplier priorities toward durability certification and rapid-turnaround fit-out capability.
Growth Catalysts
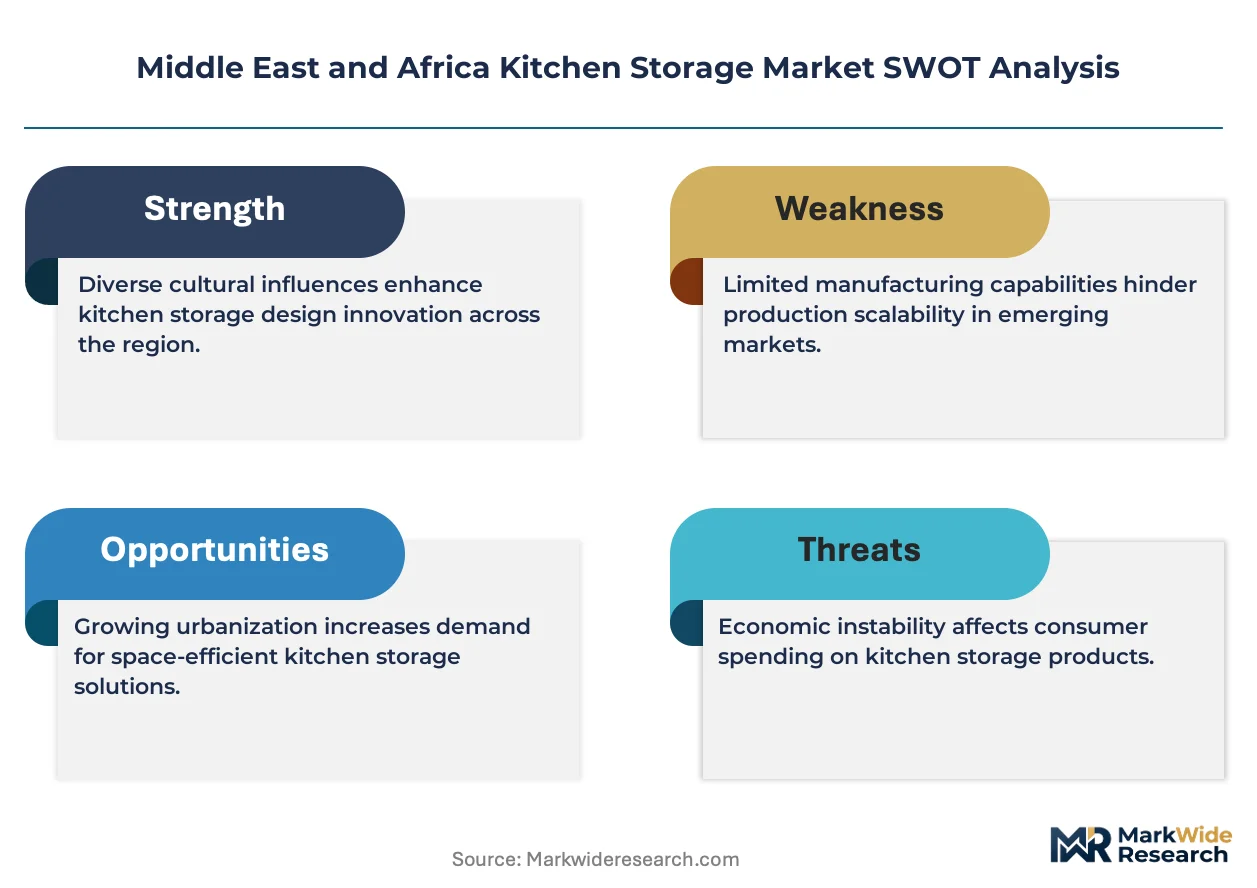
- REACH extraterritorial enforcement:The EU Green Deal's chemical restrictions on imported European components are compelling Middle Eastern assemblers to upgrade coating and adhesive certifications, creating premium-tier separation from uncertified competitors.
- Gulf tourism infrastructure:Saudi Arabian and Emirati hospitality operators are specifying commercial-grade kitchen storage systems for new hotel developments, pulling stainless steel demand ahead of residential cycles.
- Engineered bamboo substitution:Recycled polymer composites and bamboo-based carcass materials are penetrating mid-market cabinet segments as moisture-resistant alternatives to traditional particleboard.
Market Restraints
- Input cost volatility:Powder-coated steel and melamine-faced particleboard prices fluctuate with petrochemical feedstock indices, compressing margin predictability for regional distributors.
- Dual certification burden:South Africa's National Regulator for Compulsory Specifications and the UAE's Emirates Authority for Standardization and Metrology enforce non-harmonized load-bearing hardware tests, fragmenting compliance investment.
- Artisanal wood preference:Moroccan and Lebanese residential markets maintain aesthetic loyalty to hand-finished solid wood, limiting modular system penetration in high-value segments.
Strategic Opportunities
- North African flat-pack expansion:Logistics-optimized knockdown cabinet systems can capture price-sensitive demand in Algeria and Tunisia where landed cost sensitivity exceeds brand preference.
- Gulf standardization harmonization:Pending talks between Saudi, Emirati, and Qatari metrology authorities may yield unified certification protocols, reducing duplicate testing overhead for pan-regional suppliers.
- Smart hardware convergence:Sensor-integrated sliding mechanisms and app-connected pantry inventory systems are opening premium residential segments in Dubai and Riyadh.
Industry Challenges
- Certification timeline compression:South Africa's NRCS now demands accelerated compliance documentation for imported metalware, straining supplier quality assurance bandwidth.
- Legacy fit-out integration:Existing commercial kitchens in older Gulf properties use non-standard cabinet dimensions, complicating modular replacement rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Kitchen Storage Market |
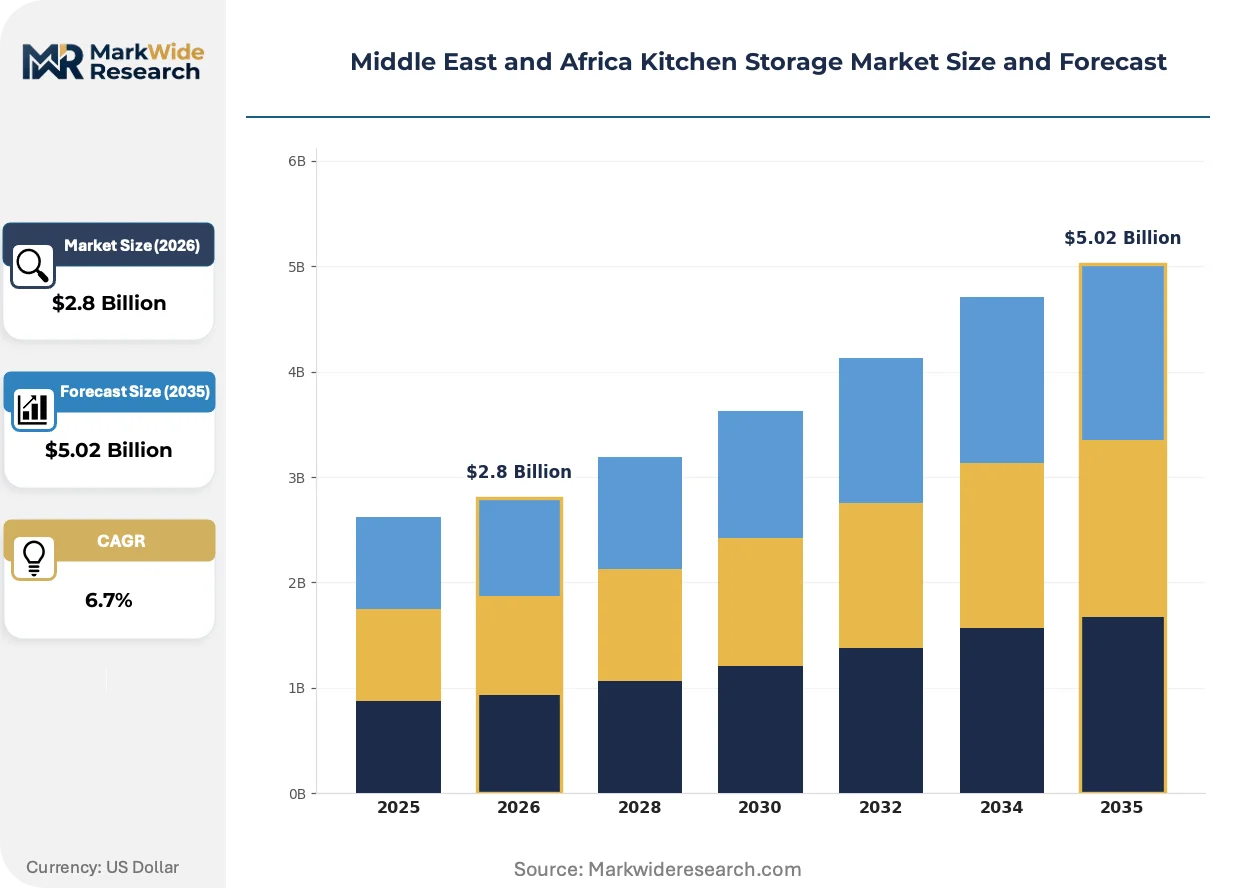
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baskets, Racks, Cabinets, Carts Material: Wood, Plastic, Metal, Glass End User: Residential, Commercial, Hospitality, Bakery Design Style: Modern, Rustic, Industrial, Vintage |
| Companies Covered | Inter IKEA Systems B.V., Rev-A-Shelf, Hettich Holding GmbH & Co. oHG, nobilia, Hafele GmbH & Co KG, Flywell International Corp, Masterclass Kitchens, Enclume Design Products, Kitchen Magic, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Kitchen Storage Market Shifts & Advancements
Material substitution and regulatory fragmentation are forcing simultaneous innovation in product chemistry and compliance architecture. Suppliers must now engineer for dual performance standards while compressing lead times.
Antimicrobial surface treatments integrated into stainless steel finishes are rewriting hygiene benchmarks for Gulf hospitality procurement. Saudi Arabian hotel operators are specifying these treatments as standard for back-of-house storage systems. The technology is compressing competitive differentiation around cleanability credentials rather than base material quality alone.
The UAE's Emirates Authority for Standardization and Metrology is tightening food-contact surface testing protocols for imported kitchen components. This regulatory pressure is diverting supply toward Emirati-certified assembly facilities. Pan-regional distributors are responding by consolidating final-stage finishing within UAE free zones to maintain market access.
Specifying behavior among large-scale developers is rotating toward outcome-based durability guarantees rather than component warranties. Dubai-based real estate operators now contract for fifteen-year functional performance across full kitchen storage systems. This shift is visible most acutely in master-planned community developments where fit-out standardization reduces long-term maintenance liability.
Middle East and Africa Kitchen Storage Market Segmentation
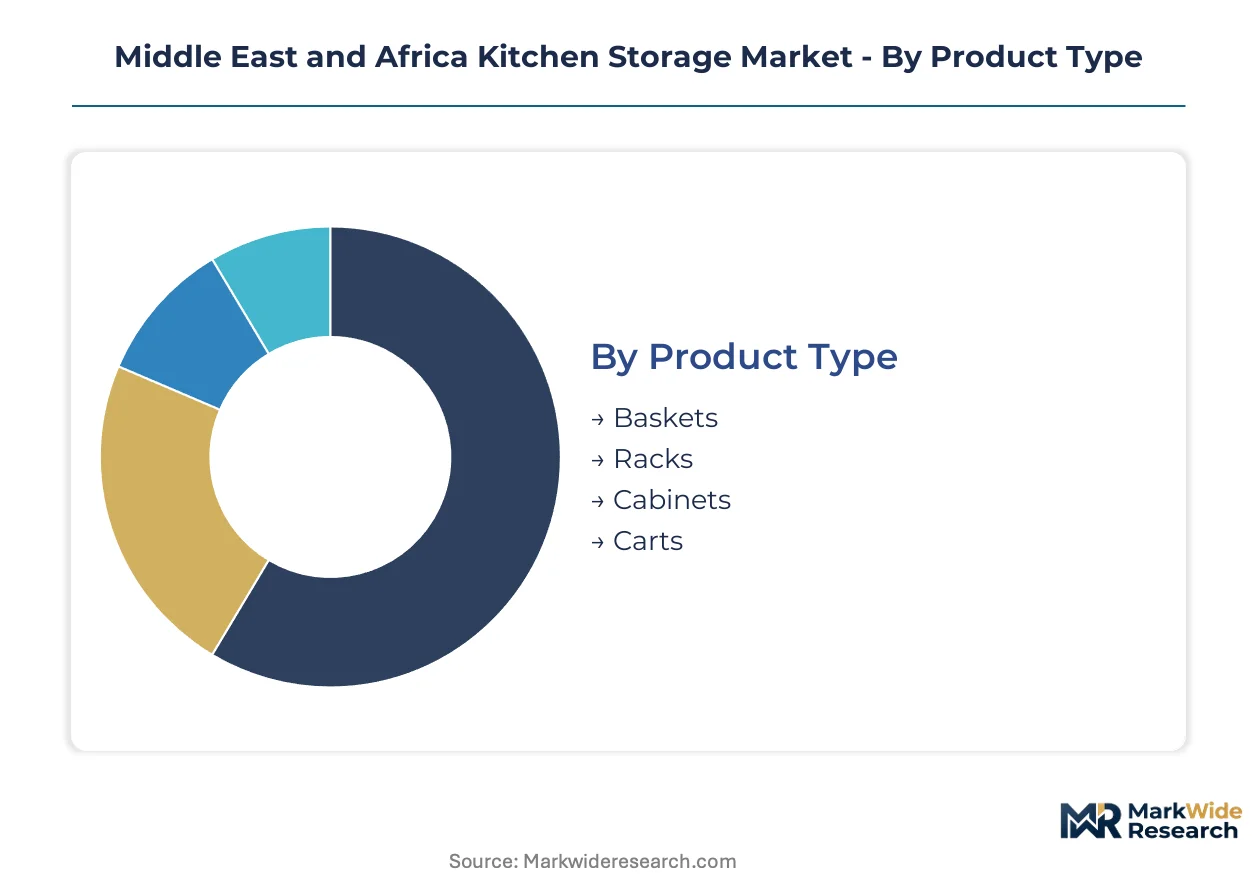
Kitchen storage procurement in the Middle East and Africa splits across performance tiers, aesthetic preferences, and regulatory exposure zones. Buyers weigh moisture resistance against certification burden differently across residential fit-outs and Gulf hospitality projects.
Product Type:
Cabinet systems command the highest per-unit spend and anchor fit-out specifications for developers and hospitality operators.
- Cabinets:Structural carcasses built from moisture-resistant particleboard with melamine facing or powder-coated steel framing dominate project tenders. Dubai's real estate pipeline and Saudi hotel developments specify these for fifteen-year functional performance guarantees.
- Baskets:Wire-formed chrome or epoxy-coated steel organizers for pantry and under-sink deployment. Moroccan and Lebanese residential markets favor these for retrofit compatibility in older kitchen footprints.
- Racks:Wall-mounted and freestanding systems for cookware and utensil storage. Gulf hospitality operators specify stainless steel variants for back-of-house durability under intensive use cycles.
- Carts:Mobile storage units with castor-mounted frames for flexible kitchen layouts. South African commercial bakeries and catering facilities deploy these for workflow reconfiguration.
Volume sits with Cabinets; growth tilts toward Racks as modular replacement cycles accelerate in aging Gulf properties.
Material:
Moisture exposure and load-bearing certification requirements split procurement between cost-optimized residential and durability-specified commercial channels.
- Metal:Powder-coated steel and stainless steel systems meet Emirates Authority for Standardization and Metrology food-contact surface protocols. Saudi and Emirati hospitality projects specify these for antimicrobial surface treatment compatibility.
- Wood:Solid timber and engineered bamboo carcasses retain preference in Moroccan and Lebanese residential markets where artisanal finishing commands aesthetic premiums. South Africa's NRCS enforces stricter imported metalware standards, diverting some residential demand toward certified timber alternatives.
- Plastic:Injection-molded polypropylene storage for budget residential and light commercial use. Algerian and Tunisian price-sensitive markets favor these for landed cost efficiency.
- Glass:Tempered glass shelving and display storage for premium residential segments. Dubai high-end developments specify these for visual lightness in open-plan kitchen designs.
Wood captures residential value share; Metal expands most quickly in Gulf hospitality procurement.
End User:
Fit-out scale and replacement frequency separate project-based demand from recurring consumer purchase cycles.
- Hospitality:Hotel and restaurant operators across the Gulf Cooperation Council specify commercial-grade stainless steel systems ahead of tourism capacity expansion. Antimicrobial surface treatments are becoming standard in Saudi back-of-house specifications.
- Residential:Individual homeowners and apartment buyers in UAE master-planned communities drive consistent cabinet procurement. Dubai's real estate pipeline feeds this channel through developer-fitted specifications.
- Commercial:Corporate cafeteria and institutional kitchen operators. South African facilities balance NRCS compliance costs against lifecycle durability.
- Bakery:Specialized storage for flour, ingredient, and finished goods handling. Mobility requirements favor cart-based systems in this segment.
Residential moves the highest unit volumes; Hospitality delivers the steepest expansion trajectory.
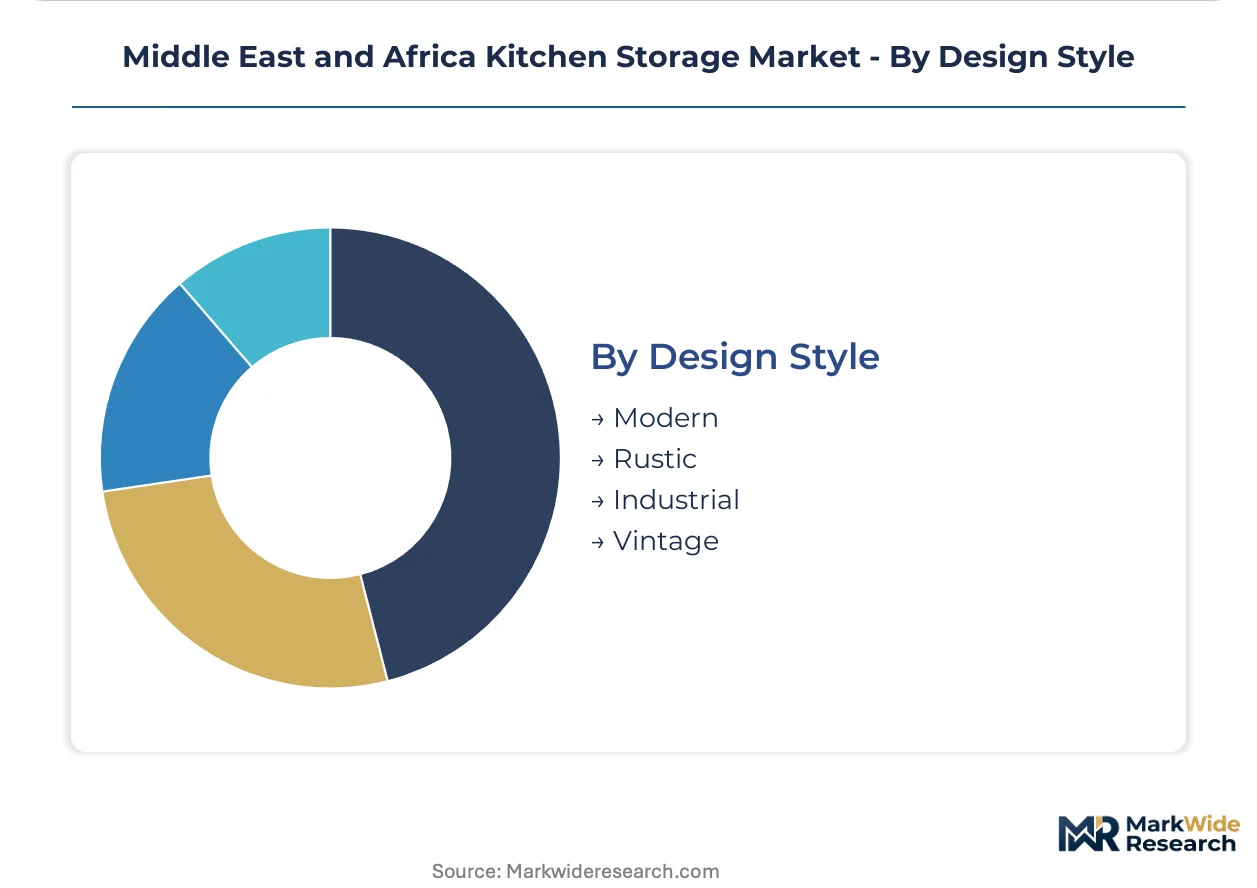
Design Style:
Aesthetic segmentation tracks regional taste formation and export manufacturing specialization.
- Modern:Clean-lined flat-panel cabinets with integrated hardware. UAE and Saudi new-build residential defaults to this style for standardization efficiency.
- Rustic:Distressed wood finishes and visible grain patterns. Moroccan residential markets maintain loyalty to hand-finished solid wood in this aesthetic.
- Industrial:Exposed metal framing and utilitarian hardware. Lebanese urban residential and commercial conversions favor this style.
- Vintage:Ornate detailing and period hardware references. Niche demand in heritage property renovations across North African markets.
Modern styling dominates new construction specification; Rustic retains its position in high-value artisanal segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United Arab Emirates, where Dubai's real estate pipeline feeds consistent residential and commercial kitchen equipment procurement. Saudi Arabia and South Africa follow as secondary volume anchors, each driven by distinct regulatory and infrastructure dynamics.
United Arab Emirates
Dubai's master-planned communities and hospitality expansion sustain premium cabinet procurement at scale. The Emirates Authority for Standardization and Metrology enforces tightening food-contact surface protocols, diverting supply toward Emirati-certified assembly facilities. Jebel Ali free zones host final-stage finishing operations to maintain market access compliance.
Saudi Arabia
Giga-project construction and tourism infrastructure rollout specify commercial-grade stainless steel storage systems. The Saudi Food and Drug Authority aligns with Gulf standardization harmonization talks for unified hardware certification. Riyadh and Jeddah development corridors anchor hospitality fit-out demand.
South Africa
Residential retrofit cycles and commercial bakery operations drive mid-market basket and cart procurement. The National Regulator for Compulsory Specifications enforces accelerated compliance documentation for imported metalware. Gauteng industrial zones concentrate distributor warehousing and certification handling.
Morocco
Artisanal wood finishing retains aesthetic preference in high-value residential segments, limiting modular system penetration. The country's national standards body maintains import quality protocols for European-sourced components. Casablanca and Marrakech urban developments balance traditional craft with modern flat-pack availability.
Lebanon
Urban residential conversions and commercial kitchen renovations sustain demand for industrial-styled metal systems. The country's central bank import licensing affects European hardware landed costs and availability timelines. Beirut's design-forward districts anchor specification influence for regional aesthetic trends.
Middle East and Africa Kitchen Storage Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with European-origin hardware specialists commanding premium positioning in Gulf hospitality while flat-pack assemblers capture North African price-sensitive demand. The vendor base organizes around three strategic archetypes: full-system European exporters, regional assembly specialists, and logistics-optimized knockdown distributors. Competitive moves concentrate on certification consolidation and free-zone assembly relocation to reduce compliance overhead.
Among German-origin hardware and cabinet specialists, Hettich Holding GmbH & Co. oHG, Hafele GmbH & Co KG, and nobilia occupy positions anchoring premium-tier specification in Saudi and Emirati developments. These GmbH-structured entities exemplify the European manufacturing base archetype serving African distributor networks through scaled production advantages. Inter IKEA Systems B.V. represents the logistics-optimized flat-pack model competing on landed cost efficiency in Algerian and Tunisian markets.
| Leading Market Players |
|---|
| Inter IKEA Systems B.V. |
| Rev-A-Shelf |
| Hettich Holding GmbH & Co. oHG |
| nobilia |
| Hafele GmbH & Co KG |
| Flywell International Corp |
| Masterclass Kitchens |
| Enclume Design Products |
| Kitchen Magic |
| Others |
Supply & Pricing Matrix
Fifteen-year functional performance guarantees demanded by Dubai-based real estate operators are forcing suppliers to absorb lifecycle cost risk into upfront pricing, compressing margin buffers and accelerating tier consolidation among assemblers.
Pricing Analysis
Volume concentrates in standard-grade melamine-faced particleboard cabinets serving UAE residential fit-outs, while margins accrue to antimicrobial-treated stainless steel systems specified for Saudi hospitality projects. Pricing stratifies across premium, standard, and economy tiers based on certification grade and hardware origin. Cost compression in mid-market segments is intensifying as engineered bamboo and recycled polymer composites displace traditional particleboard. Algerian and Tunisian buyers exhibit the sharpest landed-cost sensitivity, whereas Gulf hospitality operators prioritize durability certification over unit price.
Supply Chain Analysis
Reverse-logistics flows for cabinet hardware remain underdeveloped across the Middle East and Africa, though South African distributors are piloting refurbishment programs for commercial-grade metal storage systems. Manufacturing concentrates in Germany, Italy, and China, with European-origin components feeding premium Gulf hospitality specifications and Chinese-sourced knockdown kits supplying North African price-sensitive markets. Supply chains draw from petrochemical feedstocks for melamine and powder-coating resins, plus engineered timber and bamboo fiber for carcass materials. Single-source vulnerability sits with European hardware specialists dominating premium sliding mechanism supply. Distribution runs through Jebel Ali free zones for UAE compliance handling and Gauteng industrial zones for South African NRCS certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antimicrobial surface treatments and sensor-integrated hardware are displacing conventional stainless steel and manual sliding systems, creating a technology-transition window where certification-capable assemblers can capture premium positioning.
For Market Incumbents: To counter engineered bamboo and recycled polymer composite substitution in mid-market segments, Hettich and nobilia should deepen captive supply of certified hardware systems while consolidating final-stage finishing within UAE free zones to reduce Emirates Authority for Standardization and Metrology compliance overhead. For New Entrants and Emerging Players: Capture price-sensitive demand in Algeria and Tunisia through logistics-optimized flat-pack distribution partnerships, targeting residential retrofit cycles with knockdown cabinet systems that bypass European-origin premium positioning. For Investors and Strategic Acquirers: The window for entry favors regional assembly specialists with dual certification capability across UAE and South African protocols; monitor Gulf standardization harmonization talks for inflection signals on compliance cost consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| UAE Free-Zone Assembly Consolidation | Final-stage finishing within Jebel Ali maintains Emirates Authority for Standardization and Metrology market access. |
| Antimicrobial Surface Certification | Saudi Food and Drug Authority alignment positions suppliers for hospitality procurement standardization. |
| North African Flat-Pack Expansion | Knockdown logistics reduce landed costs in Algerian and Tunisian price-sensitive segments. |
| Dual Certification System Maintenance | Parallel UAE and South African NRCS compliance preserves pan-regional distributor flexibility. |
| Smart Hardware Integration | Sensor-integrated sliding mechanisms open premium residential segments in Dubai and Riyadh. |
Research Methodology
Multi-period observation of hospitality fit-out cycles, real estate pipeline completions, and regulatory enforcement patterns anchored the trend analysis, supplemented by interviews with kitchen equipment procurement managers at Gulf hotel operators, regulatory affairs specialists at South Africa's National Regulator for Compulsory Specifications, distributor principals in Moroccan and Lebanese markets, and technical directors at European hardware manufacturers. Secondary validation drew from Emirates Authority for Standardization and Metrology protocol documents, South African Bureau of Standards import records, Dubai Land Department construction permits, and EU Green Deal REACH restriction notices. Bottom-up project pipeline enumeration triangulated against top-down construction sector forecasts.
Segment-weighting applied product type, material composition, end-user category, and design style dimensions across the analysis window, with CAGRs derived from fitted trend extrapolation moderated by regulatory event probabilities. Input variables included tourism capacity expansion schedules, master-planned community delivery timelines, and harmonization negotiation status among Gulf metrology authorities.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Gulf standardization harmonization delays and petrochemical feedstock price volatility. Practitioners should monitor Saudi-Emirati certification protocol convergence and engineered bamboo cost curves for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Storage and Organization
Jewelry Organizer Market
Home Storage and Organization
Small Space Furniture Market
Home Storage and Organization
Shelf Display Trays Market
Home Storage and Organization
Shoe Storage and Organizers Market
Home Storage and Organization
Smart Shoe Cabinet Market
Home Storage and Organization
Kitchen Storage Market
Home Storage and Organization
Display Cabinets Market
Home Storage and Organization
Clothes Closets Market
Home Storage and Organization
Hong Kong Self-Storage Market
Home Storage and Organization
Smart Storage Cabinet Market
Home Storage and Organization
Europe Home Organizers and Storage Market
Home Storage and Organization
Wardrobe Boxes Market
Home Storage and Organization
Slipcases Market
Home Storage and Organization
Regency Shelving Market
Home Storage and Organization
Asia-Pacific Digital Home Locker Market
Home Storage and Organization
Closet Organizers Market