
 Smart Shoe Cabinet Market | 2026-2036
Smart Shoe Cabinet Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Shoe Cabinet Market Insights
Modular configuration is rebalancing buyer choice in the smart shoe cabinet space as consumers shift from fixed installations to expandable, stackable units that adapt to closet footprints. Haotian leverages its manufacturing scale to dominate the automated cabinet segment across Asian e-commerce channels. JOISCOPE competes through voice control integration, while RiverRidge anchors its position with sensor-enabled racks targeting premium residential buyers in North America.
A smart shoe cabinet is an electromechanical storage unit incorporating humidity sensors, UV sterilization modules, and wireless connectivity protocols to preserve footwear condition and enable remote inventory management. Units typically operate on 110-240V AC with standby power below 5W, utilizing PIR motion detection for automatic door actuation. Bluetooth connectivity and mobile app integration segments command the widest margin pools as consumers prioritize seamless smartphone control, while sensor-enabled racks represent the fastest-expanding category due to declining component costs. Automated cabinets remain the most mature segment, with established supply chains and standardized form factors limiting differentiation.
FCC certification governs wireless transmission protocols for US-bound units, while CE marking and RoHS compliance dictate material and electromagnetic standards for European market access. China's GB standards and MIIT radio regulations shape domestic product specifications and constrain import eligibility. Stakeholders must monitor evolving energy efficiency mandates and interoperability standards as regulatory fragmentation between regional smart home ecosystems intensifies procurement complexity.
Market Dynamics
Bluetooth connectivity and mobile app integration are compressing product lifecycles as manufacturers race to match smartphone ecosystem compatibility. The shift from fixed installations to modular, stackable configurations is redistributing value capture toward component suppliers and away from traditional cabinet assemblers.
Growth Catalysts
- Urban Space Constraints:Residential consumers in dense Chinese and German cities are prioritizing footprint-efficient storage solutions that maximize vertical space utilization.
- MIIT Radio Regulations:China's streamlined certification pathways for 2.4GHz wireless devices are accelerating domestic product iteration cycles and reducing time-to-market for connected cabinets.
- UV-C LED Cost Decline:Sterilization module prices have fallen sufficiently to enable mass-market tier inclusion without compromising margin structures.
Market Restraints
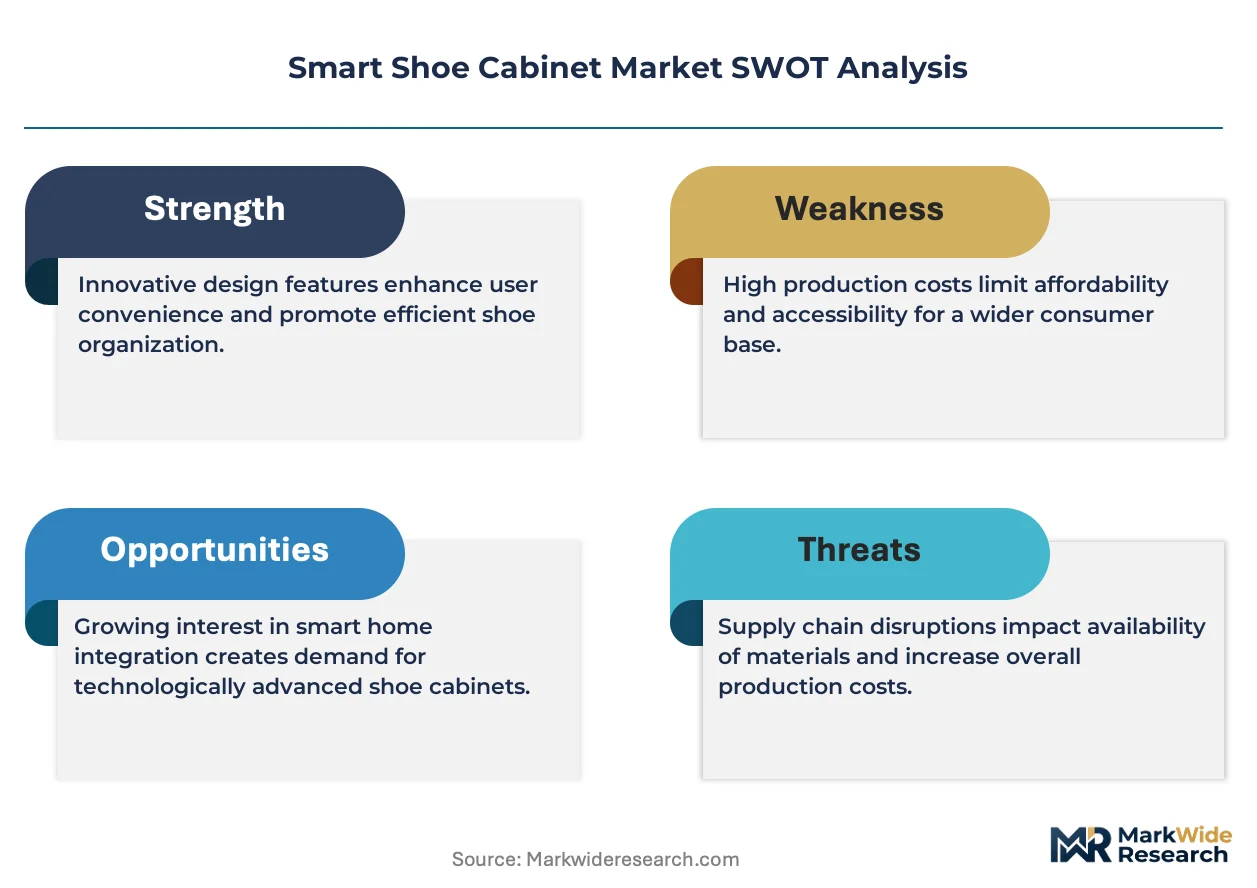
- Semiconductor Supply Concentration:PIR motion sensors and Bluetooth SoCs depend heavily on Taiwanese and South Korean foundry capacity, exposing manufacturers to allocation volatility.
- RoHS Compliance Friction:European material restrictions on lead-free solder and flame retardants are elevating BOM costs and disqualifying legacy Asian supply chains.
- Substitute Storage Solutions:Vacuum-sealed containers and passive dehumidifier boxes retain cost advantages in price-sensitive segments, limiting smart cabinet penetration below premium tiers.
Strategic Opportunities
- India Residential Expansion:BIS certification harmonization with IEC standards is lowering import barriers for connected home appliances in tier-one cities.
- Voice-AI Convergence:Integration of natural language processing with humidity control algorithms enables hands-free operation for accessibility-focused buyers.
- Direct-to-Consumer Channels:Brand-owned e-commerce platforms are bypassing traditional furniture retail markups and capturing first-party usage data for predictive maintenance services.
Industry Challenges
- FCC Certification Timelines:Wireless protocol testing for US market entry typically spans 12-16 weeks, compressing seasonal launch windows and straining working capital.
- Legacy HVAC Integration:Smart cabinets must communicate with existing residential climate control systems through fragmented proprietary protocols, multiplying firmware development overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Shoe Cabinet Market |
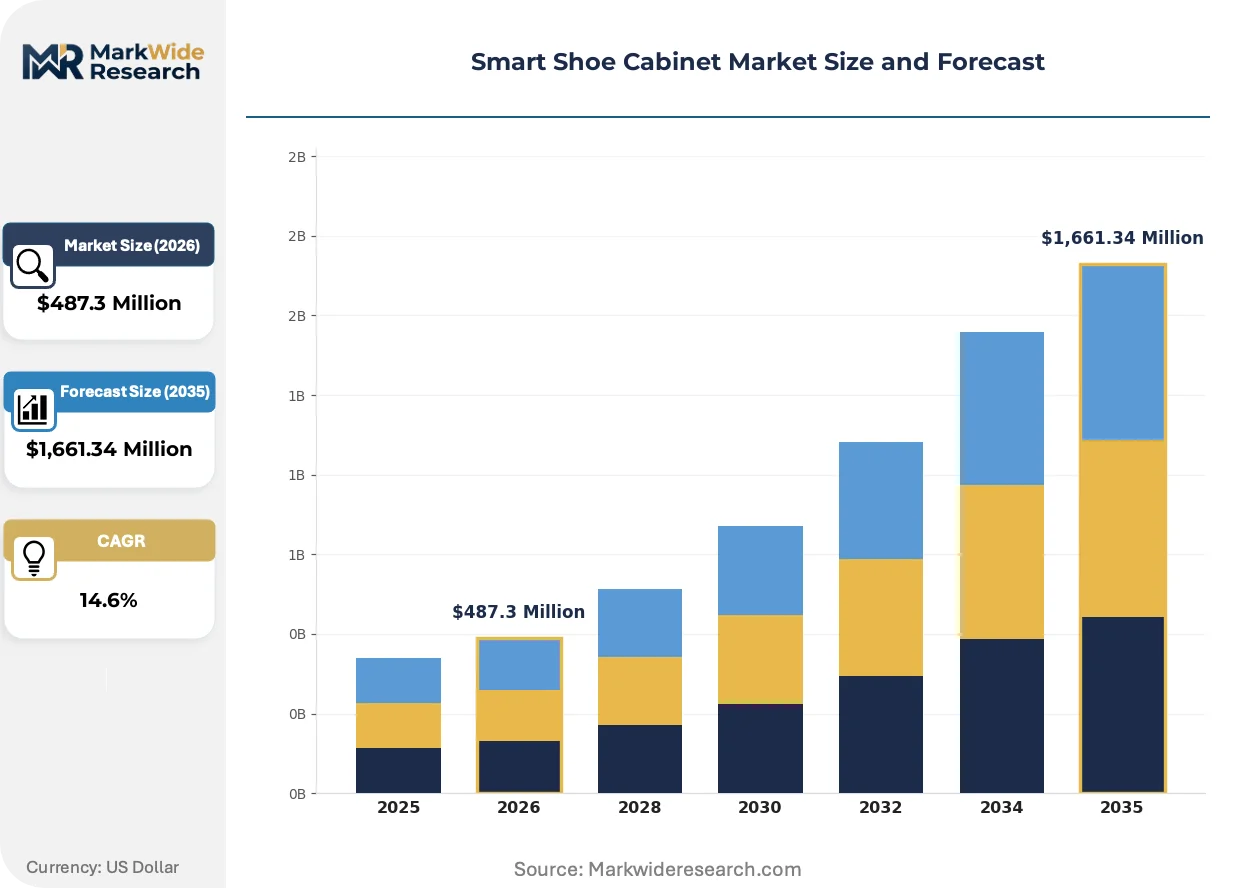
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,661.34 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Cabinets, Smart Closets, IoT Shoe Storage, Sensor-Enabled Racks Technology: Bluetooth Connectivity, Mobile App Integration, Voice Control, Smart Sensors End User: Residential Consumers, Retail Outlets, Hotels, Sports Facilities Distribution Channel: Online Retailers, Brick-and-Mortar Stores, Direct Sales, E-commerce Platforms |
| Companies Covered | Haotian, JOISCOPE, RiverRidge, Blissun, SIMPDIY, Sunshine Megastore, Baxton Studio, ClosetMaid, K KELBEL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Shoe Cabinet Market Trends and Innovations
Product functionality is bifurcating between hygiene-centric sterilization systems and inventory-management platforms, with divergent R&D investment requirements. This schism is fragmenting the vendor landscape into specialized sub-assemblers rather than integrated solution providers.
Photocatalytic oxidation modules are integrating with PIR-triggered activation circuits to deliver on-demand odor neutralization without continuous energy draw. High-rise apartment dwellers in Shanghai and Shenzhen are adopting these configurations fastest, where ventilation limitations intensify footwear degradation risks. The technology is integrating humidity sensing with sterilization cycles, compressing standalone dehumidifier demand within closet-adjacent categories.
REACH substance restrictions on perfluorinated compounds are forcing adhesive and coating reformulations for interior cabinet surfaces. Manufacturers serving EU-bound shipments are qualifying water-based alternatives that extend curing times but satisfy ECHA registration requirements. Premium residential segments absorb these cost increments most readily, while economy-tier suppliers are diverting volume toward Middle Eastern and Southeast Asian markets with less stringent chemical governance.
Subscription-based filter replacement programs are displacing transactional component sales as the dominant aftermarket revenue model. Property management companies operating multifamily housing in Texas and Florida are negotiating fleet-level service contracts that bundle hardware, connectivity, and consumables into per-unit monthly fees. This arrangement shifts capital expenditure to operating budgets and accelerates deployment velocity in build-to-rent developments.
Smart Shoe Cabinet Market Segmentation
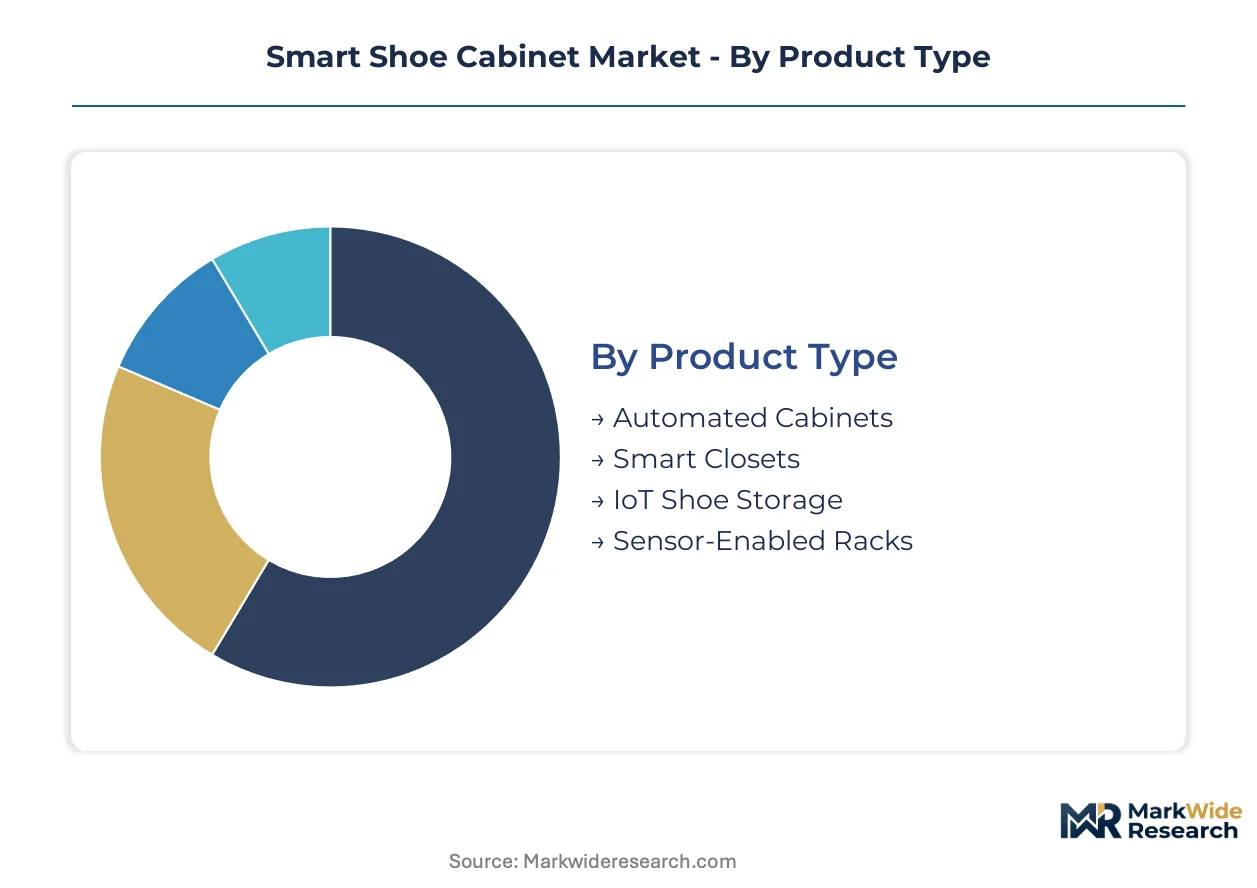
Smart shoe cabinet segmentation reveals divergent capital requirements across hardware configurations, with electromechanical complexity and connectivity integration driving fundamentally different investment profiles. Understanding these structural divisions exposes where margin pools concentrate and which technology trajectories reshape competitive positioning.
Product Type:
Capital intensity escalates sharply with electromechanical sophistication, as motorized components and integrated climate systems multiply upfront tooling and certification costs.
- Automated Cabinets:Fully motorized units with servo-driven shelving, UV-C sterilization chambers, and humidity-controlled compartments require substantial die-casting and PCB assembly investment. Demand clusters in premium residential towers across Shanghai, Shenzhen, and Frankfurt where space constraints justify four-figure price points.
- Smart Closets:Walk-in configurations integrating shoe storage with broader wardrobe management systems demand the highest per-unit capital deployment. German and Japanese luxury developers specify these in high-end multifamily projects, though extended sales cycles strain working capital.
- IoT Shoe Storage:Connected modular bins with cloud-linked inventory tracking.
- Sensor-Enabled Racks:PIR-triggered LED illumination with basic humidity monitoring.
Automated cabinets absorb the bulk of installed capacity; sensor-enabled racks are expanding most quickly.
Technology:
Connectivity protocol selection determines ongoing R&D burn rates and ecosystem partnership requirements, with platform-specific integration costs fragmenting development resource allocation.
- Bluetooth Connectivity:Low-energy 5.0/5.2 modules enable smartphone proximity control and firmware updates without WiFi infrastructure dependency. Chinese OEMs leverage MIIT streamlined certification to compress development timelines, though FCC testing for US-bound units extends launch windows.
- Mobile App Integration:Native iOS and Android applications with inventory photography, wear-tracking algorithms, and filter replacement scheduling command recurring cloud infrastructure expenditure. North American and South Korean consumers demonstrate strongest willingness-to-pay for subscription-enabled feature sets.
- Voice Control:Alexa and Google Assistant compatibility requiring natural language processing middleware.
- Smart Sensors:Multi-parameter environmental monitoring with MEMS-based humidity, temperature, and VOC detection.
Mobile app integration captures the widest margin expansion; voice control is climbing the fastest as accessibility requirements harden in building codes.
End User:
Procurement authority and replacement cycle velocity vary dramatically across buyer categories, with B2B fleet deployments offering scale economies that offset lower per-unit pricing.
- Residential Consumers:Individual purchasers prioritizing footprint efficiency and footwear preservation in urban apartments. Chinese tier-one city dwellers and German condominium owners drive volume, with purchase decisions heavily influenced by smart home ecosystem compatibility.
- Retail Outlets:Footwear boutiques and department stores deploying customer-facing units for try-on hygiene and inventory display.
- Hotels:Guest room and concierge installations requiring hospitality-grade durability certifications and centralized fleet management.
- Sports Facilities:Gym and stadium locker room deployments with high-cycle usage patterns and vandalism-resistant specifications.
Residential consumers anchor absolute unit demand; hotels are gaining share fastest through property management company fleet contracts.
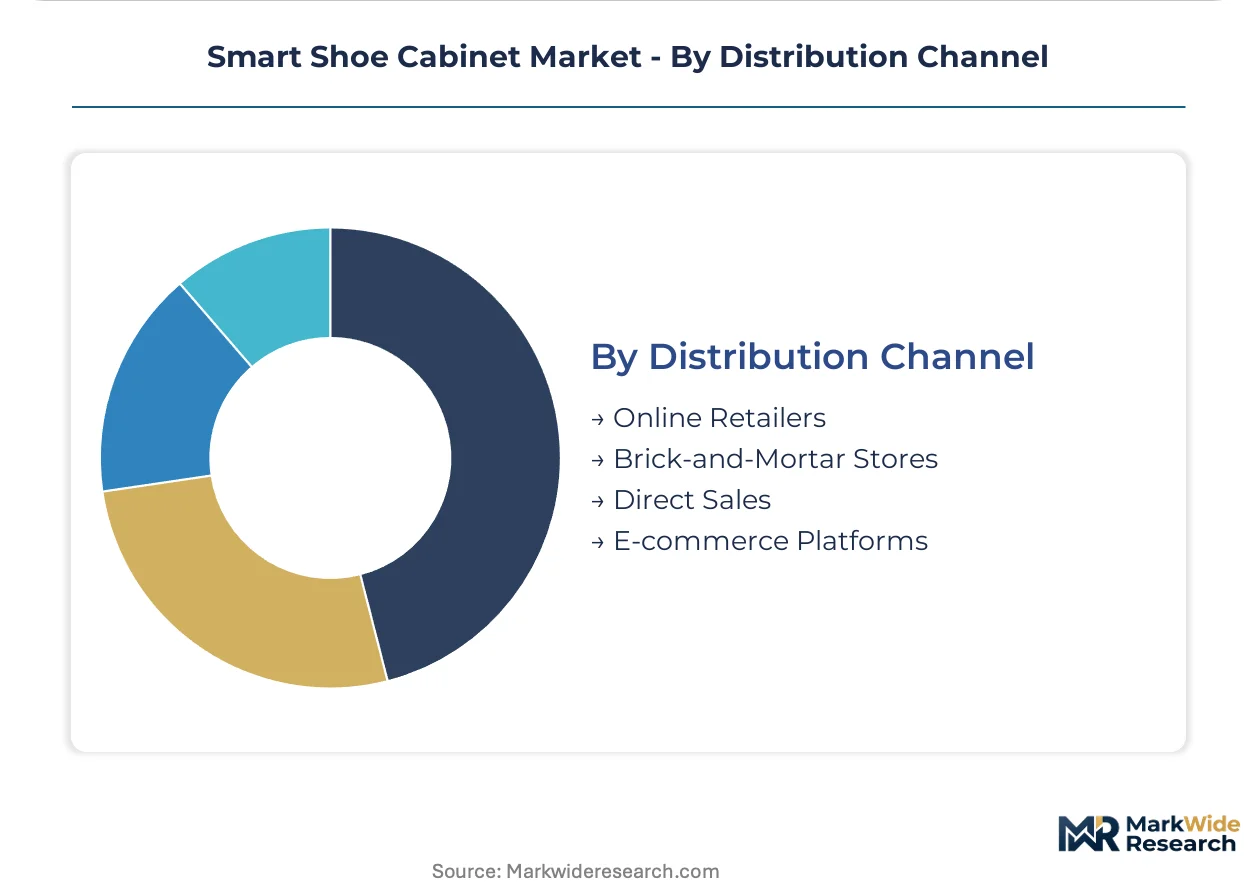
Distribution Channel:
Channel selection dictates working capital intensity and customer data ownership, with direct relationships enabling predictive maintenance revenue streams that third-party retail cannot replicate.
- Online Retailers:Amazon, Tmall, and JD.com listings with algorithmic discoverability and review-driven conversion. Chinese brands dominate this channel through domestic platform optimization, though return logistics for bulky electromechanical units erode net margins.
- Brick-and-Mortar Stores:Furniture retailers and home improvement chains offering tactile demonstration and white-glove delivery coordination. German and Japanese consumers exhibit persistent preference for in-person configuration consultation.
- Direct Sales:Manufacturer-owned websites with first-party data capture and subscription bundling.
- E-commerce Platforms:Dedicated smart home verticals and crowdfunding pre-order campaigns.
Online retailers move the greatest unit volume; direct sales are expanding most quickly as brands prioritize recurring revenue attachment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Shenzhen and Shanghai concentrate smart shoe cabinet manufacturing capacity, drawing component suppliers into clustered logistics corridors that accelerate export certification timelines.
China
MIIT radio regulations streamline 2.4GHz device certification, compressing development cycles for Bluetooth-enabled units. GB standards govern electromagnetic compatibility and energy efficiency, shaping domestic product specifications. Shenzhen manufacturers leverage Pearl River Delta electronics ecosystems to integrate UV-C LED modules at declining cost points.
Germany
CE marking and RoHS compliance elevate material standards for lead-free solder and flame retardants, disqualifying legacy Asian supply chains. REACH substance restrictions force adhesive reformulations for interior cabinet surfaces. Frankfurt and Munich anchor premium residential demand, where space-constrained condominium owners prioritize footprint-efficient storage solutions.
United States
FCC certification governs wireless transmission protocols, with testing timelines spanning 12-16 weeks and compressing seasonal launch windows. Texas and Florida property management companies negotiate fleet-level service contracts for multifamily housing developments. California and New York Metro urban apartments drive residential adoption as vertical space utilization intensifies.
Japan
METI energy efficiency mandates shape standby power requirements below 5W for connected appliances. JIS standards dictate durability specifications for electromechanical components in high-humidity environments. Tokyo and Osaka high-rise developments specify integrated smart storage in luxury multifamily projects, though extended sales cycles strain working capital.
South Korea
MFDS and related agencies monitor consumer product safety for electromechanical storage units. Seoul Capital Area consumers demonstrate strongest willingness-to-pay for subscription-enabled mobile app features. Busan-Ulsan manufacturing corridors supply MEMS-based humidity sensors to regional OEMs, reducing component lead times.
Smart Shoe Cabinet Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the smart shoe cabinet landscape, creating a tiered structure where scale advantages clash with agility. The vendor base organizes around three archetypes: integrated furniture conglomerates with captive distribution, electromechnical specialists leveraging component cost declines, and direct-to-consumer brands capturing first-party data. Dominant competitive moves include backward integration into sensor module supply and geographic expansion through e-commerce platform optimization.
Among Asian manufacturers, Haotian exemplifies scale-driven automated cabinet production, while JOISCOPE occupies a position within voice-control integration specialists. RiverRidge anchors the North American premium residential segment through sensor-enabled rack configurations. These three represent divergent strategic postures: manufacturing scale, connectivity ecosystem alignment, and regional market anchoring respectively.
| Leading Market Players |
|---|
| Haotian |
| JOISCOPE |
| RiverRidge |
| Blissun |
| SIMPDIY |
| Sunshine Megastore |
| Baxton Studio |
| ClosetMaid |
| K KELBEL |
| Others |
Pricing and Supply Chain Analysis
Electromechanical engineering talent concentration in the Pearl River Delta creates labor-cost differentials that widen pricing-tier spreads between Shenzhen-manufactured economy units and German-assembled premium cabinets. Component sourcing proximity compresses material costs for Asian producers while European RoHS compliance elevates BOM thresholds, fragmenting competitive positioning across cost structures.
Pricing Analysis
Lead-time premiums reward rapid fulfillment while spot inventory trades at discounts in Chinese e-commerce channels. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in the sensor-enabled rack segment intensifies as MEMS module prices decline. Residential consumers in tier-one Chinese cities exhibit highest price sensitivity; German luxury developers demonstrate lowest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from North American property management companies mandate multi-supplier qualification for PIR motion sensors and Bluetooth SoCs. Manufacturing concentrates in China, Taiwan, and South Korea, drawing from UV-C LED modules, humidity sensors, and electromechanical actuators. Single-source vulnerability in Taiwanese foundry capacity for sensor silicon exposes allocation volatility. Distribution runs through brand-owned e-commerce platforms and Amazon-Tmall algorithmic marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as FCC certification timelines and semiconductor supply concentration force capital-constrained assemblers toward exit or acquisition.
For Market Incumbents: Anchor defensive positioning through backward integration into sensor module supply and captive certification capacity in Shenzhen free trade zones. Haotian-scale manufacturers should compress development cycles using MIIT streamlined pathways while RoHS-compliant European production insulates against REACH substance restriction volatility. Channel control through direct-to-consumer platforms captures first-party data for predictive maintenance attachment. For New Entrants and Emerging Players: Property management companies in Texas and Florida represent the most penetrable channel partner type for fleet-level service contract penetration. White-space targets include India tier-one cities post-BIS harmonization and voice-AI convergence for accessibility-focused buyers. Direct sales platforms with subscription bundling offer the cleanest go-to-market angle against established retail markups. For Investors and Strategic Acquirers: Re-rating potential sits with electromechanical specialists possessing captive sensor supply given UV-C LED cost decline acceleration. Long-term viability favors vendors with backward integration depth and multi-regional certification capacity. Watch BIS-IEC harmonization progress in India as inflection indicator for emerging market deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Modules | Captive supply of PIR and MEMS components insulates against Taiwanese foundry allocation volatility. |
| Multi-Regional Certification Capacity | Simultaneous FCC, CE, and MIIT qualification compresses seasonal launch windows for seasonal footwear cycles. |
| Direct-to-Consumer Platform Launch | First-party data capture enables predictive maintenance subscription revenue beyond transactional hardware sales. |
| Voice-AI Convergence Development | Alexa and Google Assistant integration addresses accessibility requirements hardening in multifamily building codes. |
| Fleet Service Contract Expansion | Property management company bundles in Texas and Florida shift capital expenditure to operating budgets. |
Research Methodology
Document review covered customs and trade databases, smart home appliance SEC filings, and MIIT radio equipment certification records, complemented by interviews with connected furniture product managers, electromechanical component procurement leads, smart home platform engineers, and multifamily property management executives. Secondary validation drew from FCC equipment authorization filings, REACH substance restriction updates, and Pearl River Delta manufacturing cluster reports. Bottom-up unit shipment modeling and top-down market value triangulation anchored quantitative outputs.
Cross-referencing historical certification timeline patterns against industry panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type electromechanical complexity, connectivity protocol ecosystem alignment, end-user procurement authority, and distribution channel data ownership structure. CAGRs derived from unit trajectory analysis and value-per-unit expansion assumptions incorporating UV-C LED cost curves and mobile app subscription attachment rates.
Caveats apply where semiconductor supply allocation volatility or REACH adhesive reformulation delays could materially shift the outlook. Deviation in FCC certification timeline compression or BIS-IEC harmonization progress would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Storage and Organization
Scandinavia Self-Storage Market
Home Storage and Organization
Collapsible Wardrobe Market
Home Storage and Organization
Shoe Rack Market
Home Storage and Organization
Closet Organizers Market
Home Storage and Organization
Kitchen Storage Market
Home Storage and Organization
Toy Storage Market
Home Storage and Organization
Smart Storage Cabinet Market
Home Storage and Organization
Shelf Display Trays Market
Home Storage and Organization
Jewelry Organizer Market
Home Storage and Organization
Small Space Furniture Market
Home Storage and Organization
Shop Shelving Market
Home Storage and Organization
Slipcases Market
Home Storage and Organization
Wardrobe Boxes Market
Home Storage and Organization
Shoe Storage and Organizers Market
Home Storage and Organization
Flatware Holders and Organizers Market
Home Storage and Organization
Sheds and Outdoor Storage Market