
 Kitchen Storage Market | 2026-2036
Kitchen Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Kitchen Storage Market Foresight
Urban homeowners are rotating toward modular, space-efficient kitchen storage systems as apartment living expands in dense metropolitan areas. IKEA leverages its flat-pack logistics network to dominate entry-level modular cabinet segments across North America and Europe. The Container Store sustains premium positioning through customized closet and pantry systems that command higher margins. Newell Brands anchors mass-market penetration via Rubbermaid's ubiquitous presence in food storage containers at big-box retailers.
Kitchen storage encompasses fixed and movable systems engineered to organize cookware, dry goods, utensils, and small appliances within residential and commercial food preparation environments. Cabinet systems typically employ engineered wood substrates with thermofoil or lacquer finishes rated for moisture resistance, while metal shelving utilizes powder-coated steel to withstand load capacities exceeding 150 kilograms per tier. Wood-based cabinets occupy the largest value share due to replacement cycles in existing housing stock, though metal racks represent the fastest-expanding category as consumers adopt open-concept kitchen aesthetics. Plastic bins maintain volume leadership in pantry organization driven by transparency and stackability, while glass containers capture premium food storage segments where chemical-free preservation matters.
The EPA oversees formaldehyde emissions standards for composite wood products used in cabinet construction, while the EU Ecodesign Directive mandates recyclable material content thresholds for household storage products sold in member states. California's Air Resources Board maintains the strictest state-level composite wood emissions regulations, effectively setting the compliance floor for North American manufacturers. Stakeholders must monitor evolving extended producer responsibility frameworks in Europe and emerging state-level chemical disclosure requirements in the northeastern United States, as these will determine which material formulations and supply chain configurations sustain market access without reformulation costs.
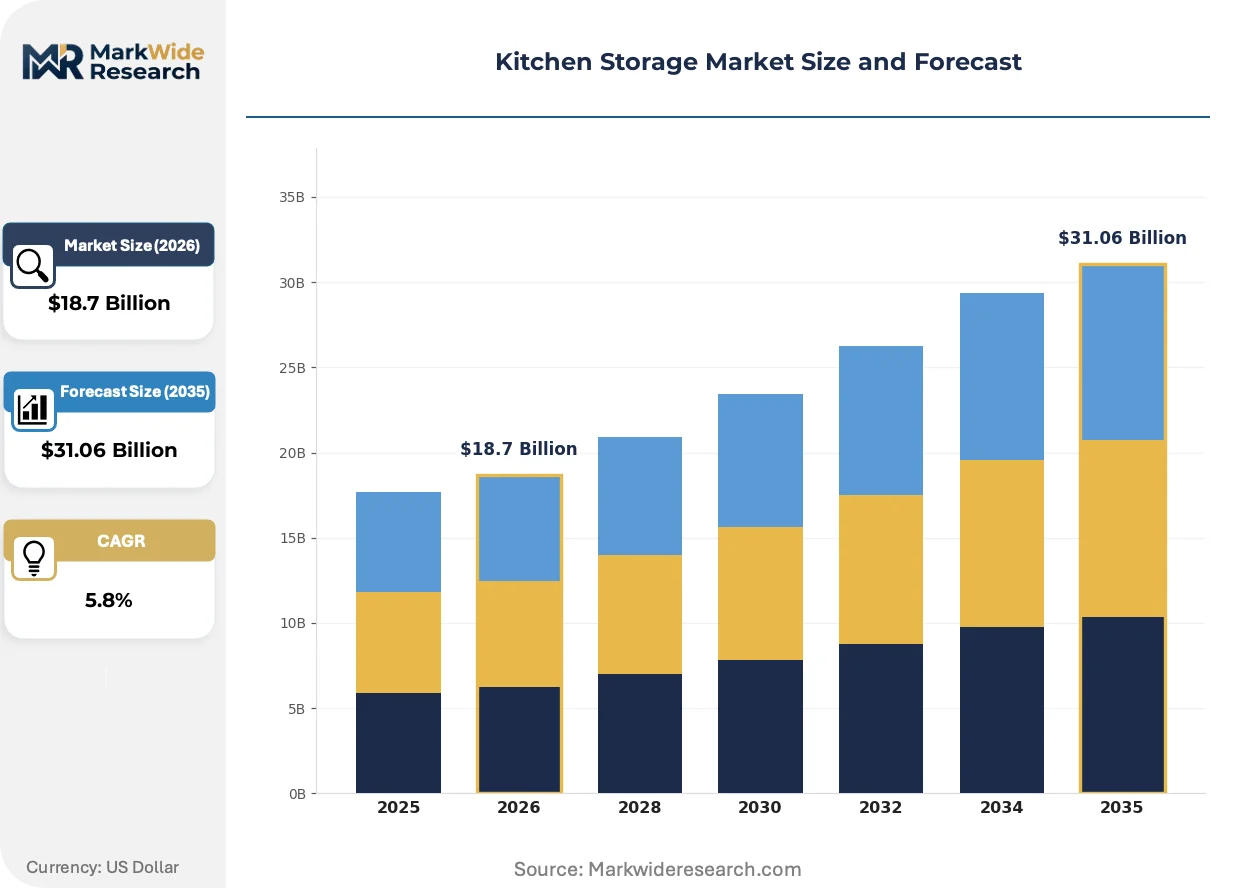
Market Dynamics
California Title 24 building efficiency standards and the EU Ecodesign framework are compressing material specifications for built-in storage systems, forcing manufacturers to reformulate substrates and finishes ahead of replacement cycles in existing housing stock.
Growth Catalysts
- Apartment densification:Urban homeowners in Sun Belt metropolitan areas are accelerating adoption of modular, space-efficient kitchen storage as apartment living expands.
- EU Ecodesign Directive:Recyclable material content thresholds for household storage products are pulling forward replacement demand in member states ahead of compliance deadlines.
- Open-concept aesthetics:Metal rack systems are capturing share from traditional cabinetry as consumers prioritize visible organization over concealed storage.
Market Restraints
- Composite wood input volatility:Formaldehyde emissions compliance costs for engineered substrates are compressing margins for cabinet manufacturers serving California and the northeastern United States.
- Supply concentration in flat-pack logistics:Dominant retailers control last-mile distribution networks, constraining pricing autonomy for independent storage system producers.
- Technical limitation in moisture resistance:Thermofoil finishes on engineered wood substrates degrade faster than solid wood alternatives in high-humidity food preparation environments.
Strategic Opportunities
- Extended producer responsibility frameworks:Emerging take-back mandates in Europe create first-mover advantage for manufacturers with closed-loop material recovery systems.
- Smart storage convergence:Integration of sensor-enabled inventory tracking with modular cabinet systems opens premium positioning in connected home ecosystems.
- Direct-to-installer channels:Bypassing traditional retail through contractor-direct procurement models captures margin in residential renovation segments.
Industry Challenges
- CAD-to-CNC programming talent scarcity:Custom storage system manufacturers face bottlenecks in skilled technicians capable of translating modular designs into production-ready machine instructions.
- Multi-jurisdiction certification timelines:Simultaneous compliance with EPA formaldehyde standards, California Air Resources Board regulations, and EU Ecodesign requirements extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kitchen Storage Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cabinets, Shelves, Racks, Bins Material: Wood, Metal, Plastic, Glass Application: Food Storage, Utensil Storage, Pantry Organization, Appliances End User: Households, Restaurants, Cafes, Catering Services |
| Companies Covered | IKEA, The Container Store, Newell Brands (Rubbermaid), Rev-A-Shelf, Sterilite Corporation, ClosetMaid, OXO, Tupperware Brands Corporation, Williams-Sonoma, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kitchen Storage Market Shifts & Advancements
Material science advances and regulatory stringency are converging to reshape competitive positioning in kitchen storage, with sustainability credentials and space efficiency becoming primary purchase determinants.
Glass food storage containers are displacing plastic alternatives in premium pantry organization segments where chemical-free preservation and microwave compatibility drive purchase decisions. Health-conscious urban households are adopting borosilicate and tempered glass systems at accelerated rates. This shift is compressing volume leadership for transparent polymer bins in above-median income brackets.
REACH chemical registration requirements in the European Union are restricting certain polymer formulations used in food-contact storage applications. Manufacturers serving EU member states are reformulating toward bio-based or mineral-filled alternatives. The Container Store and specialty retailers are prioritizing compliant SKUs in their European assortments ahead of enforcement phases.
Homeowners are unbundling storage procurement from full kitchen remodels, purchasing modular inserts and organizational accessories through standalone transactions. Big-box retailers and direct-to-consumer platforms are capturing this demand with expedited shipping and virtual space-planning tools. This pattern is most pronounced in United States metropolitan areas with elevated housing turnover and contractor backlogs.
Kitchen Storage Market Segmentation
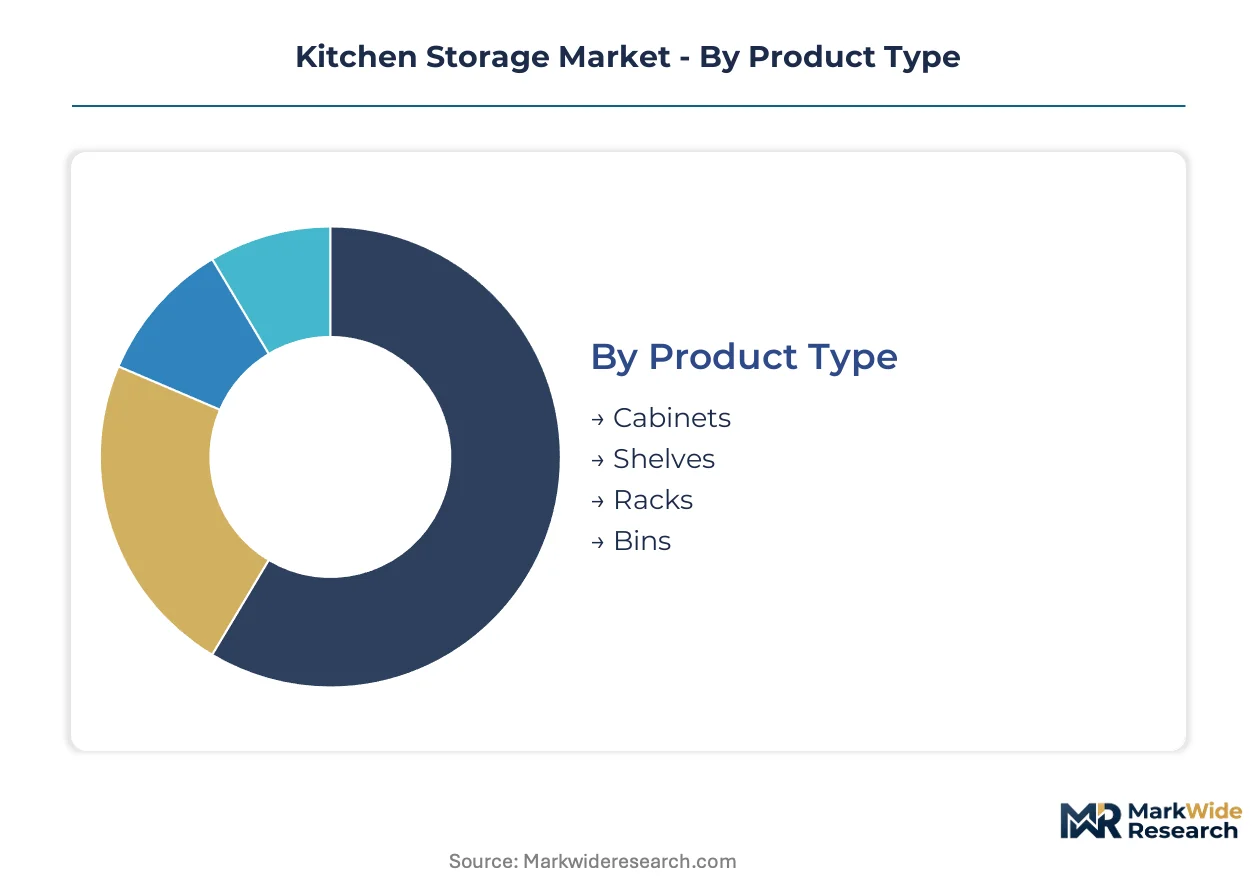
Kitchen storage procurement patterns diverge sharply across material substrates and installation contexts. Manufacturers must calibrate production capacity against these fault lines to avoid inventory mismatches in volatile housing markets.
Product Type:
Metal rack systems exert the strongest substitution pressure on traditional cabinetry as open-concept kitchen designs gain preference among urban renovators.
- Cabinets:Engineered wood substrates with thermofoil or lacquer finishes dominate replacement demand in existing housing stock. California Title 24 efficiency standards and EU Ecodesign recyclable content mandates are forcing reformulation of substrate adhesives ahead of normal replacement cycles.
- Shelves:Wall-mounted and freestanding systems capture renovation-driven demand where homeowners seek flexible reconfiguration without full cabinet replacement. Powder-coated steel variants are climbing fastest in Sun Belt metropolitan areas with elevated new construction activity.
- Racks:Open metal frameworks serve visible organization needs in compact urban kitchens.
- Bins:Stackable polymer and wire containers address pantry organization in rental units and temporary housing.
Cabinets anchor the volume base while racks gain share at the steepest rate.
Material:
Cost tier stratification determines supplier margins more than any other material dimension, with premium substrates commanding 3-4x the per-unit margin of commodity alternatives.
- Wood:Solid hardwood and engineered substrates occupy distinct price bands. Thermofoil-faced particleboard serves mass-market cabinet production, while solid maple and cherry concentrate in custom fabrication serving high-end residential renovation in the United States.
- Metal:Powder-coated steel and aluminum alloys enable open shelving systems with load capacities exceeding 150 kilograms per tier. Demand concentrates in commercial foodservice and urban residential segments prioritizing durability over warmth.
- Plastic:Polypropylene and polycarbonate formulations dominate food-contact storage at entry price points.
- Glass:Borosilicate and tempered variants capture premium pantry segments where chemical-free preservation and microwave compatibility drive purchase decisions among health-conscious households.
Wood retains the largest installed base while glass expands most quickly in above-median income brackets.
Application:
Volume concentration in food storage applications obscures faster growth in pantry organization as unbundled procurement from full kitchen remodels accelerates.
- Food Storage:Containers, canisters, and preservation systems address dry goods, leftovers, and ingredient management. Glass displacement of polymer formulations is most pronounced here as REACH chemical restrictions in Europe and consumer health concerns reshape material preferences.
- Utensil Storage:Drawer inserts, countertop crocks, and wall-mounted holders organize cooking tools within arm's reach of food preparation zones. Modular inserts are capturing standalone demand from homeowners deferring full cabinet replacement.
- Pantry Organization:Shelving systems, spice racks, and specialized bins maximize vertical storage efficiency in dedicated food storage rooms or closets.
- Appliances:Built-in and freestanding units house small electrics, with integration into cabinet systems requiring standardized dimensions and ventilation specifications.
Food storage commands the greatest shipment volume while pantry organization climbs the fastest as a standalone purchase category.
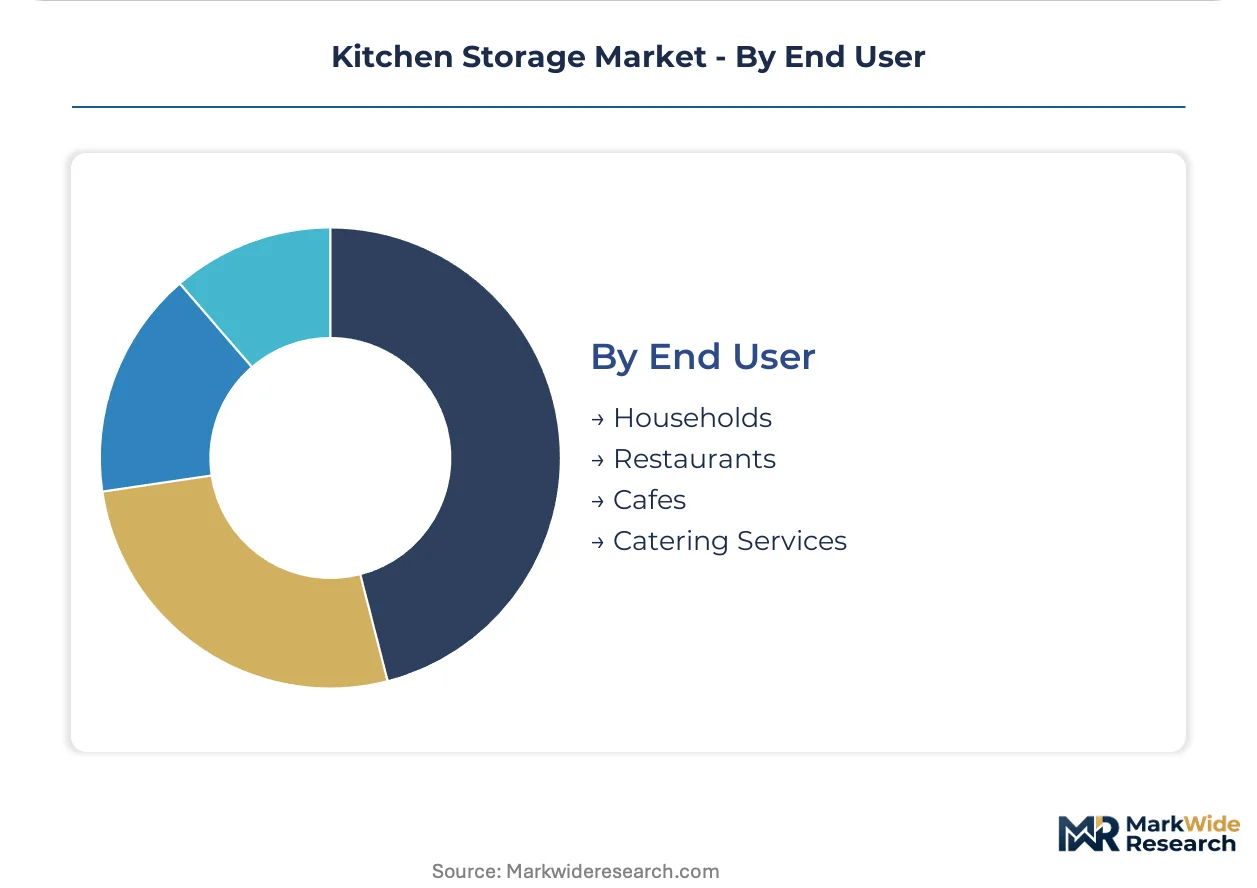
End User:
Customer type segmentation reveals diverging procurement channels, with commercial operators prioritizing durability certifications and households responding to aesthetic and space-efficiency cues.
- Households:Residential buyers drive the majority of value through renovation and new construction activity. Sun Belt metropolitan areas in the United States concentrate demand for modular systems compatible with apartment densification trends.
- Restaurants:Commercial kitchens require NSF-certified shelving and storage withstanding intensive sanitization protocols. Stainless steel dominates this specification-driven segment.
- Cafes:Smaller-footprint operations prioritize vertical storage and mobile rack systems for flexible layout reconfiguration.
- Catering Services:Transportable storage and food-safe containers support off-premise event execution, with durability requirements exceeding residential standards.
Households generate the dominant revenue share while restaurants maintain the most demanding specification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flat-pack logistics networks and engineered wood substrate production cluster most heavily in Sweden, Germany, and China, with final assembly and distribution radiating toward high-consumption metropolitan zones in North America and Western Europe.
United States
Sun Belt metropolitan areas including Phoenix, Austin, and Atlanta concentrate new housing construction and residential renovation activity. EPA formaldehyde emissions standards for composite wood products apply nationwide, with California's Air Resources Board maintaining the strictest state-level thresholds. IKEA's North American distribution hubs in California and Texas anchor flat-pack cabinet fulfillment to dense urban markets.
Germany
Precision-engineered cabinet systems serve renovation demand across aging European housing stock. The EU Ecodesign Directive mandates recyclable material content thresholds for household storage products sold in member states. Industrial clusters in North Rhine-Westphalia and Bavaria host specialized thermofoil finishing operations and CNC fabrication facilities.
China
Domestic apartment densification in Shanghai, Shenzhen, and Beijing accelerates modular storage adoption among urban homeowners. GB standards for indoor air quality and formaldehyde emissions in wood-based panels apply to manufactured substrates. Yangtze River Delta manufacturing zones supply engineered wood components to global flat-pack retailers.
Sweden
Scandinavian design aesthetics influence premium kitchen storage preferences across Northern Europe. REACH chemical registration requirements restrict certain polymer formulations used in food-contact storage applications. Stockholm-based logistics innovation centers prototype automated flat-pack distribution systems for European market penetration.
Japan
Compact urban dwellings in Tokyo, Osaka, and Nagoya maximize space efficiency through modular storage integration. METI energy efficiency guidelines influence material specifications for built-in residential systems. Kanto region manufacturing maintains specialized powder-coating facilities for metal rack systems serving visible organization trends.
Kitchen Storage Market Competitive Landscape
Concentration sits with flat-pack retailers controlling last-mile distribution networks, while premium specialists and mass-market diversified manufacturers occupy distinct competitive tiers. The vendor base stratifies across three archetypes: logistics-integrated volume players, customization-focused premium specialists, and brand-leveraged diversified consumer goods conglomerates. Dominant competitive moves include backward integration into substrate manufacturing and direct-to-installer channel development bypassing traditional retail markups.
Among logistics-integrated volume players, IKEA exemplifies flat-pack supply chain dominance through controlled distribution density. The Container Store occupies a position within the premium customization tier, serving renovation-driven demand for closet and pantry systems. Newell Brands anchors the diversified conglomerate archetype, leveraging Rubbermaid's mass-market penetration across food storage containers at big-box retail.
| Leading Market Players |
|---|
| IKEA |
| The Container Store |
| Newell Brands (Rubbermaid) |
| Rev-A-Shelf |
| Sterilite Corporation |
| ClosetMaid |
| OXO |
| Tupperware Brands Corporation |
| Williams-Sonoma, Inc. |
| Others |
Supply & Pricing Matrix
Flat-pack logistics scale economies in Sweden and Germany compress unit costs for modular cabinet systems while simultaneously anchoring price floors for independent manufacturers lacking comparable distribution density. This concentration of fulfillment infrastructure creates asymmetric pricing power where volume-integrated retailers dictate margin terms across entry-level and mid-market tiers.
Pricing Analysis
Volume-discount tiering structures separate mass-market flat-pack offerings from custom-fabricated premium systems and artisanal solid-wood alternatives. Pricing stratifies across premium, standard, and economy tiers with differentiation driven by substrate certification grade and customization depth. Cost compression in thermofoil-faced engineered wood segments intensifies as California CARB and EPA formaldehyde compliance expenses accumulate. Mass-market apartment renovators exhibit highest price sensitivity while custom residential renovation clients prioritize material provenance over unit cost.
Supply Chain Analysis
China and Germany anchor engineered wood substrate production with thermofoil finishing operations concentrated in North Rhine-Westphalia and Yangtze River Delta manufacturing zones. Raw material draws from Nordic timber suppliers, Middle Eastern petrochemical feedstocks for thermofoil resins, and Australian mineral sands for powder-coat pigments. Single-source vulnerability sits with flat-pack logistics networks controlled by dominant retailers. Distribution runs through big-box retail channels, direct-to-installer procurement platforms, and specialized home organization boutiques.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kitchen storage sits at an inflection where EU Ecodesign recyclable content mandates and California Title 24 efficiency standards are forcing substrate reformulation ahead of normal replacement cycles, compressing margins for manufacturers without closed-loop material recovery capabilities.
For Market Incumbents: Shield market position through backward integration into CARB-compliant engineered wood substrate production and captive control over thermofoil finishing capacity. Incumbent manufacturers face substitution pressure from metal rack systems capturing open-concept renovation demand. Priority lever rests with direct-to-installer channel development bypassing retail markup compression. For New Entrants and Emerging Players: EU Ecodesign certification fast-tracks offer regulatory differentiation for manufacturers with bio-based adhesive formulations and closed-loop material recovery systems. White-space concentrates in smart storage convergence where sensor-enabled inventory tracking integrates with modular cabinet architectures. Most penetrable segment spans premium pantry organization in above-median income urban households. Go-to-market angle prioritizes virtual space-planning tools paired with expedited fulfillment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors manufacturers with CAD-to-CNC programming capabilities and multi-jurisdiction certification expertise. Long-term viability across the projection horizon hinges on compliance infrastructure for evolving extended producer responsibility frameworks. Acquisition target archetype encompasses specialized powder-coating facilities for metal rack systems and CNC fabrication shops with modular design translation capacity. Signal to watch: enforcement phases for REACH chemical restrictions reshaping polymer formulation preferences in food-contact storage applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Manufacturing | Captures margin compression from CARB-compliant engineered wood supply constraints affecting California and Northeastern markets. |
| Direct-to-Installer Channel Development | Bypasses retail markup extraction in residential renovation segments where contractor procurement decisions dominate. |
| Smart Storage Convergence Investment | Opens premium positioning through sensor-enabled inventory tracking integrated with modular cabinet ecosystems. |
| Closed-Loop Material Recovery System Deployment | Creates first-mover advantage under emerging EU extended producer responsibility take-back mandates. |
| Multi-Jurisdiction Certification Infrastructure Buildout | Accelerates product launch cycles constrained by simultaneous EPA, CARB, and EU Ecodesign compliance timelines. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with cabinet system manufacturers, flat-pack logistics operators, residential renovation contractors, and specialty retail category buyers; alongside secondary validation through EPA formaldehyde emissions filings, EU Ecodesign Directive implementation documents, California Air Resources Board regulatory updates, and customs trade data for engineered wood substrate flows. Bottom-up shipment estimates triangulated against top-down housing construction and renovation expenditure models.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning material substrate, installation context, application type, and end-user category with regional production cluster differentiation. CAGRs derived from housing stock replacement cycle analysis, apartment densification trajectory assessment, and regulatory compliance deadline impacts. Industry-specific inputs incorporated thermofoil finish degradation rates in high-humidity environments and metal rack load capacity specifications for commercial foodservice certification.
Decision-makers should treat outputs as directional under base assumptions of sustained Sun Belt housing construction activity and progressive EU extended producer responsibility implementation; material deviation in either driver would warrant model refresh. Recalibration cycles align with material shifts in regulatory enforcement phases and substrate material science advances.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Storage and Organization
Cabinet & Furniture Drawer Slides Market
Home Storage and Organization
Sheds and Outdoor Storage Market
Home Storage and Organization
Closet Organizers Market
Home Storage and Organization
Small Space Furniture Market
Home Storage and Organization
Toy Storage Market
Home Storage and Organization
Smart Storage Cabinet Market
Home Storage and Organization
United Kingdom Home Decor Market
Home Storage and Organization
Jewelry Organizer Market
Home Storage and Organization
Collapsible Wardrobe Market
Home Storage and Organization
Smart Shoe Cabinet Market
Home Storage and Organization
Display Cabinets Market
Home Storage and Organization
Asia-Pacific Digital Home Locker Market
Home Storage and Organization
Shoe Rack Market
Home Storage and Organization
Flush Mount Photo Album Market
Home Storage and Organization
Tool Chest Market
Home Storage and Organization
Scandinavia Self-Storage Market