
 Toy Storage Market | 2026-2036
Toy Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Toy Storage Market Analytics
Market Context
Vietnam is rewriting regional supply dynamics through expanded furniture manufacturing clusters near Ho Chi Minh City. Williams-Sonoma Inc leverages vertical integration across design and distribution to sustain premium positioning in North American channels. KidKraft anchors mass-market penetration through broad retail partnerships and standardized product lines. Wayfair Inc dominates e-commerce reach by controlling digital shelf space and fulfillment infrastructure for home organization categories.
Technical Definition and Segments
Toy storage encompasses engineered containment systems designed to organize, display, and protect children's play items, typically constructed from molded polymers, processed timber, woven textiles, or formed metals with load-bearing specifications between fifteen and fifty pounds. These products serve residential and institutional environments by reducing clutter hazards and supporting child autonomy in item retrieval. Plastic bins lead volume throughput due to low unit costs and dishwasher-safe maintenance profiles, while wooden shelving commands margin concentration through heirloom-positioning and nursery aesthetics. Fabric baskets represent the fastest-expanding material category as collapsible designs address apartment-dwelling parents in dense urban centers. Classroom applications drive institutional procurement cycles aligned with school district budget calendars.
Regulatory Environment
The Consumer Product Safety Commission enforces ASTM F963 toy-related standards that extend to storage accessories through tip-over and small-parts provisions, while California's Proposition 65 mandates chemical disclosure labeling on coated wood and painted metal surfaces. The EU's REACH regulation restricts phthalate content in plastic formulations, compelling Asian contract manufacturers to reformulate resin compounds for export eligibility. Stakeholders must monitor evolving extended producer responsibility frameworks in Germany and France that could impose end-of-life collection obligations on furniture-category imports.
Market Dynamics
The EU Green Deal's material mandates are restructuring sourcing decisions across toy storage supply chains, forcing manufacturers to abandon virgin petroleum-based resins and verify recycled content claims through third-party certification bodies.
Growth Catalysts
- Dual-income household expansion:Parents of young children in suburban United States markets prioritize dedicated playroom infrastructure and organized containment systems as discretionary spending on home organization rises.
- REACH phthalate restrictions:European chemical regulations compel Asian contract manufacturers to reformulate polymer compounds, creating first-mover advantages for suppliers with pre-certified sustainable resin portfolios.
- Fabric basket innovation:Collapsible woven textile designs address space constraints for apartment-dwelling parents in dense urban centers, expanding addressable market beyond traditional single-family homeowners.
Market Restraints
- Resin price volatility:Petroleum-derived polypropylene and polyethylene input costs fluctuate with crude oil benchmarks, compressing margins for molded plastic bin producers without long-term supply contracts.
- Vietnam manufacturing concentration:Furniture production clusters near Ho Chi Minh City create geographic supply risk from port congestion, labor disputes, or regional climate disruptions affecting just-in-time delivery schedules.
- Wooden shelving substitution ceiling:Heirloom-positioned timber products face demand elasticity limits as mass-market consumers prioritize low-cost disposability over durability premiums in inflationary environments.
Strategic Opportunities
- Extended producer responsibility frameworks:Germany and France are developing end-of-life collection mandates for furniture-category imports, creating service-revenue potential for manufacturers establishing reverse logistics infrastructure.
- Classroom procurement cycles:Institutional buyers in United States school districts follow predictable budget calendars, enabling specialized salesforce alignment with public education purchasing timelines.
- E-commerce fulfillment integration:Digital-native retailers controlling warehouse networks and last-mile delivery can bundle storage solutions with complementary home organization categories, capturing share from traditional brick-and-mortar toy specialists.
Industry Challenges
- ASTM F963 compliance complexity:Tip-over testing and small-parts provisions extend toy safety standards to storage accessories, requiring engineering redesigns and third-party laboratory validation that delay product launches.
- California Proposition 65 labeling:Chemical disclosure mandates for coated wood and painted metal surfaces create packaging complexity and litigation exposure for manufacturers without robust supply chain documentation systems.
Report Scope
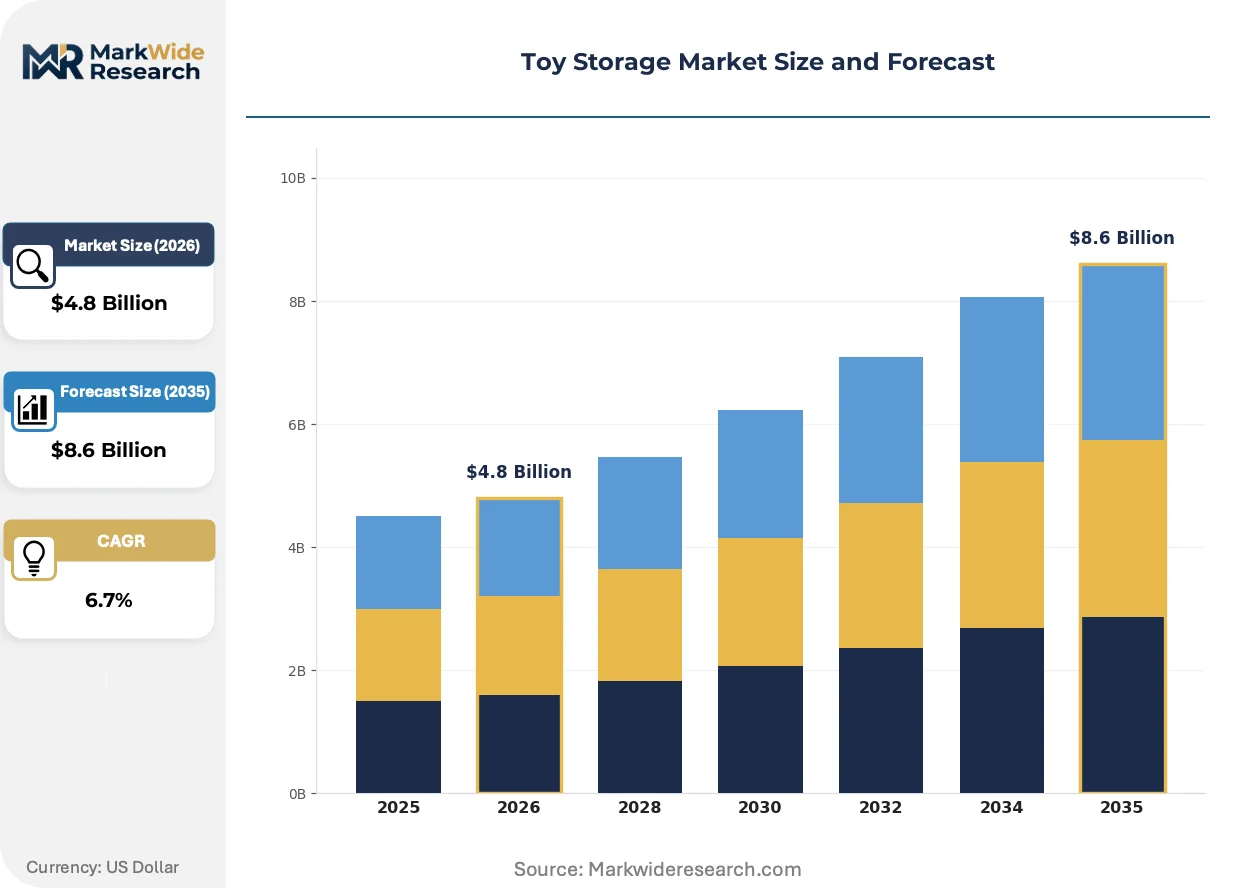
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toy Storage Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bins, Shelves, Carts, Baskets Material: Plastic, Wood, Fabric, Metal Application: Nursery, Playroom, Classroom, Outdoor Customer Type: Parents, Educators, Retailers, Organizations |
| Companies Covered | Williams-Sonoma Inc, Casa Kids, KidKraft, FirstCry, Blu Dot, Crate & Barrel, Million Dollar Baby, Humble Crew, Wayfair Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toy Storage Market Evolving Landscape
Material science advances and regulatory pressure are converging to transform how toy storage products are engineered, certified, and brought to market across residential and institutional channels.
Modular polymer systems is migrating from fixed-configuration molded bins toward interlocking, reconfigurable components that adapt to changing inventory volumes. Montessori-aligned parents and early childhood educators are adopting these systems fastest, compressing replacement cycles as families reconfigure layouts rather than discard entire units. The technology is migrating from premium positioning toward mass-market price points through Asian contract manufacturers achieving scale in standardized connector mechanisms.
REACH substance restrictions continue tightening phthalate and heavy metal thresholds in plastic formulations exported to European Union member states. Manufacturers serving German and French distribution channels must maintain comprehensive substance dossiers and supply chain audit trails, raising compliance costs that favor larger suppliers with dedicated regulatory affairs functions. Wooden shelving and fabric basket categories gain relative share as buyers seek materials outside polymer regulatory scope.
Subscription-based replenishment models are emerging among digitally native parents who treat toy storage as an evolving system rather than one-time purchase. Direct-to-consumer brands bypass traditional retail markup structures, capturing lifetime value through accessory add-ons and seasonal reconfiguration kits. This pattern concentrates in United States coastal metropolitan markets where apartment turnover rates and space constraints drive continuous organization needs.
Toy Storage Market Segmentation
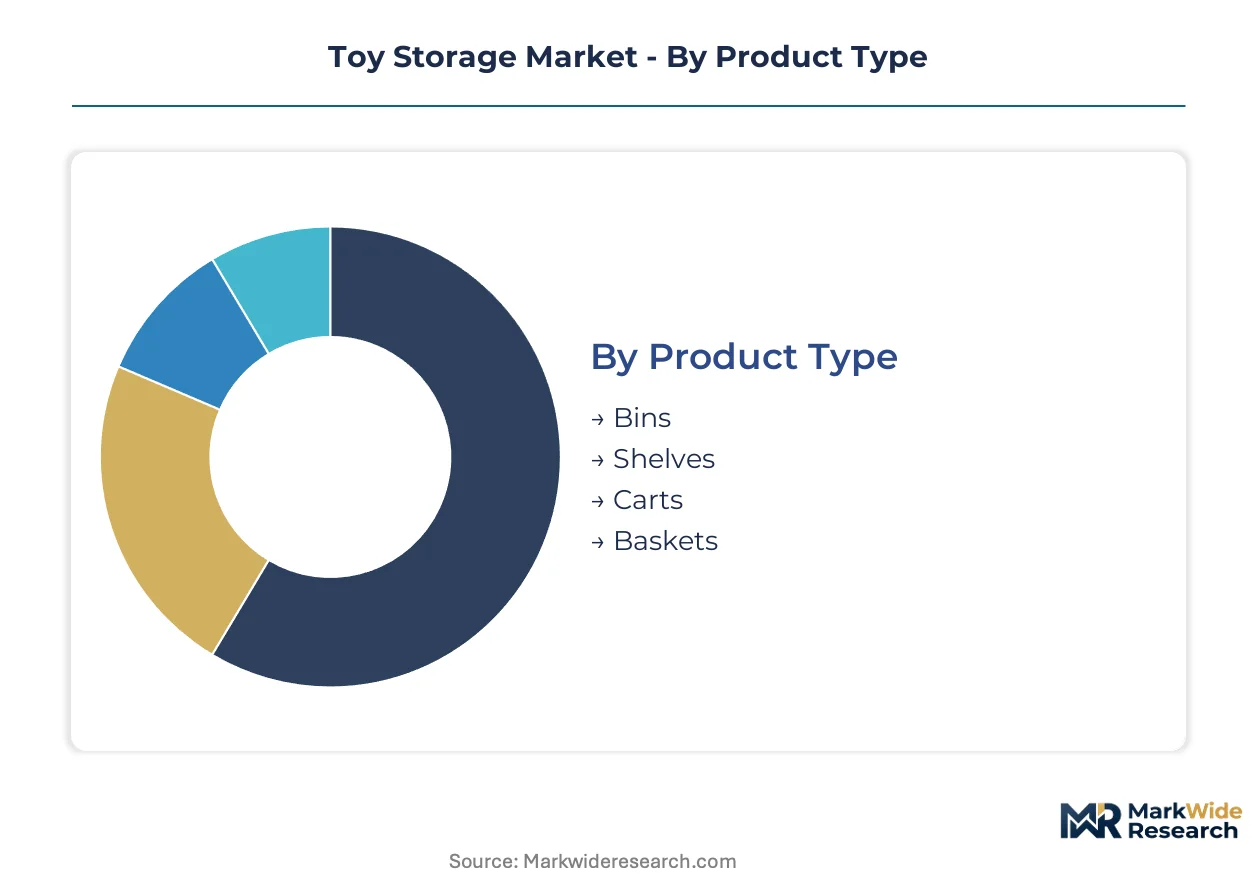
Toy storage purchasing decisions split across material preferences, spatial constraints, and end-use durability requirements. Manufacturers configure production lines around these segment boundaries to optimize margin capture and inventory turns.
Product Type:
After-sales-service intensity varies sharply across container formats, with modular systems requiring replacement component programs and fixed units demanding warranty claim management.
- Bins:Molded polymer containers with stackable geometry and snap-fit lids dominate volume throughput in suburban United States households. Dishwasher-safe polypropylene formulations sustain repeat purchases as wear-out replacement cycles compress.
- Shelves:Vertical timber or engineered wood systems with fifteen-to-fifty-pound load ratings command margin concentration through heirloom positioning and nursery aesthetic integration. California Proposition 65 compliance documentation adds fulfillment complexity for coated finishes.
- Carts:Mobile metal-frame units with caster-mounted bases address classroom reconfiguration needs in United States school districts.
- Baskets:Collapsible woven designs with wire or fabric construction expand fastest among apartment-dwelling parents in dense urban centers.
Bins hold the largest share; momentum sits with Baskets.
Material:
Cost tier stratification determines sourcing geography and regulatory exposure across the value chain.
- Plastic:Petroleum-derived polypropylene and polyethylene formulations face REACH phthalate restrictions in European Union markets. Asian contract manufacturers maintain pre-certified sustainable resin portfolios to preserve export eligibility.
- Wood:Processed timber with low-VOC finishes and FSC chain-of-custody documentation captures premium positioning in heirloom-segment purchases. EU Green Deal material mandates accelerate certified sourcing requirements.
- Fabric:Collapsible woven textiles with reinforced stitching address space constraints for urban apartment dwellers.
- Metal:Formed steel or aluminum frames with powder-coated surfaces serve institutional procurement cycles in educational facilities.
Plastic commands volume leadership; Wood captures margin concentration.
Application:
Volume patterns track residential square footage availability and institutional budget calendar alignment.
- Nursery:Aesthetic-integrated containment systems with soft-close mechanisms and tip-over resistance anchor early-childhood safety compliance. ASTM F963 testing protocols extend to storage accessories in this segment.
- Playroom:Large-capacity modular systems with reconfigurable components serve dual-income households prioritizing organized living spaces in suburban United States markets.
- Classroom:Durable institutional-grade units with mobility casters align with United States school district procurement timelines.
- Outdoor:Weather-resistant polymer or treated timber construction addresses patio and garage storage needs.
Playroom generates the highest unit volumes; Classroom follows predictable institutional purchasing patterns.
Customer Type:
Procurement authority and decision criteria fragment across consumer, institutional, and commercial channels.
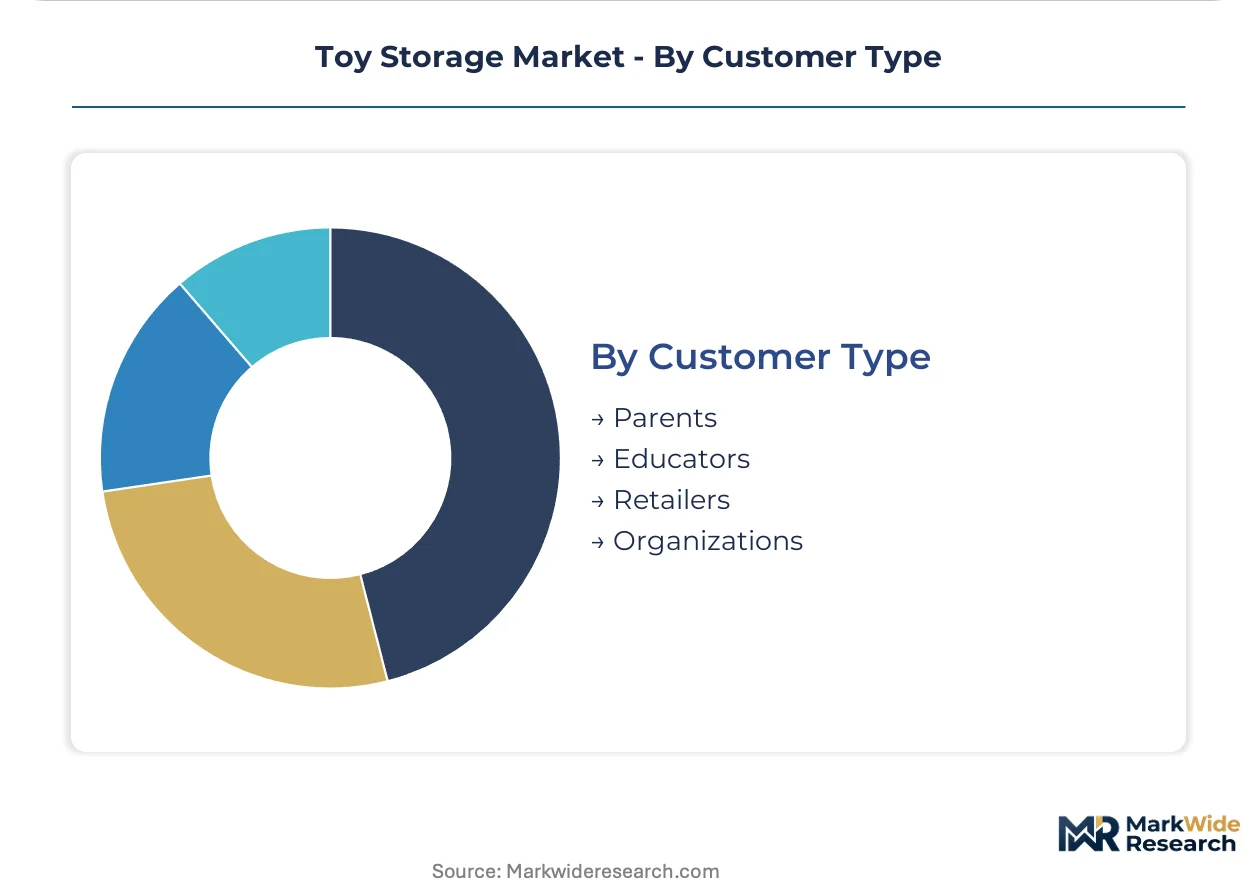
- Parents:Dual-income suburban households in the United States drive discretionary spending on dedicated playroom infrastructure and aesthetic-coordinated containment systems.
- Educators:Early childhood program administrators and public school procurement officers prioritize durability certifications and volume pricing.
- Retailers:Mass-market and specialty channel buyers negotiate slotting allowances and seasonal inventory programs.
- Organizations:Nonprofit and municipal recreation programs seek bulk procurement with extended payment terms.
Parents represent the largest addressable base; Educators provide the most predictable recurring demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing clusters for toy storage concentrate in Vietnam near Ho Chi Minh City, with procurement authority fragmenting across suburban United States households, European sustainability-mandated channels, and institutional buyers in North American school districts. Demand patterns diverge sharply between single-family homeowners prioritizing dedicated playroom infrastructure and apartment-dwelling urban parents seeking collapsible solutions.
United States
Suburban dual-income households drive discretionary spending on organized living spaces and dedicated playroom infrastructure. The Consumer Product Safety Commission enforces ASTM F963 standards extending tip-over and small-parts provisions to storage accessories. Manufacturing specification authority concentrates with retailers in Bentonville, Arkansas and Minneapolis, Minnesota who negotiate slotting allowances and seasonal inventory programs.
Germany
Extended producer responsibility frameworks are developing end-of-life collection mandates for furniture-category imports, creating service-revenue potential for manufacturers establishing reverse logistics. REACH substance restrictions tighten phthalate and heavy metal thresholds in plastic formulations, compelling comprehensive substance dossiers. Industrial buyers in North Rhine-Westphalia prioritize certified sustainable resin portfolios and FSC chain-of-custody documentation.
Vietnam
Furniture manufacturing clusters near Ho Chi Minh City are rewriting regional supply dynamics through expanded production capacity. The country's export-oriented industrial zones face geographic supply risk from port congestion and regional climate disruptions. Contract manufacturers serving European Union distribution channels maintain pre-certified sustainable resin portfolios to preserve REACH compliance eligibility.
France
EU Green Deal material mandates accelerate certified sourcing requirements for processed timber with low-VOC finishes. National regulators are developing extended producer responsibility frameworks that could impose end-of-life collection obligations on furniture-category imports. Paris-based design houses influence nursery aesthetic integration and heirloom-positioning strategies across premium-tier channels.
China
Asian contract manufacturers achieve scale in standardized connector mechanisms for modular polymer systems, migrating technology from premium positioning toward mass-market price points. Dual carbon goals and environmental regulations from the Ministry of Ecology and Environment reshape resin sourcing decisions. Production gravity in Guangdong and Zhejiang provinces supplies collapsible woven textile designs for dense urban center applications.
Toy Storage Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The vendor base stratifies between mass-market retailers controlling digital shelf space, premium furniture houses anchoring heirloom positioning, and Asian contract manufacturers achieving scale in standardized formats. Three archetypes dominate: vertically integrated design-to-distribution platforms, specialist fabricators of collapsible textile systems, and institutional-grade durability suppliers. Competitive moves concentrate on e-commerce fulfillment integration and sustainable material certification pre-positioning.
Among North American platform integrators, Williams-Sonoma Inc and Wayfair Inc occupy positions spanning premium and mass-market price tiers respectively. KidKraft exemplifies the specialist archetype focused on standardized product lines and broad retail partnerships. These three entities represent distinct strategic vectors: design-controlled vertical integration, digital-native fulfillment infrastructure, and mass-market penetration through retail channel density.
| Leading Market Players |
|---|
| Williams-Sonoma Inc |
| Casa Kids |
| KidKraft |
| FirstCry |
| Blu Dot |
| Crate & Barrel |
| Million Dollar Baby |
| Humble Crew |
| Wayfair Inc |
| Others |
Value Network & Pricing Analysis
Ho Chi Minh City furniture manufacturing clusters anchor global toy storage capacity, with expanded resin processing and timber finishing operations creating downstream pricing leverage for contract manufacturers serving European Union sustainability mandates. Buyers in Germany and France absorb certification premiums as REACH-compliant resin portfolios and FSC chain-of-custody documentation become non-negotiable entry requirements.
Pricing Analysis
EU Green Deal material mandates dictate the pricing tier structure across the toy storage market, separating FSC-certified timber heirloom products from virgin petroleum-based polymer bins and collapsible fabric alternatives. Price differentiation rests on certification grade and after-sales service intensity, with modular systems commanding replacement-component premiums while fixed units compete on warranty terms. Cost compression in mass-market plastic categories is intensifying because of resin price volatility tied to crude oil benchmarks. Mass-market retailers exhibit highest price sensitivity, while nursery-integrated wooden shelving buyers accept durability premiums.
Supply Chain Analysis
Asian contract manufacturers in Vietnam, China, and Indonesia hold concentrated capacity for molded polymer systems and woven textile assemblies. Raw material dependencies draw from petroleum-derived polypropylene, certified timber feedstocks, and synthetic textile fibers. Single-source vulnerability runs through Vietnam port infrastructure handling just-in-time delivery schedules for United States retail replenishment cycles. Distribution runs through Bentonville and Minneapolis retail specification authority, with direct-to-consumer channels bypassing traditional markup structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. Extended producer responsibility frameworks and REACH substance dossier requirements create compliance switching costs that favor established suppliers with dedicated regulatory affairs infrastructure.
For Market Incumbents: Build certification moats through pre-positioned sustainable resin portfolios and FSC chain-of-custody documentation that emerging competitors cannot replicate without 18-24 month lead times. Defend against direct-to-consumer entrants by capturing digital shelf space through e-commerce fulfillment integration and controlling last-mile delivery infrastructure for bulky home organization categories. Prioritize backward integration into recycled polymer compounding to secure margin against virgin resin price volatility. For New Entrants and Emerging Players: Collapsible fabric baskets for apartment-dwelling parents in dense United States coastal metropolitan markets represent the most penetrable entry point, as this segment sits outside the regulatory scope constraining polymer competitors and below the heirloom positioning of timber incumbents. Classroom procurement cycles in United States school districts offer predictable institutional demand with lower brand loyalty barriers than residential channels. Launch through subscription-based replenishment models capturing lifetime value through seasonal reconfiguration kits rather than competing on single-transaction economics. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regulatory compliance costs and extended producer responsibility infrastructure requirements will disproportionately burden sub-scale manufacturers. Target acquisition archetypes include specialist fabricators of collapsible textile systems with established Asian contract manufacturing relationships and modular polymer innovators with standardized connector mechanism patents. Monitor German and French regulatory filings for extended producer responsibility implementation timelines as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Sustainability Certification Investment | FSC and REACH pre-certification preserves EU market access against tightening material mandates. |
| Direct-to-Consumer Channel Launch | Subscription models bypass Bentonville retail markup structures and capture lifetime customer value. |
| Backward Integration into Recycled Resin | In-house polymer compounding insulates margins from petroleum price volatility affecting Asian contract manufacturers. |
| Classroom Salesforce Alignment | Dedicated public education procurement teams synchronize with predictable United States school district budget calendars. |
| Reverse Logistics Infrastructure Buildout | German and French end-of-life collection mandates create service-revenue streams beyond product manufacturing. |
Research Methodology
A standing panel of product development directors at furniture manufacturers, retail category buyers, early childhood program administrators, and resin procurement specialists provided ongoing calibration throughout the study. Primary fieldwork combined structured interviews with secondary validation through customs trade records, SEC retail filings, and EU regulatory submission databases. Bottom-up segment modeling triangulated against top-down macroeconomic anchors across the analysis window.
Scenario-bracketing framed volume and value outputs across material type, application environment, and customer procurement authority dimensions. CAGRs derived from fitted growth curves applied to segment-level baseline data, with cross-validation against school district budget cycle patterns and residential square footage expansion rates serving as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in crude oil benchmarks, suburban household formation rates, or EU regulatory enforcement intensity would shift the trajectory. Quarterly review of REACH substance restriction amendments and extended producer responsibility framework progressions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Storage and Organization
Clothes Closets Market
Home Storage and Organization
Small Space Furniture Market
Home Storage and Organization
Cabinet & Furniture Drawer Slides Market
Home Storage and Organization
Kitchen Storage Market
Home Storage and Organization
Middle East and Africa Kitchen Storage Market
Home Storage and Organization
Shoe Rack Market
Home Storage and Organization
Sheds and Outdoor Storage Market
Home Storage and Organization
Shoe Storage and Organizers Market
Home Storage and Organization
Kitchen Storage Organization Market
Home Storage and Organization
Smart Storage Cabinet Market
Home Storage and Organization
Regency Shelving Market
Home Storage and Organization
Wardrobe Boxes Market
Home Storage and Organization
Shop Shelving Market
Home Storage and Organization
Tool Chest Market
Home Storage and Organization
Europe Home Organizers and Storage Market
Home Storage and Organization
Shelf Display Trays Market