
 Scandinavia Self-Storage Market | 2026-2036
Scandinavia Self-Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Scandinavia Self-Storage Market Analytics
Cloud-based facility management platforms with integrated IoT sensor networks is rewriting how Scandinavian operators monitor occupancy, climate conditions, and security across distributed portfolios. Pelican Self Storage leverages predictive analytics to optimize unit pricing in real time across its Danish and Swedish facilities. Shurgard Self Storage anchors its competitive position through a dense network of purpose-built assets concentrated in Greater Copenhagen and Stockholm. City Self-Storage differentiates by targeting premium urban infill locations with architecturally integrated designs that satisfy strict municipal planning boards.
Scandinavia self-storage comprises enclosed, individually lockable rental compartments ranging from one to thirty square meters, typically constructed from corrugated steel partitions within converted warehouses or purpose-built single-story structures with reinforced concrete slabs and passive ventilation systems, serving households and enterprises requiring flexible, short-to-medium duration space for goods retention. Climate-controlled units command premium rates in subarctic zones where temperature swings degrade stored materials, while standard units dominate volume across price-sensitive residential segments in Finland and Denmark. Business storage represents the fastest-expanding customer type as Nordic e-commerce fulfillment networks require buffer inventory space outside expensive logistics centers, and vehicle storage margins concentrate in Norway where electric fleet operators need secure depot alternatives.
Sweden's Boverket enforces stringent energy performance certificates on commercial buildings, compelling operators to retrofit insulation and ventilation systems before lease renewals. Denmark's BR18 building regulations and Finland's Ympäristöministeriö waste framework collectively shape facility design standards and circular economy compliance for construction materials. Norway's Finanstilsynet consumer protection rules govern rental contract transparency, limiting automatic fee escalation clauses that operators historically relied upon for margin expansion. Stakeholders must monitor how municipal zoning liberalization in secondary Nordic cities alters site acquisition economics before competitors secure convertible industrial parcels.
Market Dynamics
Urban densification across Stockholm, Copenhagen, and Oslo is compressing residential square footage per capita, forcing households to externalize storage needs into commercial facilities while municipal zoning boards tighten greenfield development permissions.
Growth Catalysts
- Nordic e-commerce fulfillment networks:Buffer inventory requirements from online retailers are displacing goods from expensive logistics centers into flexible self-storage units near last-mile delivery nodes.
- Boverket energy retrofit mandates:Sweden's tightened building codes are accelerating conversion of existing industrial warehouses into climate-compliant storage facilities rather than permitting new construction.
- Electric fleet depot alternatives:Norwegian commercial vehicle operators require secure, grid-adjacent parking and charging infrastructure that self-storage yards with perimeter security can provision.
Market Restraints
- Construction material cost volatility:Reinforced concrete slab and steel partition input prices fluctuate with Nordic raw materials markets, squeezing development margins on purpose-built facilities.
- Secondary city zoning conservatism:Municipal planning boards in Finland's Tampere and Norway's Bergen resist industrial-to-storage conversions, limiting site pipeline expansion.
- Climate control energy intensity:Subarctic temperature swings demand continuous HVAC operation, elevating operating expenditure per square meter against milder European benchmarks.
Strategic Opportunities
- Finland's underpenetrated urban markets:Helsinki and Espoo exhibit self-storage square footage per capita at roughly half Swedish levels, presenting first-mover expansion potential.
- BR18 circular economy compliance:Denmark's building regulations incentivize adaptive reuse of existing structures, rewarding operators with expertise in industrial retrofitting over greenfield developers.
- IoT-enabled predictive maintenance:Convergence of cloud facility management platforms with sensor networks allows remote portfolio oversight, reducing on-site staffing requirements across dispersed Nordic assets.
Industry Challenges
- Specialized retrofit engineering talent:Operators struggle to recruit professionals fluent in both historic industrial building pathology and modern climate-control system integration.
- Finanstilsynet contract compliance timelines:Norwegian consumer protection rules require extensive legal review of rental agreements, slowing unit turnover and administrative throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scandinavia Self-Storage Market |
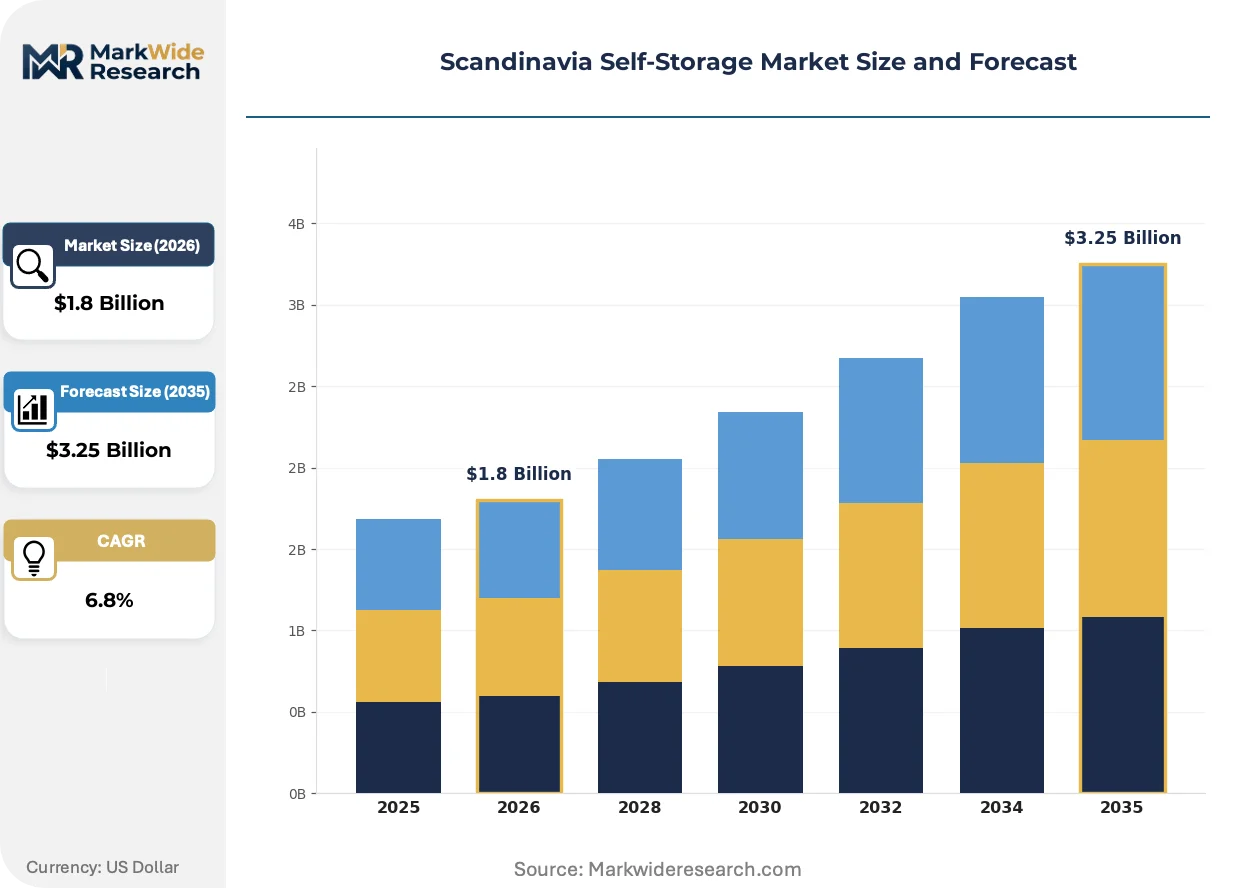
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Units, Climate-Controlled Units, Vehicle Storage, Business Storage Customer Type: Residential Users, Small Businesses, Large Corporations, Students Service Type: Short-Term Rental, Long-Term Rental, On-Demand Access, Packing Supplies Access Mode: 24/7 Access, Managed Access, Limited Access, Drive-up Access |
| Companies Covered | Pelican Self Storage, City Self-Storage, Shurgard Self Storage, Boxit A/S, Servistore Oy, Self Storage Group ASA, Green Storage, Ztorage, 24Storage, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scandinavia Self-Storage Market Evolving Landscape
Facility operations across Denmark, Sweden, and Norway are digitizing rapidly as sensor networks and predictive analytics compress manual oversight requirements while elevating real-time pricing precision.
Cloud-based management platforms are migrating from simple reservation systems to integrated IoT command centers. Scandinavian operators deploy these tools across multi-site portfolios to monitor occupancy, humidity, and security events remotely. The technology is migrating from cost center to revenue optimizer as predictive algorithms adjust unit rates dynamically based on real-time demand signals.
Sweden's Boverket energy performance certificates now mandate insulation and ventilation upgrades before commercial building lease renewals. Operators must retrofit existing warehouse conversions with thermal barriers and heat recovery systems to maintain occupancy permits. Climate-controlled unit categories face the steepest compliance burdens, accelerating capital deployment into envelope improvements.
Household downsizing patterns among urban apartment dwellers are fragmenting traditional seasonal storage contracts. Stockholm and Copenhagen residents now lease smaller units on rolling monthly terms rather than committing to annual blocks for winter sports equipment or document archives. This behavioral shift compresses revenue predictability while elevating facility turnover velocity and marketing expenditure per acquired customer.
Scandinavia Self-Storage Market Segmentation
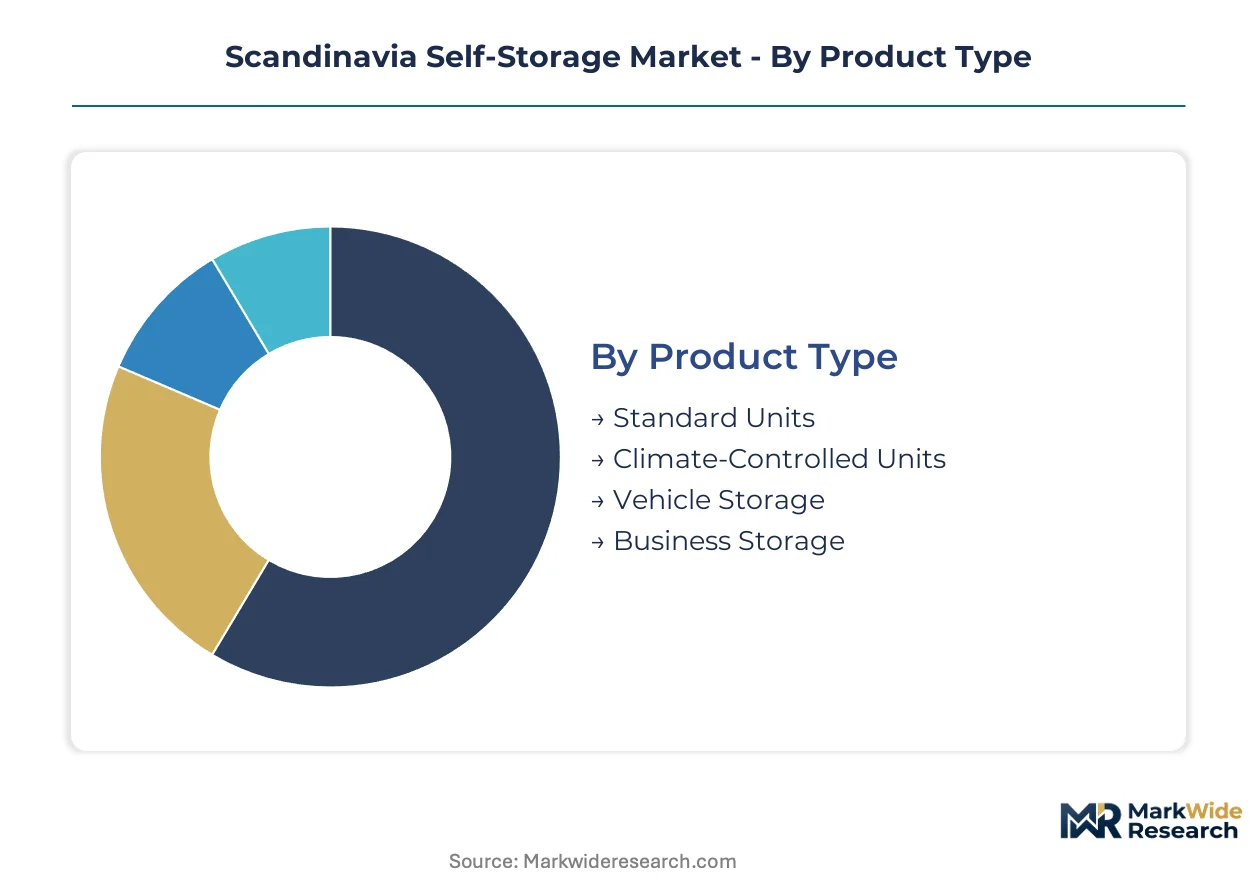
Scandinavian self-storage operators must align unit configurations with distinct demand profiles across residential downsizing, e-commerce logistics, and electric fleet depot requirements. Segmentation clarity determines pricing architecture, facility design investments, and geographic rollout priorities across Nordic urban corridors.
Product Type:
Cost tier differentiation separates commodity storage from premium climate-protected offerings and specialized vehicle accommodation.
- Standard Units:Corrugated steel partitions within converted warehouses or purpose-built single-story structures with passive ventilation serve price-sensitive residential segments. Demand concentrates in Finland and Denmark where household budgets constrain premium uptake, while municipal zoning in Stockholm and Copenhagen limits greenfield development of economy-tier facilities.
- Climate-Controlled Units:Continuous HVAC operation maintains stable temperature and humidity through subarctic swings, protecting electronics, documents, and textiles from degradation. Oslo-Akershus corridor operators command premium rates for these units as Norwegian consumers prioritize asset protection over monthly savings.
- Vehicle Storage:Secure perimeter yards with grid-adjacent charging infrastructure accommodate electric fleet operators seeking depot alternatives outside expensive logistics centers.
- Business Storage:Flexible square-meter blocks with loading dock access buffer inventory for Nordic e-commerce fulfillment networks requiring proximity to last-mile delivery nodes.
Standard units hold installed capacity. Climate-controlled units are rotating up the share rankings.
Customer Type:
Application focus varies sharply between household externalization of compressed living space and enterprise inventory management requirements.
- Residential Users:Urban apartment dwellers in Stockholm and Copenhagen lease smaller units on rolling monthly terms as residential square footage contracts, fragmenting traditional seasonal storage contracts and elevating facility turnover velocity.
- Small Businesses:Nordic e-commerce sellers and service contractors require flexible buffer space outside expensive logistics centers, with demand clustering near Port of Oslo and Greater Copenhagen distribution nodes.
- Large Corporations:Document archives and equipment staging drive contracted volume commitments, though Boverket energy retrofit mandates complicate long-term lease security in Swedish facilities.
- Students:Transient academic calendars generate concentrated summer demand in university cities like Lund, Uppsala, and Aarhus, with price sensitivity limiting margin expansion.
Residential users anchor volume throughput. Small businesses are gaining share fastest.
Service Type:
Duration and access flexibility determine revenue predictability and operational staffing models across Nordic facilities.
- Short-Term Rental:Monthly rolling contracts dominate urban infill locations where Stockholm and Copenhagen residents externalize seasonal equipment and document overflow, compressing revenue visibility while requiring dynamic pricing capabilities.
- Long-Term Rental:Annual or multi-year blocks secure occupancy stability for business inventory and corporate archive segments, with Norwegian Finanstilsynet rules limiting automatic escalation clauses that operators historically relied upon.
- On-Demand Access:Digital entry systems and mobile app integration enable retrieval without staff presence, reducing on-site labor costs across dispersed portfolios.
- Packing Supplies:Ancillary retail of boxes, tape, and protective materials generates incremental margin per customer acquisition in high-traffic facilities.
Long-term rental holds contracted base. Short-term rental is climbing the fastest.
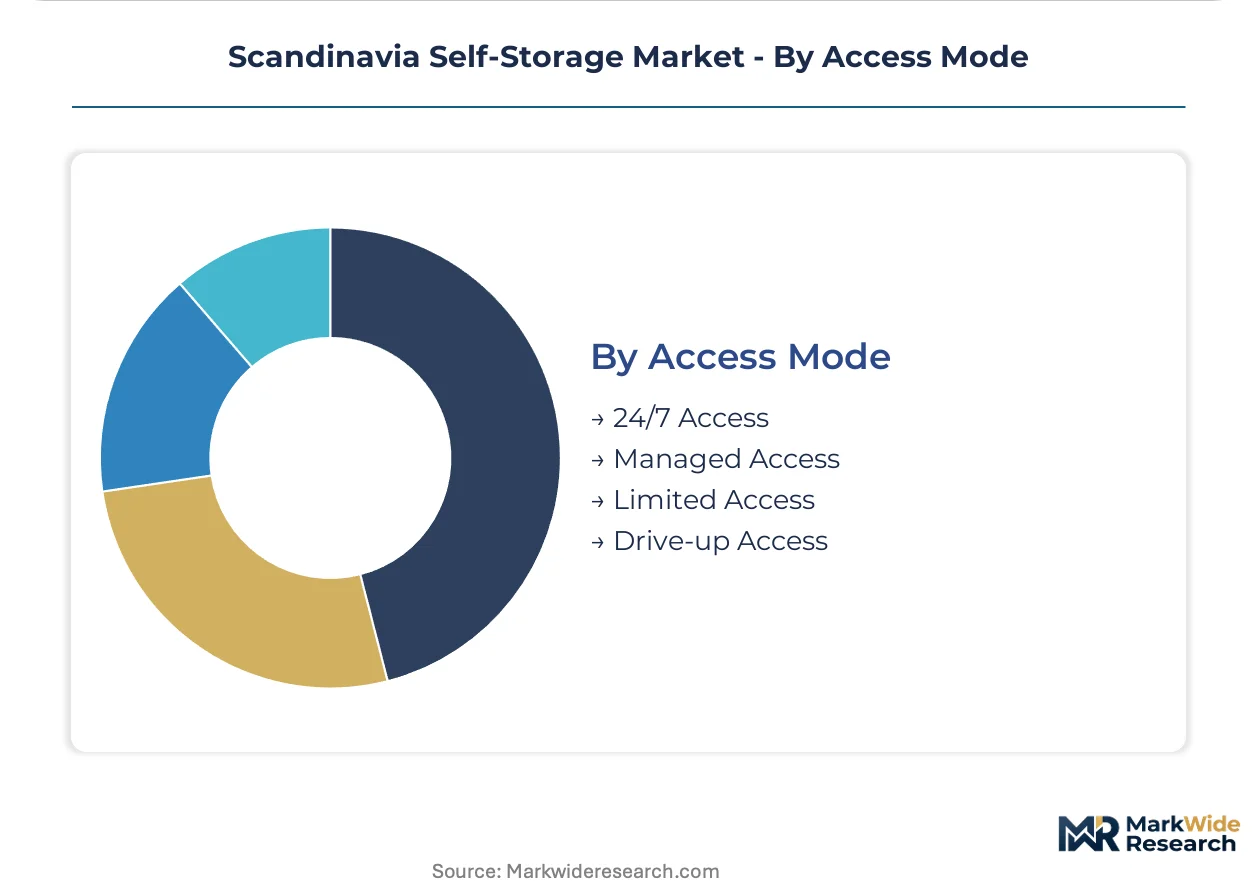
Access Mode:
Security tier and convenience level shape facility design capital and insurance underwriting across Nordic markets.
- 24/7 Access:Automated entry systems with CCTV monitoring serve residential users requiring retrieval flexibility, with IoT sensor networks enabling remote security oversight across multi-site portfolios.
- Managed Access:Staffed reception hours during business days satisfy corporate clients with scheduled inventory movements and compliance documentation requirements.
- Limited Access:Restricted hours reduce operational expenditure in secondary Nordic cities where demand density cannot support full-time staffing.
- Drive-up Access:Ground-level units with vehicle proximity accelerate loading efficiency for business storage and vehicle storage segments in Oslo-Akershus logistics clusters.
Managed access maintains institutional share. 24/7 access is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norwegian operators export climate-controlled capacity to Swedish and Danish demand corridors as cross-border portfolio strategies intensify. Stockholm-Copenhagen-Oslo logistics integration drives facility location decisions. Regulatory divergence across Boverket, BR18, and Finanstilsynet frameworks shapes capital deployment timing.
Sweden
Stockholm apartment dwellers externalize storage as residential square footage contracts below 40 square meters per capita. Boverket energy performance certificates mandate insulation upgrades before lease renewals. Gothenburg's port-adjacent industrial zones attract conversion projects from logistics-adjacent operators.
Norway
Oslo-Akershus corridor concentrates demand from electric fleet operators seeking secure depot alternatives. Finanstilsynet consumer protection rules limit automatic fee escalation clauses in rental contracts. Bergen municipal planning boards resist industrial-to-storage zoning conversions despite port logistics pressure.
Denmark
Greater Copenhagen households fragment seasonal storage contracts into rolling monthly terms. BR18 building regulations incentivize adaptive reuse of existing warehouse structures over greenfield development. Aarhus university-city demand spikes concentrate during summer academic transitions.
Finland
Helsinki and Espoo exhibit self-storage square footage per capita at roughly half Swedish penetration levels. Ympäristöministeriö waste framework shapes circular economy compliance for construction materials in facility retrofits. Tampere secondary-city zoning conservatism limits convertible industrial parcel availability.
Scandinavia Self-Storage Market Competitive Landscape
Channel-controlling players compete with product-specialist players across the Scandinavia self-storage market. The operator base clusters around three strategic archetypes: dense urban infill specialists, logistics-corridor converters, and technology-integrated multi-site portfolios. Competitive moves concentrate on industrial warehouse acquisitions and IoT-enabled facility management platform deployment. Geographic expansion through municipal zoning navigation distinguishes capital-heavy players from retrofit-focused specialists.
Among Nordic-based operators, Pelican Self Storage, Shurgard Self Storage, and City Self-Storage occupy distinct positioning vectors. Pelican represents the technology-integrated archetype with predictive analytics deployment across Danish and Swedish assets. Shurgard anchors the purpose-built density model concentrated in Greater Copenhagen and Stockholm corridors. City Self-Storage exemplifies premium urban infill specialization with architecturally integrated designs satisfying strict municipal planning boards. These three operators collectively illustrate how regulatory fluency and retrofit expertise separate scalable portfolios from site-constrained competitors.
| Leading Market Players |
|---|
| Pelican Self Storage |
| City Self-Storage |
| Shurgard Self Storage |
| Boxit A/S |
| Servistore Oy |
| Self Storage Group ASA |
| Green Storage |
| Ztorage |
| 24Storage |
| Others |
Value Network & Pricing Analysis
Oslo-Akershus corridor capacity dynamics concentrate climate-controlled inventory, granting Norwegian operators pricing leverage over Swedish and Danish demand corridors where Boverket retrofit mandates constrain new supply. This geographic asymmetry shapes how facility operators across Nordic markets calibrate rate cards against input cost volatility.
Pricing Analysis
Legacy warehouse conversion pricing diverges sharply from purpose-built facility rates, with the former commanding premiums for Boverket-compliant thermal envelope retrofits. Three-tier pricing structure across premium climate-controlled, standard ventilated, and economy unheated levels stratifies by certification grade and geographic delivery cost to last-mile nodes. Cost compression in standard units is intensifying because Swedish energy retrofit mandates accelerate capital deployment into envelope improvements. Small business e-commerce buffer users exhibit highest price sensitivity, while Norwegian electric fleet operators demonstrate lowest sensitivity due to depot alternative scarcity.
Supply Chain Analysis
Sweden's export-control equivalent in building materials—Boverket energy performance certificates—restricts flows of non-compliant insulation and HVAC components across Nordic borders. Supply concentrates in Sweden, Denmark, and Germany for reinforced concrete slab systems, corrugated steel partitions, and heat recovery ventilation units. Raw material dependencies draw from Nordic timber markets, German steel mills, and Chinese IoT sensor components. Single-source vulnerability runs through German HVAC equipment suppliers. Distribution runs through regional construction material wholesalers and direct OEM relationships with facility operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scandinavian self-storage represents a service-attach opportunity where predictive analytics subscriptions and climate-monitoring add-ons expand faster than base storage rental revenue. Facility management platforms with recurring SaaS layers now outgrow hardware-dependent income streams.
For Market Incumbents: Build zoning-navigator moats by embedding municipal relationship networks that accelerate industrial-to-storage conversion permits ahead of competitors. Consolidate through acquisition of retrofit-engineering talent pools in Gothenburg and Aarhus. Threaten margin compression from Pelican Self Storage's predictive pricing algorithms demands counter-investment in proprietary IoT command centers. Vertical integration into HVAC maintenance services secures Boverket compliance cost control. For New Entrants and Emerging Players: Finland's underpenetrated Helsinki-Espoo corridor offers white-space expansion at half Swedish square-footage-per-capita density. Target Tampere secondary-city zoning liberalization before municipal boards tighten industrial parcel conversions. Go-to-market angle: partner with Nordic e-commerce fulfillment networks for last-mile buffer inventory contracts. For Investors and Strategic Acquirers: Long-term, this sits as a regulated-utility play because Boverket, BR18, and Finanstilsynet frameworks create durable barriers to new supply while mandating recurring capital reinvestment. Acquisition target archetype: technology-integrated multi-site portfolios with established municipal zoning relationships. Signal to watch: municipal planning board staffing increases in Bergen and Tampere indicating pipeline acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Industrial Warehouse Conversion | BR18 circular economy compliance rewards adaptive reuse expertise over greenfield development in Denmark. |
| IoT Platform Integration | Pelican Self Storage's predictive analytics deployment compresses manual oversight across dispersed Nordic portfolios. |
| Climate-Controlled Capacity Buildout | Oslo-Akershus corridor operators command premium rates for subarctic asset protection services. |
| Long-term Municipal Zoning Agreement | City Self-Storage's architecturally integrated designs secure strict planning board approvals in Stockholm. |
| Electric Fleet Depot Partnership | Norwegian grid-adjacent storage yards capture commercial vehicle operator demand outside logistics centers. |
Research Methodology
The analysis maps climate-controlled, standard, vehicle, and business storage segments, each validated through facility operators, municipal planning officers, HVAC retrofit engineers, and e-commerce logistics managers. Primary interviews with Shurgard Self Storage regional directors, Pelican Self Storage technology leads, and City Self-Storage development executives combined with secondary validation through Boverket energy certificate databases, BR18 regulatory filings, Finanstilsynet consumer protection rulings, and Nordic construction material trade data. Bottom-up unit economics triangulated against top-down market sizing across the analysis window.
Assumption sets held Boverket enforcement timelines and BR18 circular economy incentives fixed while varying e-commerce penetration rates and electric fleet adoption curves across modeling scenarios. Segmentation dimensions modeled include product type, customer archetype, service duration, and access mode, with regional regulatory framework as an industry-specific overlay. CAGRs derived from historical facility absorption rates, urban densification projections, and logistics-adjacent demand clustering patterns around Port of Oslo and Greater Copenhagen distribution nodes.
Practitioners should monitor Boverket enforcement intensity, municipal zoning liberalization in secondary Nordic cities, and German HVAC equipment supply disruptions for early signals of forecast revision. Forecasts reflect documented assumptions about energy code compliance timelines and e-commerce buffer inventory permanence. Material shifts in Finanstilsynet contract transparency rules or Nordic raw materials market volatility would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Storage and Organization
Flush Mount Photo Album Market
Home Storage and Organization
Slipcases Market
Home Storage and Organization
Europe Home Organizers and Storage Market
Home Storage and Organization
Jewelry Organizer Market
Home Storage and Organization
United States Home Organizers and Storage Market
Home Storage and Organization
Closet Organizers Market
Home Storage and Organization
Shoe Rack Market
Home Storage and Organization
Collapsible Wardrobe Market
Home Storage and Organization
Small Space Furniture Market
Home Storage and Organization
Shelf Display Trays Market
Home Storage and Organization
Regency Shelving Market
Home Storage and Organization
Kitchen Storage Organization Market
Home Storage and Organization
Flatware Holders and Organizers Market
Home Storage and Organization
Display Cabinets Market
Home Storage and Organization
Shoe Storage and Organizers Market
Home Storage and Organization
Tool Chest Market