
 Jewelry Organizer Market | 2026-2036
Jewelry Organizer Market Size, Share, and Industry Trends Forecast 2026-2036
Jewelry Organizer Market Foresight
Smart manufacturing and automated laser-cutting workflows is reconfiguring how jewelry organizers achieve precision fit and customizable interior layouts at scale. Wayfair leverages its digital-native platform to control assortment breadth across price tiers and materials. Pottery Barn anchors the premium home furnishings channel with design-forward wood and fabric constructions. Bagsmart competes in the travel segment with lightweight, compartmentalized cases engineered for portability.
Jewelry organizers are enclosed or open storage systems, typically constructed from wood, acrylic, fabric, or metal, designed to sort, protect, and display rings, necklaces, bracelets, and earrings through segmented compartments, hooks, and cushioned slots. Manufacturing employs CNC routing for wood bodies, vacuum forming for acrylic shells, and die-cutting for fabric liners, with finishing processes including velvet flocking and anti-tarnish treatments to preserve metal integrity. Wall-mounted organizers lead in space-constrained urban dwellings, while travel cases represent the fastest-expanding category as mobility patterns normalize post-pandemic. Jewelry boxes occupy the mature core of the market, where margin pools concentrate in luxury tiers featuring hand-finished hardwoods and brass hardware.
EPA guidelines on formaldehyde emissions in composite wood products shape material sourcing for domestic manufacturers, while REACH restrictions on heavy metals and phthalates govern acrylic and fabric treatments entering Europe. The EU Green Deal and associated CSRD reporting obligations are pressuring brands to document supply chain carbon footprints and circularity pathways. Stakeholders must monitor evolving chemical compliance thresholds and decide whether to regionalize production or standardize formulations across markets.
Market Dynamics
Smart manufacturing workflows and automated laser-cutting systems are compressing production timelines for customizable interior layouts, while EU Green Deal mandates on circularity documentation are forcing supply chain reconfiguration across wood, acrylic, and fabric sourcing channels.
Growth Catalysts
- REACH restrictions on heavy metals:European chemical compliance is accelerating substitution toward FSC-certified wood substrates and recycled acrylic formulations, opening premium positioning for certified suppliers.
- Urban density patterns:Space-constrained dwellings in metropolitan United States clusters are driving wall-mounted organizer adoption as closet footprints shrink.
- Post-pandemic mobility normalization:Travel case demand is expanding fastest among compartmentalized, lightweight constructions engineered for portability.
Market Restraints
- Formaldehyde emission compliance:EPA guidelines on composite wood products impose material sourcing constraints and testing overhead for domestic manufacturers using particleboard or MDF cores.
- Acrylic supply concentration:Virgin and recycled acrylic substrate production clusters in East Asian chemical processing hubs create input cost volatility and logistics exposure.
- Fabric treatment limitations:Anti-tarnish chemical applications face REACH phthalate restrictions, limiting European market formulation options.
Strategic Opportunities
- CSRD reporting obligations:EU Green Deal supply chain carbon footprint documentation requirements create first-mover advantage for brands with established circularity pathways.
- Travel segment white space:Lightweight, compartmentalized cases for normalized mobility patterns represent underpenetrated positioning against traditional jewelry box incumbents.
- Digital-native platform expansion:Online retailers are broadening assortment breadth to capture convenience-seeking consumer segments underserved by legacy home furnishings channels.
Industry Challenges
- CNC programming talent scarcity:Precision wood routing for customizable interior layouts requires specialized CAD-to-machine workflow expertise that outpaces vocational training pipelines.
- Multi-jurisdiction formulation standardization:Brands must decide whether to regionalize production for EPA formaldehyde rules versus REACH chemical restrictions, fragmenting inventory and compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jewelry Organizer Market |
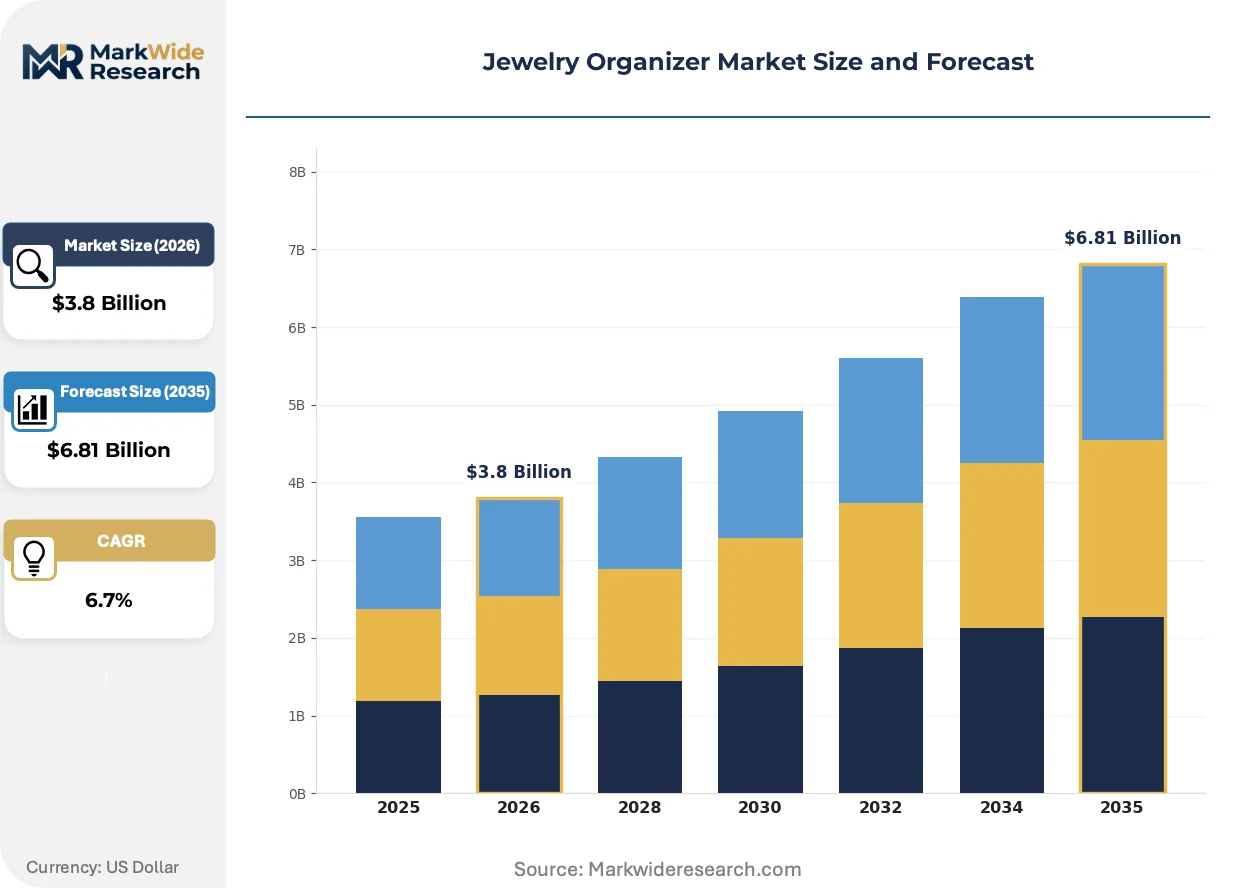
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Travel Cases, Wall-Mounted Organizers, Jewelry Boxes, Display Cases Material: Wood, Acrylic, Fabric, Metal End User: Retail Customers, Jewelry Stores, Online Retailers, Wholesale Distributors Price Tier: Luxury, Mid-Range, Budget, Premium |
| Companies Covered | Wayfair, Ed's Box & Supply, Pottery Barn, Box and Wrap, JewelryPackaging.com, Quince, Gems on Display, Allure Pack, Bagsmart, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jewelry Organizer Market Shifts & Advancements
Material science advances and regulatory disclosure mandates are simultaneously reshaping substrate selection and supply chain transparency requirements across wood, acrylic, and fabric constructions.
Automated laser-cutting workflows are migrating from prototyping labs to scaled production floors, enabling mass customization of compartment geometries and hook placements without tooling changeover delays. Urban millennial buyers in dense United States metropolitan clusters are driving adoption of these configurable systems. This technology compression is collapsing the traditional tradeoff between bespoke interior layouts and unit economics at volume.
CSRD reporting obligations under the EU Green Deal are mandating documented circularity pathways and supply chain carbon accounting for brands serving European markets. Manufacturers must now trace FSC-certified wood origins and recycled acrylic content through tier-two suppliers. Jewelry box producers with luxury hardwood positioning face the steepest compliance burden given multi-country sourcing of hand-finished materials.
Buyer concentration on digital-native platforms is consolidating discovery and purchase behavior away from traditional home furnishings retail. Wayfair and comparable aggregators now control assortment breadth across price tiers and material constructions. This channel shift is most visible in United States urban markets where convenience-seeking consumers prioritize delivery speed and return flexibility over tactile pre-purchase evaluation.
Jewelry Organizer Market Segmentation
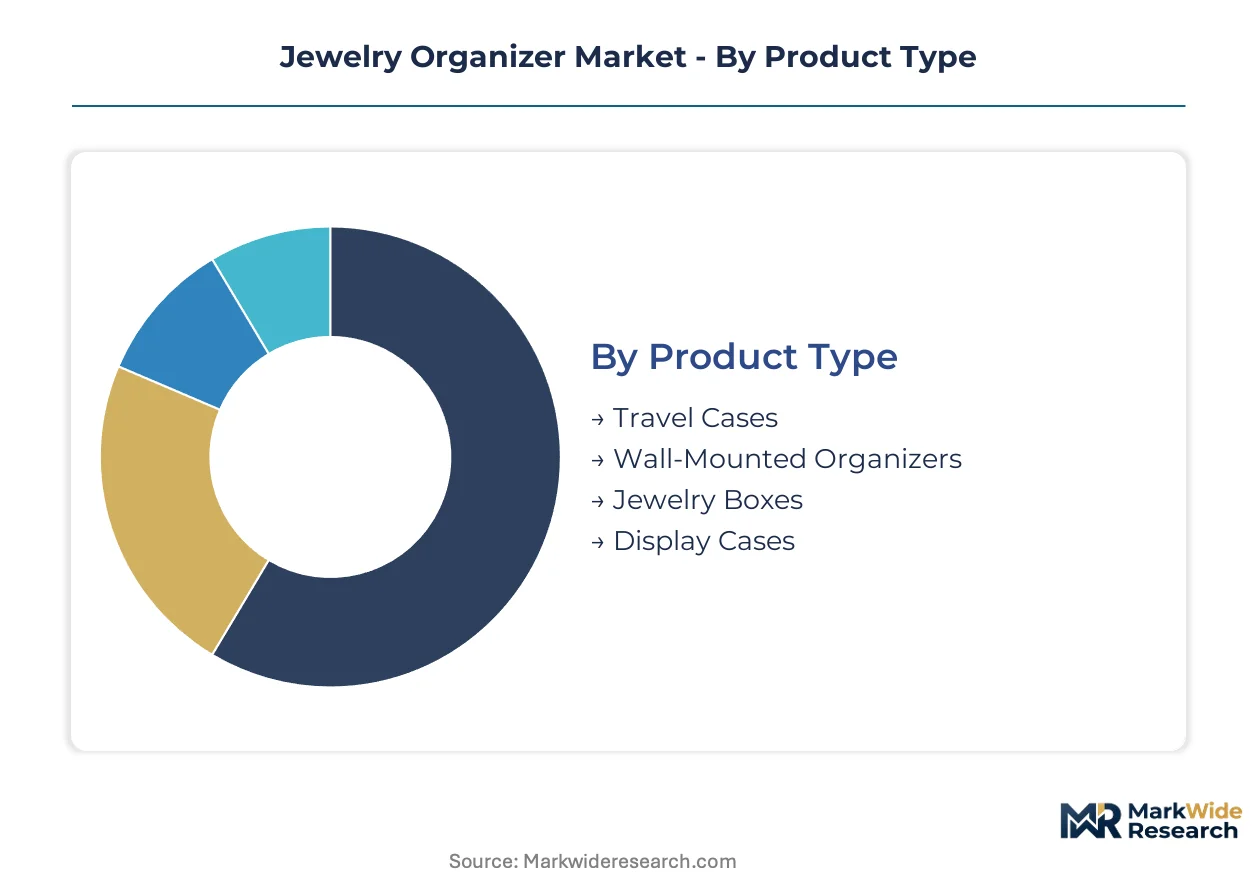
Jewelry organizer segmentation reveals how construction methods, material substrates, and channel economics fragment demand across distinct buyer workflows. Understanding these divides clarifies where margin pools concentrate versus where volume expansion accelerates.
Product Type:
Application context determines structural requirements — portability demands lightweight shells while stationary storage prioritizes capacity density and display aesthetics.
- Travel Cases:Compartmentalized constructions with padded interiors and secure closures protect pieces during transit. Demand concentrates among United States urban professionals resuming business travel patterns, with lightweight designs engineered for TSA compliance and carry-on constraints gaining preference. The steepest expansion runs through this segment as mobility normalizes post-pandemic.
- Wall-Mounted Organizers:Vertical storage systems exploit unused wall surfaces through hooks, rods, and transparent pockets. Dense metropolitan clusters in New York, San Francisco, and Chicago drive adoption as closet footprints shrink in premium apartment stock.
- Jewelry Boxes:Enclosed containers with tiered trays and cushioned slots represent the mature core of the market. Traditional constructions dominate gift-giving occasions and heirloom positioning.
- Display Cases:Open or glass-fronted systems prioritize visibility and accessibility over protection. Boutique retail environments and collector households sustain demand for illuminated and mirrored variants.
Travel cases command the established base. The steepest expansion runs through wall-mounted organizers.
Material:
Substrate selection traces directly to regulatory exposure, sustainability positioning, and price-tier targeting across manufacturing footprints.
- Wood:CNC-routed hardwoods and engineered cores deliver structural rigidity and premium tactile properties. FSC-certified sourcing is accelerating under EU Green Deal disclosure mandates, with domestic manufacturers facing EPA formaldehyde emission testing overhead for composite substrates.
- Acrylic:Vacuum-formed shells enable transparent or tinted constructions with precise dimensional tolerances. Virgin and recycled formulations face REACH heavy metal restrictions in European markets, constraining supplier flexibility.
- Fabric:Die-cut liners and exterior shells incorporate velvet flocking, canvas weaves, or synthetic blends. Anti-tarnish chemical treatments encounter phthalate limitations under REACH, fragmenting formulation options across jurisdictions.
- Metal:Brass hardware, wire frames, and mesh constructions provide durability and industrial aesthetics. Higher material costs and finishing complexity concentrate this substrate in premium and luxury tier positioning.
Wood commands the established base. The steepest expansion runs through recycled acrylic formulations.
End User:
Customer type segmentation captures divergent procurement workflows, from individual convenience purchasing to bulk commercial sourcing with custom specification requirements.
- Retail Customers:Individual buyers purchasing through digital-native platforms or home furnishings channels prioritize delivery speed, return flexibility, and visual merchandising. United States urban millennials concentrate discovery behavior on aggregator sites with broad assortment breadth.
- Jewelry Stores:Commercial buyers source display and storage systems aligned with brand aesthetics and theft-prevention protocols. Custom sizing and logo integration drive supplier selection criteria.
- Online Retailers:Channel intermediaries curate private-label and third-party assortments across price tiers and materials. Inventory velocity and margin compression dictate sourcing from flexible manufacturers with short lead times.
- Wholesale Distributors:Volume aggregators supply independent retailers and regional chains with standardized product lines. Price competitiveness and logistics reliability outweigh customization capabilities.
Retail customers command the established base. The steepest expansion runs through online retailers.
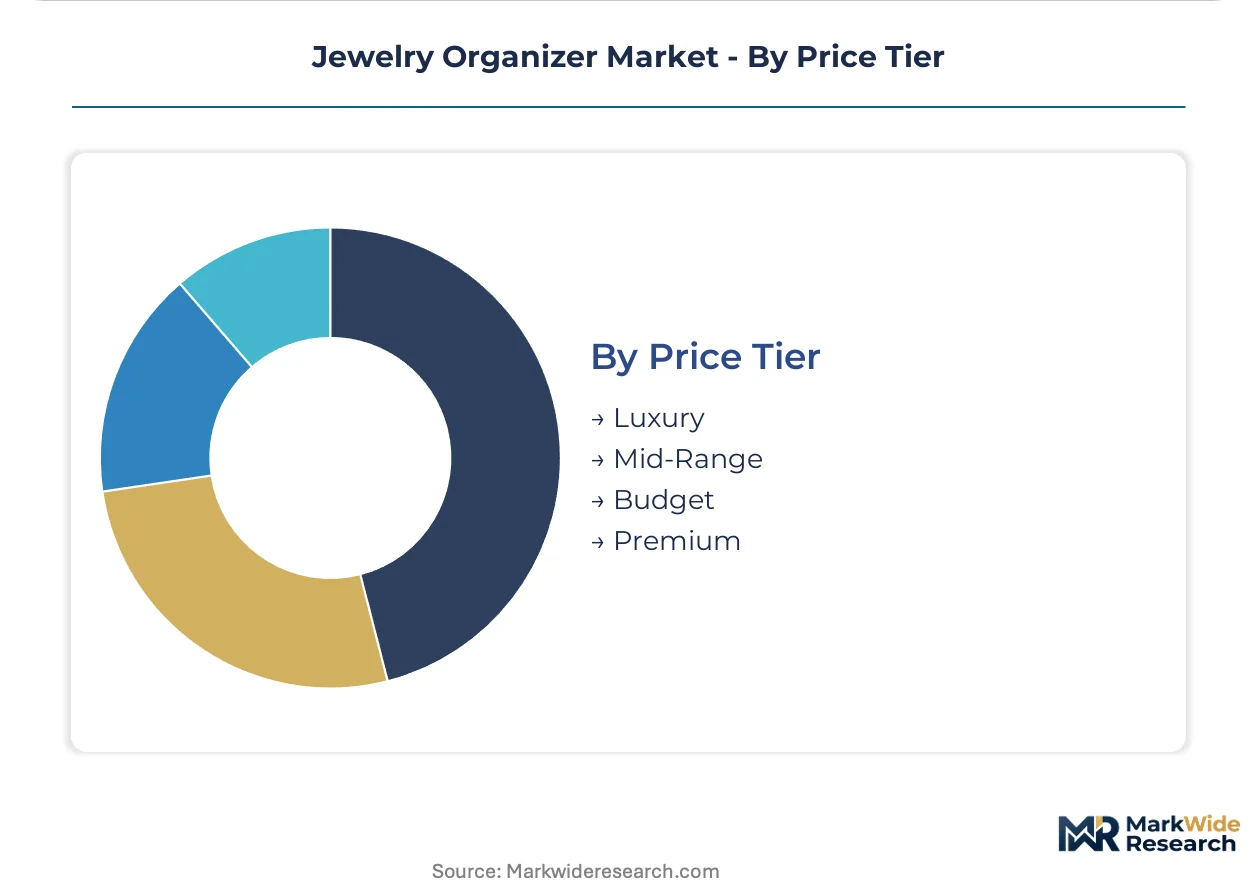
Price Tier:
Cost stratification reflects material grade, manufacturing precision, and brand positioning rather than functional differentiation alone.
- Luxury:Hand-finished hardwoods, brass hardware, and leather-lined interiors target gift and heirloom purchase occasions. Margin pools concentrate here despite lower unit volumes.
- Mid-Range:Engineered wood cores with veneer finishes and standardized compartment layouts balance quality perception with accessibility. This tier captures the broadest household penetration.
- Budget:Particleboard, non-woven fabric, and simplified constructions serve price-sensitive segments and temporary storage needs. Volume scale compensates for thin per-unit margins.
- Premium:Solid wood or recycled acrylic constructions with customizable interiors occupy the gap between mass-market and luxury positioning. Automated laser-cutting workflows are compressing production costs for this tier.
Mid-range commands the established base. The steepest expansion runs through premium customizable systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports acrylic substrates and vacuum-formed shells to United States and European assembly operations, while finished jewelry organizers flow back through digital-native retail channels concentrated in dense metropolitan clusters.
United States
Urban density in New York, San Francisco, and Chicago drives wall-mounted organizer adoption as premium apartment stock shrinks closet footprints. EPA formaldehyde emission guidelines constrain domestic manufacturers sourcing composite wood cores. Los Angeles and Dallas logistics hubs handle inbound acrylic and fabric components for final assembly and distribution.
Germany
REACH restrictions on heavy metals and phthalates accelerate substitution toward FSC-certified wood and recycled acrylic formulations. The EU Green Deal's CSRD reporting obligations mandate supply chain carbon documentation for brands serving European markets. Bavaria's precision manufacturing clusters host CNC routing operations for customizable interior layouts.
China
Concentrated chemical processing hubs in Guangdong and Zhejiang produce virgin and recycled acrylic substrates for global export. Dual carbon goals under MEE oversight pressure substrate producers toward energy-efficient vacuum-forming operations. Yangtze River Delta fabricators supply die-cut fabric liners and anti-tarnish treatment formulations.
United Kingdom
Digital-native platform penetration concentrates discovery behavior among London and Southeast England millennials prioritizing delivery speed over tactile evaluation. GDPR compliance shapes customer data handling for online retailers curating private-label assortments. Midlands distribution centers manage cross-border fulfillment into EU markets post-Brexit.
India
Maharashtra and Gujarat textile clusters supply velvet flocking and canvas weaves for export-oriented organizer manufacturers. BIS standards govern domestic product safety while PLI scheme incentives attract component assembly operations. Delhi-NCR serves as the primary consumption hub for mid-range jewelry boxes targeting gift-giving occasions.
Jewelry Organizer Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a fragmented vendor base where no single entity commands decisive share. Digital-native platforms and home furnishings retailers anchor demand aggregation, while fabricators and packaging specialists occupy manufacturing tiers. Three archetypes dominate: platform aggregators with assortment breadth, premium home furnishings brands with design authority, and travel-specialist players with portability engineering. Competitive moves concentrate on geographic expansion through logistics partnerships and portfolio diversification into sustainable material constructions.
Within the platform-aggregator tier, Wayfair exemplifies channel control through digital-native assortment curation spanning price tiers and materials. Among home furnishings specialists, Pottery Barn occupies a position anchored in premium wood and fabric constructions with design-forward positioning. On the travel-specialist vector, Bagsmart represents portability-focused engineering for compartmentalized, lightweight cases. These three entities collectively illustrate how competitive positioning fragments across control points rather than consolidating around manufacturing scale.
| Leading Market Players |
|---|
| Wayfair |
| Ed's Box & Supply |
| Pottery Barn |
| Box and Wrap |
| JewelryPackaging.com |
| Quince |
| Gems on Display |
| Allure Pack |
| Bagsmart |
| Others |
Supply & Pricing Matrix
Guangdong and Zhejiang acrylic substrate clusters feed vacuum-formed shells to United States and European assembly operations, concentrating margin capture in downstream branding and channel control rather than raw material production. This upstream concentration compresses fabricator margins while rewarding aggregators with assortment breadth and logistics scale.
Pricing Analysis
Manual fabrication workflows versus automated laser-cutting systems versus smart manufacturing platforms stratify pricing tiers across the jewelry organizer market. Three-tier pricing structure across premium customizable systems, standardized mid-range constructions, and economy particleboard offerings reflects differentiation by manufacturing precision and material certification grade. Cost compression in budget tiers intensifies because recycled acrylic feedstock volatility and EPA formaldehyde testing overhead squeeze domestic composite wood producers. Small-space urban renters in dense United States metropolitan clusters exhibit highest price sensitivity, while luxury gift buyers demonstrate lowest elasticity.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for acrylic substrate and vacuum-formed shell procurement. Manufacturing draws from concentrated chemical processing hubs in Guangdong and Zhejiang provinces, with secondary fabricator networks in Vietnam and India expanding for fabric liner and anti-tarnish treatment production. Single-source vulnerability in virgin and recycled acrylic formulations creates input cost volatility when MEE dual carbon enforcement disrupts energy-intensive vacuum-forming operations. Distribution runs through digital-native platform aggregators and home furnishings retailers controlling last-mile delivery to convenience-seeking urban consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Jewelry organizer markets reward service-attach strategies as anti-tarnish treatment subscriptions and modular interior upgrade programs expand faster than hardware unit sales alone. Recurring revenue layers from consumable care products and customization services now outpace base product growth trajectories.
For Market Incumbents: Pre-empt platform-aggregator disintermediation by capturing exclusive channel partnerships with home furnishings retailers and investing in automated laser-cutting capacity for mass-customization at scale. CNC programming talent scarcity threatens production expansion timelines; backward integration into FSC-certified wood milling secures supply against EU Green Deal disclosure mandates. Certification investment in REACH-compliant acrylic formulations defends European market access against emerging specialty chemical entrants.
For New Entrants and Emerging Players: Build out white-space positioning in lightweight travel cases engineered for TSA compliance and post-pandemic mobility normalization, where traditional jewelry box incumbents remain underrepresented. Underpenetrated demand concentrates among United States urban professionals resuming business travel patterns. Direct-to-consumer launch through social commerce platforms targeting millennial discovery behavior offers lowest customer acquisition cost versus legacy retail slotting fees.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed platform aggregators and regional fabricator roll-ups approaching holding-period exits. Long-term viability across the analysis window hinges on circularity documentation capabilities and carbon-accounting infrastructure for EU Green Deal compliance. Watch CSRD enforcement intensity as the inflection signal determining which branded portfolios command premium multiples versus stranded regulatory risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Sustainability Repositioning | FSC-certified wood sourcing and recycled acrylic formulations satisfy EU Green Deal disclosure mandates for European market access. |
| Direct-to-Consumer Launch | Social commerce platforms capture millennial discovery behavior faster than legacy home furnishings retail channels. |
| Backward Integration | In-house CNC routing capacity secures customizable interior production against programming talent scarcity. |
| Distribution Channel Expansion | Exclusive partnerships with Wayfair and Pottery Barn anchor assortment placement against aggregator competition. |
| Premium Tier Introduction | Automated laser-cut customizable systems command margin premiums from urban space-constrained buyers. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with product development directors at home furnishings retailers, supply chain managers at acrylic substrate processors, CNC operations leads at wood fabricators, and digital platform category buyers; alongside secondary validation through customs trade records, EPA formaldehyde emission compliance filings, ECHA REACH substance registrations, and EU CSRD disclosure frameworks. Bottom-up demand modeling across product type, material substrate, end-user channel, and price tier segments triangulated against top-down market sizing from production capacity and channel velocity indicators.
Forecast inputs span urban density projections for United States metropolitan clusters, post-pandemic mobility normalization patterns, EU Green Deal regulatory enforcement timelines, and smart manufacturing adoption curves for automated laser-cutting workflows. Segmentation dimensions modeled include product construction type, material substrate certification grade, procurement channel archetype, and price positioning tier across the projection horizon. CAGRs derive from elasticity-adjusted demand curves incorporating substitution effects between wall-mounted, travel case, and traditional jewelry box formats.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated platform aggregators or sustainability-first entrants would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Storage and Organization
Smart Storage Cabinet Market
Home Storage and Organization
Cabinet & Furniture Drawer Slides Market
Home Storage and Organization
Shop Shelving Market
Home Storage and Organization
Shoe Rack Market
Home Storage and Organization
Kitchen Storage Market
Home Storage and Organization
Europe Home Organizers and Storage Market
Home Storage and Organization
Sheds and Outdoor Storage Market
Home Storage and Organization
Regency Shelving Market
Home Storage and Organization
Flush Mount Photo Album Market
Home Storage and Organization
Smart Shoe Cabinet Market
Home Storage and Organization
Display Cabinets Market
Home Storage and Organization
Hong Kong Self-Storage Market
Home Storage and Organization
Closet Organizers Market
Home Storage and Organization
Collapsible Wardrobe Market
Home Storage and Organization
Small Space Furniture Market
Home Storage and Organization
United Kingdom Home Decor Market