
 United States Home Organizers and Storage Market | 2026-2036
United States Home Organizers and Storage Market Size, Share, and Industry Trends Forecast 2026-2036
United States Home Organizers and Storage Market Analytics
Buyer concentration among millennial first-time homeowners is expanding across suburban markets and exurban developments. The Container Store leverages its proprietary closet systems and in-home design services to sustain premium positioning. Lowe's anchors its storage assortment through big-box distribution density and contractor channel relationships. IKEA competes on flat-pack logistics and Scandinavian design positioning at accessible price points.
Home organizers and storage encompass modular containment systems, fixed and adjustable shelving, woven and molded baskets, and lidded containers engineered from polymer resins, engineered wood composites, powder-coated steel, and woven synthetic textiles, primarily serving residential space optimization and inventory management functions. Plastic dominates material volume due to cost scalability and moisture resistance, though wood commands margin concentration in custom closet installations. Kitchen application segments show structural momentum as open-concept floor plans eliminate traditional pantry walls and demand integrated storage solutions.
The Consumer Product Safety Commission governs tip-over stability standards for freestanding shelving, while California's Proposition 65 mandates chemical disclosure labeling on coated metal and composite wood products. The Federal Trade Commission's Green Guides constrain environmental marketing claims on recycled-content storage bins. Stakeholders must monitor evolving state-level extended producer responsibility legislation that could reshape material sourcing obligations and end-of-life collection infrastructure.
Market Dynamics
California's Title 24 energy efficiency standards are reshaping storage product specifications through building code requirements that mandate tighter thermal envelopes and reduced square footage, intensifying demand for space-optimizing containment systems across residential construction corridors.
Growth Catalysts
- Urban Density Pressures:Space-constrained apartment dwellers in Texas metropolitan corridors and California coastal cities are driving adoption of modular containment systems as housing unit sizes compress under zoning restrictions.
- Federal Housing Policy:The Inflation Reduction Act's residential energy rebates are indirectly stimulating storage retrofit demand as homeowners optimize existing square footage rather than expand footprints.
- Polymer Resin Innovation:Advanced molded polymer manufacturing is absorbing recycled feedstocks at scale, enabling cost-competitive moisture-resistant containers that displace traditional woven materials in kitchen and bath applications.
Market Restraints
- Input Cost Volatility:Powder-coated steel and engineered wood composite prices fluctuate with lumber futures and steel tariffs, compressing margins for fixed shelving manufacturers serving the contractor channel.
- Regulatory Friction:California's Proposition 65 mandates chemical disclosure labeling on coated metal products, adding compliance overhead that disadvantages smaller importers lacking dedicated regulatory affairs functions.
- Substitution Threat:Digital inventory management apps and minimalist consumption movements among younger demographics are reducing physical storage needs in urban rental markets.
Strategic Opportunities
- Exurban Development Corridors:First-time millennial homeowners in Texas suburban rings and Florida growth counties represent underpenetrated demand for custom closet installations and garage organization systems.
- Extended Producer Responsibility:Emerging state-level EPR legislation in California and New York could create first-mover advantages for manufacturers building closed-loop collection infrastructure for polymer resin containers.
- Channel Convergence:Direct-to-consumer configurators with augmented reality visualization are bypassing traditional big-box retail, capturing margin previously allocated to distributor markups.
Industry Challenges
- Tip-Over Compliance Burden:The Consumer Product Safety Commission's evolving stability standards for freestanding shelving require ongoing engineering redesign and third-party testing, extending product development cycles.
- Installation Skill Scarcity:Custom closet system deployment depends on certified in-home design consultants and specialized installers, creating bottlenecks in high-growth metropolitan markets where trained labor pools remain shallow.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Home Organizers and Storage Market |
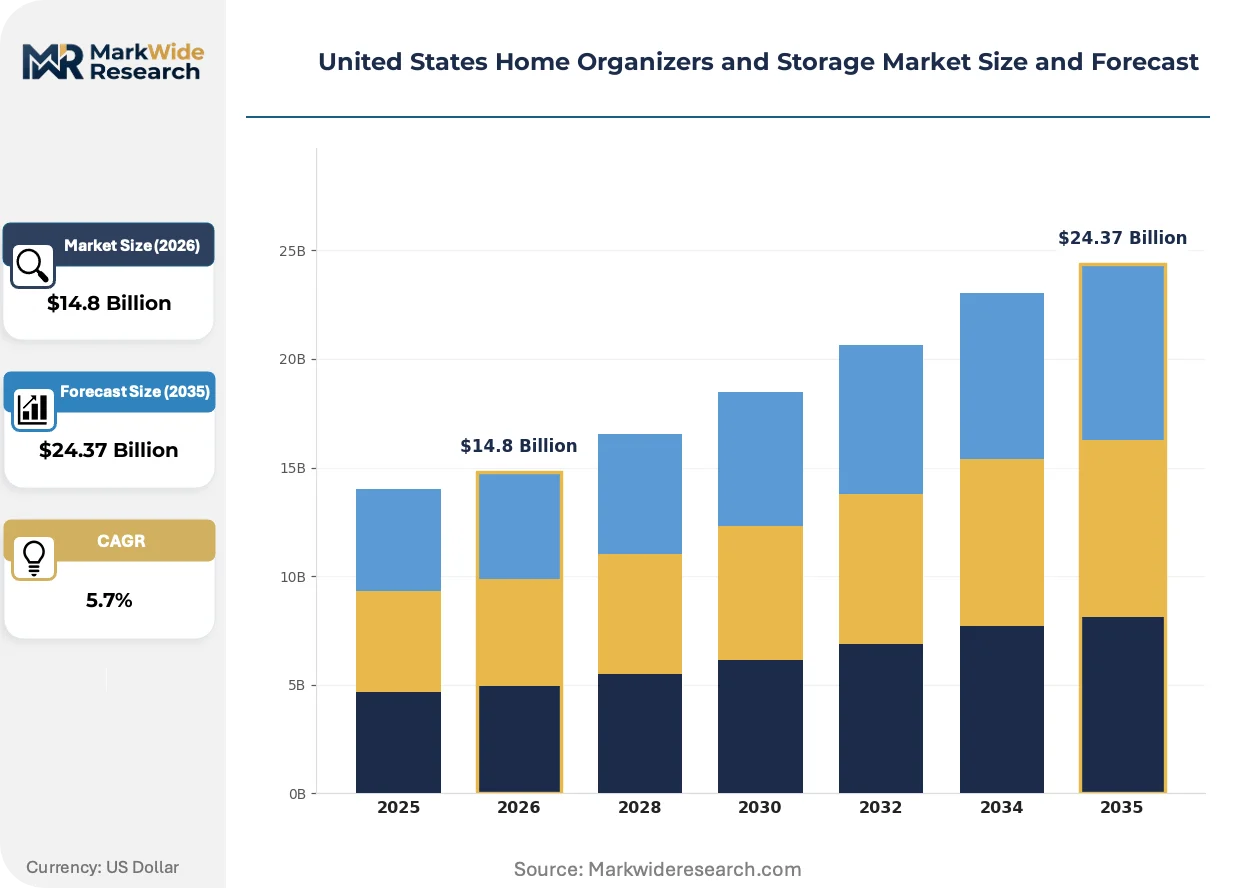
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closet Systems, Shelving Units, Baskets, Storage Boxes Material: Plastic, Wood, Metal, Fabric Application: Residential, Office, Garage, Kitchen Customer Type: Homeowners, Renters, Interior Designers, Retailers |
| Companies Covered | The Container Store, Home Depot, Lowe's, ClosetMaid, California Closets, Wayfair, IKEA, Rubbermaid, Amazon, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Home Organizers and Storage Market Evolving Landscape
Active innovation in the United States home organizers and storage market centers on material substitution, regulatory anticipation, and channel restructuring. Three developments are compressing legacy competitive advantages while opening white space for repositioned entrants.
Smart polymer formulations with embedded antimicrobial additives are absorbing premium positioning in kitchen and bath segments. Moisture-resistant molded resins now command shelf space previously held by coated steel in humid climate zones. Manufacturers adopting these compounds are capturing specification wins from hospitality and multi-family developers prioritizing durability in high-turnover rental units.
The Federal Trade Commission's Green Guides are constraining environmental marketing claims on recycled-content storage bins, forcing substantiation of post-consumer resin percentages. This regulatory tightening is disadvantaging generic imports while rewarding domestic manufacturers with verified supply chain documentation. Private-label brands at major retailers are most exposed to enforcement actions.
Millennial first-time homeowners are bypassing traditional in-store design consultations in favor of self-service digital configuration tools with photorealistic rendering. This behavioral pivot is compressing the sales cycle from weeks to hours while reducing customer acquisition costs for digitally native entrants. The shift is most pronounced in Texas and Florida growth markets where housing turnover rates exceed national averages.
United States Home Organizers and Storage Market Segmentation
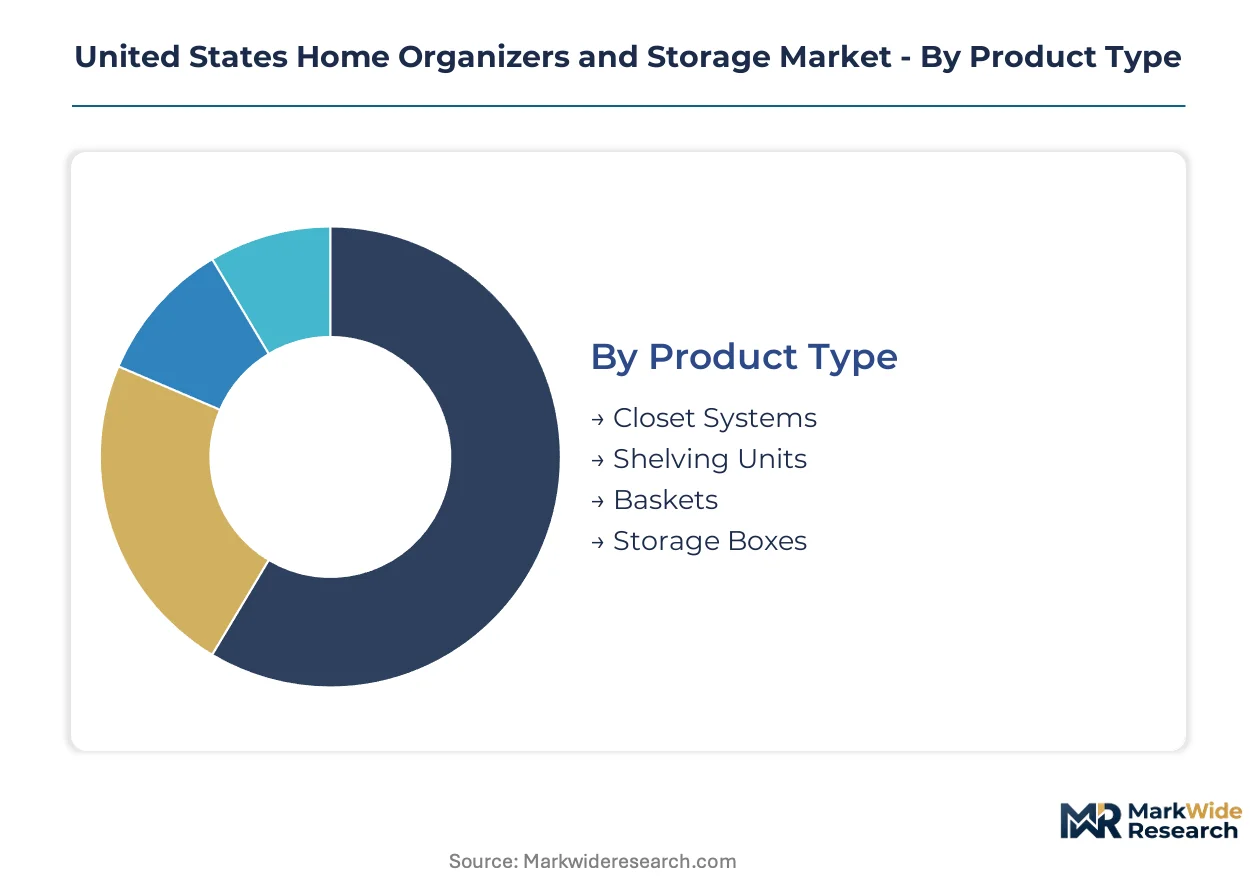
Segmentation in the United States home organizers and storage market reveals how capital deployment, material sourcing, and channel access create divergent margin structures across product categories. Understanding these fault lines helps stakeholders align manufacturing investments with demand concentration patterns in Texas metropolitan corridors and California coastal markets.
Product Type:
Capital intensity varies sharply across product categories, with fixed installations demanding the heaviest upfront tooling and certified labor networks.
- Closet Systems:Engineered wood composites and powder-coated steel frames configured to residential dimensions require substantial CNC fabrication equipment and in-home measurement infrastructure. Demand concentrates among millennial first-time homeowners in Texas suburban rings where new construction and inbound migration cluster, though installation skill scarcity creates fulfillment bottlenecks in high-growth markets.
- Shelving Units:Freestanding and wall-mounted systems span particleboard, solid wood, and steel tube constructions with adjustable bracket mechanisms. The Container Store and Lowe's compete aggressively here through proprietary bracket designs and contractor channel relationships, while tip-over compliance burdens from the Consumer Product Safety Commission extend product development cycles for freestanding variants.
- Baskets:Woven seagrass, rattan, and synthetic fiber constructions serve open-shelf containment with lower capital barriers to entry.
- Storage Boxes:Lidded polymer resin and cardboard composite containers dominate volume through big-box retail distribution.
Closet systems absorb the bulk of installed capacity; storage boxes are expanding most quickly through mass-market channel penetration.
Material:
Cost tier stratification separates premium custom installations from mass-market disposable containment, with material choice directly determining margin capture and regulatory exposure.
- Plastic:Molded polymer resins—polypropylene, ABS, and recycled-content polyethylene—dominate volume through cost scalability and moisture resistance in kitchen and bath applications. Advanced formulations with embedded antimicrobial additives are displacing coated steel in humid climate zones, with polymer resin innovation enabling absorption of recycled feedstocks at scale.
- Wood:Solid hardwood and engineered wood composites command margin concentration in custom closet installations, particularly in California where Title 24 energy efficiency standards intensify demand for space-optimizing built-ins as thermal envelope requirements compress residential square footage.
- Metal:Powder-coated steel tubing and wire shelving face input cost volatility from lumber futures correlation and steel tariff exposure.
- Fabric:Woven synthetic textiles and canvas constructions serve collapsible storage with minimal tooling requirements.
Plastic commands the greatest production volume; wood captures the steepest expansion trajectory in premium residential retrofits.
Application:
Geographic demand concentration tracks housing construction patterns and migration flows, with application-specific requirements shaping specification standards.
- Residential:Whole-home organization spanning bedrooms, living areas, and entryways represents the foundational demand pool, with urban apartment dwellers in California coastal cities driving modular containment adoption as zoning restrictions compress unit sizes.
- Kitchen:Open-concept floor plans eliminating traditional pantry walls have created structural momentum for integrated storage solutions, with moisture-resistant molded resins capturing specification wins from multi-family developers prioritizing durability in high-turnover rental units.
- Garage:Tool storage and seasonal item containment in suburban single-family homes.
- Office:Document storage and workspace organization systems serving remote work arrangements.
Residential applications anchor installed base; kitchen segments are climbing the fastest as floor plan evolution eliminates legacy storage architecture.
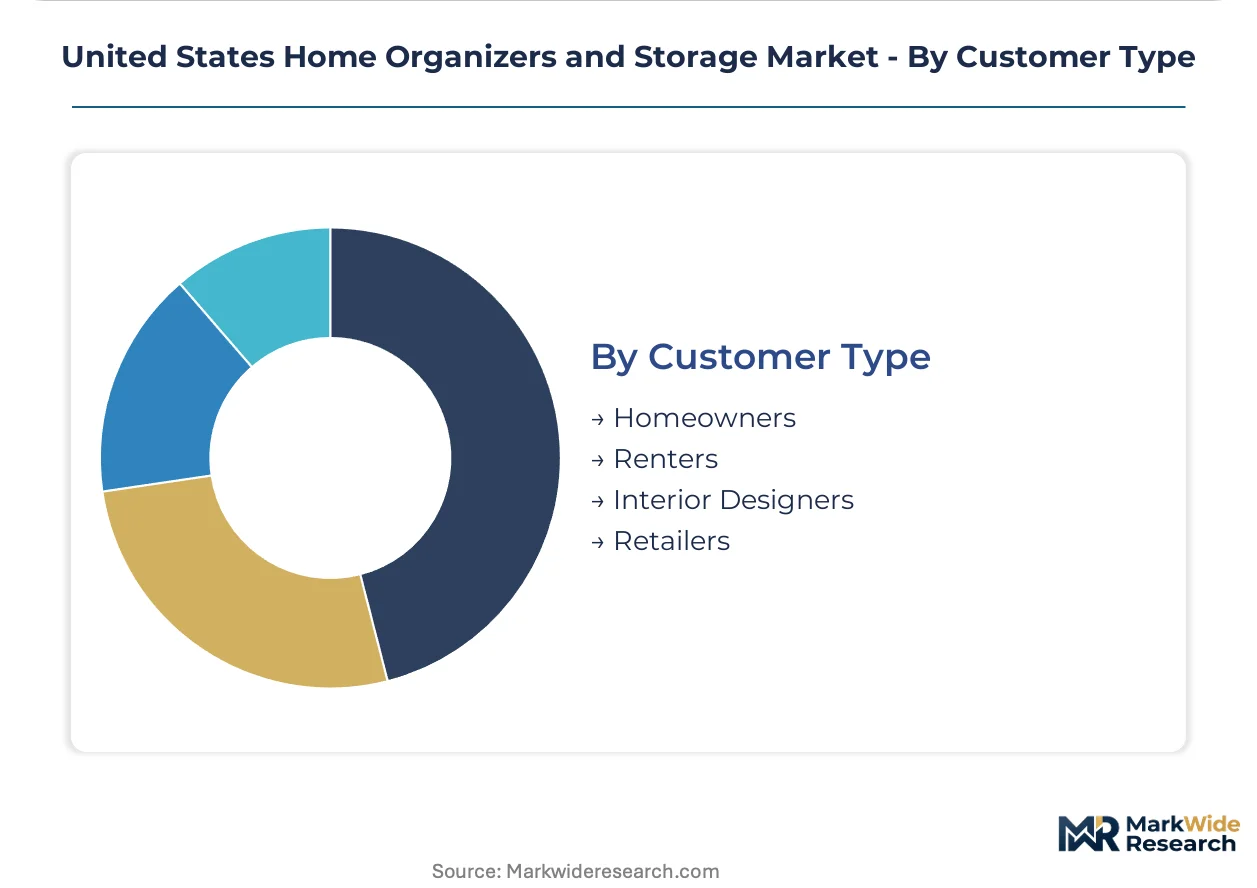
Customer Type:
Procurement authority and decision-making timeline vary dramatically across customer categories, with direct-to-consumer configurators disrupting traditional channel structures.
- Homeowners:Permanent installation decisions with multi-year replacement cycles and willingness to invest in custom closet systems. The Inflation Reduction Act's residential energy rebates are indirectly stimulating storage retrofit demand as this segment optimizes existing square footage rather than expand footprints.
- Interior Designers:Specification authority in high-value residential projects with access to trade-only product lines and margin structures.
- Renters:Portable, non-permanent solutions with price sensitivity and turnover-driven replacement demand.
- Retailers:Private-label sourcing decisions for mass-market distribution with exposure to FTC Green Guides enforcement on recycled-content claims.
Homeowners drive the majority of revenue concentration; interior designers are gaining share fastest as project values escalate in exurban development corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Texas metropolitan corridors and California coastal cities where housing construction and inbound migration cluster, with state-level energy codes and zoning restrictions intensifying space optimization needs across residential markets.
Texas
First-time millennial homeowners in Dallas-Fort Worth and Houston suburban rings drive custom closet installation demand as new construction permits surge. The state's absence of income tax attracts corporate relocations that feed housing turnover. Austin's tech corridor generates specification activity for premium garage organization systems among remote workers optimizing home workspaces.
California
Urban apartment dwellers in Los Angeles and San Francisco adopt modular containment systems as Title 24 energy efficiency standards compress residential square footage. Proposition 65 mandates chemical disclosure labeling on coated metal products, adding compliance overhead for storage manufacturers. San Diego's multi-family development pipeline prioritizes moisture-resistant molded resin solutions for high-turnover rental units.
Florida
Exurban development in Tampa and Orlando growth counties creates underpenetrated demand for whole-home organization systems among relocating retirees and remote workers. The state's humidity accelerates material substitution toward polymer resin containers that displace traditional woven materials. Miami's condominium market specifications favor antimicrobial-additive formulations in kitchen and bath applications.
New York Metro
Space-constrained renters in Brooklyn and Queens drive portable, non-permanent storage solutions with high turnover-driven replacement cycles. New York's emerging extended producer responsibility legislation could reshape material sourcing obligations for polymer resin containers. Westchester County's suburban retrofit market shows momentum for integrated pantry solutions as open-concept renovations eliminate traditional storage walls.
Pacific Northwest
Seattle's density restrictions and Portland's urban growth boundaries intensify demand for vertical storage optimization in compact housing units. Washington's building codes emphasize thermal envelope performance that indirectly shapes built-in storage specifications. The region's sustainability preferences create specification wins for manufacturers with verified recycled-content supply chain documentation.
United States Home Organizers and Storage Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer configurators with augmented reality visualization. The market structure reflects a bifurcated competitive environment where big-box retailers leverage distribution density against specialty retailers emphasizing in-home design services. Three archetypes dominate: scale-driven mass-market suppliers, premium custom installation specialists, and digitally native direct-to-consumer brands. Competitive moves center on channel convergence strategies and certified installer network expansion.
Within the specialty retail tier, The Container Store and California Closets exemplify premium positioning through proprietary closet systems and in-home design consultation infrastructure. Among mass-market retailers, Home Depot and Lowe's occupy positions anchored by contractor channel relationships and big-box distribution density. IKEA represents the accessible design archetype competing on flat-pack logistics and Scandinavian aesthetic positioning.
| Leading Market Players |
|---|
| The Container Store |
| Home Depot |
| Lowe's |
| ClosetMaid |
| California Closets |
| Wayfair |
| IKEA |
| Rubbermaid |
| Amazon |
| Others |
Value Network & Pricing Analysis
Polymer resin feedstock costs cascade through three distinct pricing tiers as virgin polypropylene and recycled polyethylene move from Gulf Coast petrochemical complexes through injection molders to big-box retail shelves. Powder-coated steel tubing from domestic mills feeds premium custom closet installations, while flat-pack particleboard draws from engineered wood composite manufacturers concentrated in the Southeast.
Pricing Analysis
Volume-mass polymer containers compete on landed cost per cubic foot, while engineered wood closet systems capture margin through customization depth and certified installation bundling. Price differentiation hinges on moisture-resistance certification tier and brand equity in design consultation. Cost compression in standard-grade shelving intensifies as steel tariff exposure feeds through to contractor channel quotes. Renters in urban coastal markets exhibit highest price sensitivity; millennial first-time homeowners in Texas suburban corridors show lowest sensitivity for built-in system investments.
Supply Chain Analysis
Regional distribution centers in Dallas-Fort Worth and Ontario, California anchor hub-and-spoke patterns serving Texas metropolitan corridors and West Coast markets respectively. Manufacturing concentrates in China for molded polymer components, Vietnam for woven synthetic textiles, and domestic Southeast facilities for engineered wood composites. Raw material dependencies span Saudi-origin polymer resins, Appalachian hardwood feedstocks, and Chinese steel coil. Tariff exposure on imported wire shelving creates margin volatility for mass-market suppliers. Distribution runs through big-box retail DCs, direct-to-consumer fulfillment nodes, and contractor supply houses in parallel channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Installation labor scarcity functions as the binding capacity constraint, propping pricing power for certified in-home design networks while extending fulfillment timelines across high-growth metropolitan markets.
For Market Incumbents: Acquire certified installer networks in Dallas-Fort Worth and Houston suburban rings to lock in fulfillment capacity ahead of competitor expansion. Consolidate regional distribution center footprints to reduce last-mile cost exposure against direct-to-consumer entrants. Defend against digitally native configurators by embedding augmented reality tools into existing in-home consultation workflows. For New Entrants and Emerging Players: The mid-market price gap between The Container Store's premium positioning and IKEA's flat-pack economy tier offers white-space capture opportunity. Target Florida exurban growth counties where housing turnover exceeds national averages and established players lack installer density. Pursue channel entry through Amazon's home services marketplace to bypass capital-intensive retail footprint requirements. For Investors and Strategic Acquirers: Extended producer responsibility legislation passage in California or New York is the leading indicator that closed-loop collection infrastructure will separate viable acquisition targets from stranded asset risks. Favor manufacturers with verified post-consumer resin supply chain documentation and backward integration into polymer compounding. Watch for FTC Green Guides enforcement actions against private-label brands as signal of regulatory compliance premium widening.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Installer Network Expansion | Captures bottlenecked labor capacity in Texas and Florida growth corridors ahead of competitor access. |
| Post-Consumer Resin Supply Chain Verification | Insulates against FTC Green Guides enforcement exposure while commanding specification preference from sustainability-focused developers. |
| Augmented Reality Configuration Platform | Compresses sales cycles from weeks to hours in millennial first-time homeowner segments bypassing traditional retail. |
| Regional Distribution Center Consolidation | Reduces landed cost per unit in California and Texas markets where housing construction clusters. |
| Antimicrobial Polymer Formulation Patent Portfolio | Captures specification wins from multi-family developers prioritizing durability in high-turnover rental units. |
Research Methodology
Independent corroboration across in-home design consultants, big-box category buyers, polymer resin procurement managers, and certified installation contractors underwrites the qualitative findings in this study. Primary interviews with storage product manufacturers, multi-family developers, and contractor channel distributors combined with secondary validation from SEC 10-K filings, customs import records, and building permit databases. Bottom-up unit shipment estimates triangulated against top-down construction spending allocations across residential application segments.
Comparable-period anchoring to historical housing starts, migration flow data, and retail square footage expansion rates established the forecast window baseline. The analytical framework models demand across product type, material composition, application, and customer procurement authority dimensions throughout the projection horizon. CAGRs derived from regression analysis against macroeconomic drivers including household formation rates and residential fixed investment. Forecast inputs incorporate Title 24 energy code adoption timelines and extended producer responsibility legislative tracking.
Inputs from building permit databases and retail point-of-sale systems were available through the study window; gaps in real-time installer capacity utilization introduce uncertainty bands around custom closet system penetration assumptions. Forecasts reflect documented assumptions regarding housing construction trajectories and regulatory implementation schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Storage and Organization
Kitchen Storage Organization Market
Home Storage and Organization
Shop Shelving Market
Home Storage and Organization
Collapsible Wardrobe Market
Home Storage and Organization
Toy Storage Market
Home Storage and Organization
Hong Kong Self-Storage Market
Home Storage and Organization
Slipcases Market
Home Storage and Organization
Flush Mount Photo Album Market
Home Storage and Organization
Regency Shelving Market
Home Storage and Organization
Middle East and Africa Kitchen Storage Market
Home Storage and Organization
Scandinavia Self-Storage Market
Home Storage and Organization
Shoe Rack Market
Home Storage and Organization
Smart Shoe Cabinet Market
Home Storage and Organization
Sheds and Outdoor Storage Market
Home Storage and Organization
Shelf Display Trays Market
Home Storage and Organization
Shoe Storage and Organizers Market
Home Storage and Organization
Jewelry Organizer Market