
 Asia-Pacific Digital Home Locker Market | 2026-2036
Asia-Pacific Digital Home Locker Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Digital Home Locker Market Insights
Biometric authentication tier is collapsing into mainstream pricing as fingerprint and facial recognition modules drop below legacy keypad costs. Logistan Technologies leverages its India manufacturing base to supply modular systems across Southeast Asia. Intelligent Locker Solutions anchors its position through captive cloud software that integrates with property management platforms. TAGSYS competes on RFID traceability layers that track custody chains from courier to resident.
Asia-Pacific digital home lockers are electromechanical storage units with embedded IoT connectivity, typically featuring steel alloy enclosures between 1.2mm and 2.0mm gauge, electronic locking mechanisms, and cellular or Wi-Fi communication modules for remote access management and delivery notifications. These systems serve residential and commercial buildings by automating secure parcel receipt, eliminating failed delivery attempts, and reducing concierge labor overhead. Smart lockers lead volume shipments due to e-commerce logistics integration, while biometric scanners command premium positioning as property developers differentiate amenity packages. Package lockers sustain the fastest growth trajectory among product types, driven by apartment construction booms and delivery service partnerships in Australia and Singapore.
Japan's METI enforces electrical appliance safety standards that dictate EMI shielding and fail-safe unlocking protocols for networked locker systems. Australia's ACCC consumer protection frameworks and Singapore's IMDA cybersecurity labeling requirements shape product certification pathways and import compliance costs. India's BIS mandatory registration scheme for electronic goods creates a compliance threshold that filters out unbranded imports. Stakeholders must monitor evolving data localization mandates across ASEAN members, as resident biometric storage regulations will determine cloud architecture investments and cross-border service delivery models.
Market Dynamics
The Asia-Pacific digital home locker market is being restructured by the convergence of biometric authentication cost collapse and mandatory data localization mandates across ASEAN member states, forcing vendors to re-architect cloud infrastructure and hardware sourcing strategies.
Growth Catalysts
- India's PLI scheme for electronics:Domestic production incentives for IoT-enabled components reduce import dependency and accelerate locker assembly localization for Southeast Asian export markets.
- Contactless parcel receipt protocols:Residential developers in Japan and South Korea deploy smart lockers as standard amenities, driven by e-commerce logistics integration and concierge labor reduction targets.
- Biometric module cost deflation:Fingerprint and facial recognition hardware now undercuts legacy keypad systems, eliminating the price barrier to premium authentication tiers in mass-market deployments.
Market Restraints
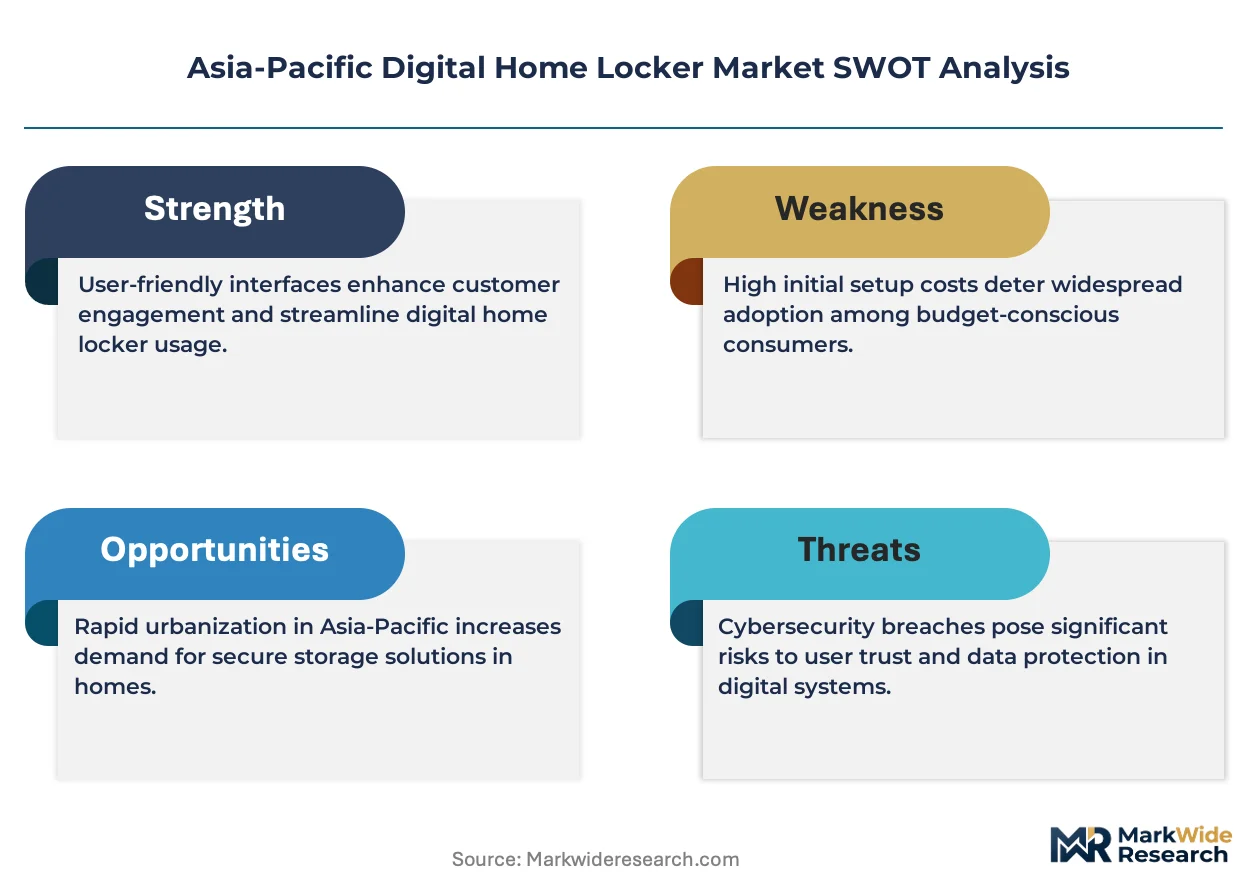
- Steel alloy input volatility:Enclosure gauge specifications between 1.2mm and 2.0mm expose manufacturers to commodity price swings in cold-rolled steel, compressing margin predictability on fixed-price municipal contracts.
- China supply concentration:Cellular and Wi-Fi communication module production clusters in Shenzhen and Dongguan create single-source vulnerability for ASEAN integrators seeking supply chain redundancy.
- Biometric data localization mandates:Evolving resident storage regulations across ASEAN members fragment cloud architecture investments and block cross-border service delivery models for multinational operators.
Strategic Opportunities
- Tier-two Chinese urban penetration:E-commerce density and last-mile infrastructure in Chengdu, Hangzhou, and Wuhan remain underdeployed relative to saturated Beijing and Shanghai markets.
- RFID custody chain integration:Courier-to-resident traceability layers create premium positioning for property management platforms seeking differentiated amenity packages.
- Australia and Singapore construction booms:Apartment development pipelines and delivery service partnerships sustain package locker demand acceleration unmatched elsewhere in the region.
Industry Challenges
- EMI shielding certification timelines:Japan's METI electrical appliance safety standards impose extended testing protocols for networked locker systems, delaying product launch windows.
- Legacy property management system integration:Captive cloud software platforms require custom API development to interface with incumbent building automation infrastructure, inflating deployment costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Digital Home Locker Market |
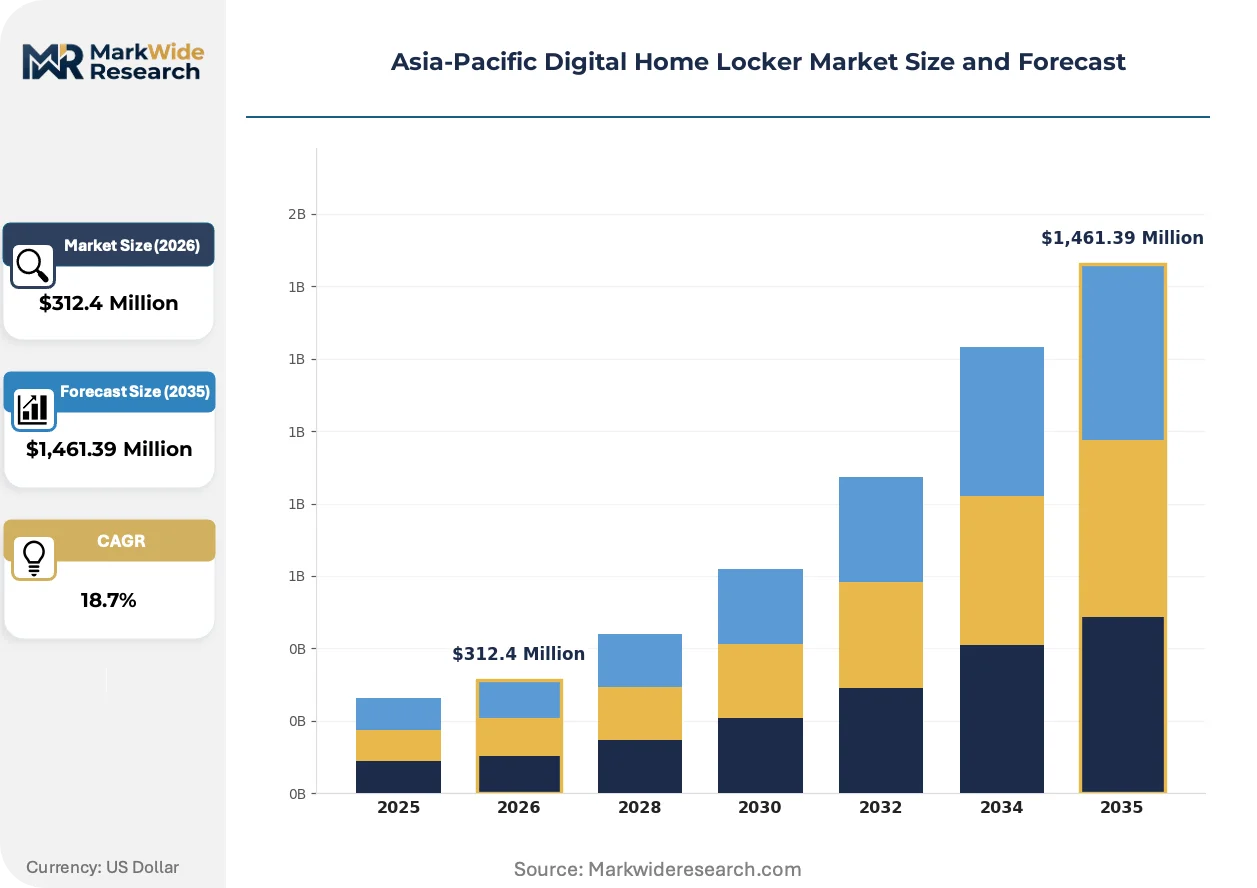
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,461.39 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Lockers, Package Lockers, Personal Lockers, High-Security Lockers End User: Residential Users, Property Managers, Delivery Services, Retail Customers Installation Type: Built-in Systems, Freestanding Units, Wall-mounted Options, Modular Designs Security Features: Biometric Scanners, RFID Technology, Digital Keypads, Surveillance Integration |
| Companies Covered | Logistan Technologies, Intelligent Locker Solutions, TAGSYS, Quadient, Parcel Pending, SmartBox, KEBA AG, Aiko Group, Cannon Safe, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Digital Home Locker Market Trends and Innovations
Biometric authentication architectures are fragmenting market segmentation as hardware costs collapse and regulatory frameworks force localization. Three developments are restructuring competitive positioning and procurement patterns across the region.
Edge-based facial recognition is fragmenting the authentication stack by processing biometric templates locally rather than transmitting data to centralized servers. Property developers in Singapore and Australia are specifying on-device processing to preempt cybersecurity labeling compliance costs under IMDA and ACCC frameworks. This shift is fragmenting vendor business models away from recurring cloud subscription revenue toward higher upfront hardware margins and firmware maintenance contracts.
Singapore's IMDA cybersecurity labeling scheme and Australia's ACCC consumer protection frameworks are mandating disclosure of data handling practices for IoT-connected storage systems. Manufacturers must now document encryption standards and breach notification protocols before market entry, extending certification timelines by four to six months. Premium-tier suppliers are responding by pre-certifying entire product families to capture specification mandates from risk-averse institutional buyers.
Leasing structures are displacing capital purchase models as building operators seek to transfer obsolescence risk to locker providers. Japanese and South Korean residential REITs now favor ten-year service contracts bundling hardware, software, and maintenance over upfront equipment procurement. This shift concentrates vendor selection authority with facilities management platforms rather than construction-phase general contractors, lengthening sales cycles but improving lifetime value capture for integrated service providers.
Asia-Pacific Digital Home Locker Market Segmentation
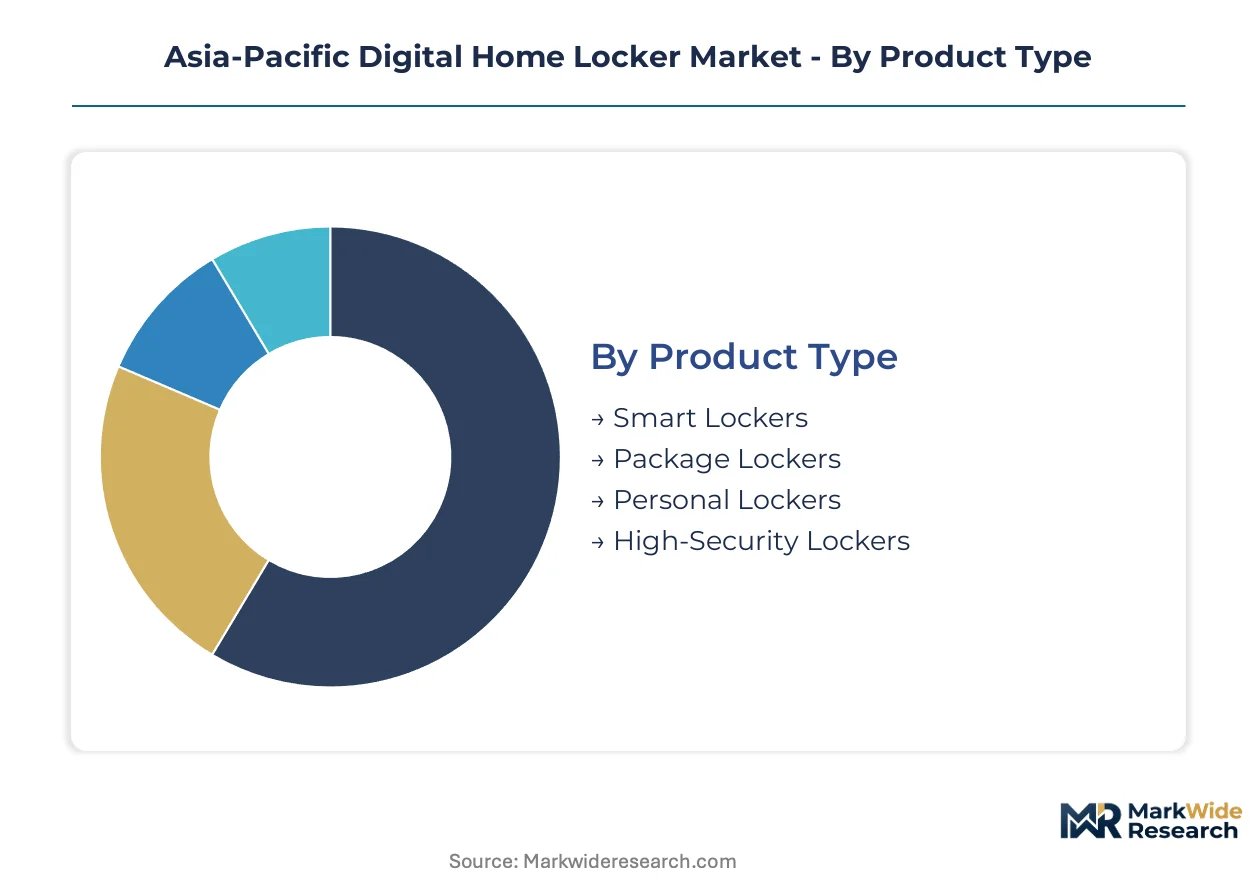
Product architecture and security tier selection in Asia-Pacific digital home lockers diverge sharply between export manufacturing hubs and domestic consumption markets. Procurement patterns across Japan, South Korea, and tier-one Chinese cities favor premium authentication layers, while Southeast Asian deployments prioritize cost-optimized package handling density.
Product Type:
Domestic demand concentrates in Japan and South Korea for biometric-enabled residential systems, whereas Indian and Vietnamese manufacturing output supplies freestanding and modular formats across Southeast Asian export channels.
- Smart Lockers:These units embed cellular or Wi-Fi communication modules for real-time delivery notifications and remote access management. Property developers in Tokyo and Seoul specify smart lockers as standard amenities in new apartment construction, driven by contactless parcel receipt protocols and concierge labor reduction targets. Smart lockers command the established base.
- Package Lockers:Steel alloy enclosures between 1.2mm and 2.0mm gauge optimize for high-turnover e-commerce logistics integration. Australia's apartment construction pipeline and Singapore's delivery service partnerships sustain demand acceleration unmatched elsewhere in the region. The steepest expansion runs through package lockers.
- Personal Lockers:Compact footprints serve individual residential units or small commercial premises with localized access control.
- High-Security Lockers:Reinforced gauge specifications and multi-factor authentication address banking and pharmaceutical custody requirements in Hong Kong and Singapore.
Smart lockers anchor installed capacity across mature Northeast Asian markets. Package lockers gain share fastest where e-commerce penetration outpaces last-mile infrastructure.
End User:
Customer procurement authority is shifting from construction-phase general contractors toward facilities management platforms as leasing models displace capital purchases.
- Residential Users:Individual apartment dwellers access lockers through mobile applications or biometric credentials for automated parcel receipt. Tier-one Chinese cities exhibit highest user density, though Chengdu, Hangzhou, and Wuhan remain underdeployed relative to saturated Beijing and Shanghai markets.
- Property Managers:Japanese and South Korean residential REITs now favor ten-year service contracts bundling hardware, software, and maintenance over upfront equipment procurement, concentrating vendor selection authority with integrated service providers.
- Delivery Services:Courier-to-resident traceability requirements drive RFID integration specifications.
- Retail Customers:Click-and-collect fulfillment models in Australian urban centers generate demand for temporary storage handoff points.
Property managers control specification authority in Northeast Asia. Delivery services are expanding fastest as logistics platforms integrate locker networks into route optimization.
Installation Type:
Physical configuration choices reflect building age, space constraints, and developer willingness to absorb construction-phase integration costs versus post-occupancy retrofit.
- Built-in Systems:These require coordination with structural framing and MEP routing during construction. New apartment developments across Australia and Singapore specify built-in formats to maximize lobby space efficiency and aesthetic integration.
- Freestanding Units:Self-supporting steel enclosures enable rapid deployment without structural modification. India's domestic manufacturing base supplies modular freestanding systems for Southeast Asian markets seeking supply chain redundancy outside China.
- Wall-mounted Options:Compact footprints suit retrofit installations in aging residential stock.
- Modular Designs:Scalable cell configurations allow capacity expansion without full system replacement.
Built-in systems dominate premium new construction. Freestanding units climb fastest where retrofit demand outpaces development pipelines.
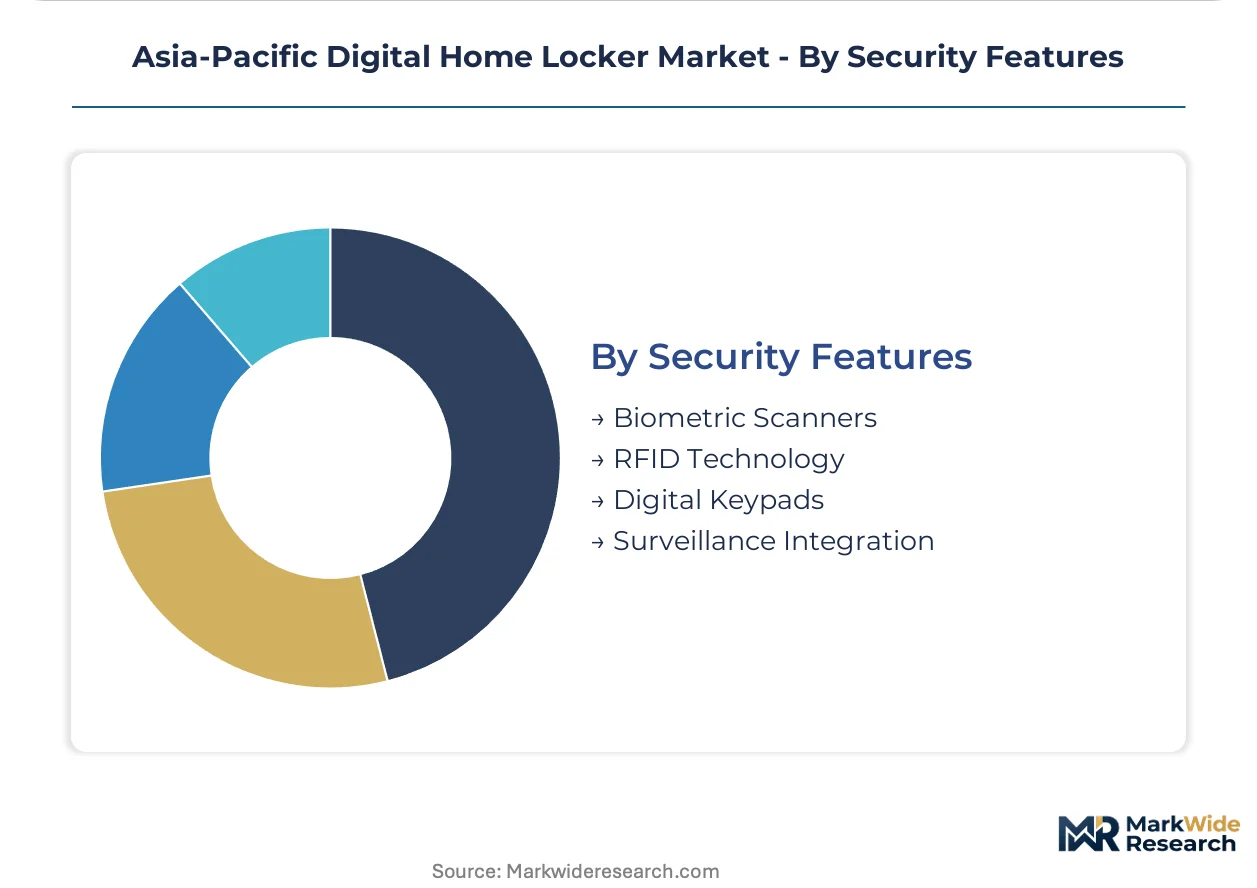
Security Features:
Authentication technology selection is fragmenting as hardware cost deflation collides with data localization mandates across ASEAN members.
- Biometric Scanners:Fingerprint and facial recognition modules now undercut legacy keypad costs, eliminating price barriers to premium tiers in mass-market deployments. Singapore and Australian developers specify on-device processing to preempt IMDA cybersecurity labeling and ACCC compliance costs.
- RFID Technology:Courier-to-resident custody chain traceability creates premium positioning for property management platforms. TAGSYS competes on this layer across Southeast Asian markets seeking differentiated amenity packages.
- Digital Keypads:Legacy PIN entry persists in cost-sensitive deployments where biometric module sourcing remains constrained.
- Surveillance Integration:Camera and sensor fusion addresses liability concerns in high-value custody applications.
Biometric scanners are penetrating fastest as module costs collapse. RFID technology anchors logistics-integrated deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentration in China's Yangtze and Pearl River Delta manufacturing clusters shapes regional availability, while demand fragmentation across Northeast Asia, Southeast Asia, and Oceania creates divergent procurement patterns for authentication tiers and installation formats.
China
Tier-one cities of Beijing, Shanghai, Shenzhen, and Guangzhou exhibit saturated smart locker penetration from e-commerce logistics integration, while Chengdu, Hangzhou, and Wuhan remain underdeployed relative to their delivery density. MIIT cybersecurity standards and SAMR product certification requirements govern networked storage system market entry. Shenzhen and Dongguan cellular module production clusters supply ASEAN integrators seeking supply chain redundancy.
Japan
Tokyo and Osaka residential REITs mandate smart lockers as standard amenities in new apartment construction, driven by contactless parcel receipt protocols and concierge labor reduction targets. METI electrical appliance safety standards enforce EMI shielding and fail-safe unlocking protocols that extend product certification timelines. Kanto and Kansai industrial corridors concentrate domestic system integration capacity for premium biometric-enabled deployments.
South Korea
Seoul Capital Area apartment construction pipelines integrate package lockers as differentiated amenity offerings, with delivery service partnerships accelerating network density. MFDS data handling guidelines and national cybersecurity frameworks shape biometric authentication architecture decisions. Busan-Ulsan manufacturing zones supply steel alloy enclosures for domestic and export markets.
India
Maharashtra and Karnataka manufacturing hubs leverage PLI scheme incentives for electronics to localize IoT-enabled locker component production and reduce import dependency. BIS mandatory registration for electronic goods filters unbranded imports and elevates compliance thresholds. Tamil Nadu and Telangana assembly plants supply modular freestanding systems across Southeast Asian export channels.
Australia
Sydney and Melbourne apartment construction booms sustain package locker demand acceleration unmatched elsewhere in the region, with delivery service partnerships driving route optimization integration. ACCC consumer protection frameworks mandate disclosure of data handling practices for IoT-connected storage systems. New South Wales and Victoria property developers specify built-in formats to maximize lobby space efficiency.
Asia-Pacific Digital Home Locker Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with Northeast Asian vendors commanding premium authentication tiers and Indian manufacturers capturing Southeast Asian volume through modular cost-optimized formats. The vendor base separates into three strategic archetypes: integrated platform providers bundling captive cloud software, component specialists supplying biometric and RFID modules, and regional fabricators leveraging domestic manufacturing incentives for export competitiveness. M&A activity concentrates on cloud software capability acquisition, while capacity expansion targets Indian PLI-subsidized assembly for ASEAN market supply.
Within the integrated platform tier, Logistan Technologies and Intelligent Locker Solutions exemplify contrasting geographic anchoring strategies. Logistan Technologies leverages its India manufacturing base to supply modular systems across Southeast Asia, occupying a position shaped by PLI scheme economics and ASEAN export logistics. Intelligent Locker Solutions anchors its competitive stance through captive cloud software that integrates with property management platforms, representing the software-forward archetype prevalent in developed Northeast Asian markets. TAGSYS sits within the traceability specialist tier, competing on RFID custody chain layers that track possession from courier to resident across Southeast Asian deployments seeking differentiated amenity packages.
| Leading Market Players |
|---|
| Logistan Technologies |
| Intelligent Locker Solutions |
| TAGSYS |
| Quadient |
| Parcel Pending |
| SmartBox |
| KEBA AG |
| Aiko Group |
| Cannon Safe |
| Others |
Pricing and Supply Chain Analysis
Biometric module cost deflation is simultaneously shifting component sourcing toward Indian PLI-subsidized facilities and collapsing the premium tier entry threshold across Southeast Asian deployments. This substitution dynamic compresses margin buffers for legacy keypad manufacturers while rewarding vendors with captive semiconductor procurement channels.
Pricing Analysis
Japan's METI electrical appliance safety standards dictate the pricing tier structure across Northeast Asian deployments. Three-tier pricing stratifies across biometric-enabled premium systems, RFID-integrated standard units, and keypad-based economy configurations. Price differentiation hinges on certification grade under IMDA cybersecurity labeling and after-sales service bundling. Cost compression in economy tiers is intensifying because Indian manufacturing subsidies undercut Chinese module costs. Property managers in Australian residential REITs exhibit lowest price sensitivity due to ten-year service contract preferences, while Southeast Asian retrofit buyers remain most cost-constrained.
Supply Chain Analysis
Container availability fluctuations on the Shanghai-Singapore trade lane expose ASEAN integrators to inbound logistics cost volatility. Manufacturing gravity centers on China's Shenzhen and Dongguan cellular module clusters, South Korea's Busan-Ulsan steel alloy corridors, and India's Maharashtra-Karnataka electronics assembly hubs. The supply chain draws from cold-rolled steel gauge stock, biometric sensor arrays, and Wi-Fi communication chipsets. Single-source vulnerability in Shenzhen module production creates systemic exposure for vendors lacking dual-sourcing arrangements. Distribution runs through facilities management platforms in Japan and South Korea, general contractors in Australian new construction, and regional distributors across Southeast Asian retrofit markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in authentication architecture divergence, as biometric cost collapse and data localization mandates simultaneously create tiered service niches and geographic specialization requirements.
For Market Incumbents: Secure captive cloud software integration with property management platforms to defend against modular hardware commoditization. Lock in ten-year service contract templates with Japanese and South Korean residential REITs before leasing models fully displace capital purchases. Invest in edge-based facial recognition firmware to preempt IMDA cybersecurity labeling compliance costs in Singapore and Australian specifications. For New Entrants and Emerging Players: Anchor in India's PLI-subsidized manufacturing corridors to supply cost-optimized freestanding units across Southeast Asian export channels. Target tier-two Chinese urban penetration in Chengdu, Hangzhou, and Wuhan where e-commerce density outpaces locker deployment. Pursue RFID custody chain integration as the primary go-to-market angle for property developers seeking differentiated amenity packages. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated platform providers with captive cloud capabilities over pure hardware fabricators. Long-term viability hinges on software subscription retention and biometric data localization compliance infrastructure. Acquisition target archetype: regional fabricators with Indian PLI-qualified assembly capacity and nascent firmware development teams. The signal to watch is ASEAN member state biometric storage regulation harmonization, which would trigger cross-border service model feasibility and vendor re-rating.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Based Biometric Processing | On-device facial recognition preempts IMDA cybersecurity labeling costs in Singapore deployments. |
| PLI-Subsidized Manufacturing Scale-Up | Indian electronics incentives reduce component import dependency for Southeast Asian export supply. |
| Captive Cloud Software Development | Property management platform integration secures recurring revenue against hardware commoditization. |
| RFID Custody Chain Integration | Courier-to-resident traceability layers differentiate amenity packages in Australian premium residential. |
| Leasing Model Transition | Ten-year service contracts transfer obsolescence risk and concentrate vendor selection authority. |
Research Methodology
A spread of perspectives from property technology procurement officers, residential REIT asset managers, logistics platform integration specialists, and steel alloy enclosure fabricators converged on the working assumptions. Primary interview inputs combined with secondary validation against BIS mandatory registration databases, MIIT cybersecurity standards filings, ACCC consumer protection guidance documents, and Japan METI electrical appliance safety protocols. Bottom-up unit deployment estimates triangulated against top-down e-commerce logistics infrastructure spending patterns.
Segmentation dimensions modeled encompass product architecture, authentication technology tier, installation format, and end-user procurement authority across the projection horizon. CAGRs derived from logistic density trajectories, apartment construction pipeline data, and biometric module cost deflation curves. Industry-specific forecast inputs incorporated PLI scheme subsidy utilization rates and evolving ASEAN data localization mandate implementation timelines.
Material uncertainties — steel alloy commodity price volatility, biometric storage regulation fragmentation, and cellular module supply concentration — sit outside the modeled envelope. Forecasts reflect documented assumptions about e-commerce penetration continuity and residential construction cycle persistence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Storage and Organization
Smart Shoe Cabinet Market
Home Storage and Organization
Shoe Rack Market
Home Storage and Organization
Smart Storage Cabinet Market
Home Storage and Organization
Clothes Closets Market
Home Storage and Organization
Shelf Display Trays Market
Home Storage and Organization
Hong Kong Self-Storage Market
Home Storage and Organization
Middle East and Africa Kitchen Storage Market
Home Storage and Organization
Europe Home Organizers and Storage Market
Home Storage and Organization
Shop Shelving Market
Home Storage and Organization
Small Space Furniture Market
Home Storage and Organization
Flatware Holders and Organizers Market
Home Storage and Organization
Toy Storage Market
Home Storage and Organization
Sheds and Outdoor Storage Market
Home Storage and Organization
Slipcases Market
Home Storage and Organization
Scandinavia Self-Storage Market
Home Storage and Organization
Kitchen Storage Market