
 Closet Organizers Market | 2026-2036
Closet Organizers Market Size, Share, and Industry Trends Forecast 2026-2036
Closet Organizers Market Analysis
Multifamily residential construction is repositioning closet organizers from aftermarket accessories to standard amenity packages. California Closets dominates the premium installed segment through its franchised design-consultant network. IKEA competes on flat-pack logistics and price-accessible modularity across mass-market channels. ClosetMaid sustains wholesale dominance in big-box retail through wire-system standardization and builder-program relationships.
Closet organizers are integrated storage systems comprising shelving, hanging rods, drawer modules, and accessory hardware, typically fabricated from engineered wood substrates, powder-coated steel, or injection-molded polymers, designed to maximize cubic efficiency within fixed wardrobe enclosures. Wood-based systems command the highest installed-value per linear foot but face pressure from metal-wire alternatives in entry-level residential specifications. The commercial end-user segment, encompassing hospitality and corporate fit-outs, trails residential volume but carries superior project margins and repeat-specification potential through architect and interior-designer channels.
The EPA oversees formaldehyde emissions standards for composite wood products under TSCA Title VI, directly affecting panel-material sourcing for domestic manufacturers. ISO 9001 quality-management certification functions as a de facto qualification threshold for commercial and institutional procurement tenders. Stakeholders must monitor evolving state-level building codes and sustainability disclosure requirements as these increasingly filter down to interior-finish specifications and supplier qualification criteria.
Market Dynamics
Residential developers are embedding closet systems as standard specifications rather than aftermarket upgrades, compressing the traditional two-step purchase cycle into single-point procurement decisions during new construction.
Growth Catalysts
- California Title 24 energy codes:Broader building efficiency mandates indirectly elevate material performance standards for interior finishes, pushing developers toward certified panel substrates that incidentally improve closet system specifications.
- Multifamily residential construction:Built-to-rent developers in Sun Belt metropolitan areas treat organized storage as competitive amenity packages, standardizing modular systems across unit types.
- Wire-system standardization:Powder-coated steel configurations reduce installed cost per linear foot while meeting durability benchmarks for entry-level housing starts.
Market Restraints
- Engineered wood substrate volatility:Formaldehyde-compliant composite panels face input cost pressure from resin chemistry fluctuations and timber supply concentration in Pacific Northwest and Southeast US mills.
- Installation labor scarcity:Skilled carpentry for custom wood-based systems concentrates in high-cost metropolitan markets, limiting geographic scalability of premium installed offerings.
- Metal-wire aesthetic ceiling:Powder-coated steel alternatives face specification resistance in luxury residential segments where visible hardware conflicts with interior design intent.
Strategic Opportunities
- Hospitality renovation cycles:Hotel property improvement plans in Florida and Arizona represent repeat-specification channels through interior designer relationships.
- Flat-pack logistics innovation:E-commerce fulfillment networks enable direct-to-consumer modular systems bypassing traditional big-box retail distribution.
- Corporate fit-out standardization:Workplace storage specifications for hybrid office configurations create architect-driven demand for reconfigurable systems.
Industry Challenges
- ISO 9001 certification timelines:Commercial and institutional procurement tenders require quality-management documentation that smaller fabricators struggle to maintain.
- Legacy builder-program relationships:Established wholesale channels lock in specification access for incumbent suppliers, raising customer acquisition costs for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Closet Organizers Market |
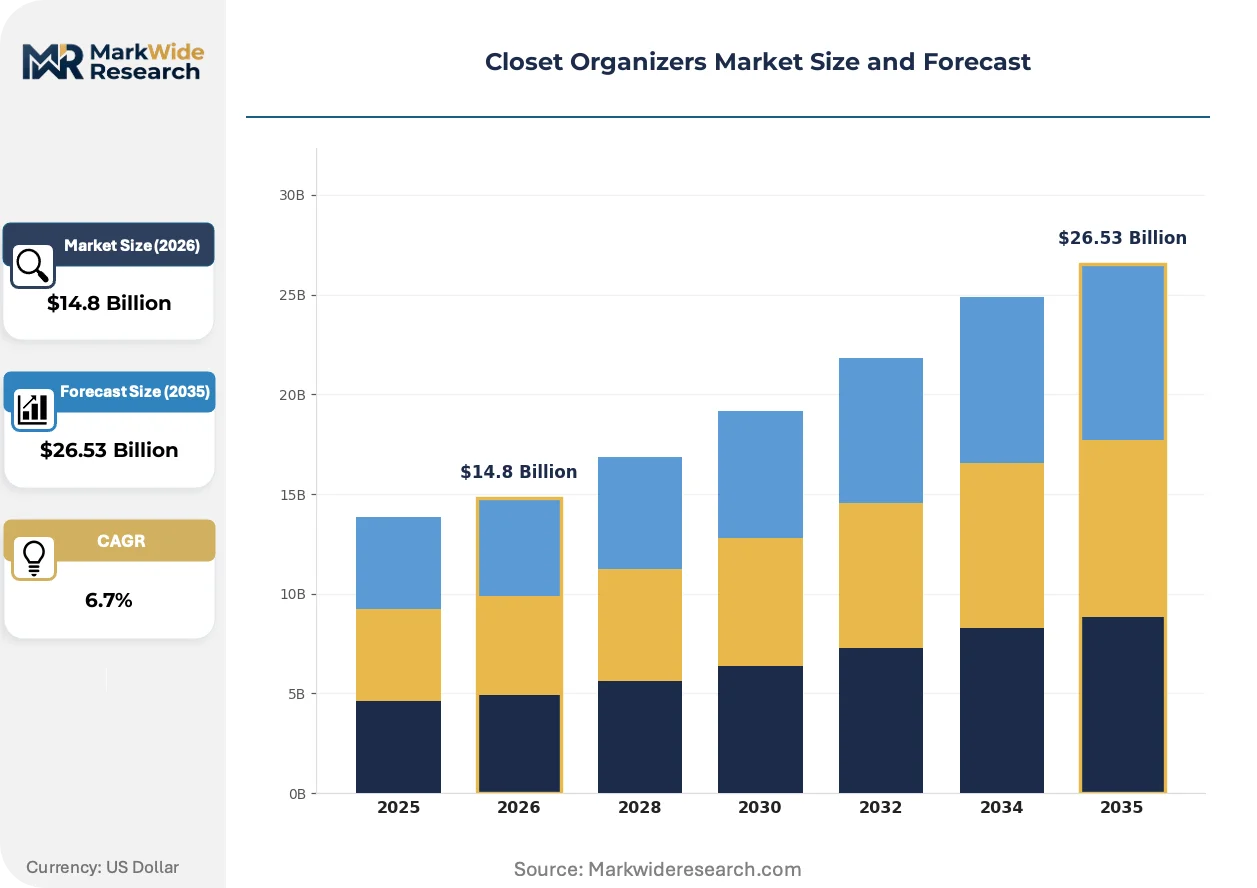
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hanging Organizers, Drawer Organizers, Shelf Dividers, Shoe Racks Material: Wood, Plastic, Metal, Fabric End User: Residential, Commercial, Retail, Offices Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Closet Factory, Organized Living, IKEA, OPPEIN, EasyClosets, California Closets, The Stow Company, Oppolia, ClosetMaid, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Closet Organizers Market Emerging Trajectories
Material science advances and procurement model compression are redefining competitive advantage away from pure product differentiation toward integrated specification and fulfillment capabilities.
Melamine-faced particleboard with low-emission binders is absorbing specification share from solid wood alternatives in mid-market residential construction. Production homebuilders in Texas and North Carolina specify these substrates for cost predictability and California Air Resources Board compliance. The technology is absorbing volume that previously required premium carpentry labor, compressing regional price differentials between installed and DIY segments.
EPA TSCA Title VI formaldehyde emissions standards for composite wood products now function as baseline qualification rather than differentiation. Domestic manufacturers must maintain third-party certification chains for panel sourcing, raising compliance overhead. Hospitality developers in California and New York now require documentation disclosure as standard bid-package elements, filtering supplier pools before design review.
Builder-direct procurement is consolidating specification authority away from individual homeowners. National production builders in Phoenix, Atlanta, and Dallas-Fort Worth negotiate system-wide closet packages during land development phase, treating storage as commodity input rather than design feature. This pattern is most visible in master-planned communities where option packages standardize across hundreds of units.
Closet Organizers Market Segmentation
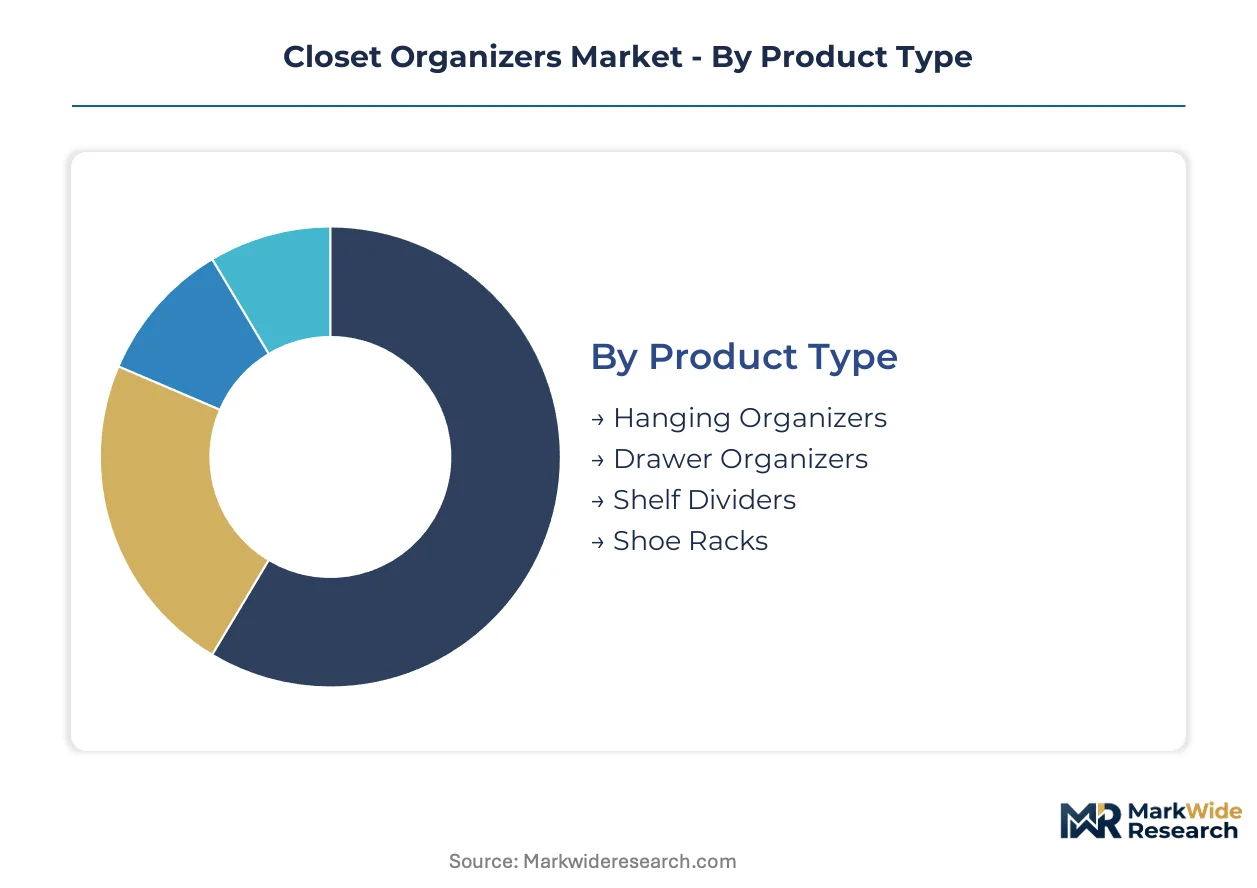
Closet organizer procurement splits sharply between specification-driven commercial channels and discretionary residential purchases. Material choices cascade through distribution economics, while end-user context determines whether systems ship flat-packed or install-ready.
Product Type:
Supply concentration favors modular components over fixed installations, with fabricators optimizing SKU economics around interchangeable sub-assemblies.
- Hanging Organizers:Fabric or canvas-based suspended units with reinforced rod pockets and cascading tier configurations. Demand concentrates in Sun Belt rental markets where built-in closet depth falls below national averages, forcing vertical storage solutions. California Title 24 compliance pressures indirectly elevate durability specifications for textile substrates.
- Drawer Organizers:Injection-molded polymer or bamboo-composite modular bins with non-slip bases and stackable geometry. Phoenix and Dallas-Fort Worth production homebuilders specify these as standard amenity packages, compressing aftermarket upgrade rates.
- Shelf Dividers:Powder-coated steel or acrylic vertical separators for existing wire shelving systems.
- Shoe Racks:Slanted tier configurations in engineered wood or ventilated polymer for climate-sensitive storage.
Today's leader: Hanging Organizers. Tomorrow's challenger: Drawer Organizers.
Material:
Cost tier stratification separates premium installed systems from mass-market alternatives, with resin chemistry volatility driving substitution patterns.
- Wood:Melamine-faced particleboard with TSCA Title VI-compliant binders, plus solid hardwood edge-banding for visible surfaces. Texas and North Carolina production builders specify these substrates for cost predictability, though skilled carpentry scarcity limits premium custom penetration to high-cost metropolitan markets.
- Metal:Powder-coated steel wire systems with epoxy finishes for corrosion resistance. Entry-level residential specifications in Sun Belt markets favor these configurations for installed cost efficiency, despite aesthetic limitations in luxury segments.
- Plastic:Injection-molded polypropylene or ABS modular components for DIY assembly.
- Fabric:Non-woven polyester or canvas-based collapsible systems for seasonal storage.
Metal commands volume. Wood captures margin.
End User:
Application context determines specification authority, with institutional procurement filtering supplier pools before design review.
- Residential:Single-family and multifamily installations spanning production builder specifications to aftermarket upgrades. Master-planned communities in Atlanta and Phoenix treat closet systems as commodity inputs negotiated during land development phase.
- Commercial:Hospitality property improvement plans and corporate fit-outs with repeat-specification potential through interior designer relationships. Florida and Arizona hotel renovation cycles sustain project margins superior to residential volume.
- Retail:Display fixture and back-of-house storage for apparel and accessories merchandising.
- Offices:Workplace locker systems and personal storage for hybrid office configurations.
Residential drives volume. Commercial sustains margin.
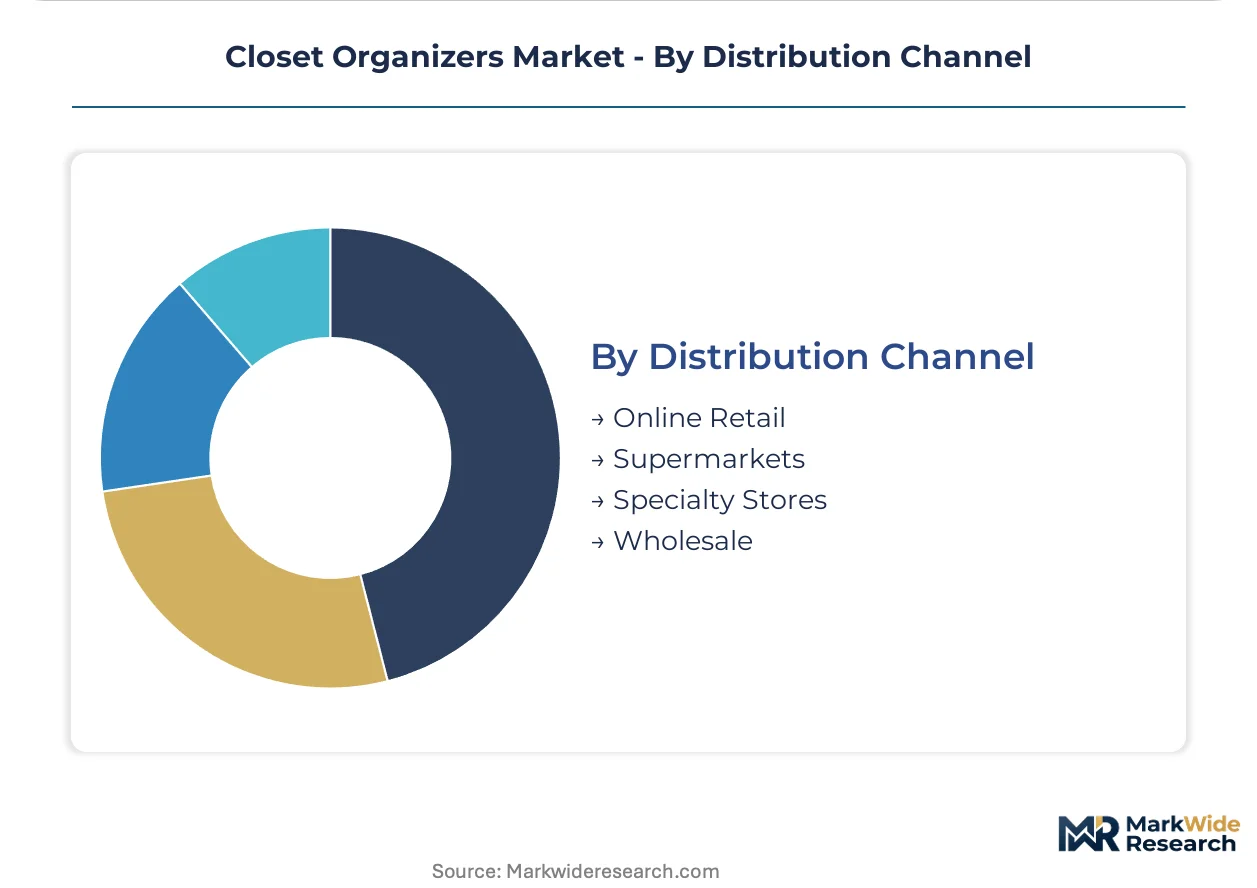
Distribution Channel:
Customer type bifurcates between specification professionals and end consumers, with fulfillment infrastructure determining competitive access.
- Online Retail:Direct-to-consumer flat-pack logistics bypassing traditional big-box intermediaries. E-commerce networks enable modular system penetration into secondary markets lacking specialty store presence.
- Specialty Stores:Design-consultant channels with installed-service capabilities and franchise territorial exclusivity. Premium segments concentrate here through in-home measurement and custom fabrication workflows.
- Supermarkets:Mass-market wire systems and basic polymer organizers for impulse and seasonal purchase.
- Wholesale:Builder-program relationships with national production homebuilders for new construction specifications.
Wholesale locks in new construction. Online retail is gaining share fastest in replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping closet organizer production geography, with fabricators migrating toward jurisdictions offering lower compliance costs for composite wood substrates while maintaining access to major consumption centers.
United States
Sun Belt metropolitan areas including Phoenix, Atlanta, and Dallas-Fort Worth drive residential specification volume through master-planned community development. EPA TSCA Title VI formaldehyde emissions standards filter supplier pools for domestic panel sourcing. Texas and North Carolina production homebuilders negotiate system-wide closet packages during land development phase, treating organized storage as commodity input.
China
Guangdong and Zhejiang provinces anchor flat-pack manufacturing capacity serving export markets through cost-optimized logistics networks. GB standards for indoor air quality and formaldehyde emissions in wood-based panels create compliance differentiation between export-grade and domestic-market production. Yangtze River Delta clusters specialize in melamine-faced particleboard fabrication for mid-market residential specifications.
Germany
Baden-Württemberg and North Rhine-Westphalia concentrate precision-engineered storage system manufacturing with emphasis on modular reconfigurability. REACH chemical regulations and CE marking requirements elevate material disclosure standards for panel substrates entering commercial fit-out channels. Bavaria-based fabricators serve architect-driven hospitality renovation cycles across European markets.
India
Maharashtra and Gujarat states exhibit residential construction growth in Mumbai and Ahmedabad metropolitan corridors, with organized storage penetrating mid-market housing segments. BIS certification for engineered wood products functions as procurement qualification threshold for institutional developers. Karnataka's Bangalore cluster supports interior fit-out contractors serving corporate workplace reconfiguration demand.
Canada
Ontario and British Columbia provinces sustain demand through multi-unit residential construction in Toronto and Vancouver markets. Health Canada guidelines on volatile organic compound emissions from composite wood products align with cross-border supply chain integration with US fabricators. Quebec-based distributors leverage proximity to Northeast US corridor for specification access.
Closet Organizers Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium installed-service networks commanding margin concentration while mass-market channels favor scale-driven logistics players. The vendor base organizes around three strategic archetypes: design-consultant franchises with territorial exclusivity, flat-pack specialists optimizing e-commerce fulfillment, and wholesale suppliers locked into builder-program relationships. M&A activity concentrates on regional design-service networks, while capacity expansion focuses on automated panel processing for cost predictability in entry-level specifications.
Among US-based installed-service specialists, California Closets and Closet Factory exemplify the franchise-network archetype with design-consultant workflows. IKEA anchors the flat-pack mass-market vector through logistics-optimized modularity. ClosetMaid occupies a position within wholesale builder-program channels, while Chinese specialists OPPEIN and Oppolia represent Asia-Pacific manufacturing scale serving export specifications. The Stow Company and Organized Living sit within the mid-market modular systems tier, with EasyClosets exemplifying direct-to-consumer digital distribution.
| Leading Market Players |
|---|
| Closet Factory |
| Organized Living |
| IKEA |
| OPPEIN |
| EasyClosets |
| California Closets |
| The Stow Company |
| Oppolia |
| ClosetMaid |
| Others |
Supply Flow & Price Mechanics
Resin chemistry fluctuations in formaldehyde-compliant composite panels cascade through three distinct pricing tiers, with Pacific Northwest and Southeast US mill concentration amplifying cost volatility for mid-market melamine-faced particleboard specifications.
Pricing Analysis
Distributor margin layers separate premium installed-service networks from mass-market flat-pack channels, with design-consultant workflows capturing 40-60 point markups over wholesale builder-program pricing. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with EPA TSCA Title VI compliance functioning as a baseline qualifier rather than premium justification. Cost compression in entry-level wire systems intensifies because powder-coated steel alternatives face specification resistance in luxury residential segments. Production homebuilders exhibit highest price sensitivity, while hospitality developers prioritize repeat-specification reliability over unit cost.
Supply Chain Analysis
ISO 9001 certification gating filters supplier pools before commercial tender participation, with documentation overhead raising effective barriers for smaller fabricators. Panel substrate supply concentrates in China, Germany, and the United States, with Guangdong and Zhejiang provinces anchoring flat-pack export capacity. Raw material dependencies encompass timber feedstock from Pacific Northwest mills, resin chemistry from Gulf Coast petrochemical complexes, and powder-coated steel from Ohio Valley metal fabrication clusters. Single-source vulnerability persists in low-emission binder formulations compliant with California Air Resources Board mandates. Distribution runs through builder-program relationships for new construction, while e-commerce fulfillment networks penetrate replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in closet organizers hinges on melamine-faced particleboard absorption of solid wood volume, compressing regional price differentials while elevating certified substrate premiums.
For Market Incumbents: Extend territorial exclusivity in design-consultant networks to capture hospitality renovation cycles in Florida and Arizona, while automating panel processing for cost predictability in entry-level specifications threatened by flat-pack e-commerce entrants. Backward integration into captive resin chemistry supply hedges against Pacific Northwest timber concentration. For New Entrants and Emerging Players: Direct-to-consumer digital routes unlock geographic white space in secondary markets lacking California Closets or Closet Factory franchise presence, with modular flat-pack systems penetrating Sun Belt rental markets where built-in closet depth constraints favor vertical storage solutions. Target multifamily built-to-rent developers in Atlanta and Phoenix through specification-as-amenity positioning. For Investors and Strategic Acquirers: Consolidation pressure builds where regional design-service networks lack ISO 9001 documentation capabilities required for commercial procurement tenders. Long-term viability favors fabricators with automated panel processing and cross-border supply chain integration between US specification channels and Chinese manufacturing scale. Watch hospitality property improvement plan acceleration in Florida as inflection indicator for repeat-specification channel health.| Strategic Initiative | Industry Significance |
|---|---|
| Builder-Program Relationship Deepening | Locks in specification access for national production homebuilders in Phoenix and Dallas-Fort Worth. |
| Flat-Pack Logistics Optimization | Enables direct-to-consumer penetration into secondary markets lacking specialty store presence. |
| ISO 9001 Certification Investment | Qualifies fabricators for commercial and institutional procurement tenders requiring documentation. |
| Hospitality Designer Network Cultivation | Captures repeat-specification potential through Florida and Arizona hotel renovation cycles. |
| Automated Panel Processing Scale-Up | Compresses cost predictability for entry-level melamine-faced particleboard specifications. |
Methodological Framework
Multiple input streams — executive interviews with production homebuilder procurement directors, franchise design-consultant workflow analysis, and customs records from USITC — were reconciled against EPA TSCA Title VI certification databases and builder-program specification disclosures. Primary engagement encompassed residential developers, hospitality interior designers, wholesale distribution managers, and panel substrate procurement leads at engineered wood mills. Secondary validation drew from US Census Bureau construction spending data, California Air Resources Board compliance filings, and SEC 10-K disclosures from publicly traded building products companies. Bottom-up unit economics and top-down construction spending aggregates were triangulated.
Historical specification penetration rates were cross-referenced against panel input cost trajectories and franchise territory expansion patterns. Segmentation dimensions modeled encompass product type, material substrate, end-user application, and distribution channel complexity. CAGRs were derived from fitted trend extrapolation adjusted for regulatory compliance phase-in schedules. Forecast inputs included multifamily housing starts in Sun Belt metropolitan areas and hospitality property improvement plan cycles in Florida and Arizona.
The model assumes a particular technology adoption path; alternative pathways for low-emission binder chemistry or reconfigurable modular hardware would alter the outlook. Forecasts reflect assumptions about California Title 24 code propagation and EPA enforcement intensity. A model refresh is warranted upon material change in Sun Belt housing start velocity or hospitality renovation financing availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Storage and Organization
Scandinavia Self-Storage Market
Home Storage and Organization
Wardrobe Boxes Market
Home Storage and Organization
Hong Kong Self-Storage Market
Home Storage and Organization
Toy Storage Market
Home Storage and Organization
United Kingdom Home Decor Market
Home Storage and Organization
Regency Shelving Market
Home Storage and Organization
Shoe Storage and Organizers Market
Home Storage and Organization
Display Cabinets Market
Home Storage and Organization
Shop Shelving Market
Home Storage and Organization
Tool Chest Market
Home Storage and Organization
Sheds and Outdoor Storage Market
Home Storage and Organization
Small Space Furniture Market
Home Storage and Organization
Collapsible Wardrobe Market
Home Storage and Organization
Clothes Closets Market
Home Storage and Organization
Flatware Holders and Organizers Market
Home Storage and Organization
Middle East and Africa Kitchen Storage Market