
 Tool Chest Market | 2026-2036
Tool Chest Market Size, Share, and Industry Trends Forecast 2026-2036
Tool Chest Market Analytics
Equipment leasing and pay-per-use financing is reconfiguring procurement patterns for mid-sized trade fleets that previously deferred bulk purchases. Snap-on Incorporated leverages captive finance subsidiaries to lock in multi-year contractor relationships. Milwaukee Tool sustains premium positioning through battery-integrated storage systems that dominate cordless platform ecosystems. Stanley Black & Decker competes across price tiers with modular stackable configurations that reduce replacement cycle friction.
A tool chest is a lockable storage unit engineered to organize, protect, and transport hand tools, power tools, and accessories, typically constructed from cold-rolled steel with ball-bearing drawer slides rated for loads exceeding 100 pounds per compartment. Its primary commercial purpose centers on reducing tool loss, improving jobsite efficiency, and ensuring compliance with workplace safety protocols that mandate secure equipment storage. Rolling tool chests lead volume shipments due to mobility requirements in automotive and construction environments, while aluminum variants represent the fastest-expanding material category as weight-sensitive service trades prioritize transportability. Professional contractors anchor margin pools through specification-grade purchases, whereas DIY enthusiasts occupy a mature, promotion-driven segment with lower attachment rates for accessories.
OSHA lockout/tagout standards and EPA surface coating regulations shape steel fabrication processes and finishing chemistry choices for domestic manufacturers. ISO 9001 quality management certifications function as baseline qualifiers for industrial procurement contracts, filtering supplier pools before technical evaluation begins. Stakeholders must monitor how state-level right-to-repair legislation alters tool ownership patterns and consequently storage investment cycles.
Market Dynamics
Fleet standardization programs among professional contractors are compressing replacement cycles and elevating specification-grade procurement above price-driven purchasing in the tool chest market.
Growth Catalysts
- OSHA workplace safety mandates:Federal lockout/tagout standards mandate secure equipment storage on active jobsites, converting compliance expenditure into category pull-through. Construction and automotive repair facilities face audit-driven procurement acceleration.
- Battery-integrated storage systems:Cordless power tool ecosystems from Milwaukee and DeWalt create platform-locked accessory demand, with charging-capable chests commanding attachment rate premiums among electrical and mechanical trades.
- Texas and California construction corridors:Residential and commercial build-out concentration in these states generates localized demand density that supports distributor inventory pre-positioning and same-day fulfillment infrastructure.
Market Restraints
- Cold-rolled steel price volatility:Input material cost swings compress fabrication margins and destabilize manufacturer pricing commitments to multi-year fleet contracts.
- Aluminum supply concentration:Primary aluminum smelting capacity clusters in China and the Gulf states, exposing domestic fabricators to tariff and logistics disruption cascades.
- Specification-grade certification timelines:ISO 9001 and ANSI qualification processes extend 12-18 months, filtering supplier pools and limiting new entrant velocity in industrial procurement channels.
Strategic Opportunities
- Service trade weight sensitivity:HVAC and elevator maintenance technicians in dense urban markets prioritize aluminum variants that reduce transport burden across multi-story facilities.
- Equipment leasing penetration:Pay-per-use financing reconfigures mid-sized fleet procurement from capital expenditure to operational budgeting, opening access to premium specification-grade product.
- State right-to-repair legislation:Extended tool ownership mandates in California and Minnesota lengthen storage investment cycles and elevate durability specifications in replacement purchasing.
Industry Challenges
- Ball-bearing slide fabrication expertise:Precision machining capability for 100+ pound load-rated drawer mechanisms concentrates among legacy metalworking suppliers, constraining quality scaling.
- EPA surface coating compliance:VOC emission restrictions on powder coat and paint finishing processes require capital-intensive abatement equipment and chemistry reformulation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tool Chest Market |
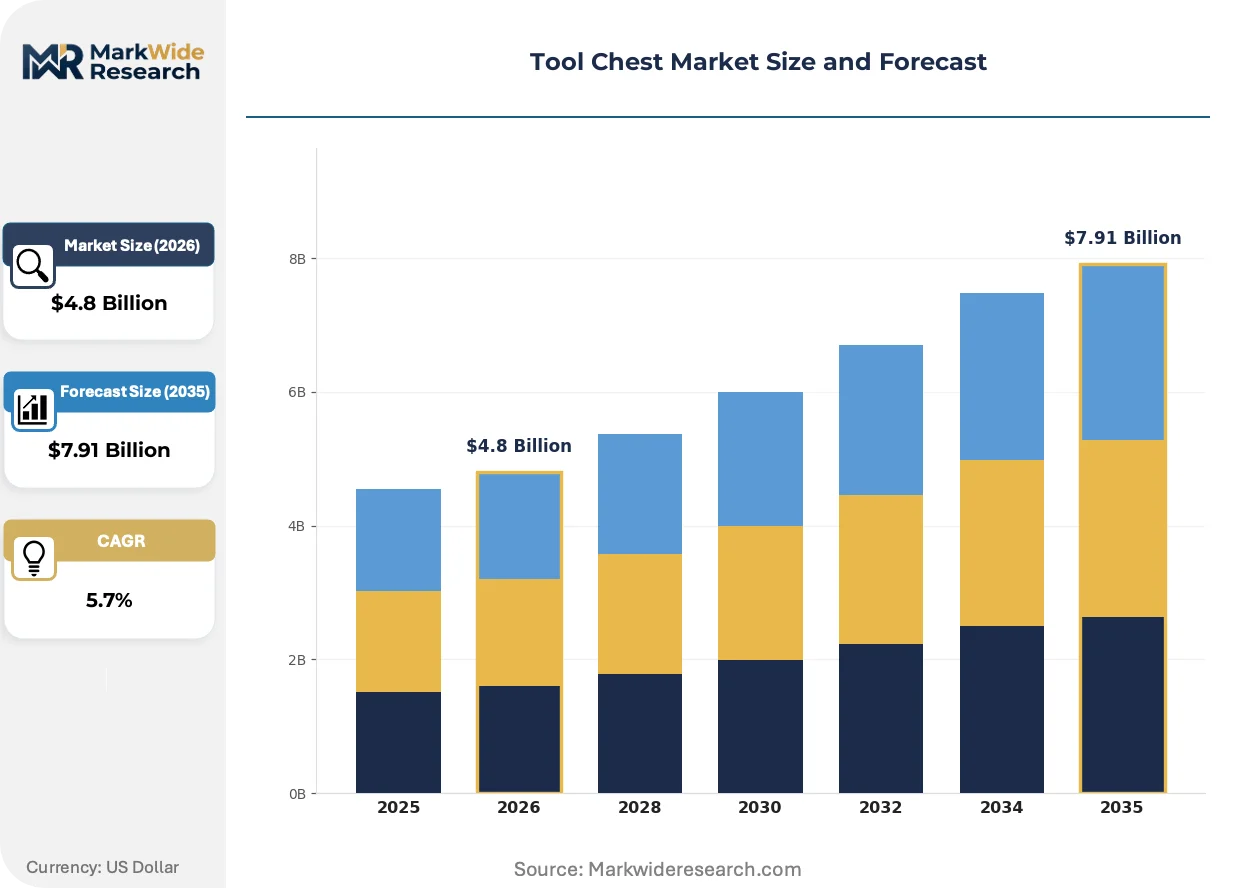
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Tool Chests, Rolling Tool Chests, Wall-Mounted Tool Chests, Stationary Tool Chests Material: Steel, Aluminum, Plastic, Wood End User: DIY Enthusiasts, Professional Contractors, Tradespeople, Industrial Users Size: Small, Medium, Large, Extra Large |
| Companies Covered | Snap-on Incorporated, RIDGID, Stanley Black & Decker, Keter Group, Matco Tools, Apex Tool Group, Klein Tools, Homak Manufacturing, Milwaukee Tool, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tool Chest Market Evolving Landscape
Digital inventory tracking and connected workspace technologies are redefining how contractors manage tool accountability and fleet utilization across dispersed jobsites.
RFID and Bluetooth-enabled tool chests are digitizing asset management for mechanical and electrical contractors operating multi-crew deployments. Large fleet operators in Texas and California are piloting these systems to reduce loss rates and compress tool location time. Real-time inventory visibility is digitizing procurement planning, shifting reorder triggers from physical audits to automated threshold alerts.
OSHA lockout/tagout enforcement is tightening secure storage requirements for energized equipment maintenance. The standard mandates tamper-evident locking mechanisms on tool storage within arc flash and hazardous energy boundaries. Electrical contractors and industrial facility managers are responding by specifying chests with integrated hasp systems and serialized lock compatibility.
Contractor buying committees are consolidating vendor relationships to reduce procurement administrative burden and secure volume pricing. Mid-sized mechanical and HVAC trade fleets are displacing fragmented spot purchasing with multi-year supply agreements anchored by captive finance subsidiaries. This concentration is most visible in the Southwest and Southeast construction markets where fleet scale thresholds trigger preferred pricing tiers.
Tool Chest Market Segmentation
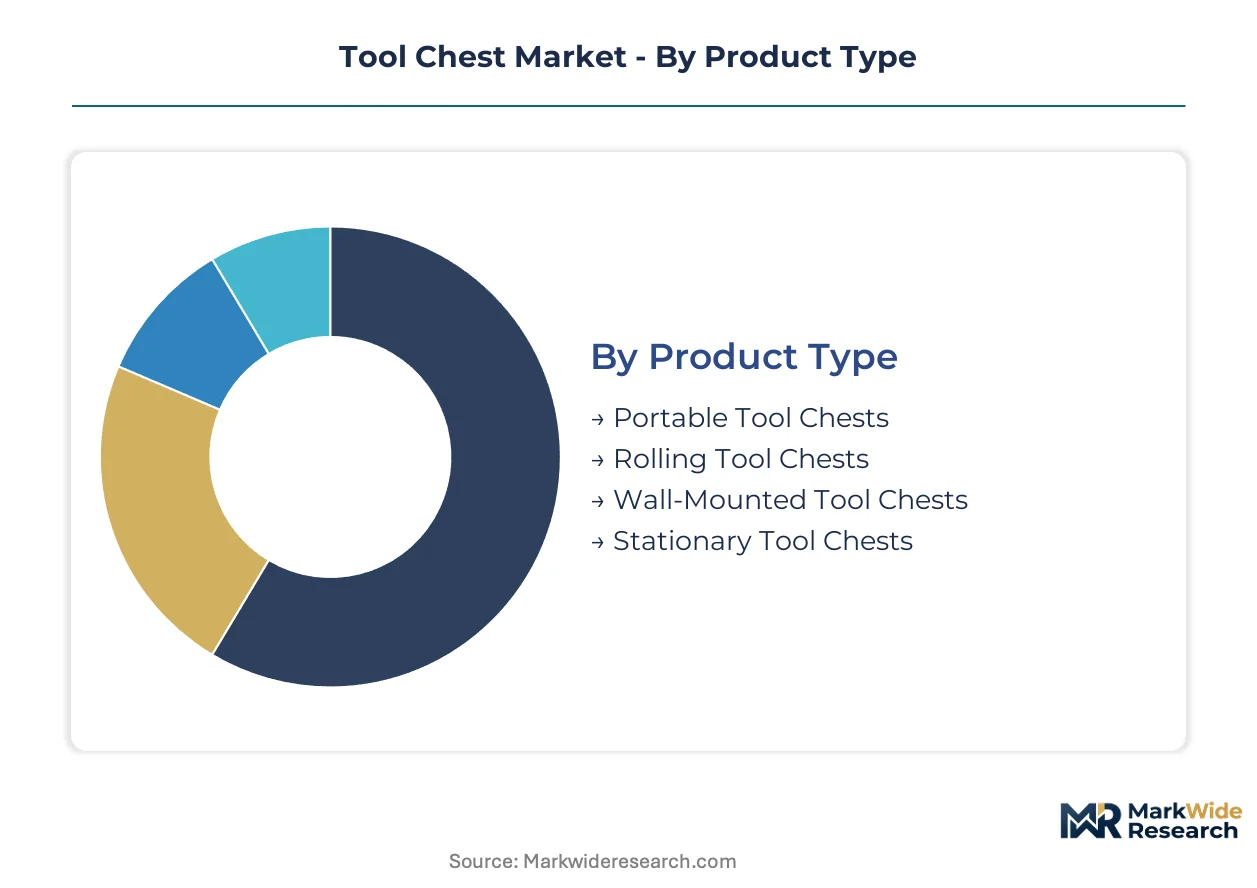
Tool chest procurement patterns diverge sharply across product configurations, material grades, and end-user sophistication levels. Fleet operators prioritize specification-grade durability and platform compatibility, while residential purchasers respond to promotional pricing and retail availability.
Product Type:
Rolling variants turn inventory fastest in construction corridors, while stationary units cycle slowest due to extended replacement timelines in industrial facilities.
- Rolling Tool Chests:Casters rated for 1,000+ pounds and telescoping handles enable transport across uneven jobsite terrain. Demand clusters among automotive technicians in Texas and California facilities requiring mobility between service bays. OSHA lockout/tagout mandates accelerate specification-grade procurement with integrated hasp systems.
- Portable Tool Chests:Compact footprints under 24 inches prioritize weight reduction for elevator maintenance and HVAC service technicians navigating multi-story buildings. California right-to-repair legislation extends tool ownership cycles, elevating aluminum-variant preference for transportability.
- Wall-Mounted Tool Chests:Vertical storage configurations maximize floor space in dense urban workshops and fleet maintenance depots.
- Stationary Tool Chests:Fixed-position units anchor permanent workstations in industrial manufacturing and heavy equipment repair facilities.
Rolling configurations dominate installed base. Portable variants are where expansion concentrates.
Material:
Cost tier stratification separates specification-grade procurement from price-sensitive spot purchasing across trade segments.
- Steel:Cold-rolled construction with powder-coat finishing delivers 100+ pound drawer load ratings demanded by fleet standardization programs. Texas and California construction corridors absorb volume shipments despite input cost volatility from tariff-exposed supply chains.
- Aluminum:Weight reductions of 40-60% versus steel serve HVAC and elevator technicians in dense urban markets where transport burden dictates material selection. EPA surface coating compliance requirements filter domestic fabrication capacity.
- Plastic:Polymer construction targets residential DIY segments with corrosion resistance for humid coastal environments.
- Wood:Aesthetic finishes serve boutique woodworking shops and restoration-focused craft professionals.
Steel anchors installed base. Aluminum is climbing the fastest.
End User:
Customer type determines margin structure, with professional procurement committees extracting volume pricing unavailable to fragmented residential purchasers.
- Professional Contractors:Fleet standardization programs compress replacement cycles and elevate specification-grade purchasing above price-driven procurement. Captive finance subsidiaries lock in multi-year relationships through equipment leasing structures.
- Tradespeople:Individual electricians and plumbers prioritize platform-locked battery integration with cordless tool ecosystems, accepting premium attachment rates for charging-capable storage.
- DIY Enthusiasts:Promotion-driven segment exhibits lower accessory attachment rates and extended replacement cycles.
- Industrial Users:Facility maintenance departments mandate ISO 9001 certification and serialized lock compatibility for audit compliance.
Professional contractors dominate installed base. Fleet leasing penetration is gaining share fastest.
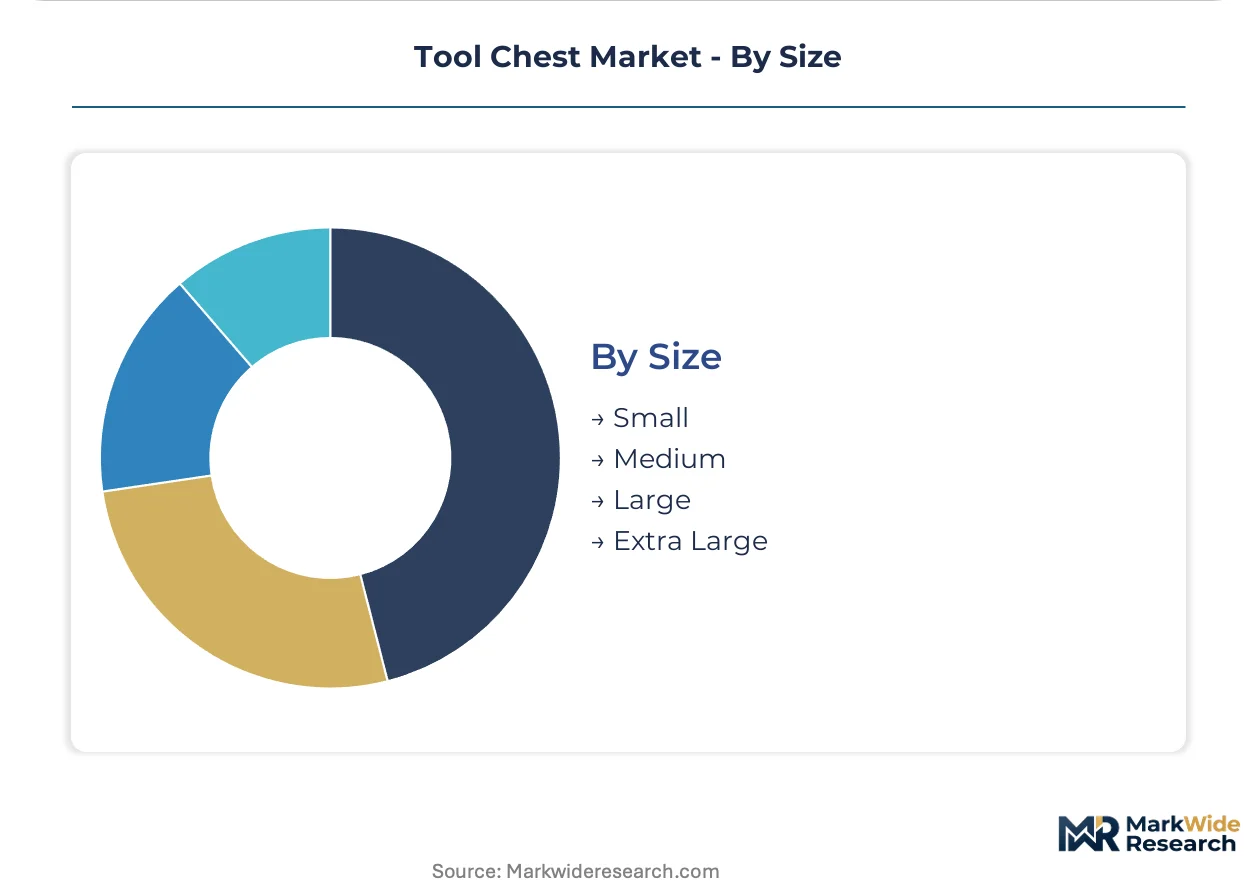
Size:
Volume concentration in medium and large configurations reflects trade fleet scale thresholds that trigger preferred pricing tiers.
- Large:40+ inch widths accommodate comprehensive cordless platform storage with integrated charging bays. Mechanical contractors in Texas commercial build-out corridors specify these for multi-crew deployments.
- Medium:26-36 inch configurations balance capacity with transportability for mid-sized HVAC and electrical trade fleets.
- Small:Compact footprints under 26 inches serve residential garages and mobile service technicians.
- Extra Large:50+ inch specialty units anchor centralized tool cribs in industrial manufacturing and heavy equipment maintenance facilities.
Medium configurations dominate installed base. Large sizes are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA workplace safety mandates and fleet standardization programs are redrawing procurement intensity across construction corridors, with regulatory enforcement creating compliance-driven demand clusters in specific state and metropolitan markets.
United States
Texas and California construction corridors absorb the densest tool chest shipments, driven by residential and commercial build-out concentration. OSHA lockout/tagout standards mandate secure equipment storage on active jobsites, converting audit compliance into category pull-through. Fleet operators in Houston and Los Angeles metro areas are consolidating vendor relationships through multi-year supply agreements.
Germany
Industrial machinery maintenance and automotive repair facilities anchor specification-grade demand for ISO 9001-certified storage systems. REACH regulations on surface coating chemistry filter domestic fabrication capacity and elevate compliance costs for powder-coat finishing processes. Manufacturing clusters in Baden-Württemberg and Bavaria prioritize serialized lock compatibility for facility audit compliance.
China
Primary aluminum smelting capacity concentration exposes downstream fabricators to logistics disruption cascades and tariff exposure. GB standards for metal fabrication quality function as baseline qualifiers for industrial procurement contracts. Construction equipment fleets in the Yangtze River Delta and Pearl River Delta are standardizing storage configurations to reduce tool loss rates.
Japan
Automotive technicians and precision manufacturing maintenance crews drive demand for ball-bearing drawer systems rated for 100+ pound loads. METI industrial standards shape quality management certification requirements for supplier qualification. Industrial corridors in Aichi Prefecture and the Kansai region exhibit elevated attachment rates for platform-locked battery-integrated storage.
India
Infrastructure build-out and urban construction activity are elevating procurement of rolling configurations with casters rated for uneven terrain. BIS certification requirements for steel fabrication products extend supplier qualification timelines. Commercial construction in Maharashtra and Karnataka is absorbing medium and large configuration volumes for multi-crew deployments.
Tool Chest Market Competitive Landscape
On the supply side, the industry is tiered between specification-grade fabricators serving fleet operators and price-competitive producers targeting fragmented residential demand. Three strategic archetypes dominate: premium platform-integrated specialists, modular stackable system providers, and aluminum-weight-optimized fabricators. Capacity expansion and captive finance subsidiary formation represent the dominant competitive moves for securing multi-year contractor relationships.
Among premium-tier specialists, Snap-on Incorporated and Milwaukee Tool occupy positions defined by battery-integrated storage ecosystems and platform-locked accessory demand. Stanley Black & Decker exemplifies the multi-tier competitor archetype, spanning specification-grade and promotion-driven segments through modular product architectures. These three companies anchor the competitive structure by representing distinct strategic vectors: finance-integrated fleet locking, cordless platform dominance, and price-tier breadth.
| Leading Market Players |
|---|
| Snap-on Incorporated |
| RIDGID |
| Stanley Black & Decker |
| Keter Group |
| Matco Tools |
| Apex Tool Group |
| Klein Tools |
| Homak Manufacturing |
| Milwaukee Tool |
| Others |
Value Network & Pricing Analysis
Primary aluminum smelting capacity concentration in China and the Gulf states concentrates margin capture upstream, while domestic fabricators in the United States and Germany absorb tariff and logistics disruption cascades that compress downstream profitability in specification-grade segments.
Pricing Analysis
Certification level creates the primary spread between specification-grade and spot-market procurement. Three-tier pricing structure across premium ISO 9001-certified, mid-grade ANSI-qualified, and economy non-certified levels separates fleet operators from price-sensitive residential purchasers. Pricing pressure stems from cold-rolled steel input cost volatility that destabilizes multi-year fleet contract commitments. Professional contractors exhibit lowest price sensitivity due to captive finance structures, while DIY enthusiasts drive promotional discounting cycles.
Supply Chain Analysis
Contract manufacturing for ball-bearing drawer slides concentrates among legacy metalworking suppliers in Taiwan, Japan, and Germany with precision machining expertise rated for 100+ pound loads. Raw material dependencies center on cold-rolled steel from domestic mills, primary aluminum from China and Gulf states, and powder-coat chemistry subject to EPA VOC restrictions. Tariff exposure on aluminum imports represents the dominant structural risk. Distribution runs through construction equipment distributors and industrial supply houses serving Texas and California corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ball-bearing slide fabrication expertise functions as the scarce capability constraining quality scaling, with precision machining rated for 100+ pound drawer loads concentrating among legacy suppliers and filtering new entrant velocity.
For Market Incumbents: Build captive finance moats through equipment leasing subsidiaries that lock in multi-year contractor relationships and displace fragmented spot purchasing. Defend against aluminum-weight-optimized fabricators by securing ISO 9001 certification ahead of state right-to-repair legislation extensions. Prioritize backward integration into powder-coat finishing to buffer EPA compliance cost volatility. For New Entrants and Emerging Players: Southeast Asian fleet markets present underpenetrated demand for medium-configuration aluminum variants serving HVAC and elevator maintenance technicians. Target pay-per-use financing gaps among mid-sized mechanical trade fleets in India and Brazil where specification-grade procurement remains capital-constrained. Enter through platform-locked battery integration partnerships with cordless tool ecosystems. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed aluminum fabricators possessing EPA-compliant surface coating capacity and urban service trade customer bases. Five-to-ten year viability hinges on durability specification elevation from extended tool ownership mandates. Monitor state-level right-to-repair legislative progression as the inflection signal for replacement cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Finance Subsidiary Formation | Equipment leasing structures convert capital expenditure to operational budgeting for mid-sized Texas and California fleets. |
| Aluminum Fabrication Capacity Expansion | Weight-reduced variants capture HVAC and elevator technician demand in dense urban multi-story facilities. |
| ISO 9001 Certification Investment | Quality management certification filters supplier pools before industrial procurement technical evaluation begins. |
| Battery-Integrated Storage Development | Charging-capable chests command attachment rate premiums among platform-locked cordless tool ecosystems. |
| RFID-Enabled Inventory Tracking Integration | Real-time asset visibility reduces loss rates for mechanical contractors operating multi-crew deployments. |
Research Methodology
Desk research of trade association shipment data, customs import records, and regulatory filing databases preceded structured interviews with fleet procurement managers, distributor inventory planners, OEM product development directors, and industrial facility maintenance supervisors. Primary fieldwork captured specification-grade purchasing criteria and replacement cycle compression patterns. Secondary validation drew from OSHA enforcement records, EPA compliance disclosures, and ISO certification registries. Bottom-up unit shipment modeling triangulated against top-down construction spending allocation analysis.
Assumptions held OSHA lockout/tagout enforcement intensity and cold-rolled steel tariff structures fixed across the analysis window, while battery platform adoption curves and state right-to-repair legislative timelines varied under sensitivity testing. Segmentation modeling spanned product configuration, material grade, end-user sophistication, and geographic demand density dimensions. CAGRs derived from regression analysis against construction permit issuance and fleet standardization program penetration. Industry-specific inputs incorporated cordless tool platform attachment rates and aluminum alloy price index trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated steel mills into downstream fabrication would shift outcomes through margin compression. Regulatory acceleration in EPA surface coating restrictions or OSHA secure storage mandates could accelerate specification-grade procurement beyond modeled trajectories. Quarterly review of construction permit issuance in Texas and California corridors and state legislative tracking for right-to-repair expansion is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Storage and Organization
Flatware Holders and Organizers Market
Home Storage and Organization
Cabinet & Furniture Drawer Slides Market
Home Storage and Organization
Slipcases Market
Home Storage and Organization
Clothes Closets Market
Home Storage and Organization
Shoe Storage and Organizers Market
Home Storage and Organization
Shop Shelving Market
Home Storage and Organization
Kitchen Storage Market
Home Storage and Organization
Hong Kong Self-Storage Market
Home Storage and Organization
Collapsible Wardrobe Market
Home Storage and Organization
Sheds and Outdoor Storage Market
Home Storage and Organization
Regency Shelving Market
Home Storage and Organization
Asia-Pacific Digital Home Locker Market
Home Storage and Organization
Closet Organizers Market
Home Storage and Organization
Scandinavia Self-Storage Market
Home Storage and Organization
Toy Storage Market
Home Storage and Organization
Flush Mount Photo Album Market