
 Wardrobe Boxes Market | 2026-2036
Wardrobe Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Wardrobe Boxes Market Analysis
Digital printing and automated die-cutting is reshaping how wardrobe boxes are manufactured and customized for regional markets. Smurfit Kappa leverages integrated containerboard mills to control fiber costs across Europe. DS Smith differentiates through circular design protocols that prioritize recyclability in retail and moving applications. U-Haul International dominates the North American rental channel with a captive logistics network for box recovery and reuse.
Wardrobe boxes are tall-format corrugated or rigid containers, typically 24 to 48 inches in height, incorporating an internal hanging rail to transport garments without folding during relocation or storage. Their primary commercial purpose is protecting apparel from wrinkle damage and environmental exposure during transit. Cardboard variants anchor the volume base due to low unit cost and widespread curbside recyclability, while plastic boxes capture repeat-use demand in commercial moving fleets where return logistics justify higher upfront investment. The large and extra-large size tiers command disproportionate margin contribution from full-service moving contracts.
The US EPA sets recycled content benchmarks for corrugated packaging, while the EU's Packaging and Packaging Waste Regulation tightens extended producer responsibility obligations for single-use transit materials. China's GB standards for packaging and the State Administration for Market Regulation enforce labeling and material safety rules for consumer-facing box sales. Stakeholders must monitor how diverging regional compliance timelines affect cross-border product standardization and sourcing flexibility.
Market Dynamics
Recycled content mandates from the US EPA and the EU's Packaging and Packaging Waste Regulation are forcing corrugated manufacturers to reconfigure fiber sourcing and certify supply chains for wardrobe box production.
Growth Catalysts
- Urban Relocation Density:Residential moving volumes in the United States, Germany, and China are concentrating demand for tall-format garment protection containers.
- REACH Compliance:The EU's chemical safety framework is accelerating substitution of virgin plastic rails with recycled polymer or cardboard alternatives in hanging box designs.
- Digital Die-Cutting:Automated cutting systems are enabling mass customization of box dimensions for regional moving company fleets without retooling costs.
Market Restraints
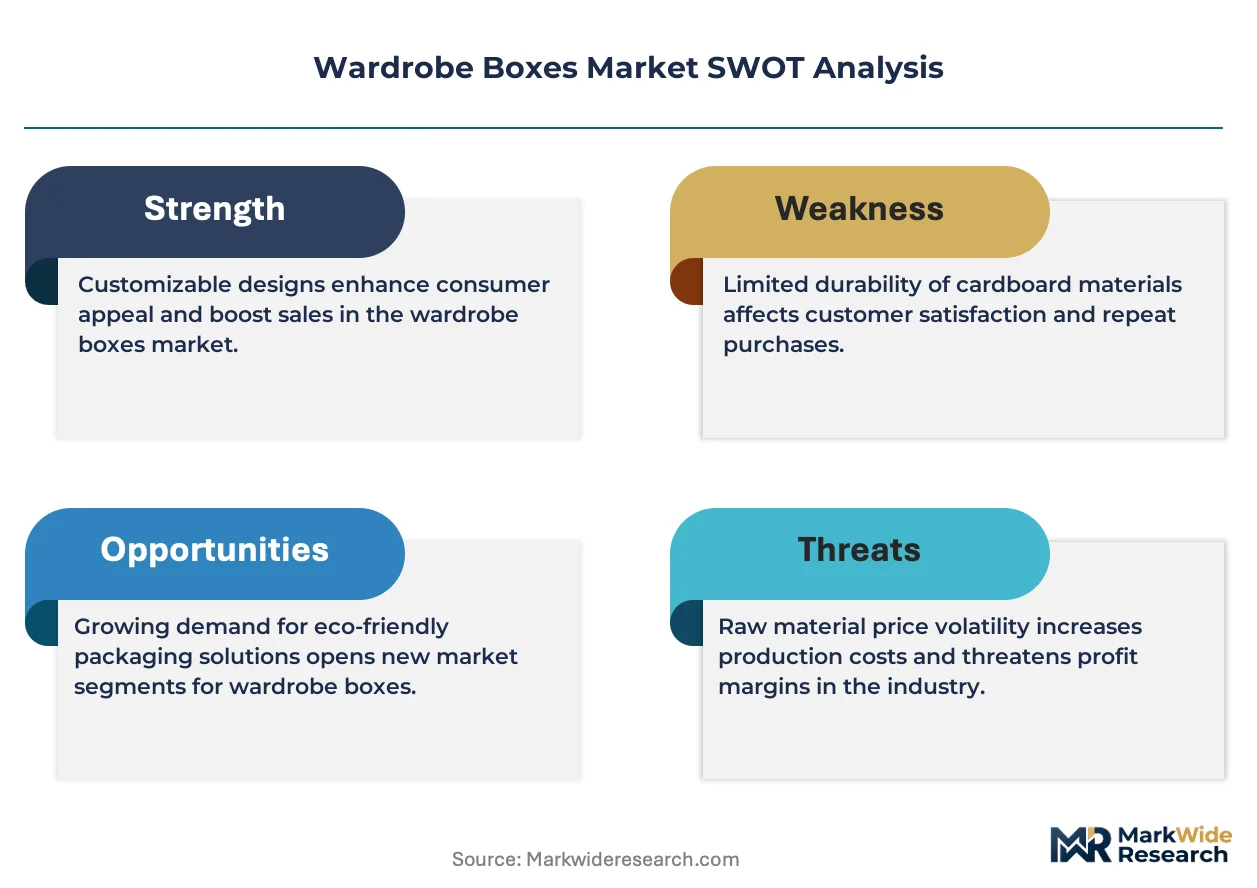
- OCC Price Volatility:Old corrugated containerboard input costs fluctuate with Chinese import quotas, squeezing margin on standard-grade wardrobe boxes.
- Single-Use Perception:Consumer preference for reusable plastic totes in high-frequency commercial moving is displacing cardboard in fleet operator procurement.
- EPR Timeline Divergence:The EU's extended producer responsibility rollout varies by member state, fragmenting compliance costs for cross-border box suppliers.
Strategic Opportunities
- China GB Standards Alignment:Certification to national packaging safety rules opens access to consumer-facing retail channels in tier-one cities.
- Reverse Logistics Integration:Partnerships with moving van line networks enable box recovery and refurbishment programs at scale.
- Water-Based Barrier Coatings:Advances in moisture-resistant fiber treatments are creating recyclable alternatives to wax-coated garment boxes for humid climates.
Industry Challenges
- Die-Cut Technician Scarcity:Skilled operators for high-speed rotary die equipment are concentrated in legacy packaging regions, constraining plant expansion.
- Multi-Material Rail Attachment:Integrating metal or plastic hanging hardware with fiber bodies complicates automated assembly and end-of-life sorting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wardrobe Boxes Market |
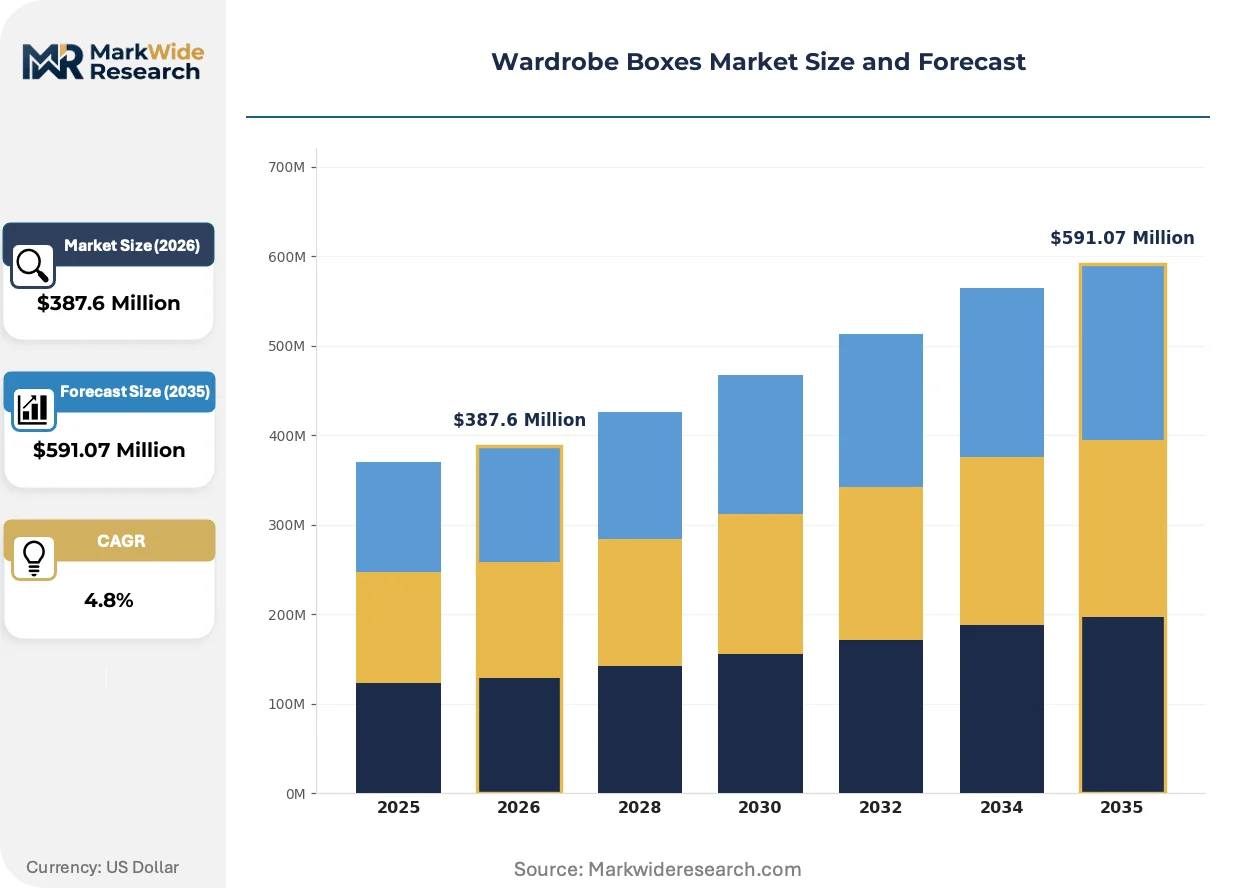
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $591.07 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardboard Boxes, Plastic Boxes, Wooden Boxes, Metal Boxes Application: Residential Moving, Commercial Moving, Storage Solutions, Retail Display Size: Small, Medium, Large, Extra Large Distribution Channel: Online Sales, Retail Stores, Direct Sales, Wholesalers |
| Companies Covered | U-Haul International, WestRock, Smurfit Kappa, Mondi Group, International Paper, DS Smith, Packaging Corporation of America, Georgia-Pacific, The Boxery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wardrobe Boxes Market Emerging Trajectories
Automation in converting plants and tightening material compliance frameworks are compressing production economics while opening premium positioning for certified sustainable wardrobe boxes.
Digital printing with water-based inks is rendering obsolete the minimum order quantities that previously locked small moving companies into generic stock boxes. Regional distributors in the United States are adopting web-to-print portals that deliver custom-branded wardrobe containers within 72-hour windows. This capability is compressing the addressable market for undifferentiated commodity boxes and shifting margin toward digitally enabled converters.
The EU's Packaging and Packaging Waste Regulation is mandating recyclability-by-design assessments for all single-use transit packaging placed on the European market. Corrugated producers must now document fiber provenance and adhesive chemistry through third-party certification. German retail and moving supply channels are responding fastest, with several major distributors delisting non-compliant suppliers ahead of formal enforcement deadlines.
Full-service moving companies are consolidating procurement through national account structures that demand volume-tier pricing and dedicated inventory programs. This concentration is displacing the fragmented dealer network that historically supplied independent local movers. The shift is most visible in North American metropolitan corridors, where three van lines now control the majority of wardrobe box specification decisions.
Wardrobe Boxes Market Segmentation
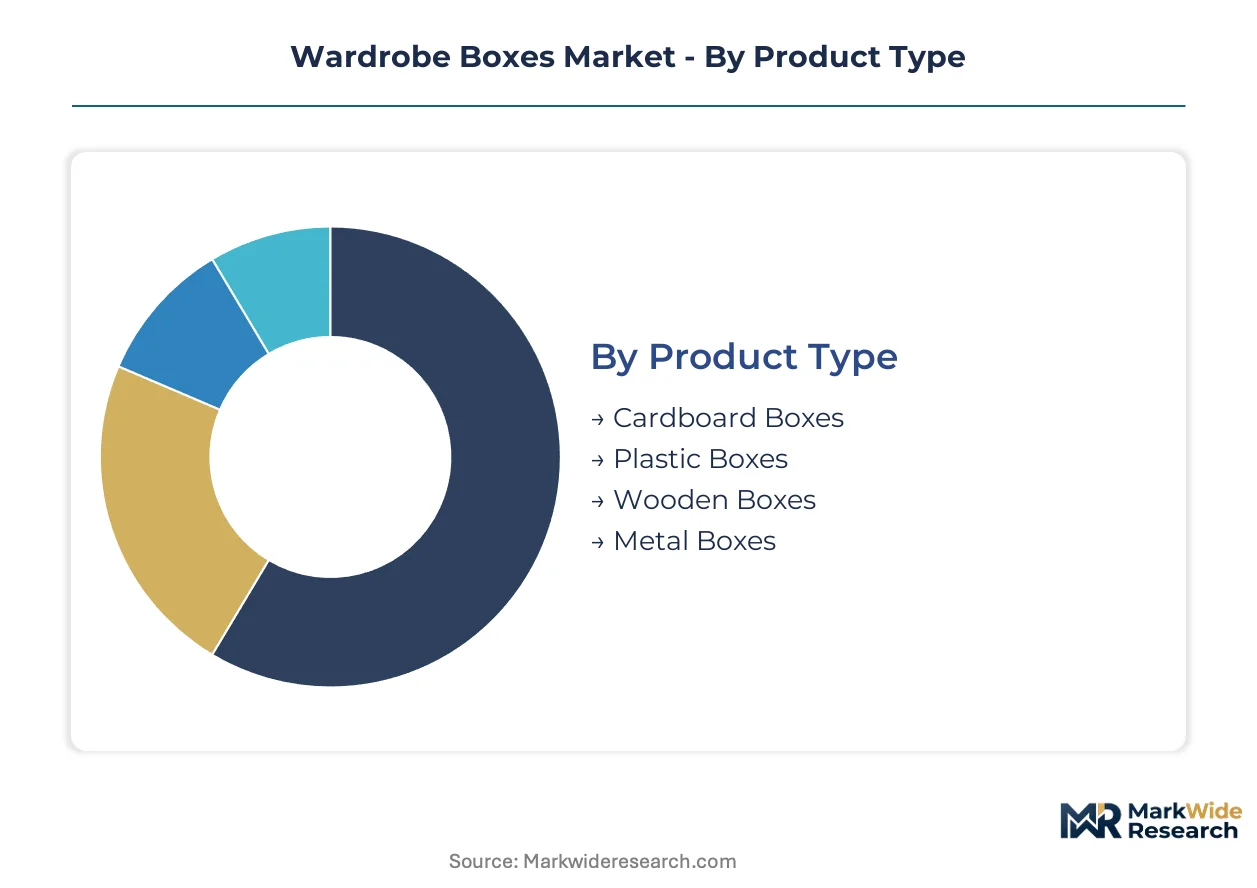
Wardrobe box segmentation reveals stark differences in purchase frequency and lifecycle economics. Cardboard variants turn over rapidly in residential channels, while plastic and metal formats sustain multi-year deployment cycles in commercial fleets. Understanding these velocity patterns shapes inventory planning and margin capture strategies for converters and distributors.
Product Type:
Cardboard boxes rotate through supply chains fastest, with typical single-use consumption in residential moving. Plastic and wooden variants stretch replacement cycles across five to ten years in commercial storage applications.
- Cardboard Boxes:Single-wall and double-wall corrugated constructions dominate unit economics, with recycled fiber content ranging from 35% to 95% depending on EPA or EU certification requirements. Demand concentrates in United States metropolitan corridors and German urban centers where residential relocation volumes and curbside recycling infrastructure align. OCC price volatility directly squeezes converter margins on standard grades.
- Plastic Boxes:Polypropylene and high-density polyethylene shells with integrated metal hanging rails support 50+ use cycles in van line rental fleets. Commercial moving operators in North American and Chinese tier-one cities are consolidating procurement around standardized plastic formats to enable reverse logistics recovery programs.
- Wooden Boxes:Plywood and oriented strand board enclosures serve antique garment transport and high-value costume storage in museum and theater logistics channels.
- Metal Boxes:Steel and aluminum constructions anchor archival garment preservation for military uniform repositories and institutional textile collections requiring fire-rated containment.
Cardboard dominates installed base by unit volume. Plastic is where expansion concentrates as van lines professionalize fleet management.
Application:
Cost tier differentiation separates one-time residential purchases from negotiated multi-year service contracts. Full-service moving companies extract volume discounts that independent renters cannot match.
- Residential Moving:Individual consumers purchase single units or small sets through retail and online channels, prioritizing low unit cost over durability. United States home sale velocity and German housing turnover rates directly correlate with seasonal demand spikes.
- Commercial Moving:Corporate relocation contracts and government office moves specify standardized container fleets with barcode tracking and damage liability terms. Chinese state-owned enterprise procurement is formalizing technical specifications through GB standards alignment.
- Storage Solutions:Self-storage operators in United States Sun Belt markets bundle wardrobe containers with climate-controlled unit rentals.
- Retail Display:Apparel brands deploy branded wardrobe boxes for in-store visual merchandising and e-commerce premium packaging in European fashion capitals.
Residential Moving anchors revenue by transaction frequency. Commercial Moving is climbing the fastest as national account consolidation accelerates.
Size:
Volume concentration in large and extra-large formats reflects full-service moving contract economics, where garment count per box drives labor efficiency in loading operations.
- Large:24-inch width configurations accommodate standard closet rod lengths and maximize truck cube utilization. United States van lines specify this format as fleet standard to simplify inventory management across metropolitan hubs.
- Extra Large:48-inch height variants capture bridal gown, formal wear, and costume rack applications where vertical clearance prevents hem damage. German and Austrian opera house logistics departments specify this tier for touring productions.
- Small:Compact 18-inch formats serve studio apartment moves and dormitory relocations in dense Asian urban centers.
- Medium:Intermediate dimensions fill gaps in retail stock-keeping unit strategies for mixed-format moving kit bundles.
Large dominates procurement specifications. Extra Large is gaining share fastest as specialty garment logistics professionalizes.
Distribution Channel:
Customer type fragmentation separates price-sensitive individual purchasers from contract-negotiated fleet operators, with channel choice determining margin structure and service attachment opportunities.
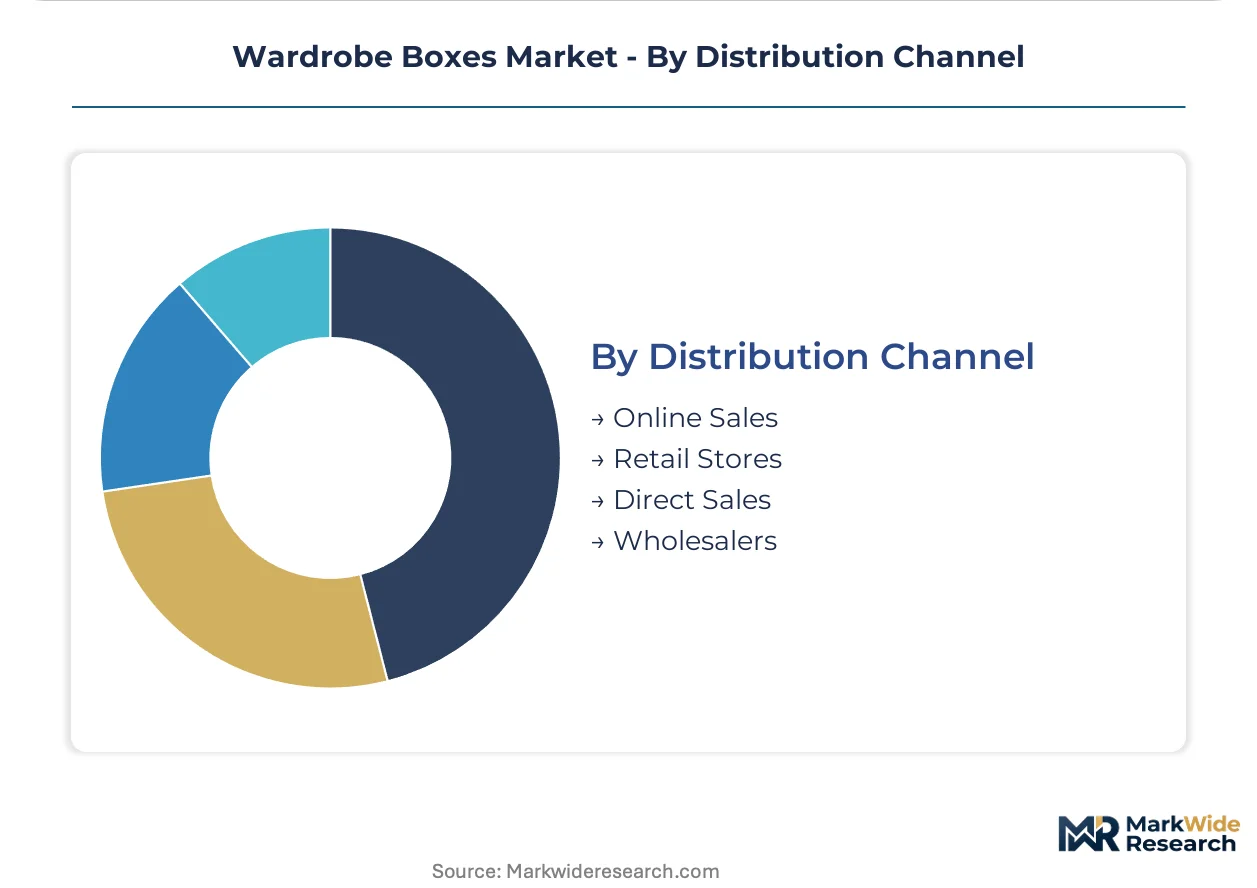
- Online Sales:E-commerce platforms enable 72-hour customization turnaround for regional moving company branding, compressing minimum order quantities that previously locked out smaller operators. United States distributors are deploying web-to-print portals to capture this demand.
- Direct Sales:National account teams at major converters negotiate multi-year wardrobe box supply agreements with van line holding companies, embedding dedicated inventory programs and volume-tier pricing.
- Retail Stores:Big-box home improvement and moving supply outlets serve emergency purchase occasions and small-scale residential needs.
- Wholesalers:Regional packaging distributors aggregate fragmented independent mover demand and provide just-in-time delivery to local storage facilities.
Direct Sales dominates contract value. Online Sales is expanding most quickly as digital printing collapses customization economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Full-service moving companies and self-storage operators concentrate procurement in metropolitan corridors where residential turnover and corporate relocation volumes intersect. National account structures now dominate specification decisions, favoring suppliers with dedicated inventory programs and certified fiber provenance.
United States
Van line consolidation across metropolitan corridors drives standardization around 24-inch large-format specifications. EPA recycled content benchmarks for corrugated packaging force converters to certify fiber sourcing through third-party verification. The Sun Belt self-storage expansion—particularly in Texas and Florida—bundles wardrobe containers with climate-controlled unit rentals.
Germany
Urban housing turnover in Berlin, Munich, and Hamburg sustains steady demand for tall-format garment protection. The EU's Packaging and Packaging Waste Regulation mandates recyclability-by-design assessments, with German distributors delisting non-compliant suppliers ahead of enforcement deadlines. Bavarian opera house logistics departments specify extra-large 48-inch formats for touring costume collections.
China
Tier-one city relocation volumes in Shanghai, Beijing, and Shenzhen concentrate demand for both cardboard retail sales and plastic fleet formats. GB standards for packaging and SAMR labeling rules enforce material safety compliance for consumer-facing box sales. State-owned enterprise procurement is formalizing technical specifications through national standards alignment.
United Kingdom
London's residential property velocity and corporate relocation activity sustain premium-format demand. REACH compliance frameworks accelerate substitution of virgin plastic rails with recycled alternatives in hanging box designs. Midlands-based converting operations serve national moving company fleets through dedicated inventory programs.
France
Parisian fashion logistics and Île-de-France corporate relocation sustain demand for branded retail display formats. Extended producer responsibility timelines under EU regulation fragment compliance costs for cross-border suppliers. Lyon-based distributors aggregate demand from independent movers across the Rhône-Alpes cluster.
Wardrobe Boxes Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement tiers. National moving van lines and integrated containerboard producers anchor the upper tier through captive logistics networks and fiber cost control. Mid-scale converters survive through digital customization capabilities and regional just-in-time delivery. Dominant competitive moves include backward integration into containerboard mills and partnerships with reverse logistics networks for box recovery programs.
Among integrated packaging groups, Smurfit Kappa and DS Smith exemplify archetypes of fiber-cost control and circular design certification respectively. U-Haul International occupies a position as a channel-controlling operator with captive logistics infrastructure for rental fleet management. These three entities represent the strategic poles—upstream integration, sustainability certification, and downstream channel capture—that structure competitive positioning in wardrobe box supply.
| Leading Market Players |
|---|
| U-Haul International |
| WestRock |
| Smurfit Kappa |
| Mondi Group |
| International Paper |
| DS Smith |
| Packaging Corporation of America |
| Georgia-Pacific |
| The Boxery |
| Others |
Supply Flow & Price Mechanics
Midwest U.S. containerboard mill clusters around Wisconsin and Michigan anchor fiber supply leverage, with OCC cost pass-through clauses in long-term van line contracts determining margin compression tolerance across the value chain. This geographic concentration of pulping capacity creates asymmetric pricing power where converters with captive fiber access extract premium terms from independent box assemblers.
Pricing Analysis
Cost-plus contracts indexed to RISI OCC price assessments dominate procurement between major van lines and integrated converters, with quarterly adjustments flowing through to end-user rates. Price differentiation hinges on EPA-certified recycled content tiers and volume-scale commitments, with national accounts commanding 15-20 point spreads over spot retail purchases. Pricing pressure intensifies in standard-grade cardboard as Chinese import quota volatility feeds raw material uncertainty. Independent local movers exhibit highest price sensitivity, while full-service van lines prioritize reliability and dedicated inventory over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and Canadian softwood pulp suppliers dominates supply chain risk planning for domestic wardrobe box producers. Fiber sourcing concentrates in the United States, Canada, and Brazil, with linerboard and medium grades drawing from integrated kraft pulp operations. Supply chain vulnerability rests on single-source railcar logistics for OCC collection in dense urban corridors. Distribution runs through van line hub-and-spoke networks with dedicated inventory pools, bypassing traditional wholesale channels for national account fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Skilled rotary die-cut technician scarcity constrains capacity expansion timelines, with qualified operators concentrated in legacy packaging regions of the Upper Midwest and Bavaria. This talent bottleneck limits how quickly converters can respond to demand surges from van line consolidation.
For Market Incumbents: Build captive reverse logistics networks as the defensive moat, deploying box recovery and refurbishment programs at scale to lock in fleet operator relationships. Invest in automated die-cutting capacity in the Dallas-Fort Worth corridor to escape legacy labor markets. Defend against plastic fleet substitution by accelerating water-based barrier coating certification for humid-climate recyclability. For New Entrants and Emerging Players: Tier-two Chinese cities present the most penetrable white-space opportunity, where GB standards compliance gaps create entry windows for certified foreign suppliers. Target self-storage bundling partnerships in Florida and Texas Sun Belt markets where climate-controlled unit expansion outpaces incumbent box supply. Pursue web-to-print customization portals to capture fragmented independent mover demand with 72-hour turnaround capabilities. For Investors and Strategic Acquirers: Long-term, this sits as a circular-economy infrastructure play because extended producer responsibility mandates will revalue box recovery and fiber certification capabilities. Acquisition focus should center on mid-scale converters with integrated digital printing and established van line national account relationships. Monitor EU member state EPR enforcement timelines as the critical inflection signal for compliance-premium pricing emergence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Containerboard Mills | Captive fiber supply insulates Smurfit Kappa and WestRock from OCC price volatility in wardrobe box production. |
| Reverse Logistics Partnership with Van Lines | U-Haul's captive recovery network enables rental fleet reuse economics that cardboard competitors cannot replicate. |
| Digital Print Customization Platform | Web-to-print portals collapse minimum order quantities and shift margin from commodity stock boxes to regional converters. |
| Water-Based Barrier Coating Certification | Recyclable moisture resistance opens humid-climate markets currently served by wax-coated non-recyclable alternatives. |
| GB Standards Alignment for China Access | SAMR compliance certification unlocks consumer-facing retail channels in Shanghai and Beijing tier-one markets. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of trade association filings, customs import records, and EPA corrugated packaging guidance documents. Primary interviews engaged plant managers at integrated containerboard mills, procurement directors at national van line holding companies, and technical sales leads at regional converting operations. Secondary validation drew from RISI pulp and paper price assessments, SEC 10-K disclosures by publicly traded packaging groups, and EU Packaging and Packaging Waste Regulation implementation notices. Bottom-up demand modeling triangulated against top-down industry shipment estimates.
Forecast inputs incorporate urban relocation velocity indices, van line fleet standardization timelines, and recycled content mandate phase-in schedules across the projection horizon. Segmentation dimensions span material type, application channel, size tier, and distribution format, with regional regulatory clusters treated as distinct demand scenarios. CAGRs derive from slope analysis of historical shipment trends adjusted for structural shifts in procurement consolidation and sustainability certification premiums. OCC price volatility and EPR compliance cost trajectories inform sensitivity bounds.
Macroeconomic conditions sit as an overlay; deviation in housing turnover rates, mortgage interest rate movements, or commercial real estate lease velocity would shift the trajectory. Forecasts embed assumptions regarding Chinese import quota stability and EU member state enforcement harmonization that warrant monitoring. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Storage and Organization
Clothes Closets Market
Home Storage and Organization
Scandinavia Self-Storage Market
Home Storage and Organization
Closet Organizers Market
Home Storage and Organization
Tool Chest Market
Home Storage and Organization
Smart Shoe Cabinet Market
Home Storage and Organization
Small Space Furniture Market
Home Storage and Organization
Hong Kong Self-Storage Market
Home Storage and Organization
Smart Storage Cabinet Market
Home Storage and Organization
Jewelry Organizer Market
Home Storage and Organization
Flush Mount Photo Album Market
Home Storage and Organization
Collapsible Wardrobe Market
Home Storage and Organization
Shoe Rack Market
Home Storage and Organization
Europe Home Organizers and Storage Market
Home Storage and Organization
Kitchen Storage Organization Market
Home Storage and Organization
United States Home Organizers and Storage Market
Home Storage and Organization
Asia-Pacific Digital Home Locker Market