
 Display Cabinets Market | 2026-2036
Display Cabinets Market Size, Share, and Industry Trends Forecast 2026-2036
Display Cabinets Market Outlook
LED-integrated smart glass is rewriting how display cabinets balance transparency with thermal management and programmable illumination. American Woodmark Corporation leverages captive hardwood sourcing to sustain margin stability across residential and light commercial lines. Fabuwood Cabinetry anchors its competitive position through dense distribution in the Northeast corridor. Oppein dominates Asian project channels with modular systems engineered for rapid retail rollout.
Display cabinets are enclosed or open-fronted storage and exhibition fixtures, typically constructed from engineered wood substrates, tempered safety glass, aluminum extrusions, or acrylic panels, with integrated lighting, climate control, or locking mechanisms to preserve and present objects. Their primary purpose spans retail merchandising, museum conservation, residential storage, and corporate presentation environments. Free-standing units command the largest volume share in retail and museum deployments where floor flexibility matters. Glass and metal material combinations capture premium specification in high-traffic commercial settings. Custom sizing generates the highest margin pools as architects and interior designers specify exact dimensions for branded environments.
The EPA regulates formaldehyde emissions from composite wood products under TSCA Title VI, directly affecting domestic cabinet manufacturing substrate choices. REACH compliance in Europe restricts certain wood preservatives and glass coatings, while China's GB standards enforce volatile organic compound limits on finished furniture. Stakeholders must monitor how diverging chemical compliance regimes between the United States, European Union, and China reshape supplier qualification requirements and cross-border material sourcing strategies.
Market Dynamics
LED-integrated smart glass technology is compressing fixture refresh cycles across luxury retail and museum sectors, forcing substrate suppliers to retool for thermal management compatibility while regulatory divergence between EPA TSCA Title VI, EU REACH, and China's GB standards fragments material qualification protocols.
Growth Catalysts
- EPA TSCA Title VI compliance:Stricter formaldehyde emission limits on composite wood products are accelerating substrate upgrades in domestic manufacturing, pulling demand toward certified low-emission engineered panels.
- Museum conservation protocols:Climate-controlled display specifications for artifact preservation are expanding specification volumes for humidity-regulated cabinet systems in cultural institutions.
- China's GB standards enforcement:Volatile organic compound limits on finished furniture are redirecting procurement toward compliant coating suppliers in Asian project channels.
Market Restraints
- Tempered glass supply concentration:Flat glass manufacturing clusters in specific coastal Chinese provinces create input cost volatility when energy pricing shifts affect furnace operations.
- Aluminum extrusion energy intensity:Smelting power requirements tie cabinet frame costs to regional electricity tariff fluctuations, compressing margin stability for metal-intensive product lines.
- Acrylic substitution threat:Shatter-resistant polymer panels are capturing share in high-traffic retail environments where impact resistance outweighs optical clarity requirements.
Strategic Opportunities
- Modular rapid-retail systems:Pre-engineered cabinet modules designed for 48-hour store rollout are opening project channel penetration in fast-fashion expansion cycles.
- EU Green Deal procurement incentives:Public sector tender preferences for circular material content are creating specification advantages for reclaimed wood substrate suppliers.
- Smart glass-IoT convergence:Programmable transparency systems integrated with inventory sensors are enabling premium pricing in automated retail environments.
Industry Challenges
- Cross-border certification timelines:Divergent testing protocols between EPA, ECHA, and SAMR qualification requirements extend product launch cycles by 8-14 months for multi-territory suppliers.
- LED thermal management integration:Cabinet engineers face skill gaps in marrying glass conductivity properties with semiconductor heat dissipation specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Display Cabinets Market |
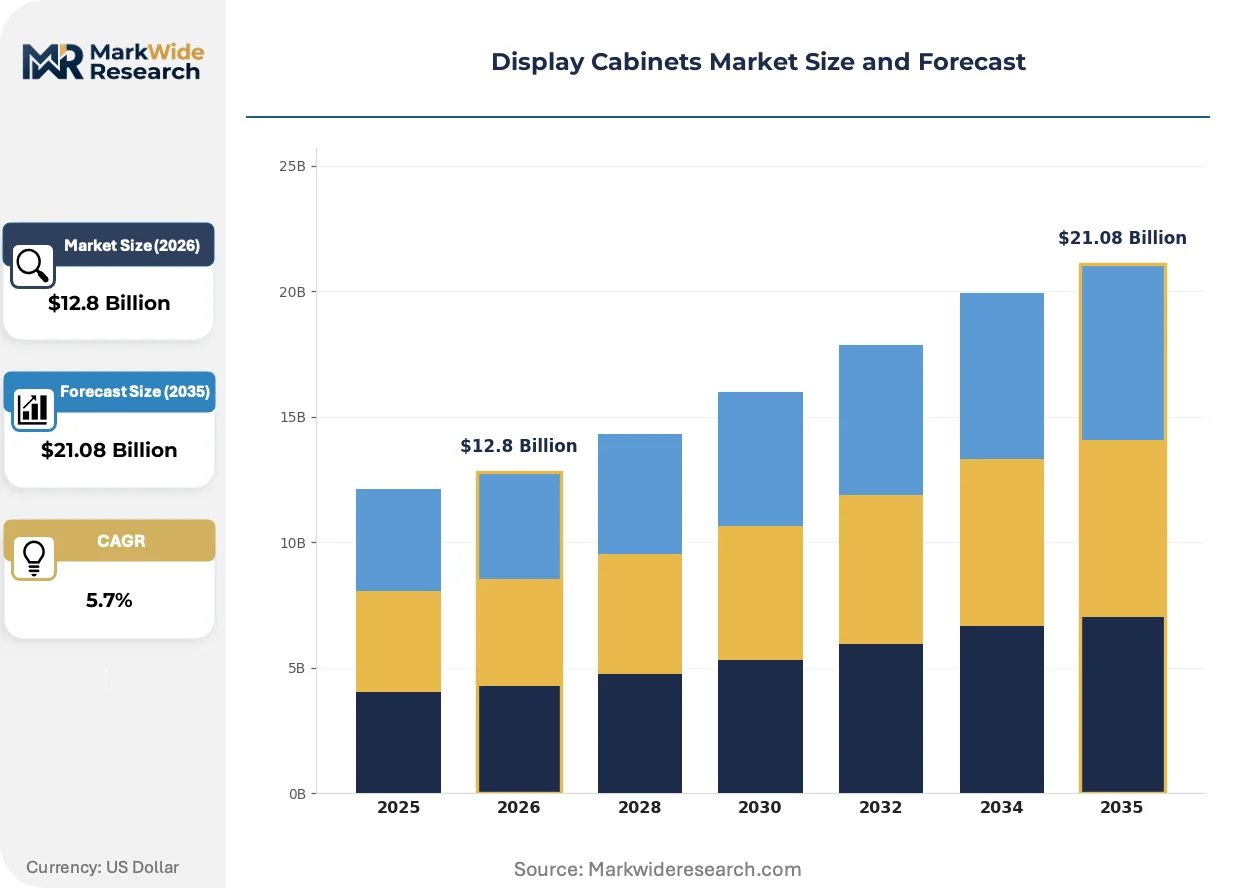
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted, Free-Standing, Countertop, Display Cases Material: Wood, Glass, Metal, Acrylic Size: Small, Medium, Large, Custom End User: Retail Stores, Museums, Homes, Offices |
| Companies Covered | Medallion Cabinetry, Fabuwood Cabinetry, American Woodmark Corporation, GoldenHome, Oppein, Wellborn Cabinet, Inc., MasterBrand Cabinets, REBON Cabinets, KraftMaid, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Display Cabinets Market Strategic Shifts
Active illumination and programmable transparency technologies are rewiring how display fixtures balance aesthetic presentation with functional performance, compressing the boundary between architectural element and digital interface.
Electrochromic smart glass is migrating from high-end museum conservation units toward mainstream retail merchandising. Department store chains are specifying these panels for seasonal campaign flexibility. The technology is migrating from fixed-transparency shelving toward dynamic opacity control that enables same-surface promotional rotation without physical retrofit.
EU REACH restrictions on certain wood preservatives and glass coatings are forcing substrate reformulation across export-oriented manufacturing. ECHA substance evaluation processes are extending compliance documentation requirements. European luxury retail specifications are most affected, with buyers now demanding full material disclosure certificates from Asian suppliers.
Specification authority is consolidating among architectural firms managing branded environment rollouts for multinational retail chains. Direct manufacturer relationships are displacing traditional fixture distributor channels in large-format projects. This concentration is most visible in United States and German markets where design-build contracts bundle cabinet procurement within broader interior construction agreements.
Display Cabinets Market Segmentation
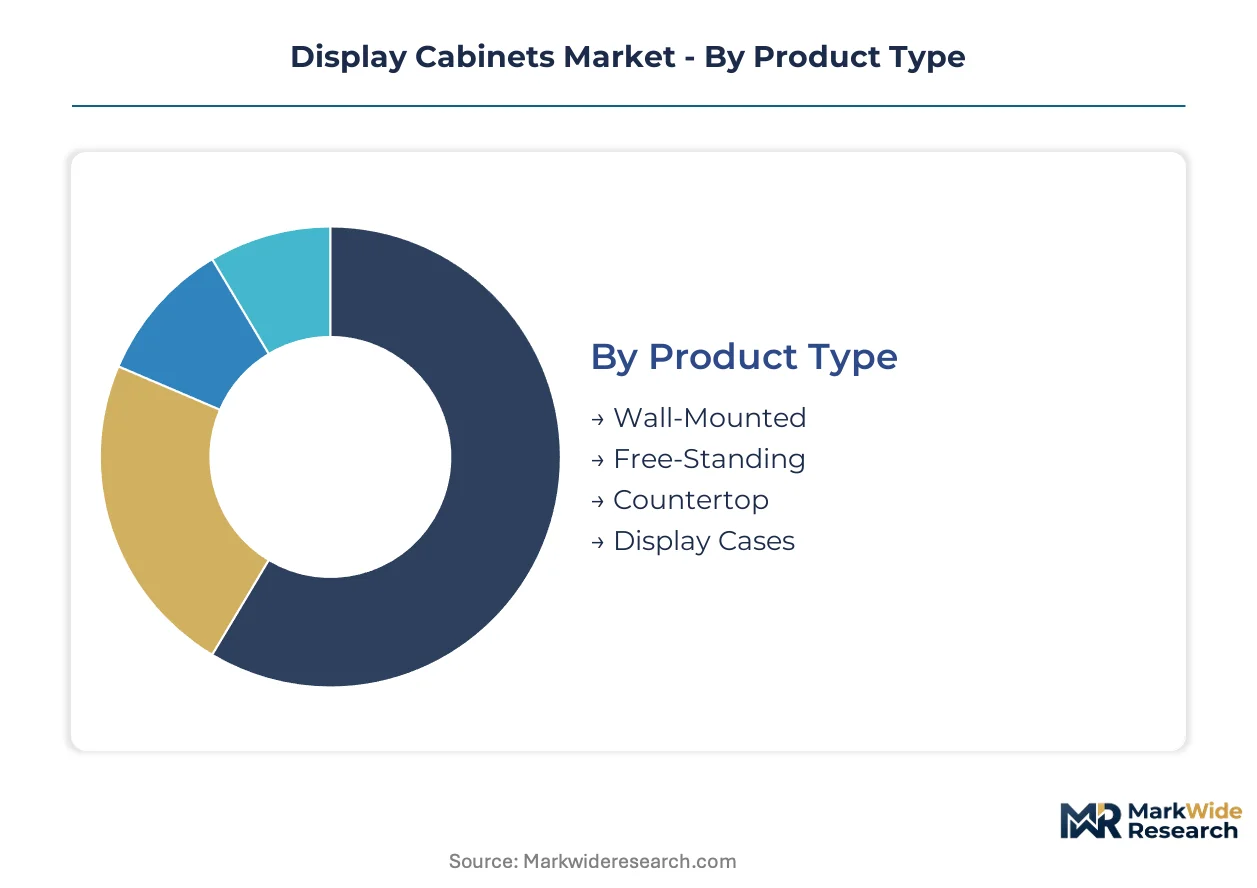
Display cabinet procurement patterns diverge sharply across installation constraints, material specifications, and end-use preservation requirements. Understanding these segment boundaries clarifies where specification authority concentrates and how supplier capabilities must align to capture margin pools.
Product Type:
After-sales service intensity varies dramatically by installation complexity, with wall-mounted systems requiring specialized mounting hardware support and free-standing units demanding floor-load engineering consultation.
- Wall-Mounted:These units attach directly to structural walls using concealed brackets or French cleat systems, demanding load-bearing assessments and seismic anchoring in commercial environments. Museums in California and Japan specify these for artifact conservation where floor space is constrained, though installation certification requirements extend project timelines.
- Free-Standing:Floor-based units with integrated leveling systems and castor mobility options dominate retail rollout programs where fixture repositioning drives seasonal merchandising flexibility. German luxury department stores and American mall anchors specify these for branded environment consistency across multiple locations.
- Countertop:Compact units designed for point-of-sale impulse merchandising and jewelry presentation, typically under 24 inches in height.
- Display Cases:Enclosed systems with integrated climate control and security locking, common in museum conservation and high-value retail.
Free-standing units hold the largest share; momentum sits with wall-mounted systems as urban retail footprints shrink.
Material:
Raw material cost volatility and regulatory compliance burden reshape competitive positioning across substrate categories.
- Wood:Engineered panels, solid hardwoods, and veneer-wrapped substrates form the structural backbone of premium residential and museum specifications. EPA TSCA Title VI certification requirements are redirecting procurement toward CARB Phase 2-compliant suppliers in domestic manufacturing, while EU Green Deal incentives favor reclaimed timber content in public sector tenders.
- Glass:Tempered safety glass, low-iron optical panels, and electrochromic smart glass enable programmable transparency and thermal management integration. REACH restrictions on certain glass coatings are fragmenting supplier qualification between European and Asian manufacturing bases.
- Metal:Aluminum extrusions and stainless steel framing provide structural rigidity for high-traffic commercial deployments.
- Acrylic:Shatter-resistant polymer panels substitute for glass in impact-prone environments where optical clarity is secondary.
Wood substrates dominate specification volume; glass combinations command the steepest expansion trajectory as smart transparency technology matures.
Size:
Manufacturing economies of scale concentrate in standard dimensional ranges, while custom work captures disproportionate margin contribution.
- Small:Units under 30 inches in any dimension, typical for countertop jewelry and collectibles presentation.
- Medium:Standard retail merchandising dimensions between 30 and 72 inches, optimized for palletized shipping and rapid store assembly.
- Large:Floor-to-ceiling installations and multi-bay systems for flagship retail and museum atrium displays.
- Custom:Architect-specified dimensions engineered for exact branded environment requirements, generating the highest per-unit margins but demanding extended production cycles and specialized installation protocols.
Medium sizes anchor volume production; custom specifications are climbing the fastest as design-build contracts consolidate procurement authority.
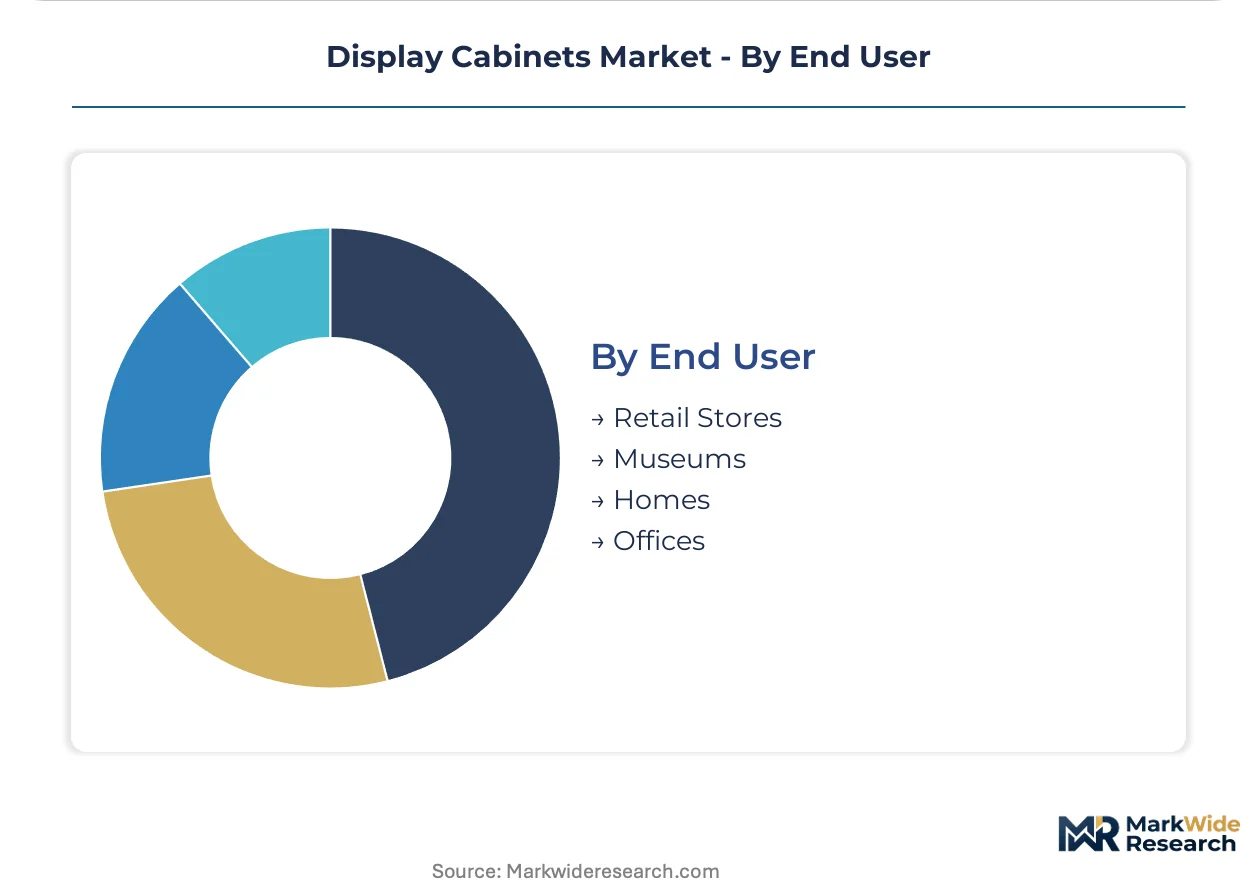
End User:
Specification sophistication and compliance requirements create distinct service models across buyer categories.
- Retail Stores:Fast-fashion chains and luxury department stores drive fixture refresh programs with compressed rollout timelines. Modular rapid-assembly systems are penetrating this channel as expansion cycles demand 48-hour store configuration turnaround.
- Museums:Conservation-grade specifications with humidity regulation, UV filtration, and seismic anchoring dominate cultural institution procurement. Climate-controlled systems for artifact preservation are expanding specification volumes as collection digitization programs free physical display capacity.
- Homes:Residential collectors and interior designers specify aesthetic-forward units with lower engineering requirements than commercial deployments.
- Offices:Corporate presentation environments for awards, product samples, and reception area merchandising.
Retail stores represent the largest addressable base; museums are gaining share fastest as conservation protocol standardization spreads through institutional accreditation programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for tempered glass and aluminum extrusions shapes competitive positioning across manufacturing bases, while fixture export flows concentrate where retail expansion cycles and museum construction programs intersect with compliant substrate supply chains.
United States
Department store fixture refresh programs and museum digitization initiatives drive specification volumes for climate-controlled and LED-integrated systems. EPA TSCA Title VI enforcement redirects domestic manufacturing toward CARB Phase 2-certified engineered wood panels. Grand Rapids, Michigan anchors hardwood cabinetry production for residential and light commercial lines.
Germany
Luxury department store chains and cultural institution procurement sustain premium demand for conservation-grade specifications. EU REACH restrictions on wood preservatives and glass coatings fragment supplier qualification requirements. The North Rhine-Westphalia manufacturing corridor concentrates metal framing and glass integration capabilities for high-traffic commercial deployments.
China
Fast-fashion retail rollout programs and domestic museum construction expand addressable volumes for modular rapid-assembly systems. GB standards enforcement on volatile organic compound limits redirects coating procurement toward compliant domestic suppliers. Guangdong Province manufacturing clusters dominate tempered glass furnace operations and aluminum extrusion output for regional project channels.
Japan
Precision retail environments and private collector demand sustain specification volumes for compact countertop and wall-mounted systems. METI energy efficiency guidelines influence LED thermal management integration requirements. The Kansai region around Osaka maintains specialized glass coating and metal finishing capabilities for premium commercial specifications.
United Kingdom
Heritage museum renovation programs and boutique retail expansion sustain demand for custom-dimensioned conservation systems. CSRD reporting requirements and EU Green Deal procurement preferences favor reclaimed timber content in public sector tenders. London-based architectural practices consolidate specification authority for multinational branded environment rollouts.
Display Cabinets Market Competitive Environment
On the supply side, the industry is bifurcated between scale-driven residential fabricators and project-specialized commercial systems providers. Tiered competitive positioning separates captive hardwood sourcing operations, modular rapid-retail specialists, and climate-control engineering firms. Dominant competitive moves include backward integration into certified substrate supply and geographic expansion through design-build contract consolidation.
Within the scale-driven tier, American Woodmark Corporation and MasterBrand Cabinets occupy positions anchored in North American residential and light commercial distribution density. Fabuwood Cabinetry exemplifies Northeast corridor market penetration through distributor network concentration. Oppein represents the Asian project channel archetype with modular systems engineered for compressed retail rollout timelines. These three fabricators illustrate how supply-side configuration aligns with distinct demand segment access.
| Leading Market Players |
|---|
| Medallion Cabinetry |
| Fabuwood Cabinetry |
| American Woodmark Corporation |
| GoldenHome |
| Oppein |
| Wellborn Cabinet, Inc. |
| MasterBrand Cabinets |
| REBON Cabinets |
| KraftMaid |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Rotterdam maritime corridor shapes landed cost dynamics for tempered glass and aluminum extrusions, compressing margin pools for European fabricators while amplifying price differentiation between LED-integrated smart glass systems and conventional illuminated shelving. Supply concentration in Guangdong Province furnace operations and North Rhine-Westphalia metal framing clusters feeds directly into three-tier pricing stratification across premium conservation-grade, standard commercial, and economy retail specifications.
Pricing Analysis
The technology-generation pricing gap separates electrochromic smart glass installations from LED-integrated conventional units and legacy fluorescent fixtures. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence—EPA TSCA Title VI and EU REACH compliance command material premiums—while cost compression in economy tiers stems from acrylic substitution in high-traffic retail. Fast-fashion chains exhibit highest price sensitivity; museum conservation officers prioritize climate-control performance over unit economics.
Supply Chain Analysis
Contract manufacturing concentration rests with Guangdong-based tempered glass furnace operators and North Rhine-Westphalia aluminum extrusion specialists, with secondary capacity in Michigan hardwood panel fabrication. Raw material flows draw from coastal Chinese flat glass clusters, German smelter operations, and Appalachian hardwood reserves. Single-source vulnerability concentrates in electrochromic glass coating supply. Distribution runs through specification-consolidating architectural practices and traditional fixture distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The display cabinets market functions as a defensive-moat story anchored in regulatory entrenchment—EPA TSCA Title VI, EU REACH, and China's GB standards create multi-year certification barriers that lock qualified suppliers into recurring specification cycles.
For Market Incumbents: Insulate market position by deepening captive hardwood sourcing in Michigan and Appalachia to buffer against engineered panel cost volatility, while accelerating LED thermal management engineering capabilities to defend against smart glass-IoT convergence threats from adjacent building automation suppliers. For New Entrants and Emerging Players: Build out white-space presence in EU Green Deal-compliant reclaimed timber substrates for public sector museum tenders, and in modular rapid-assembly systems for fast-fashion rollout programs. The most penetrable entry point sits with mid-size American retail chains seeking 48-hour store configuration turnaround without legacy distributor relationships. For Investors and Strategic Acquirers: Climate-control engineering specialists with museum accreditation represent the priority acquisition archetype, given conservation protocol standardization through institutional accreditation programs. Long-term viability across the analysis window hinges on smart glass-IoT integration capabilities. The signal to watch is accelerated specification consolidation among London-based and New York-based architectural practices managing multinational branded environment rollouts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Substrate Supply | EPA TSCA Title VI compliance secures qualification priority in domestic manufacturing channels. |
| Smart Glass-IoT Platform Integration | Programmable transparency systems with inventory sensors capture premium pricing in automated retail. |
| EU Green Deal Certification Investment | Reclaimed timber content unlocks public sector tender preferences in European museum procurement. |
| Modular Rapid-Retail System Expansion | Pre-engineered 48-hour rollout modules penetrate fast-fashion expansion cycles in Asian project channels. |
| Climate-Control Engineering Acquisition | Humidity-regulated cabinet capabilities address museum digitization-driven display capacity expansion. |
Study Parameters
Initial hypotheses were tested against primary input from fixture procurement managers at luxury department store chains, museum conservation officers, architectural specification leads, and engineered wood panel suppliers, and refined through secondary validation against EPA TSCA Title VI compliance databases, EU ECHA substance evaluation registers, China GB standards enforcement bulletins, and customs trade flow records for tempered glass and aluminum extrusions. Bottom-up project pipeline aggregation and top-down macroeconomic adjustment were cross-referenced for triangulation.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling product type, material specification, end-use sector, and regional regulatory cluster dimensions. CAGRs were derived from segment-level volume trajectories weighted by pricing tier evolution, incorporating LED refresh cycle compression rates, museum construction program pipelines, and retail footprint expansion schedules as industry-specific inputs.
Stress conditions across energy tariff volatility for aluminum smelting, formaldehyde emission regulation enforcement intensity, and fast-fashion rollout cycle acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technology substitution timelines and regulatory harmonization probabilities. Quarterly review of architectural specification consolidation indicators and GB standards enforcement actions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Storage and Organization
Clothes Closets Market
Home Storage and Organization
Wardrobe Boxes Market
Home Storage and Organization
Asia-Pacific Digital Home Locker Market
Home Storage and Organization
Collapsible Wardrobe Market
Home Storage and Organization
Jewelry Organizer Market
Home Storage and Organization
Sheds and Outdoor Storage Market
Home Storage and Organization
Toy Storage Market
Home Storage and Organization
Scandinavia Self-Storage Market
Home Storage and Organization
Shop Shelving Market
Home Storage and Organization
Europe Home Organizers and Storage Market
Home Storage and Organization
Tool Chest Market
Home Storage and Organization
Shoe Rack Market
Home Storage and Organization
Small Space Furniture Market
Home Storage and Organization
Shelf Display Trays Market
Home Storage and Organization
Flush Mount Photo Album Market
Home Storage and Organization
Closet Organizers Market