
 Europe Gas Market | 2026-2036
Europe Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Gas Market Analysis
Industrial energy buyers are rotating away from pure natural gas contracts toward blended and certified low-carbon gas supply agreements. Shell PLC leverages its integrated LNG trading infrastructure to secure long-term offtake across Northwest European hubs. Equinor ASA anchors its position through upstream control over North Sea reserves and direct pipeline connections to Germany and the United Kingdom. TotalEnergies competes by extending its biomethane production capacity across France and expanding synthetic natural gas pilot projects.
Europe gas encompasses methane-based energy carriers—natural gas, biogas, liquefied natural gas, and synthetic natural gas—distributed through high-pressure pipelines, underground storage facilities, and cryogenic LNG terminals operating at minus 162 degrees Celsius, serving combustion, process heat, and grid-balancing functions. Natural gas still occupies the largest volume share, yet biogas and synthetic natural gas represent the fastest-growing type segments as renewable gas certificates trade at structural premiums. Pipeline infrastructure dominates capital deployment, though LNG terminals attract disproportionate investment as regasification capacity expands along North Sea and Mediterranean coastlines.
The EU Green Deal, F-Gas Regulation, and national implementations of the Renewable Energy Directive shape fuel quality standards and carbon accounting methodologies across member states. EMA and national regulators like Germany's Federal Network Agency enforce methane leak monitoring and blending mandates that alter supplier compliance costs. Stakeholders must monitor biomethane certificate liquidity and cross-border pipeline tariff reforms as these mechanisms determine which infrastructure investments recover capital fastest.
Market Dynamics
Industrial energy buyers across Germany, Italy, and the Netherlands are rotating procurement portfolios away from unabated natural gas toward certified low-carbon blends as the EU Green Deal tightens carbon intensity benchmarks and pipeline interconnections reshape supply security calculations.
Growth Catalysts
- EU Green Deal carbon intensity mandates:The framework forces industrial heat users to document lifecycle emissions, creating structural pull for biomethane certificates and synthetic natural gas offtake agreements.
- LNG terminal expansions:New regasification capacity along North Sea and Mediterranean coastlines diversifies import routes and reduces dependency on single-source pipeline deliveries.
- Power-to-X pilot scaling:Electrolyzer capacity additions in Denmark and the Netherlands enable synthetic methane production from curtailed renewable electricity, anchoring demand for grid-balancing gas carriers.
Market Restraints
- Biomethane feedstock competition:Agricultural residue availability constrains output scaling as food security policies prioritize crop use.
- Pipeline tariff fragmentation:Cross-border transport cost disparities between German and Dutch hub pricing distort locational incentives for storage injection.
- Methane slip monitoring costs:EMA leak detection mandates impose capital burdens on aging distribution networks that lack continuous emissions monitoring infrastructure.
Strategic Opportunities
- Polish and Baltic storage development:Underground salt cavern expansions offer seasonal arbitrage potential as regional pipeline reversals enable new flow patterns.
- Renewable gas certificate pooling:Trading platforms aggregating Guarantees of Origin from biogas, hydrogen, and synthetic methane create liquid hedging instruments.
- Industrial cluster conversion:Rotterdam and Antwerp chemical complexes present anchor demand for hydrogen-natural gas blending trials under F-Gas Regulation compliance pathways.
Industry Challenges
- Cross-border tariff harmonization delays:National implementations of the Renewable Energy Directive create inconsistent biomethane certification recognition between member states.
- Cryogenic maintenance specialization:LNG terminal operators face technician shortages for minus 162 degree Celsius pump and vaporizer systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Gas Market |
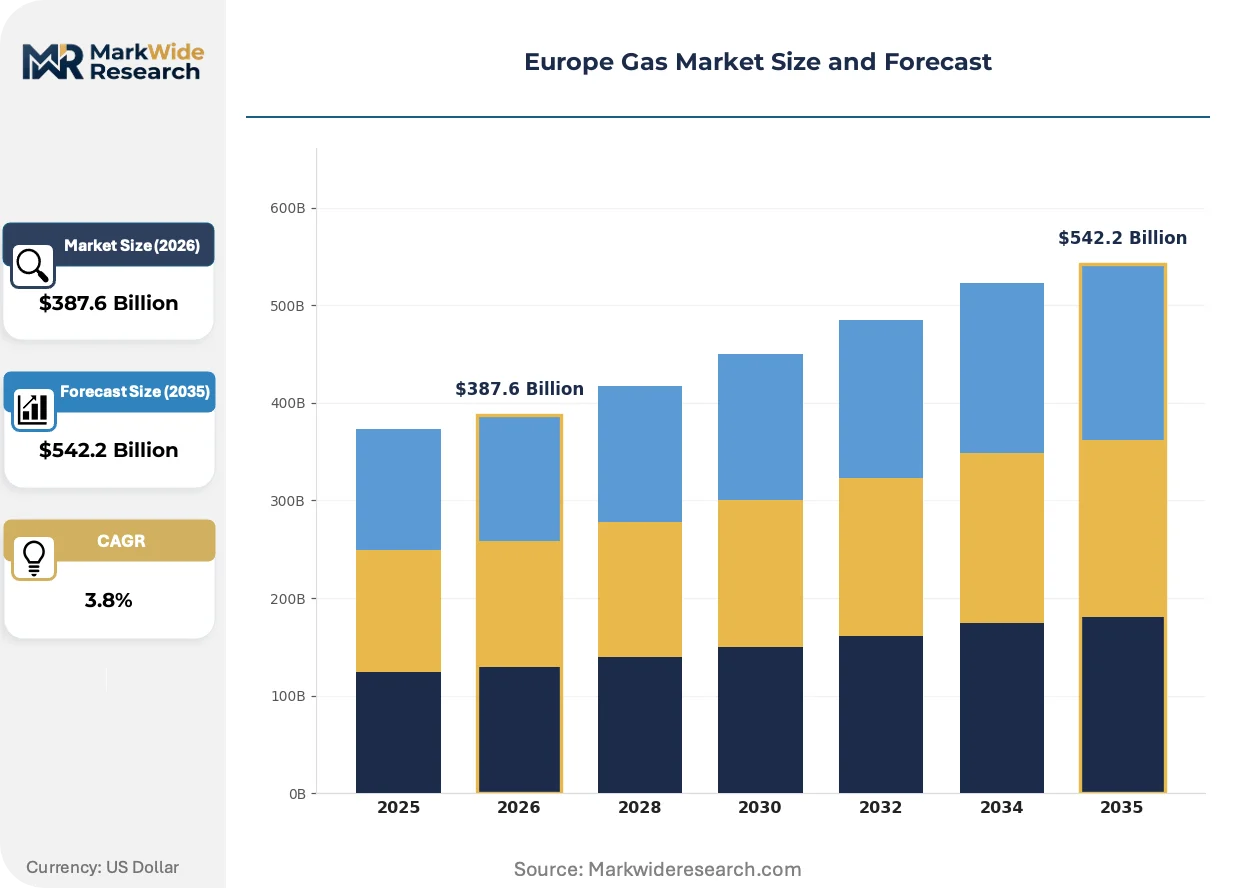
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $542.2 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Residential Heating, Commercial Cooking, Industrial Energy, Power Generation Type: Natural Gas, Biogas, Liquefied Natural Gas, Synthetic Natural Gas Infrastructure: Pipelines, Storage Facilities, LNG Terminals, Compression Stations End User: Households, Utilities, Manufacturers, Energy Traders |
| Companies Covered | Equinor ASA, OMV Group, Shell PLC, PKN Orlen, Repsol SA, TotalEnergies, Eni, Gazprom (Russian operations in Europe), BP PLC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Gas Market Emerging Trajectories
Synthetic natural gas produced via power-to-methane pathways is actively reshaping procurement specifications as industrial buyers seek carbon-neutral alternatives compatible with existing combustion infrastructure.
Power-to-methane systems combining electrolysis with catalytic methanation are supplanting conventional biogas upgrading in regions with surplus renewable curtailment. Chemical processors in the Netherlands and Denmark are contracting synthetic methane offtake at five-year tenors. This technology is compressing the premium spread between renewable gas certificates and conventional LNG cargoes.
The F-Gas Regulation phase-down schedule for fluorinated greenhouse gases is forcing refrigeration-dependent LNG terminals to retrofit cargo handling systems with magnetic bearing compressors. Terminal operators in Belgium and Spain face accelerated capex timelines. Mediterranean import facilities are responding by clustering maintenance windows to amortize compliance costs across multiple vessel calls.
Certificate-stacked procurement contracts bundling biomethane Guarantees of Origin with carbon removal credits are displacing simple volume-based supply agreements among German chemical conglomerates. Traders now quote basis spreads against TTF hub pricing that embed renewable content premiums. This model concentrates most visibly in the Rhine-Ruhr industrial corridor where corporate net-zero commitments outpace pipeline decarbonization timelines.
Europe Gas Market Segmentation
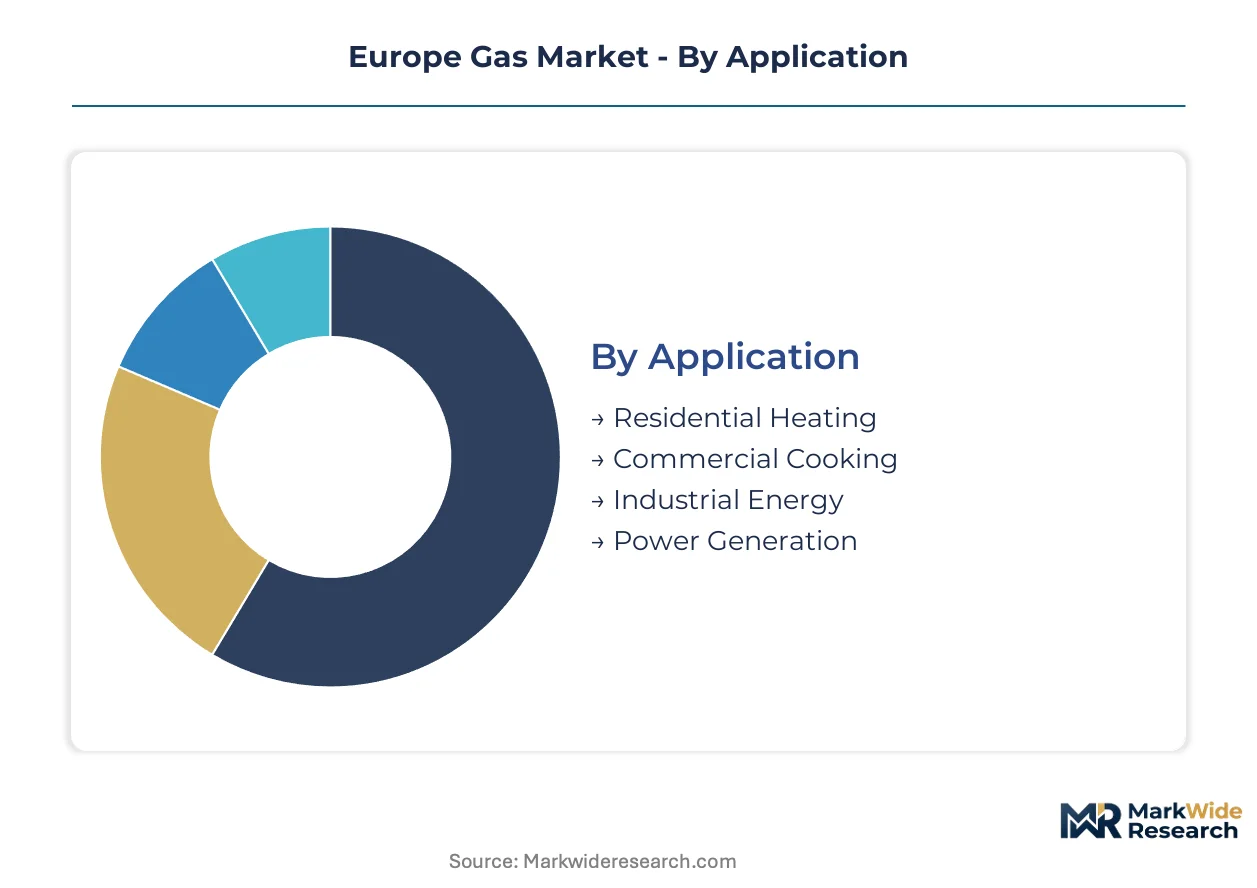
Segmentation reveals how carbon intensity regulations and infrastructure access reshape procurement economics across buyer categories. Understanding these divides exposes where blending mandates and certificate premiums concentrate margin pressure.
Application:
Industrial Energy faces the most acute substitution pressure as EU Green Deal benchmarks force heat-intensive processes toward certified low-carbon alternatives.
- Industrial Energy:Process heat and steam generation dominate offtake volumes. Rhine-Ruhr chemical clusters and Rotterdam refining complexes drive demand for biomethane certificates as corporate net-zero commitments outpace pipeline decarbonization timelines.
- Power Generation:Grid-balancing combustion turbines absorb peak renewable curtailment. Dutch and German utilities are contracting synthetic natural gas offtake to maintain dispatchable capacity under tightening methane leak monitoring mandates.
- Residential Heating:Condensing boiler replacements concentrate in Germany and the Netherlands as building efficiency directives accelerate heat pump displacement of pure natural gas connections.
- Commercial Cooking:Restaurant and hospitality gas connections face municipal decarbonization ordinances in Paris and Milan urban cores.
Industrial Energy anchors the volume base while Power Generation gains share at the steepest rate.
Type:
Cost tier stratification separates pipeline-delivered molecules from cryogenic and synthetic alternatives carrying certificate premiums.
- Natural Gas:Conventional methane extracted from North Sea and Russian pipeline deliveries still commands the largest volume position. German and Italian buyers leverage TTF hub liquidity for price discovery despite carbon border adjustment exposure.
- Synthetic Natural Gas:Power-to-methane pathways using curtailed Danish and Dutch wind electricity enable carbon-neutral combustion compatibility. Electrolyzer capacity additions are compressing the premium spread against conventional LNG cargoes.
- Biogas:Agricultural residue fermentation with upgrading to grid specifications serves regional industrial clusters. Feedstock competition from food security policies constrains output scaling in France and Poland.
- Liquefied Natural Gas:Minus 162 degree Celsius cryogenic cargoes diversify import routes for Atlantic and Mediterranean terminals. Regasification capacity expansions along Belgian and Spanish coastlines reduce single-source pipeline dependency.
Natural Gas retains the dominant volume position while Synthetic Natural Gas expands most quickly as power-to-X pilot scaling accelerates.
Infrastructure:
Geographic concentration of capital deployment favors coastal LNG terminals over inland pipeline extensions.
- Pipelines:High-pressure transmission grids connect North Sea production to German industrial demand centers. Cross-border tariff fragmentation between Dutch and German hub pricing distorts locational storage incentives.
- LNG Terminals:Cryogenic regasification facilities at minus 162 degrees Celsius enable Atlantic and Mediterranean supply diversity. F-Gas Regulation compliance is forcing Belgian and Spanish operators toward magnetic bearing compressor retrofits.
- Storage Facilities:Underground salt caverns in Poland and the Baltics offer seasonal arbitrage as pipeline reversals enable new flow patterns. EMA leak detection mandates impose capital burdens on aging distribution networks.
- Compression Stations:Grid balancing infrastructure maintains pressure differentials across long-distance transmission corridors. Maintenance specialization shortages constrain throughput optimization.
Pipelines anchor the volume base while LNG Terminals attract disproportionate investment as import diversification accelerates.
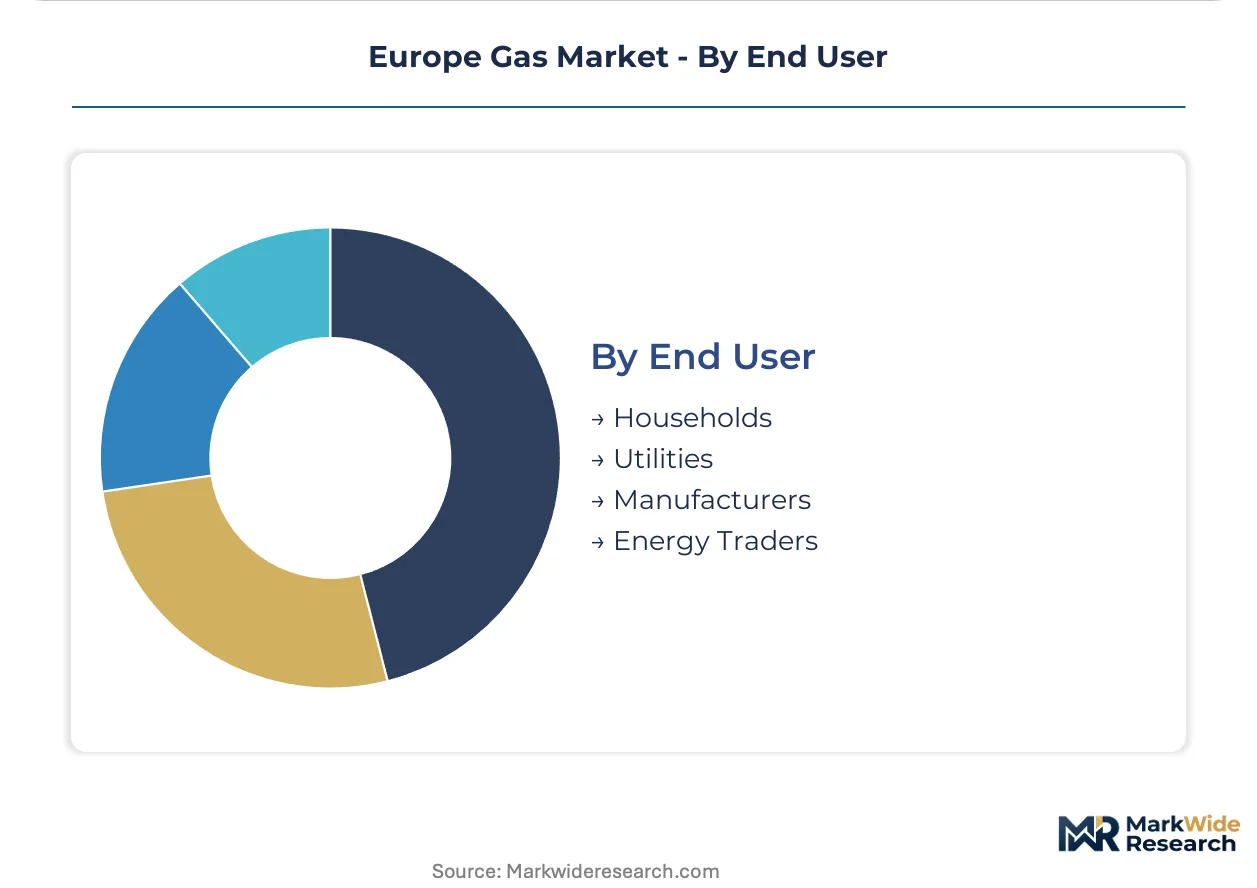
End User:
Customer type determines contract structure sophistication from standardized household tariffs to certificate-stacked procurement.
- Utilities:Grid operators and municipal distributors balance seasonal demand swings through storage injection programs. German Federal Network Agency blending mandates alter compliance cost structures.
- Manufacturers:Chemical and steel producers negotiate long-term offtake with renewable content guarantees. Certificate-stacked contracts bundling Guarantees of Origin with carbon removal credits displace simple volume agreements.
- Energy Traders:Hub-based speculators quote basis spreads embedding biomethane premiums against TTF benchmarks. Liquidity concentration in Northwest European hubs favors sophisticated hedging instruments.
- Households:Residential consumers face regulated tariff structures with limited exposure to wholesale volatility. Building efficiency retrofits are accelerating heat pump displacement.
Utilities anchor the volume base while Manufacturers drive the steepest contract sophistication gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Sea production infrastructure and LNG terminal access determine competitive positioning across European gas markets. Pipeline interconnections and storage geology create divergent procurement economics between Atlantic and continental buyers.
Germany
Rhine-Ruhr chemical clusters and Hamburg industrial zones drive biomethane certificate demand as corporate net-zero commitments accelerate. The Federal Network Agency enforces blending mandates that alter supplier compliance structures. Wilhelmshaven and Brunsbüttel LNG terminals reduce single-source pipeline dependency through new regasification capacity.
Netherlands
Rotterdam refining complexes and Amsterdam data centers anchor synthetic natural gas offtake from electrolyzer pilots in Groningen. EU Green Deal carbon intensity benchmarks force heat-intensive processes toward certified low-carbon alternatives. TTF hub liquidity concentrates price discovery for Northwest European gas trading.
Italy
Milan-Turin industrial corridors and Po Valley manufacturing absorb biogas from agricultural residue fermentation. National implementations of the Renewable Energy Directive create certification recognition frameworks for Guarantees of Origin. Adriatic LNG terminals at Panigaglia diversify import routes away from Alpine pipeline constraints.
United Kingdom
Grangemouth and Teesside chemical processors leverage North Sea pipeline connections for process heat requirements. EMA methane leak monitoring mandates impose capital burdens on aging distribution networks. Grain and Milford Haven LNG terminals enable Atlantic supply diversity independent of continental hub pricing.
Spain
Barcelona and Valencia industrial zones face F-Gas Regulation compliance timelines for refrigeration-dependent cargo handling. Mediterranean LNG terminals retrofit magnetic bearing compressors to phase down fluorinated greenhouse gases. Basque Country steel producers negotiate renewable content guarantees in long-term supply contracts.
Europe Gas Market Vendor Landscape
Concentration sits with integrated energy majors controlling upstream reserves and regasification infrastructure. The vendor base spans state-backed national champions, privately held trading houses, and specialized biomethane producers. Two strategic archetypes dominate: vertically integrated upstream-downstream operators and infrastructure-focused terminal developers. Competitive moves center on long-term offtake contracting and synthetic methane pilot scaling.
Among North Sea reserve holders, Equinor ASA exemplifies the upstream-anchored archetype through Norwegian production control and direct pipeline connections. Shell PLC occupies a position as the integrated trading infrastructure specialist with LNG hub presence across Northwest Europe. TotalEnergies represents the portfolio diversification vector through biomethane production capacity and power-to-methane pilot investments. These three players anchor distinct competitive positioning without overlapping strategic emphasis.
| Leading Market Players |
|---|
| Equinor ASA |
| OMV Group |
| Shell PLC |
| PKN Orlen |
| Repsol SA |
| TotalEnergies |
| Eni |
| Gazprom (Russian operations in Europe) |
| BP PLC |
| Others |
Supply Flow & Price Mechanics
Regasification capacity utilization at Wilhelmshaven and Brunsbüttel LNG terminals shapes both supply concentration and price floors across Northwest European hubs. Pipeline tariff differentials between Dutch TTF and German hub pricing compress margins for storage operators while certificate premiums for biomethane create tiered procurement economics.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified low-carbon molecules from conventional pipeline gas and spot LNG cargoes. Premium tiers command structural spreads for Guarantees of Origin bundled with carbon removal credits, while standard pipeline contracts track TTF hub benchmarks. Cost compression in the economy tier intensifies as Russian pipeline volumes face EU Green Deal carbon border adjustments. Chemical conglomerates in the Rhine-Ruhr corridor exhibit the least price sensitivity due to corporate net-zero commitments, whereas municipal utilities face acute budget constraints for blending mandate compliance.
Supply Chain Analysis
Strategic stockpiling dominates inventory strategy as seasonal demand swings and pipeline reversal risks force utilities to maintain 90-day coverage in Polish and Baltic salt caverns. Supply concentrates in Norway, Russia, and Qatar for pipeline and LNG feedstock, with North Sea production drawing from Groningen and Barents Sea reserves. Raw material dependencies center on natural gas liquids, electrolyzer-produced hydrogen, and agricultural residue feedstocks for biomethane upgrading. Single-source vulnerability persists for Alpine pipeline corridors serving Italian demand. Distribution runs through high-pressure transmission grids to industrial clusters, with LNG terminals providing coastal bypass capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
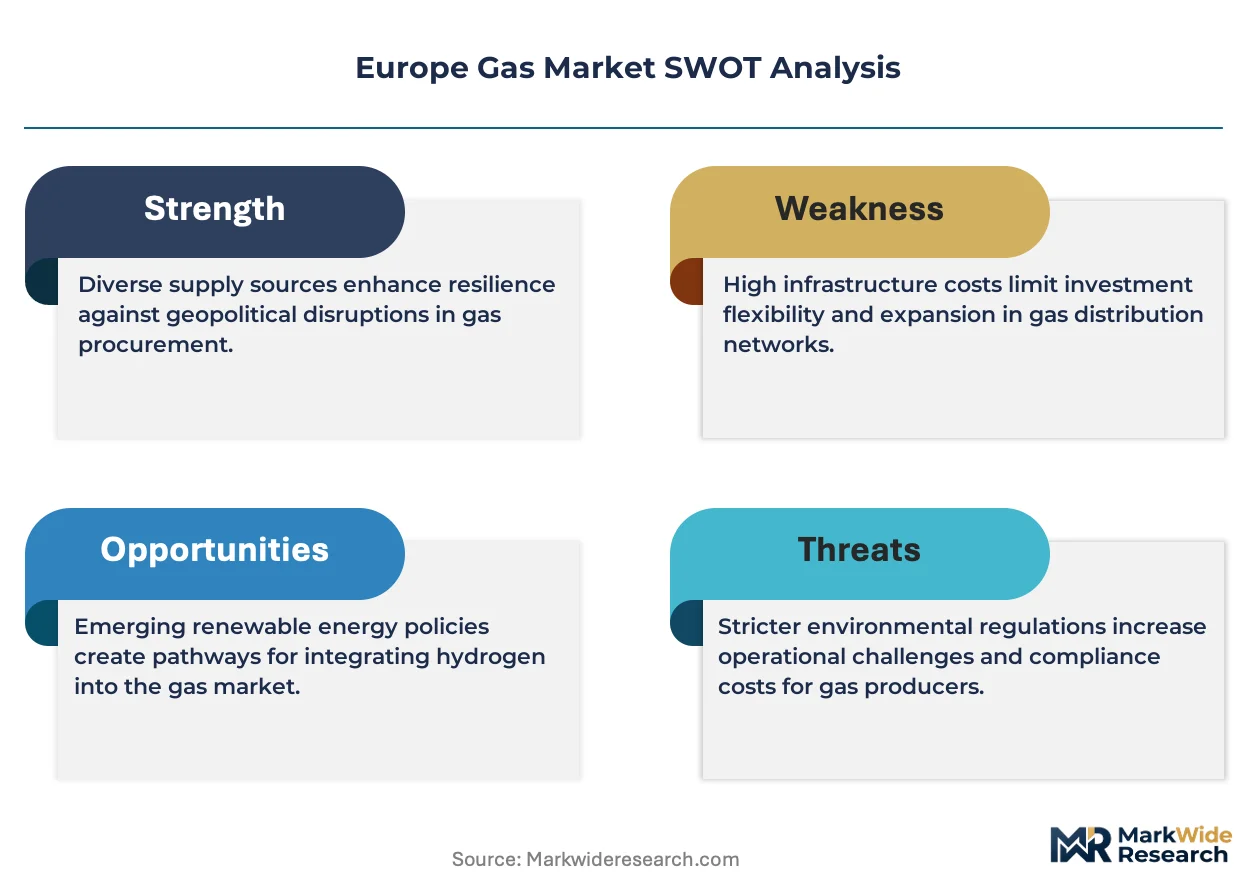
EU Green Deal fragmentation creates niche opportunities across certificate-stacked procurement, synthetic methane pilots, and storage arbitrage plays as industrial buyers diverge in compliance timelines and carbon intensity targets.
For Market Incumbents: Fortify long-term offtake positions by anchoring synthetic natural gas pilot capacity in Denmark and the Netherlands before electrolyzer cost curves flatten. Deepen upstream control over North Sea reserves to offset margin pressure from biomethane certificate premiums. Secure F-Gas Regulation compliance pathways for LNG terminal refrigeration retrofits to avoid accelerated capex timelines.
For New Entrants and Emerging Players: Biomethane certification fast-tracks through national implementations of the Renewable Energy Directive offer entry points in Poland and Italy where agricultural residue supply exceeds current upgrading capacity. Target industrial cluster conversion opportunities in Rotterdam and Antwerp for hydrogen-natural gas blending trials. Pursue tolling arrangements with existing pipeline operators rather than greenfield infrastructure development.
For Investors and Strategic Acquirers: Specialized biomethane producers with captive agricultural feedstock contracts and grid interconnection permits represent the most defensible acquisition archetype. Long-term viability hinges on certificate liquidity deepening across EU member states and cross-border tariff harmonization progress. Watch EMA methane leak monitoring mandate enforcement intensity as the inflection signal for compliance cost structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Power-to-Methane Capacity Buildout | Electrolyzer additions in Denmark anchor carbon-neutral gas supply for Dutch chemical processors. |
| Biomethane Certificate Pooling Platform | Aggregating Guarantees of Origin from biogas and synthetic methane creates liquid hedging instruments for German traders. |
| LNG Terminal F-Gas Compliance Retrofit | Magnetic bearing compressor installations at Belgian and Spanish facilities phase down fluorinated greenhouse gases. |
| Underground Storage Salt Cavern Expansion | Polish and Baltic cavern developments enable seasonal arbitrage as pipeline reversals unlock new flow patterns. |
| Industrial Cluster Hydrogen Blending Trial | Rotterdam and Antwerp chemical complexes test compliance pathways under tightening EU Green Deal benchmarks. |
Methodological Framework
Operator-level perspectives from utility planning officers, LNG terminal operators, biomethane upgrading facility managers, and industrial energy procurement leads anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation through EIA data, IEA market reports, FERC filings, and EU Green Deal implementation tracking databases. Bottom-up capacity assessments across regasification terminals and electrolyzer pilots triangulated against top-down demand modeling for industrial heat and power generation segments.
Sensitivity analysis tested forecast robustness across biomethane feedstock availability scenarios, carbon border adjustment implementation timelines, and LNG terminal utilization rates over the projection horizon. Segmentation dimensions modeled include fuel source type, infrastructure access tier, end-use application, and national regulatory framework cluster. CAGRs derived from historical volume trajectories adjusted for policy-driven substitution elasticities and power-to-X pilot scaling curves.
Decision-makers should treat outputs as directional under assumptions of continued EU Green Deal enforcement and stable North Sea production decline rates; material deviation would warrant model refresh. Revision becomes warranted when cross-border pipeline tariff harmonization progress or synthetic methane cost parity thresholds cross critical inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Briquette Market
Fuels
Europe Compressed Natural Gas Dispenser Market
Fuels
Saudi Arabia Chemical Logistics Market
Fuels
Collapsible Fuel Tank Market
Fuels
North America Commercial Aircraft Aviation Fuel Market
Fuels
CNG Dispenser Market
Fuels
Marine Fuel Optimization Market
Fuels
Global Chemical Logistics Market
Fuels
Methane Market
Fuels
India City Gas Distribution (CGD) Market
Fuels
Europe Coal Market
Fuels
LPG Gas Cylinder Market
Fuels
Smart Gas Solutions Market
Fuels
Middle-East and Africa Commercial Aircraft Aviation Fuel Market
Fuels
Wood Charcoal Market
Fuels
South Africa Bunker Fuel Market