
 Middle-East and Africa Commercial Aircraft Aviation Fuel Market | 2026-2036
Middle-East and Africa Commercial Aircraft Aviation Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Commercial Aircraft Aviation Fuel Market Foresight
Cargo carriers is rotating toward higher fuel commitments as e-commerce logistics and pharmaceutical cold-chain shipments expand across African trade lanes. Emirates National Oil Company leverages its integrated refining and terminal infrastructure to dominate supply continuity at Dubai International Airport. Saudi Arabian Oil Company anchors downstream coverage through its Jeddah and Riyadh distribution nodes, while TotalEnergies SE competes via specialized Jet A-1 quality testing and storage solutions partnerships with regional airport authorities.
Commercial aircraft aviation fuel comprises refined kerosene-based formulations, primarily Jet A and Jet A-1, engineered to specific flash points above 38 degrees Celsius and freeze points below minus 40 degrees Celsius for safe turbine combustion at altitude. The fuel serves to power turbofan and turboprop engines across scheduled passenger and freight operations, with energy density and thermal stability determining operational range and payload capacity. Jet A-1 leads fuel type demand across Middle Eastern hubs due to its wider operational temperature envelope suited to desert climates and high-altitude departures, while cargo carriers represent the fastest-growing end user segment as dedicated freighter fleets multiply between Addis Ababa, Nairobi, and Gulf hub airports. Storage solutions and quality testing command disproportionate margin pools given the scarcity of certified aviation fuel terminals and laboratory capacity across sub-Saharan Africa.
The General Civil Aviation Authority of the United Arab Emirates mandates strict fuel quality certification aligned with ASTM D1655 and DEF STAN 91-091 specifications, while Saudi Arabia's national standards body enforces analogous batch testing protocols for all aviation fuel discharged at kingdom airports. South Africa's civil aviation regulator applies equivalent quality surveillance through its designated fuel inspection regime, collectively shaping product standards and market access across the region. Stakeholders must monitor SAF blending mandates under development in Gulf jurisdictions and assess infrastructure readiness for co-processing renewable feedstocks without disrupting existing Jet A-1 supply chains.
Market Dynamics
The International Air Transport Association's carbon offset and reduction scheme for international aviation is pressuring Middle Eastern and African carriers to certify lower-carbon fuel batches, redirecting procurement criteria and infrastructure investment priorities across the region.
Growth Catalysts
- CORSIA Compliance Deadlines:The International Civil Aviation Organization's carbon offsetting scheme is mandating emissions reporting from Gulf carriers, forcing fleet operators to document fuel carbon intensity and accelerating demand for certified sustainable aviation fuel blends at Dubai and Abu Dhabi hubs.
- Long-Haul Network Expansion:Full-service carriers across the Gulf Cooperation Council corridor are extending non-stop services to secondary African cities, multiplying fuel uplift volumes at Jeddah, Riyadh, and Doha airports as wide-body deployment frequencies intensify.
- Cargo Fleet Proliferation:Dedicated freighter operations between Addis Ababa, Nairobi, and Gulf hub airports are multiplying as pharmaceutical cold-chain and e-commerce logistics expand, positioning cargo carriers as the fastest-growing fuel consumption segment.
Market Restraints
- Crude Price Volatility:Jet kerosene refining margins track Brent crude fluctuations, exposing African operators to working capital strain during price spikes and compressing budget certainty for sub-Saharan airlines with limited hedging instruments.
- Terminal Infrastructure Scarcity:Certified aviation fuel storage and laboratory testing capacity concentrates at Gulf hub airports, leaving secondary African markets dependent on trucked supply from distant coastal terminals with extended lead times.
- Feedstock Competition:Renewable diesel and marine biofuel offtake agreements are diverting hydroprocessed esters and fatty acids from aviation pathways, constraining sustainable aviation fuel batch availability for Middle Eastern blenders.
Strategic Opportunities
- Saf Blending Mandates:Gulf jurisdictions are developing compulsory sustainable aviation fuel incorporation thresholds, creating first-mover advantage for refiners co-processing renewable feedstocks through existing hydrocracker units without disrupting Jet A-1 supply chains.
- East African Hub Development:Ethiopia and Kenya are positioning Addis Ababa and Nairobi as alternative cargo transfer points, offering fuel suppliers opportunity to establish certified terminals outside traditional Gulf concentration.
- Digital Fuel Quality Tracking:Blockchain-based batch certification systems are emerging as a channel innovation, enabling real-time traceability from refinery discharge to wing-tip delivery and reducing documentation friction for multi-leg international flights.
Industry Challenges
- Specialized Laboratory Talent:ASTM D1655 and DEF STAN 91-091 testing protocols require trained chemists and chromatography equipment operators, skills that remain concentrated at Gulf hub airports and South African facilities.
- Co-Processing Retrofit Costs:Refinery modifications to handle renewable feedstocks alongside fossil kerosene demand capital allocation decisions that compete with conventional Jet A-1 capacity maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Commercial Aircraft Aviation Fuel Market |
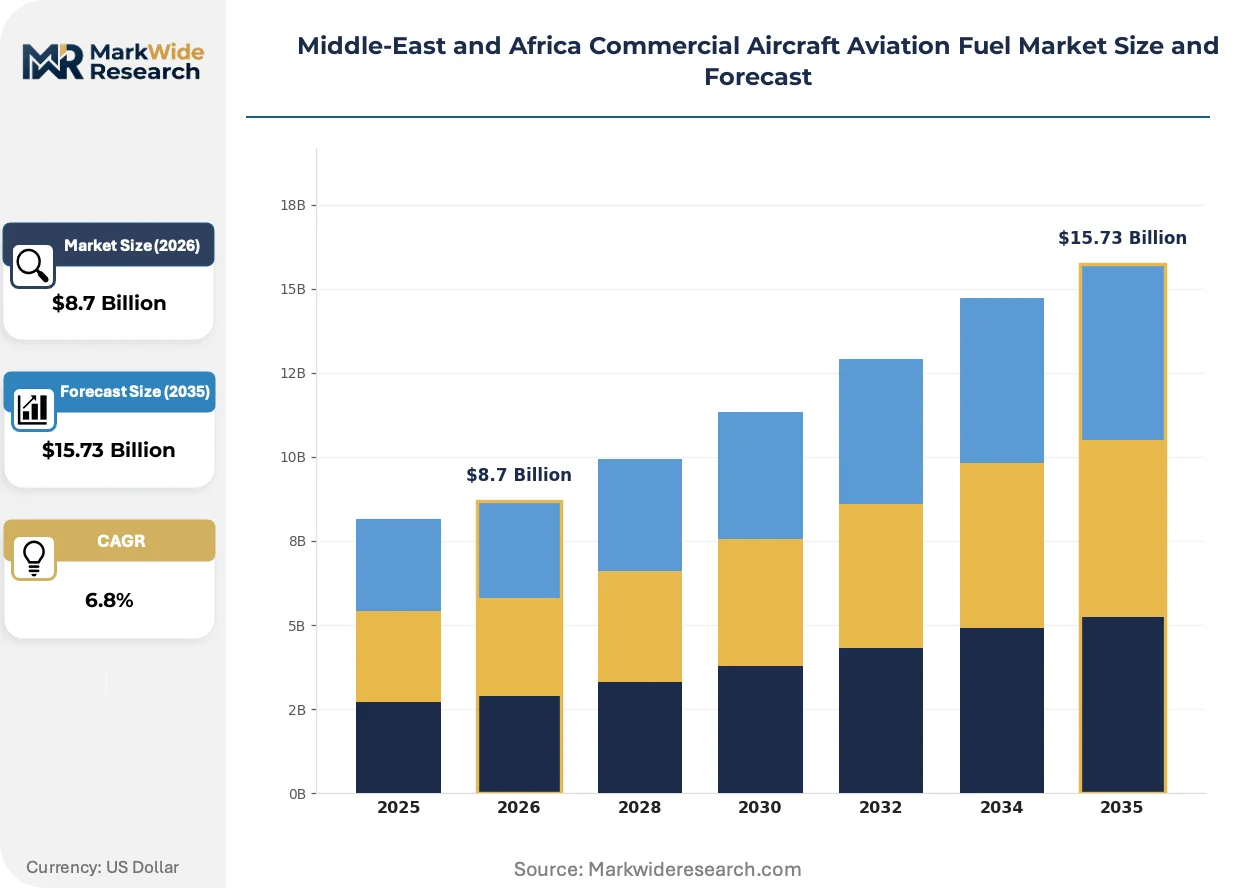
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Jet A, Jet A-1, Jet B, Avgas End User: Commercial Airlines, Cargo Carriers, Charter Services, Government Operators Distribution Channel: Direct Supply, Fuel Stations, Airport Hubs, Refueling Services Service Type: Fuel Supply, Storage Solutions, Transportation Services, Quality Testing |
| Companies Covered | Emirates National Oil Company, Abu Dhabi National Oil Company, Saudi Arabian Oil Company, TotalEnergies SE, Shell PLC, Chevron Corporation, BP PLC, Exxon Mobil Corporation, QatarEnergy, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Commercial Aircraft Aviation Fuel Market Shifts & Advancements
Aviation fuel supply chains across the Middle East and Africa are digitizing batch traceability and co-processing infrastructure to accommodate regulatory pressure for emissions intensity reduction without compromising turbine combustion specifications.
Advanced hydroprocessed ester and fatty acid refining technology is miniaturizing. This renewable feedstock conversion process produces drop-in synthetic paraffinic kerosene at smaller unit scales than conventional refinery configurations. African terminal operators with limited capital budgets are piloting modular co-processing skids. The technology is miniaturizing capital barriers for sustainable aviation fuel production, enabling distributed blending capacity at secondary airports previously excluded from certification.
The General Civil Aviation Authority of the United Arab Emirates has aligned its fuel quality certification mandates with ASTM D1655 and DEF STAN 91-091 specifications, creating a regulatory template that Saudi Arabia's national standards body and South Africa's civil aviation regulator have partially mirrored. This harmonization is reducing cross-border batch rejection rates for multi-leg flights transiting Gulf and African airports. Carriers operating Dubai-Addis Ababa-Johannesburg routes are consolidating supplier qualification processes to satisfy all three regulatory regimes simultaneously.
Freight forwarders and cargo carriers are consolidating fuel procurement under long-term offtake agreements rather than spot market purchases, compressing supplier switching cycles and prioritizing supply continuity over price arbitrage. This behavioral shift is restructuring competitive dynamics at Nairobi and Addis Ababa airports, where dedicated freighter fleets now anchor multi-year contracts with integrated refinery-terminal operators. Ethiopian Airlines Cargo and Kenya Airways' freight division are leading this consolidation in East African markets.
Middle-East and Africa Commercial Aircraft Aviation Fuel Market Segmentation
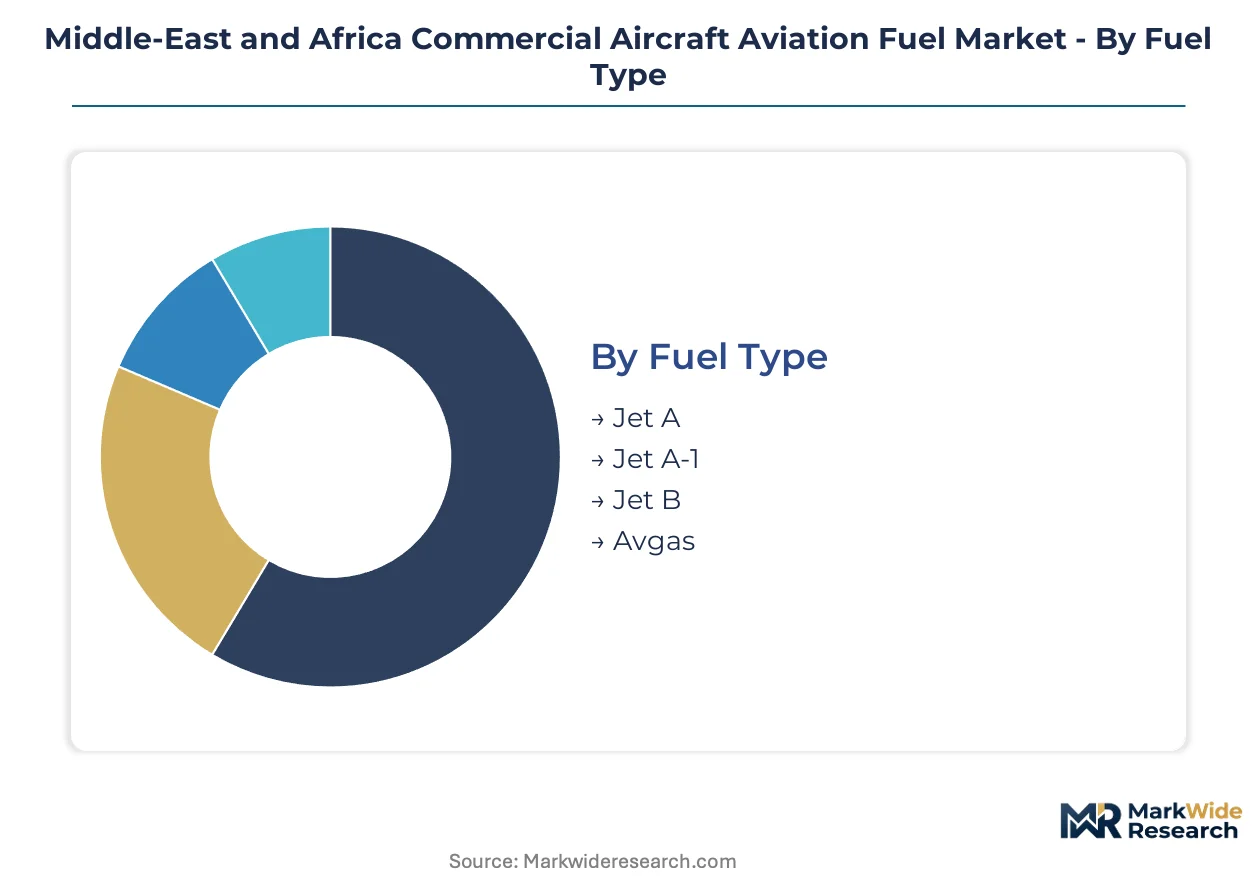
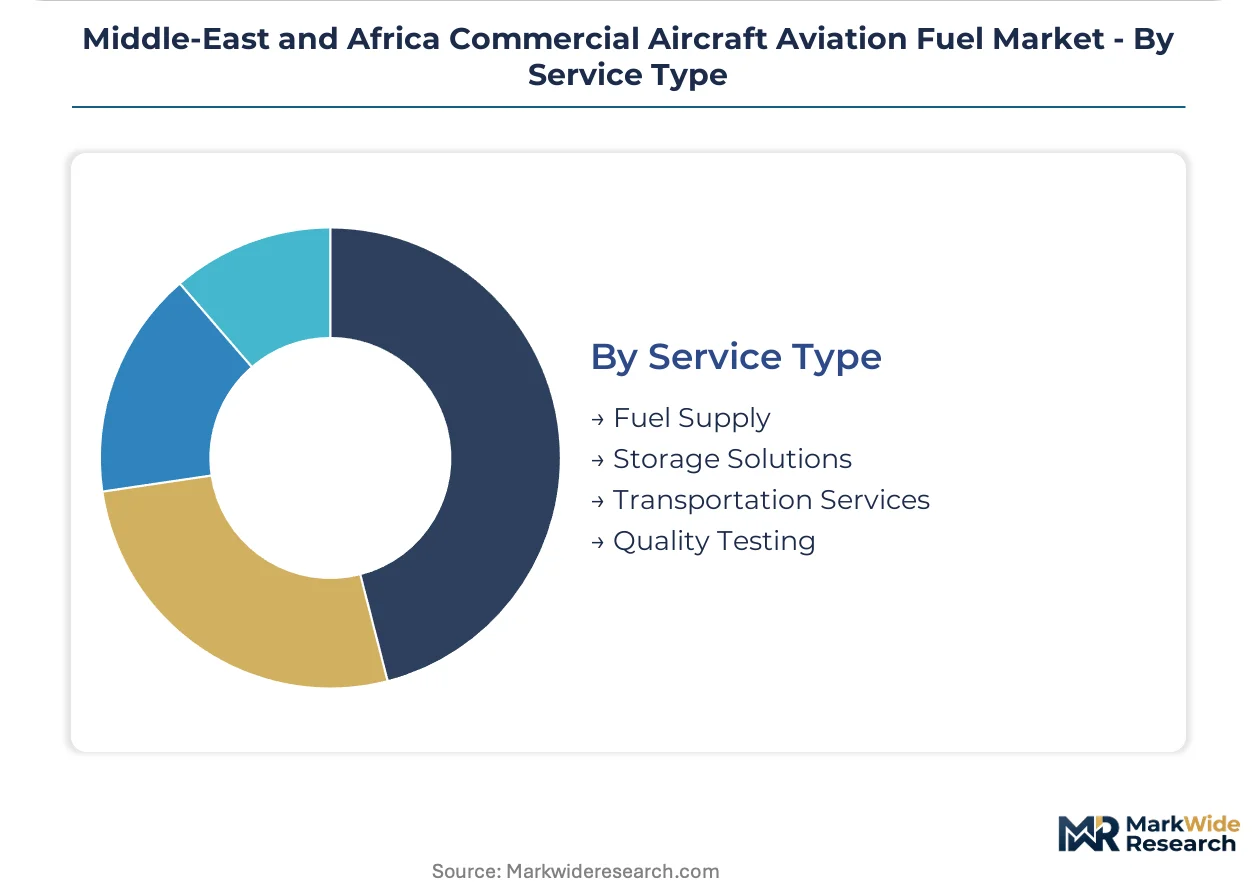
Segmentation across the Middle-East and Africa commercial aircraft aviation fuel market reveals how procurement patterns diverge between Gulf hub concentration and sub-Saharan distribution constraints. Understanding these divisions clarifies where infrastructure investment yields margin protection versus volume capture.
Fuel Type:
Jet A-1 dominates uplift at Dubai and Abu Dhabi airports due to its superior cold-weather performance, while Jet A retains share at Saudi domestic terminals with less extreme altitude exposure.
- Jet A:Refined kerosene with freeze point of minus 40 degrees Celsius serves turbofan engines at Saudi domestic airports and select North African terminals where temperature extremes are moderated. Demand clusters at Jeddah and Riyadh distribution nodes serving narrow-body fleets on regional routes.
- Jet A-1:Lower freeze point of minus 47 degrees Celsius and mandatory static dissipater additive meets DEF STAN 91-091 specifications for long-haul departures from Dubai International Airport and high-altitude African hubs. Emirates and Etihad Airways mandate this grade for all wide-body operations.
- Jet B:Wide-cut naphtha-kerosene blend for extreme cold climates sees limited uptake at high-altitude East African airports during monsoon season temperature drops.
- Avgas:Aviation gasoline for piston-engine aircraft serves general aviation and training fleets at smaller UAE and South African airfields outside scheduled commercial networks.
Jet A-1 holds the largest share; momentum sits with Jet B as high-altitude African route expansion accelerates.
End User:
Procurement scale and contract duration separate scheduled carriers with hedged offtake agreements from spot-market dependent operators.
- Commercial Airlines:Full-service Gulf carriers anchor volume through multi-year contracts with integrated refinery-terminal operators like Emirates National Oil Company, leveraging Dubai's super-connector position for transfer traffic between Europe and Asia.
- Cargo Carriers:Dedicated freighter fleets at Addis Ababa and Nairobi airports are expanding fuel commitments fastest as pharmaceutical cold-chain and e-commerce logistics multiply across African trade lanes.
- Charter Services:Irregular operations at secondary African markets rely on trucked supply from distant coastal terminals with compressed lead time certainty.
- Government Operators:State aviation units in Saudi Arabia and the UAE procure through national oil company frameworks with priority supply guarantees during disruption events.
Commercial airlines consume the greatest volume; cargo carriers are climbing the fastest as dedicated freighter deployment intensifies.
Distribution Channel:
Channel selection tracks airport certification status, with uncertified terminals forcing operators toward mobile refueling services.
- Direct Supply:Integrated refinery-to-wing pipelines at Dubai International Airport and Jeddah eliminate intermediate handling, preserving Jet A-1 specification integrity for high-frequency wide-body turnarounds.
- Fuel Stations:Off-airport storage facilities with road tanker transfer serve general aviation and training operators at secondary UAE and South African airfields lacking dedicated aviation terminals.
- Airport Hubs:Certified storage and laboratory infrastructure concentrates at Abu Dhabi, Doha, and Johannesburg, creating margin pools from scarcity premiums on quality-tested batches.
- Refueling Services:Into-plane operators with mobile dispensing equipment reach uncertified African terminals where fixed infrastructure investment remains uneconomic.
Airport hubs capture the greatest value; refueling services are expanding most quickly as East African cargo hub development proceeds.
Service Type:
Margin concentration follows certification scarcity, with quality testing commanding disproportionate returns relative to commodity fuel supply.
- Fuel Supply:Commodity Jet A-1 and Jet A delivery represents volume foundation but compresses margins where multiple suppliers compete at Gulf hub airports with surplus refining capacity.
- Storage Solutions:Certified aviation fuel tanks with nitrogen blanketing and water bottom monitoring concentrate at Dubai, Abu Dhabi, and Johannesburg, leaving sub-Saharan markets structurally undersupplied.
- Transportation Services:Road tanker fleets with dedicated aviation fuel compartments bridge supply gaps between coastal refineries and inland African airports, with lead times extending to 72 hours for Nairobi and Addis Ababa.
- Quality Testing:ASTM D1655 and DEF STAN 91-091 laboratory certification requires chromatography equipment and trained chemists, skills concentrated at Gulf hubs and South African facilities with regional monopoly pricing power.
Quality testing generates the highest margins; storage solutions are gaining share fastest as East African hub development creates demand for certified terminal infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Abu Dhabi Crude Oil Pipeline anchors regional fuel security by bypassing the Strait of Hormuz, ensuring uninterrupted kerosene feedstock access for Gulf refining complexes serving aviation demand.
United Arab Emirates
Dubai International Airport and Al Maktoum International together handle transfer traffic exceeding 89 million passengers annually, driving Jet A-1 consumption volumes. The General Civil Aviation Authority enforces ASTM D1655 and DEF STAN 91-091 fuel quality specifications through mandatory batch testing protocols. Emirates National Oil Company operates integrated refining and terminal infrastructure at Jebel Ali, supplying Dubai's super-connector hub with direct pipeline delivery.
Saudi Arabia
Jeddah and Riyadh airports anchor domestic and international wide-body operations for full-service carriers expanding African network coverage. The Saudi Standards, Metrology and Quality Organization mandates national fuel quality surveillance aligned with international aviation specifications. Saudi Arabian Oil Company maintains downstream distribution nodes at both hub cities, prioritizing supply continuity for flag carrier operations.
South Africa
Johannesburg's OR Tambo International serves as sub-Saharan Africa's primary certified aviation fuel terminal, handling connecting traffic to European and Asian destinations. The South African Civil Aviation Authority applies equivalent quality inspection regimes through designated fuel surveillance programs. Coastal refining capacity at Durban feeds inland distribution via dedicated road tanker fleets with 72-hour lead times to Johannesburg.
Ethiopia
Addis Ababa Bole International positions as an emerging cargo transfer point for pharmaceutical cold-chain and e-commerce logistics across African trade lanes. The Ethiopian Civil Aviation Authority administers fuel quality certification through adopted international standards. Ethiopian Airlines Cargo anchors dedicated freighter fleet expansion, multiplying fuel commitments through multi-year offtake agreements with integrated suppliers.
Kenya
Nairobi Jomo Kenyatta International functions as East Africa's secondary cargo hub, capturing freight diversion from congested Gulf terminals. The Kenya Civil Aviation Authority regulates aviation fuel standards through compliance with international testing protocols. Kenya Airways' freight division consolidates procurement under long-term contracts, restructuring competitive dynamics for terminal operators seeking certified infrastructure investment.
Middle-East and Africa Commercial Aircraft Aviation Fuel Market Competitive Landscape
Listed majors compete with state-controlled specialists across integrated supply chains, creating a tiered structure where scale advantages concentrate at Gulf hub airports. National oil companies leverage captive refining capacity and terminal infrastructure to dominate supply continuity, while international majors compete through specialized quality testing and storage solutions partnerships. Two archetypes define positioning: vertically integrated refinery-terminal operators with pipeline-to-wing delivery, and international traders with modular storage and laboratory certification capabilities. Competitive moves center on co-processing retrofit investments for sustainable aviation fuel readiness and multi-year offtake agreements locking cargo carrier demand.
Among Gulf-based integrated operators, Emirates National Oil Company and Abu Dhabi National Oil Company exemplify the refinery-terminal archetype with direct pipeline infrastructure. Saudi Arabian Oil Company anchors the national champion model through kingdom-wide distribution node coverage. Internationally, TotalEnergies SE occupies a position representing the quality-specialist tier, competing via laboratory certification and storage partnerships with regional airport authorities.
| Leading Market Players |
|---|
| Emirates National Oil Company |
| Abu Dhabi National Oil Company |
| Saudi Arabian Oil Company |
| TotalEnergies SE |
| Shell PLC |
| Chevron Corporation |
| BP PLC |
| Exxon Mobil Corporation |
| QatarEnergy |
| Others |
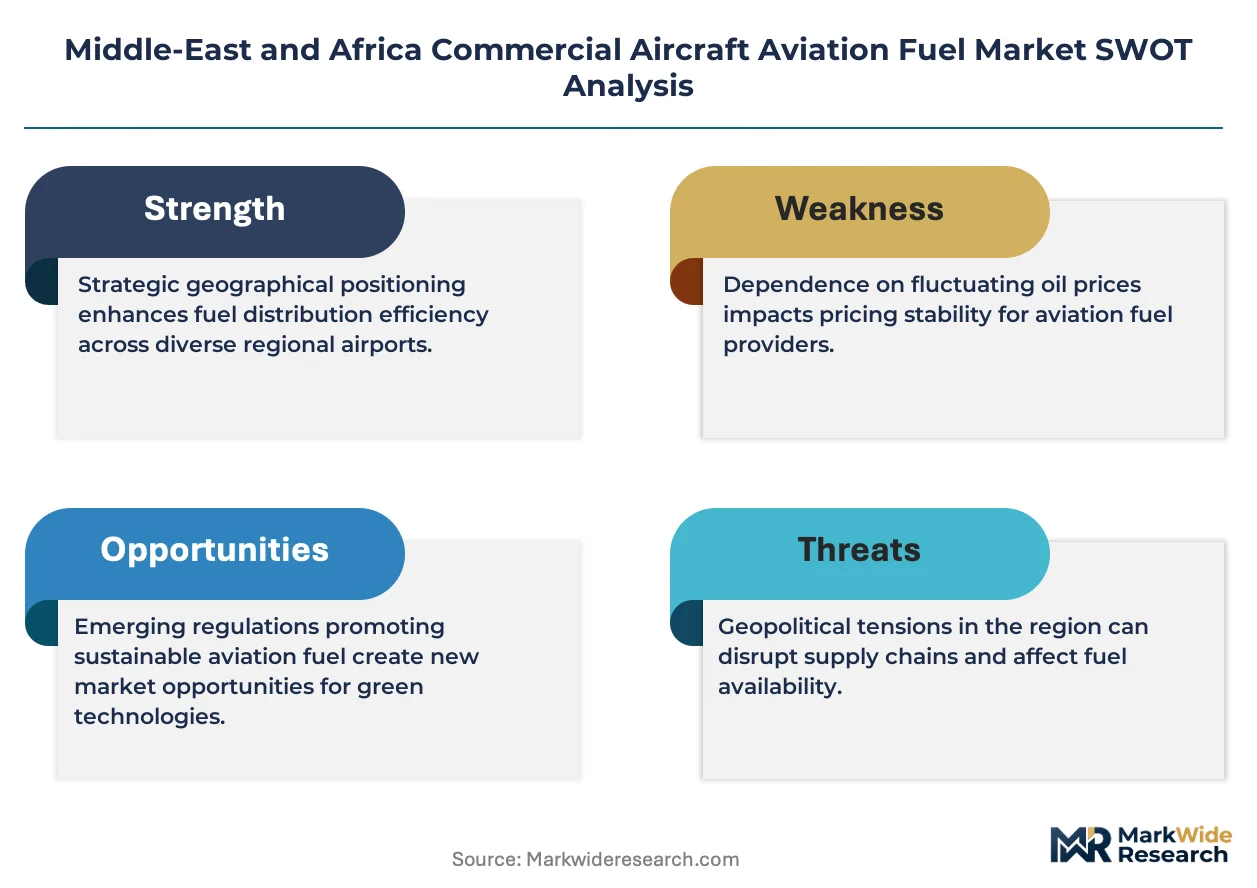
Supply & Pricing Matrix
Refinery throughput scale at Gulf hub airports creates disproportionate margin leverage for integrated operators, concentrating price-setting power among pipeline-connected suppliers while forcing truck-dependent African operators to absorb logistics premiums that erode competitive position.
Pricing Analysis
Volume-discount tiering separates full-service Gulf carriers with multi-year offtake agreements from spot-market dependent sub-Saharan operators. Three-tier pricing structure across premium certified, standard tested, and economy unbundled levels tracks batch certification depth and laboratory proximity. Pricing pressure stems from renewable diesel and marine biofuel offtake diverting hydroprocessed esters from aviation pathways. Cargo carriers at Addis Ababa and Nairobi exhibit highest price sensitivity due to thin operating margins on African trade lanes, while Emirates and Etihad leverage volume scale for least-sensitive procurement.
Supply Chain Analysis
Just-in-time inventory strategies dominate at Dubai and Abu Dhabi with direct pipeline-to-wing delivery, while East African hubs maintain strategic stockpiles against 72-hour road tanker lead times from coastal terminals. Supply concentrates in the United Arab Emirates, Saudi Arabia, and South Africa as certified terminal infrastructure. Raw material dependencies include Brent crude feedstock, hydroprocessed ester and fatty acid renewable inputs, and static dissipater additive packages. Single-source vulnerability runs through the Strait of Hormuz chokepoint for Gulf refining complexes. Distribution runs through integrated refinery-terminal pipelines at hub airports, with road tanker bridging for secondary African markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from pandemic-induced demand collapse as long-haul network expansion and cargo fleet proliferation restore uplift volumes across Gulf and African corridors.
For Market Incumbents: Compound terminal infrastructure advantage by extending certified storage and laboratory capacity into Nairobi and Addis Ababa before competitor co-processing retrofits mature. Deepen backward integration into renewable feedstock sourcing to secure hydroprocessed ester supply against marine biofuel competition. Prioritize multi-year offtake lock-in with Ethiopian Airlines Cargo and Kenya Airways freight divisions as cargo carriers consolidate procurement. For New Entrants and Emerging Players: Differentiate on modular co-processing skid deployment for sustainable aviation fuel production at secondary African airports excluded from Gulf hub certification. Target quality testing services as the most penetrable segment, where ASTM D1655 laboratory scarcity at sub-Saharan terminals creates margin pools. Pursue partnership-based go-to-market with East African civil aviation authorities seeking to adopt international fuel surveillance standards. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated refinery-terminal operators with pipeline infrastructure and long-term carrier contracts. Five-to-ten year viability favors suppliers with co-processing retrofit readiness for impending Gulf sustainable aviation fuel mandates. Acquisition focus should center on African terminal operators with certified storage expansion permits. The signal to watch is CORSIA compliance deadline acceleration forcing emissions intensity documentation and certified sustainable aviation fuel blend procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Co-Processing Retrofit Investment | Enables renewable feedstock handling alongside fossil kerosene without disrupting Jet A-1 supply chains at Gulf refineries. |
| East African Terminal Certification | Captures cargo hub development at Addis Ababa and Nairobi with ASTM D1655 laboratory infrastructure investment. |
| Long-Term Offtake Agreement | Locks Ethiopian Airlines Cargo and Kenya Airways freight demand into multi-year supply continuity contracts. |
| Digital Batch Traceability Platform | Deploys blockchain certification from refinery discharge to wing-tip delivery for multi-leg international flights. |
| Renewable Feedstock Supply Partnership | Secures hydroprocessed ester and fatty acid allocation against competing marine biofuel and renewable diesel offtake. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with airline fuel procurement managers, refinery operations directors, into-plane service providers, civil aviation authority certification officers, and cargo carrier fleet planners. Secondary validation drew from IATA fuel reports, ICAO CORSIA documentation, national standards body publications, customs and trade flow data, and airport authority infrastructure disclosures. Bottom-up triangulation across carrier uplift volumes and top-down reconciliation against refinery throughput data anchored market sizing.
Across the analysis window, forecasts employed segmented modeling by fuel type, end user archetype, distribution channel, and service tier. CAGRs were derived from trend extrapolation of uplift volumes against fleet deployment schedules and route expansion announcements. Jet A-1 versus Jet A substitution patterns, sustainable aviation fuel blend mandate trajectories, and East African cargo hub development timelines fed scenario-weighted projections.
Forecasts assume regulatory continuity in UAE General Civil Aviation Authority, Saudi Standards Metrology and Quality Organization, and South African Civil Aviation Authority surveillance regimes; material policy shifts would require re-modeling. Crude price volatility, CORSIA implementation acceleration, and renewable feedstock competition present specific revision triggers. Revision becomes warranted when sustainable aviation fuel batch availability crosses thresholds that disrupt existing procurement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Coal Trading Market
Fuels
Palm Methyl Ester Market
Fuels
Europe Wood Pellet Market
Fuels
Canada Coal Market
Fuels
India Bunker Fuel Market
Fuels
China LNG Market
Fuels
Turbine Drip Oil Market
Fuels
Italy Automotive Engine Oils Market
Fuels
Brazil LNG Market
Fuels
North America Commercial Aircraft Aviation Fuel Market
Fuels
Global Turbine Oil Market
Fuels
Diesel Fuel Market
Fuels
Global Methane Hydrate Market
Fuels
Renewable Fuel Quality and Regulatory Compliance Test Instruments Market
Fuels
Chafing Fuel Market
Fuels
Alcohol-To-Jet (ATJ) Fuel Market