
 Europe Compressed Natural Gas Dispenser Market | 2026-2036
Europe Compressed Natural Gas Dispenser Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Compressed Natural Gas Dispenser Market Insights
Modular dispenser configurations is expanding buyer choice across Europe as station operators mix light-duty and heavy-duty dispensing units within single installations. Gilbarco Inc leverages its fueling heritage to anchor positions in electronic dispenser technology across Southern Europe. Tatsuno Europe AS specializes in advanced control systems for high-throughput fleet applications. Dover Corporation extends its industrial automation expertise into payment-integrated CNG dispensers for unmanned stations.
A compressed natural gas dispenser is a pressurized fueling terminal engineered to deliver methane-based fuel at operating pressures up to 250 bar through calibrated flow meters and safety interlocks, serving commercial and public transport vehicles requiring gaseous fuel alternatives. Fast-fill systems dominate margin pools where commercial fleets prioritize vehicle uptime, while time-fill systems sustain steady demand from depot-based municipal bus operators running overnight refueling cycles. Electronic dispensers with integrated payment modules are displacing mechanical units as station automation becomes standard across European markets.
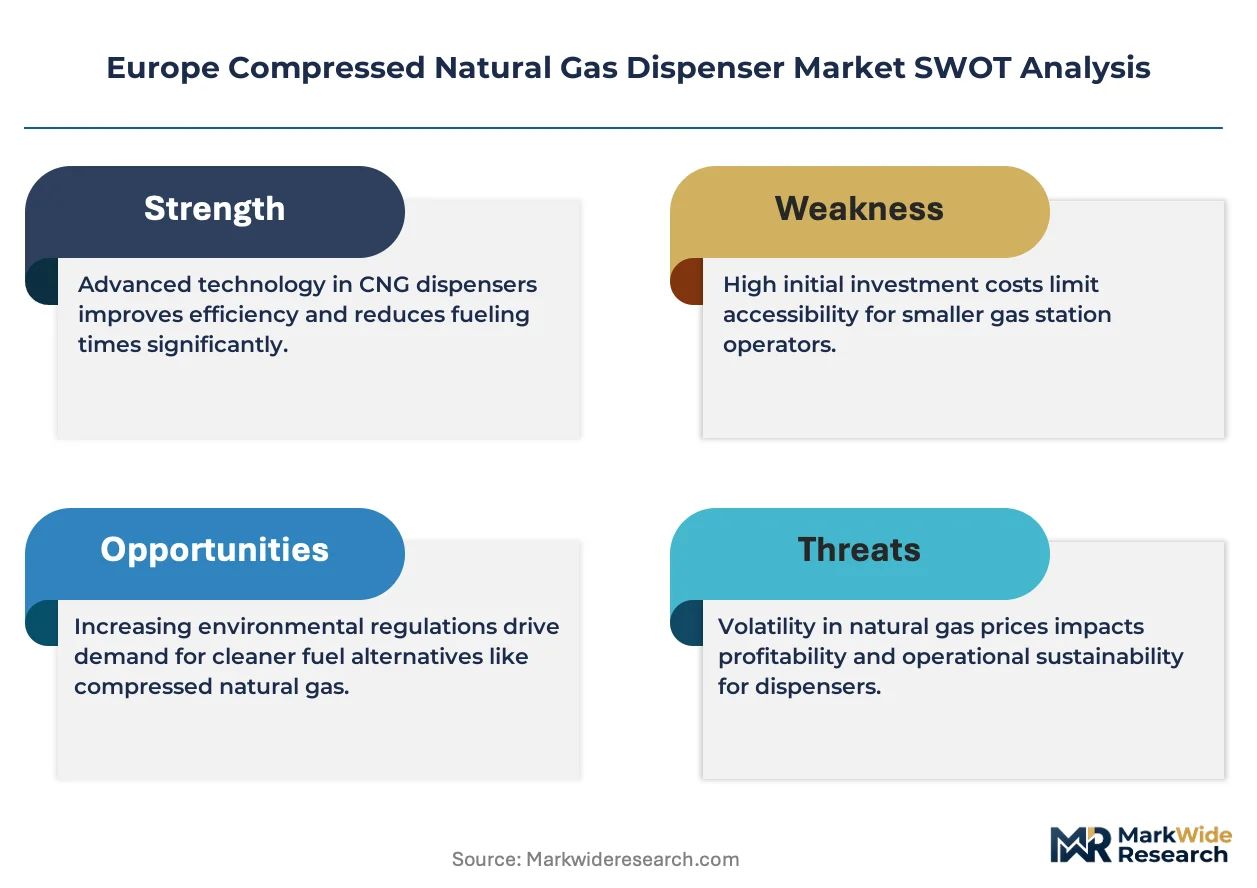
The EU Green Deal and F-Gas Regulation shape product standards by mandating leak-tight performance and compatible materials for methane handling equipment, while CE marking requirements govern market access for dispenser manufacturers selling into member states. ECHA oversight of material compliance adds testing burdens for seals and gaskets in pressurized fueling environments. Stakeholders must monitor evolving EU taxonomy criteria for clean transport infrastructure to anticipate which installation types qualify for green financing instruments.
Market Dynamics
The EU Green Deal mandates are compressing fleet operator decision timelines, forcing municipal transport authorities across Germany, Poland, and Italy to accelerate CNG infrastructure deployment ahead of diesel phase-out deadlines.
Growth Catalysts
- EU Green Deal fleet mandates:Binding decarbonization targets for public transport are compelling municipal operators in Germany and Poland to convert bus fleets and install dedicated refueling infrastructure.
- Fast-fill technology maturation:High-pressure dispensing systems now achieve 250 bar fills in under five minutes, meeting commercial logistics requirements for rapid vehicle turnaround on trans-European corridors.
- France and Italy logistics corridor concentration:Dense freight traffic along Alpine and Mediterranean routes is creating localized demand clusters that justify high-throughput station investments.
Market Restraints
- Stainless steel and high-grade alloy input volatility:Pressurized vessel construction depends on specialty metals subject to energy-intensive production costs and supply concentration in select European mills.
- CE marking compliance timeline:Extended certification cycles for methane-handling equipment under Pressure Equipment Directive create market access friction for non-EU component suppliers.
- Electric drivetrain substitution threat:Battery-electric bus procurement is accelerating in Nordic markets and Dutch urban centers, diverting infrastructure capital from CNG alternatives.
Strategic Opportunities
- Underpenetrated Eastern European municipal fleets:Romanian and Bulgarian public transport operators lag Western counterparts in alternative fuel adoption, presenting first-mover installation contracts.
- EU taxonomy green financing eligibility:Clean transport infrastructure classification under sustainable finance frameworks unlocks preferential lending terms for station developers.
- Payment-integrated unmanned station models:Automated dispensing with contactless transaction systems reduces labor costs and extends service hours for commercial fleet customers.
Industry Challenges
- High-pressure systems engineering talent scarcity:Specialized expertise in 250 bar methane containment and flow calibration is concentrated among aging workforce cohorts in German and Italian industrial clusters.
- ECHA material compliance documentation burden:Extended safety data sheet requirements for seals and gaskets in pressurized fueling environments delay component sourcing and assembly timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Compressed Natural Gas Dispenser Market |
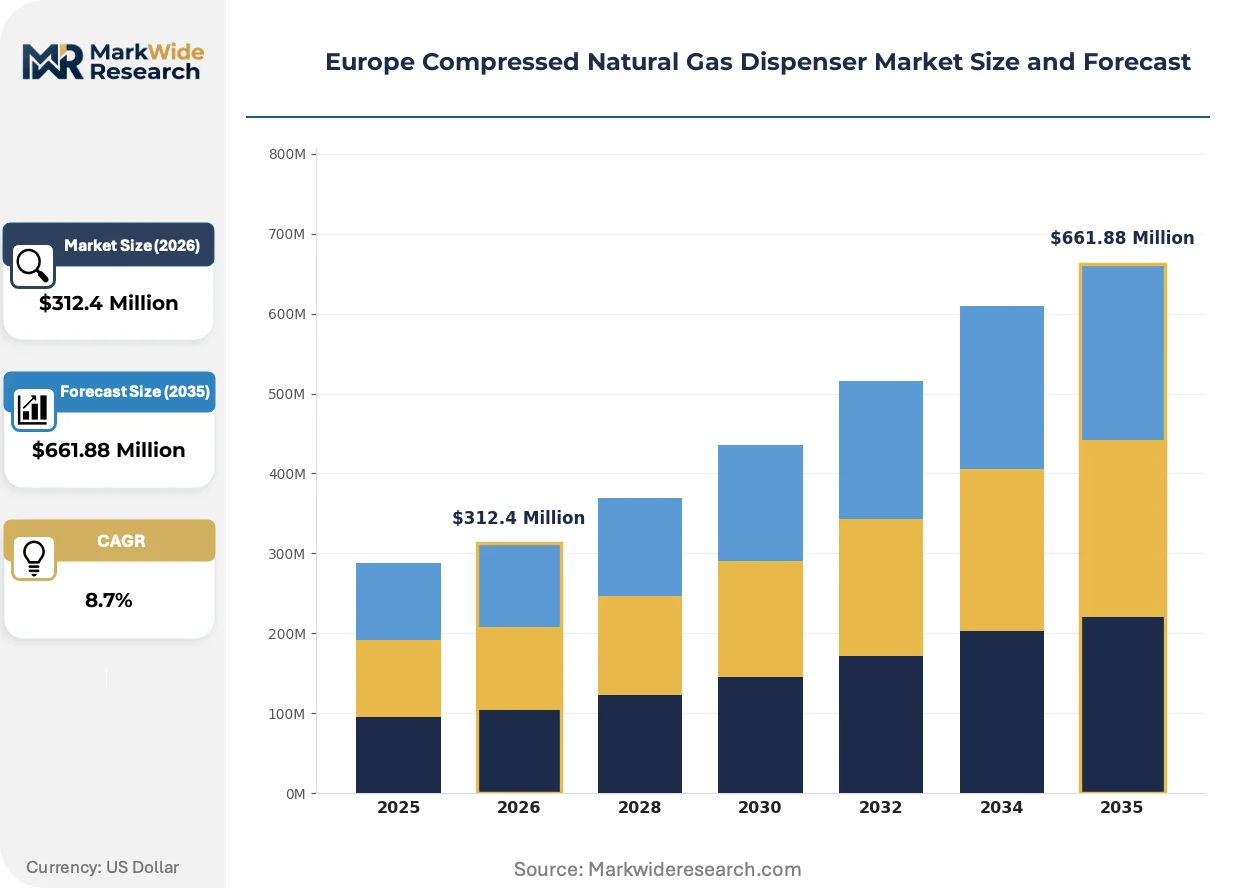
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light-Duty Dispensers, Heavy-Duty Dispensers, Time-Fill Systems, Fast-Fill Systems End User: Public Transport, Commercial Fleets, Industrial Users, Private Users Technology: Mechanical Dispensers, Electronic Dispensers, Advanced Control Systems, Payment Integration Installation: On-Site Installations, Retrofitting Existing Stations, New Station Development, Mobile Dispenser Units |
| Companies Covered | Cetil Dispensing Technology S.L, FTI Group Ltd, Gilbarco Inc, Dover Corporation, Wayne Fueling Systems LLC, Tatsuno Europe AS, Sherex Europe ApS, ANGI Energy Systems Inc, Parker Hannifin Corp, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Compressed Natural Gas Dispenser Market Trends and Innovations
Dispenser architecture is converging around modular platforms that accommodate mixed fleet profiles, while regulatory pressure on methane leakage is driving material science advances in sealing systems.
Electronic payment-integrated dispenser platforms are unifying transaction processing, flow metering, and remote diagnostics within single terminal architectures. Fleet operators in France and Italy are adopting these systems at accelerated rates to minimize station staffing costs. This convergence is compressing the competitive window for mechanical-only dispenser suppliers across Southern European markets.
The EU F-Gas Regulation and complementary ECHA oversight are tightening material specifications for methane-compatible seals and gaskets in pressurized environments. Industrial consequence includes mandatory third-party testing protocols that extend product development cycles by six to nine months for new dispenser launches. Italian and German manufacturers with established ECHA documentation libraries are capturing disproportionate share of municipal tender awards.
Service contract unbundling is altering procurement patterns among commercial fleet operators who now separate hardware acquisition from maintenance agreements. Traditional bundled suppliers face margin compression as independent service providers enter aftermarket segments. This pattern is most visible in German long-haul logistics corridors where fleet managers prioritize uptime guarantees over manufacturer-locked service terms.
Europe Compressed Natural Gas Dispenser Market Segmentation
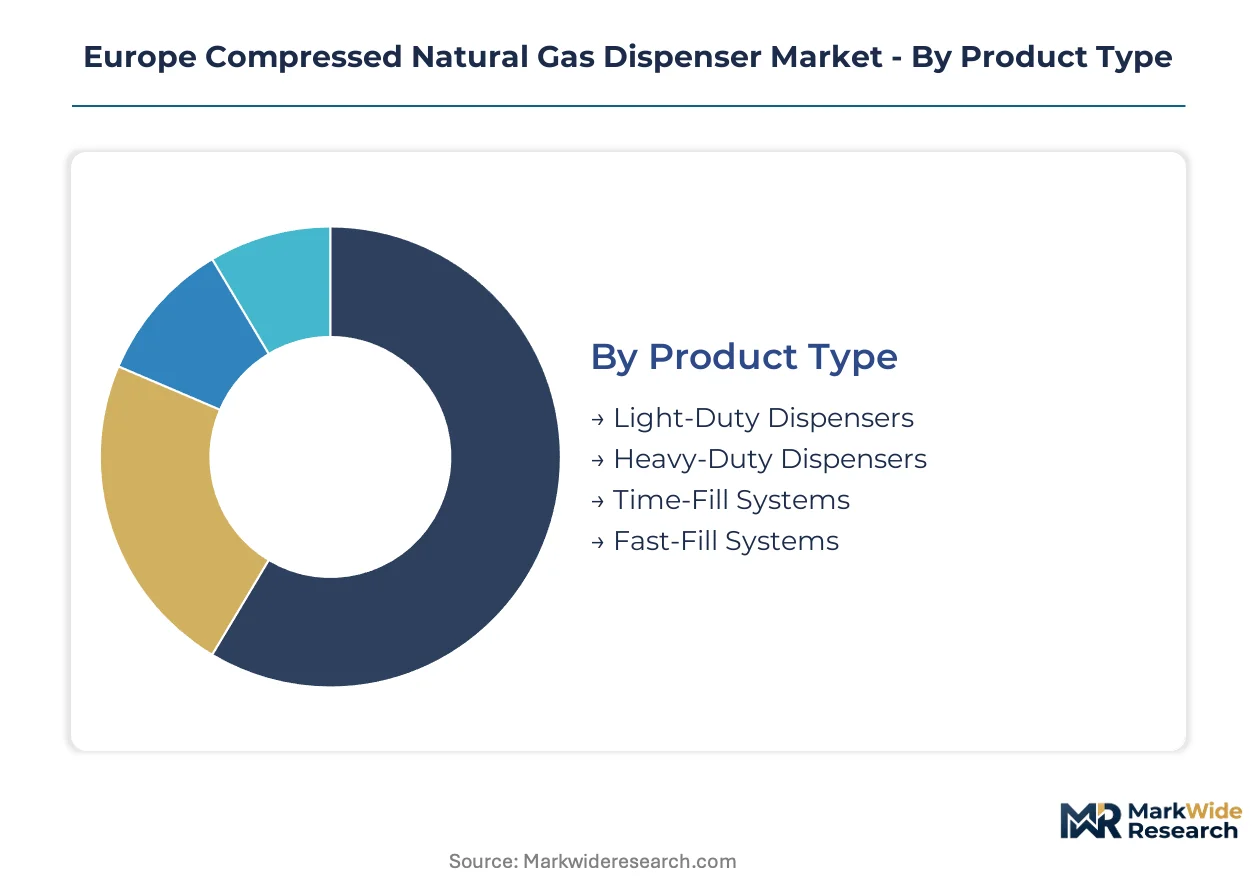
Dispenser configurations vary sharply in capital requirements and operational complexity across European markets. Fleet operators weigh upfront station investment against vehicle turnaround economics when selecting system architectures. Municipal procurement patterns diverge from commercial logistics priorities, creating distinct segment performance profiles.
Product Type:
Capital intensity escalates with pressure ratings and throughput capacity, separating depot-scale infrastructure from corridor refueling networks.
- Light-Duty Dispensers:Lower-pressure systems rated for passenger vehicles and small commercial vans require modest compressor investments. German municipal fleets deploy these units for mixed-service stations serving both transit buses and municipal pool vehicles.
- Heavy-Duty Dispensers:High-flow architectures engineered for 250 bar delivery to articulated buses and long-haul trucks demand substantial compressor and storage vessel outlays. French logistics operators along the A6 motorway corridor prioritize these configurations for rapid tractor-trailer refueling.
- Time-Fill Systems:Overnight depot refueling via slow-fill posts eliminates high-pressure compressor cycling. Polish bus operators favor this approach for dedicated fleet yards with predictable dwell times.
- Fast-Fill Systems:Cascade storage and priority panels enable sub-five-minute fills. Italian commercial fleet tenders increasingly specify these units for intermodal freight terminals.
Heavy-duty dispensers absorb the bulk of installed capacity; fast-fill systems are expanding most quickly.
End User:
Customer procurement sophistication ranges from regulated public tenders to negotiated fleet service agreements, reshaping vendor engagement models.
- Public Transport:Municipal authorities operate under EU Green Deal procurement mandates with extended payback horizons. German Verkehrsverbünde and Polish municipal transport companies anchor demand for depot-based time-fill infrastructure.
- Commercial Fleets:Logistics operators prioritize total cost of ownership metrics and uptime guarantees. French retail distribution fleets and Italian cold-chain operators drive fast-fill corridor station development.
- Industrial Users:Manufacturing facilities with captive vehicle fleets and process heat requirements integrate CNG dispensers into on-site energy systems. Chemical plants in the Rhine-Ruhr cluster represent concentrated demand pockets.
- Private Users:Individual vehicle owners access public retail networks with limited price elasticity. This segment remains marginal outside Italy's established biomethane retail infrastructure.
Public transport commands the largest committed capital pipeline; commercial fleets show the steepest expansion trajectory.
Technology:
Automation intensity separates legacy mechanical platforms from integrated digital architectures, with compliance burdens favoring established European suppliers.
- Mechanical Dispensers:Analog flow metering and manual valve control persist in legacy installations. Eastern European markets with limited payment integration requirements retain modest demand for these units.
- Electronic Dispensers:Microprocessor-controlled flow calibration and automated safety interlocks dominate new installations. CE marking requirements under the Pressure Equipment Directive accelerate displacement of mechanical alternatives.
- Advanced Control Systems:Real-time pressure monitoring and predictive maintenance algorithms reduce unplanned downtime. High-throughput fleet applications in the Netherlands and Belgium specify these capabilities in tender documents.
- Payment Integration:Contactless transaction processing and remote diagnostic connectivity enable unmanned station operation. Unattended corridor stations across France and Spain incorporate these modules as standard.
Electronic dispensers account for the majority of current shipments; payment-integrated variants are climbing the fastest.
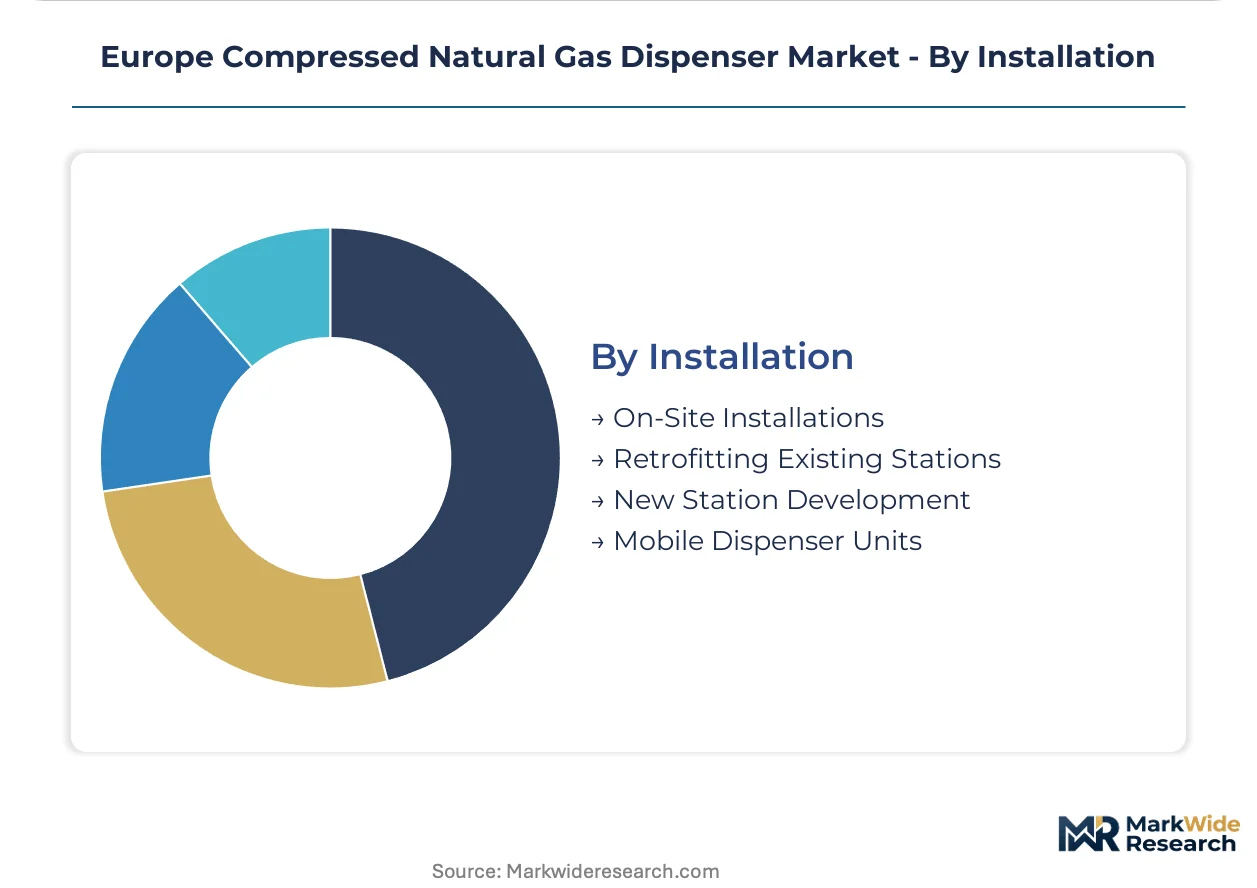
Installation:
Project delivery modes range from greenfield development with full regulatory burden to retrofit deployments leveraging existing permitting and grid connections.
- On-Site Installations:Purpose-built infrastructure at fleet depots or industrial facilities with dedicated compressor installations. German municipal bus depots in Berlin and Munich exemplify this approach.
- Retrofitting Existing Stations:Conversion of diesel or gasoline retail sites to dual-fuel capability. Italian motorway service operators retrofit Autostrade per l'Italia locations to add CNG islands alongside conventional pumps.
- New Station Development:Greenfield construction on trans-European transport corridors with coordinated grid and permitting processes. Priority routes under the EU Alternative Fuels Infrastructure Regulation attract this investment category.
- Mobile Dispenser Units:Containerized systems for temporary fleet deployment or emergency fueling services. Construction and mining operations in Romania utilize these for remote site vehicle supply.
Retrofitting existing stations captures the dominant share of near-term project volume; new station development is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of CNG dispenser systems concentrates in German and Italian industrial clusters, while consumption spreads across municipal fleet operators from Warsaw to Madrid. This geographic split shapes vendor logistics and service network requirements.
Germany
Municipal transport authorities in Berlin and Munich are converting bus depots to time-fill CNG infrastructure under binding EU Green Deal fleet mandates. The KBA enforces stringent type-approval standards for pressurized fueling equipment entering commercial service. Industrial fabricators in North Rhine-Westphalia supply heavy-duty dispenser systems to Verkehrsverbünde across the country.
Italy
Commercial logistics operators along the A1 and A14 motorway corridors demand fast-fill configurations for rapid tractor-trailer turnaround. The F-Gas Regulation drives material specification upgrades for methane-compatible seals in dispenser manufacturing. Lombardy-based equipment specialists serve cold-chain distribution fleets concentrated around Milan's intermodal freight terminals.
France
Retail distribution fleets and postal operators prioritize payment-integrated unmanned stations to minimize labor costs on trans-European routes. CE marking requirements under the Pressure Equipment Directive govern market access for all dispenser installations. Auvergne-Rhône-Alpes hosts manufacturing operations supplying corridor refueling infrastructure along Alpine logistics axes.
Poland
Municipal bus operators in Warsaw and Kraków favor depot-based time-fill systems with predictable overnight dwell cycles. National fleet decarbonization programs channel public investment into dedicated CNG refueling yards. Silesian industrial zones support component fabrication for dispenser assemblies serving Eastern European markets.
Netherlands
Advanced control systems with predictive maintenance capabilities attract procurement specifications from high-throughput fleet operators in Rotterdam's port logistics zone. ECHA oversight of material compliance documentation extends sourcing timelines for seals and gaskets. Randstad urban transit authorities evaluate mixed-fuel station architectures for regional bus networks.
Europe Compressed Natural Gas Dispenser Market Competitive Landscape
The competitive structure tilts toward established industrial automation and fueling heritage players with proven ECHA documentation libraries. Vendor differentiation rests on CE marking compliance speed, payment integration capabilities, and aftermarket service network density. Two strategic archetypes dominate: diversified industrial conglomerates leveraging cross-sector automation expertise, and specialized fueling equipment fabricators with deep pressure-system engineering heritage. Capacity expansion and strategic partnerships constitute the primary competitive moves, as players position for municipal tender awards and corridor station development contracts.
Among diversified industrial conglomerates, Dover Corporation and Parker Hannifin Corp occupy positions anchored by broad automation and fluid systems portfolios. Gilbarco Inc and Tatsuno Europe AS exemplify the fueling heritage archetype, drawing on decades of petroleum dispensing expertise translated into pressurized methane applications. These four entities collectively represent the competitive core, with specialized European fabricators such as Cetil Dispensing Technology S.L and FTI Group Ltd occupying niche positions in regional tender markets.
| Leading Market Players |
|---|
| Cetil Dispensing Technology S.L |
| FTI Group Ltd |
| Gilbarco Inc |
| Dover Corporation |
| Wayne Fueling Systems LLC |
| Tatsuno Europe AS |
| Sherex Europe ApS |
| ANGI Energy Systems Inc |
| Parker Hannifin Corp |
| Others |
Pricing and Supply Chain Analysis
Captive integration of high-pressure vessel fabrication into German and Italian manufacturing clusters anchors both supply security and pricing power for established dispenser suppliers serving EU Green Deal infrastructure tenders. This vertical control over specialty alloy processing and ECHA-compliant seal assembly insulates incumbents from commodity volatility while compressing margins for non-integrated competitors bidding on municipal contracts.
Pricing Analysis
Margin tightening in electronic dispenser tiers reflects CE marking compliance burdens and extended certification timelines under the Pressure Equipment Directive. Three-tier pricing structure across premium, standard, and economy levels separates payment-integrated unmanned stations from mechanical legacy units, with certification grade and after-sales service bundling as primary differentiation drivers. Cost compression accelerates in standard tiers as Polish and Romanian municipal buyers consolidate procurement through framework agreements. Commercial fleet operators in France and Italy exhibit lowest price sensitivity, prioritizing uptime guarantees over unit economics.
Supply Chain Analysis
Dual-sourcing mandates from German Verkehrsverbünde and French logistics operators require qualified suppliers for both cascade storage vessels and control system electronics. Manufacturing concentrates in Germany, Italy, and Poland, with specialty stainless steel and high-grade alloys drawing from North Rhine-Westphalia and Lombardy mills. Single-source vulnerability persists for ECHA-documented methane-compatible seals, where Italian and German fabricators maintain proprietary formulation libraries. Distribution runs through direct OEM channels for large fleet deployments and specialized industrial distributors for retrofit station projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as CE marking compliance timelines and ECHA documentation burdens force smaller fabricators into acquisition or exit. Regulatory friction advantages scaled suppliers with established certification libraries.
For Market Incumbents: Deepen backward integration into specialty alloy processing and ECHA-compliant seal manufacturing to defend margin position against emerging Asian component suppliers. Prioritize capacity addition in Poland and Romania to capture Eastern European municipal tender awards before local fabrication capacity matures. Certification investment in advanced control systems with predictive maintenance capabilities secures differentiation in Dutch and Belgian high-throughput specifications. For New Entrants and Emerging Players: Fleet service operators represent the most accessible channel partner type for market entry without legacy ECHA documentation burdens. Underpenetrated Romanian and Bulgarian municipal bus fleets offer white-space installation contracts with less stringent incumbent lock-in. Mobile dispenser units for construction and mining operations provide a go-to-market angle with lower certification barriers and faster revenue conversion. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial conglomerates seeking fueling infrastructure exposure. Long-term viability hinges on positioning within EU taxonomy-eligible clean transport financing flows. Acquisition target archetype: Italian or German mid-cap fabricators with complete ECHA documentation libraries and established municipal tender relationships. Watch battery-electric bus procurement acceleration in Nordic markets as inflection signal for CNG infrastructure investment trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Acceleration Program | Compresses certification timelines for Pressure Equipment Directive compliance in German municipal tenders. |
| Payment-Integrated Platform Launch | Unmanned station capability captures French logistics operator specifications for Alpine corridor deployment. |
| Eastern European Manufacturing Footprint | Polish and Romanian assembly capacity reduces delivery costs for underpenetrated municipal fleet markets. |
| ECHA Documentation Library Acquisition | Proprietary seal and gasket compliance records accelerate tender qualification against non-integrated competitors. |
| Predictive Maintenance Algorithm Development | Advanced control systems meet Dutch port logistics operator uptime guarantee requirements in Rotterdam zone. |
Research Methodology
Independent corroboration across fleet procurement directors, station engineering consultants, and ECHA regulatory specialists underwrites the qualitative findings in this study. Primary interviews with municipal transport authority technical leads, commercial logistics fleet managers, and dispenser OEM product strategists combined with secondary validation from EU Alternative Fuels Infrastructure Regulation filings, KBA type-approval databases, and national fleet decarbonization program disclosures. Bottom-up installation volume triangulation against top-down infrastructure investment flows anchored market sizing.
Comparable-period anchoring to historical CNG station commissioning data across the analysis window established baseline trajectory assumptions. Segmentation modeling incorporated dispenser pressure rating, fleet application type, automation tier, and installation mode dimensions. CAGRs derived from logistic diffusion curves fitted to municipal procurement cycle patterns and commercial fleet turnover timelines. Forecast inputs included EU Green Deal mandate enforcement schedules and battery-electric substitution elasticity parameters by member state.
Caveats apply where electric drivetrain substitution acceleration or ECHA material specification revisions could materially shift the outlook. Deviation in EU taxonomy clean transport infrastructure classification criteria would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
South America Commercial Aircraft Aviation Fuel Market
Fuels
Europe Renewable Aviation Fuel Market
Fuels
UAE Chemical Logistics Market
Fuels
Hydrogen Cylinder Market
Fuels
Ethyl Tertiary Butyl Ether Market
Fuels
Asia-Pacific Bunker Fuel Market
Fuels
United Kingdom Bunker Fuel Market
Fuels
Gas to Liquid (GTL) Market
Fuels
Biobutanol Market
Fuels
Smart Gas Market
Fuels
Compressed Natural Gas (CNG) Dispenser Market
Fuels
Europe Firewood Market
Fuels
High-Temperature Industrial Burner Market
Fuels
Global Butane Gas Cartridges Market
Fuels
Wood Charcoal Market
Fuels
Saudi Arabia Chemical Logistics Market