
 South Africa Bunker Fuel Market | 2026-2036
South Africa Bunker Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Bunker Fuel Market Insights
A shift from single-source refinery supply toward multi-source import blending is restructuring procurement patterns across South African ports. BP Southern Africa leverages its downstream terminal network to sustain coastal coverage from Durban to Cape Town. Engen Petroleum anchors inland logistics corridors that feed bunkering operations at Richards Bay. Vivo Energy competes through retail-to-marine distribution bridges that reduce port congestion delays.
Bunker fuel denotes residual and distillate petroleum products burned in marine propulsion and auxiliary engines, with sulfur content specifications governed by IMO 2020 caps at 0.50% mass fraction for conventional fuels outside emission control areas. Its primary commercial purpose is to power commercial vessels on international and coastal trade routes. Heavy fuel oil still dominates volume throughput at South African terminals, though low sulfur fuel oil captures expanding margin pools as vessel operators phase out high-sulfur residual burning. Marine gas oil grows fastest among refined distillates, particularly for fishing fleet operators and offshore supply vessels facing tighter port-state inspections.
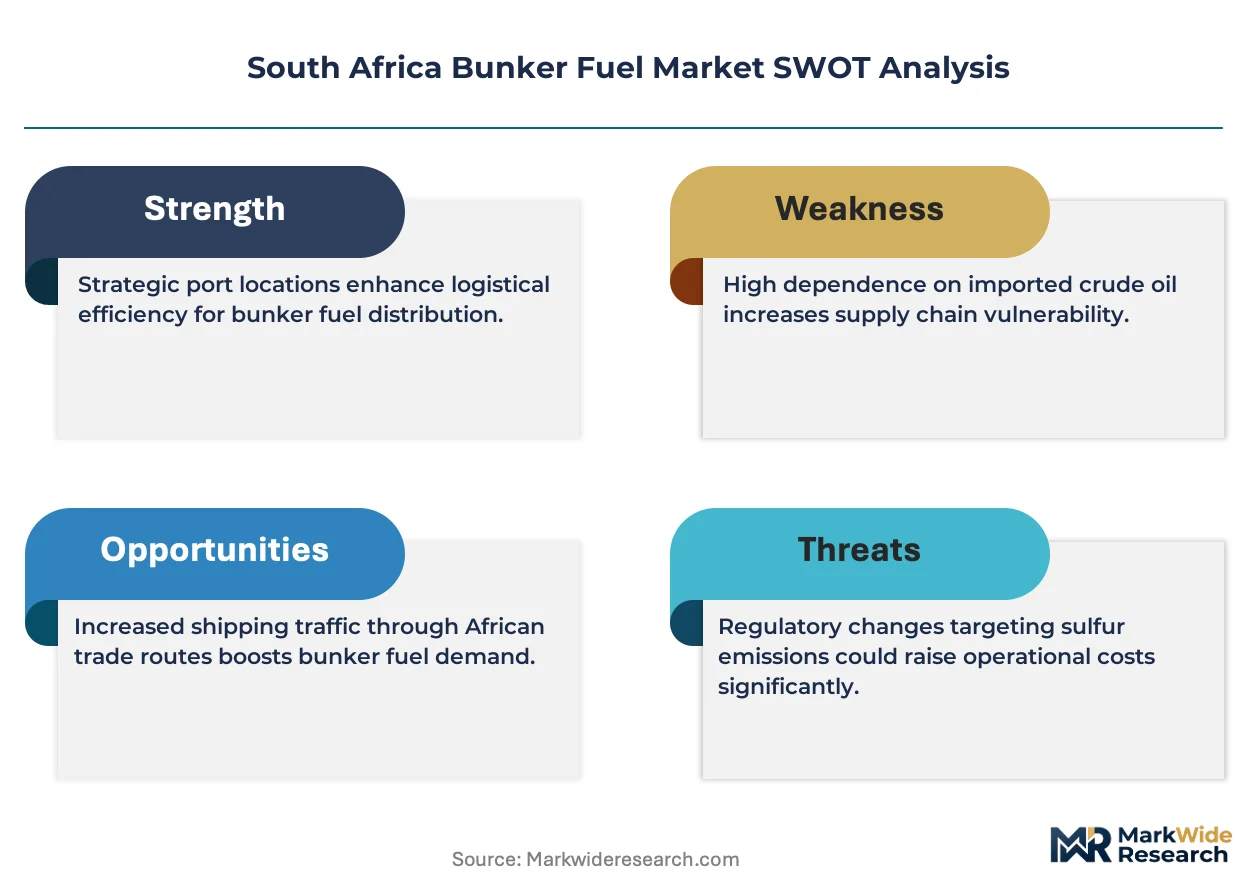
South Africa's bunkering sector operates under the Petroleum Products Act administered by the Department of Mineral Resources and Energy, with additional environmental oversight from the South African Maritime Safety Authority aligning with MARPOL Annex VI protocols. The IMO sulfur regulations and forthcoming EU carbon border adjustments on maritime trade will reshape fuel quality requirements and supplier certification burdens. Stakeholders must monitor refinery upgrade timelines at Sapref and Engen Durban to assess domestic low-sulfur production capacity against rising import dependency for compliant blends.
Market Dynamics
The transition from high-sulfur residual fuels to IMO 2020-compliant low-sulfur blends is compressing refinery margins and forcing procurement networks toward multi-source import dependency. This structural shift reconfigures supplier relationships across Durban, Cape Town, and Richards Bay corridors.
Growth Catalysts
- IMO 2020 Sulfur Cap:The International Maritime Organization's 0.50% mass fraction limit on conventional fuels outside emission control areas mandates vessel operators to source compliant bunker blends. This regulatory pressure sustains demand for low sulfur fuel oil and marine gas oil at South African terminals.
- Deep-Sea Container Traffic:Container shipping lines operating through Durban and Cape Town anchor procurement volumes for residual and distillate marine fuels. Their scheduled port calls create predictable offtake patterns that stabilize supplier throughput.
- Offshore Supply Vessel Expansion:Marine gas oil consumption accelerates among fishing fleet operators and offshore support vessels facing tighter port-state inspections under South African Maritime Safety Authority protocols.
Market Restraints
- Refinery Capacity Concentration:Domestic low-sulfur production depends on upgrade timelines at Sapref and Engen Durban facilities, creating supply vulnerability during maintenance cycles or unplanned outages.
- Crude Import Dependency:South Africa lacks indigenous crude reserves sufficient for refined product self-sufficiency, exposing bunker blend costs to Brent-linked volatility and rand-dollar exchange rate fluctuations.
- Technical Blending Constraints:Achieving stable 0.50% sulfur fuel oil requires precise cutter stock ratios and additive packages that not all coastal storage terminals can consistently deliver.
Strategic Opportunities
- Western Cape Bunkering Hub:Cape Town's container terminal expansion and cruise ship traffic growth create underpenetrated demand for marine gas oil and distillate blends outside the Durban corridor.
- Biofuel Blend Pilots:Fatty acid methyl ester and hydrotreated vegetable oil trials for marine applications align with forthcoming EU carbon border adjustments on maritime trade calling at European ports.
- Digital Bunker Delivery:Blockchain-verified mass flow metering and automated berth scheduling reduce port congestion delays and inspection disputes at Richards Bay.
Industry Challenges
- Marine Chemist Certification Bottleneck:Qualified fuel testing personnel scarcity slows bunker delivery clearance times, particularly for vessels requiring MARPOL Annex VI compliance documentation.
- Storage Terminal Retrofit Costs:Converting existing heavy fuel oil tanks for low-sulfur product segregation demands capital expenditure that independent terminal operators struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Bunker Fuel Market |
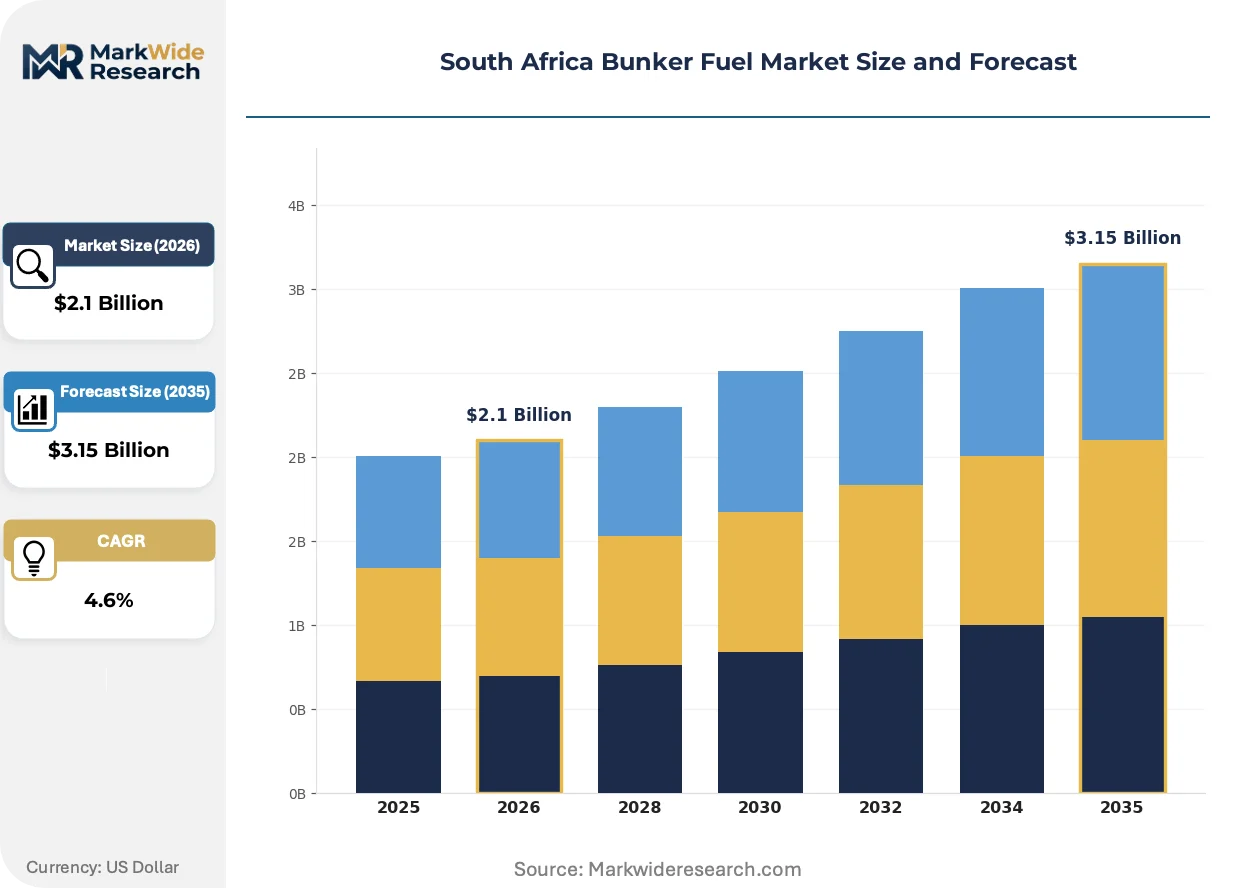
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy Fuel Oil, Marine Gas Oil, Low Sulfur Fuel Oil, Others End User: Shipping Lines, Offshore Vessels, Fishing Fleet, Naval Ships Distribution Channel: Direct Supply, Bunker Barges, Terminals, Brokers Application: Commercial Shipping, Fishing Operations, Naval Operations, Recreational Boating |
| Companies Covered | Linsen Nambi Bunker Services (Pty) Ltd, BP PLC (BP Southern Africa Pty Ltd), Ocean South Petroleum RSA (Pty) Ltd, Engen Petroleum Ltd, Africa Bunkering and Shipping (Pty) Ltd, Vivo Energy, Monjasa, Minerva Bunkering, Dan-Bunkering, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Bunker Fuel Market Trends and Innovations
Digital fuel verification systems and alternative marine propulsion trials are fragmenting traditional bunker procurement patterns. Supplier differentiation increasingly depends on traceability infrastructure rather than volume scale alone.
Mass flow metering technology is absorbing inspection and dispute-resolution functions previously handled by manual sampling and shore-side laboratory analysis. Container lines and bulk operators at Durban are adopting these systems to compress bunker delivery windows and reduce demurrage exposure. The technology is absorbing documentation burdens that previously delayed vessel sailing schedules.
South Africa's Petroleum Products Act administration by the Department of Mineral Resources and Energy is tightening environmental oversight alignment with MARPOL Annex VI protocols. This regulatory convergence elevates supplier certification burdens and mandates more frequent fuel quality reporting. Vessel operators calling at South African ports are responding by pre-qualifying bunker suppliers against stricter documentation standards.
Long-term supply agreements are displacing spot-market purchases among container shipping lines seeking price predictability amid volatile low-sulfur fuel oil differentials. This contracting pattern shift concentrates procurement leverage with fleet operators possessing credit depth and volume commitment scale. The behavioral change is most visible in Durban, where scheduled liner services dominate berth utilization patterns.
South Africa Bunker Fuel Market Segmentation
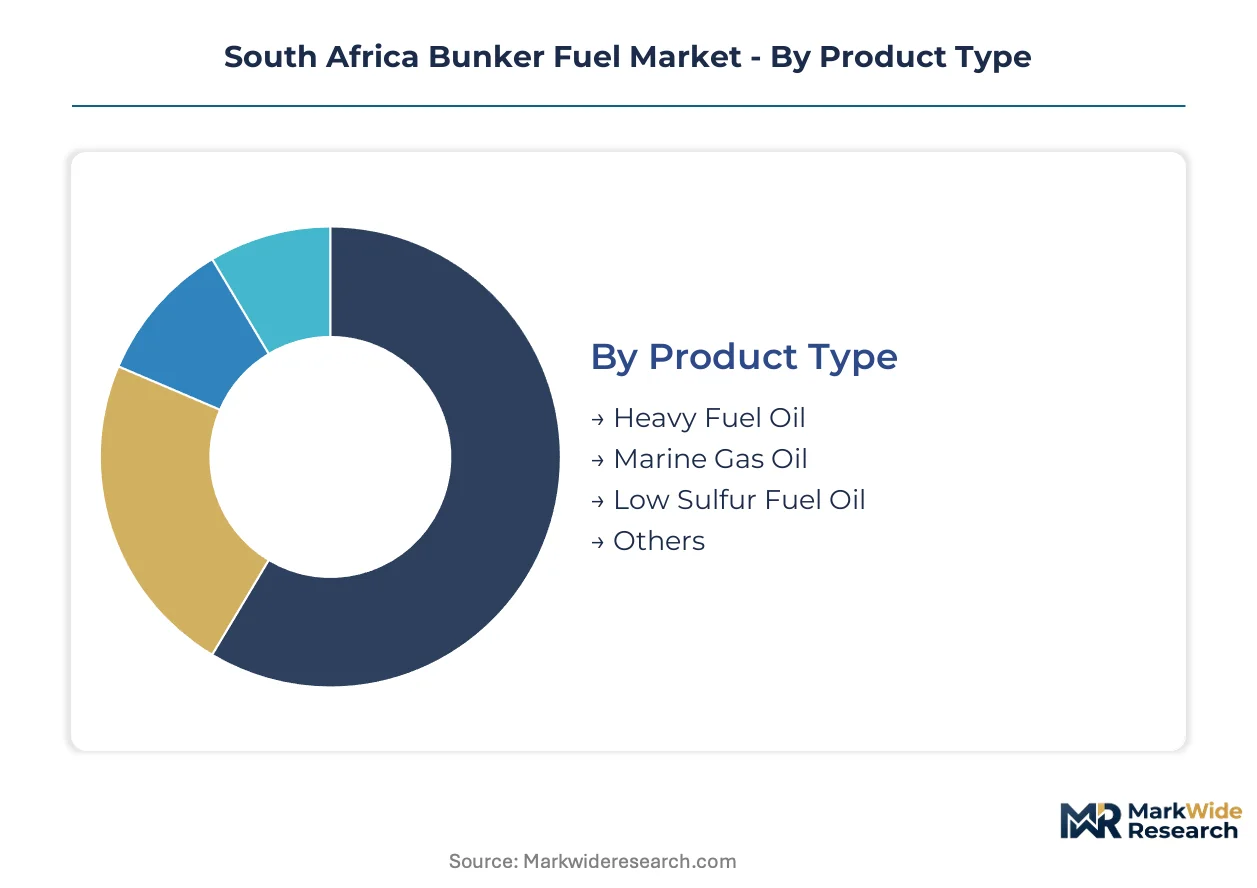
Segmentation in South Africa's bunker fuel market tracks the regulatory transition from high-sulfur residuals to compliant blends. Procurement patterns diverge sharply across vessel types and supply channels as refinery upgrades and import dependencies reshape availability.
Product Type:
Fuel specification upgrades are cycling through South African terminals as vessel operators replace legacy bunker stocks with IMO 2020-compliant alternatives. The replacement cycle favors products that blend easily with limited domestic cutter stock availability.
- Heavy Fuel Oil:Residual petroleum product with sulfur content historically above 3.50% mass fraction now restricted to vessels equipped with exhaust gas cleaning systems. Demand concentrates among bulk carriers and tankers calling at Durban with scrubber installations, though volumes contract as fleet operators decommission non-compliant vessels.
- Low Sulfur Fuel Oil:Blended residual-distillate mixture meeting the 0.50% sulfur cap through precise cutter stock ratios and additive packages. Procurement concentrates at the Port of Durban corridor where BP Southern Africa and Engen Petroleum maintain blending infrastructure for deep-sea container lines.
- Marine Gas Oil:Refined distillate fuel with inherently low sulfur content, favored by fishing fleet operators and offshore supply vessels facing stringent South African Maritime Safety Authority port-state inspections.
- Others:Emerging biofuel blends and liquefied natural gas bunkering trials at Richards Bay targeting European Union carbon border adjustment compliance.
Volume placements concentrate in Low Sulfur Fuel Oil; the faster expansion belongs to Marine Gas Oil.
End User:
Customer procurement scale determines supply channel access and pricing leverage across South African ports. Large fleet operators command dedicated barge schedules while fragmented users rely on broker-mediated spot purchases.
- Shipping Lines:Container and bulk operators with scheduled liner services at Durban and Cape Town anchor residual fuel procurement volumes through long-term supply agreements that displace spot-market purchases.
- Offshore Vessels:Supply boats and exploration support craft operating from Richards Bay drive marine gas oil demand for auxiliary engines and dynamic positioning systems.
- Fishing Fleet:Trawlers and long-line vessels along the Western Cape and KwaZulu-Natal coasts require distillate fuels for propulsion and on-board refrigeration, with consumption patterns tied to seasonal licensing windows.
- Naval Ships:South African Navy vessels operating from Simon's Town maintain dedicated fueling protocols through state procurement channels with distinct quality certification requirements.
Procurement scale favors Shipping Lines for residual fuels; Fishing Fleet generates the steepest expansion trajectory in distillate segments.
Distribution Channel:
Physical infrastructure constraints at congested berths are forcing channel selection toward modalities that compress delivery windows and reduce demurrage exposure.
- Direct Supply:Refinery-to-vessel deliveries from Sapref and Engen Durban facilities, limited by coastal tanker availability and jetty scheduling conflicts with crude import operations.
- Bunker Barges:Floating delivery vessels operating at anchorage outside Durban harbor, reducing berth congestion for container lines with tight sailing schedules.
- Terminals:Coastal storage facilities at Cape Town and Richards Bay offering segregated low-sulfur product tanks with mass flow metering infrastructure for dispute reduction.
- Brokers:Intermediary arrangements for spot purchasers lacking credit depth or volume commitment scale, absorbing price volatility risk in exchange for margin capture.
Cargo volumes concentrate through Bunker Barges; infrastructure investment is climbing fastest at Terminals with metering upgrades.
Application:
Operational intensity and regulatory scrutiny vary sharply across marine activity types, fragmenting fuel quality requirements and supplier certification burdens.
- Commercial Shipping:International container and bulk trade routes through Durban and Cape Town generate predictable offtake patterns that stabilize supplier throughput and justify storage terminal investments.
- Fishing Operations:Licensed fleet activity concentrated in Saldanha Bay and Gansbaai drives seasonal marine gas oil demand spikes aligned with squid and hake harvesting windows.
- Naval Operations:Military vessel fueling at Simon's Town Naval Base operates under defense procurement protocols with specialized security and quality traceability requirements.
- Recreational Boating:Yacht and pleasure craft marinas in Cape Town and Durban represent marginal volume but premium pricing for high-specification distillate products.
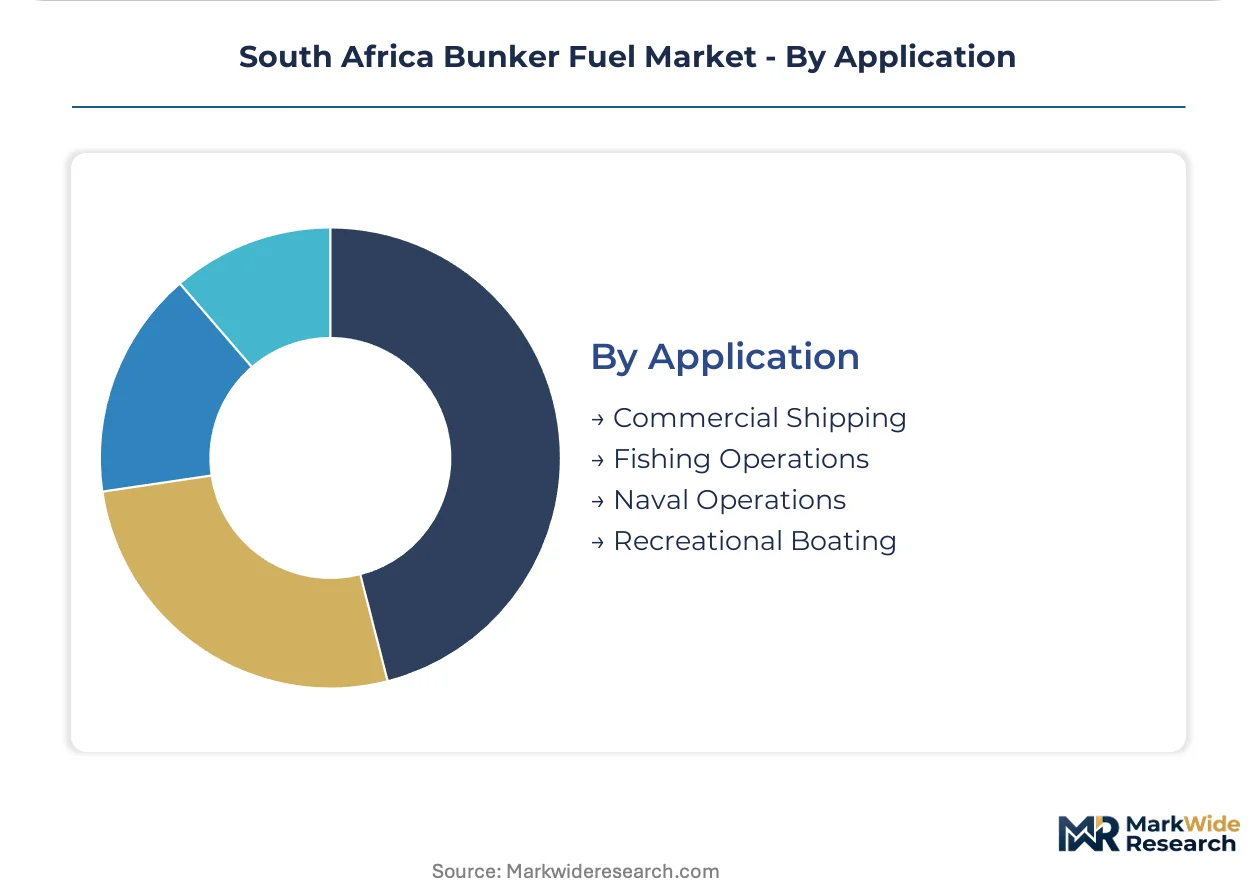
Commercial Shipping dominates volume placements; Fishing Operations are gaining share fastest on regulatory enforcement intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Crude import terminals at Durban and Cape Town anchor bunkering infrastructure along South Africa's coastline. The Petroleum Products Act administered by the Department of Mineral Resources and Energy governs fuel quality standards across port zones. Refinery upgrade timelines at Sapref and Engen Durban facilities determine domestic low-sulfur production capacity.
KwaZulu-Natal
Durban's container terminal expansion and scheduled liner services generate predictable heavy fuel oil and low sulfur fuel oil offtake. The South African Maritime Safety Authority enforces MARPOL Annex VI compliance documentation at this corridor. Engen Petroleum maintains blending infrastructure near the port to supply deep-sea shipping lines.
Western Cape
Cape Town's cruise ship traffic growth and container terminal operations create expanding marine gas oil demand outside the Durban corridor. The Department of Mineral Resources and Energy coordinates environmental oversight with port authorities for fuel quality reporting. BP Southern Africa leverages its downstream terminal network to sustain coastal coverage from this hub.
Richards Bay
Offshore supply vessels and fishing fleet operators drive marine gas oil consumption at this coal export terminal. The South African Maritime Safety Authority conducts port-state inspections that enforce distillate fuel standards for auxiliary engines. Storage terminals here offer segregated low-sulfur product tanks with mass flow metering infrastructure.
Eastern Cape
Coega Industrial Development Zone near Port Elizabeth attracts bunkering services for automotive export vessels. The Petroleum Products Act mandates fuel certification burdens that elevate supplier documentation standards. Limited refinery proximity forces this corridor toward multi-source import dependency for compliant blends.
South Africa Bunker Fuel Market Competitive Landscape
Capacity expansion dominates the current landscape as terminal operators retrofit heavy fuel oil tanks for low-sulfur product segregation. The supplier base clusters around integrated petroleum majors with downstream terminal networks and independent bunkering specialists with floating delivery capabilities. Two strategic archetypes prevail: refinery-anchored blenders controlling cutter stock access, and marine fuel traders aggregating multi-source supply. Competitive moves center on storage terminal metering upgrades and long-term supply agreements that displace spot-market purchases.
Among integrated petroleum majors, BP PLC and Engen Petroleum occupy positions exemplifying the refinery-anchored archetype with blending infrastructure at Durban. Vivo Energy represents the retail-to-marine distribution bridge model that compresses port congestion delays. Linsen Nambi Bunker Services and Ocean South Petroleum RSA sit within the independent specialist tier focused on barge-based delivery at anchorage.
| Leading Market Players |
|---|
| Linsen Nambi Bunker Services (Pty) Ltd |
| BP PLC (BP Southern Africa Pty Ltd) |
| Ocean South Petroleum RSA (Pty) Ltd |
| Engen Petroleum Ltd |
| Africa Bunkering and Shipping (Pty) Ltd |
| Vivo Energy |
| Monjasa |
| Minerva Bunkering |
| Dan-Bunkering |
| Others |
Pricing and Supply Chain Analysis
Refinery-anchored vertical integration by BP Southern Africa and Engen Petroleum secures cutter stock access that underpins both supply reliability and pricing leverage at Durban terminals. This captive blending infrastructure insulates integrated majors from Brent-linked volatility that squeezes independent traders dependent on multi-source import arbitrage.
Pricing Analysis
Warranty-backed fuel quality certification bundled with mass flow metering documentation commands premium positioning against unbundled spot purchases. Three-tier pricing structure across premium, standard, and economy levels stratifies by sulfur compliance grade and delivery certainty. Price differentiation hinges on IMO 2020 documentation completeness and berth scheduling priority. Cost compression in standard-tier LSFO is intensifying because independent terminal operators struggle to finance segregated tank retrofits. Fishing fleet operators exhibit highest price sensitivity due to seasonal revenue volatility, while container lines prioritize delivery predictability over unit cost minimization.
Supply Chain Analysis
Single-source vulnerability sits with Middle Eastern crude suppliers feeding Sapref and Engen Durban upgrade timelines. Geographic supply concentration centers on Saudi Arabia, Nigeria, and Angola for Brent-linked crude grades. Raw material dependencies encompass vacuum gas oil cutter stocks, additive packages, and marine gas oil blending components. Tariff exposure on refined product imports from Singapore and Rotterdam threatens margin stability during rand depreciation cycles. Distribution runs through coastal storage terminals at Cape Town and Richards Bay with barge-based final delivery to vessel anchorage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where IMO 2020 compliance certification burdens force sub-scale independents toward exit or acquisition by integrated majors with laboratory infrastructure.
For Market Incumbents: Deepen backward integration into cutter stock storage at Richards Bay to capture fishing fleet and offshore vessel demand migrating from Durban congestion. Engen Petroleum and BP Southern Africa should accelerate mass flow metering deployment across Western Cape terminals before independent specialists achieve first-mover positioning. Regulatory convergence with EU carbon border adjustments threatens margin pools for non-compliant blenders lacking biofuel trial capabilities. For New Entrants and Emerging Players: Offshore supply vessel operators at Richards Bay represent an underserved buyer archetype seeking marine gas oil with dynamic positioning system compatibility documentation. Specialist traders can penetrate this segment through pre-qualified supplier status with South African Maritime Safety Authority protocols. Digital bunker delivery platforms offering blockchain-verified documentation present the most penetrable go-to-market angle against incumbent manual processes. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated petroleum majors seeking coastal terminal footprints with low-sulfur segregation capacity. Long-term viability favors blenders with captive cutter stock logistics and MARPOL Annex VI laboratory certification. Watch for refinery upgrade completion at Sapref and Engen Durban as the inflection indicator shifting domestic supply adequacy and import dependency ratios.| Strategic Initiative | Industry Significance |
|---|---|
| Storage Terminal Metering Upgrade | Mass flow metering infrastructure at Richards Bay terminals compresses delivery windows and reduces demurrage disputes for container lines. |
| Long-term Supply Agreement Expansion | Contracting patterns with scheduled liner services at Durban stabilize throughput and displace volatile spot-market purchases. |
| Biofuel Blend Pilot Investment | Fatty acid methyl ester trials align bunker offerings with forthcoming EU carbon border adjustment compliance requirements. |
| Western Cape Distribution Bridge | Retail-to-marine logistics corridors at Cape Town capture cruise ship and fishing fleet demand outside Durban concentration. |
| Marine Chemist Certification Pipeline | Qualified fuel testing personnel development accelerates bunker delivery clearance times under tightened SAMSA protocols. |
Research Methodology
Multi-period observation of refinery utilization rates, bunker delivery volumes, and sulfur compliance certification timelines anchored the trend analysis, supplemented by interviews with fuel supply specialists, terminal operations managers, shipping line procurement officers, and South African Maritime Safety Authority inspectors. Secondary validation drew from Department of Mineral Resources and Energy regulatory filings, MARPOL Annex VI port-state inspection records, customs trade data for refined product imports, and SEC disclosures from listed petroleum majors. Bottom-up volume triangulation across product grades and end-user segments converged with top-down macroeconomic scenario testing.
Segment-weighting approaches applied differential growth assumptions across low sulfur fuel oil, marine gas oil, and residual fuel categories by vessel type and port corridor. The analytical framework modeled product type, end user scale, distribution channel infrastructure, and application intensity dimensions throughout the forecast period. CAGRs were derived from regression analysis against container throughput projections and fishing fleet licensing data. Forecast inputs incorporated rand-dollar exchange rate sensitivity bands and refinery upgrade timeline probability distributions.
Revisions become necessary when Brent crude volatility exceeds modeled bands, when refinery outages extend beyond maintenance windows, or when EU carbon border adjustment implementation accelerates biofuel displacement timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Coal Intelligent Dry Separators Market
Fuels
Commercial Aircraft Aviation Fuel Market
Fuels
Diesel Fuel Market
Fuels
Europe Coal Market
Fuels
Brazil Bunker Fuel Market
Fuels
Saudi Arabia Automotive Fuels Market
Fuels
Mobile Fuel Storage Tank Market
Fuels
North America Bunker Fuel Market
Fuels
Italy Chemical Logistics Market
Fuels
Europe Commercial Aircraft Aviation Fuel Market
Fuels
Coal Trading Market
Fuels
Aviation Fuel Market
Fuels
North America Oil and Gas Lubricants Market
Fuels
Bunker Fuel Market
Fuels
Fuel Oil Market
Fuels
Global Wood Gas Generator Market