
 North America Commercial Aircraft Aviation Fuel Market | 2026-2036
North America Commercial Aircraft Aviation Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
North America Commercial Aircraft Aviation Fuel Market Analytics
Multi-source procurement among legacy carriers is expanding as airlines hedge against refinery outages and price volatility. Chevron Corporation leverages its integrated West Coast refining network to secure long-term supply contracts with major hub airports. Shell PLC competes through dedicated aviation fuel terminals at key logistical chokepoints. Exxon Mobil Corporation anchors its position via proprietary jet fuel additives that meet stringent cold-flow specifications.
North America commercial aircraft aviation fuel comprises refined kerosene-based formulations, primarily Jet A and Jet A-1, with minimum flash points of 38°C and freeze points below -40°C, engineered to deliver stable combustion performance across wide temperature and altitude ranges. Jet A dominates terminal volumes across the United States due to its higher freeze point tolerance and extensive pipeline infrastructure, while Jet A-1 maintains stronger penetration in Canadian operations where colder ambient conditions prevail. Distribution through airport fuel farms captures the bulk of margin pools, given the capital intensity of hydrant systems and the regulatory barriers to terminal access.
The US EPA enforces renewable fuel standard pathways for aviation applications, while ASTM International certifies alternative jet fuel blends through its D7566 specification, and Transport Canada mandates sulfur limits through the Canadian Environmental Protection Act. These frameworks compel refiners to invest in hydrotreated renewable jet capacity and limit market access for uncertified blendstocks. Stakeholders must track state-level low-carbon fuel standard expansion and blending credit mechanics to anticipate which supply configurations will secure offtake priority.
Market Dynamics
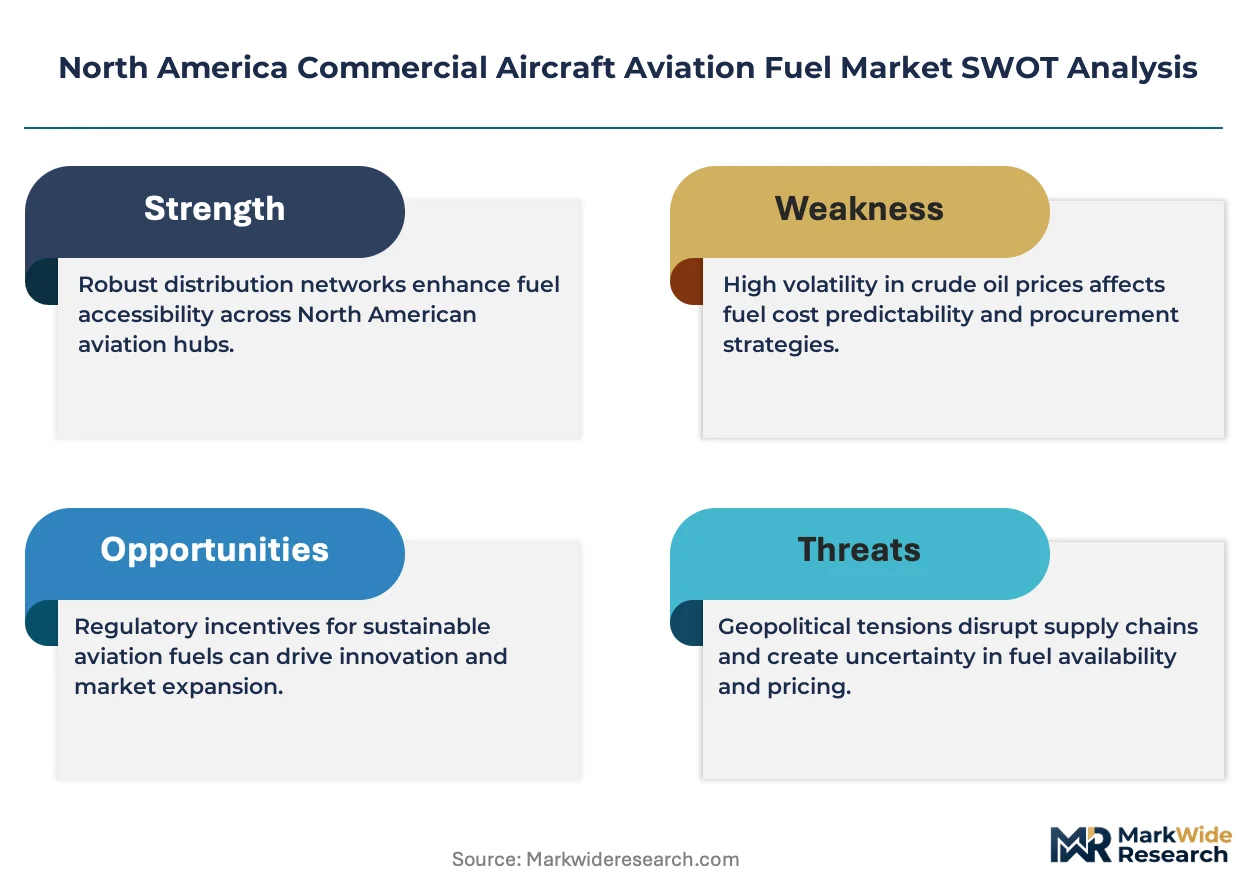
The US EPA's tightening carbon intensity benchmarks for aviation fuels are forcing refiners to reconfigure hydrotreatment capacity and secure certified biomass feedstocks ahead of mandate deadlines.
Growth Catalysts
- California LCFS expansion:The state's Low Carbon Fuel Standard generates tradable credits for sustainable aviation fuel blending, pulling investment toward West Coast biorefinery projects.
- Full-service carrier hedging:Legacy airlines are diversifying offtake agreements across multiple refiners to mitigate exposure to Gulf Coast hurricane disruptions and price spikes.
- Hydrotreated renewable jet (HRJ) certification:ASTM D7566 approval pathways for Fischer-Tropsch and hydroprocessed esters enable commercial-scale SAF deployment at major hub airports.
Market Restraints
- Feedstock cost volatility:Tallow, used cooking oil, and agricultural residue prices swing with commodity markets, compressing SAF refinery margins unpredictably.
- Gulf Coast concentration risk:Over half of US jet fuel refining capacity clusters between Houston and New Orleans, creating systemic vulnerability to weather and infrastructure outages.
- Pipeline specification lock-in:Colonial Pipeline and Kinder Morgan systems are optimized for conventional Jet A, limiting batch-size flexibility for higher-blend SAF movements.
Strategic Opportunities
- Texas SAF hub development:Existing refinery clusters near Beaumont and Port Arthur offer brownfield sites for hydrotreater retrofits with pipeline connectivity to Dallas-Fort Worth and Houston airports.
- Airport hydrant electrification:Underground fueling infrastructure at Denver International and Seattle-Tacoma enables integrated SAF blending without tanker truck bottlenecks.
- Canadian cold-climate premium:Jet A-1 demand in Edmonton and Calgary commands price premiums for enhanced cold-flow additives, rewarding specialty formulation capabilities.
Industry Challenges
- ASTM D7566 batch certification:Each renewable feedstock pathway requires separate qualification testing, stretching timeline-to-market for novel biomass sources.
- Refinery technician retraining:Hydrotreater operations for SAF demand different catalyst management and corrosion monitoring than conventional hydrocracking units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Commercial Aircraft Aviation Fuel Market |
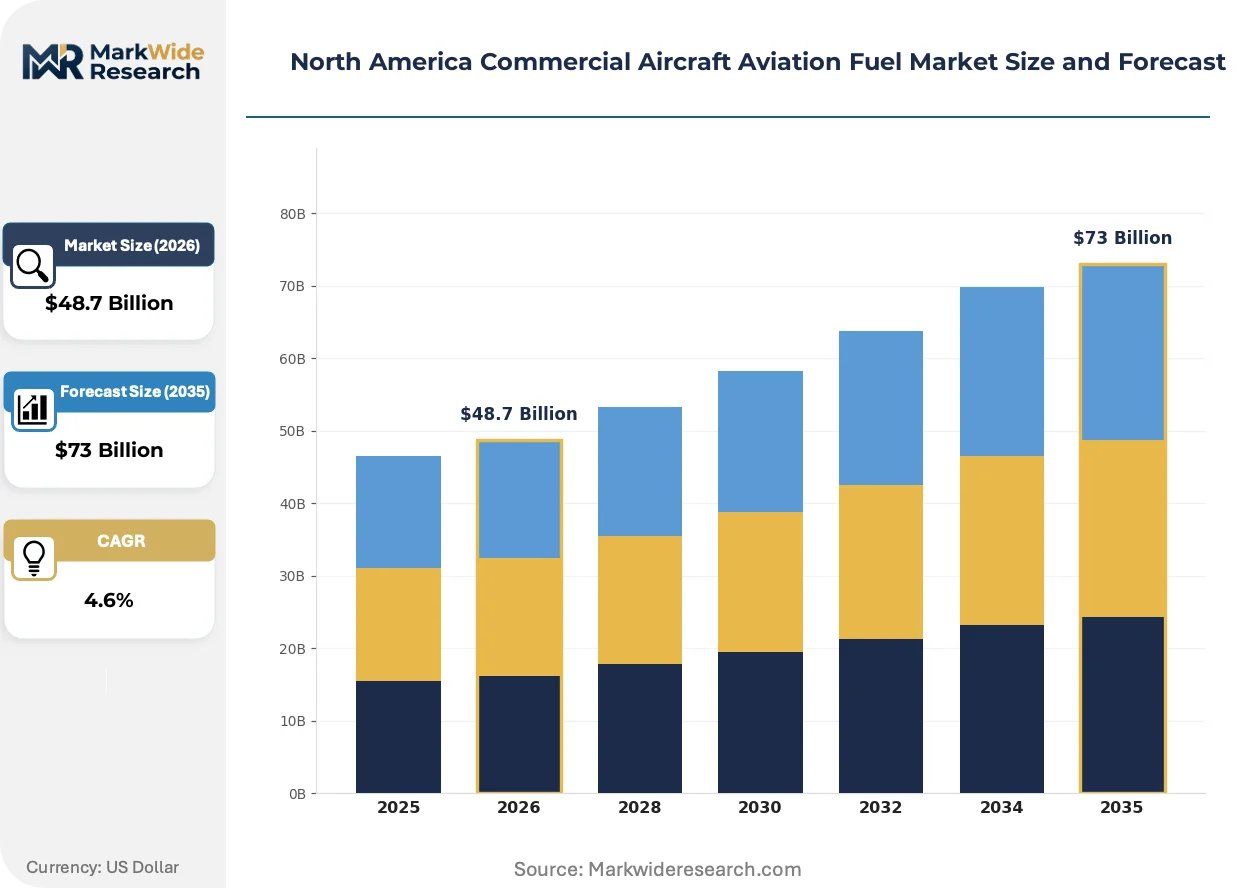
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $73 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Jet A, Jet A-1, Jet B, Aviation Gasoline Distribution Channel: Retail Stations, Airports, Fuel Suppliers, Direct Sales End User: Commercial Airlines, Charter Services, Cargo Carriers, Private Aviation Application: Passenger Transport, Cargo Transport, Maintenance Operations, Flight Training |
| Companies Covered | Chevron Corporation, World Fuel Services Corp, Vitol Holding BV, Shell PLC, TotalEnergies SE, Exxon Mobil Corporation, Valero Energy Corporation, Phillips 66, BP plc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Commercial Aircraft Aviation Fuel Market Evolving Landscape
Refinery technology and regulatory frameworks are converging to accelerate sustainable aviation fuel integration, while procurement patterns among carriers are compressing traditional supply contracting cycles.
Power-to-liquid (PtL) synthesis is rewriting the long-term feedstock economics for aviation decarbonization. This electrofuel pathway combines green hydrogen with captured carbon dioxide to produce synthetic paraffinic kerosene. European pilot projects at Rotterdam and Oslo airports are validating commercial-scale production economics. The technology is rewriting the competitive positioning of refiners lacking access to conventional biomass waste streams.
Transport Canada's sulfur limit enforcement under the Canadian Environmental Protection Act is tightening marine and aviation fuel specifications simultaneously. Refiners serving Vancouver and Toronto Pearson must now coordinate multi-product hydrotreatment campaigns. The policy is compressing operational flexibility at cross-border facilities supplying both Canadian and US Great Lakes markets.
Airlines are consolidating fuel purchasing through joint procurement consortia rather than individual refinery negotiations. Delta, United, and American have formed shared SAF offtake pools to aggregate volume commitments and secure priority allocation from limited production capacity. This behavior is most visible in California, where carriers compete for LCFS credit generation rights attached to each blended gallon delivered at Los Angeles International and San Francisco International.
North America Commercial Aircraft Aviation Fuel Market Segmentation
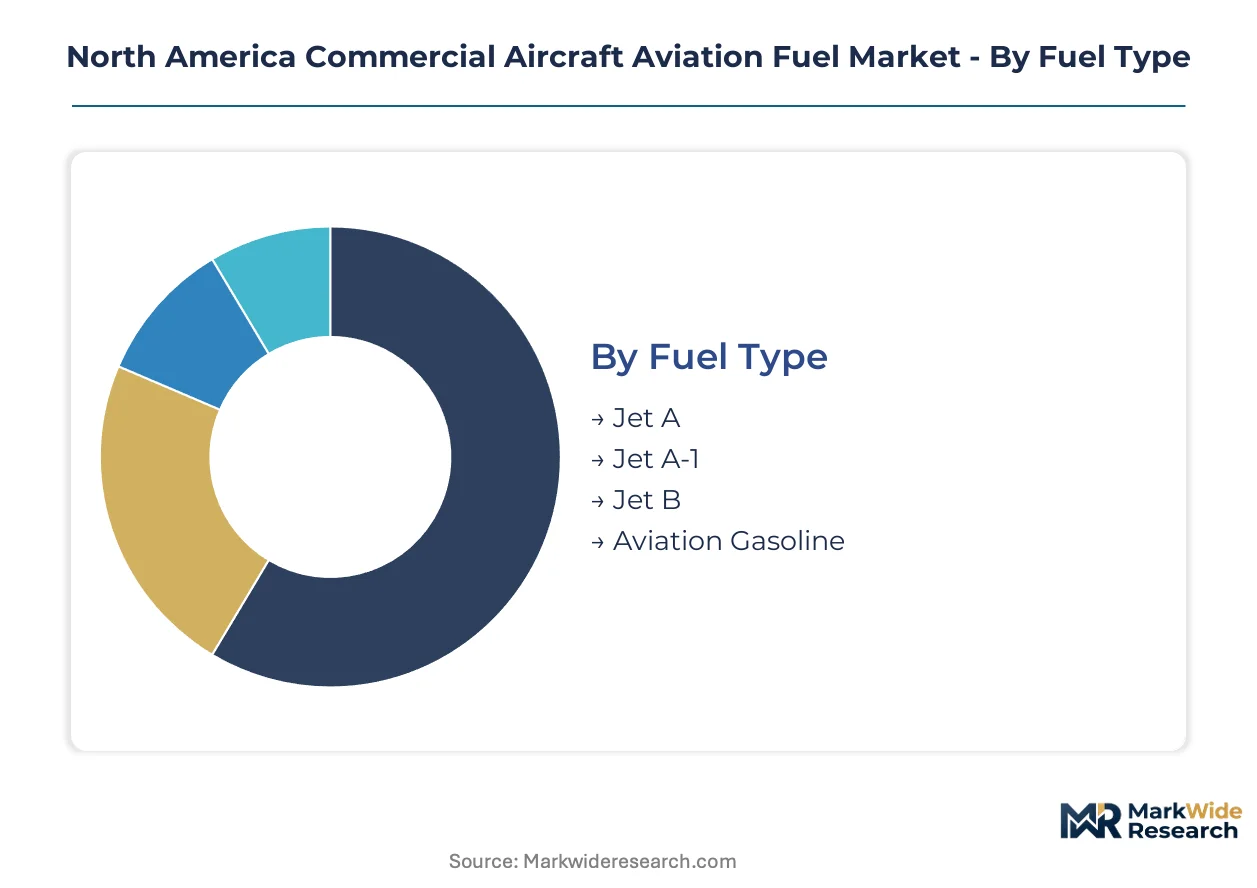
Aviation fuel segmentation in North America tracks how capital deployment, regulatory certification, and infrastructure access create divergent margin profiles across supply configurations. Distinct fuel specifications, distribution modalities, and end-use applications each demand specialized asset bases and operational expertise.
Fuel Type:
Capital intensity varies sharply across fuel categories, with hydrotreatment retrofits for renewable blending requiring the heaviest infrastructure investment.
- Jet A:Refined kerosene with a freeze point of -40°C and flash point minimum of 38°C, formulated specifically for US domestic operations where pipeline networks dominate supply logistics. Terminal volumes concentrate at Gulf Coast refineries feeding Atlanta Hartsfield-Jackson and Chicago O'Hare through Colonial Pipeline distribution, though specification lock-in limits batch flexibility for higher renewable blends.
- Jet A-1:Lower freeze point specification (-47°C) with identical energy density, engineered for cold-climate reliability across Canadian operations and northern US routes. Edmonton and Calgary command sustained premiums for enhanced cold-flow additive packages, while cross-border facilities serving Toronto Pearson coordinate multi-product campaigns under Transport Canada sulfur mandates.
- Jet B:Wide-cut gasoline-kerosene blend optimized for extreme cold environments with freeze points below -50°C, serving remote Arctic operations and military applications where operational temperature floors are non-negotiable.
- Aviation Gasoline:Leaded and unleaded formulations for piston-engine aircraft, distributed through fragmented retail networks rather than airport hydrant systems, with octane ratings of 100LL dominating the installed general aviation base.
Most installed capacity flows through Jet A. Expansion is steepest in Jet A-1 as Canadian cold-climate demand intensifies.
Distribution Channel:
Channel selection determines working capital requirements and margin capture, with airport hydrant infrastructure demanding the longest asset deployment timelines.
- Retail Stations:Ground-level dispensing infrastructure serving general aviation airfields and regional operators, requiring lower capital commitment but capturing thinner per-gallon margins due to competitive fragmentation.
- Airports:Hydrant systems and fuel farms at major hubs including Denver International and Seattle-Tacoma enable integrated SAF blending and direct airline procurement, with capital intensity justified by volume concentration and long-term offtake security.
- Fuel Suppliers:Intermediate wholesalers aggregating refinery output for redistribution to smaller airfields, occupying working capital intensive inventory positions while providing geographic coverage refiners bypass.
- Direct Sales:Refiner-to-airline contracts eliminating intermediary margins, favored by full-service carriers consolidating procurement through joint consortia to aggregate volume commitments.
Volume concentrates at airports. Direct sales channels are climbing the fastest as carrier procurement consolidates.
End User:
End-user segmentation maps to operational scale and fuel specification complexity, with scheduled carriers driving standardization while fragmented operators sustain specialty demand.
- Commercial Airlines:Scheduled passenger and cargo operations at major hubs, consuming standardized Jet A and Jet A-1 through long-term supply agreements and driving SAF blending mandates through collective procurement power.
- Charter Services:On-demand operators with variable route profiles and thinner fuel hedging capabilities, sourcing through spot markets and fuel supplier intermediaries rather than direct refinery contracts.
- Cargo Carriers:Dedicated freighter fleets and belly-hold operators with nighttime hub operations, prioritizing supply reliability over price optimization given schedule inflexibility.
- Private Aviation:Fractional ownership and corporate flight departments with dispersed geographic footprints, sustaining aviation gasoline demand and premium Jet A-1 requirements at secondary airfields.
Commercial airlines absorb the largest volume share. Cargo carriers are expanding most quickly as e-commerce fulfillment networks densify.
Application:
Application segmentation reveals divergent fuel burn profiles and operational constraints, with maintenance and training sustaining baseline demand independent of passenger traffic cycles.
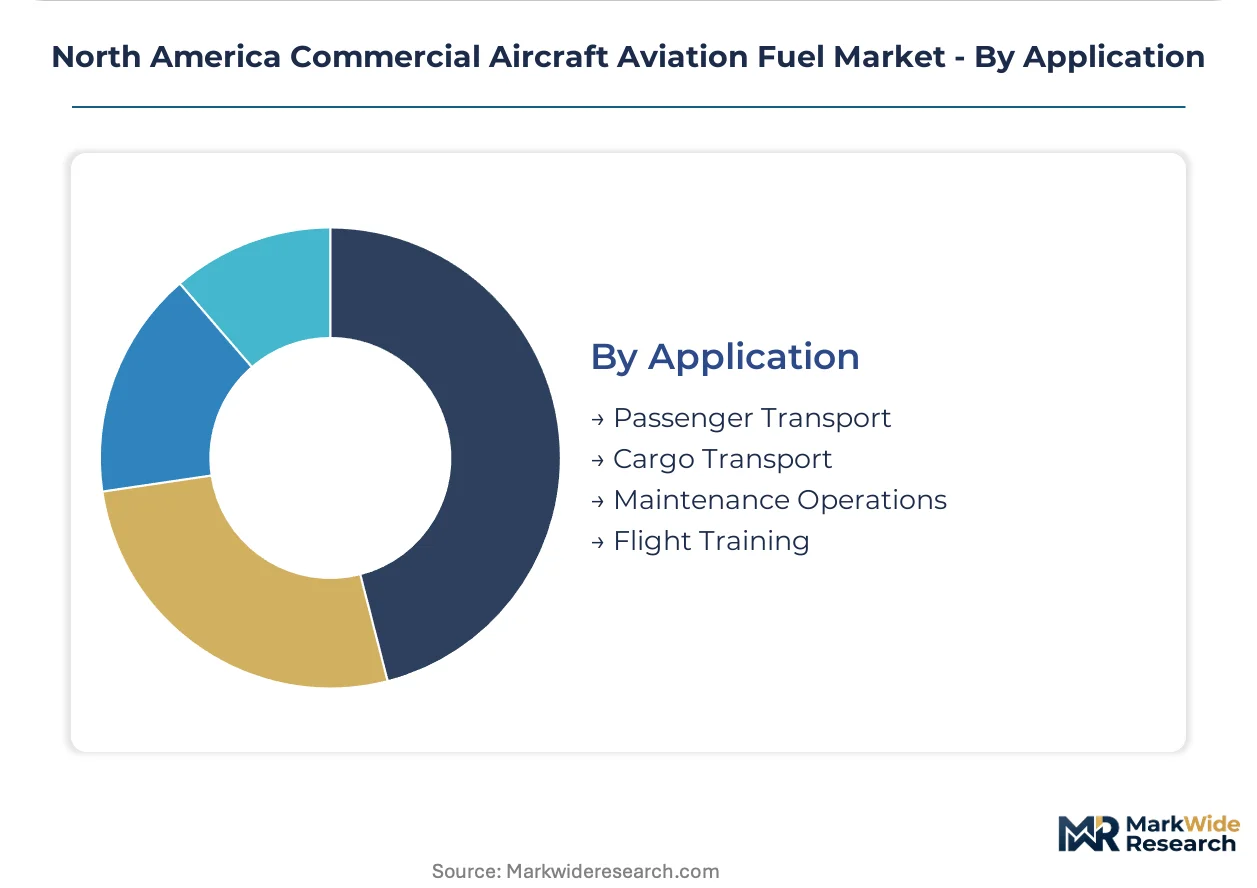
- Passenger Transport:Scheduled and charter revenue services accounting for the dominant share of jet fuel combustion, with route networks concentrated at coastal hubs and interior transfer points.
- Cargo Transport:Dedicated freighter operations and integrated express networks with distinct hub-and-spoke fueling patterns, often operating at secondary terminals with specialized ground handling.
- Maintenance Operations:Engine testing and airframe checks at MRO facilities, generating steady demand for test-cell fuel burn and ferry flight positioning.
- Flight Training:Ab initio and recurrent instruction at dedicated academies, sustaining piston-engine aviation gasoline consumption and turboprop Jet A-1 requirements.
Passenger transport channels the greatest throughput. Cargo transport is gaining share fastest as dedicated freighter fleets expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast refinery corridor stretching from Houston to New Orleans channels the dominant share of North American jet fuel production, with pipeline networks feeding distribution hubs across the continent.
United States
California's Low Carbon Fuel Standard generates tradable credits for sustainable aviation fuel blending, pulling investment toward West Coast biorefinery projects. The EPA enforces renewable fuel standard pathways that compel refiners to reconfigure hydrotreatment capacity ahead of mandate deadlines. Dallas-Fort Worth and Houston airports anchor Texas demand clusters where existing refinery infrastructure offers brownfield sites for hydrotreater retrofits.
Canada
Edmonton and Calgary command sustained price premiums for Jet A-1 formulations with enhanced cold-flow additives suited to subarctic operations. Transport Canada mandates sulfur limits through the Canadian Environmental Protection Act, tightening specifications simultaneously for marine and aviation applications. Cross-border facilities serving Toronto Pearson coordinate multi-product hydrotreatment campaigns under these dual regulatory pressures.
Mexico
Mexico City International Airport concentrates domestic carrier demand as Aeromexico and Volaris expand fleet renewals requiring consistent Jet A supply security. Energy sector liberalization has opened aviation fuel import channels previously controlled by state monopoly Pemex. Tijuana and Cancun airports serve cross-border tourism corridors where US-registered aircraft create blended demand for ASTM-certified formulations.
North America Commercial Aircraft Aviation Fuel Market Competitive Landscape
Global majors compete with regional champions across terminal access and long-term offtake security. The market structure concentrates around integrated refiners with proprietary pipeline positions and independent fuel suppliers aggregating volume for fragmented general aviation demand. Three archetypes dominate: integrated oil majors controlling upstream-through-terminal value chains, independent marketers leveraging logistics flexibility, and specialist blenders capturing SAF certification premiums. Competitive moves center on hydrotreater capacity expansion for renewable blending and strategic partnerships with full-service carriers seeking supply diversification.
Within the integrated major tier, Chevron Corporation and Exxon Mobil Corporation exemplify asset-heavy positioning anchored to West Coast and Gulf Coast refining networks respectively. Shell PLC occupies a position bridging integrated production with dedicated aviation terminal operations at logistical chokepoints. These three entities represent the scale-driven end of competitive positioning, each leveraging distinct geographic infrastructure advantages to secure long-term hub airport contracts.
| Leading Market Players |
|---|
| Chevron Corporation |
| World Fuel Services Corp |
| Vitol Holding BV |
| Shell PLC |
| TotalEnergies SE |
| Exxon Mobil Corporation |
| Valero Energy Corporation |
| Phillips 66 |
| BP plc |
| Others |
Value Network & Pricing Analysis
Biomass feedstock costs cascade through hydrotreater economics to stratify aviation fuel pricing across conventional, certified blend, and fully synthetic tiers. Tallow and used cooking oil price volatility at Gulf Coast collection points compresses sustainable aviation fuel margins before California LCFS credits partially offset downstream.
Pricing Analysis
Input-cost pass-through from agricultural residue markets to refinery gate pricing intensifies margin compression for sustainable aviation fuel producers. Contract-based long-term offtake agreements dominate procurement between full-service carriers and integrated refiners, with price differentiation resting on ASTM D7566 certification tier and volume scale. Pricing pressure stems from feedstock competition with renewable diesel mandates in California. Charter operators exhibit highest price sensitivity due to thin hedging capabilities, while cargo carriers prioritize supply security over optimization.
Supply Chain Analysis
Dual-sourcing requirements from Delta, United, and American Airlines mandate multi-refiner qualification for hub airport supply security. Production concentrates in the United States, Canada, and Mexico, with Gulf Coast refinery clusters feeding pipeline networks northward. The supply chain draws from crude oil, biomass waste streams, and emerging power-to-liquid synthetic pathways. Single-source vulnerability at Colonial Pipeline chokepoints creates systemic exposure. Distribution runs through airport hydrant systems capturing margin pools from direct airline procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American aviation fuel has entered a late-cycle quality phase where Jet A-1 cold-flow specifications and SAF certification tiers command procurement priority from full-service carriers consolidating purchasing power.
For Market Incumbents: To counter Gulf Coast concentration risk, Chevron and Exxon Mobil should diversify hydrotreater capacity across West Coast biorefinery brownfield sites. Backward integration into certified biomass feedstock collection networks secures supply priority under California LCFS expansion. Terminal control at Denver International and Seattle-Tacoma anchors long-term offtake security.
For New Entrants and Emerging Players: Digital procurement platforms aggregating fragmented general aviation demand offer the lowest barrier to terminal access. White-space targets include aviation gasoline retail networks at secondary airfields and specialty Jet B formulations for Arctic operations. Joint venture structures with existing fuel farm operators bypass capital intensity of hydrant infrastructure.
For Investors and Strategic Acquirers: Roll-up economics work for regional fuel suppliers because carrier procurement consolidation demands geographic coverage breadth beyond single-refiner reach. Five-to-ten year viability hinges on hydrotreater retrofit completion ahead of EPA carbon intensity deadlines. The signal to watch is ASTM D7566 pathway approval velocity for novel feedstocks.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrotreater Capacity Expansion | Enables SAF blending at Beaumont and Port Arthur clusters serving Dallas-Fort Worth demand. |
| Long-term Supply Agreement | Aggregates volume commitments through Delta-United-American procurement consortia. |
| Backward Integration | Captures tallow and used cooking oil streams before renewable diesel competition. |
| Joint Venture | Combines refinery expertise with airline offtake security for West Coast biorefinery development. |
| Green Certification Program | Generates LCFS credit rights attachable to each blended gallon at Los Angeles International. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each territory combined with secondary validation. Interviews with refinery operations directors, airline fuel procurement managers, airport authority supply planners, and sustainable aviation fuel certification specialists informed demand-side assumptions. Secondary sources include EPA renewable fuel standard filings, ASTM D7566 certification records, Transport Canada sulfur limit enforcement data, and Colonial Pipeline throughput disclosures. Bottom-up refinery capacity modeling triangulates against top-down carrier consumption estimates.
Granularity-level modeling disaggregates volume and value across fuel type, distribution channel, end user, and application dimensions throughout the forecast period. CAGRs derive from production capacity buildout timelines and mandate-driven blending requirement trajectories. Industry-specific inputs incorporate hydrotreater retrofit completion schedules and LCFS credit price forecasting.
The model assumes a particular technology adoption path; alternative pathways for power-to-liquid electrofuel synthesis would alter the outlook if green hydrogen cost curves steepen faster than projected. Deviation in EPA carbon intensity benchmark enforcement timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Global Liquid Gas Cylinder (LGC) Market
Fuels
Tire Derived Fuel Market
Fuels
Wood Charcoal Market
Fuels
Global Butane Gas Cartridges Market
Fuels
Aerospace Aviation Fuels Market
Fuels
Asia-Pacific Coal Market
Fuels
Global Turbine Oil Market
Fuels
City Gas Distribution Market
Fuels
Refuse Derived Fuel Market
Fuels
Singapore Bunker Fuel Market
Fuels
Oil Dispensing Stations Market
Fuels
Mobile Fuel Delivery Market
Fuels
Europe Wood Pellet Market
Fuels
Coal Gasification Market
Fuels
China LNG Market
Fuels
Global Gas Cylinder Market