
 Europe Biogas Market | 2026-2036
Europe Biogas Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Biogas Market Analysis
Municipal utilities is collapsing toward industrial off-takers as the dominant buyer archetype for upgraded biomethane. EnviTec Biogas leverages its engineering footprint across German agricultural clusters to dominate turnkey plant construction. Scandinavian Biogas Fuels International anchors Nordic maritime demand by specializing in liquefied biogas bunkering infrastructure. VERBIO Vereinigte BioEnergie AG extends its vertical reach from crop cultivation through grid injection, controlling feedstock quality and offtake pricing simultaneously.
Biogas comprises methane, carbon dioxide, and trace gases produced through anaerobic digestion of organic matter at mesophilic or thermophilic temperatures, typically yielding methane concentrations of 50-75% that require upgrading to 96%+ for grid injection or vehicle fuel compliance. The technology dimension tilts heavily toward anaerobic digestion as the baseline platform, though co-digestion is accelerating fastest where food waste regulations mandate source separation. Feedstock type reveals a structural margin divergence: agricultural residues and manure offer lower input costs but energy crops command premium pricing in biomethane certificates under national greenhouse gas quota systems.
The EU Green Deal and REPowerEU framework shape demand through binding biomethane targets, while the F-Gas Regulation and national implementations under the Renewable Energy Directive enforce sustainability criteria for feedstock eligibility. EMA guidance on renewable gas certification and member-state greenhouse gas quota schemes determine market access thresholds for cross-border biomethane trade. Stakeholders must monitor the trajectory of EU hydrogen blending mandates and their interaction with biomethane grid priority rights.
Market Dynamics
The EU Green Deal and REPowerEU framework are compressing project timelines by binding national biomethane targets to grid-priority access rights, forcing developers to secure feedstock contracts before permitting begins.
Growth Catalysts
- REPowerEU biomethane targets:The framework mandates 35 billion cubic meters of annual biomethane production by 2030, locking in demand visibility for agricultural cluster developers across northern Germany and Denmark.
- District heating decarbonization:Municipal utilities in the Netherlands and Sweden are converting combined heat and power plants to accept upgraded biomethane, creating anchor offtake contracts with 15-20 year tenors.
- Food waste source-separation mandates:Co-digestion regulations in France and Italy are unlocking high-energy feedstock streams that boost plant yields without expanding agricultural land use.
Market Restraints
- Manure supply concentration:The agricultural corridor linking Lower Saxony to Overijssel dominates feedstock availability, exposing developers in peripheral regions to transport cost penalties of 15-25%.
- Grid injection tariff uncertainty:German Bundesnetzagentur reviews of feed-in premiums create 18-24 month revenue visibility gaps that stall final investment decisions.
- Hydrogen blending mandate competition:Draft EU hydrogen network regulations threaten biomethane priority access rights in transmission pipelines serving industrial clusters.
Strategic Opportunities
- Polish agricultural biogas:The country's dairy consolidation and delayed grid-connection queue position it for leapfrog deployment of containerized upgrading units.
- Liquefied biomethane bunkering:Baltic Sea port authorities in Estonia and Finland are tendering LNG-compatible infrastructure that accepts bio-LNG without hardware modification.
- Carbon capture integration:The F-Gas Regulation's tightening of industrial CO2 quotas creates value pools for biogas plants installing amine-based capture on upgrading exhaust streams.
Industry Challenges
- Anaerobic digestion process engineering talent:The specialized skill set combining microbiology and mechanical design concentrates in German technical universities, constraining plant commissioning schedules elsewhere.
- Sustainability certification timelines:ISCC EU and national greenhouse gas quota scheme audits require 8-14 months for first-time applicants, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Biogas Market |
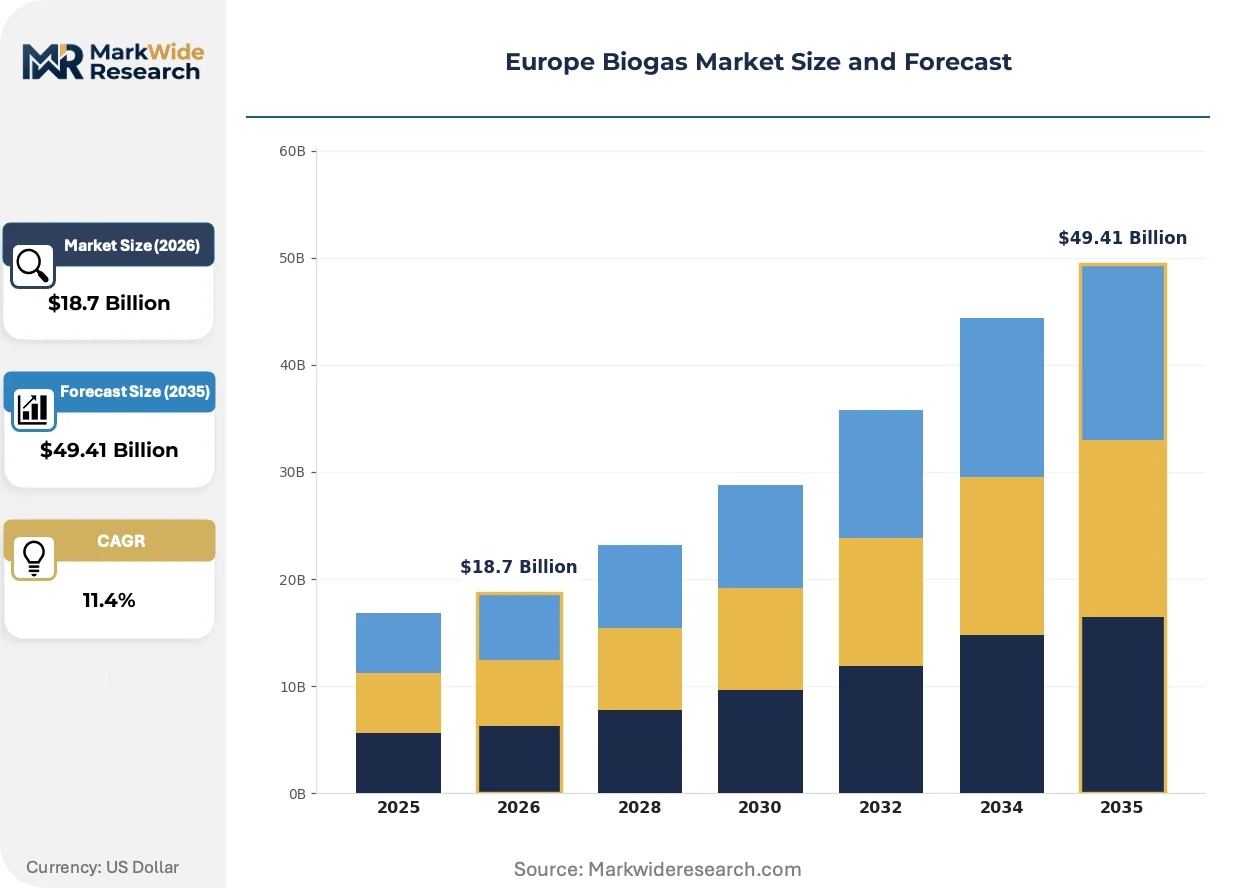
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feedstock Type: Agricultural Residues, Food Waste, Manure, Energy Crops Technology: Anaerobic Digestion, Biochemical Processing, Thermal Gasification, Co-Digestion End User: Electricity Generation, Heat Production, Vehicle Fuel, Grid Injection Application: Power Generation, Bioenergy, Waste Treatment, Combined Heat and Power |
| Companies Covered | EnviTec Biogas, Viessmann Group, Scandinavian Biogas Fuels International, Agrinz Technologies, Weltec Biopower, PlanET Biogas Global, Gasum, VERBIO Vereinigte BioEnergie AG, Nature Energy A/S, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Biogas Market Emerging Trajectories
Membrane upgrading technology is compressing plant footprints while policy instruments are resequencing investment flows toward integrated carbon capture configurations.
Membrane separation for biogas upgrading is miniaturizing. Containerized membrane units from suppliers in Germany and Denmark now process 100-400 Nm³/hour within standard shipping frames, enabling dairy cooperatives to deploy upgrading without dedicated civil works. Agricultural clusters in the Netherlands are adopting these units at 40% faster deployment cycles than amine or PSA alternatives, collapsing the capital barrier between raw biogas and grid-ready biomethane.
The F-Gas Regulation's phase-down of fluorinated greenhouse gases is reshaping upgrading technology selection. Refrigerant-based upgrading systems face refrigerant cost escalation and servicing restrictions, accelerating water wash and membrane technology adoption in new plant specifications. German engineering procurement contracts now explicitly exclude refrigerant-dependent systems for projects commissioning after 2027.
Long-term offtake contracting is displacing merchant exposure in developer financing. Project finance lenders in the agricultural corridor now require 10-year biomethane purchase agreements with investment-grade counterparty ratings before debt drawdown. Danish district heating cooperatives and Dutch industrial gas users are structuring indexed contracts that transfer certificate value volatility while fixing volume commitments.
Europe Biogas Market Segmentation
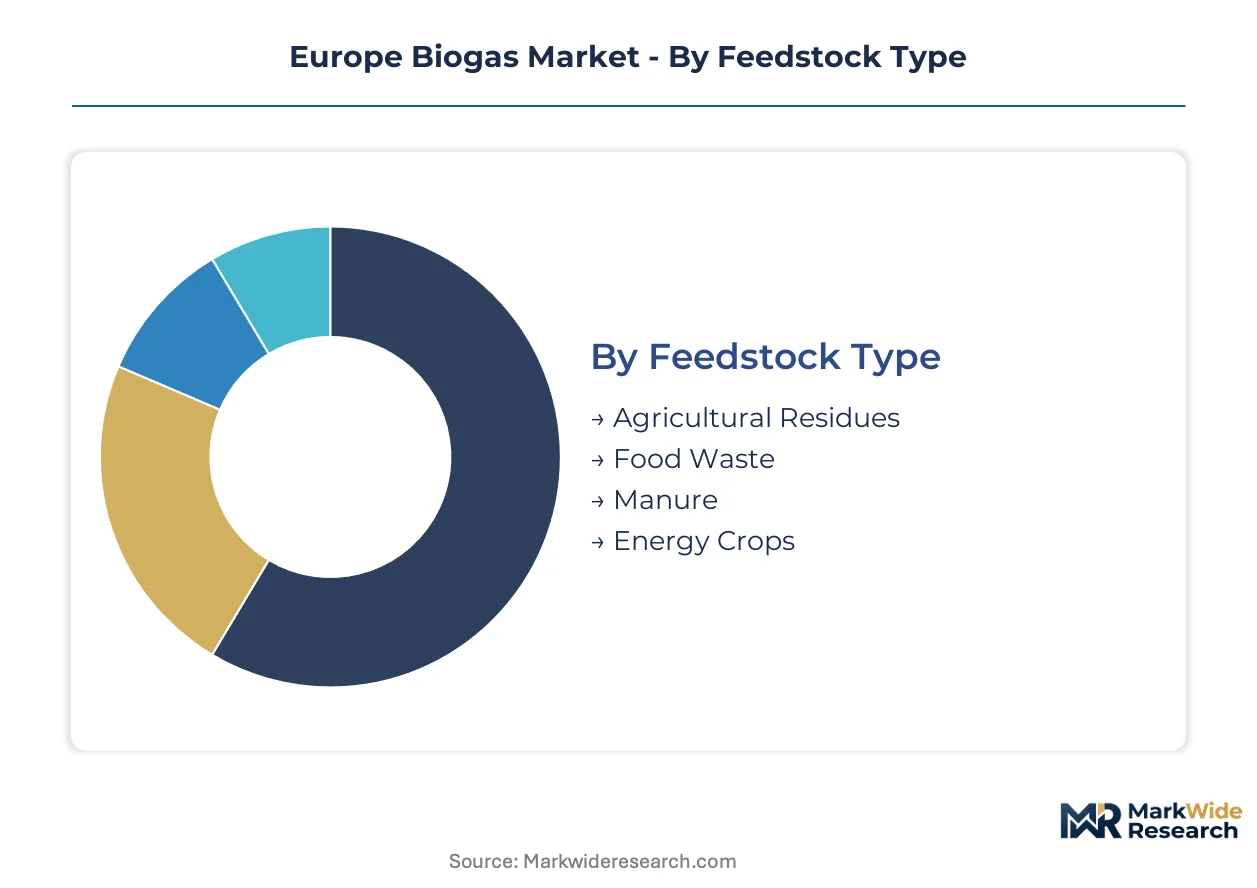
Segmentation in the Europe Biogas Market reveals how margin pools shift between feedstock sourcing, upgrading technology, and offtake contracting. Developers optimize project returns by matching feedstock availability to end-user pricing power across district heating networks and transport fuel markets.
Feedstock Type:
Margin concentration follows regulatory treatment of greenhouse gas quota eligibility, with certified feedstocks commanding certificate premiums in German and Dutch schemes.
- Manure:Dairy operations in Lower Saxony and Overijssel supply this feedstock at scale through clustered collection networks. Northern Germany's agricultural corridor dominates procurement, with transport cost penalties of 15-25% exposing peripheral developers to margin compression.
- Food Waste:Source-separated organic streams from French and Italian municipal mandates deliver higher methane yields per tonne than agricultural alternatives. Co-digestion regulations in these markets are unlocking this feedstock without expanding agricultural land use, rotating demand toward urban peripheral plants.
- Agricultural Residues:Straw and crop waste from cereal production regions offers lower input costs but variable energy density.
- Energy Crops:Maize silage and dedicated cultivation command premium biomethane certificate pricing under national greenhouse gas quota systems.
Manure holds installed capacity. Food waste is rotating up the share rankings.
Technology:
Technology selection determines capital recovery timelines, with membrane upgrading compressing deployment cycles versus amine-based alternatives.
- Anaerobic Digestion:Mesophilic and thermophilic digestion at 35-55°C yields methane concentrations of 50-75%, requiring downstream upgrading for grid injection. This baseline platform dominates existing capacity across Danish agricultural cooperatives and German municipal utilities.
- Co-Digestion:Blending manure with food waste or agricultural residues boosts biogas yields per digester volume. The Netherlands leads deployment of this technology, where dairy cooperatives pair containerized upgrading units with multi-feedstock intake systems.
- Thermal Gasification:High-temperature conversion of lignocellulosic biomass to syngas remains pre-commercial at scale in European markets.
- Biochemical Processing:Enzymatic pre-treatment of recalcitrant feedstocks is gaining traction for agricultural residue valorization.
Anaerobic digestion dominates capacity totals. Co-digestion is climbing the fastest.
End User:
Offtake contract duration and counterparty credit quality segment developer financing access, with grid injection and district heating offering longest tenors.
- Grid Injection:Upgraded biomethane at 96%+ methane content enters transmission pipelines serving Dutch and Swedish district heating networks. Municipal utilities in these markets are converting combined heat and power plants, creating anchor contracts with 15-20 year tenors that satisfy project finance requirements.
- Vehicle Fuel:Compressed and liquefied biomethane serves heavy transport and maritime bunkering demand. Scandinavian port authorities in Estonia and Finland are tendering LNG-compatible infrastructure that accepts bio-LNG without hardware modification.
- Electricity Generation:Raw biogas combustion in combined heat and power units faces margin pressure from declining feed-in tariffs.
- Heat Production:Direct thermal use in industrial processes offers stable demand but limited scale expansion.
Grid injection holds installed capacity. Vehicle fuel is rotating up the share rankings.
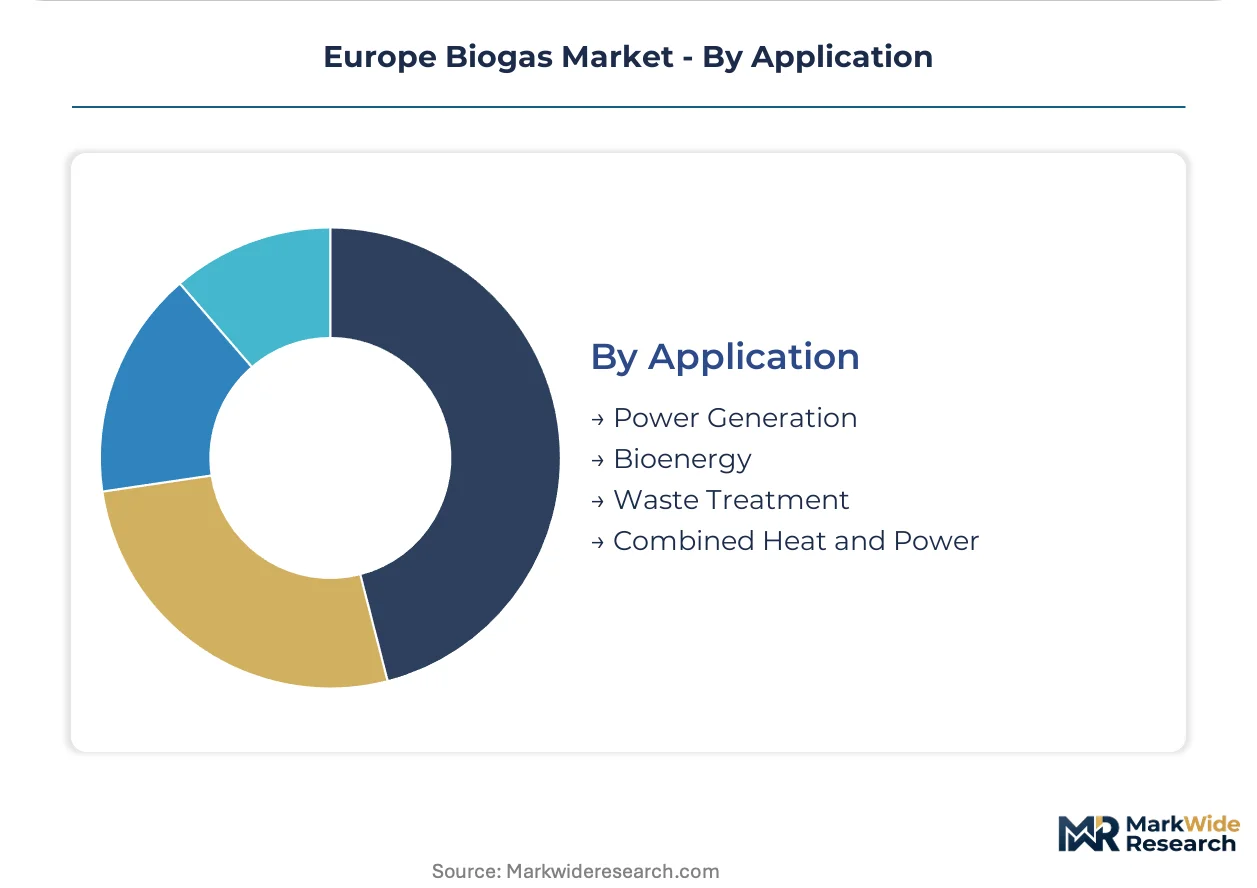
Application:
Application segmentation tracks how policy instruments resequence investment flows toward integrated carbon capture and power-to-heat configurations.
- Combined Heat and Power:Cogeneration plants capture thermal output for district heating while generating electricity, maximizing energy conversion efficiency. Swedish and Dutch municipal utilities are retrofitting existing gas-fired CHP plants for biomethane acceptance.
- Bioenergy:Standalone biomethane production for grid injection or transport fuel represents the highest-value application tier. The F-Gas Regulation's tightening of industrial CO2 quotas creates value pools for plants installing amine-based capture on upgrading exhaust streams.
- Power Generation:Electricity-only output faces competitive pressure from renewable electricity auctions.
- Waste Treatment:Organic waste diversion from landfill drives regulatory compliance value rather than energy revenue.
Combined heat and power holds installed capacity. Bioenergy is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial off-takers are displacing municipal utilities as the dominant buyer archetype for upgraded biomethane across the continent. Grid-injection capacity expansions concentrate in agricultural corridors where clustered dairy operations supply manure feedstock at scale.
Germany
Lower Saxony's dairy cooperatives anchor feedstock supply for biomethane upgrading clusters. The Bundesnetzagentur's feed-in tariff reforms under the EU Green Deal reward biomethane upgrades over raw biogas combustion. Northern Germany's agricultural corridor dominates procurement networks linking manure collection to grid-injection terminals.
Denmark
District heating cooperatives are converting combined heat and power plants to accept upgraded biomethane. National biomethane targets align with REPowerEU framework mandates for 35 billion cubic meters by 2030. Jutland's agricultural regions host containerized upgrading units deployed at 40% faster cycles than conventional alternatives.
Netherlands
Municipal utilities expanding grid-injection capacity prioritize biomethane for district heating network decarbonization. Co-digestion regulations unlock food waste streams from urban source-separation mandates without agricultural land use expansion. The Overijssel-Groningen corridor channels dairy manure into clustered upgrading infrastructure.
Sweden
Industrial gas users are structuring indexed biomethane purchase agreements with 10-year tenors to satisfy project finance requirements. National greenhouse gas quota schemes determine market access thresholds for cross-border biomethane trade. Baltic Sea port authorities tender LNG-compatible bunkering infrastructure accepting bio-LNG without hardware modification.
Poland
Dairy consolidation and delayed grid-connection queues position the country for leapfrog deployment of containerized upgrading units. EU Green Deal binding targets compress project timelines by linking national biomethane objectives to grid-priority access rights. Masovian and Greater Poland voivodeships concentrate agricultural feedstock availability for first-mover developers.
Europe Biogas Market Vendor Landscape
Player mix skews toward engineering-led turnkey specialists and vertically integrated energy conglomerates. The vendor base concentrates in German and Nordic agricultural clusters where proximity to feedstock sources determines contract win rates. Strategic archetypes separate into three tiers: full-service engineering procurement construction firms controlling plant commissioning schedules, crop-to-grid integrators capturing certificate premiums through feedstock quality control, and regional gas utilities leveraging distribution infrastructure for biomethane offtake. Dominant competitive moves include capacity expansion in containerized upgrading technology and strategic partnerships securing long-term manure supply contracts.
Within the engineering-led tier, EnviTec Biogas and Weltec Biopower exemplify turnkey specialists leveraging German technical university talent pipelines. Scandinavian Biogas Fuels International occupies a position anchoring Nordic maritime demand through liquefied biogas bunkering infrastructure specialization. VERBIO Vereinigte BioEnergie AG represents the crop-to-grid integrator archetype, extending control from cultivation through grid injection to manage offtake pricing simultaneously.
| Leading Market Players |
|---|
| EnviTec Biogas |
| Viessmann Group |
| Scandinavian Biogas Fuels International |
| Agrinz Technologies |
| Weltec Biopower |
| PlanET Biogas Global |
| Gasum |
| VERBIO Vereinigte BioEnergie AG |
| Nature Energy A/S |
| Others |
Supply Flow & Price Mechanics
Membrane upgrading technology replacing amine-based systems across German and Danish plant specifications simultaneously compresses capital recovery timelines and relocates supplier bargaining power toward containerized equipment manufacturers. This substitution dynamic reshapes procurement geography as engineering procurement contracts now explicitly exclude refrigerant-dependent systems, forcing developers to absorb premium pricing for modular units or face extended commissioning delays.
Pricing Analysis
Cost-plus contracts with Dutch TTF natural gas indexation dominate biomethane offtake agreements between agricultural cooperatives and municipal utilities. Price differentiation hinges on ISCC EU certification tier and biomethane certificate vintage under national greenhouse gas quota schemes. Pricing pressure stems from German Bundesnetzagentur feed-in premium reviews creating 18-24 month revenue visibility gaps. Industrial off-takers exhibit lowest price sensitivity due to long-term decarbonization commitments, while merchant-exposed developers face acute margin compression.
Supply Chain Analysis
Inbound logistics costs for containerized membrane upgrading units from German and Danish suppliers face periodic strain from Baltic Sea port congestion and refrigerated container availability constraints on the Hamburg-Rotterdam trade lane. Feedstock supply concentrates in Lower Saxony, Overijssel, and Jutland where clustered dairy operations anchor manure procurement networks. Component dependencies include specialized polymer membranes, stainless steel digester vessels, and grid-connection hardware. Single-source vulnerability concentrates in anaerobic digestion process engineering talent pipelines from German technical universities. Distribution runs through turnkey engineering procurement construction contracts linking equipment suppliers to agricultural cooperative developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Biogas Market rewards players commanding scarce anaerobic digestion microbiology expertise and grid-priority access rights, with project finance availability hinging on demonstrated feedstock contract execution before permitting initiation.
For Market Incumbents: Secure long-term manure supply contracts in Poland's Masovian and Greater Poland voivodeships before dairy consolidation completes and transport cost penalties lock out peripheral developers. Deepen backward integration into containerized upgrading unit manufacturing to capture margin pools shifting from civil works toward modular equipment, insulating against hydrogen blending mandate competition threatening biomethane priority access rights in EU transmission pipelines. For New Entrants and Emerging Players: Lead with containerized upgrading deployment in Estonia and Finnish Baltic Sea ports where LNG-compatible bunkering infrastructure tenders accept bio-LNG without hardware modification, bypassing established grid-injection queues. Target Polish agricultural biogas where delayed grid-connection queues and dairy consolidation create leapfrog deployment opportunities for standardized membrane units, positioning for cross-border biomethane trade under EMA certification frameworks. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors crop-to-grid integrators with captive feedstock quality control and indexed offtake pricing power. Long-term viability rests on vertical reach from cultivation through certificate monetization rather than pure-play engineering exposure. Watch the trajectory of EU hydrogen blending mandates and their interaction with biomethane grid priority rights as the critical inflection signal for asset stranding risk.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Manure Supply Contracting | Locks in feedstock availability ahead of Polish dairy consolidation completing. |
| Containerized Upgrading Capacity Buildout | Compresses deployment cycles 40% faster than amine alternatives in Dutch clusters. |
| ISCC EU Certification Investment | Unlocks premium biomethane certificate pricing under German and Dutch quota schemes. |
| Carbon Capture Integration | Captures value pools from F-Gas Regulation tightening on industrial CO2 quotas. |
| Baltic Sea Bunkering Infrastructure Partnership | Positions for bio-LNG demand from Scandinavian port authority tenders. |
Methodological Framework
Desk research of EU regulatory filings under REPowerEU and the F-Gas Regulation, national greenhouse gas quota scheme documentation, and EMA renewable gas certification guidance preceded structured interviews with biomethane project developers, municipal utility planning officers, agricultural cooperative procurement leads, and membrane upgrading equipment suppliers. Primary fieldwork combined with secondary validation from Bundesnetzagentur tariff review records, Danish district heating cooperative annual reports, and Dutch TTF pricing data. Bottom-up plant-level capacity aggregation and top-down policy-target alignment provided cross-check triangulation.
Variance decomposition across feedstock type, upgrading technology, end-user segment, and regional regulatory framework shaped the analytical framework over the projection horizon. Modeled segmentation dimensions included manure versus food waste feedstock sourcing, membrane versus amine upgrading technology selection, grid injection versus vehicle fuel offtake contracting, and national biomethane target compliance status. CAGRs derived from capacity buildout trajectories anchored to REPowerEU's 35 billion cubic meter mandate and project finance lender requirements for 10-year purchase agreements.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal policy commitment, stable TTF-indexed contract availability, and uninterrupted ISCC EU certification pathway access would require recalibration. Forecasts reflect assumptions regarding feedstock transport cost stability, membrane technology cost curves, and hydrogen-biomethane regulatory interaction. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioenergy
Global Biomass Briquette Market
Bioenergy
Biogas Market
Bioenergy
Organic Biogas Market
Bioenergy
Bio CHP Market
Bioenergy
Biopellets Energy Market
Bioenergy
Biopower Market
Bioenergy
Bioenergy Market
Bioenergy
Europe Bioenergy Market
Bioenergy
Micro-Scale Biogas Plant Market
Bioenergy
Biomass Wood Chip Market
Bioenergy
Biomass Molding Fuel Market
Bioenergy
Biomass Solid Fuel Market