
 Europe Coal Market | 2026-2036
Europe Coal Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Coal Market Foresight
Power purchase agreements with embedded carbon hedges are reshaping who can finance coal-fired generation in Europe. Suek AG leverages its integrated mining and logistics footprint to sustain deliveries into Central European utilities. Jastrzębska Spółka Węglowa SA anchors premium hard coal supply to steelmakers in Poland and Germany. Mitteldeutsche Braunkohlengesellschaft mbH dominates lignite extraction in eastern Germany's remaining open-cast operations.
Europe coal encompasses solid fossil fuels with carbon content ranging from lignite's 25-35% to anthracite's 86-97%, formed through progressive burial and thermal maturation of organic matter over geological timescales. Bituminous grades serve metallurgical coke production and high-efficiency power generation, while lignite feeds mine-mouth power plants with lower energy density but minimal transport cost. Lignite extraction occupies the largest volume share across Germany and Poland due to shallow deposits and established surface mining infrastructure. Metallurgical-grade bituminous coal generates disproportionate margin pools as steelmakers face limited substitution options for blast furnace coke. Residential heating demand through wholesale and direct sales channels contracts steadily as EU member states enforce building efficiency mandates and ban solid fuel combustion in urban zones.
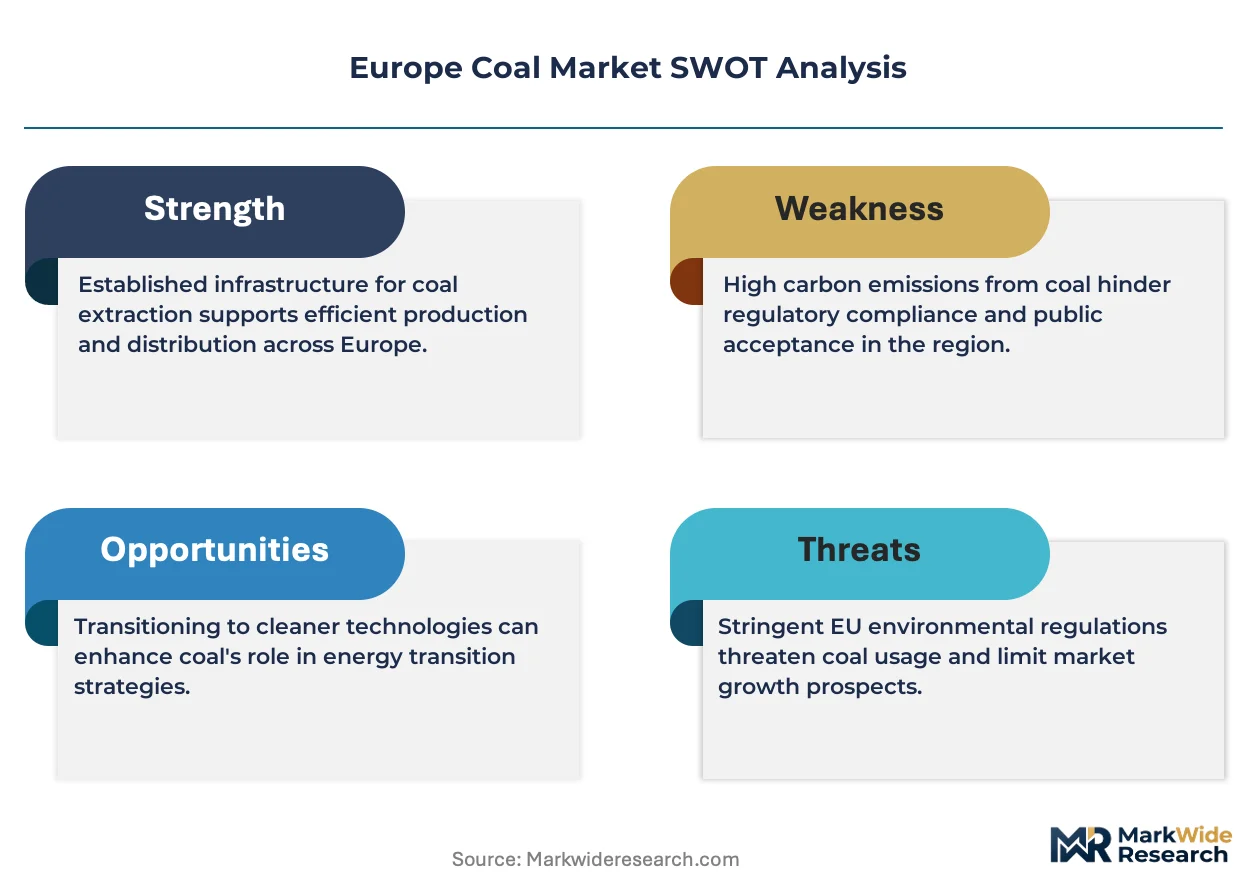
The EU Emissions Trading System caps and prices CO2 from coal combustion, while the F-Gas Regulation and national coal exit laws in Germany, Poland, and the Czech Republic mandate plant retirements or conversions. REACH and the EU Green Deal framework restrict coal use in industrial processes by embedding carbon border adjustments and clean hydrogen substitution targets. Stakeholders must monitor carbon price volatility and national subsidy regimes for just-transition coal regions to calibrate asset retirement timelines and workforce retraining investments.
Market Dynamics
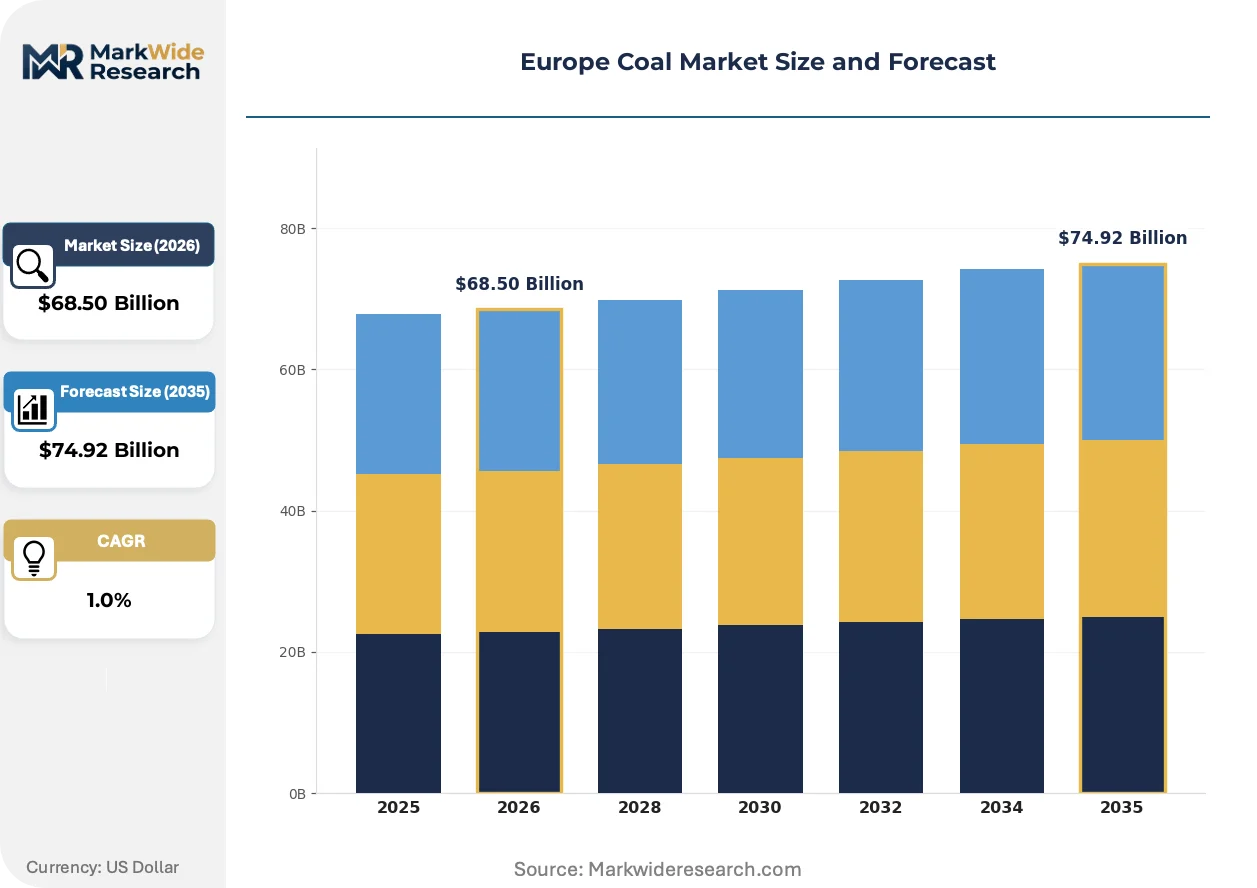
The EU Emissions Trading System compresses investment horizons for coal-fired assets while Poland's Silesian corridor sustains baseload demand through cost advantages over imported natural gas. Utilities face simultaneous pressure from carbon pricing mechanisms and national phase-out mandates.
Growth Catalysts
- Baseload power security:Poland and Germany retain coal-fired capacity to hedge against natural gas supply volatility and renewable intermittency, preserving operational fleets through capacity-market payments.
- EU Green Deal just-transition funding:Subsidies for coal-dependent regions in Silesia and Lusatia extend operational timelines for politically sensitive mines and power plants.
- Metallurgical coke demand:Steelmakers in the Rhine-Ruhr and Upper Silesia lack scalable substitutes for blast furnace coke, anchoring premium bituminous coal consumption.
Market Restraints
- EU ETS carbon price volatility:Compliance costs for coal combustion erode plant economics and deter long-term maintenance capital.
- German lignite supply concentration:Mitteldeutsche Braunkohlengesellschaft mbH dominates eastern German open-cast operations, creating single-source dependency for mine-mouth power plants.
- Natural gas substitution:LNG infrastructure expansion and pipeline diversification enable fuel switching at dual-fired power stations.
Strategic Opportunities
- Carbon capture retrofits:Poland's Bełchatów and Turów plants pilot post-combustion capture to extend asset life under EU decarbonization frameworks.
- Hydrogen-coal co-firing:Pilot projects in the Czech Republic blend hydrogen into coal gasification for steel-sector feedstock transition.
- District heating integration:Combined heat and power plants in Kraków and Katowice convert stranded coal assets into thermal energy hubs serving municipal networks.
Industry Challenges
- Workforce transition timelines:Mining regions in Silesia and Lusatia face compressed retraining windows as EU Green Deal deadlines accelerate plant closures.
- Grid stability obligations:System operators in Poland must balance coal decommissioning with synchronous inertia requirements for renewable-heavy networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Coal Market |
| Market Size in 2026 | $68.50 Billion |
| Market Size in 2035 | $74.92 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bituminous, Anthracite, Lignite, Sub-bituminous End User: Power Generation, Steel Manufacturing, Cement Industry, Residential Heating Distribution Channel: Direct Sales, Wholesale, Retail, E-commerce Quality Grade: High-Calorific, Low-Calorific, Metallurgical, Other |
| Companies Covered | Suek AG, UK Kuzbassrazrezugol OAO, Mitteldeutsche Braunkohlengesellschaft mbH (MIBRAG), Lubelski Wegiel Bogdanka SA, Jastrzębska Spółka Węglowa SA, HMS Bergbau AG, Bumech SA, Coal Energy SA, Ruzy Madencilik ve Enerji Yatirimlari Sanayi ve Ticaret AS, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Coal Market Shifts & Advancements
Carbon border adjustments and hydrogen substitution mandates are reconfiguring how coal-derived products enter European supply chains. Technology deployment now focuses on emission containment rather than combustion efficiency alone.
Post-combustion carbon capture technology is collapsing the operational lifespan calculus for existing coal-fired stations. Polish utilities pilot amine-based capture at Bełchatów to qualify for EU Innovation Fund support. The technology enables continued baseload dispatch under tightening ETS caps.
REACH and the EU Green Deal embed carbon border adjustment mechanisms that penalize imported steel and cement with embedded coal emissions. German manufacturers face compliance costs that favor domestic low-carbon production. The regulation accelerates scrap-based electric arc furnace investment in the Rhine-Ruhr.
Utility procurement now favors short-term fuel supply contracts with embedded carbon hedges. Central European power generators abandon long-term offtake agreements with mining groups. The shift concentrates in Poland's Silesian corridor where spot market liquidity supports flexible sourcing.
Europe Coal Market Segmentation
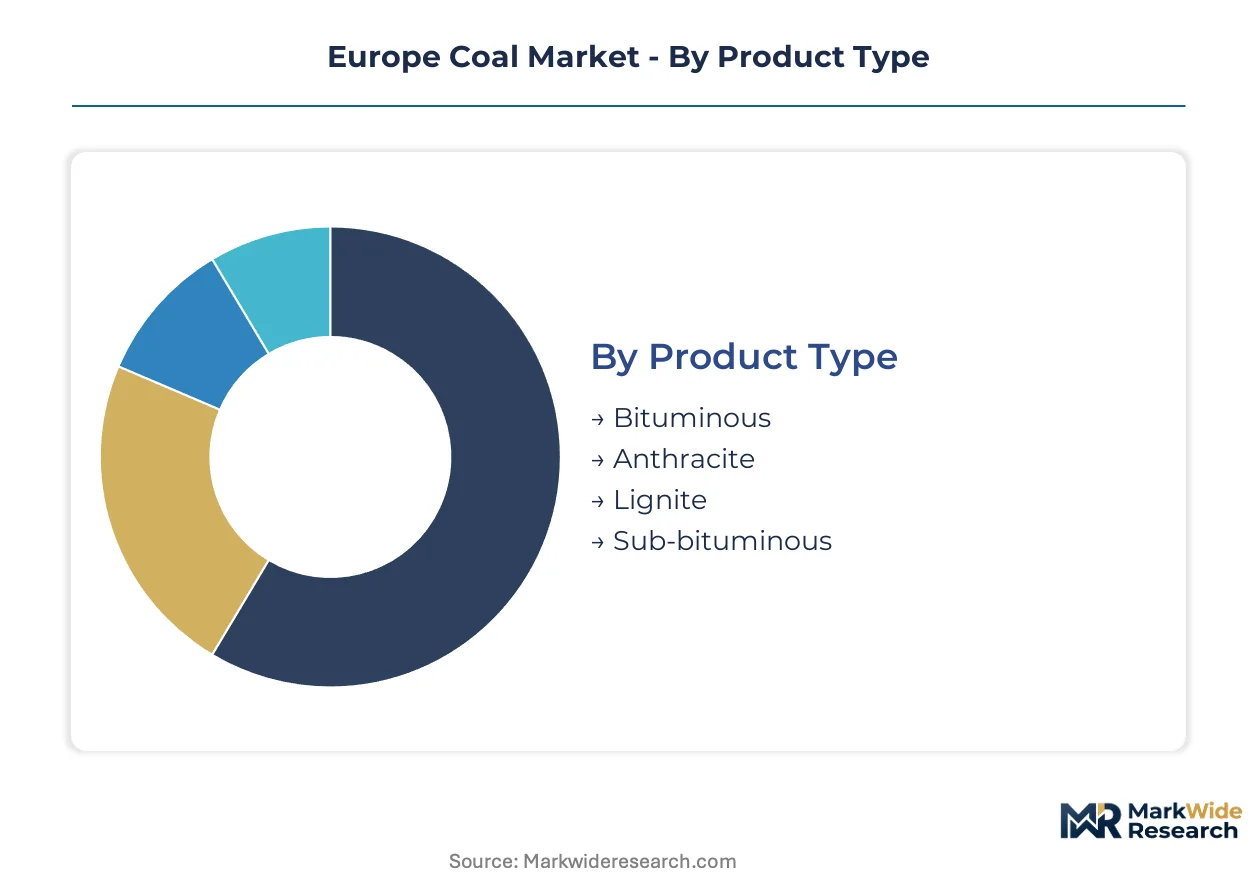
Coal segmentation in Europe reflects divergent fates across combustion technologies and regulatory exposure. Product quality and end-use application determine which segments retain commercial viability under tightening EU ETS caps and national phase-out mandates.
Product Type:
Cost tier stratification separates premium thermal grades from marginal lignite volumes facing accelerated retirement timelines.
- Bituminous:Higher carbon content (45-86%) and energy density make this grade essential for metallurgical coke production and efficient power generation. Demand concentrates in Poland's Silesian corridor where steelmakers and utilities prize its combustion characteristics over lignite alternatives. The segment commands pricing premiums that partially offset carbon compliance costs.
- Anthracite:Highest carbon concentration (86-97%) and lowest volatile matter deliver superior thermal efficiency for specialized industrial applications. Residential heating demand in rural Poland and the Czech Republic sustains niche volumes despite urban combustion bans spreading across EU member states.
- Lignite:Shallow deposits in eastern Germany enable low extraction costs, though 25-35% carbon content limits efficiency. Mine-mouth power plants at Bełchatów and Turów depend on this feedstock.
- Sub-bituminous:Intermediate properties find limited European application; imports serve small-scale industrial boilers in border regions.
Bituminous holds installed capacity. Lignite is rotating up the share rankings for phase-out urgency.
End User:
Application exposure to carbon pricing and substitution technology divides segments between terminal decline and structural persistence.
- Power Generation:Utilities across Poland and Germany operate the remaining fleet under capacity market payments and grid stability obligations. Bełchatów and Turów plants pilot carbon capture to extend operational windows against EU Green Deal deadlines.
- Steel Manufacturing:Blast furnace coke demand anchors premium bituminous consumption in the Rhine-Ruhr and Upper Silesia where hydrogen substitution remains uneconomical at scale. This segment exhibits the strongest resistance to fuel switching.
- Cement Industry:Clinker kilns in Poland and the Czech Republic blend coal with alternative fuels; EU ETS compliance accelerates waste-derived feedstock adoption.
- Residential Heating:Direct combustion faces prohibition in urban zones under building efficiency mandates; rural volumes contract steadily.
Steel manufacturing exhibits the steepest margin protection. Residential heating is climbing fastest toward obsolescence.
Distribution Channel:
Customer type and procurement scale determine contract structures and carbon hedge integration.
- Direct Sales:Long-term offtake agreements between mining groups and power utilities dominate volume flows in Poland's Silesian corridor.
- Wholesale:Aggregators serve smaller industrial consumers and district heating operators across Central Europe.
- Retail:Bagged coal for residential heating contracts as municipal bans proliferate.
- E-commerce:Minimal penetration; regulatory complexity and bulk logistics favor established trading relationships.
Direct sales concentrate contract value. Wholesale is ascending as utilities shorten procurement horizons.
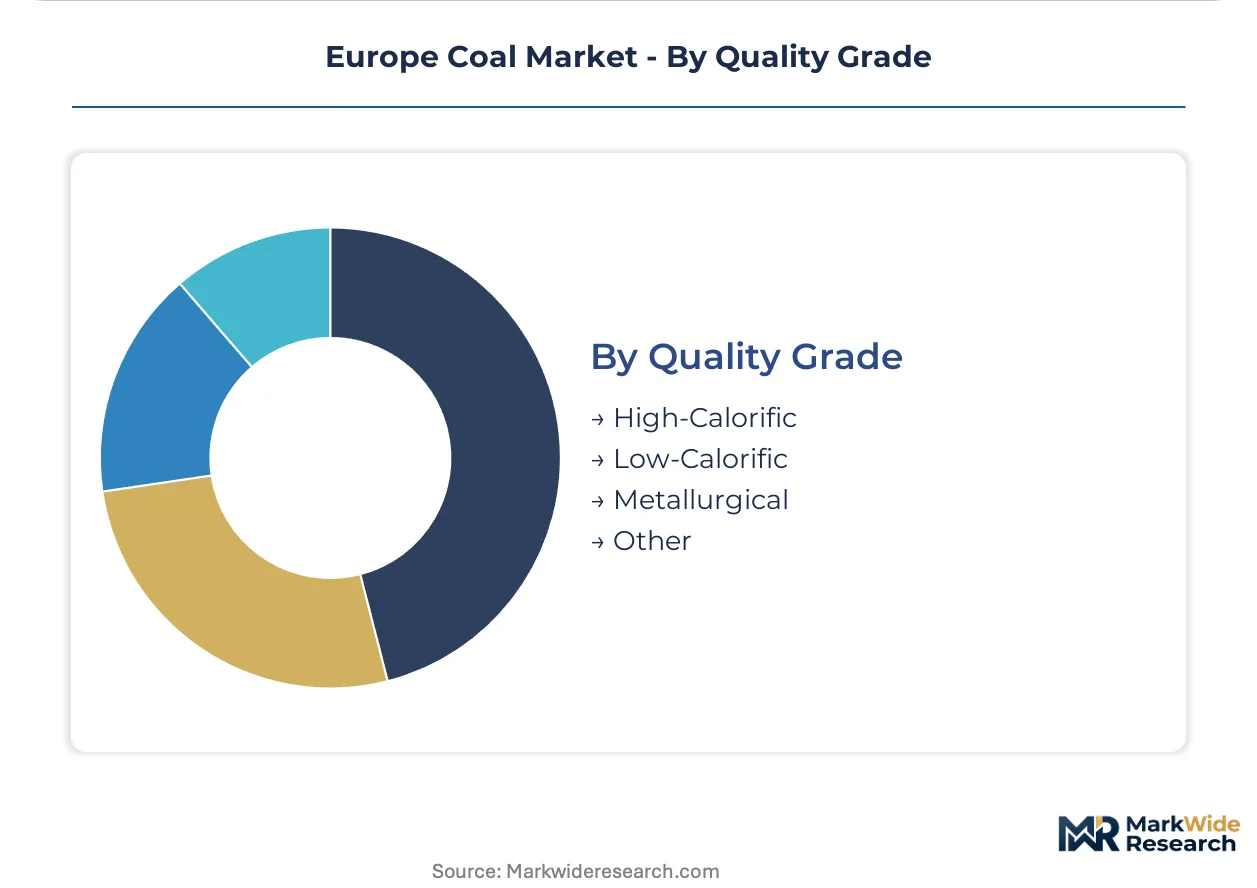
Quality Grade:
Specification tier determines eligibility for premium applications and carbon intensity calculations under EU ETS verification.
- High-Calorific:Superior energy density supports efficient combustion in advanced supercritical plants and metallurgical processes. Steelmakers in Germany and Poland specify these grades for coke quality consistency.
- Metallurgical:Low-ash, low-sulfur specifications mandatory for blast furnace coke production. Jastrzębska Spółka Węglowa SA and comparable suppliers command durable demand from integrated steelworks.
- Low-Calorific:Lignite and sub-bituminous grades serve mine-mouth power generation with minimal transport economics.
- Other:Specialty grades for activated carbon and chemical feedstock applications.
Metallurgical grade secures replacement demand. High-calorific is gaining share fastest among thermal segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal just-transition funding and national coal phase-out laws are compressing operational timelines across Central and Eastern Europe. Poland and Germany retain the largest installed coal-fired capacity. Utilities in both countries navigate carbon price volatility through capacity market mechanisms and grid stability obligations.
Poland
Poland's Silesian industrial corridor sustains baseload coal demand through cost advantages over imported natural gas for electricity and district heating. The EU Emissions Trading System caps CO2 emissions while national energy security priorities preserve operational fleets. Bełchatów and Turów plants pilot post-combustion carbon capture to extend asset life under tightening decarbonization deadlines.
Germany
German lignite extraction concentrates in eastern open-cast operations serving mine-mouth power plants with minimal transport economics. The national coal exit law mandates plant retirements by 2038, though recent energy security revisions have delayed some closures. Lusatia's industrial clusters face compressed workforce retraining windows as EU Green Deal subsidies attempt to smooth the transition.
Czech Republic
Czech steelmakers and power utilities anchor bituminous coal consumption despite EU ETS compliance cost pressures. The F-Gas Regulation and national decarbonization targets accelerate alternative fuel adoption in cement and industrial heat applications. Hydrogen-coal co-firing pilots in North Bohemia test feedstock transition pathways for the steel sector.
Romania
Romania's Jiu Valley mining region retains limited hard coal production for domestic power generation and industrial customers. REACH restrictions and building efficiency mandates phase out residential heating demand in urban centers. Oltenia's lignite complex struggles with carbon intensity calculations under EU ETS verification protocols.
Bulgaria
Bulgarian power utilities operate aging coal fleets under grid stability obligations for renewable-heavy networks. The EU Green Deal framework restricts access to transition funding without accelerated retirement commitments. Maritsa Iztok's mining and generation complex represents the largest concentration of lignite-dependent employment in Southeast Europe.
Europe Coal Market Competitive Landscape
On the supply side, the industry is consolidating around integrated mining-logistics operators and state-affiliated extraction groups with captive utility relationships. Strategic archetypes divide between premium metallurgical-grade suppliers serving steelmakers and volume-driven lignite operators feeding mine-mouth power plants. Dominant competitive moves include portfolio diversification into carbon capture equipment partnerships and geographic contraction to core baseload demand corridors.
Within the integrated mining-logistics tier, Suek AG anchors supply deliveries into Central European utilities through its cross-border rail and port infrastructure. Jastrzębska Spółka Węglowa SA exemplifies the premium hard coal archetype with metallurgical-grade positioning for steel sector customers. Mitteldeutsche Braunkohlengesellschaft mbH occupies the lignite extraction position in eastern Germany's remaining open-cast operations.
| Leading Market Players |
|---|
| Suek AG |
| UK Kuzbassrazrezugol OAO |
| Mitteldeutsche Braunkohlengesellschaft mbH (MIBRAG) |
| Lubelski Wegiel Bogdanka SA |
| Jastrzębska Spółka Węglowa SA |
| HMS Bergbau AG |
| Bumech SA |
| Coal Energy SA |
| Ruzy Madencilik ve Enerji Yatirimlari Sanayi ve Ticaret AS |
| Others |
Supply & Pricing Matrix
Upper Silesia's mining cluster anchors thermal coal supply into Polish utilities, concentrating pricing power among state-affiliated extraction groups while EU ETS compliance costs compress margins across the value chain. The interplay between carbon border adjustments and mine-mouth logistics determines which grades retain commercial viability against imported natural gas alternatives.
Pricing Analysis
Carbon intensity certification under EU ETS verification protocols creates the primary spread between metallurgical and thermal grades, with blast furnace coke specifications commanding substantial premiums over lignite alternatives. Contract structures have shifted toward short-term offtake agreements with embedded carbon hedges as utilities abandon long-term procurement commitments. Cost compression in lignite supply is intensifying because mine-mouth power plants face accelerated retirement timelines under national phase-out laws. Industrial steelmakers exhibit the least price sensitivity due to limited substitution options for blast furnace feedstock, while district heating operators demonstrate highest sensitivity to fuel switching economics.
Supply Chain Analysis
Single-source dependency on Mitteldeutsche Braunkohlengesellschaft mbH for eastern German lignite extraction dominates supply chain risk assessment for Central European power generators. Geographic supply concentration centers on Poland, Germany, and the Czech Republic for bituminous extraction, with shallow lignite deposits concentrated in Germany's Lusatia region. Raw material dependencies draw from specialized mining equipment, ammonium nitrate explosives, and diesel fuel for overburden removal operations. Distribution runs through captive rail networks linking Silesian mines to power plants and steelworks, supplemented by barge transport along the Oder and Vistula river systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has concentrated among integrated steelmakers and state-backed utilities, fragmenting procurement leverage for smaller industrial consumers and district heating cooperatives.
For Market Incumbents: Entrench metallurgical-grade supply relationships with Rhine-Ruhr and Upper Silesian steelworks through long-term coke quality guarantees, while accelerating carbon capture partnerships at Bełchatów and Turów to qualify for EU Innovation Fund support. Hydrogen substitution pilots in the Czech Republic threaten premium bituminous demand; defend position through backward integration into mine-mouth power generation assets. For New Entrants and Emerging Players: Southeast European district heating markets in Bulgaria and Romania present the most penetrable white-space opportunity, where aging lignite fleets face compressed replacement windows and municipal procurement favors flexible short-term contracts. Carbon capture equipment retrofit services offer a specialized entry angle, leveraging Polish pilot project experience to serve utilities across the broader region. For Investors and Strategic Acquirers: Long-term, this sits as a managed-decline cash-extraction play because metallurgical coke demand anchors durable margin pools even as thermal generation volumes contract toward terminal phase-out deadlines. Target acquisition archetypes include premium hard coal operators with steel sector offtake concentration and minimal thermal power exposure. The signal to watch is hydrogen-based direct reduction steelmaking cost curves crossing blast furnace economics in the Rhine-Ruhr cluster.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit Deployment | Polish utilities at Bełchatów pilot amine-based systems to extend asset life under tightening EU ETS caps. |
| Metallurgical Supply Agreement Extension | Jastrzębska Spółka Węglowa SA anchors premium bituminous contracts with Upper Silesian blast furnace operators. |
| Hydrogen-Coal Co-firing Pilot | Czech steelmakers in North Bohemia test feedstock transition pathways for hydrogen-enriched gasification processes. |
| District Heating Asset Conversion | Combined heat and power plants in Kraków repurpose stranded coal infrastructure for municipal thermal network service. |
| Just-Transition Workforce Retraining | Lusatia and Silesian mining regions deploy EU Green Deal subsidies to accelerate plant closure timelines. |
Research Methodology
Operator-level perspectives from utility fuel procurement officers, steel plant raw materials managers, mining operations directors, and EPC contractors anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews across Poland's Silesian corridor and Germany's Lusatia region with secondary validation from EU ETS transaction registries, national energy regulator filings, and customs trade data for coal imports. Bottom-up volume estimates from individual mine and power plant operations were triangulated against top-down consumption figures from Eurostat energy balances and IEA coal market reports.
Scenario bracketing around carbon price volatility, national phase-out schedule revisions, and hydrogen substitution economics framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product quality grade, end-use application exposure, and regional regulatory framework intensity. CAGRs were derived from trend extrapolation of historical production and consumption patterns, adjusted for announced plant retirement schedules and steel sector demand elasticity assumptions. Industry-specific forecast inputs incorporated EU Innovation Fund disbursement timelines and REACH restriction implementation calendars.
The forecast holds incumbent behavior within observed patterns; aggressive acceleration of hydrogen-based steelmaking by German manufacturers or unilateral Polish withdrawal from EU ETS compliance would shift outcomes materially from projected baseload demand retention. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Global Methane Hydrate Market
Fuels
LPG Gas Cylinder Market
Fuels
Charcoal Briquette Market
Fuels
Ethyl Tertiary Butyl Ether Market
Fuels
China Coal Market
Fuels
India LNG Market
Fuels
North America Oil and Gas Lubricants Market
Fuels
Singapore Bunker Fuel Market
Fuels
Europe Bunker Fuel Market
Fuels
Coal Intelligent Dry Separators Market
Fuels
Alcohol-To-Jet (ATJ) Fuel Market
Fuels
South America Bunker Fuel Market
Fuels
Solid Recovered Fuel Market
Fuels
Gasoline Market
Fuels
United States LNG Bunkering Market
Fuels
Underground Coal Gasification Market