
 Europe Biomethane Market | 2026-2036
Europe Biomethane Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Biomethane Market Analysis
Long-term offtake contracting is shifting how biomethane value gets captured across Europe. ENGIE SA leverages its utility scale to secure pipeline interconnection priority in France. Waga Energy sustains technology leadership through proprietary membrane upgrading systems deployed at landfill sites. EnviTec Biogas AG anchors its position with integrated engineering, construction, and operational service packages across German agricultural digesters.
Biomethane denotes biogas refined to methane concentrations exceeding 90 percent through pressure swing adsorption, water scrubbing, or membrane separation, yielding a pipeline-compatible substitute for geological natural gas in heating, transport, and industrial feedstock applications. Upgraded biogas dominates current European volume owing to mature anaerobic digestion infrastructure and established grid injection protocols. Renewable natural gas from thermal gasification occupies a nascent but expanding margin pool as woody biomass conversion achieves commercial scale. Bio-CNG for transportation fuels commands premium pricing in markets where member states enforce renewable fuel mandates under the EU Green Deal framework.
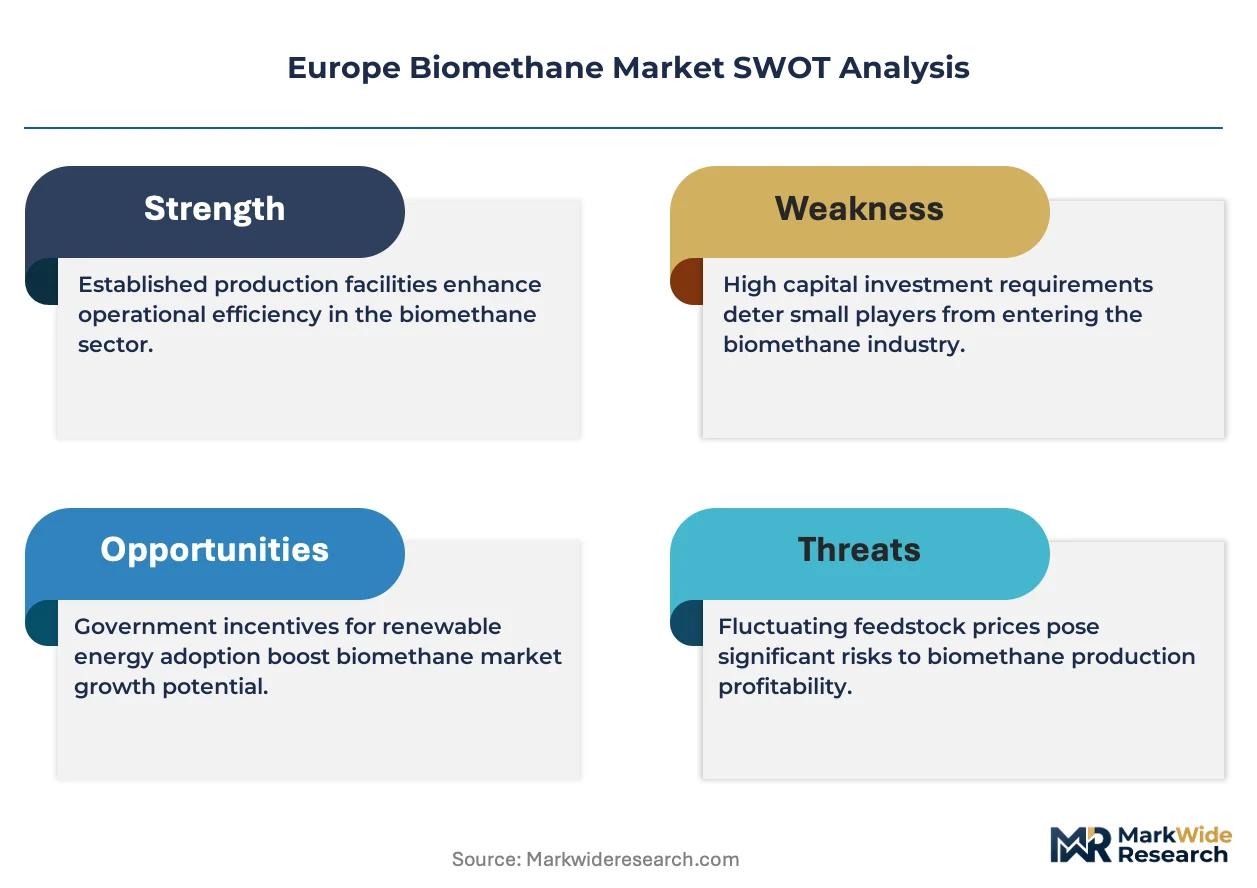
The EU Green Deal and Renewable Energy Directive establish binding targets that compel utilities to source specified shares of gas supply from renewable origins, while EMA guidelines and national regulators in Germany and France certify grid injection quality standards. REACH compliance for upgrading chemical agents and CE marking for compression equipment further condition market access for technology providers. Stakeholders must monitor the trajectory of national carbon border adjustments and hydrogen blending mandates to calibrate capital allocation between biomethane and competing low-carbon gases.
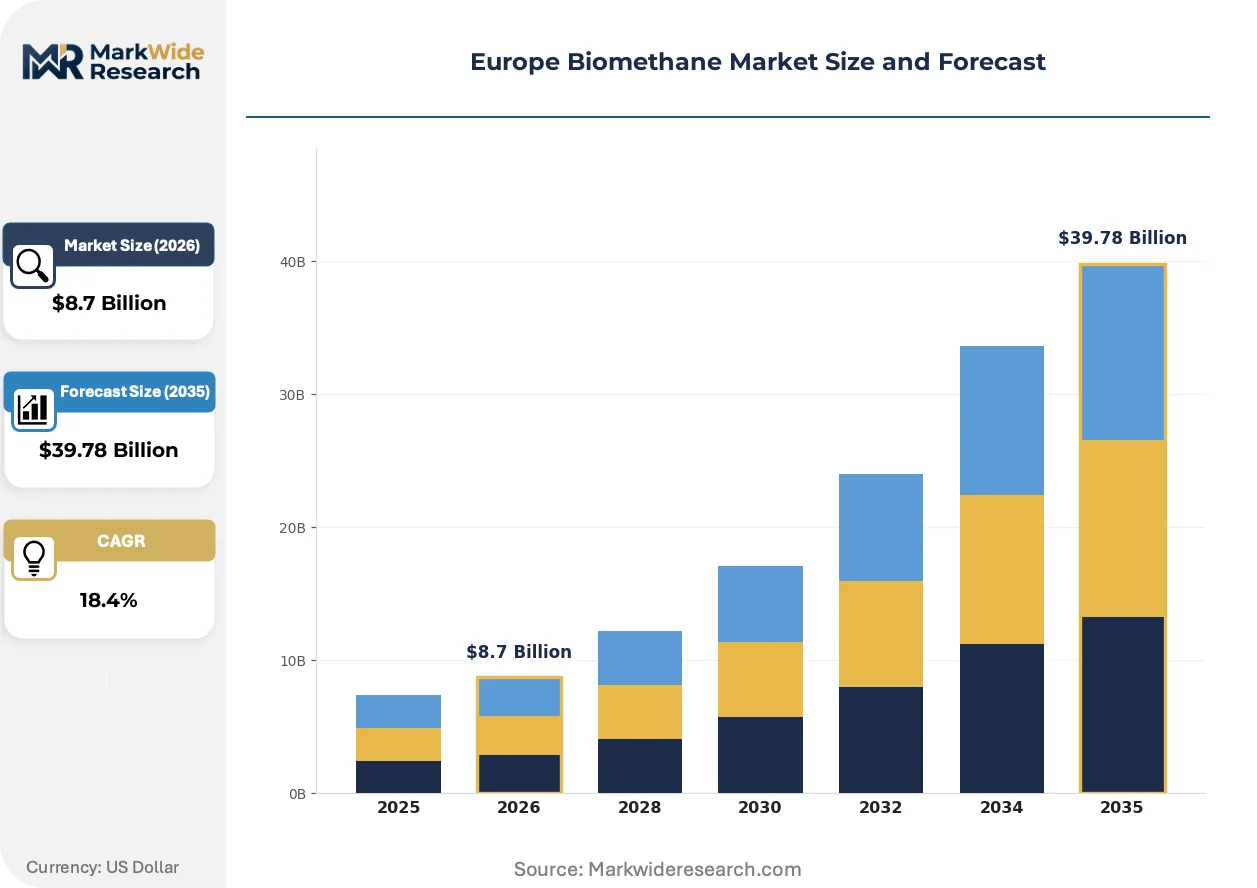
Market Dynamics
Grid injection tariff guarantees in Denmark and France are concentrating capital flows among upgrading technology providers, while transport fleet procurement of bio-CNG under EU Green Deal mandates is compressing payback periods for anaerobic digestion investments.
Growth Catalysts
- EU Green Deal transport mandates:Binding renewable fuel quotas for heavy-duty logistics fleets in Germany and the Netherlands are pulling bio-CNG volumes into dedicated refueling corridors.
- Membrane upgrading systems:Proprietary separation technologies are reducing methane slip losses below 0.5 percent, improving project economics at landfill and agricultural digester sites.
- France grid priority access:Pipeline interconnection tariffs guarantee offtake for biomethane producers meeting CE-marked compression and REACH-compliant chemical upgrading standards.
Market Restraints
- Feedstock cost volatility:Agricultural residue and organic waste supply contracts face seasonal price swings that destabilize digester project finance models.
- Electrolyzer substitution threat:Green hydrogen blending mandates under EU hydrogen strategy are diverting utility R&D budgets away from biomethane grid injection.
- Grid connection queues:Distribution network operators in Germany and Italy are delaying injection point commissioning by 18-24 months due to capacity constraints.
Strategic Opportunities
- Polish agricultural corridor:Untapped manure-to-biomethane potential across Polish livestock regions lacks upgrading infrastructure but offers low feedstock acquisition costs.
- Industrial heat offtake:Cement and steel producers under EU carbon border adjustment mechanisms are sourcing biomethane for process heat to avoid import tariffs.
- Power-to-gas convergence:Electrolyzer-biogas hybrid systems combining renewable hydrogen with biogenic CO2 are opening synthetic methane pathways for hard-to-abate sectors.
Industry Challenges
- Upgrading technician scarcity:Pressure swing adsorption and water scrubbing operations require specialized maintenance skills that vocational training programs have not scaled to match deployment rates.
- Certification timeline compression:EMA quality standards and national regulator audits for grid injection are extending project commissioning by 8-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Biomethane Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upgraded Biogas, Renewable Natural Gas, Bio-CNG, Bio-SNG Application: Transportation Fuels, Power Generation, Heating, Industrial Uses End User: Utilities, Transport Sector, Residential, Commercial Production Method: Anaerobic Digestion, Gasification, Fermentation, Upgrading Technologies |
| Companies Covered | ENGIE SA, Waga Energy, EnviTec Biogas AG, E.ON SE, Gasrec Ltd, VERBIO SE, Nature Energy Biogas A/S, Air Liquide S.A., Future Biogas Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Biomethane Market Emerging Trajectories
Technology providers are fragmenting the upgrading value chain while regulatory pressure compresses certification timelines and industrial buyers rewrite procurement terms around carbon intensity guarantees.
Modular membrane upgrading skids are decentralizing biomethane production economics by enabling sub-500 Nm3/hour deployments at distributed agricultural digesters previously excluded from grid injection economics. Danish and French farm cooperatives are adopting containerized units on lease structures rather than capex ownership. This shift is decentralizing project development away from centralized utility-led models toward asset-light operator partnerships.
EU F-Gas Regulation phase-down schedules are restricting hydrofluorocarbon use in biomethane liquefaction and cooling systems, forcing technology providers to redesign compression trains around natural refrigerants. Equipment manufacturers are accelerating R&D partnerships with industrial gas specialists to certify alternative cooling cycles. Food-grade CO2 offtake agreements from upgrading plants are facing the steepest compliance cost increases under this transition.
Carbon intensity scoring is restructuring how transport fleet operators evaluate bio-CNG supply contracts, with German logistics buyers now mandating third-party verified lifecycle emissions below 20 gCO2eq/MJ. Traditional volume-based tenders are losing share to index-linked agreements tied to certified feedstock traceability. This recalibration is most visible in Netherlands-Germany cross-border haulage corridors where renewable fuel mandates enforce strict sustainability criteria.
Europe Biomethane Market Segmentation
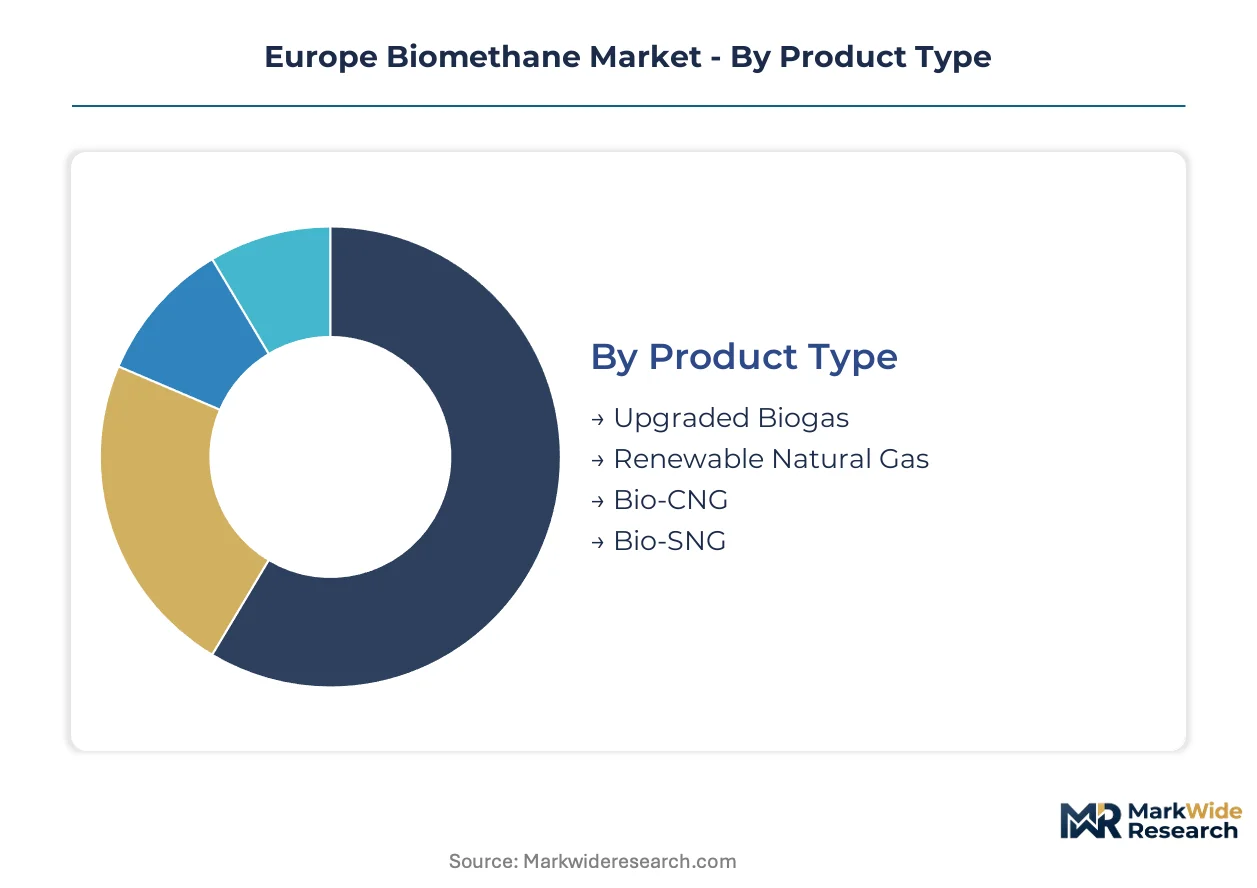
Biomethane value chains fragment across four critical dimensions where production method determines cost structure, product type shapes grid compatibility, and application dictates pricing power against fossil alternatives. Segment boundaries are shifting as membrane upgrading and hybrid electrolyzer systems redraw competitive economics.
Product Type:
Volume concentration favors pipeline-grade methane substitutes, while premium capture clusters in transport fuels where EU Green Deal mandates enforce renewable quotas.
- Upgraded Biogas:Refined biogas achieving methane purity above 90 percent through pressure swing adsorption, water scrubbing, or membrane separation. Danish and French farm cooperatives dominate procurement under guaranteed grid injection tariffs that de-risk anaerobic digestion capex.
- Bio-CNG:Compressed biomethane for vehicle fuel dispensing at pressures exceeding 200 bar. German and Dutch heavy-duty logistics fleets are scaling offtake along dedicated refueling corridors where renewable fuel mandates bind fleet operators to specified biomethane blends.
- Renewable Natural Gas:Pipeline-injectable biomethane meeting EMA quality standards and national regulator specifications for geological natural gas substitution. Grid connection queues in Germany and Italy currently constrain deployment velocity.
- Bio-SNG:Synthetic natural gas derived from woody biomass gasification with methanation. Thermal conversion pathways occupy nascent commercial scale as lignocellulosic feedstock processing achieves technical maturity.
Mature deployment sits with Upgraded Biogas. Newer deployment is concentrated in Bio-SNG.
Application:
Transport fuel premiums exceed heating value by 40-60 percent where member states enforce binding renewable quotas, while industrial heat offtake is accelerating under carbon border adjustment exposure.
- Transportation Fuels:Bio-CNG and bio-LNG dispensing for heavy-duty road freight and maritime bunkering. Netherlands-Germany haulage corridors enforce third-party verified lifecycle emissions below 20 gCO2eq/MJ, restructuring procurement toward certified feedstock traceability.
- Industrial Uses:Process heat and chemical feedstock substitution in cement, steel, and ammonia production. EU carbon border adjustment mechanisms are pulling biomethane into import-competing sectors seeking tariff avoidance.
- Heating:Residential and commercial building heat through natural gas grid injection or localized district heating. Seasonal demand peaks align with agricultural digester output cycles in German and Polish livestock regions.
- Power Generation:Combined heat and electricity production in gas engines and turbines. Grid balancing services are emerging as ancillary revenue streams where biomethane storage buffers renewable intermittency.
Heating applications anchor current volume. Industrial uses are gaining share fastest.
End User:
Utility offtake guarantees underwrite project finance, while transport sector procurement compresses payback periods through mandate-linked premium pricing.
- Utilities:Grid operators and gas distribution companies sourcing renewable gas to meet EU Green Deal and Renewable Energy Directive binding targets. ENGIE SA leverages pipeline interconnection priority in France to secure feedstock aggregation.
- Transport Sector:Fleet operators and fuel retailers procuring bio-CNG under Germany's KBA-enforced renewable fuel quotas and Netherlands' renewable transport fuel obligations. Carbon intensity scoring now dominates contract terms over volume-based tenders.
- Residential:Household consumers accessing biomethane through blended natural gas supply or dedicated green gas tariffs. Danish cooperative ownership models distribute value capture among agricultural feedstock providers.
- Commercial:Hotels, hospitals, and manufacturing facilities seeking Scope 1 emissions reduction. Corporate renewable power purchase agreements are extending into biomethane procurement for thermal decarbonization.
Utility contracting dominates financing structures. Transport sector offtake is climbing the fastest.
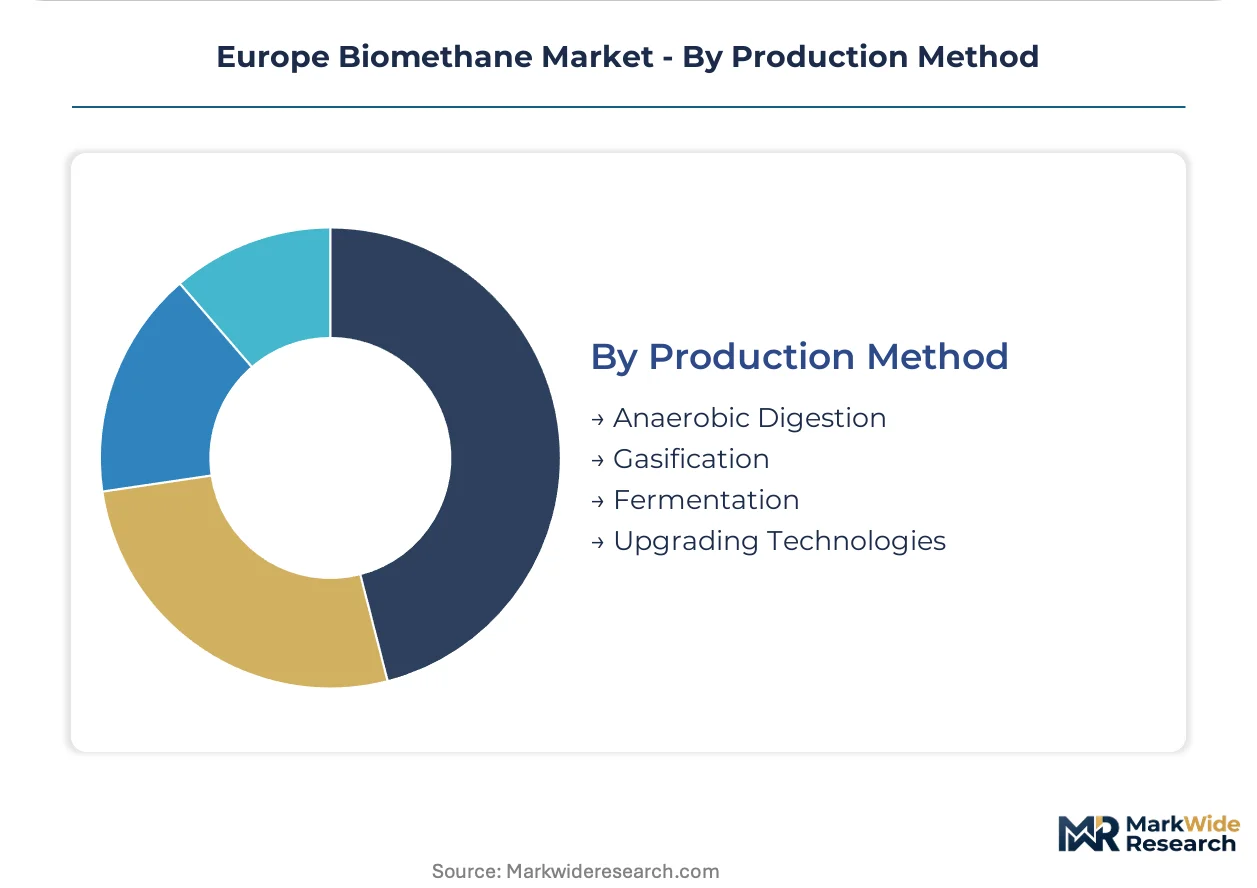
Production Method:
Anaerobic digestion concentrates in agricultural corridors with established waste collection infrastructure, while gasification development clusters where woody biomass supply chains achieve scale.
- Anaerobic Digestion:Microbial decomposition of organic feedstocks in oxygen-free environments yielding raw biogas for subsequent upgrading. German agricultural digesters anchor European volume through integrated engineering and operational service ecosystems.
- Upgrading Technologies:Pressure swing adsorption, water scrubbing, and membrane separation systems refining raw biogas to pipeline specifications. Proprietary membrane systems from technology providers are reducing methane slip below 0.5 percent.
- Gasification:High-temperature partial oxidation of lignocellulosic biomass producing syngas for methanation. Woody biomass conversion is achieving commercial scale in Nordic regions with established forest residue logistics.
- Fermentation:Biochemical conversion of sugars and starches to methane through specialized microbial cultures. Food waste and dedicated energy crop streams feed emerging deployments where feedstock segregation infrastructure exists.
Mature deployment sits with Anaerobic Digestion. Newer deployment is concentrated in Gasification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters in northwestern Europe supply upgrading capacity, while consumption concentrates in transport corridors and industrial zones where grid injection tariffs and carbon border mechanisms pull biomethane volumes. The mismatch between agricultural feedstock availability and industrial demand centers is reshaping pipeline interconnection priorities.
Germany
Agricultural digesters in Lower Saxony and Bavaria anchor European anaerobic digestion volume through integrated engineering ecosystems. The KBA enforces renewable fuel quotas that bind heavy-duty logistics fleets to specified bio-CNG blends. The Netherlands-Germany haulage corridor now mandates third-party verified lifecycle emissions below 20 gCO2eq/MJ, compressing payback periods for upgrading investments at farm cooperative sites.
France
Pipeline interconnection priority access under tariff guarantees is concentrating upgrading technology deployment in the Grand Est and Pays de la Loire agricultural regions. The ANSM certifies grid injection quality standards alongside CE-marked compression requirements. ENGIE SA leverages utility scale to secure feedstock aggregation contracts across the Île-de-France industrial perimeter.
Denmark
Farm cooperatives in Jutland are adopting containerized membrane upgrading skids on lease structures rather than capex ownership. National grid injection tariffs de-risk anaerobic digestion investments through guaranteed offtake mechanisms. The Nordic woody biomass corridor is piloting gasification-to-methanation pathways where forest residue logistics achieve commercial scale.
Netherlands
Rotterdam-Amsterdam transport logistics zones enforce renewable transport fuel obligations that pull bio-CNG volumes into dedicated refueling infrastructure. Carbon intensity scoring now dominates procurement terms over volume-based tenders in cross-border haulage contracts. Distribution network operators are managing grid connection queues that currently delay injection point commissioning.
Poland
Untapped manure-to-biomethane potential across Masovian and Greater Poland livestock regions offers low feedstock acquisition costs absent established upgrading infrastructure. Seasonal demand peaks for residential heating align with agricultural digester output cycles. Industrial heat offtake from cement and steel producers is emerging under EU carbon border adjustment exposure.
Europe Biomethane Market Vendor Landscape
Top-tier vendors anchor utility-scale grid injection, while mid-tier technology providers concentrate on modular upgrading systems for distributed agricultural sites. The vendor base stratifies across three tiers: integrated energy majors with pipeline priority access, specialized biogas engineering firms with captive EPC capabilities, and membrane technology licensors with asset-light deployment models. Dominant competitive moves include strategic partnerships for feedstock aggregation and geographic licensing of proprietary upgrading systems.
Within the integrated utility tier, ENGIE SA and E.ON SE exemplify players leveraging pipeline interconnection scale to secure offtake guarantees. Among specialized biogas engineering firms, EnviTec Biogas AG occupies a position representing integrated construction and operational service packaging across agricultural digesters. Waga Energy sits within the technology licensing archetype, with its proprietary membrane systems deployed at landfill upgrading sites.
| Leading Market Players |
|---|
| ENGIE SA |
| Waga Energy |
| EnviTec Biogas AG |
| E.ON SE |
| Gasrec Ltd |
| VERBIO SE |
| Nature Energy Biogas A/S |
| Air Liquide S.A. |
| Future Biogas Ltd. |
| Others |
Supply Flow & Price Mechanics
Family-owned farm cooperatives across Denmark and France anchor supply-side discipline through lease-structured containerized upgrading skids, compressing feedstock aggregation costs while grid injection tariffs stabilize offtake pricing. This ownership pattern concentrates bargaining power with agricultural producers and tightens margin capture for technology licensors competing on membrane system deployment economics.
Pricing Analysis
Cost-down pressure on bio-CNG transport fuels accelerates because German and Dutch fleet operators now mandate third-party verified lifecycle emissions below 20 gCO2eq/MJ, restructuring procurement toward certified feedstock traceability over volume-based tenders. Three-tier pricing structure across premium certified, standard grid-injectable, and economy non-certified grades reflects carbon intensity scoring and REACH compliance status as primary differentiation drivers. Margin tightening in standard-grade pipeline biomethane traces to grid connection queues in Germany and Italy extending commissioning timelines. Transport sector buyers exhibit lowest price sensitivity due to binding renewable fuel quotas, while residential heating consumers face highest sensitivity where green gas tariffs compete with conventional natural gas blending.
Supply Chain Analysis
CE marking for compression equipment and REACH compliance for upgrading chemical agents gate market access for component suppliers serving the European biomethane value chain. Manufacturing concentration centers on Germany, Denmark, and France where membrane upgrading system providers and anaerobic digestion engineering firms cluster near agricultural feedstock corridors. Raw material dependencies include specialized polymer membranes, biogas-compatible compressors, and chemical scrubbing agents for pressure swing adsorption systems. Single-source vulnerability sits with proprietary membrane technology licensors controlling methane slip performance below 0.5 percent. Distribution runs through utility-led grid injection partnerships in France and Denmark alongside transport corridor fuel retail networks in Germany and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biomethane market positioning is converging on vertical-integration races where players pursue captive feedstock aggregation to secure pipeline interconnection priority and compress certification timelines under EMA quality standards.
For Market Incumbents: Deepen backward integration into agricultural waste collection infrastructure across Polish and German livestock regions to preempt feedstock cost volatility and anchor digester project finance. Secure ANSM and KBA pre-certification pathways for membrane upgrading systems to compress grid connection queues threatening deployment velocity. Prioritize lease-structured equipment partnerships with farm cooperatives to defend against modular technology providers eroding utility-scale margins. For New Entrants and Emerging Players: Containerized membrane upgrading systems offer a technology-first wedge into Poland's untapped manure-to-biomethane corridor where low feedstock acquisition costs meet absent upgrading infrastructure. Target industrial heat offtake from cement and steel producers facing EU carbon border adjustment exposure as the most penetrable application segment. Pursue power-to-gas convergence partnerships combining electrolyzer-biogas hybrid architectures to differentiate from established anaerobic digestion engineering incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized membrane technology licensors with asset-light deployment models in Denmark and France where grid injection tariffs de-risk anaerobic digestion capex. Long-term viability hinges on 5-10 year trajectories of hydrogen blending mandates diverting utility R&D budgets and national carbon border adjustment enforcement tightening. Watch for inflection signals in German distribution network operator queue clearance rates and French pipeline interconnection tariff renegotiations.| Strategic Initiative | Industry Significance |
|---|---|
| Feedstock Aggregation Partnerships | Secures pipeline interconnection priority under French ANSM and German KBA certification pathways. |
| Modular Upgrading System Deployment | Enables sub-500 Nm3/hour installations at Polish agricultural digesters previously excluded from grid economics. |
| Industrial Heat Supply Contracts | Captures cement and steel producer demand under EU carbon border adjustment tariff avoidance strategies. |
| Power-to-Gas Hybrid Development | Combines renewable hydrogen with biogenic CO2 for synthetic methane pathways in hard-to-abate sectors. |
| Carbon Intensity Certification Investment | Meets German logistics buyer mandates for third-party verified emissions below 20 gCO2eq/MJ in transport fuels. |
Methodological Framework
Multi-period observation of grid injection tariff trajectories, feedstock contract pricing, and certification timeline compression anchored the trend analysis, supplemented by interviews with utility planning officers, anaerobic digestion plant managers, membrane technology R&D directors, and transport fleet procurement leads. Secondary validation drew from EU Green Deal implementation reports, EMA quality standard filings, KBA renewable fuel quota enforcement data, and ANSM grid connection records. Bottom-up project economics modeling and top-down regulatory obligation tracking were triangulated to calibrate segment-level demand projections.
Input-output matrices mapped anaerobic digestion capacity buildouts, upgrading technology deployment rates, and pipeline interconnection approvals across production method, product type, application, and end user dimensions over the projection horizon. CAGRs were derived from regression analysis of historical tariff guarantee adjustments and mandate enforcement intensity, incorporating feedstock availability indices and carbon intensity scoring adoption curves as biomethane-specific forecast inputs.
Several conditions sit outside the modeled scope, including unannounced revisions to EU hydrogen strategy blending mandates, abrupt carbon border adjustment mechanism expansion to additional industrial sectors, and force majeure disruptions to agricultural residue supply chains. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and technology cost reduction trajectories. A model refresh is warranted upon material change in German distribution network operator queue clearance rates or French pipeline interconnection tariff renegotiation outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
South Africa Solar Energy Market
Renewable Energy
Peru Renewable Energy Market
Renewable Energy
PV Water Heater Market
Renewable Energy
South Africa Wind Energy Market
Renewable Energy
Renewable Energy Inverters Market
Renewable Energy
France Renewable Energy Market
Renewable Energy
Biogas Upgrading Technology Market
Renewable Energy
Tidal Turbines Market
Renewable Energy
Portugal Renewable Energy Market
Renewable Energy
Turkey Renewable Energy Market
Renewable Energy
Solar Tracker Market
Renewable Energy
Solar Thermal Water Heater Market
Renewable Energy
Algeria Renewable Energy Market
Renewable Energy
Venezuela Renewable Energy Market
Renewable Energy
Drone Inspection Service for Renewable Energy Market
Renewable Energy
Austria Renewable Energy Market