
 Smart Gas Solutions Market | 2026-2036
Smart Gas Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Gas Solutions Market Analytics
Modular platform bundling is expanding as the dominant configuration pattern across smart gas deployments, with utilities preferring integrated meter-to-cash packages over standalone hardware procurement. Itron leverages its vertically integrated AMI software stack to anchor large-scale municipal contracts in North America. Landis+Gyr competes through deep manufacturing scale across European meter standards. Honeywell International differentiates via sensor fusion capabilities that combine gas leak detection with pressure monitoring in a single device architecture.
Smart gas solutions encompass networked measurement, monitoring, and control systems for natural gas and alternative fuel distribution, incorporating ultrasonic or diaphragm metering elements with temperature-pressure compensation accurate to within one percent across flow ranges from 0.04 to 40 cubic meters per hour. These systems enable automated meter reading, real-time leak detection, and demand-response integration for gas network operators. Communication Devices represents the fastest-growing technology segment as utilities migrate from drive-by RF mesh to cellular LPWAN architectures for last-mile connectivity. The Industrial application category sustains premium pricing due to custody-transfer accuracy requirements and hazardous-area certification burdens. Gas Distributors as an end-user group occupies the deepest margin pools because their procurement cycles span fifteen-to-twenty-year asset lifecycles with embedded service contracts.
The US EPA methane emissions rules and EU F-Gas Regulation together mandate continuous monitoring and reporting protocols that directly expand sensor deployment obligations across transmission and distribution networks. Germany's national implementation of EU energy efficiency directives through BSI-certified smart meter gateways creates product-standard barriers for non-compliant hardware vendors. Stakeholders must monitor evolving cybersecurity certification requirements under IEC 62056 and comparable national frameworks as network-connected gas infrastructure becomes a critical target for critical infrastructure protection regimes.
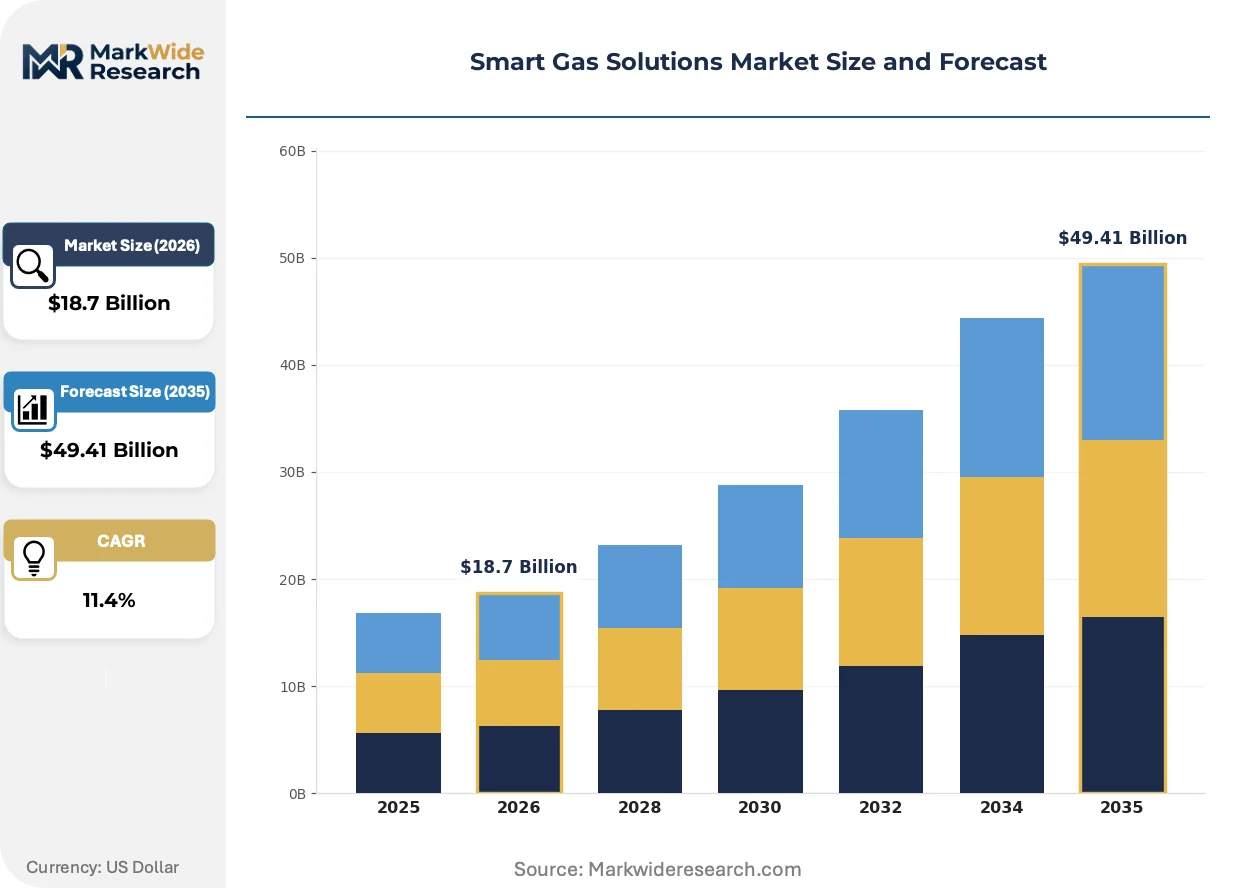
Market Dynamics
Networked measurement infrastructure is displacing legacy mechanical meters as utilities confront methane emissions accountability and real-time network visibility requirements. This hardware-to-software transition compresses replacement cycles and reconfigures vendor relationships around data platforms rather than device procurement.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant-phase-down mandates force industrial gas consumers to deploy continuous monitoring systems for leak detection and compliance reporting across manufacturing facilities.
- Cellular LPWAN architectures:Utilities migrate from drive-by RF mesh to cellular last-mile connectivity, expanding addressable endpoints for remote pressure and flow monitoring without infrastructure buildout.
- German district heating networks:District operators accelerate replacement cycles for legacy meter estates to integrate with BSI-certified smart meter gateways under national energy efficiency directives.
Market Restraints
- Semiconductor supply concentration:Sensor fusion devices require specialized analog front-end chips sourced primarily from East Asian foundries, exposing procurement to geopolitical disruption.
- IEC 62056 cybersecurity certification:Evolving critical infrastructure protection regimes impose multi-year approval timelines for network-connected gas hardware, delaying deployment schedules.
- Diaphragm meter residual stock:Utilities face sunk-cost pressure from recently installed mechanical assets with remaining ten-to-fifteen-year service life, slowing AMI conversion rates.
Strategic Opportunities
- Industrial custody-transfer applications:Hazardous-area certification requirements create pricing power for vendors delivering accuracy within one percent across extended flow ranges.
- US EPA methane rules:Continuous monitoring mandates expand sensor deployment obligations across transmission networks, opening service contract opportunities for integrated platform providers.
- Ultrasonic-pressure sensor convergence:Single-device architectures combining leak detection with pressure monitoring reduce installation complexity and total cost of ownership for gas distributors.
Industry Challenges
- AMI-legacy system integration:Municipal utilities struggle to reconcile cellular LPWAN endpoints with existing drive-by meter data management platforms, requiring middleware development.
- Field technician skill gaps:Deployment of sensor fusion devices demands training in hazardous-area electrical installation and cybersecurity hardening protocols that legacy meter workforces lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Gas Solutions Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Smart Meters, Gas Sensors, Measurement Instruments, Communication Devices Application: Residential, Commercial, Industrial, Utilities End User: Homeowners, Gas Distributors, Energy Companies, Facility Managers Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | Itron, Diehl Stiftung & Co. KG, Landis+Gyr, Honeywell International, ABB Group, General Electric Company, Badger Meter, Apator S.A., Aclara Technologies LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Gas Solutions Market Evolving Landscape
Smart gas infrastructure is pivoting from hardware-centric meter replacement toward software-defined network management. This shift elevates data platform vendors and compresses margins for standalone device manufacturers.
Ultrasonic metering with temperature-pressure compensation is decentralizing flow measurement accuracy across distribution networks. Gas distributors in Germany and North America are deploying these devices at residential and commercial endpoints previously served by mechanical diaphragm meters. The technology is decentralizing network visibility from centralized measurement stations to distributed edge nodes, enabling real-time leak localization without truck rolls.
The EU F-Gas Regulation and parallel US EPA methane emissions rules are mandating continuous monitoring protocols across transmission and distribution infrastructure. These frameworks require automated reporting of leak events and pressure anomalies, forcing hardware vendors to embed cellular connectivity and edge computing capabilities as standard features. Industrial gas consumers face the steepest compliance burdens due to custody-transfer accuracy requirements and hazardous-area certification standards.
Gas distributors are unbundling after-sales service contracts from initial hardware procurement, favoring fifteen-to-twenty-year performance agreements with embedded maintenance and software updates. This purchasing pattern displaces transactional meter sales with recurring revenue relationships. The shift is most pronounced in North American municipal utilities, where procurement committees now evaluate total cost of ownership across full asset lifecycles rather than upfront capital expenditure.
Smart Gas Solutions Market Segmentation
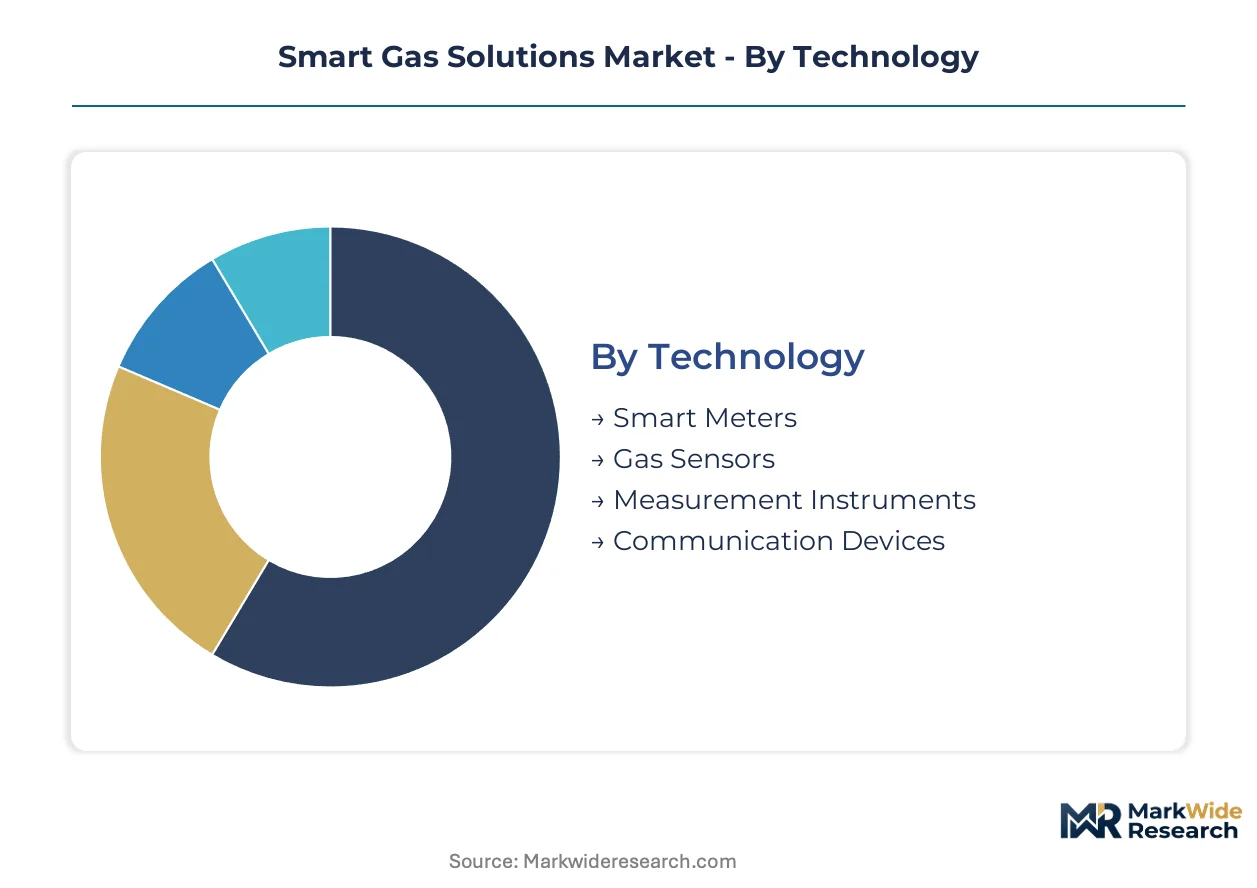
Smart gas solutions demand diverges sharply across deployment contexts, from embedded residential endpoints to standalone industrial custody-transfer systems. Vendors configure product architectures and service models around these integration-depth differences rather than treating the market as uniform.
Technology:
Integration depth separates standalone field-deployable units from tightly coupled system components that require AMI backbone integration.
- Communication Devices:Cellular LPWAN modules and RF mesh endpoints enable last-mile connectivity for remote pressure monitoring and automated meter reading. Utilities in Germany and North America are migrating to these architectures to eliminate drive-by reading costs while satisfying EPA methane reporting mandates.
- Smart Meters:Ultrasonic and diaphragm metering elements with temperature-pressure compensation deliver accuracy within one percent across flow ranges from 0.04 to 40 cubic meters per hour. German district heating networks and North American municipal utilities are accelerating replacement cycles for legacy mechanical estates to integrate with BSI-certified smart meter gateways.
- Gas Sensors:Leak detection and pressure monitoring devices deployed across transmission and distribution networks for continuous emissions surveillance.
- Measurement Instruments:Calibration and verification equipment maintaining custody-transfer accuracy standards for industrial gas consumers.
Smart Meters lead volumes today; Communication Devices are gaining share fastest.
Application:
Cost tier stratification creates three distinct procurement patterns, from mass-market residential deployments to premium-priced industrial systems.
- Industrial:Hazardous-area certified systems meeting custody-transfer accuracy requirements for manufacturing facilities and chemical processing plants. The EU F-Gas Regulation mandates continuous monitoring and automated reporting protocols, forcing these installations to embed cellular connectivity and edge computing capabilities.
- Residential:Mass-deployment ultrasonic meters replacing mechanical diaphragm units across single-family and multi-family housing. German utilities are bundling these with BSI-certified gateways under national energy efficiency directives.
- Commercial:Mid-scale installations serving retail, hospitality, and small manufacturing with modular platform configurations.
- Utilities:Network-wide infrastructure encompassing transmission monitoring, distribution pressure management, and centralized data platforms.
Residential dominates unit shipments; Industrial commands the steepest pricing premiums.
End User:
Procurement sophistication separates long-horizon asset owners from transactional equipment purchasers.
- Gas Distributors:Network operators managing fifteen-to-twenty-year asset lifecycles with embedded service contracts and total cost of ownership evaluation frameworks. These stakeholders unbundle after-sales agreements from initial hardware procurement, favoring performance-based relationships over transactional meter sales.
- Energy Companies:Integrated utilities combining gas distribution with electricity generation and retail operations, requiring cross-commodity data platform integration.
- Facility Managers:Commercial and industrial building operators procuring monitoring systems for compliance and operational efficiency.
- Homeowners:Individual consumers receiving smart meters through utility deployment programs rather than direct purchase.
Gas Distributors anchor procurement value; Facility Managers are expanding their specification influence fastest.
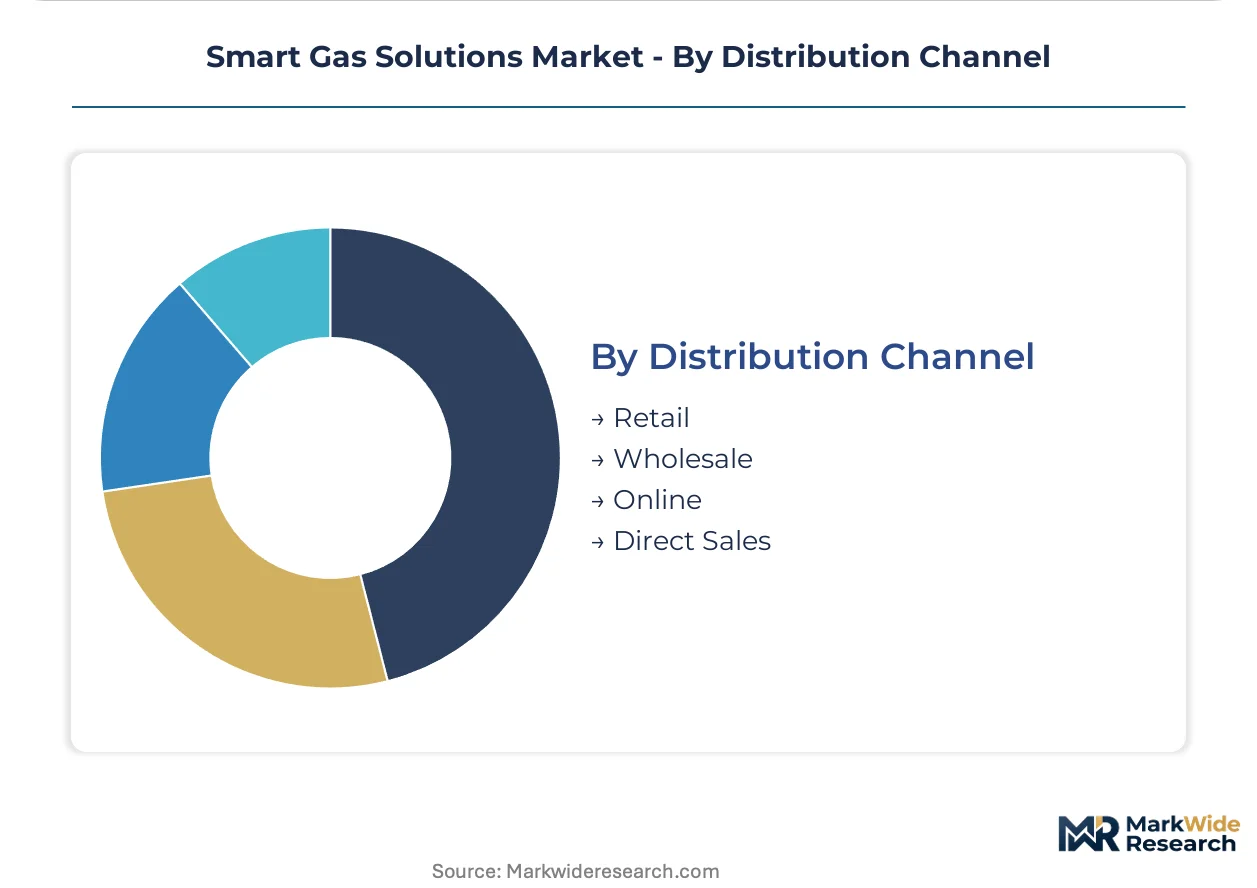
Distribution Channel:
Supply concentration varies by contract scale, with direct relationships dominating utility-scale deployments and intermediaries serving fragmented endpoints.
- Direct Sales:Large-scale municipal and industrial contracts negotiated through procurement committees evaluating full-lifecycle cost models. Itron and Landis+Gyr anchor major deployments through vertically integrated AMI software stacks and manufacturing scale.
- Wholesale:Regional distributors stocking certified devices for mid-tier utilities and commercial installers across North America and Europe.
- Online:Component-level sales of sensors and communication modules for system integrators and retrofit applications.
- Retail:Limited consumer-facing sales of standalone leak detection devices and home energy monitors.
Direct Sales captures the deepest margin pools; Wholesale channels are expanding geographic coverage fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The smart gas solutions industry traces its commercial scaling to Germany's post-reunification infrastructure modernization programs and the subsequent EU energy liberalization directives of the 1990s. These regulatory foundations established the technical standards and procurement frameworks that now govern networked gas measurement across industrial economies.
United States
EPA methane emissions rules mandate continuous monitoring across transmission and distribution networks, expanding sensor deployment obligations for gas distributors. FERC pipeline safety directives reinforce cybersecurity hardening requirements for network-connected infrastructure. The Permian Basin and Appalachian shale corridors drive demand for custody-transfer accuracy in high-volume production zones.
Germany
District heating networks and industrial gas consumers accelerate replacement cycles for legacy meter estates to integrate with BSI-certified smart meter gateways. The national implementation of EU energy efficiency directives creates product-standard barriers for non-compliant hardware vendors. The Ruhr industrial corridor and Bavarian manufacturing clusters anchor procurement volumes for ultrasonic metering systems.
China
MIIT smart city initiatives and SAMR metrology standards push municipal gas utilities toward automated meter reading architectures. Dual carbon goals impose emissions accountability requirements that expand leak detection system deployment. The Yangtze River Delta and Pearl River Delta urban agglomerations concentrate smart meter installation programs.
United Kingdom
OfGEM smart meter rollout obligations compel distribution network operators to complete residential AMI conversions by mandated deadlines. The UK Green Deal and subsequent efficiency frameworks embed long-term service contracting into procurement evaluations. Greater Manchester and the West Midlands industrial belt sustain demand for commercial-scale pressure monitoring systems.
Japan
METI hydrogen economy roadmaps and city gas decarbonization targets reshape monitoring requirements for blended fuel distribution. JIS standards for ultrasonic gas meters establish certification hurdles for imported equipment. The Tokyo metropolitan area and Osaka-Kobe industrial zone drive premium-tier demand for sensor fusion devices.
Smart Gas Solutions Market Competitive Landscape
The competitive structure tilts toward vertically integrated platform providers with captive AMI software stacks. Consolidation pressures favor vendors bundling meter hardware, communication modules, and data management platforms into unified procurement offerings. Three archetypes dominate: full-stack integrators controlling end-to-end infrastructure, manufacturing-scale specialists delivering across multiple meter standards, and sensor fusion innovators combining leak detection with pressure monitoring. Dominant competitive moves include strategic partnerships between hardware vendors and cellular network operators, plus geographic expansion through certified gateway compliance in regulated European markets.
Within the full-stack integrator tier, Itron and Landis+Gyr exemplify platform-centric positioning through vertically bundled meter-to-cash solutions. Honeywell International occupies a sensor fusion specialization, representing the convergence architecture archetype that combines multiple measurement modalities. These three anchors illustrate the strategic divergence between software-defined network management and hardware-centric device supply.
| Leading Market Players |
|---|
| Itron |
| Diehl Stiftung & Co. KG |
| Landis+Gyr |
| Honeywell International |
| ABB Group |
| General Electric Company |
| Badger Meter |
| Apator S.A. |
| Aclara Technologies LLC |
| Others |
Value Network & Pricing Analysis
EPA methane emissions rules and EU F-Gas Regulation compliance gates both qualified supply and premium-tier pricing access, as BSI-certified smart meter gateways and hazardous-area certifications create product-standard barriers that only vertically integrated vendors can surmount.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates IEC 62056-certified industrial custody-transfer systems from residential ultrasonic meters and basic diaphragm replacements. Price differentiation hinges on hazardous-area certification grade and fifteen-to-twenty-year embedded service contract scope. Cost compression in the residential tier intensifies because utilities evaluate total cost of ownership rather than upfront capital expenditure. Facility Managers exhibit the highest price sensitivity due to budget-constrained procurement cycles, while Gas Distributors accept premium pricing for integrated platform bundles.
Supply Chain Analysis
Dual-sourcing requirements from German utilities and North American municipal procurement committees mandate multi-supplier qualification for cellular LPWAN modules and ultrasonic sensor arrays. Manufacturing concentrates in Germany, China, and the United States for AMI software stacks and meter hardware. Specialized analog front-end chips for sensor fusion devices draw from East Asian foundries. Single-source vulnerability in semiconductor supply exposes procurement to geopolitical disruption. Distribution runs through direct sales relationships for utility-scale deployments and wholesale channels for regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart gas solutions represent a late-cycle quality story as procurement committees shift evaluation criteria from upfront hardware cost toward full-lifecycle performance metrics and cybersecurity certification depth.
For Market Incumbents: Deploy captive AMI software stack integration to anchor large-scale municipal contracts against modular platform competitors. Deepen manufacturing scale across European meter standards to defend position against sensor fusion specialists entering from adjacent industrial automation markets. Accelerate BSI-certified gateway compliance investments ahead of German district heating network replacement cycles.
For New Entrants and Emerging Players: Enter via industrial custody-transfer applications where hazardous-area certification requirements sustain pricing power and incumbent presence remains thinner. Target Facility Managers in commercial building segments with standalone leak detection devices that bypass utility procurement complexity. Pursue channel partnerships with regional wholesale distributors rather than direct utility sales.
For Investors and Strategic Acquirers: Roll-up economics work for sensor fusion specialists because ultrasonic-pressure convergence architectures consolidate multiple device categories into single-vendor relationships. Five-to-ten-year viability hinges on cellular LPWAN endpoint penetration rates and recurring revenue attachment. Monitor IEC 62056 cybersecurity certification timelines as the signal indicating which hardware vendors will clear critical infrastructure protection barriers.
| Strategic Initiative | Industry Significance |
|---|---|
| AMI Software Stack Integration | Captive data platforms lock in fifteen-to-twenty-year service relationships with Gas Distributors. |
| Cellular LPWAN Module Certification | EPA methane reporting mandates expand addressable endpoints for remote pressure monitoring. |
| BSI-Certified Gateway Compliance | German national energy efficiency directives create product-standard barriers for non-compliant vendors. |
| Sensor Fusion Device Convergence | Single-device architectures combining leak detection with pressure monitoring reduce total cost of ownership. |
| Hazardous-Area Certification Investment | Industrial custody-transfer accuracy requirements sustain premium pricing for certified equipment vendors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility planning officers, gas distributor procurement leads, AMI platform engineers, and industrial facility managers with secondary validation against FERC filings, EPA emissions databases, EU energy efficiency directive implementations, and customs trade records. Bottom-up endpoint enumeration triangulated against top-down infrastructure investment forecasts.
Historical reference periods anchored the projection horizon across technology adoption curves, regulatory implementation timelines, and asset replacement cycles. Segmentation modeling incorporated deployment model, application tier, end-user procurement sophistication, and regional regulatory framework. CAGRs derived from fitted growth curves applied to meter shipment volumes and platform service contract values. Forecast inputs included district heating network modernization schedules and cellular LPWAN network coverage expansion.
Inputs from utility procurement databases and regulatory filing repositories were available through the study window; gaps in real-time industrial gas consumer deployment data introduce uncertainty bands around custody-transfer system forecasts. Deviation in IEC 62056 cybersecurity certification timelines or EPA methane rule enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Hybrid Propellants Market
Fuels
Coal Trading Market
Fuels
Oil Dispensing Stations Market
Fuels
Catalytic Hydrothermolysis Jet [CHJ] Fuel Market
Fuels
Marine Fuel Filter Market
Fuels
Hydrogen Cylinder Market
Fuels
Diesel As Fuel Market
Fuels
Europe Defense Aircraft Aviation Fuel Market
Fuels
Global Charcoal Market
Fuels
LNG Filling Station Market
Fuels
Australia Coal Market
Fuels
Brazil LNG Market
Fuels
North America LNG Bunkering Market
Fuels
China LNG Bunkering Market
Fuels
Liquefied Helium Tanks Market
Fuels
Oil Dispenser Market