
 Europe FMD Vaccine Market | 2026-2036
Europe FMD Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Europe FMD Vaccine Market Intelligence
Aluminum hydroxide adjuvant substitution with saponin-based formulations is recalibrating cost structures across European FMD vaccine production. Boehringer Ingelheim International GmbH leverages captive antigen manufacturing in Germany to sustain supply security for government tenders. Merck & Co., Inc. anchors its position through R&D intensity in recombinant platforms, while Zoetis Inc. competes via channel control into veterinary clinic networks across Iberia and Eastern Europe.
Foot-and-mouth disease vaccines are inactivated or live attenuated preparations containing purified viral antigens, typically formulated with adjuvants to elicit protective neutralizing antibodies in cloven-hoofed livestock within 14-21 days post-administration. Reverse genetics technology leads European manufacturing investment due to its precision in antigen matching against circulating serotypes, while virus-like particle platforms represent the fastest-growing segment as producers seek DIVA-compatible (Differentiating Infected from Vaccinated Animals) formulations. Intramuscular administration dominates volume, though oral delivery gains traction in extensive grazing systems where handling infrastructure is sparse.
EMA veterinary biologics guidelines, EU F-Gas Regulation on propellant alternatives, and REACH chemical safety mandates collectively shape antigen formulation standards and environmental release protocols across European manufacturing sites. EFSA surveillance directives further tighten batch-release testing for FMD vaccines distributed under EU emergency stockpiling programs. Stakeholders must monitor serotype shift patterns in North African and Middle Eastern reservoirs to anticipate antigen strain updates before formal regulatory revision cycles trigger.
Market Dynamics
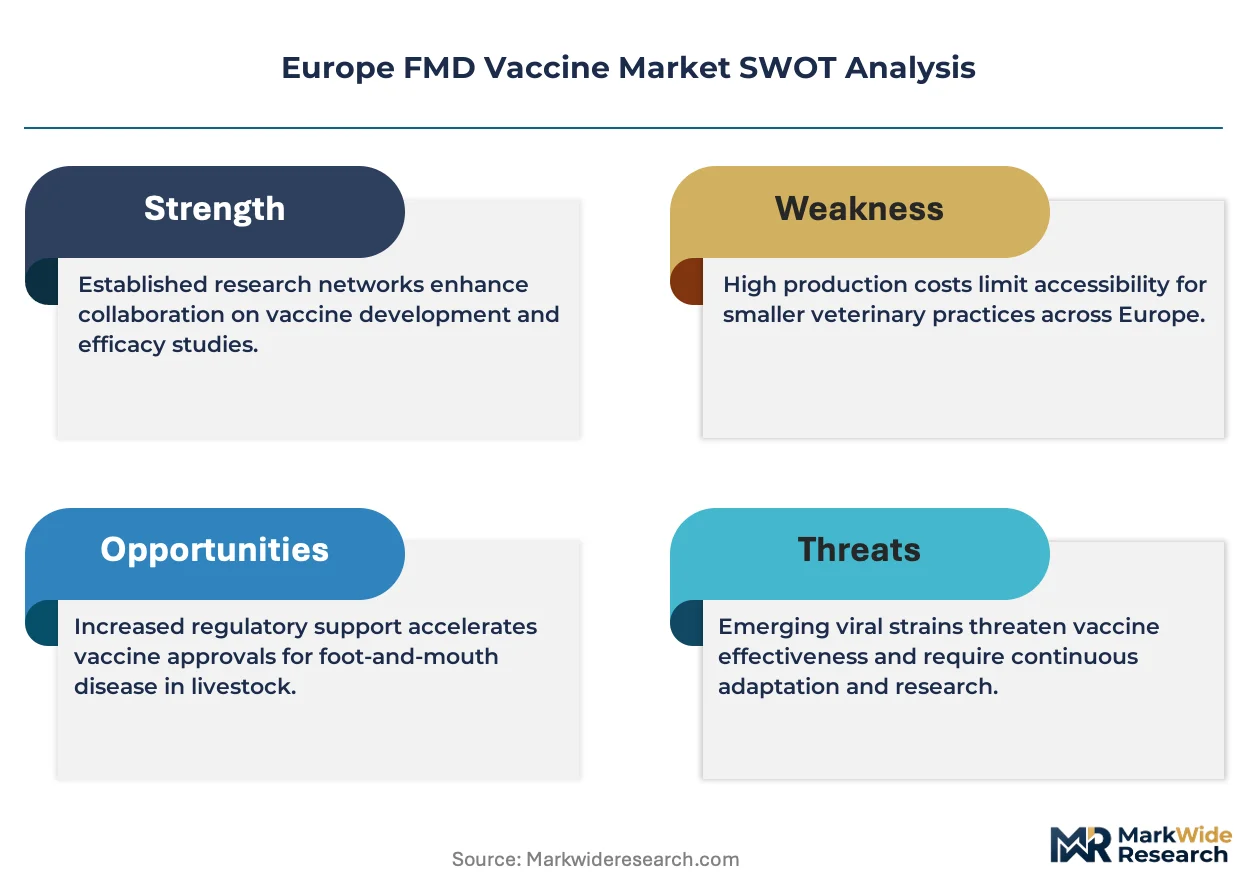
EMA veterinary biologics guidelines and the EU F-Gas Regulation are forcing antigen manufacturers to reformulate adjuvant systems and eliminate fluorinated propellants from production processes, compressing legacy product margins while opening pathways for saponin-based and plant-derived alternatives.
Growth Catalysts
- EU F-Gas Regulation:Mandates for propellant alternatives accelerate investment in aqueous-based formulations and dry powder delivery systems across German and French manufacturing sites.
- Livestock herd expansion:Dairy and beef operations in the Netherlands and Poland are implementing mandatory vaccination protocols under national animal health frameworks.
- Reverse genetics platforms:Precision antigen matching capabilities enable faster strain updates against circulating serotypes from North African reservoirs.
Market Restraints
- Aluminum hydroxide supply concentration:Dependence on Chinese and Turkish raw material sources creates input cost volatility and batch-to-batch adjuvant consistency challenges.
- REACH chemical compliance:Registration requirements for novel saponin extracts extend formulation approval timelines by 18-24 months.
- Virus-like particle technical barriers:Scalable mammalian cell culture infrastructure remains limited to three European contract manufacturing organizations.
Strategic Opportunities
- Eastern European veterinary networks:Underpenetrated clinic infrastructure in Romania and Bulgaria offers first-mover advantages for oral delivery formulation distributors.
- CSRD sustainability reporting:Mandatory environmental disclosure creates procurement preference for carbon-footprint-certified vaccine suppliers in Dutch and Danish retail cooperatives.
- Digital traceability convergence:Integration of blockchain batch tracking with DIVA-compatible serology platforms enables premium positioning in government tender processes.
Industry Challenges
- Bioprocess engineering talent scarcity:Shortage of mammalian cell culture specialists constrains viral antigen yield optimization at manufacturing scale.
- EMA batch-release timelines:Extended stability testing protocols for novel adjuvant combinations delay commercial launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe FMD Vaccine Market |
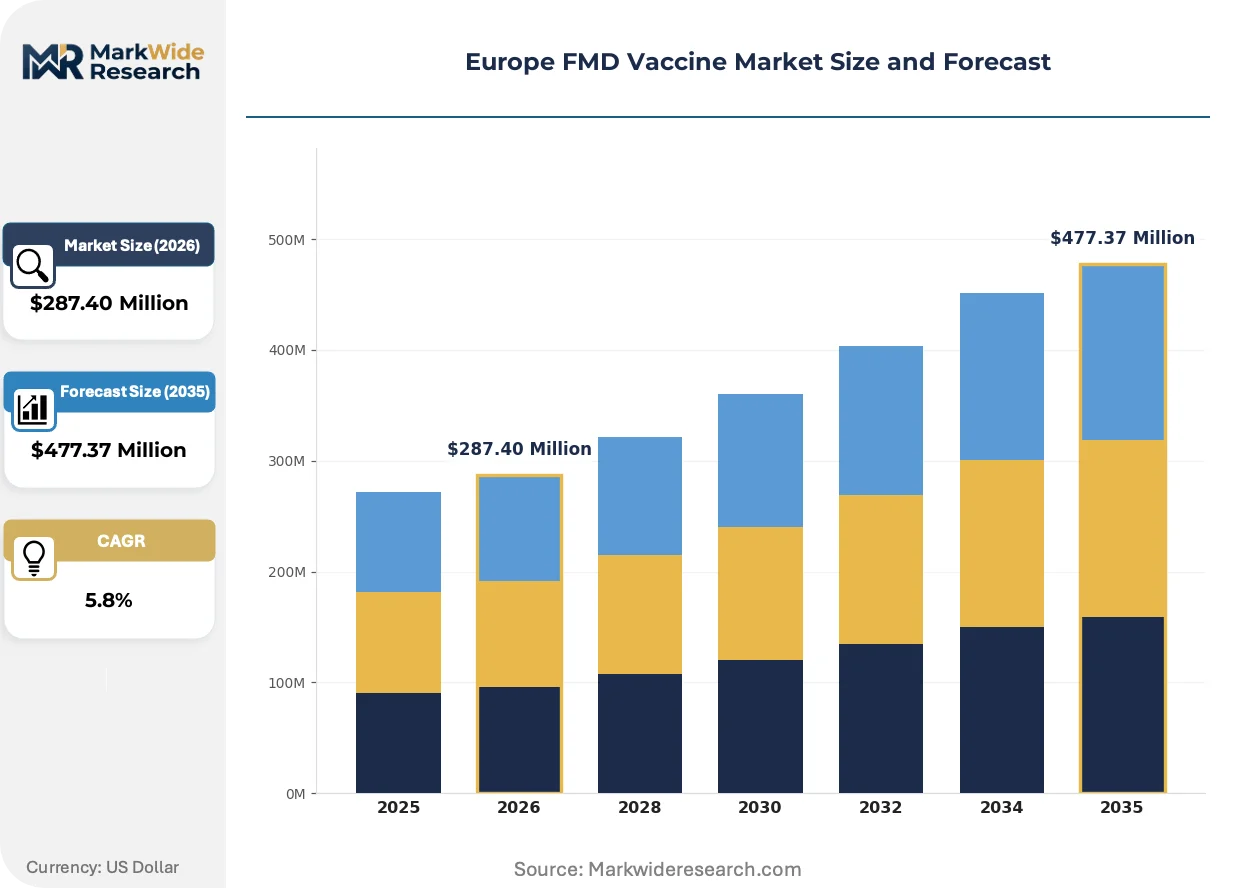
| Market Size in 2026 | $287.40 Million |
| Market Size in 2035 | $477.37 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inactivated Vaccines, Live Attenuated Vaccines, Subunit Vaccines, DNA Vaccines Technology: Reverse Genetics, Virus-Like Particle, Recombinant Protein, Adenoviral Vector End User: Livestock Farms, Veterinary Clinics, Research Laboratories, Government Agencies Administration Route: Intramuscular, Subcutaneous, Oral, Intranasal |
| Companies Covered | Biogenesis Bago, Bayer AG, Boehringer Ingelheim International GmbH, Hester Biosciences Limited, Indian Immunologicals Limited, Merck & Co., Inc., IDT Biologika, Brilliant Bio Pharma Limited, Zoetis Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe FMD Vaccine Market Strategic Shifts & Innovations
European FMD vaccine production is pivoting toward precision antigen platforms and sustainable formulation chemistry as regulatory pressure on environmental release protocols intensifies and veterinary buyers demand faster serotype matching capabilities.
Plant-based expression systems utilizing Nicotiana benthamiana hosts are decentralizing antigen manufacturing away from centralized embryonated egg facilities. Regional bioprocessing hubs in Spain and Portugal are adopting transient expression protocols to shorten supply chains for Iberian livestock cooperatives. Distributed production networks reduce cold-chain dependency and enable faster response to localized serotype emergence.
EMA's tightened veterinary biologics guidelines on residual host cell DNA limits are forcing purification process upgrades across European manufacturing sites. Chromatography resin suppliers report extended lead times as antigen producers retrofit downstream operations. German and French facilities face the steepest compliance costs due to legacy protein A capture infrastructure.
Consolidation among European veterinary clinic chains is compressing procurement cycles and unbundling after-sales serology services from vaccine supply contracts. Large livestock cooperatives in Denmark and the Netherlands now negotiate direct antigen supply agreements, bypassing traditional wholesale distributors. Channel disintermediation favors manufacturers with captive diagnostic capabilities and regional cold-chain infrastructure.
Europe FMD Vaccine Market Segmentation
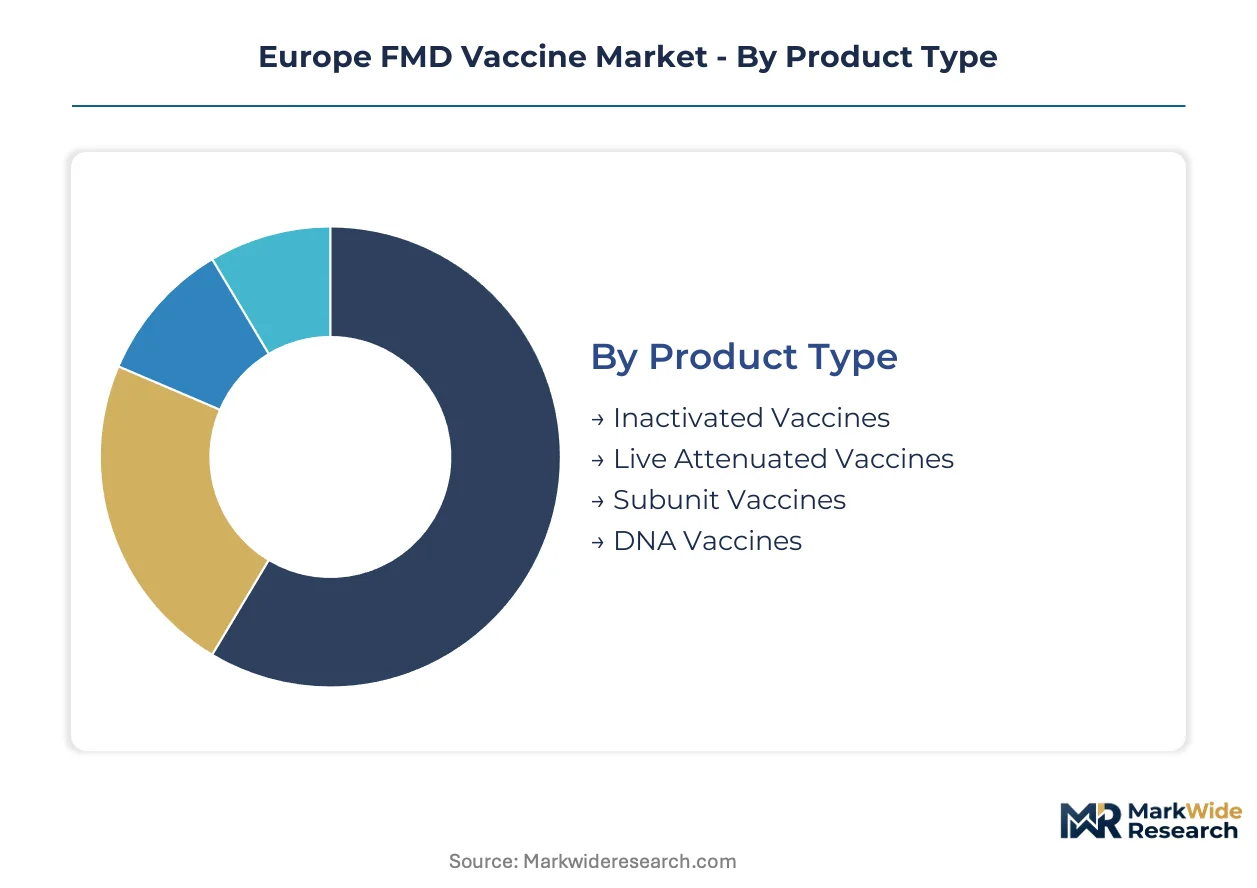
Segmentation in the Europe FMD Vaccine Market reveals how formulation chemistry, delivery technology, and procurement channel each command distinct margin profiles and regulatory pathways. Manufacturers must align R&D investment with the specific compliance burdens and handling infrastructure of each segment cluster.
Product Type:
Inactivated formulations function as standalone products requiring dedicated cold-chain infrastructure, while live attenuated and subunit platforms embed into broader veterinary health protocols with lighter handling demands.
- Inactivated Vaccines:These preparations contain chemically treated viral particles that retain immunogenicity without replication capability. Demand concentrates in Dutch and Danish dairy cooperatives where EMA batch-release standards and government tender specifications favor proven safety profiles over novel platforms.
- Live Attenuated Vaccines:Attenuated viral strains elicit cellular and humoral immunity through limited replication in the host. German beef operations in Bavaria and Lower Saxony are expanding procurement of these formulations where rapid onset of immunity offsets the stricter biosecurity protocols required during handling.
- Subunit Vaccines:Purified protein antigens eliminate residual viral RNA concerns under EFSA surveillance directives.
- DNA Vaccines:Plasmid-based platforms remain in pilot distribution through research consortia pending EMA veterinary biologics pathway clarification.
Inactivated vaccines lead volumes today; DNA vaccines are gaining share fastest as DIVA compatibility attracts government stockpiling interest.
Technology:
Cost tier differentiation separates precision-engineered platforms with mammalian cell culture overhead from bacterial or yeast expression systems with lower upstream capital requirements.
- Reverse Genetics:Site-directed mutagenesis enables rapid serotype matching against North African reservoir strains. French and German manufacturing sites deploy these platforms for emergency antigen updates when EFSA surveillance detects novel viral variants.
- Virus-Like Particle:Self-assembling capsid structures without viral genetic material offer DIVA-compatible serology. Scalable production remains constrained to three European contract manufacturing organizations, limiting volume expansion despite premium positioning in Dutch retail cooperative procurement.
- Recombinant Protein:Bacterial and yeast expression systems dominate cost-sensitive Eastern European markets.
- Adenoviral Vector:Viral delivery platforms enable single-dose immunization protocols in extensive grazing systems.
Reverse genetics leads volumes today; virus-like particle platforms are climbing the fastest as sustainability reporting favors animal-origin-free production.
End User:
Customer type determines whether vaccines flow through wholesale veterinary distribution or direct antigen supply agreements with integrated procurement functions.
- Livestock Farms:Large cooperatives in the Netherlands and Poland negotiate direct supply contracts, bypassing traditional distributors. These operations demand bulk packaging and on-farm cold-chain validation under national animal health framework mandates.
- Veterinary Clinics:Consolidated clinic chains in Iberia and France compress procurement cycles and unbundle after-sales serology from vaccine supply. Channel disintermediation favors manufacturers with captive diagnostic capabilities.
- Research Laboratories:Academic and government facilities drive pilot-scale demand for novel platform evaluation.
- Government Agencies:National veterinary services and EU emergency stockpiling programs specify aluminum-free adjuvants and blockchain batch traceability.
Livestock farms lead volumes today; government agencies are expanding procurement fastest under EU F-Gas Regulation compliance mandates.
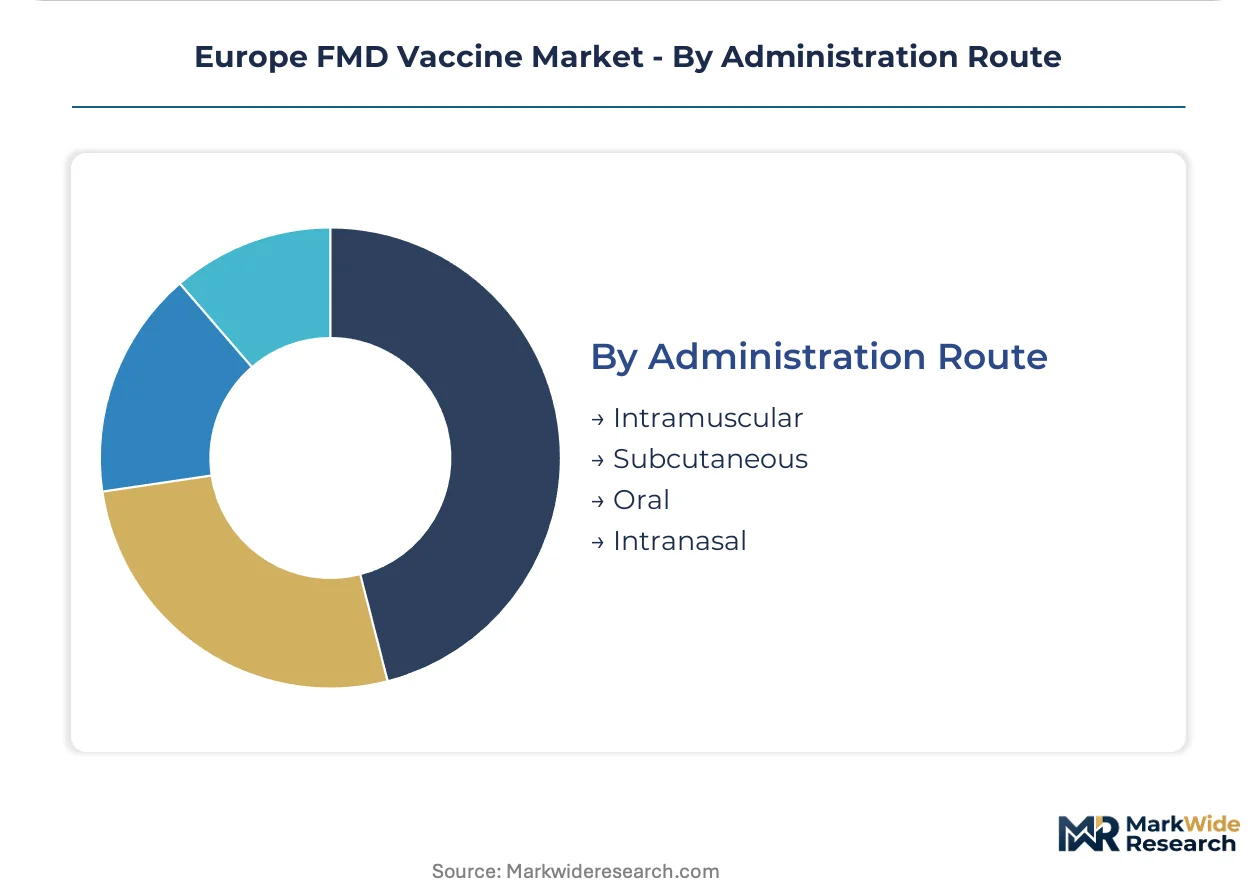
Administration Route:
Volume concentration versus margin premium splits between mass administration methods in commercial operations and precision delivery in controlled settings.
- Intramuscular:Deep muscle injection remains the standard for inactivated formulations, requiring trained personnel and restraint infrastructure. This route dominates German and French commercial dairy where handling facilities justify labor investment.
- Oral:Baits and feed-additive formulations eliminate handling stress in extensive Polish and Romanian grazing systems. Distribution runs through agricultural supply cooperatives rather than veterinary clinic networks.
- Subcutaneous:Neck or shoulder administration suits smaller ruminant operations with limited restraint equipment.
- Intranasal:Mucosal delivery platforms target mucosal immunity pathways with reduced antigen dose requirements.
Intramuscular administration leads volumes today; oral delivery is expanding most quickly where sparse infrastructure favors self-administration protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturing clusters around Saxony-Anhalt and Lower Saxony anchor European FMD vaccine production capacity. National animal health frameworks and EMA batch-release protocols shape procurement patterns across member states. Regional differentiation reflects varying livestock densities, adjuvant reformulation timelines, and veterinary infrastructure maturity.
Germany
Bavarian and Lower Saxon dairy cooperatives drive inactivated vaccine procurement under federal animal health mandates. EMA veterinary biologics guidelines enforce aluminum hydroxide adjuvant documentation standards. Manufacturing concentration in Saxony-Anhalt supports captive antigen production for government tender security.
France
Auvergne-Rhône-Alpes livestock operations expand live attenuated vaccine adoption for rapid immunity onset in beef herds. EU F-Gas Regulation compliance deadlines accelerate aqueous formulation transitions at Lyon-area production sites. Regional bioprocessing hubs adopt transient expression protocols for decentralized antigen supply.
Netherlands
Dutch retail cooperatives in Gelderland and Friesland negotiate direct antigen supply agreements bypassing wholesale distributors. CSRD sustainability reporting mandates create procurement preference for carbon-footprint-certified suppliers. National frameworks require on-farm cold-chain validation for bulk vaccine packaging.
Poland
Masovian and Greater Poland voivodeships implement mandatory vaccination protocols under national animal health frameworks. Oral delivery formulations gain traction in extensive grazing systems where handling infrastructure remains sparse. Agricultural supply cooperatives distribute feed-additive vaccines outside veterinary clinic networks.
Spain
Andalusian and Catalonian livestock cooperatives pilot plant-based expression systems using Nicotiana benthamiana hosts. Regional bioprocessing hubs shorten supply chains for Iberian peninsula serotype response. EFSA surveillance directives tighten batch-release testing for emergency stockpiling programs.
Europe FMD Vaccine Market Key Industry Players
Global majors compete with regional champions across formulation chemistry and distribution channel control. The vendor base separates into captive antigen manufacturers, contract biologics specialists, and veterinary service integrators. Three archetypes dominate: German-anchored integrated pharmaceutical groups, Indian-origin biosimilar exporters, and North American animal health conglomerates. Competitive moves concentrate on backward integration into adjuvant raw material sourcing and regional diagnostic capability acquisition.
Among German-anchored integrated players, Boehringer Ingelheim International GmbH occupies a position exemplifying captive manufacturing advantages. Merck & Co., Inc. and Zoetis Inc. represent North American animal health conglomerates competing through channel depth and R&D platform breadth. These three companies anchor the competitive structure, with Boehringer Ingelheim leveraging domestic production infrastructure, Merck emphasizing recombinant platform development, and Zoetis building veterinary clinic network penetration across Southern and Eastern Europe.
| Leading Market Players |
|---|
| Biogenesis Bago |
| Bayer AG |
| Boehringer Ingelheim International GmbH |
| Hester Biosciences Limited |
| Indian Immunologicals Limited |
| Merck & Co., Inc. |
| IDT Biologika |
| Brilliant Bio Pharma Limited |
| Zoetis Inc. |
| Others |
Cost & Logistics Intelligence
Mammalian cell culture specialists in Saxony-Anhalt and Lower Saxony command wage premiums that widen pricing spreads between premium recombinant platforms and standard inactivated formulations. Labor-cost differentials between German manufacturing hubs and Eastern European distribution points stratify procurement tiers across Dutch dairy cooperatives and Polish beef operations.
Pricing Analysis
Input-cost pass-through from aluminum hydroxide and saponin extract sourcing determines margin compression across formulation tiers. Three-tier pricing structure across premium virus-like particle, standard inactivated, and economy recombinant platforms reflects adjuvant certification grades and EMA batch-release documentation depth. Pricing pressure stems from REACH compliance timelines extending novel formulation approval cycles. Government tender specifications show lowest price sensitivity; Eastern European agricultural cooperatives exhibit highest elasticity.
Supply Chain Analysis
Direct-to-livestock-farm channels handle bulk procurement from Dutch and Danish cooperatives, while veterinary clinic networks manage precision delivery for smaller operations. Antigen manufacturing concentrates in Germany, France, and Spain; adjuvant raw materials draw from Chinese and Turkish sources. Chromatography resin and embryonated egg supply dependencies create single-source vulnerability for downstream purification. Distribution runs through regional cold-chain hubs with government stockpiling programs bypassing wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe FMD Vaccine Market functions as a stable compounder anchored by mandatory national vaccination frameworks that institutionalize recurring procurement cycles regardless of commodity livestock price cycles.
For Market Incumbents: Anchor government tender security through captive antigen manufacturing in German production clusters. Backward integration into saponin raw material sourcing mitigates Turkish supply concentration risk. EMA veterinary biologics batch-release capacity investments defend against contract manufacturing organization encroachment. For New Entrants and Emerging Players: Enter via oral delivery formulation distribution through Polish and Romanian agricultural supply cooperatives where veterinary clinic penetration remains sparse. Plant-based expression platforms utilizing Nicotiana benthamiana hosts offer regulatory differentiation under EFSA surveillance directives. Digital traceability bundling with DIVA-compatible serology enables premium positioning in government procurement. For Investors and Strategic Acquirers: Valuations sit cheapest among regional bioprocessing hubs with transient expression capabilities and underutilized mammalian cell culture infrastructure. Five-to-ten year viability hinges on EU F-Gas Regulation compliance execution and serotype matching agility against North African reservoir strains. Watch EFSA surveillance bulletins for emergency strain update triggers as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Adjuvant Reformulation Investment | Saponin-based alternatives satisfy EU F-Gas Regulation mandates while reducing Chinese raw material dependency. |
| Reverse Genetics Platform Expansion | Site-directed mutagenesis capabilities accelerate serotype matching against EFSA-tracked North African variants. |
| Eastern European Distribution Buildout | Oral delivery penetration in Poland and Romania captures underpenetrated extensive grazing systems. |
| Blockchain Traceability Integration | DIVA-compatible batch tracking meets Dutch CSRD procurement preferences and government tender specifications. |
| Plant-Based Expression Scale-Up | Nicotiana benthamiana systems in Iberian hubs decentralize supply chains and reduce cold-chain intensity. |
Research Approach
Direct dialogue with vaccine manufacturing executives, EMA regulatory affairs specialists, Dutch cooperative procurement managers, and German veterinary clinic chain operators grounded qualitative findings. Secondary validation drew from EMA veterinary biologics submissions, EFSA surveillance bulletins, EU F-Gas Regulation implementation reports, and REACH chemical registration databases. Bottom-up antigen production capacity modeling and top-down livestock herd vaccination rate estimates were triangulated to calibrate volume projections.
Bottom-up segment-level modeling across formulation type, technology platform, end-user category, and administration route fed into aggregate market sizing. CAGRs were derived from regression analysis of historical procurement patterns against livestock population forecasts and regulatory compliance timeline assumptions. Industry-specific inputs included EMA batch-release queue durations, adjuvant raw material lead times, and serotype shift probability distributions from North African reservoir monitoring.
Inputs from EMA submission databases and national animal health framework documentation were available through the study window; gaps in real-time veterinary clinic procurement transaction data introduce uncertainty bands around channel split estimates. Forecasts reflect assumptions regarding EU F-Gas Regulation enforcement consistency and EFSA surveillance protocol continuity. Periodic stress-testing of base assumptions against serotype emergence patterns and adjuvant supply disruption scenarios is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Nasal Drug Delivery Technology Market
Pharmaceuticals
Global Acyclovir Market
Pharmaceuticals
Opioid Induced Constipation Drug Market
Pharmaceuticals
Xerostomia Therapeutics Market
Pharmaceuticals
Fertility Drug and Surgery Market
Pharmaceuticals
Dual Migraine Treatment Market
Pharmaceuticals
Valganciclovir Market
Pharmaceuticals
Human Immunodeficiency Virus Therapeutics Market
Pharmaceuticals
Nephrology Drugs Market
Pharmaceuticals
US Plasma Fractionation Market
Pharmaceuticals
Global Orally Disintegrating Tablet Market
Pharmaceuticals
Immunoglobulin Products Market
Pharmaceuticals
Norway Pharmaceutical Market
Pharmaceuticals
Antiviral Immunoglobulin Market
Pharmaceuticals
Global Adult Vaccines Market
Pharmaceuticals
Sleeping Medications Market