
 Fertility Drug and Surgery Market | 2026-2036
Fertility Drug and Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Fertility Drug and Surgery Market Foresight
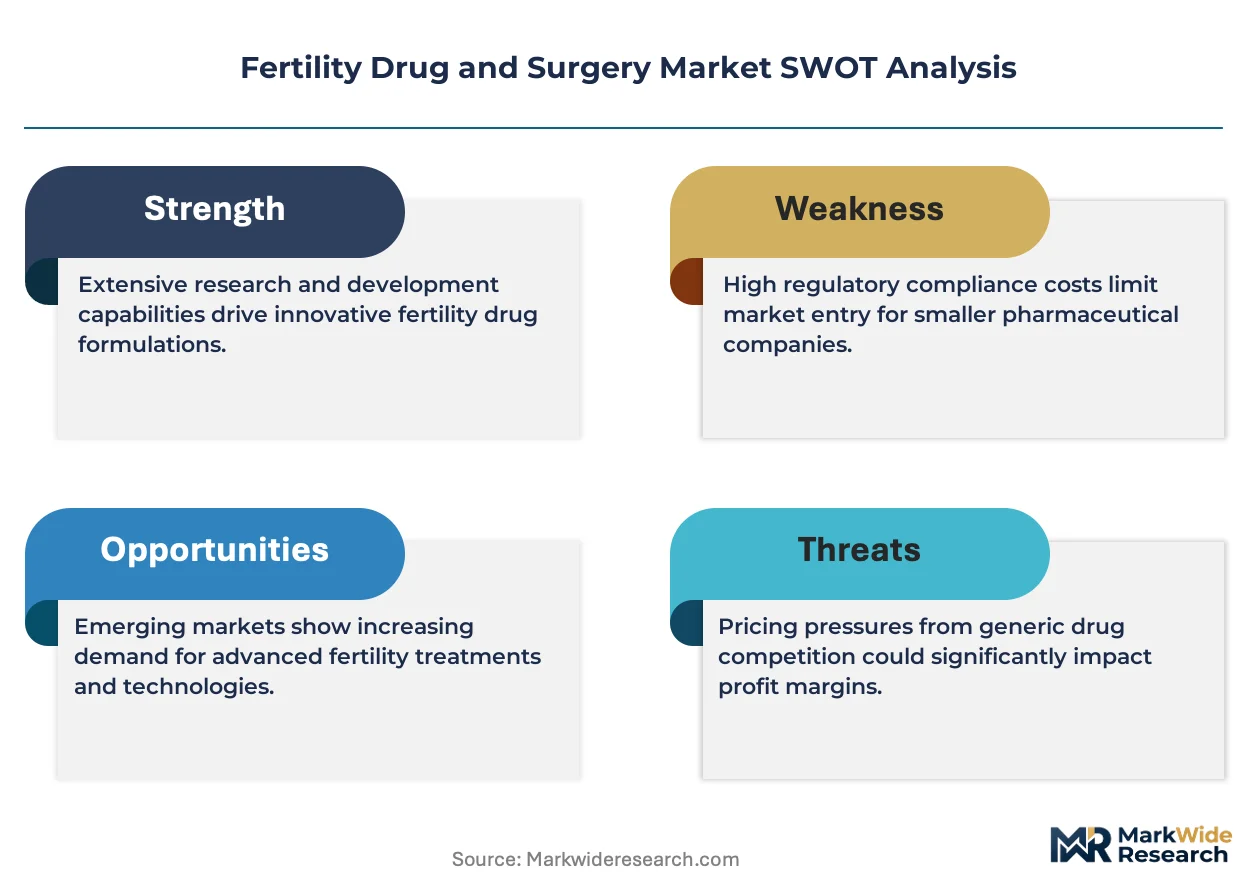
European pharmaceutical manufacturers is pivoting toward recombinant gonadotropin production to secure supply chain stability for fertility clinics worldwide. Merck leverages its long-standing expertise in reproductive hormone therapies to sustain leadership across European and North American distribution channels. Ferring Pharmaceuticals anchors its competitive position through specialized manufacturing of peptide-based fertility drugs with controlled-temperature logistics networks.
Fertility drugs and surgical interventions encompass pharmacological agents that modulate hypothalamic-pituitary-ovarian axis function alongside minimally invasive procedures for gamete retrieval and transfer, with gonadotropin formulations requiring precise FSH-to-LH ratios measured in international units to stimulate controlled follicular development. These therapies serve the primary commercial purpose of overcoming anovulation, tubal obstruction, or severe male factor infertility within structured clinical protocols. Gonadotropins command the deepest margin pools among product types due to biologic manufacturing complexity and cold-chain dependency, while intracytoplasmic sperm injection represents the fastest-expanding therapy area as andrological indications broaden. Oral clomiphene citrate occupies a mature, price-sensitive position dominated by generic competition across outpatient settings.
The FDA enforces stringent potency and purity standards for injectable gonadotropin biologics under 21 CFR regulations, directly elevating manufacturing compliance costs and filtering market access to established producers with validated GMP infrastructure. The EMA's MDR framework and REACH chemical safety protocols impose additional documentation burdens on device-drug combination products used in embryo transfer procedures. Stakeholders must monitor evolving reimbursement policies from national health authorities and private insurers, as coverage determinations for IVF cycles and associated drug protocols increasingly dictate patient access volumes and regional market expansion feasibility.
Market Dynamics
Recombinant gonadotropin manufacturing is concentrating among European biologics producers with validated cold-chain infrastructure, tightening supply access for fertility clinics dependent on precise FSH-to-LH ratio formulations.
Growth Catalysts
- Assisted reproductive technology reimbursement:Favorable coverage policies from private insurers in the United States attract domestic and international patients to large fertility clinic networks, expanding procedure volumes.
- EMA fertility treatment guidelines:Standardized protocols across European markets reduce regulatory friction for cross-border patient mobility and clinic accreditation.
- Intracytoplasmic sperm injection:Broadening andrological indications drive adoption of this surgical intervention among male-factor infertility cases previously managed through pharmacological approaches alone.
Market Restraints
- Biologic manufacturing complexity:Injectable gonadotropins require fermentation-based production with stringent potency validation, limiting supplier base to established GMP-certified facilities.
- Cold-chain dependency:Peptide-based fertility drugs demand controlled-temperature logistics from manufacturing through clinic administration, elevating distribution costs and spoilage risk.
- Generic clomiphene citrate saturation:Oral ovulation induction agents face commoditized pricing across outpatient settings, compressing margin pools for manufacturers without biologic portfolios.
Strategic Opportunities
- Device-drug combination products:Embryo transfer catheter systems integrated with hormonal delivery protocols create differentiated positioning under the EMA's MDR framework.
- REACH chemical safety compliance:Early adoption of enhanced documentation standards for surgical instruments enables premium pricing in European fertility clinic procurement.
- International patient mobility hubs:Specialized reproductive health centers in Spain and the Czech Republic attract cross-border demand from markets with restricted public funding cycles.
Industry Challenges
- Embryologist certification timelines:Extended training requirements for intracytoplasmic sperm injection proficiency create workforce bottlenecks at expanding clinic networks.
- 21 CFR biologics compliance:FDA potency and purity enforcement for gonadotropin formulations demands continuous validation investments that strain mid-scale manufacturing operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fertility Drug and Surgery Market |
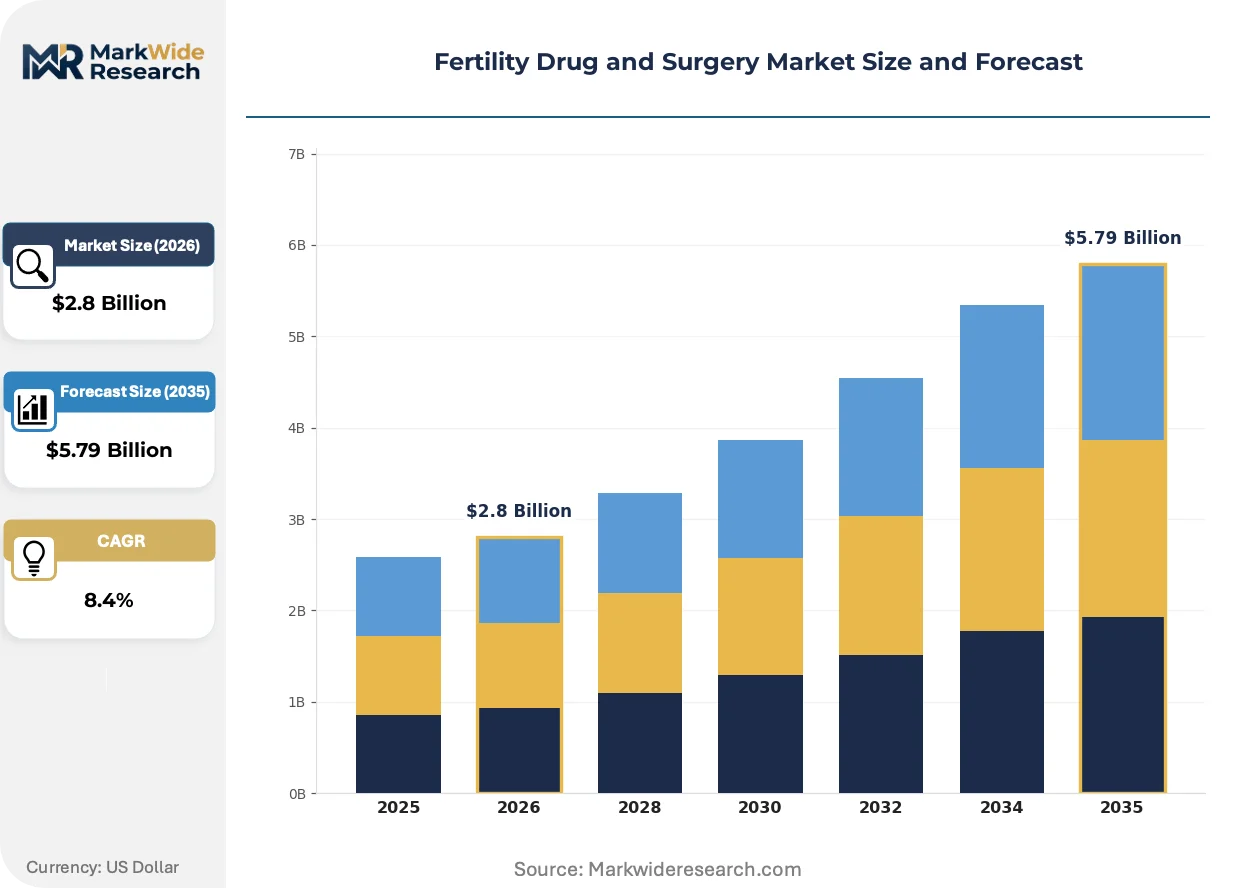
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: In Vitro Fertilization, Ovulation Induction, Intracytoplasmic Sperm Injection, Sperm Retrieval Product Type: Clomiphene Citrate, Gonadotropins, Aromatase Inhibitors, Human Chorionic Gonadotropin End User: Infertility Clinics, Hospitals, Research Laboratories, Private Practices Delivery Mode: Oral, Injectable, Transdermal, Intranasal |
| Companies Covered | Cook Group, Vitrolife, Merck, FUJIFILM Irvine Scientific, Thermo Fisher Scientific, Ferring Pharmaceuticals, Cooper Companies, Bayer, Organon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fertility Drug and Surgery Market Shifts & Advancements
Digital follicular monitoring platforms are reshaping how fertility clinics optimize gonadotropin dosing protocols, replacing manual ultrasound scheduling with algorithm-driven stimulation tracking.
Artificial intelligence-powered embryo selection systems are converging with time-lapse incubation technology to automate morphokinetic assessment. Large fertility clinic networks in the United States are deploying these integrated platforms to standardize transfer decisions across multiple sites. This convergence is compressing variability in pregnancy outcome rates that previously depended on individual embryologist expertise.
The FDA's 21 CFR potency standards for injectable gonadotropins are tightening analytical method requirements for lot release testing. Manufacturers must now demonstrate extended stability data under accelerated degradation conditions. European producers with existing EMA quality management system certifications are adapting fastest, while newer market entrants face extended approval timelines.
Direct-to-clinic procurement platforms are disintermediating traditional pharmaceutical distributors for high-volume fertility drug purchasing. Consolidated clinic networks in the United States negotiate annual supply agreements directly with recombinant gonadotropin manufacturers, bypassing wholesale markups. This channel shift is most visible among multi-site operators managing centralized inventory across state lines.
Fertility Drug and Surgery Market Segmentation
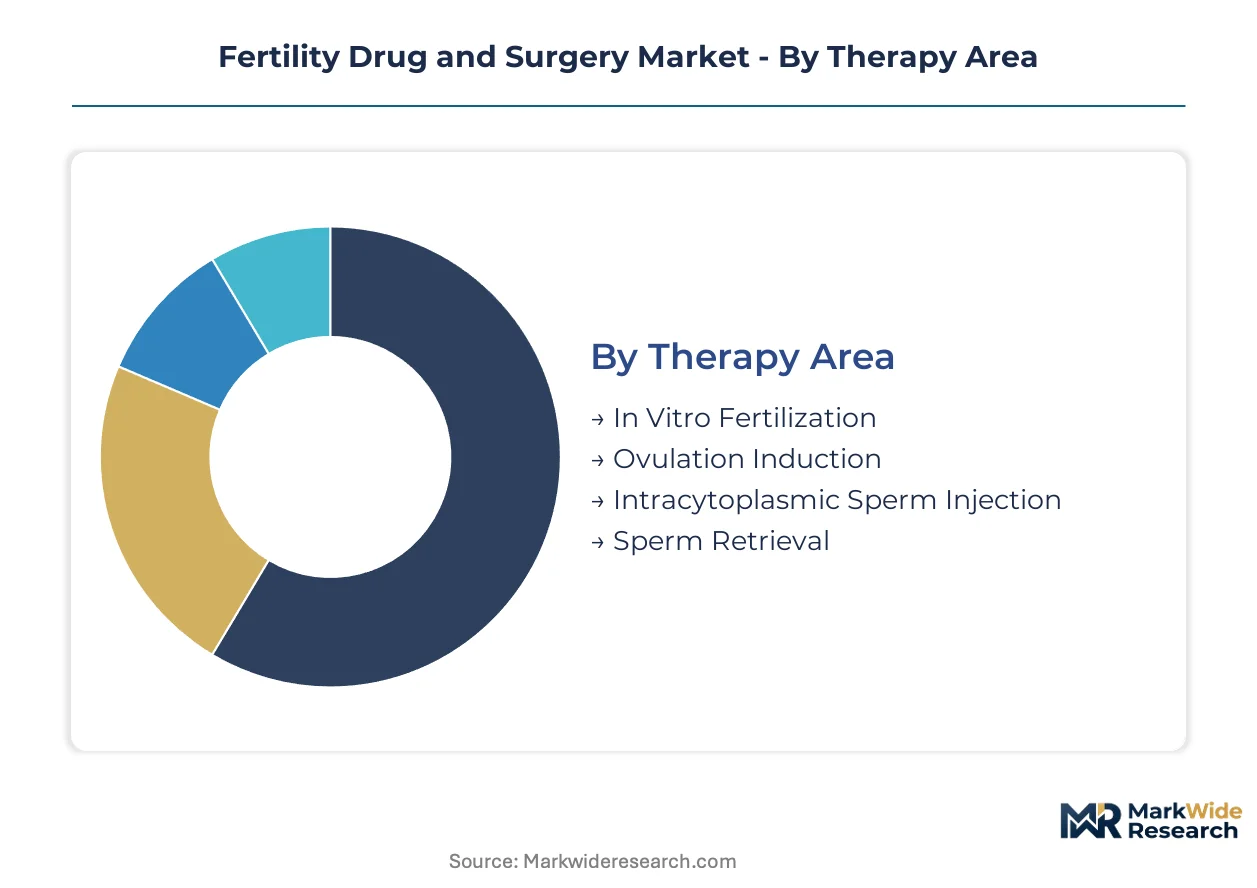
Therapy selection in fertility care hinges on diagnostic categorization of infertility factors, with treatment protocols cascading from pharmacological ovulation support through surgical gamete retrieval. Product and delivery specifications further stratify procurement decisions across clinic settings with varying infrastructure and patient volumes.
Therapy Area:
Patient diagnosis and male-factor prevalence determine therapy allocation across clinical workflows.
- In Vitro Fertilization:Multi-step procedure combining ovarian stimulation, oocyte retrieval, laboratory fertilization, and embryo transfer. Demand concentrates in United States metropolitan fertility networks where bundled cycle packages attract insured and self-pay patients seeking comprehensive outcome guarantees.
- Intracytoplasmic Sperm Injection:Micromanipulation technique injecting single sperm directly into ooplasm for severe male-factor cases. Adoption accelerates in Spain and Czech Republic cross-border reproductive centers where andrological indications drive procedural expansion beyond conventional IVF protocols.
- Ovulation Induction:Pharmacological stimulation for anovulatory patients using oral or injectable agents.
- Sperm Retrieval:Surgical extraction procedures for obstructive or non-obstructive azoospermia.
Volume sits with In Vitro Fertilization; growth tilts toward Intracytoplasmic Sperm Injection.
Product Type:
Manufacturing complexity and cold-chain requirements stratify margin structures and supplier concentration.
- Gonadotropins:Recombinant or urinary-derived FSH and LH formulations requiring precise ratio calibration for follicular recruitment. European biologics producers with validated fermentation capacity and temperature-controlled distribution dominate supply to high-volume United States clinic networks.
- Clomiphene Citrate:Selective estrogen receptor modulator inducing ovulation through hypothalamic feedback disruption. Generic saturation across United States outpatient settings compresses pricing power, relegating this agent to initial-line therapy before gonadotropin escalation.
- Aromatase Inhibitors:Off-label ovulation induction with letrozole protocols gaining traction in PCOS populations.
- Human Chorionic Gonadotropin:Trigger agent for final oocyte maturation with established biosimilar competition.
Revenue concentrates in gonadotropins; steepest expansion trajectory belongs to aromatase inhibitors in PCOS-specialized protocols.
End User:
Procedure volume and reimbursement access determine site-level procurement scale and product mix.
- Infertility Clinics:Dedicated reproductive medicine facilities performing cycle management from stimulation through transfer. United States multi-site networks achieve centralized purchasing leverage for gonadotropin annual supply agreements, bypassing wholesale distribution layers.
- Hospitals:Academic medical centers integrating fertility services with maternal-fetal medicine and genetics programs.
- Research Laboratories:Investigational sites conducting embryo culture protocol development and pharmaceutical trials.
- Private Practices:Solo or small-group obstetrics-gynecology providers offering limited ovulation induction services.
Cycle volume aggregates at infertility clinics; capability investment flows toward hospital-based academic centers.
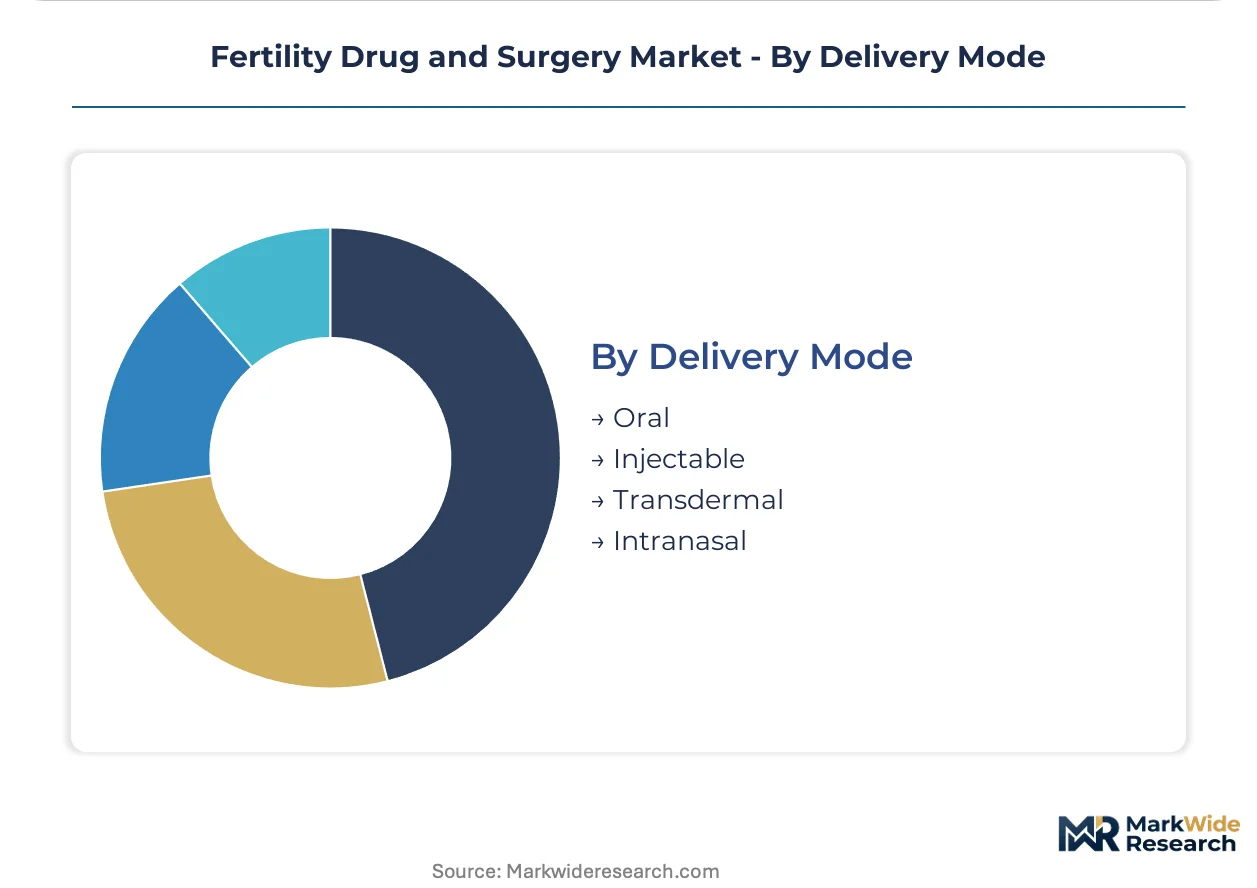
Delivery Mode:
Patient self-administration feasibility and pharmacokinetic requirements shape formulation development priorities.
- Injectable:Subcutaneous or intramuscular gonadotropin and hCG delivery enabling precise dose titration during ovarian stimulation. Cold-chain dependency from manufacturing through clinic dispensing elevates spoilage risk and logistics costs for peptide-based fertility drugs.
- Oral:Clomiphene and letrozole tablets supporting outpatient initiation without injection training requirements.
- Transdermal:Patch-based hormone delivery under investigation for patient convenience advantages.
- Intranasal:Nasal spray gonadotropin formulations in limited commercial availability.
Injectable modes capture procedural revenue; convenience-driven development targets transdermal alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recombinant gonadotropin fermentation capacity anchors commercial supply for fertility clinics across major consumption centers. European biologics producers with validated cold-chain infrastructure supply high-volume markets in North America and Asia-Pacific.
United States
Large multi-site fertility clinic networks in metropolitan corridors drive gonadotropin procurement volumes through direct-to-manufacturer annual supply agreements. FDA oversight under 21 CFR biologics regulations elevates compliance costs for imported recombinant formulations. Boston and New York corridor academic medical centers integrate IVF services with maternal-fetal medicine programs.
Germany
Specialized peptide manufacturing clusters in Baden-Württemberg and Bavaria sustain European gonadotropin supply for domestic and export markets. EMA fertility treatment guidelines and MDR device regulations standardize cross-border clinic accreditation protocols. Frankfurt-Rhine-Main logistics hubs enable temperature-controlled distribution to Central and Eastern European fertility centers.
Spain
Cross-border reproductive health tourism from France, Italy, and the UK concentrates procedure volumes in Barcelona and Madrid clinic networks. EMA-aligned regulatory frameworks facilitate patient mobility from markets with restricted public IVF funding cycles. Valencia and Andalusia specialized centers attract andrological cases requiring intracytoplasmic sperm injection expertise.
Japan
Aging demographics and delayed childbearing patterns expand addressable patient populations for assisted reproductive technology services. PMDA oversight of biologic fertility drugs maintains stringent lot-release testing requirements for imported gonadotropins. Tokyo-Osaka metropolitan corridors host concentrated fertility clinic networks with advanced embryology laboratory infrastructure.
India
Cost-competitive IVF cycle pricing attracts international patients from Middle East and Southeast Asian markets seeking affordable assisted reproduction. CDSCO regulatory pathways for biosimilar gonadotropins enable domestic manufacturing scale-up for regional export. Maharashtra and Karnataka urban centers develop fertility hub capacity with specialized embryologist training programs.
Fertility Drug and Surgery Market Competitive Landscape
Global majors compete with regional champions across recombinant biologics manufacturing and specialized device portfolios. Market structure tilts toward consolidated supply for gonadotropin APIs with fragmented distribution at the clinic procurement level. Three archetypes dominate: integrated pharmaceutical-biologics conglomerates, specialized reproductive health device manufacturers, and dedicated fertility drug formulators. Competitive moves concentrate on backward integration into fermentation capacity and geographic expansion through clinic network partnerships.
Within the integrated pharmaceutical tier, Merck and Bayer occupy positions anchored by long-standing hormone therapy expertise and validated GMP infrastructure across European and North American markets. Ferring Pharmaceuticals exemplifies the specialized fertility drug archetype with peptide-based formulation capabilities and controlled-temperature logistics networks. Among device-focused manufacturers, Cook Group and Cooper Companies represent the surgical instrument and embryology laboratory equipment segment serving high-volume clinic networks.
| Leading Market Players |
|---|
| Cook Group |
| Vitrolife |
| Merck |
| FUJIFILM Irvine Scientific |
| Thermo Fisher Scientific |
| Ferring Pharmaceuticals |
| Cooper Companies |
| Bayer |
| Organon |
| Others |
Supply & Pricing Matrix
Fermentation-grade cell culture media costs cascade through recombinant gonadotropin manufacturing into tiered clinic procurement contracts, with European biologics producers commanding premium positioning against urinary-derived alternatives in United States fertility networks.
Pricing Analysis
Cycle-outcome guarantees bundled with annual supply agreements separate premium-tier United States multi-site networks from standard-tier regional clinics and economy-tier international patient hubs in Spain and the Czech Republic. Price differentiation hinges on cold-chain certification grade and embryology laboratory accreditation tier, with FDA 21 CFR compliance adding substantial service overhead. Cost compression in oral ovulation induction agents intensifies as generic clomiphene citrate saturation eliminates brand premium. Self-pay international patients at cross-border reproductive centers exhibit highest price sensitivity; insured patients at large United States networks demonstrate lowest sensitivity due to bundled coverage structures.
Supply Chain Analysis
Specialized biologics workforce availability in Baden-Württemberg and Bavaria manufacturing clusters anchors European gonadotropin fermentation capacity, with secondary concentration in Tokyo-Osaka metropolitan corridors serving Asia-Pacific demand. Production draws from recombinant DNA cell lines, pharmaceutical-grade culture media, and temperature-controlled packaging materials. Single-source vulnerability concentrates in validated cold-chain logistics providers spanning Frankfurt-Rhine-Main distribution hubs. Distribution runs through direct-to-clinic procurement platforms that disintermediate wholesale layers for high-volume United States fertility networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recombinant gonadotropin fermentation capacity constraints prop pricing power for validated GMP-certified producers, with embryologist certification bottlenecks limiting clinic network expansion regardless of capital availability.
For Market Incumbents: Acquire distressed fermentation assets in European manufacturing corridors to consolidate recombinant gonadotropin supply. Biologic manufacturing complexity and FDA 21 CFR potency enforcement create defensive moats against emerging biosimilar entrants. Backward integration into peptide formulation capabilities secures margin capture from raw inputs through finished dose. For New Entrants and Emerging Players: Direct-to-clinic digital procurement platforms offer the lowest-friction entry vector for specialized fertility drug distribution. White-space concentrates in aromatase inhibitor protocols for PCOS-specialized clinics and transdermal hormone delivery development. Target Spanish and Czech Republic cross-border reproductive centers with andrology-focused service bundles. For Investors and Strategic Acquirers: Distressed-cycle entries favor device-drug combination specialists with EMA MDR certification progress in Central European manufacturing geographies. Long-term viability centers on embryology laboratory automation and AI-powered embryo selection platforms. Watch FDA analytical method requirement tightening for gonadotropin lot release as inflection signal for incumbent margin pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | Temperature-controlled logistics networks from Baden-Württemberg fermentation sites enable premium United States clinic supply agreements. |
| Embryology Laboratory Automation | AI-powered embryo selection platforms compress outcome variability across multi-site fertility networks in metropolitan corridors. |
| Device-Drug Combination Development | Integrated embryo transfer catheter systems with hormonal delivery protocols differentiate positioning under EMA MDR frameworks. |
| Cross-Border Reproductive Center Partnerships | Spanish and Czech Republic clinic networks attract French and Italian patients seeking unrestricted IVF cycle access. |
| Embryologist Training Program Scale-Up | Specialized micromanipulation certification pipelines alleviate workforce bottlenecks constraining intracytoplasmic sperm injection expansion. |
Research Methodology
Independent corroboration across fertility clinic procurement managers, reproductive endocrinology practice administrators, and pharmaceutical regulatory affairs specialists underwrites the qualitative findings. Secondary validation sources include FDA 21 CFR biologics filings, EMA fertility treatment guideline documentation, and hospital system GPO contract databases. Bottom-up procedure volume estimates from infertility clinic networks triangulate against top-down gonadotropin manufacturer shipment data.
Comparable historical reference periods anchored the forecast window to pre-pandemic baseline cycle volumes and reimbursement policy shifts. Segmentation dimensions modeled include therapy area, product type, end user facility scale, and regional regulatory cluster. CAGRs were derived from trend extrapolation of procedure volume growth and pricing trajectory analysis. Industry-specific inputs encompass embryologist workforce pipeline data and cross-border patient mobility flow estimates.
The model holds under stable reimbursement policy conditions; deviation in Medicare coverage determinations or private insurer IVF cycle limits would shift demand concentration patterns. A small set of named triggers warrants ongoing watch: FDA potency standard enforcement intensity, EMA MDR device certification timelines, and national health authority fertility funding policy revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Cryoprecipitated Antihemophilic Factor Market
Pharmaceuticals
Global Autoimmune Drugs Market
Pharmaceuticals
Global Chickenpox Vaccine Market
Pharmaceuticals
Clindamycin Palmitate Hcl Market
Pharmaceuticals
Valganciclovir Market
Pharmaceuticals
Macrolides Market
Pharmaceuticals
Europe Diabetes Drugs Market
Pharmaceuticals
Europe Anesthesia Drugs Market
Pharmaceuticals
Global Ovulation Inducing Drugs Market
Pharmaceuticals
Asia-Pacific Pharmaceutical Contract Manufacturing Organization Market
Pharmaceuticals
Global Hepatitis B Vaccines Market
Pharmaceuticals
Short-Acting Insulin Market
Pharmaceuticals
Anticonvulsants Market
Pharmaceuticals
Retinal Drugs and Biologics Market
Pharmaceuticals
Contract Pharmaceutical Fermentation Services Market
Pharmaceuticals
Pharmaceutical Solid Dosage Contract Manufacturing Market