
 Canada Animal Health Care Market | 2026-2036
Canada Animal Health Care Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Animal Health Care Market Insights
Pharmaceutical-grade biologics certification is redrawing competitive boundaries in Canadian animal health. Zoetis leverages its transboundary disease portfolio to anchor supply relationships with federal quarantine programs. Boehringer Ingelheim sustains dominance in respiratory vaccines through captive manufacturing at its Laval facility. Merck Animal Health differentiates via digital diagnostic integration with Prairie veterinary networks.
Canada animal health care encompasses prescription therapeutics, biologicals, nutritional additives, and diagnostic services formulated to prevent, treat, or manage disease across production and companion animals. Products must meet Health Canada and PMRA stability specifications, with cold-chain distribution mandatory for attenuated live vaccines destined for remote northern operations. Vaccines command the deepest margin pools due to federal mandatory immunization schedules for bovine brucellosis and avian influenza. Feed additives face accelerating scrutiny as the Canadian Food Inspection Agency tightens medicated feed oversight, redirecting formulation investment toward non-antibiotic growth promoters. Veterinary clinics represent the most concentrated end-user channel, capturing the majority of companion animal pharmaceutical dispensing under provincial practice acts.
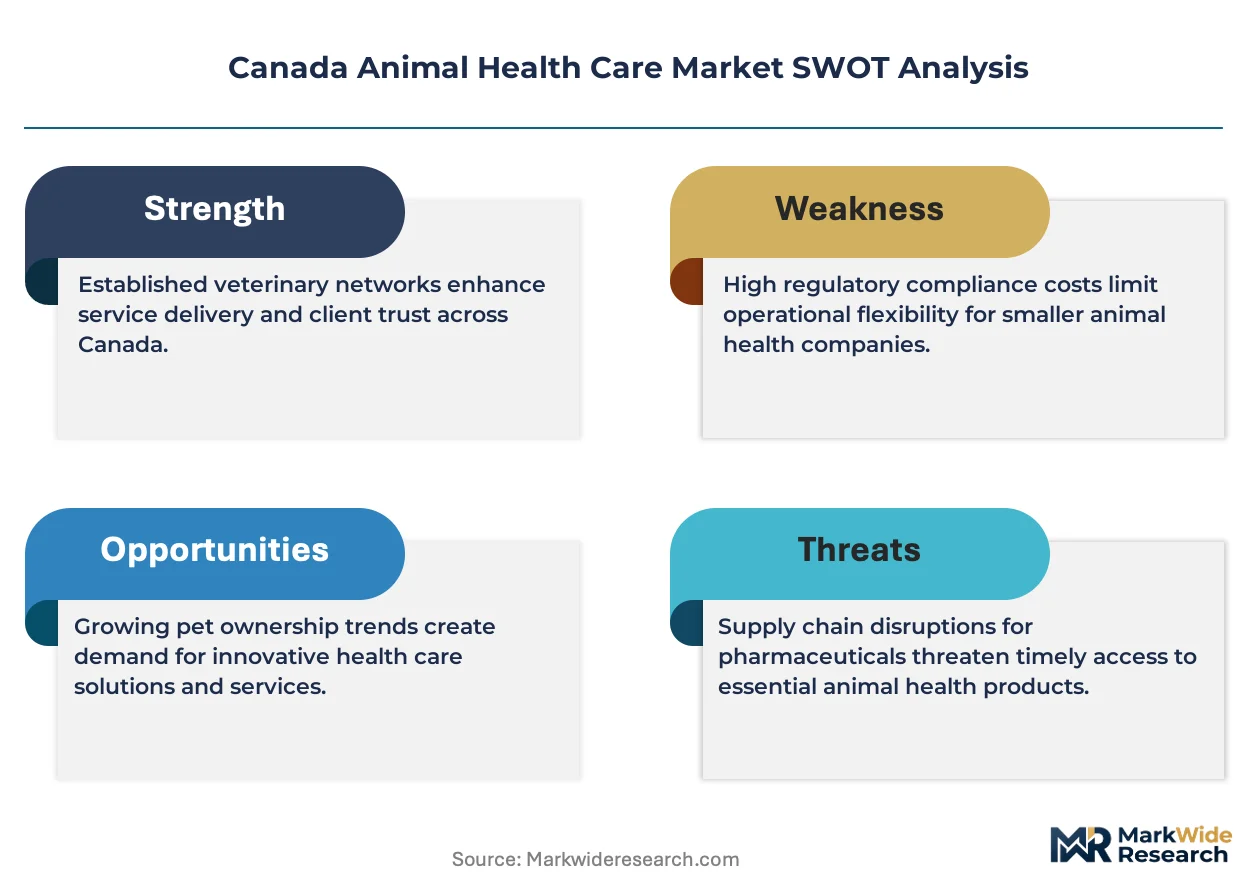
Health Canada, the PMRA, and the Canadian Food Inspection Agency collectively govern product registration, residue limits, and import biosecurity for animal health inputs. The Veterinary Drugs Directorate mandates veterinary prescription status for all medically important antimicrobials, restructuring farm-level procurement through accredited clinics. Stakeholders must monitor pending changes to the Feeds Act regulations governing novel ingredients, as these will determine market access timelines for probiotic and enzyme additive suppliers.
Market Dynamics
Federal antimicrobial prescription mandates from Health Canada and the PMRA are restructuring procurement flows across Canadian livestock operations, forcing veterinary clinic intermediation into previously direct farm-level pharmaceutical purchases.
Growth Catalysts
- Preventive Diagnostics Expansion:Companion animal owners in Ontario and British Columbia are expanding spending on routine screening panels, creating recurring revenue streams for veterinary service networks.
- Health Canada Residue Protocols:Tightened monitoring standards for livestock antimicrobials are pushing producers toward accredited veterinary oversight, formalizing clinic-based procurement relationships.
- Prairie Feedlot Consolidation:Large-scale cattle operations across Alberta and Saskatchewan drive bulk vaccine procurement, concentrating demand among high-volume pharmaceutical suppliers.
Market Restraints
- Cold-Chain Distribution Costs:Attenuated live vaccines require uninterrupted refrigeration for remote northern operations, elevating logistics expenditure and limiting supplier participation.
- Feed Additive Regulatory Scrutiny:The Canadian Food Inspection Agency's tightening oversight of medicated feeds is compressing formulation flexibility and elevating compliance expenditure for additive manufacturers.
- Antibiotic Substitution Pressure:Non-antibiotic growth promoters face efficacy variability against established pharmaceutical alternatives, creating adoption friction among risk-averse producers.
Strategic Opportunities
- Digital Diagnostic Integration:Remote monitoring platforms converging with laboratory information systems enable real-time herd health surveillance across dispersed Prairie operations.
- Northern Territories Undersupply:Yukon and Northwest Territories veterinary infrastructure gaps present white-space potential for mobile clinical services and telemedicine platforms.
- Novel Ingredient Regulatory Pathway:Pending Feeds Act amendments governing probiotics and enzymes will determine first-mover advantage timelines for alternative additive suppliers.
Industry Challenges
- Veterinary Workforce Scarcity:Rural large-animal practitioner shortages across Manitoba and Saskatchewan strain service capacity for expanding feedlot operations.
- Biologics Stability Certification:Health Canada stability specifications for temperature-sensitive vaccines extend product registration timelines and elevate capital requirements for manufacturing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Animal Health Care Market |
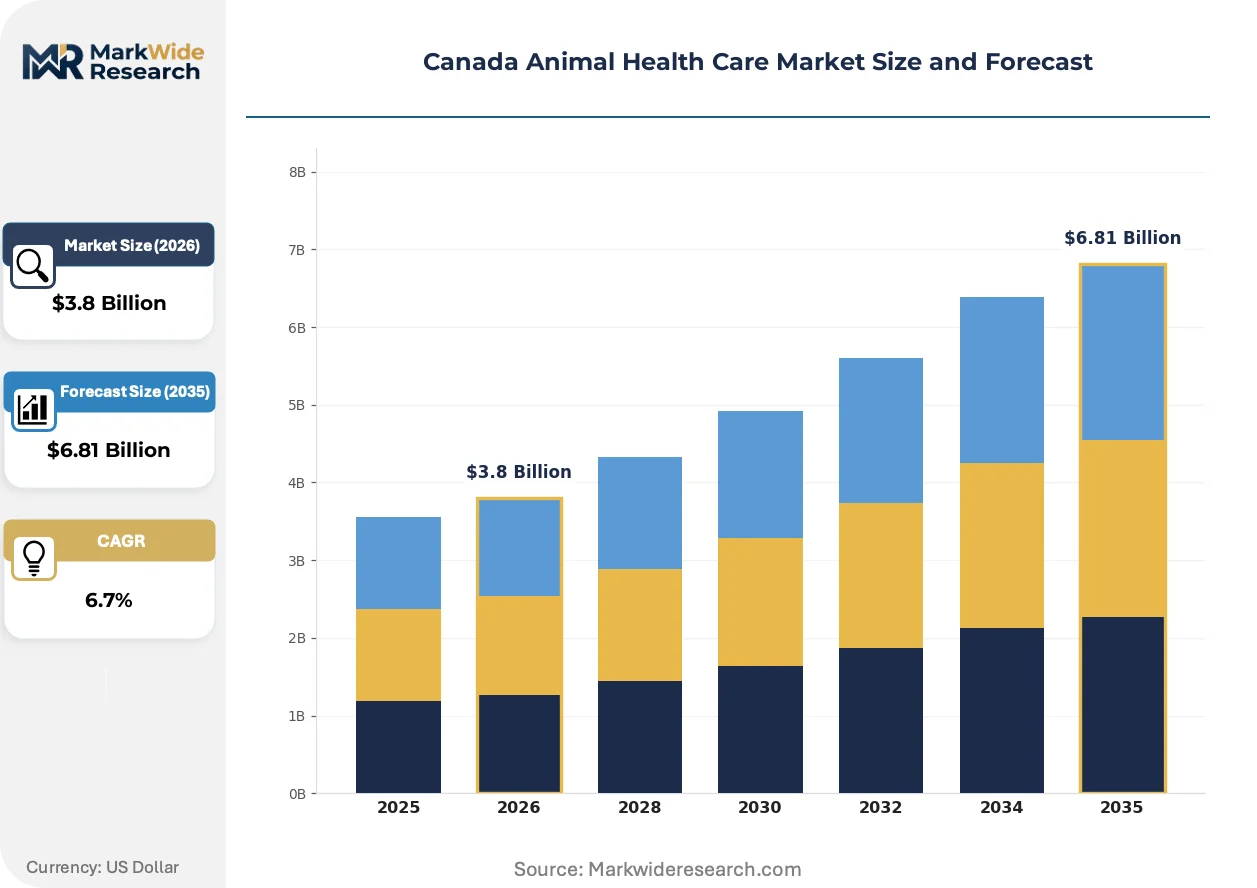
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Medicines, Feed Additives, Supplements Animal Type: Livestock, Poultry, Companion Animals, Aquaculture Delivery Mode: Injectables, Oral, Topical, Implants End User: Veterinary Clinics, Farms, Research Institutions, Pet Retailers |
| Companies Covered | Zoetis, Boehringer Ingelheim, Merck Animal Health, Elanco Animal Health, IDEXX Laboratories, Virbac, Ceva Santé Animale, Vetoquinol Canada, Neogen Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Animal Health Care Market Trends and Innovations
Technology convergence and regulatory stringency are compressing traditional supply relationships while elevating data-centric service models across Canadian animal health channels.
Point-of-care PCR diagnostic platforms are supplanting centralized laboratory testing for respiratory pathogen identification in feedlot settings. Large-scale Alberta cattle operations are adopting pen-side molecular screening to compress disease response windows from days to hours. This acceleration is collapsing traditional veterinary service billing models built on sample transport and external lab markups.
Health Canada's Veterinary Drugs Directorate prescription mandate for medically important antimicrobials is restructuring farm-level procurement through accredited clinic networks. Producers now face transaction friction and margin compression from intermediated pharmaceutical purchasing. Prairie beef operations are responding by consolidating veterinary service contracts to secure volume pricing and streamline compliance documentation.
Subscription-based preventive care packages are displacing episodic treatment billing in companion animal channels. Ontario and British Columbia clinic networks are bundling vaccinations, diagnostics, and telehealth access into annual membership structures. This shift concentrates client retention risk with service providers while transferring cost predictability to pet owners in urban markets.
Canada Animal Health Care Market Segmentation
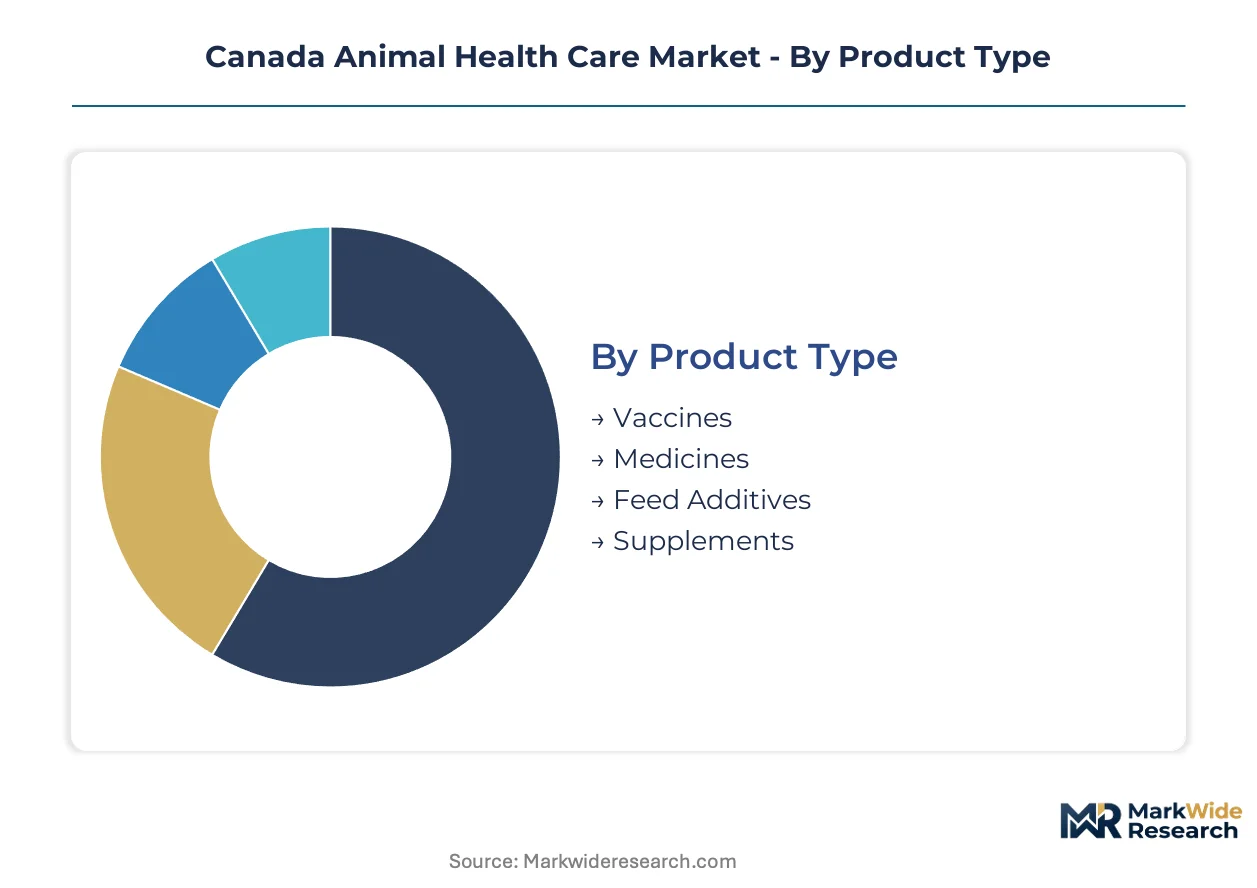
Segmentation in Canadian animal health reveals how regulatory pressure and supply chain configuration concentrate margin pools. Understanding these divisions exposes where substitution threats and pricing power intersect across product categories, animal types, and delivery channels.
Product Type:
Substitution pressure runs strongest against pharmaceutical-dependent segments as Health Canada antimicrobial mandates force formulation pivots toward biological alternatives.
- Vaccines:Attenuated live and inactivated biologicals requiring PMRA stability certification and cold-chain integrity. Prairie feedlots drive bulk procurement of bovine respiratory and clostridial vaccines under federal mandatory immunization schedules for brucellosis.
- Medicines:Prescription antimicrobials, parasiticides, and anti-inflammatories now intermediated through veterinary clinics under Health Canada Veterinary Drugs Directorate mandates. Ontario and British Columbia companion animal channels absorb the majority of dispensed therapeutics under provincial practice acts.
- Feed Additives:Medicated and non-medicated nutritional modifiers facing Canadian Food Inspection Agency scrutiny.
- Supplements:Nutraceuticals and dietary enhancers for companion animal wellness channels.
Vaccines retain volume leadership; feed additives hold the steepest expansion curve as probiotic alternatives displace antibiotic growth promoters.
Animal Type:
Cost tier stratification separates capital-intensive production systems from discretionary-spend companion channels with divergent procurement pathways.
- Livestock:Cattle, swine, and sheep operations across Alberta and Saskatchewan feedlots. Health Canada residue protocols and veterinary prescription mandates restructure pharmaceutical procurement through accredited clinic networks, compressing direct farm-level purchasing.
- Companion Animals:Canine and feline populations concentrated in Ontario and British Columbia urban corridors. Preventive diagnostics and subscription wellness packages displace episodic treatment billing, concentrating client retention risk with veterinary service providers.
- Poultry:Broiler and layer operations under federal avian influenza immunization requirements.
- Aquaculture:Salmon and shellfish health inputs for British Columbia marine farming.
Livestock retains volume leadership; companion animals hold the steepest expansion curve.
Delivery Mode:
Application method determines cold-chain burden and administration labor, with implications for remote northern coverage and feedlot efficiency.
- Injectables:Parenteral vaccines and pharmaceuticals requiring sterile administration technique. Prairie cattle operations favor subcutaneous and intramuscular delivery for respiratory vaccine protocols, though workforce scarcity across Manitoba and Saskatchewan strains service capacity.
- Oral:Feed-through medications and water-soluble therapeutics. Medicated feed oversight from the Canadian Food Inspection Agency elevates compliance documentation for inclusion-level tracking and withdrawal period management.
- Topical:Transdermal parasiticides and wound treatments for companion animal and equine channels.
- Implants:Sustained-release hormonal and pharmaceutical devices for feedlot growth optimization.
Injectables retain volume leadership; oral formulations hold the steepest expansion curve as feed additive regulation redirects investment toward water and feed delivery systems.
End User:
Customer type dictates procurement authorization, with regulatory gatekeeping concentrating dispensing power in accredited clinical channels.
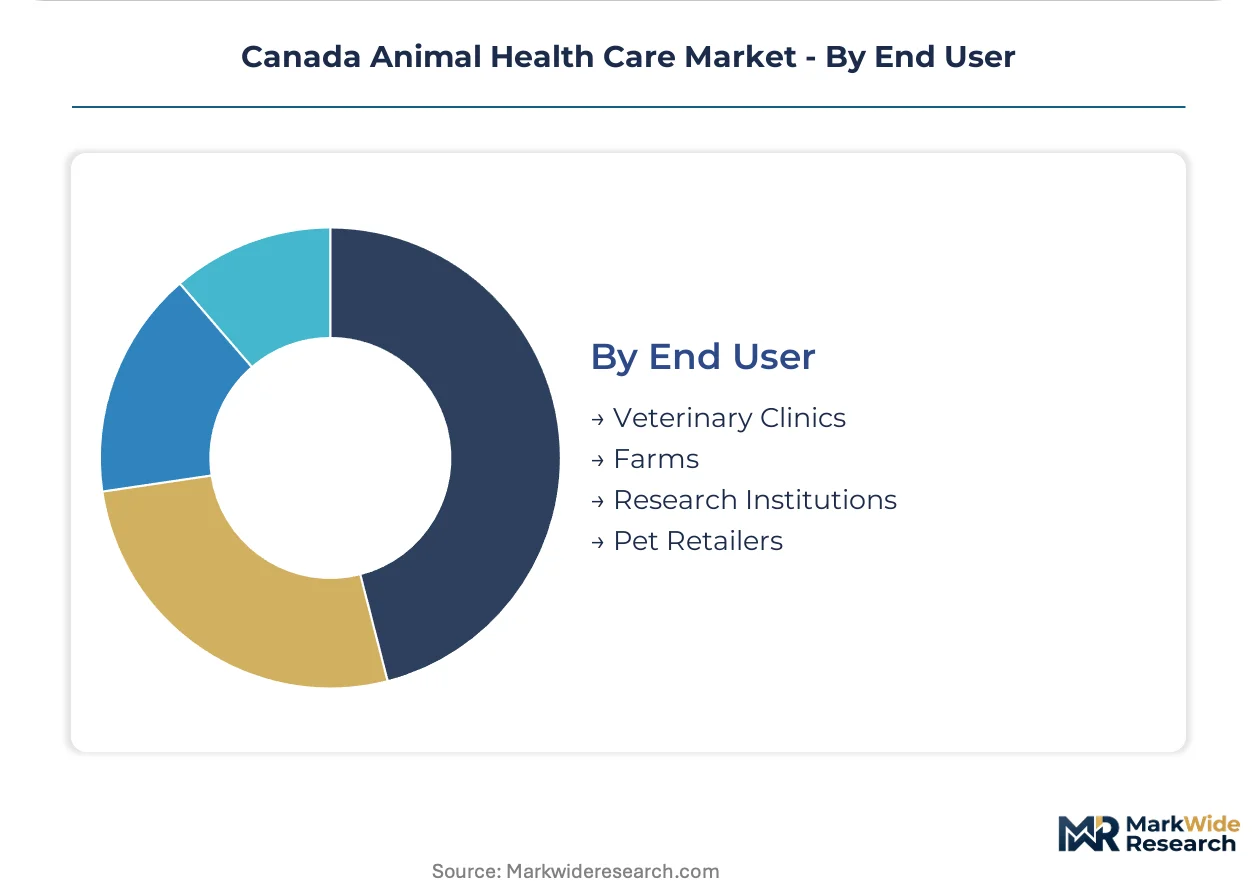
- Veterinary Clinics:Provincial practice acts mandate clinic-based pharmaceutical dispensing for prescription antimicrobials. Ontario and British Columbia networks bundle diagnostics, vaccination, and telehealth into annual membership structures, transferring cost predictability to urban pet owners.
- Farms:Livestock operations consolidating veterinary service contracts to secure volume pricing and streamline Health Canada compliance documentation. Direct pharmaceutical purchasing now restricted to over-the-counter categories.
- Research Institutions:Universities and federal facilities conducting veterinary pharmaceutical and vaccine trials under PMRA investigational protocols.
- Pet Retailers:Non-prescription supplements and wellness products for companion animal over-the-counter channels.
Veterinary clinics retain volume leadership; farms hold the steepest expansion curve as feedlot consolidation drives contract restructuring toward integrated service models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's animal health trade flows reflect a net import position for specialized biologics, with domestic production concentrated in Quebec and Ontario while Prairie feedlot demand draws supply from cross-border distributors. Provincial regulatory divergence creates distinct procurement corridors across the federation.
Ontario
Companion animal spending concentrates in the Greater Toronto Area and Ottawa corridor, where urban pet ownership drives preventive diagnostics adoption. Health Canada Veterinary Drugs Directorate prescription enforcement has restructured pharmaceutical dispensing through accredited clinic networks. Guelph anchors veterinary research capacity through the Ontario Veterinary College, supporting local vaccine development pipelines.
Quebec
Laval hosts Boehringer Ingelheim's captive manufacturing facility for respiratory vaccines, anchoring domestic biologics production. The province's dairy sector generates concentrated demand for reproductive health pharmaceuticals and mastitis therapeutics. PMRA stability certification requirements extend product registration timelines for temperature-sensitive vaccines distributed to northern operations.
Alberta
Cattle feedlot consolidation across the Calgary-Edmonton corridor drives bulk procurement of bovine respiratory and clostridial vaccines. Large-scale operators are consolidating veterinary service contracts to secure volume pricing under Health Canada antimicrobial prescription mandates. Cold-chain distribution costs for attenuated live vaccines elevate logistics expenditure for remote northern coverage.
British Columbia
Companion animal channels in Vancouver and Victoria absorb premium wellness spending, with subscription preventive care packages displacing episodic billing. The province's aquaculture sector generates specialized demand for salmon health inputs. Canadian Food Inspection Agency medicated feed oversight redirects investment toward non-antibiotic growth promoters in marine farming operations.
Prairie Provinces
Saskatchewan and Manitoba livestock operations face veterinary workforce scarcity, straining service capacity for expanding feedlot infrastructure. Federal mandatory immunization schedules for bovine brucellosis sustain vaccine volume procurement. Mobile clinical services and telemedicine platforms present white-space potential for underserved rural territories.
Canada Animal Health Care Market Competitive Landscape
Listed leaders compete with private specialists across manufacturing scale and distribution reach. The Canadian market exhibits tiered concentration, with multinational pharmaceutical corporations commanding biologics certification and captive production infrastructure while regional distributors capture feed additive and generic pharmaceutical channels. Three archetypes dominate: integrated biologics manufacturers with Health Canada-approved stability protocols, veterinary clinic network consolidators intermediating prescription dispensing, and specialized feed additive formulators navigating CFIA oversight. Competitive positioning hinges on M&A-driven clinic network expansion and backward integration into cold-chain distribution infrastructure.
Within the integrated biologics tier, Zoetis and Boehringer Ingelheim occupy positions anchored by federal quarantine program relationships and captive Laval manufacturing respectively. Merck Animal Health exemplifies the diagnostic convergence archetype through digital platform integration with Prairie veterinary networks. These three entities represent distinct competitive vectors: transboundary disease portfolio depth, respiratory vaccine manufacturing proximity, and real-time herd health surveillance capability.
| Leading Market Players |
|---|
| Zoetis |
| Boehringer Ingelheim |
| Merck Animal Health |
| Elanco Animal Health |
| IDEXX Laboratories |
| Virbac |
| Ceva Santé Animale |
| Vetoquinol Canada |
| Neogen Corporation |
| Others |
Pricing and Supply Chain Analysis
Ninety-day cold-chain integrity requirements for attenuated live vaccines concentrate pricing power with Health Canada-certified biologics manufacturers while elevating logistics expenditure for remote northern coverage. Prairie feedlot consolidation amplifies volume-based procurement leverage, compressing margins for non-integrated pharmaceutical suppliers unable to match captive manufacturing scale.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across Alberta and Saskatchewan feedlot operations. Three-tier pricing structure across premium, standard, and economy levels reflects Health Canada stability certification grade, volume scale, and geographic delivery cost to remote territories. Pricing pressure stems from veterinary clinic intermediation under PMRA prescription mandates, transferring margin to accredited dispensing networks. Small-scale Manitoba livestock operations exhibit highest price sensitivity due to fragmented procurement scale, while integrated Prairie feedlots secure least-sensitive positioning through consolidated annual contracts.
Supply Chain Analysis
Cold-chain distribution chokepoints across northern Quebec and Ontario underwrite supply vulnerability for temperature-sensitive vaccines destined for Yukon and Northwest Territories operations. Manufacturing concentration in Quebec and Ontario draws from US and European API sources, with formulation dependencies on bovine serum and embryonated egg substrates. Single-source vulnerability runs through captive Laval production for respiratory biologics. Distribution runs through veterinary clinic networks intermediating prescription antimicrobials, with direct farm-level purchasing restricted to over-the-counter categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in digital diagnostic convergence and northern territory service gaps, as federal prescription mandates and geographic undersupply create defendable niches for specialized entrants.
For Market Incumbents: Shield market position by deepening backward integration into cold-chain distribution infrastructure for remote northern coverage, and accelerate Health Canada stability certification investment to extend product registration timelines as a competitive moat against generic biologics entrants. Veterinary workforce scarcity across Manitoba and Saskatchewan threatens service capacity for expanding feedlot operations. For New Entrants and Emerging Players: Differentiate on telemedicine platform integration for Yukon and Northwest Territories veterinary infrastructure gaps, where mobile clinical services face minimal incumbent saturation. Target subscription-based preventive care packaging for Ontario and British Columbia companion animal channels as the most penetrable segment, deploying direct-to-consumer digital onboarding to bypass established clinic network gatekeeping. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational pharmaceutical parents seeking to divest non-core feed additive portfolios facing Canadian Food Inspection Agency regulatory compression. Long-term viability favors integrated biologics manufacturers with captive Health Canada-approved stability protocols and federal quarantine program relationships. Monitor pending Feeds Act amendments governing probiotic and enzyme novel ingredients as the critical inflection signal for alternative additive supplier market access timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Distribution Expansion | Health Canada stability specifications mandate uninterrupted refrigeration for attenuated live vaccines reaching remote northern operations. |
| Digital Diagnostic Platform Integration | Point-of-care PCR convergence with Prairie veterinary networks compresses disease response windows from days to hours. |
| Veterinary Clinic Network Consolidation | PMRA prescription mandates formalize accredited clinic intermediation, capturing pharmaceutical dispensing margin pools. |
| Novel Ingredient Regulatory Pathway Investment | Pending Feeds Act amendments determine first-mover advantage timelines for probiotic and enzyme additive suppliers. |
| Subscription Preventive Care Packaging | Ontario and British Columbia urban pet owners transfer cost predictability through annual membership structures bundling diagnostics and telehealth. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with veterinary clinic network directors, Prairie feedlot operations managers, Health Canada regulatory affairs specialists, and pharmaceutical distribution channel partners. Secondary validation drew from PMRA product registration databases, Canadian Food Inspection Agency medicated feed oversight filings, provincial veterinary practice act documentation, and customs trade flow records. Bottom-up volume estimates from feedlot procurement patterns and clinic dispensing data were triangulated against top-down market sizing from manufacturer production disclosures.
Across the analysis window, forecasts were constructed through multi-dimensional segmentation modeling across product type, animal category, delivery mode, and end-user channel, with additional granularity for provincial regulatory cluster variations. CAGRs were derived from historical procurement trend extrapolation adjusted for policy intervention impacts, incorporating veterinary workforce scarcity indices and cold-chain logistics cost trajectories as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside Health Canada regulatory stability, PMRA prescription enforcement continuity, or Prairie feedlot consolidation trajectories would require recalibration. Practitioners should keep alternative scenarios live as Feeds Act amendment timelines and northern territory infrastructure investment decisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Animal Health
China Companion Animal Health Market
Animal Health
Canine Arthritis Treatment Market
Animal Health
Duck Medicine and Vaccines Market
Animal Health
Cattle Health Market
Animal Health
Global Farm Animal Healthcare Market
Animal Health
Animal Blood Plasma Products and Derivatives Market
Animal Health
Companion Animal Healthcare Market
Animal Health
US Companion Animal Health Market
Animal Health
Zoonotic Disease Treatment Market
Animal Health
Rat Model Market
Animal Health
Laboratory Animal Models Market
Animal Health
US Military Animals Market
Animal Health
Equine Healthcare Market
Animal Health
African Horse Sickness Treatment Market
Animal Health
Artificial Intelligence (AI) in Animal Health Market
Animal Health
Equine Fluid Therapy Market