
 Adiponectin Testing Market | 2026-2036
Adiponectin Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Adiponectin Testing Market Outlook
The EU Green Deal is pivoting biomedical manufacturers toward greener reagent formulations and reduced hazardous waste in immunoassay production. Thermo Fisher Scientific leverages its global distribution network to sustain kit availability across regulated markets. Bio-Rad Laboratories specializes in precision antibody pair development, anchoring its position in high-sensitivity ELISA workflows. Merck KGaA competes through controlled supply of recombinant adiponectin standards used in assay calibration.
Adiponectin testing quantifies circulating concentrations of this adipokine protein, typically measured in micrograms per milliliter using antibody-based detection systems, to assess metabolic health and insulin sensitivity in clinical and research settings. The ELISA Kits segment dominates current volume due to established protocols and lower capital requirements, while Mass Spectrometry platforms represent the fastest-growing technology category as laboratories seek multiplexed, high-specificity quantification. Diagnostic Labs capture the largest end-user share through centralized high-throughput processing, whereas Research Institutions drive premium pricing for custom assay development in obesity studies and cardiovascular disease cohorts.
The FDA regulates adiponectin assays as Class II medical devices requiring 510(k) clearance, while the EU MDR imposes stricter clinical evidence standards for in vitro diagnostic kits marketed in Europe. ISO 13485 certification shapes supplier qualification, determining which reagent manufacturers gain access to hospital procurement channels. Stakeholders must monitor evolving biomarker qualification pathways at the FDA and EMA, as formal recognition would unlock reimbursement and accelerate clinical adoption beyond research settings.
Market Dynamics
The adiponectin testing market is restructuring around biomarker qualification pathways that determine reimbursement eligibility and clinical protocol adoption. FDA and EMA biomarker recognition programs are compressing the validation timeline for assay manufacturers while raising evidentiary thresholds.
Growth Catalysts
- Metabolic syndrome panel expansion:Clinical diagnostic laboratories in the United States are integrating adiponectin assays into routine cardiovascular risk assessments. This protocol standardization drives volume through centralized high-throughput processing.
- EU Green Deal compliance:Biomedical manufacturers are reformulating immunoassay reagents to reduce hazardous waste. This regulatory pressure accelerates greener production methods across European supply chains.
- Mass spectrometry multiplexing:Research institutions are adopting LC-MS platforms for simultaneous adipokine quantification. The technology enables higher specificity measurements in obesity cohort studies.
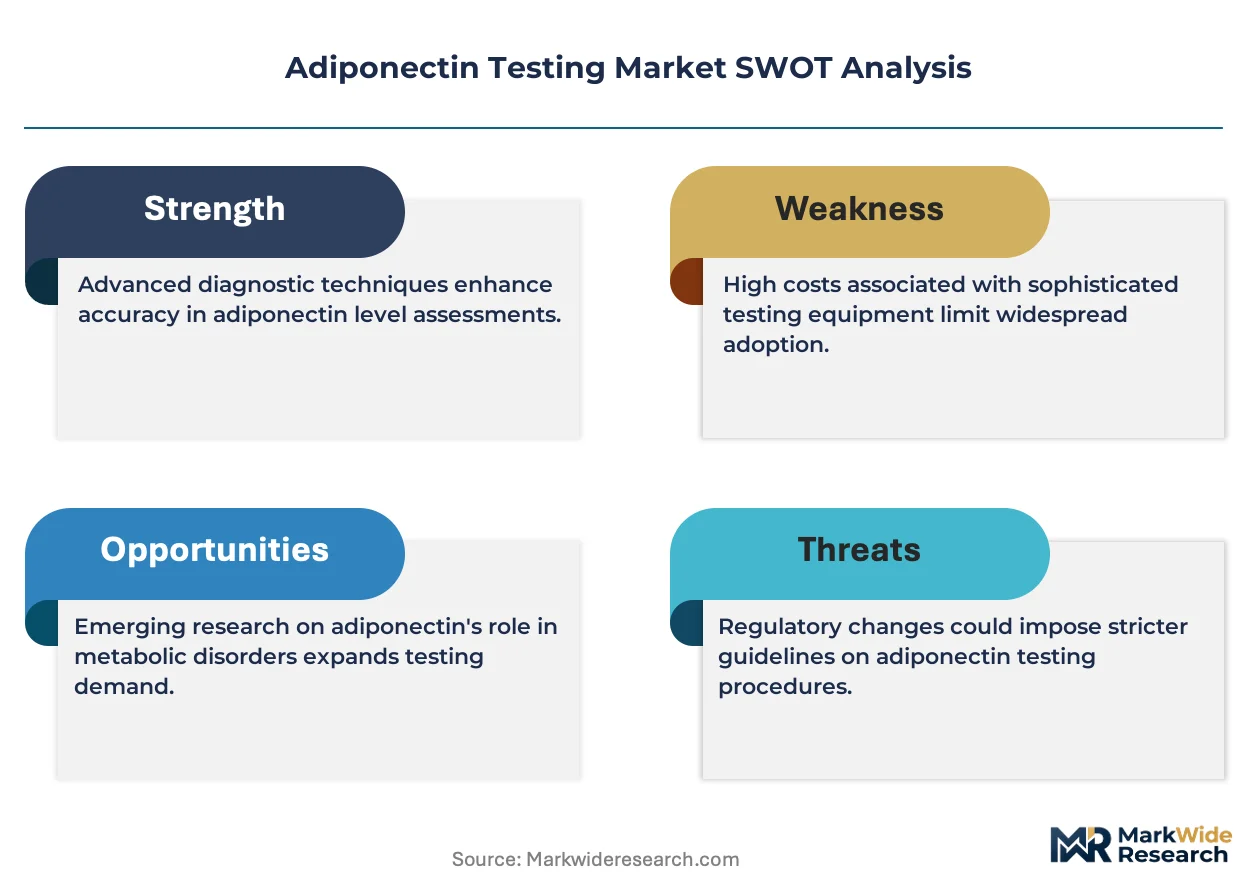
Market Restraints
- Antibody pair scarcity:High-affinity monoclonal antibodies for adiponectin detection remain concentrated among specialized developers. This supply bottleneck constrains kit manufacturing scale-up.
- EU MDR clinical evidence requirements:Stricter documentation standards for in vitro diagnostic kits extend regulatory timelines. Small manufacturers face disproportionate compliance burdens.
- Recombinant standard cost volatility:Purified adiponectin protein for assay calibration commands premium pricing. Input cost fluctuations compress margins for mid-tier kit producers.
Strategic Opportunities
- Point-of-care decentralization:Miniaturized lateral flow formats could penetrate physician office laboratories. This channel expansion bypasses centralized lab dependency.
- Japan's metabolic disease screening mandate:METI-supported preventive health programs create demand for adiponectin testing in diabetes management protocols.
- Digital pathology convergence:AI-assisted image analysis is integrating with immunoassay workflows. This pairing enables automated result interpretation in high-volume settings.
Industry Challenges
- ISO 13485 certification timelines:Quality management system audits for IVD manufacturers extend 12-18 months. Hospital procurement channels remain inaccessible during this gap.
- Cross-platform standardization gaps:ELISA and mass spectrometry outputs lack harmonized reference ranges. Clinical interpretation variability limits protocol adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adiponectin Testing Market |
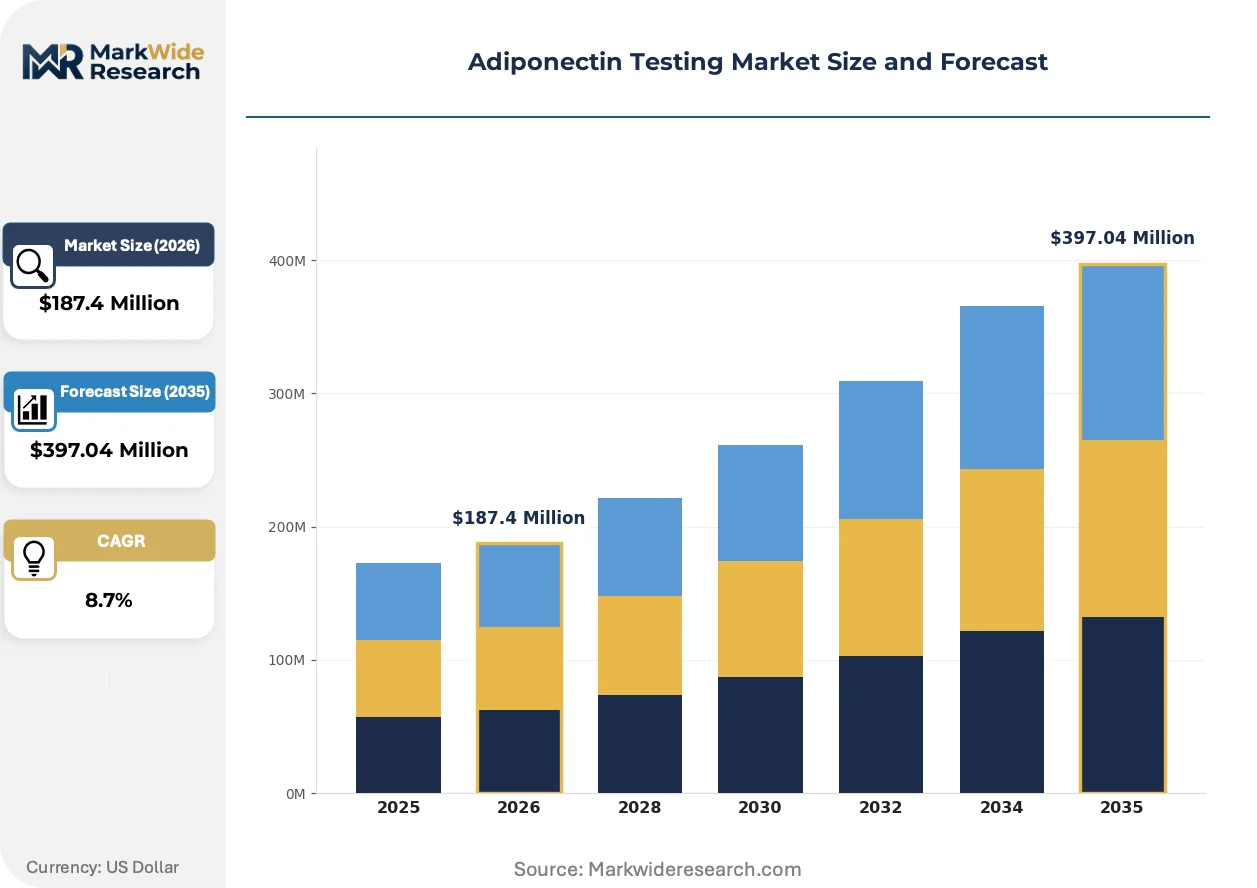
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
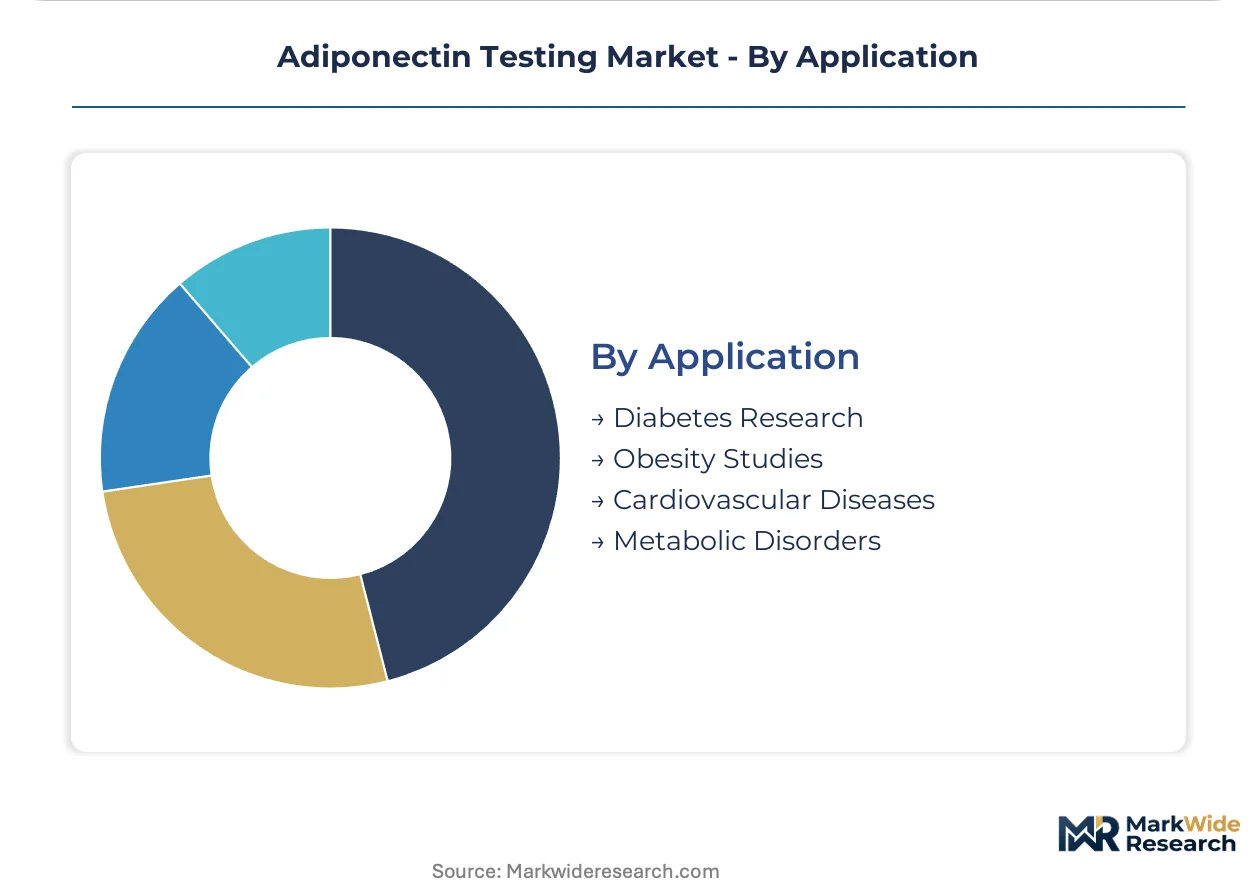
| Segmentation | Product Type: ELISA Kits, Western Blotting Kits, Reagents, Assay Kits Technology: Immunoassays, PCR, Mass Spectrometry, Microarrays End User: Hospitals, Diagnostic Labs, Research Institutions, Clinics Application: Diabetes Research, Obesity Studies, Cardiovascular Diseases, Metabolic Disorders |
| Companies Covered | Thermo Fisher Scientific Inc., Merck KGaA, Bio-Rad Laboratories, Inc., Eagle Biosciences, Inc., Boster Biological Technology, STRATEC SE, Laboratory Corporation of America Holdings, ERBA Diagnostics, Inc., Randox Laboratories Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adiponectin Testing Market Strategic Shifts
Technology convergence and regulatory biomarker pathways are compressing the gap between research-grade and clinical-grade adiponectin quantification. Assay developers must navigate simultaneous pressures for higher analytical specificity and streamlined validation.
Mass spectrometry platforms are integrating multiplexed adipokine panels into single-run workflows. Academic medical centers in Germany and the United States are piloting these systems for metabolic syndrome research. The technology is integrating high-specificity quantification with reduced sample volume requirements, compressing the cost-per-analyte for large cohort studies.
The FDA's biomarker qualification program is reshaping evidentiary standards for adiponectin assay clearance. Sponsors must now submit longitudinal clinical utility data rather than analytical validation alone. In vitro diagnostic kit manufacturers are responding by embedding real-world evidence collection into early-access programs.
Research procurement is fragmenting from sole-source contracts toward modular reagent sourcing. University core facilities now mix antibody pairs from specialized developers with detection chemistries from alternative suppliers. This unbundling is most pronounced in the United States, where NIH funding pressures force cost optimization across consumable budgets.
Adiponectin Testing Market Segmentation
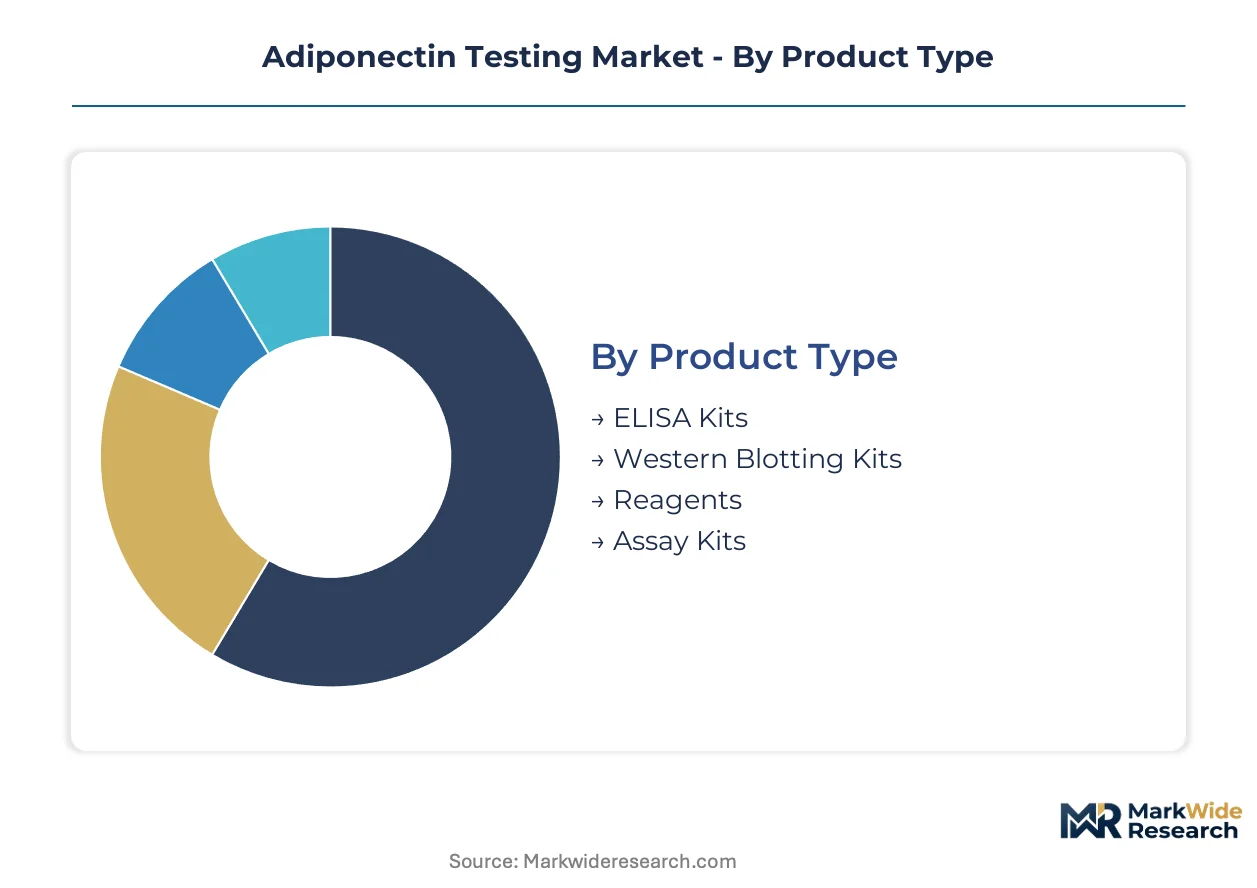
Adiponectin testing segments diverge sharply between high-throughput clinical workflows and specialized research configurations. Understanding where each segment sits within integrated metabolic panels versus standalone diagnostic use determines procurement patterns and margin structures across the value chain.
Product Type:
ELISA Kits anchor standalone diagnostic workflows with minimal capital requirements, while Reagents and Assay Kits embed into larger automated systems requiring deeper integration.
- ELISA Kits:These antibody-based detection systems quantify adiponectin in microgram-per-milliliter ranges using 96-well plate formats. Diagnostic laboratories in the United States concentrate procurement here for cardiovascular risk panel integration, driven by established protocol familiarity and lower per-test costs.
- Reagents:Modular antibody pairs, detection chemistries, and buffer systems supply custom assay developers. Research institutions in Germany and Japan drive premium demand for high-affinity monoclonal antibody sourcing, constrained by limited qualified suppliers.
- Western Blotting Kits:Protein separation and detection systems for adiponectin isoform analysis in academic settings.
- Assay Kits:Pre-configured reagent combinations for automated immunoassay platforms in hospital laboratories.
Volume placements concentrate in ELISA Kits; the faster expansion belongs to modular Reagents as research procurement fragments toward specialized sourcing.
Technology:
Cost tiers separate mature immunoassay platforms from capital-intensive mass spectrometry installations, with PCR and microarrays occupying intermediate positions.
- Immunoassays:Enzyme-linked and chemiluminescent detection methods dominate current clinical throughput. Centralized diagnostic laboratories across France and the United Kingdom standardize on these platforms for metabolic syndrome screening, constrained by antibody cross-reactivity limitations.
- Mass Spectrometry:LC-MS platforms enable multiplexed adipokine quantification with superior specificity. Academic medical centers in the United States and Germany pilot these systems for obesity cohort studies, climbing the fastest as sample volume requirements compress.
- PCR:Nucleic acid amplification supports adiponectin gene expression analysis in research protocols.
- Microarrays:High-density protein detection formats for biomarker discovery applications in pharmaceutical research.
Procurement volume clusters in Immunoassays; steepest expansion trajectory sits with Mass Spectrometry as specificity demands intensify.
End User:
Customer type determines whether adiponectin testing operates within centralized reimbursement frameworks or discretionary research budgets.
- Diagnostic Labs:High-throughput processing centers capture the largest placement volumes through standardized metabolic panels. Commercial reference laboratories in the United States drive protocol adoption for cardiovascular risk assessment, shaped by Medicare reimbursement determinations.
- Research Institutions:University core facilities and pharmaceutical laboratories command premium pricing for custom assay development. NIH-funded centers in Boston and San Francisco concentrate demand for multiplexed adipokine profiling, gaining share fastest as obesity study funding expands.
- Hospitals:In-house clinical laboratories processing adiponectin as part of inpatient metabolic workups.
- Clinics:Physician office laboratories with limited testing menus and lower sample volumes.
Revenue concentration sits with Diagnostic Labs; the premium expansion channel belongs to Research Institutions.
Application:
Maturity levels vary across metabolic disease categories, with diabetes and cardiovascular applications approaching clinical standardization while obesity studies remain research-intensive.
- Diabetes Research:Adiponectin quantification supports insulin sensitivity assessment and type 2 diabetes progression monitoring. Clinical trials in Japan and the United States embed these assays into glucose metabolism protocols, pressured by METI-supported preventive health mandates.
- Cardiovascular Diseases:Risk stratification applications link low adiponectin levels to atherosclerotic events. Hospital systems in Germany and France integrate testing into cardiac rehabilitation programs, expanding most quickly as biomarker qualification pathways mature.
- Obesity Studies:Cohort research examining adipokine dysregulation in metabolic syndrome.
- Metabolic Disorders:Broad-spectrum assessment of lipid and glucose homeostasis dysfunction.
Protocol standardization concentrates in Diabetes Research; the fastest clinical adoption belongs to Cardiovascular Diseases as reimbursement frameworks solidify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kit production concentrates in Germany and the United States, while diagnostic consumption spreads across academic medical centers in Japan and commercial reference laboratories in France. Reagent formulation and antibody development anchor supply-side capabilities in specific industrial clusters.
United States
Academic medical centers in Boston and San Francisco drive adiponectin assay protocol standardization for cardiovascular risk panels. FDA biomarker qualification programs compress validation timelines for assay developers seeking 510(k) clearance. NIH-funded obesity research at Stanford University and Harvard Medical School anchors demand for multiplexed adipokine profiling.
Germany
Specialized antibody developers in Baden-Württemberg supply high-affinity monoclonal pairs for ELISA workflows. EU MDR clinical evidence requirements extend regulatory timelines for IVD kit manufacturers seeking CE marking. The Heidelberg-Mannheim medical technology corridor hosts pilot LC-MS installations for metabolic syndrome research.
Japan
METI-supported preventive health programs create institutional demand for adiponectin testing in diabetes management protocols. PMDA consultation pathways guide assay developers through biomarker-based diagnostic approvals. Tokyo and Osaka academic hospitals integrate adiponectin quantification into glucose metabolism clinical trials.
France
Hospital systems in Paris and Lyon embed adiponectin assays into cardiac rehabilitation programs for atherosclerotic risk stratification. ANSM oversight of in vitro diagnostics shapes quality management system requirements for kit suppliers. The Île-de-France region concentrates commercial reference laboratory capacity for centralized metabolic panel processing.
United Kingdom
NHS England metabolic screening initiatives drive procurement of high-throughput immunoassay platforms in London and Manchester diagnostic hubs. MHRA post-market surveillance requirements influence supplier qualification criteria for hospital procurement channels. Cambridge and Oxford research institutions command premium pricing for custom assay development in obesity cohort studies.
Adiponectin Testing Market Competitive Environment
The competitive structure tilts toward diversified life science conglomerates with captive antibody development and distribution infrastructure. Thermo Fisher Scientific and Merck KGaA occupy positions that span reagent supply through finished kit assembly, compressing margin capture for mid-tier specialists. Three archetypes dominate: integrated conglomerates controlling upstream antibody supply, precision antibody specialists serving modular research procurement, and regional IVD manufacturers competing on localized regulatory compliance. M&A activity targets specialized antibody developers, while strategic partnerships between mass spectrometry platform vendors and assay kit manufacturers accelerate technology convergence.
Among diversified laboratory supply conglomerates, Thermo Fisher Scientific Inc. exemplifies the integrated archetype with global distribution reach, while Merck KGaA occupies a position anchored in recombinant protein standards for assay calibration. Bio-Rad Laboratories, Inc. represents the precision specialist tier focused on antibody pair development for high-sensitivity workflows. These three entities illustrate how competitive positioning diverges between scale-driven supply consolidation and technical specialization in detection chemistry.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Bio-Rad Laboratories, Inc. |
| Eagle Biosciences, Inc. |
| Boster Biological Technology |
| STRATEC SE |
| Laboratory Corporation of America Holdings |
| ERBA Diagnostics, Inc. |
| Randox Laboratories Ltd |
| Others |
Value Chain & Pricing Dynamics
High-affinity monoclonal antibody production costs cascade through adiponectin testing tiers, with recombinant protein calibration standards from German and US suppliers anchoring premium pricing while Chinese buffer reagents feed economy kit segments. This input-cost stratification compresses margins for mid-tier manufacturers unable to secure captive antibody supply.
Pricing Analysis
Throughput-based pricing anchors diagnostic laboratory contracts, with per-test rates scaling inversely to annual volume commitments. Price differentiation separates ISO 13485-certified kits from research-grade alternatives, while after-sales technical support bundles command premiums in Japanese and German markets. Pricing pressure stems from NIH funding constraints forcing US research institutions toward unbundled reagent sourcing. Academic core facilities exhibit highest price sensitivity; commercial reference laboratories in France and the United Kingdom demonstrate lowest sensitivity due to centralized reimbursement frameworks.
Supply Chain Analysis
EU MDR local-content requirements are reshaping sourcing patterns for European kit manufacturers, accelerating domestic antibody pair development in Baden-Württemberg. Supply concentrates in Germany, the United States, and China, with recombinant adiponectin standards, high-affinity monoclonal antibodies, and detection chemistries as critical inputs. Single-source vulnerability sits with specialized antibody developers holding exclusive clone licenses. Distribution runs through Thermo Fisher's global logistics network and regional IVD distributors serving hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The adiponectin testing market is transitioning from ELISA-dominated workflows toward mass spectrometry multiplexing, with LC-MS platforms displacing legacy immunoassays in academic medical centers seeking higher analytical specificity.
For Market Incumbents: Anchor defensive positioning through backward integration into recombinant protein production, securing captive supply of adiponectin calibration standards against input cost volatility. Deepen ISO 13485 certification coverage across European manufacturing sites to preempt EU MDR compliance gaps. Prioritize real-world evidence collection partnerships with Stanford and Harvard Medical School cohorts to accelerate FDA biomarker qualification timelines.
For New Entrants and Emerging Players: Direct-to-researcher digital procurement platforms offer the most penetrable route, bypassing entrenched distributor relationships serving diagnostic laboratories. Target NIH-funded obesity research centers in Boston and San Francisco with modular antibody pair offerings unbundled from full kit configurations. Pursue white-label manufacturing partnerships with Japanese PMDA-registered facilities to access METI-supported diabetes screening programs.
For Investors and Strategic Acquirers: FDA biomarker qualification program advancement is the leading indicator that reimbursement frameworks will unlock clinical adoption beyond research settings. Position for five-to-ten year holding periods as protocol standardization matures. Target acquisition profiles featuring specialized monoclonal antibody developers with exclusive clone licenses and established relationships with German academic medical centers.
| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker Qualification Pathway Investment | FDA recognition unlocks Medicare reimbursement for cardiovascular risk panels in US hospital systems. |
| Mass Spectrometry Platform Partnership | LC-MS integration with assay kits captures academic medical center demand in Germany and the United States. |
| Antibody Developer Acquisition | Exclusive clone licenses eliminate supply bottlenecks constraining high-sensitivity ELISA manufacturing scale. |
| EU Green Deal Compliance Program | Greener reagent formulations secure CE marking access under tightened MDR clinical evidence standards. |
| Digital Pathology Convergence Development | AI-assisted image analysis integration enables automated result interpretation in high-volume diagnostic laboratories. |
Study Parameters
Document review covered FDA 510(k) clearance databases, EMA biomarker qualification guidance, and ISO 13485 certification registries, complemented by interviews with diagnostic laboratory directors, IVD regulatory affairs specialists, biomedical reagent procurement managers, and academic core facility administrators. Secondary sources included ClinicalTrials.gov adiponectin protocol listings, CMS Medicare reimbursement determinations, and EU MDR technical documentation standards. Bottom-up segment sizing triangulated against top-down metabolic syndrome screening volume estimates.
Cross-referencing historical assay adoption curves with expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology platform, end-user category, and application area, with regional regulatory cluster as an additional industry-specific dimension. CAGRs derived from weighted average of technology diffusion rates and reimbursement pathway maturation timelines, incorporating antibody pair availability constraints and mass spectrometry platform cost compression curves as forecast inputs.
Inputs from FDA pre-submission meeting minutes and PMDA consultation pathway records were available through the study window; gaps in real-world clinical utility data from longitudinal cohort studies introduce uncertainty bands around biomarker qualification timeline assumptions. Forecasts reflect documented regulatory guidance and stakeholder capacity expansion plans. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Fecal Pancreatic Elastase Testing Market
Testing Services
Blood Sugar Tester Market
Testing Services
Global Drug Abuse Testing Market
Testing Services
Malaria Ag Rapid Testing Market
Testing Services
Global Biological Safety Testing Market
Testing Services
Vaginal Panel Testing Market
Testing Services
US Viral Clearance Market
Testing Services
Pancreatic Stone Protein Testing Market
Testing Services
Global Direct to Consumer Laboratory Testing Market
Testing Services
Global Forensic Testing Services Market
Testing Services
Industrial Radiography Testing Market
Testing Services
Ovulation Testing Kits Market
Testing Services
Middle East and Africa IVD Regulatory Affairs Outsourcing Market
Testing Services
Indoor Allergen and Particulate Exposure Assessment Test Devices Market
Testing Services
Pyrogen Testing Market
Testing Services
Bimetallic Thermometer Market