
 Sleeping Medications Market | 2026-2036
Sleeping Medications Market Size, Share, and Industry Trends Forecast 2026-2036
Sleeping Medications Market Analytics
Hospital-based prescribing is unwinding as home care settings and outpatient clinics capture a larger share of sleep medication volumes. Pfizer Inc. leverages its distribution scale to serve retail pharmacy channels. Merck & Co. Inc. anchors its position through sustained R&D investment in orexin receptor antagonists. Sanofi S.A. competes across both prescription and over-the-counter melatonin segments in Europe.
Sleeping medications comprise pharmacological agents that modulate gamma-aminobutyric acid receptors, melatonin pathways, or histamine signaling to induce or maintain sleep, with potency measured by sleep latency reduction and maintenance duration. Non-benzodiazepines lead prescription value due to superior safety profiles versus older sedative-hypnotics, while melatonin segments grow fastest in self-directed consumer channels. Oral delivery dominates unit volumes, though sublingual formulations command premium positioning for rapid-onset insomnia indications.
The FDA, EMA, and national equivalents enforce REMS protocols, bioequivalence standards, and controlled-substance scheduling that constrain new entrants and shape formulation development priorities. These frameworks elevate compliance costs but also protect incumbent manufacturers with established pharmacovigilance infrastructure. Stakeholders must monitor evolving digital therapeutics regulations and reimbursement decisions that could either complement or substitute traditional pharmaceutical sleep interventions.
Market Dynamics
The FDA's Risk Evaluation and Mitigation Strategy for sedative-hypnotics is compressing formulation development timelines while elevating pharmacovigilance burdens, forcing manufacturers to restructure clinical trial protocols and post-market surveillance systems around orexin receptor antagonist safety profiles.
Growth Catalysts
- Geriatric institutionalization:Long-term care facilities in the United States are expanding prescription volumes for sleep maintenance therapies as resident acuity rises.
- EMA bioequivalence pathways:Streamlined abbreviated approval routes for complex generics are accelerating market entry for melatonin receptor agonist formulations in Europe.
- Home diagnostic proliferation:Wearable sleep trackers and at-home polysomnography devices are expanding addressable patient pools beyond traditional sleep clinic referrals.
Market Restraints
- Active pharmaceutical ingredient concentration:Three contract manufacturers in India control the majority of zolpidem intermediate supply, creating single-source vulnerability.
- Controlled-substance scheduling friction:DEA quota restrictions on gamma-aminobutyric acid modulators limit production scale-up regardless of demand signals.
- Next-day impairment liability:Persistent cognitive and motor performance deficits associated with non-benzodiazepine hypnotics constrain dosing flexibility and expand litigation exposure.
Strategic Opportunities
- Sub-regional Brazil expansion:ANVISA's recent harmonization with ICH guidelines reduces regulatory duplication for orexin antagonist filings in South America's largest pharmaceutical market.
- Digital therapeutic bundling:Cognitive behavioral therapy for insomnia platforms are creating reimbursement pathways for combination pharmacology-software protocols.
- Sublingual rapid-onset formats:Dissolvable film technologies are capturing premium positioning in shift-work and jet-lag segments previously served by conventional tablets.
Industry Challenges
- Pharmacovigilance talent scarcity:Specialists capable of managing REMS-mandated adverse event reporting for sedative-hypnotics command compensation premiums that strain mid-tier sponsor budgets.
- Legacy system integration:Electronic health record interoperability between sleep clinics and retail pharmacy dispensing systems fragments prescription fulfillment tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sleeping Medications Market |
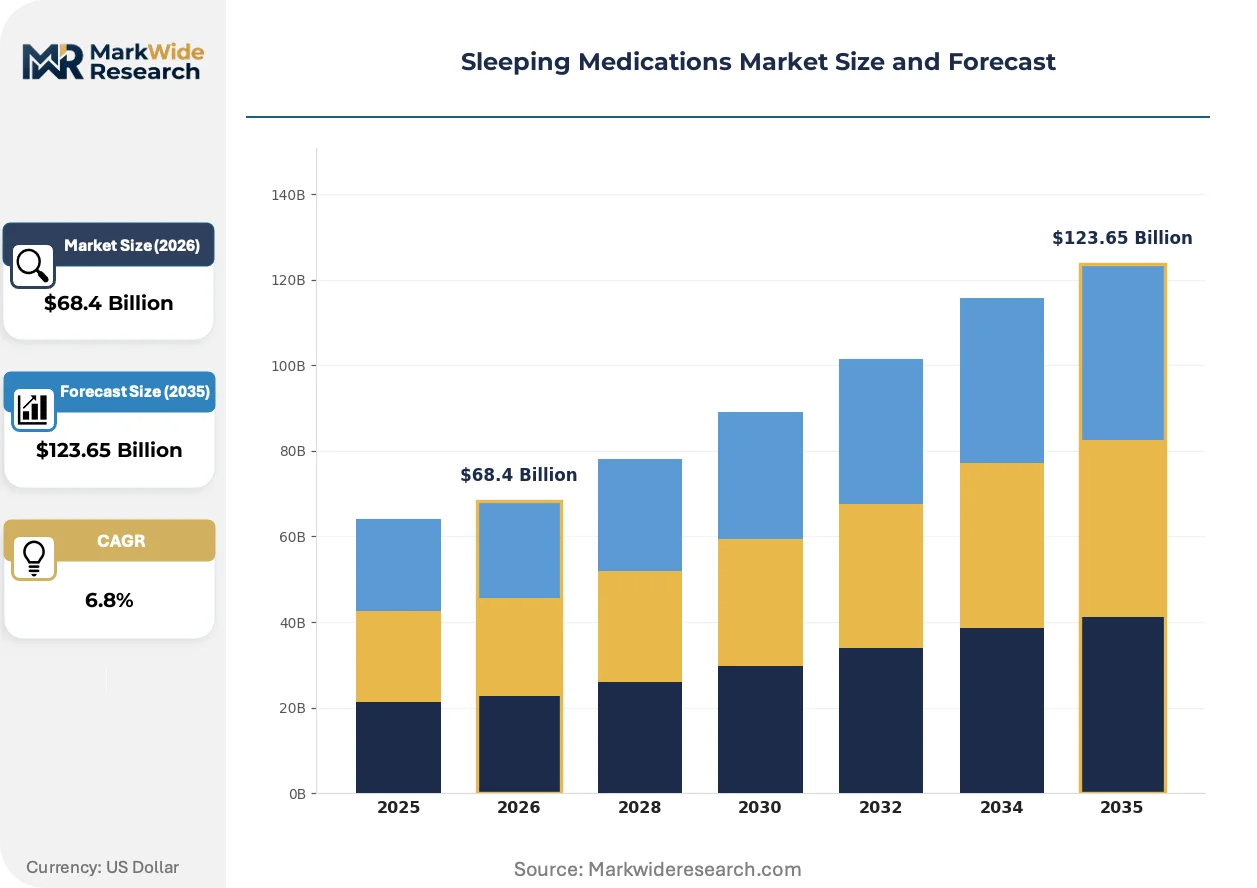
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benzodiazepines, Non-Benzodiazepines, Melatonin, Antidepressants Delivery Mode: Oral, Injectable, Sublingual, Transdermal End User: Hospitals, Outpatient Clinics, Home Care Settings, Long-term Care Facilities Therapy Area: Insomnia, Anxiety Disorders, Depression, Sleep Apnea |
| Companies Covered | Pfizer Inc., Merck & Co. Inc., Sanofi S.A., Johnson & Johnson, F. Hoffmann-La Roche AG, GSK plc, Eisai Co. Ltd., Idorsia Pharmaceuticals Ltd, Jazz Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sleeping Medications Market Evolving Landscape
Formulation science and delivery mechanisms are converging to reshape competitive positioning across prescription and consumer sleep aid channels, with speed-to-sleep and next-day clarity emerging as the primary performance vectors.
Transdermal patch delivery systems for melatonin are miniaturizing wearable form factors while extending controlled-release profiles through microneedle arrays. Consumer wellness brands in Germany and the United States are adopting these platforms for jet-lag and circadian rhythm applications. The technology is miniaturizing the distinction between cosmetic sleep supplements and regulated drug delivery, compressing regulatory classification debates.
The FDA's updated guidance on abuse-deterrent formulations for sedative-hypnotics is mandating novel excipient combinations and tamper-resistant packaging for new drug applications. Manufacturers are reformulating pipeline candidates to incorporate viscosity-building agents that resist intranasal or intravenous misuse. Extended-release zolpidem variants face the steepest compliance cost increases under this framework.
Direct-to-consumer subscription models for sleep medications are displacing traditional pharmacy fulfillment for maintenance therapies. Telehealth platforms in California and New York are integrating prescription authorization with continuous monitoring devices, unbundling the annual sleep specialist visit. This pattern concentrates in metropolitan corridors where employer-sponsored virtual care benefits have achieved critical penetration.
Sleeping Medications Market Segmentation
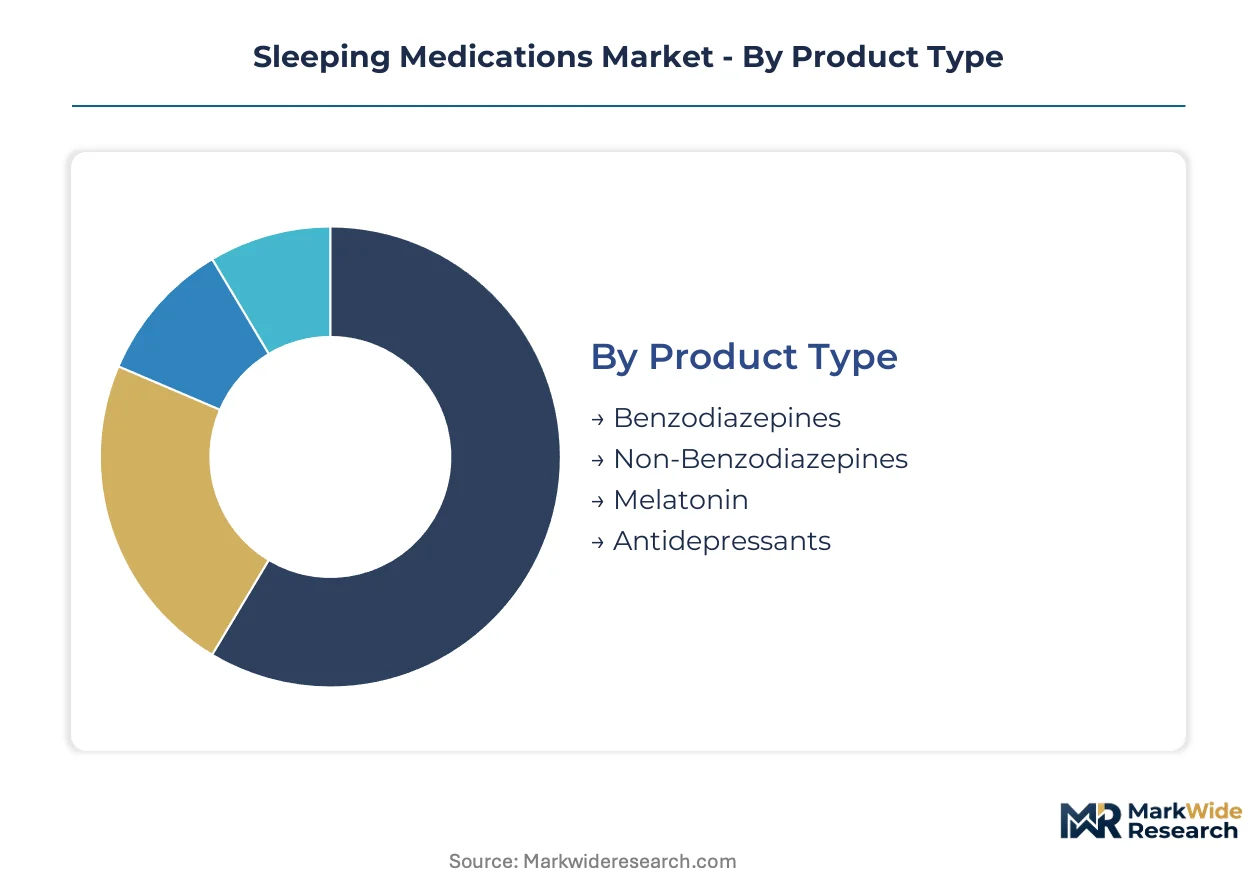
Channel dynamics in the sleeping medications market diverge sharply across product categories. Prescription sedative-hypnotics flow through controlled distribution networks, while melatonin and consumer sleep aids migrate toward direct-to-consumer platforms. Understanding these pathway distinctions enables accurate demand forecasting and inventory positioning.
Product Type:
Channel-mix patterns vary dramatically by pharmacological class, with retail pharmacy dominance for maintenance therapies contrasting specialty distribution for acute interventions.
- Non-Benzodiazepines:Zolpidem, eszopiclone, and zaleplon modulate GABA-A receptor subtypes with shorter half-lives than legacy benzodiazepines. Demand concentrates in United States retail pharmacy chains where FDA REMS compliance infrastructure is embedded. The DEA's Schedule IV classification constrains channel expansion despite superior safety profiles versus older agents.
- Melatonin:Synthetic and plant-derived melatonin agonists target MT1/MT2 receptors to regulate circadian phase. European consumer wellness channels and United States supplement retailers capture the steepest volume expansion as self-directed sleep management proliferates. EMA's borderline classification debates between food supplement and medicinal product create regulatory friction in Germany and France.
- Benzodiazepines:Temazepam and triazolam retain niche positioning for acute insomnia flares in hospital settings where respiratory depression monitoring is available.
- Antidepressants:Trazodone and mirtazapine prescribed off-label for sleep maintenance channel through psychiatric specialty practices and long-term care formularies.
Non-Benzodiazepines dominate installed base. Melatonin is where expansion concentrates.
Delivery Mode:
Cost tier stratification separates premium rapid-onset formats from economy tablet volumes, with reimbursement elasticity determining channel penetration depth.
- Oral:Immediate-release and extended-release tablets and capsules constitute the volume foundation across all prescribing settings. Manufacturing scale concentrates in Indian and Chinese contract facilities serving multinational pharmaceutical distributors.
- Sublingual:Dissolvable films and orally disintegrating tablets achieve faster T-max through buccal absorption, commanding 40-60% price premiums in shift-work and jet-lag segments. Zolpidem tartrate sublingual formulations from Sanofi and generics manufacturers anchor this tier in United States and French markets.
- Transdermal:Microneedle array patches for melatonin delivery are emerging from German and Korean cosmetic-device crossover manufacturers, blurring regulatory boundaries between drug and wellness categories.
- Injectable:Intravenous midazolam and propofol derivatives serve procedural sedation in hospital operating suites and intensive care units, with zero retail pharmacy presence.
Oral formulations anchor volume economics. Sublingual formats are climbing the fastest.
End User:
Patient acuity and reimbursement access shape facility-level prescribing patterns, with Medicare and private payer formularies diverging sharply across settings.
- Long-term Care Facilities:Nursing homes and assisted living residences in the United States generate concentrated demand for sleep maintenance therapies as resident age and comorbidity burden intensify. CMS reimbursement protocols and fall-risk liability concerns constrain benzodiazepine utilization despite historical precedent.
- Home Care Settings:Telehealth-authorized prescriptions and mail-order pharmacy fulfillment are displacing traditional sleep clinic referrals in California, Texas, and Florida metropolitan corridors. Continuous positive airway pressure device integration creates combination therapy opportunities for sleep apnea comorbidities.
- Outpatient Clinics:Sleep medicine specialists and primary care practices in academic medical centers handle complex polysomnography-confirmed diagnoses with prior authorization requirements.
- Hospitals:Emergency departments and inpatient units reserve sedative-hypnotics for acute agitation and alcohol withdrawal protocols, with discharge planning driving limited continuation prescriptions.
Long-term care facilities dominate prescription volumes. Home care settings are gaining share fastest.
Therapy Area:
Diagnostic coding specificity and comorbidity patterns determine addressable population sizing, with insomnia maintaining broadest eligibility and sleep apnea requiring device-pharmacy combination protocols.
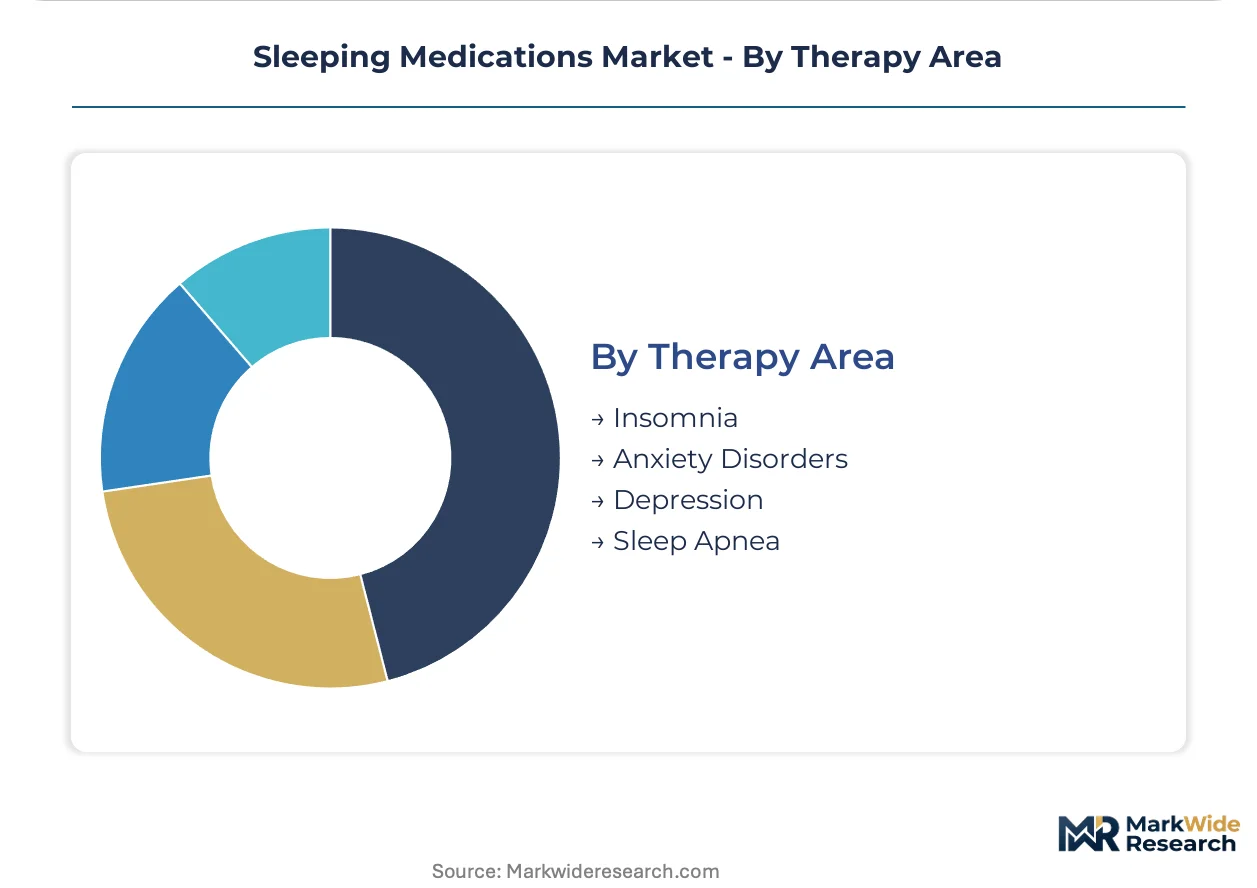
- Insomnia:Chronic and acute sleep initiation and maintenance disorders represent the primary labeled indication across all sedative-hypnotic classes. ICD-10 coding expansion in United States electronic health records has broadened reimbursement eligibility beyond traditional sleep specialist gatekeeping.
- Sleep Apnea:Obstructive and central sleep apnea pharmacotherapy remains limited to adjunctive orexin antagonist trials and residual daytime sleepiness management, with continuous positive airway pressure maintaining first-line status. ResMed and Philips device ecosystems create bundled care opportunities in Australian and United States markets.
- Anxiety Disorders:Off-label hydroxyzine and benzodiazepine prescribing for generalized anxiety with sleep disruption channels through psychiatric and primary care practices with overlapping symptom targeting.
- Depression:Adjunctive trazodone and sedating antidepressants address insomnia comorbid to major depressive disorder, with serotonin modulation providing dual therapeutic benefit.
Insomnia commands the broadest installed base. Sleep apnea represents the steepest expansion trajectory as device-pharmacy protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Institutional buyers in long-term care facilities and outpatient sleep clinics concentrate demand in the United States, Germany, Japan, United Kingdom, and Brazil, with each market shaped by distinct reimbursement protocols and regulatory frameworks.
United States
Long-term care facilities and Medicare Advantage formularies drive prescription volumes for sleep maintenance therapies. The FDA's REMS protocols for sedative-hypnotics mandate specialized pharmacovigilance infrastructure that elevates compliance costs for new entrants. The Boston-Cambridge corridor anchors orexin receptor antagonist R&D clusters where biotech incubators partner with academic sleep medicine centers.
Germany
Consumer wellness channels and pharmacy-led melatonin distribution capture expanding self-directed sleep management demand. EMA bioequivalence pathways for complex generics accelerate market entry for melatonin receptor agonist formulations. The Rhine-Main region around Frankfurt hosts contract manufacturing organizations serving European distribution networks for sublingual rapid-onset formats.
Japan
Aging demographics and institutionalized elder care generate concentrated demand for non-benzodiazepine hypnotics with reduced fall-risk profiles. PMDA guidelines on sedative-hypnotic safety labeling shape formulation development priorities for domestic manufacturers. The Kanto region surrounding Tokyo concentrates sleep disorder diagnostic centers and pharmaceutical headquarters operations.
United Kingdom
NHS formularies and primary care gatekeeping patterns channel prescription volumes toward cost-effective generic non-benzodiazepines. NICE guidelines on insomnia management prioritize cognitive behavioral interventions, constraining pharmacological first-line use. The Greater London area hosts telehealth platforms integrating prescription authorization with wearable sleep monitoring devices.
Brazil
Expanding private health insurance penetration and diagnostic infrastructure drive addressable patient pool growth in metropolitan corridors. ANVISA's harmonization with ICH guidelines reduces regulatory duplication for orexin antagonist filings, accelerating product registration timelines. The São Paulo state pharmaceutical manufacturing cluster supplies Latin American distribution networks for controlled-release formulations.
Sleeping Medications Market Competitive Landscape
Player mix skews toward multinational pharmaceutical conglomerates with established REMS compliance infrastructure and specialized biotech developers focused on novel mechanisms. Market structure consolidates around prescription sedative-hypnotic leaders with embedded pharmacovigilance systems, while consumer-facing melatonin segments fragment across wellness brands and private-label retailers. Three strategic archetypes dominate: orexin receptor antagonist specialists, legacy GABA-modulator incumbents, and direct-to-consumer subscription platforms. Competitive moves center on formulation patent extensions for rapid-onset delivery formats and strategic partnerships with telehealth providers for prescription fulfillment integration.
Among multinational pharmaceutical conglomerates, Pfizer Inc., Merck & Co. Inc., and Sanofi S.A. occupy positions representing distinct competitive vectors. Pfizer exemplifies scale-driven distribution reach across retail pharmacy channels with embedded FDA compliance systems. Merck anchors the orexin antagonist development archetype through sustained pipeline investment in novel sleep-wake mechanisms. Sanofi sits within the dual-prescription-consumer positioning tier, competing across regulated hypnotics and over-the-counter melatonin segments in European markets. These three entities collectively represent the structural tension between legacy GABA-modulator maintenance and next-generation receptor targeting strategies reshaping therapeutic category development priorities.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co. Inc. |
| Sanofi S.A. |
| Johnson & Johnson |
| F. Hoffmann-La Roche AG |
| GSK plc |
| Eisai Co. Ltd. |
| Idorsia Pharmaceuticals Ltd |
| Jazz Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
Contract manufacturing scale in Indian active pharmaceutical ingredient facilities anchors both supply concentration and price floors for zolpidem intermediates and melatonin precursors. This scale dynamic compresses margins for mid-tier formulation sponsors while elevating procurement leverage for multinational pharmaceutical distributors with embedded FDA compliance infrastructure.
Pricing Analysis
Cost-plus contracts with Indian and Chinese API suppliers index to energy and solvent feedstock benchmarks, creating transparency gaps for Western formulation sponsors. Pricing stratifies across premium sublingual rapid-onset formats, standard extended-release tablets, and economy generic immediate-release volumes. Price differentiation hinges on FDA REMS compliance certification and DEA Schedule IV handling infrastructure. Cost compression in economy oral tablets is intensifying because EMA bioequivalence pathways accelerate European generic entry. Retail pharmacy chains exhibit highest price sensitivity, while long-term care facility formularies prioritize fall-risk liability coverage over unit cost.
Supply Chain Analysis
Inventory lead times for orexin receptor antagonist precursors stretch across twelve-to-eighteen-month synthetic cycles, constraining just-in-time procurement flexibility. Supply concentrates in Indian API intermediates, Chinese raw material precursors, and German sublingual film manufacturing. The chain draws from piperazine derivatives, specialty solvents, and microneedle array substrates. Single-source vulnerability in zolpidem intermediate supply creates concentration risk. Distribution runs through controlled wholesale networks for DEA-scheduled substances and direct-to-consumer platforms for unscheduled melatonin segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits cyclical recovery characteristics as post-pandemic sleep clinic visit normalization and Medicare Advantage formulary expansion restore prescription volumes. The cyclical driver is geriatric institutionalization rebound in United States long-term care facilities.
For Market Incumbents: Compound pharmacovigilance infrastructure advantages by acquiring REMS-specialized adverse event reporting capabilities from mid-tier sponsors facing talent cost pressure. Deepen orexin antagonist pipeline investment to preempt generic erosion in GABA-modulator franchises. The threat is digital therapeutic substitution for maintenance insomnia therapies. For New Entrants and Emerging Players: Differentiate on sublingual rapid-onset delivery technology for shift-work and jet-lag segments where premium pricing tolerates novel entrant cost structures. Target Brazilian private insurance corridors where ANVISA harmonization accelerates registration timelines. Pursue telehealth platform partnerships for prescription fulfillment integration. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer subscription platforms with embedded wearable monitoring device bundling. Long-term viability favors acquirers of orexin antagonist specialists with Phase III-ready assets and established pharmacovigilance systems. The inflection signal to watch is FDA digital therapeutic reimbursement parity decisions that could either complement or cannibalize pharmaceutical sleep interventions.| Strategic Initiative | Industry Significance |
|---|---|
| REMS Compliance Infrastructure Investment | Embedded FDA pharmacovigilance systems protect incumbent positioning against generic entrants. |
| Orexin Antagonist Pipeline Advancement | Novel mechanism development captures next-generation sleep maintenance therapy share. |
| Sublingual Film Manufacturing Scale-Up | Rapid-onset delivery commands premium positioning in shift-work and jet-lag segments. |
| Telehealth Platform Integration | Direct-to-consumer subscription models displace traditional pharmacy fulfillment channels. |
| Brazil Regulatory Harmonization Exploitation | ANVISA alignment with ICH guidelines accelerates Latin American market entry timelines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with regulatory affairs leads, formulary directors at long-term care facilities, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA REMS documentation, EMA bioequivalence assessment reports, ClinicalTrials.gov orexin antagonist filings, and DEA controlled substance quota publications. Bottom-up prescription volume modeling triangulated against top-down pharmaceutical distributor shipment data.
Across the analysis window, forecasts segmented by pharmacological class, delivery mode, end-user facility type, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to historical prescription volume trajectories and reimbursement policy elasticity estimates. Inputs incorporated geriatric demographic projections, sleep disorder diagnosis coding expansion rates, and digital therapeutic regulatory pathway maturation.
Decision-makers should treat outputs as directional under assumptions of sustained Medicare Advantage formulary access and stable DEA scheduling frameworks; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Systemic Antibiotics Market
Pharmaceuticals
Global Anti-Retroviral Drugs Market
Pharmaceuticals
4-Valent HPV Vaccine (4vHPV) Market
Pharmaceuticals
Global Esketamine Market
Pharmaceuticals
Global Muscle Relaxant Drugs Market
Pharmaceuticals
HIV Antivirals Market
Pharmaceuticals
Unfractionated Heparin Market
Pharmaceuticals
Global Ceftiofur Market
Pharmaceuticals
Cytomegalovirus Treatment Market
Pharmaceuticals
Brazil Diabetes Drugs Market
Pharmaceuticals
Nuclear Medicines Radioisotopes Market
Pharmaceuticals
Diphtheria Tetanus Pertussis Vaccine Market
Pharmaceuticals
Collagenase Clostridium Histolyticum Market
Pharmaceuticals
Over the Counter (OTC) Drugs Market
Pharmaceuticals
Meningococcal Vaccines Market
Pharmaceuticals
Advanced Therapy Medicinal Products CDMO Market