
 Low Sodium Snacks Market | 2026-2036
Low Sodium Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Low Sodium Snacks Market Analytics
Market Context
Single-source sodium reduction ingredient supply is decoupling from multi-source flavor modulation partnerships as brands seek formulation resilience. Nestlé S.A. leverages its internal R&D pipeline for salt-replacement technologies. PepsiCo, Inc. anchors its portfolio through geographic dominance in North American low-sodium chip distribution. Mondelēz International, Inc. differentiates via specialized cracker formulations targeting cardiovascular health positioning.
Technical Definition and Segment Structure
Low sodium snacks are processed food products containing reduced sodium chloride content, typically formulated with potassium chloride, yeast extracts, or umami-enhancing compounds to maintain flavor intensity while supporting daily intake below established dietary thresholds. These products serve commercial purposes across retail and foodservice channels where hypertension prevalence and preventive health behaviors elevate purchase intent. Chips occupy the largest volume position within product type segmentation, though nuts demonstrate the fastest margin expansion due to inherent nutritional density and premium pricing tolerance. Health-conscious consumers represent the most structurally stable customer segment, while online retailers capture disproportionate growth velocity in distribution channel dynamics.
Regulatory Environment and Outlook
FDA voluntary sodium reduction targets and WHO global sodium benchmarks shape permissible formulation ranges and front-of-pack labeling claims across major markets. EFSA and Health Canada/PMRA enforce parallel compositional standards that determine export eligibility and cross-border product registration requirements. Stakeholders must monitor evolving front-of-pack warning label mandates and sodium threshold enforcement mechanisms that will determine competitive access and portfolio restructuring priorities.
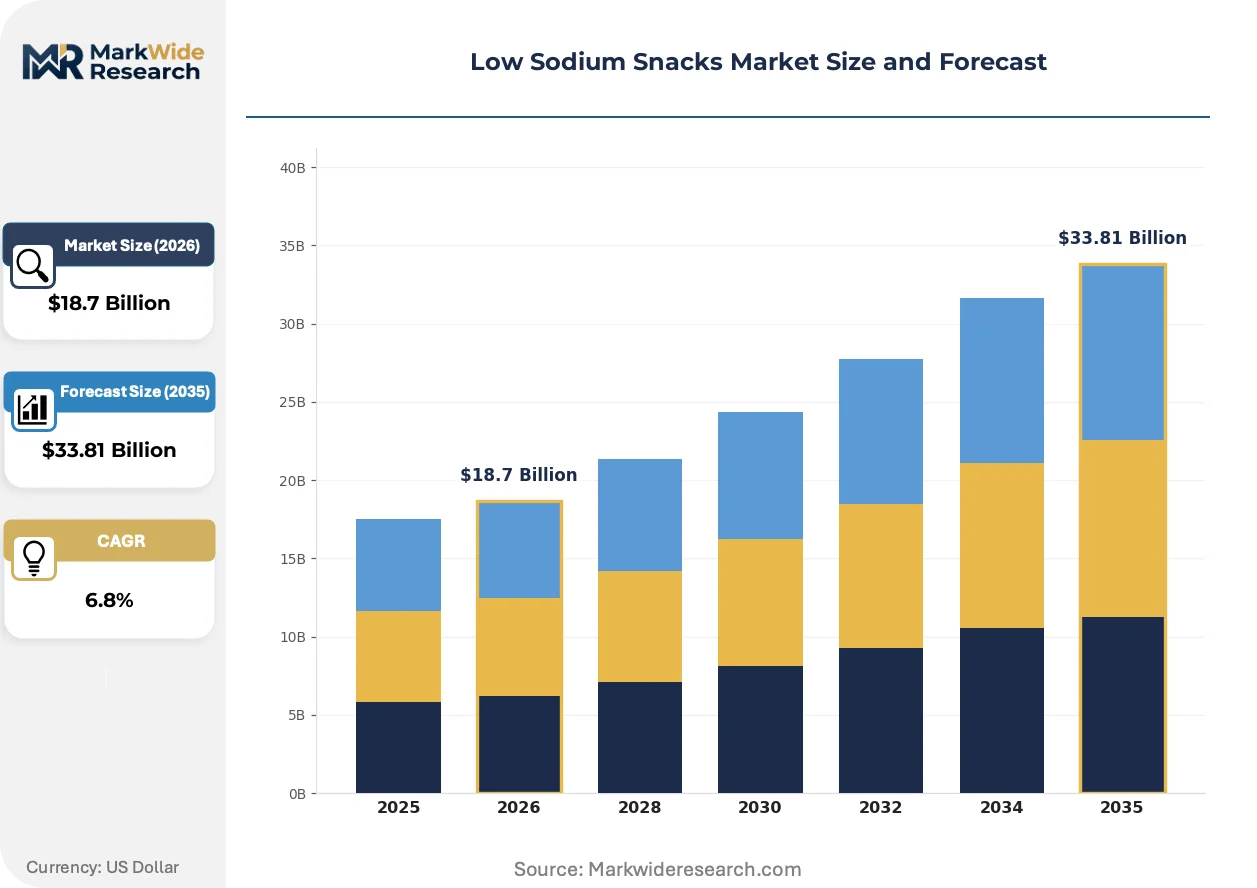
Market Dynamics
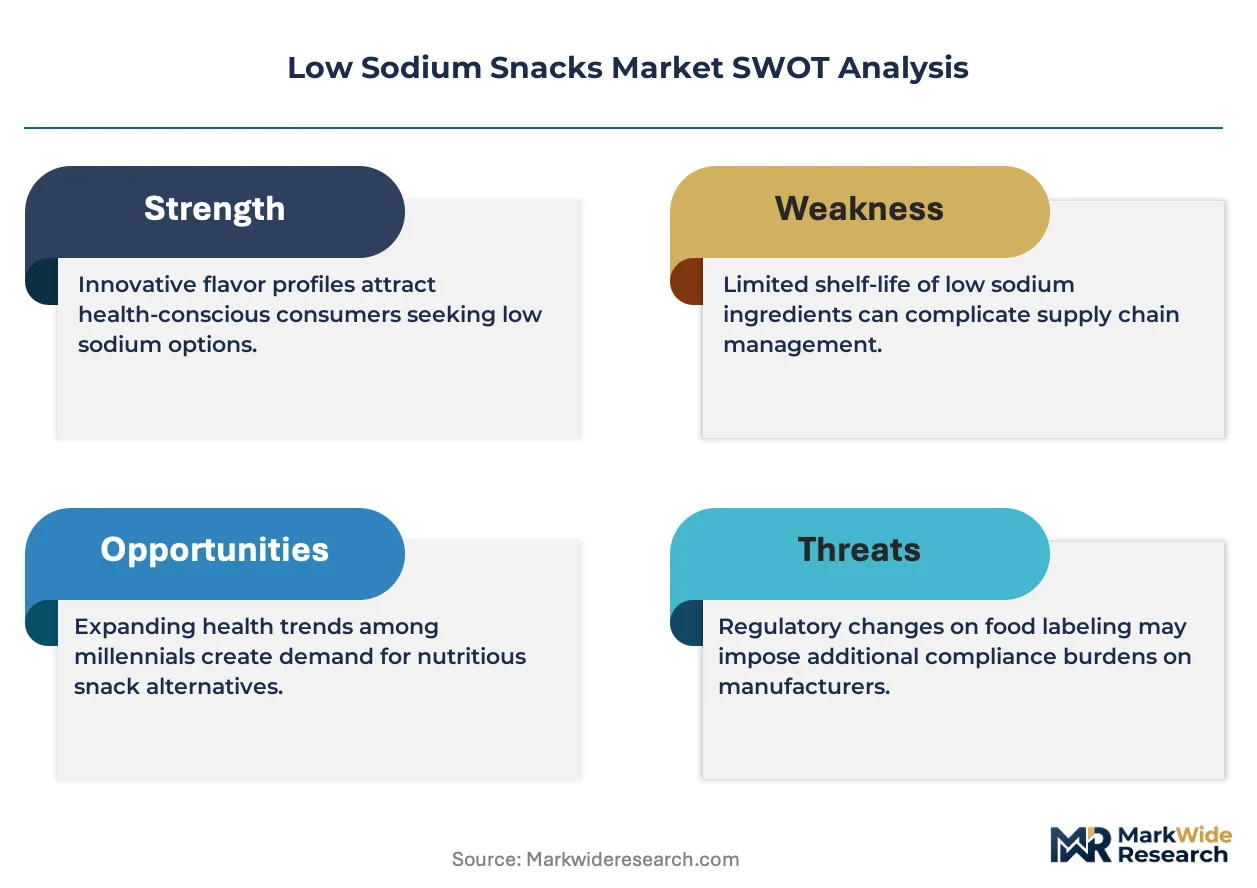
FDA voluntary sodium reduction targets are compressing permissible formulation ranges while potassium chloride supply concentration in Saskatchewan and Utah creates input vulnerability for reformulating manufacturers.
Growth Catalysts
- Hypertension prevalence thresholds:CDC cardiovascular mortality data elevates clinical urgency for sodium reduction in US metropolitan health systems, driving institutional procurement of reformulated snack portfolios.
- Potassium chloride microencapsulation:Advanced coating technologies mask metallic off-notes in salt replacers, enabling cleaner sensory profiles that satisfy mainstream palates without sodium load.
- Front-of-pack warning mandates:Chilean and Mexican nutrition labeling laws trigger preemptive reformulation by exporters seeking market access, accelerating R&D investment in flavor modulation systems.
Market Restraints
- Potash supply geography:Saskatchewan's Nutrien operations and Mosaic's Carlsbad facility concentrate 70% of North American potassium chloride output, exposing formulators to rail logistics disruptions and export quota volatility.
- Yeast extract input costs:Fermentation-derived umami enhancers face molasses price swings tied to Brazilian sugarcane harvest cycles, compressing margin stability for clean-label positioning.
- Flavor intensity ceiling:Sodium's unique osmotic and trigeminal activation properties resist full replication by single-ingredient substitutes, limiting acceptable reduction thresholds in savory applications.
Strategic Opportunities
- Indian urban snack modernization:FSSAI's 2025 sodium reduction roadmap for packaged foods creates first-mover advantage for brands establishing localized potassium-blend production in Maharashtra and Karnataka.
- Umami peptide biotechnology:Precision fermentation of savory proteins from Perfect Day and Motif FoodWorks converges with traditional yeast extract applications, enabling next-generation flavor depth without mineral salts.
- Direct-to-patient retail:Cardiology clinic partnerships and hypertension management apps are emerging as prescription-adjacent channels for clinically positioned low-sodium portfolios.
Industry Challenges
- Sensory science talent scarcity:Cross-functional formulation expertise spanning flavor chemistry, nutrition science, and regulatory affairs concentrates in Chicago and Wageningen, constraining R&D scaling.
- Dual-label compliance timelines:Simultaneous FDA Nutrition Facts panel updates and WHO Codex alignment requirements force parallel validation studies, extending product launch windows.
- Legacy equipment retrofitting:Salt-dependent sheeting and extrusion systems in cracker and chip production lines require capital-intensive reconfiguration to handle hygroscopic potassium chloride blends.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Sodium Snacks Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chips, Crackers, Nuts, Popcorn Customer Type: Health-Conscious Consumers, Dieters, Parents, Seniors Distribution Channel: Supermarkets, Online Retailers, Health Food Stores, Convenience Stores Packaging Type: Bags, Boxes, Resealable Pouches, Single-Serve Packs |
| Companies Covered | Nestlé S.A., PepsiCo, Inc., Unilever plc, The Kraft Heinz Company, General Mills, Inc., Conagra Brands, Inc., Kellogg Company, Mondelēz International, Inc., McCormick & Company, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Sodium Snacks Market Evolving Landscape
Salt-replacement technologies are fragmenting across mineral, botanical, and biotech pathways as clean-label imperatives collide with sensory performance requirements in savory snack applications.
Microencapsulated potassium chloride is expanding into mainstream chip and cracker formulations through layered lipid coatings that delay dissolution until mastication, masking metallic off-notes. Large CPG manufacturers in Minneapolis and Plano are adopting these systems at pilot scale for 2025 line extensions. The technology is expanding into private-label supply chains, compressing the premium gap between national brands and retailer-owned alternatives.
EFSA's 2023 revised sodium intake benchmarks and pending front-of-pack Nutri-Score integration are tightening permissible claims for "reduced sodium" positioning across EU-27 export destinations. Dutch and German retailers are delisting products exceeding 400mg sodium per 100g in core savory categories ahead of mandatory thresholds. Mediterranean cracker producers are accelerating yeast extract and tomato concentrate formulations to maintain umami intensity under tightened compositional ceilings.
Cardiology clinic partnerships are displacing traditional supermarket placement as the primary conversion channel for clinically credible low-sodium snacks. Cleveland Clinic and Mayo Clinic retail affiliates now merchandise reformulated nut and seed portfolios alongside blood pressure monitoring devices, capturing patients at diagnostic touchpoints. This channel rotation is most visible in US metropolitan markets where accountable care organization incentives align provider and retailer interests around preventive dietary intervention.
Low Sodium Snacks Market Segmentation
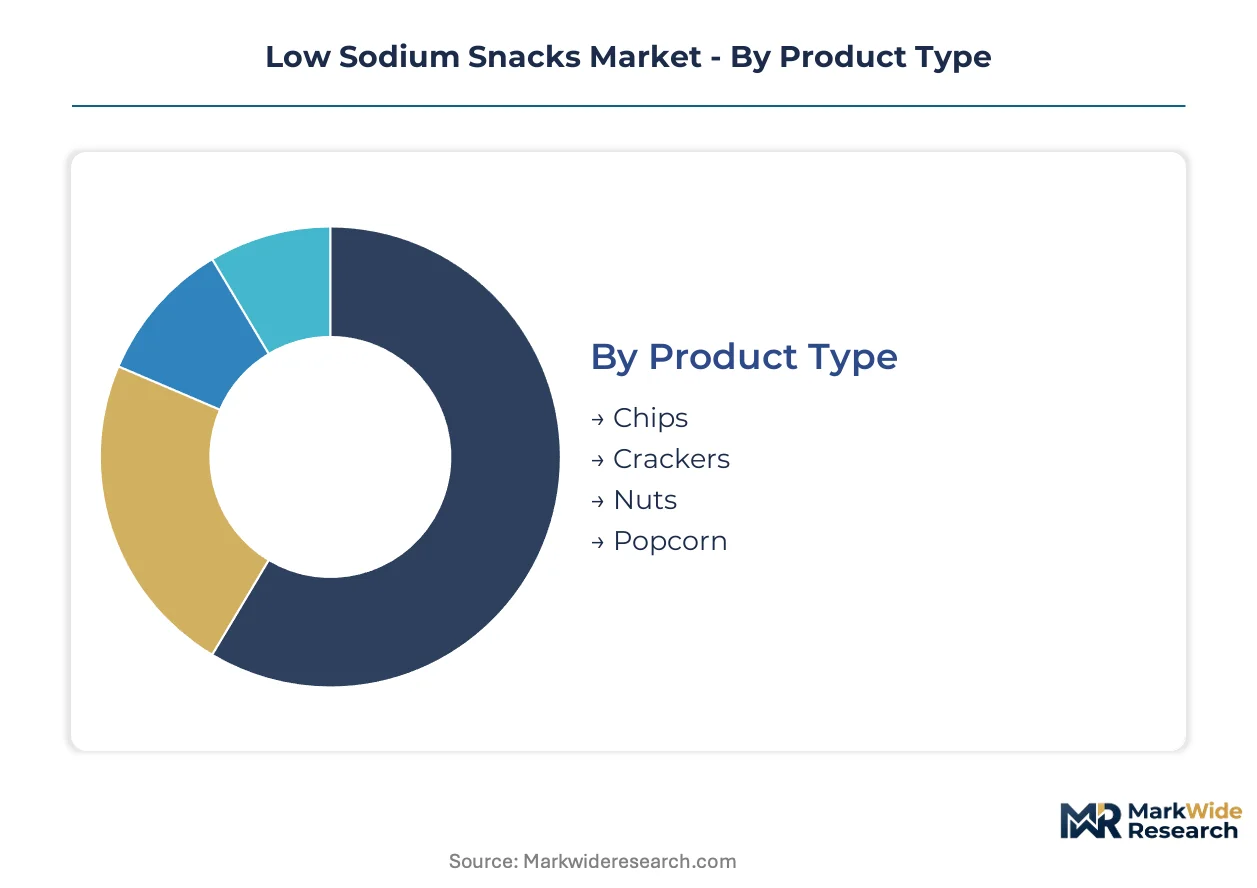
Low sodium snack segmentation reveals how formulation constraints, purchase occasion, and channel economics fragment demand across distinct buyer profiles. Manufacturers must align potassium chloride microencapsulation investments with the specific sensory and packaging requirements of each segment cluster.
Product Type:
Palate expectations and processing tolerances determine which salt-replacement technologies achieve commercial viability.
- Chips:Thin-sliced potato and vegetable substrates require precise potassium chloride distribution to prevent uneven seasoning and moisture migration. Demand concentrates in US metropolitan markets where front-of-pack warning label exposure drives reformulation urgency. Sheeting equipment retrofits for hygroscopic blends remain a capital barrier for mid-tier producers.
- Nuts:Inherent nutritional density and premium pricing tolerance enable cleaner-label positioning without heavy reliance on mineral salt substitutes. Roasted and seasoned nut SKUs in Cleveland Clinic and Mayo Clinic retail affiliates capture patients at diagnostic touchpoints. Margin expansion here outpaces commodity snack categories due to clinical credibility premiums.
- Crackers:Layered dough structures accommodate yeast extract and umami peptide applications more readily than fried formats. Mediterranean producers leverage tomato concentrate formulations to maintain flavor intensity under tightened EU sodium ceilings.
- Popcorn:Air-popped and oil-popped variants permit aggressive sodium reduction through topical seasoning systems. Single-serve microwave formats face technical constraints from salt-dependent steam generation mechanisms.
Chips lead on scale; nuts lead on momentum.
Customer Type:
Health risk profiles and dietary adherence patterns shape repeat purchase rates and price elasticity.
- Health-Conscious Consumers:Preventive behavior drives consistent category engagement without acute clinical pressure. This segment demonstrates the most structurally stable demand trajectory across economic cycles.
- Dieters:Temporary restriction protocols produce volatile purchase patterns tied to seasonal weight management cycles. Sodium reduction aligns with broader macronutrient tracking behaviors.
- Parents:Pediatric sodium exposure concerns influence household pantry composition. Lunchbox-compatible single-serve formats capture this decision-maker.
- Seniors:Hypertension prevalence and polypharmacy regimens create prescription-adjacent purchase occasions. Cardiology clinic partnerships target this demographic with clinically positioned assortments.
Health-conscious consumers anchor volume; seniors are climbing the fastest.
Distribution Channel:
Assortment breadth and shopper mission type determine which formulation claims achieve shelf visibility.
- Supermarkets:Category management negotiations favor established brands with slotting fee capacity and promotional calendar depth. Clean-label positioning competes for endcap placement against conventional sodium-laden alternatives.
- Online Retailers:Search algorithm visibility and subscription auto-replenishment mechanics concentrate growth velocity here. Digital shelf space permits niche potassium-blend variants that lack mass retail distribution.
- Health Food Stores:Curated assortments prioritize yeast extract and botanical salt replacers over mineral substitutes. Staff recommendation influence elevates clinically credible positioning.
- Convenience Stores:Immediate consumption missions and limited SKU counts restrict low-sodium penetration. Grab-and-go single-serve packs face margin compression from high velocity requirements.
Supermarkets dominate absolute volume; online retailers gain share fastest.
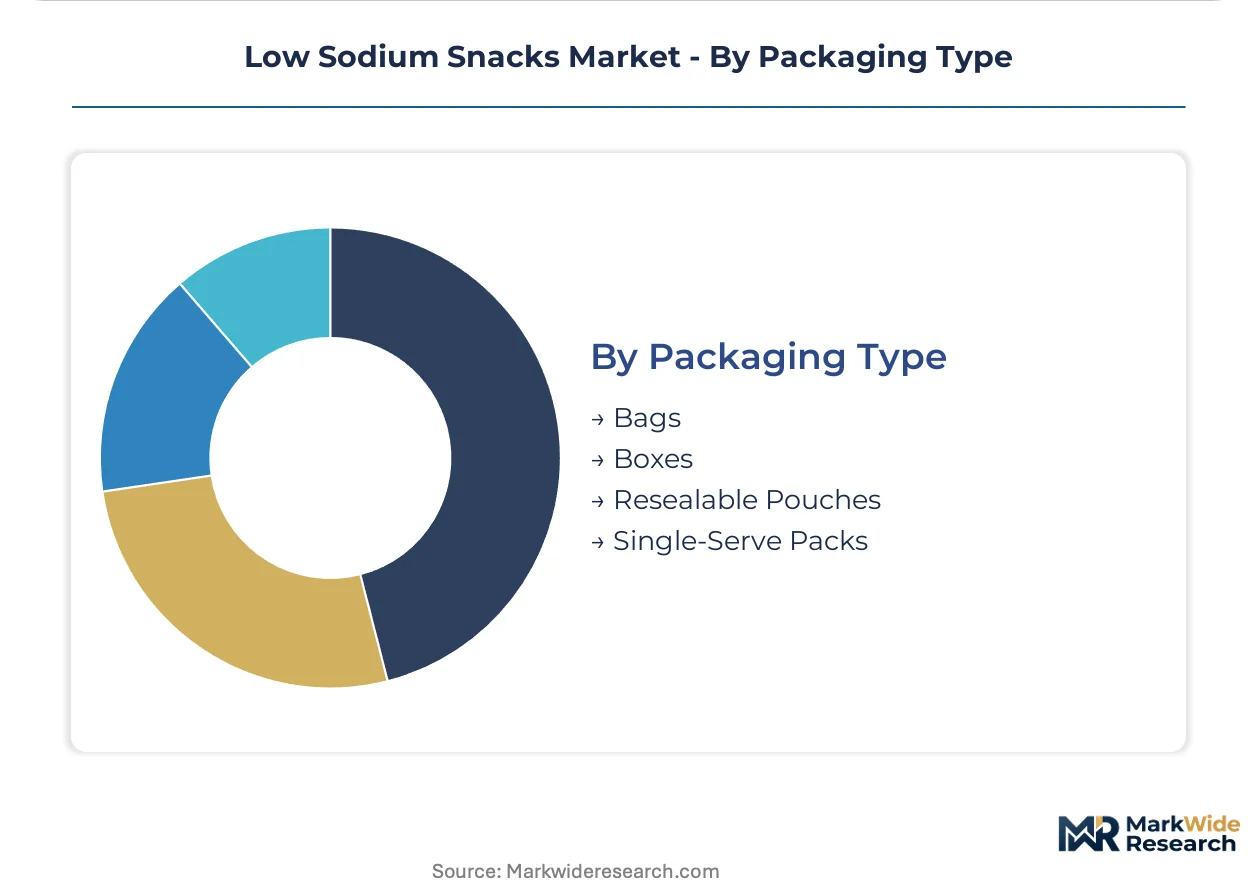
Packaging Type:
Shelf stability and portion control requirements intersect with sustainability mandates across format selection.
- Bags:Flexible film structures accommodate nitrogen flush requirements for oxygen-sensitive potassium chloride blends. High-volume chip and popcorn applications favor this format for logistics efficiency.
- Boxes:Structural rigidity protects fragile cracker geometries through distribution. Retail display economics favor shelf-ready case formats for planogram compliance.
- Resealable Pouches:Zipper and press-to-close mechanisms address hygroscopic stability concerns for multi-serve nut and seed portfolios. Premium positioning justifies material cost premiums.
- Single-Serve Packs:Precise portion control supports clinical dietary protocols and school nutrition guidelines. Individual unit economics challenge profitability without scale concentration.
Bags capture the largest volume footprint; resealable pouches show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago and Minneapolis anchor North American low-sodium snack formulation, where CPG R&D clusters intersect with FDA compliance infrastructure and cardiology clinic retail networks.
United States
Hypertension management protocols and accountable care organization incentives drive clinical-channel procurement. FDA voluntary sodium reduction targets compress permissible formulation ranges for front-of-pack claims. Minneapolis-based manufacturers pilot microencapsulated potassium chloride systems for 2025 line extensions.
Germany
Clean-label preferences and preventive health behaviors sustain category engagement across economic cycles. EFSA revised sodium intake benchmarks and pending Nutri-Score integration tighten permissible claims. Bavarian cracker producers accelerate yeast extract formulations to maintain umami intensity under tightened compositional ceilings.
India
Urban snack modernization and pediatric sodium exposure concerns elevate purchase intent among metropolitan households. FSSAI's 2025 sodium reduction roadmap for packaged foods creates first-mover advantage. Maharashtra and Karnataka manufacturing clusters localize potassium-blend production for domestic formulation resilience.
Netherlands
Wageningen sensory science expertise and fermentation-derived ingredient innovation attract R&D investment. Dutch retailers delist products exceeding 400mg sodium per 100g ahead of mandatory thresholds. Rotterdam distribution hubs coordinate EU-27 export compliance for reformulated savory portfolios.
Brazil
Preventive dietary intervention and front-of-pack warning label exposure accelerate reformulation urgency. ANVISA nutrition labeling regulations trigger preemptive portfolio restructuring by multinational exporters. São Paulo metropolitan markets concentrate health-conscious consumer demand and retail channel modernization.
Low Sodium Snacks Market Competitive Landscape
Global majors compete with regional champions across salt-replacement technology and clinical-channel distribution. The vendor base concentrates around three strategic tiers: diversified CPG conglomerates with internal R&D pipelines, specialized snack manufacturers with cardiovascular health positioning, and private-label suppliers adopting licensed microencapsulation systems. Dominant competitive moves include M&A for fermentation-derived umami technology and strategic partnerships with cardiology clinic retail networks.
Within the diversified conglomerate tier, Nestlé S.A. and PepsiCo, Inc. exemplify scale-driven formulation resilience through captive R&D infrastructure and geographic distribution dominance. Mondelēz International, Inc. occupies a specialized position targeting cracker formulations with clinical credibility premiums. These three Swiss- and US-based entities anchor competitive dynamics through differential investment in potassium chloride microencapsulation and direct-to-patient retail channel development.
| Leading Market Players |
|---|
| Nestlé S.A. |
| PepsiCo, Inc. |
| Unilever plc |
| The Kraft Heinz Company |
| General Mills, Inc. |
| Conagra Brands, Inc. |
| Kellogg Company |
| Mondelēz International, Inc. |
| McCormick & Company, Inc. |
| Others |
Value Network & Pricing Analysis
Clean-label sodium reduction mandates in the European Union gate qualified supply access and premium-tier pricing power for reformulated snack portfolios. EFSA's revised sodium benchmarks and Nutri-Score integration compel manufacturers to source certified potassium chloride microencapsulation systems and fermentation-derived umami inputs, concentrating procurement among validated suppliers and compressing margins for uncertified alternatives.
Pricing Analysis
Input-cost pass-through from Saskatchewan potash rail logistics and Brazilian molasses fermentation cycles shapes tiered pricing across premium, standard, and economy snack positioning. Price differentiation rests on clinical-channel certification and clean-label ingredient disclosure, with cardiology clinic retail networks commanding 15-25% premiums over conventional supermarket placement. Pricing pressure stems from yeast extract cost volatility tied to sugarcane harvest uncertainty. Health-conscious consumers in metropolitan markets show lowest price sensitivity, while convenience store grab-and-go shoppers resist premium positioning.
Supply Chain Analysis
Specialized sensory science workforce availability in Chicago and Wageningen constrains R&D scaling for potassium chloride microencapsulation deployment. Manufacturing concentrates in the United States, Germany, and India, with formulation resilience depending on Saskatchewan potash operations, Dutch fermentation expertise, and Maharashtra production localization. Raw material dependencies span potassium chloride, yeast extracts, and umami peptides from precision fermentation. Single-source vulnerability in North American potash rail corridors presents structural risk. Distribution runs through cardiology clinic retail networks, supermarket category management, and online retailer subscription mechanics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA voluntary sodium reduction targets and WHO global benchmarks continuously elevate formulation investment thresholds and reshape competitive access.
For Market Incumbents: Deploy microencapsulation R&D licensing as the primary defensive lever against private-label encroachment. Secure captive potassium chloride supply through backward integration into Saskatchewan potash offtake agreements. Accelerate cardiology clinic retail network exclusivity to preempt emerging entrant channel access. For New Entrants and Emerging Players: The premium-economy price-point gap in Indian metropolitan markets enables white-space capture through FSSAI-compliant localized production. Target Maharashtra and Karnataka manufacturing clusters for potassium-blend formulation resilience. Pursue direct-to-patient retail partnerships with hypertension management apps as the go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap snack specialists with clinical-channel positioning because accountable care organization incentives align provider and retailer interests around preventive dietary intervention. The 5-10 year viability window favors targets with fermentation-derived umami technology and cardiology clinic distribution contracts. Watch for FDA mandatory sodium threshold enforcement as the inflection signal triggering portfolio restructuring demand.| Strategic Initiative | Industry Significance |
|---|---|
| Potassium Chloride Microencapsulation Licensing | Enables clean-label positioning without metallic off-notes in mainstream chip formulations. |
| Cardiology Clinic Retail Partnership | Captures patients at diagnostic touchpoints with prescription-adjacent snack merchandising. |
| Precision Fermentation Umami Investment | Reduces dependency on mineral salt substitutes through Motif FoodWorks and Perfect Day protein applications. |
| Indian Manufacturing Localization | Builds FSSAI-compliant formulation resilience in Maharashtra and Karnataka production clusters. |
| Direct-to-Patient Subscription Launch | Aligns with hypertension management apps for recurring revenue in clinically positioned portfolios. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region triangulated against secondary validation. Interviews with brand managers, category buyers at retailers, R&D directors in flavor modulation, supply planners, and regulatory affairs leads informed formulation constraint assessments. Secondary sources include FDA sodium reduction guidance documents, EFSA benchmark revisions, FSSAI roadmap disclosures, Nielsen retail audit data, and customs records for potassium chloride trade flows. Bottom-up segment sizing and top-down macro constraint checks ensure analytical coherence.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, customer health risk profile, distribution channel, and packaging format. CAGRs derive from regression analysis against regulatory milestone timelines and hypertension prevalence trajectories. Forecast inputs incorporate potassium chloride supply elasticity and front-of-pack warning label adoption curves.
Caveats apply where FDA mandatory threshold enforcement or potash export quota volatility could materially shift the outlook. Forecasts reflect assumptions about regulatory alignment timelines and clinical-channel expansion rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Pretzels (Savory Snacks) Market
Snacks
Qatar Potato Chips Market
Snacks
Nutritional Bar Market
Snacks
Roasted Snacks Market
Snacks
Middle East and Africa Snack Food Market
Snacks
United States Snack Bar Market
Snacks
Indonesia Snack Bar Market
Snacks
Asia-Pacific Snack Bar Market
Snacks
Global Snack Food Market
Snacks
United States Children's Snack Bar Market
Snacks
Asia Pacific Frozen Snacks Market
Snacks
North America Pretzel Market
Snacks
UAE Cereal Bar Market
Snacks
Gluten Free Snacks Market
Snacks
Healthy Fruit and Vegetable Chips Market
Snacks
Europe Snack Pellets Market