
 Snacks Market | 2026-2036
Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Snacks Market Intelligence
AI-driven flavor profiling and predictive analytics is reshaping how new snack products are developed and brought to market. PepsiCo leverages its extensive data infrastructure to test novel flavor combinations in specific markets. Mondelēz International specializes in adapting its core brands to local taste preferences across Asia and Latin America. Nestlé sustains its market position through continuous R&D in healthier snack formulations.
Snacks are defined as commercially prepared, ready-to-eat food items designed for consumption between primary meals. They are typically produced using industrial processes such as extrusion, baking, or frying and are packaged for portability and extended shelf life. The savory flavor profile, particularly within the chips and crackers product types, continues to hold the largest market share. However, demand for granola bars and nuts is expanding rapidly, driven by consumer preferences for healthier, protein-rich options.
Food safety and labeling standards from regulators like the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) govern ingredient usage and health claims. In India, the Food Safety and Standards Authority of India (FSSAI) imposes strict rules on packaging and nutritional information, impacting market entry. Navigating the evolving landscape of sugar and sodium reduction mandates will be a critical determinant of brand success and profitability.
Market Dynamics
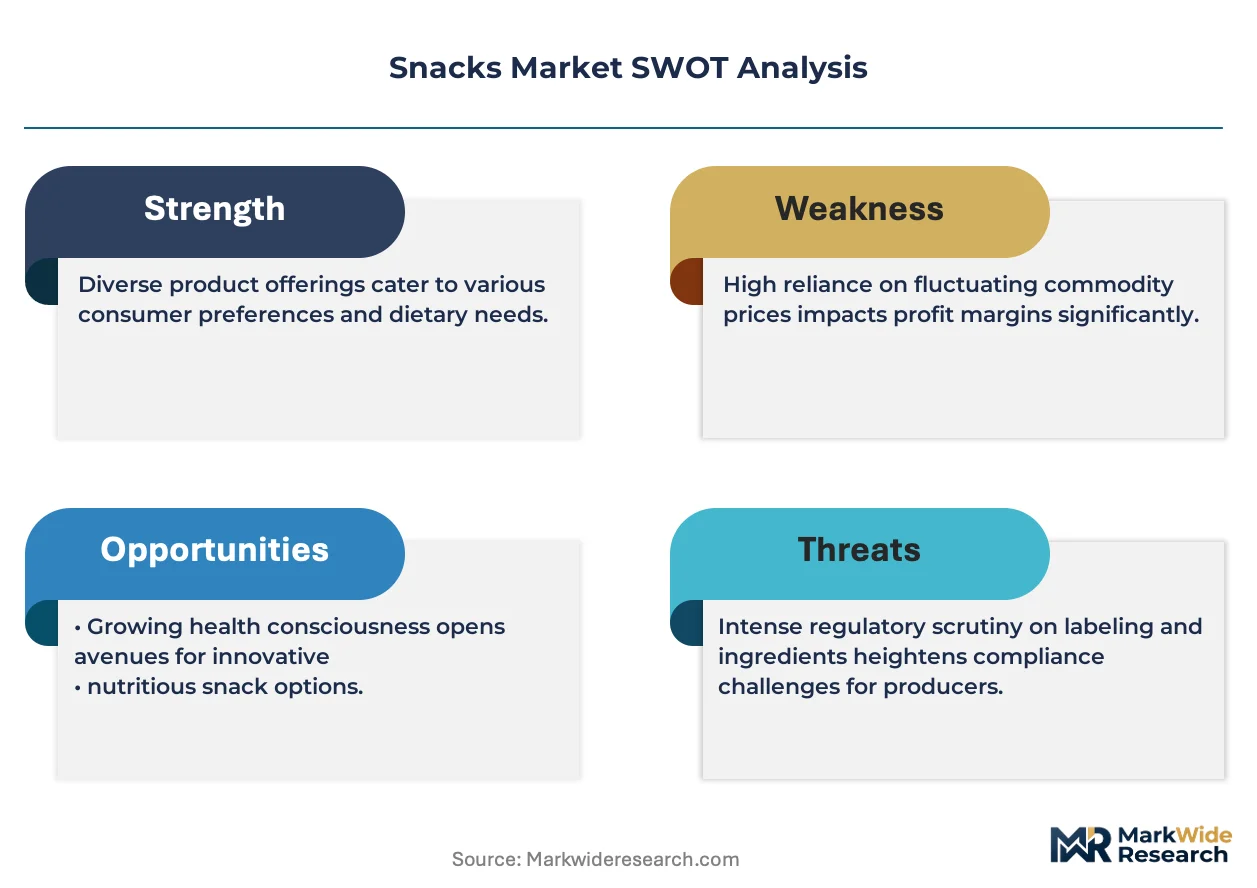
The central dynamic shaping the snacks market is the tension between consumer demand for indulgent, convenient food and the increasing global regulatory pressure for healthier product formulations, particularly concerning sugar, sodium, and fat content.
Growth Catalysts
- Plant-Based Formulations:Consumer shifts toward flexitarian, vegetarian, and vegan diets are driving innovation and sales in snacks featuring plant-derived proteins and ingredients, such as those made from chickpeas, lentils, and peas.
- Emerging Market Consumption:Rising disposable incomes and urbanization in countries like India and Brazil are expanding the consumer base for packaged and branded snacks, moving consumption away from traditional, unpackaged alternatives.
- Direct-to-Consumer Channels:The proliferation of e-commerce platforms and social media marketing enables niche and startup snack brands to bypass traditional retail gatekeepers, reaching targeted consumer segments with specialized products.
Market Restraints
- Commodity Price Volatility:Fluctuations in the prices of key agricultural inputs, including cocoa, sugar, nuts, and edible oils, create significant margin pressure and forecasting challenges for manufacturers.
- Complex Regulatory Compliance:Adhering to a patchwork of disparate international food safety and labeling standards from bodies like the US FDA and EFSA increases operational costs and complicates cross-border trade.
- Ingredient Sourcing Risks:The geographic concentration of certain specialty crops in limited regions exposes the supply chain to disruptions from climate change, geopolitical instability, and local agricultural policies.
Strategic Opportunities
- Personalized Nutrition:The convergence of food science with data analytics presents an opportunity to develop customized snacks tailored to individual dietary needs, biometric data, or wellness goals.
- Untapped Geographic Markets:Certain regions within Africa and Southeast Asia represent significant white space, with low penetration of formally manufactured and packaged snack products.
- Upcycled Ingredients:Utilizing byproducts from food production, such as fruit peels or vegetable pulp, as ingredients for new snack products can appeal to environmentally conscious consumers and create new value streams.
Industry Challenges
- Reformulation Complexity:Reducing sugar, sodium, and fat content to meet health guidelines without compromising taste, texture, and shelf life requires extensive R&D investment and potential retooling of production lines.
- Packaging Sustainability:Transitioning to recyclable, compostable, or biodegradable packaging materials while maintaining food safety standards and barrier properties presents a significant technical and cost challenge.
- Accelerated Compliance Deadlines:Manufacturers face difficulties in adapting to staggered and often rapidly implemented changes in nutritional labeling regulations across different national and regional markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Snacks Market |
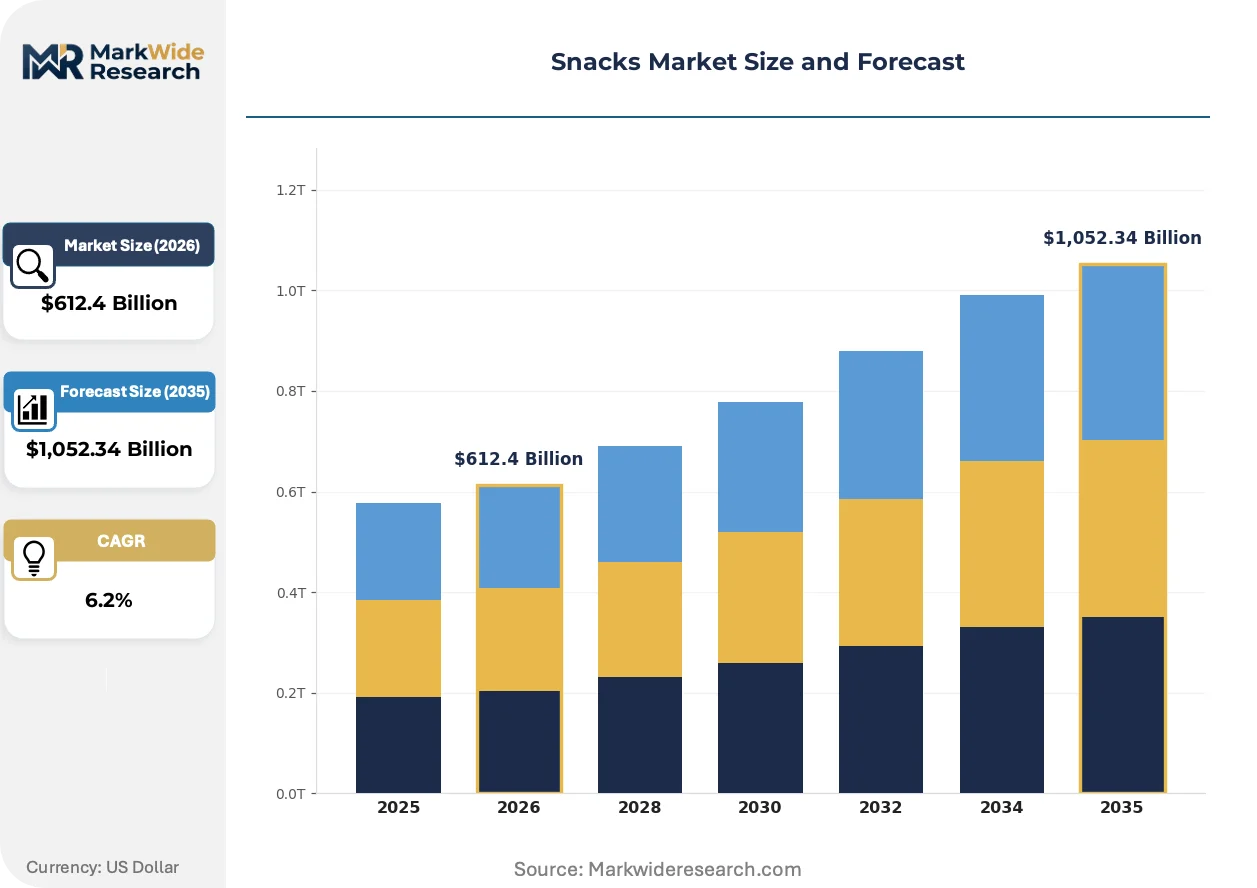
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $1,052.34 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chips, Crackers, Nuts, Granola Bars Flavor Profile: Sweet, Savory, Spicy, Tangy Packaging Type: Bags, Boxes, Jars, Pouches Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Vending Machines |
| Companies Covered | Mars, Hershey, Nestlé, Calbee, Intersnack, PepsiCo, General Mills, Campbell's Company, Mondelēz International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Snacks Market Strategic Shifts & Innovations
The industrialization of health and the digitization of flavor development are defining the next generation of snack products. This evolution is driven by a synthesis of advanced food science, data analytics, and shifting consumer expectations around nutrition and convenience.
AI-Driven Flavor Profiling AI-powered platforms analyze vast datasets on chemical compounds, consumer reviews, and sales trends to predict successful flavor combinations. Major food manufacturers and ingredient suppliers are adopting this technology to shorten development timelines. This capability is virtualizing the traditionally lengthy and expensive trial-and-error R&D process, allowing for more targeted and rapid product introductions.
Front-of-Pack Nutrition Labeling New mandatory front-of-pack labeling systems, like the Nutri-Score adopted in several European countries, are increasing food-content transparency. These regulations directly influence consumer choices at the point of sale by providing simple, visual cues about a product's health profile. The savory snacks and confectionery segments are most affected, accelerating reformulation efforts to improve nutritional ratings.
Snackification of Mealtimes A prominent behavioral shift involves consumers replacing traditional, structured meals with multiple smaller, convenient, and often healthier snack-sized portions throughout the day. This "snackification" trend disrupts the conventional three-meals-a-day model, elevating the role of snacks in daily dietary planning. The pattern is most pronounced among urban consumers in developed economies across North America and Europe.
Snacks Market Segmentation
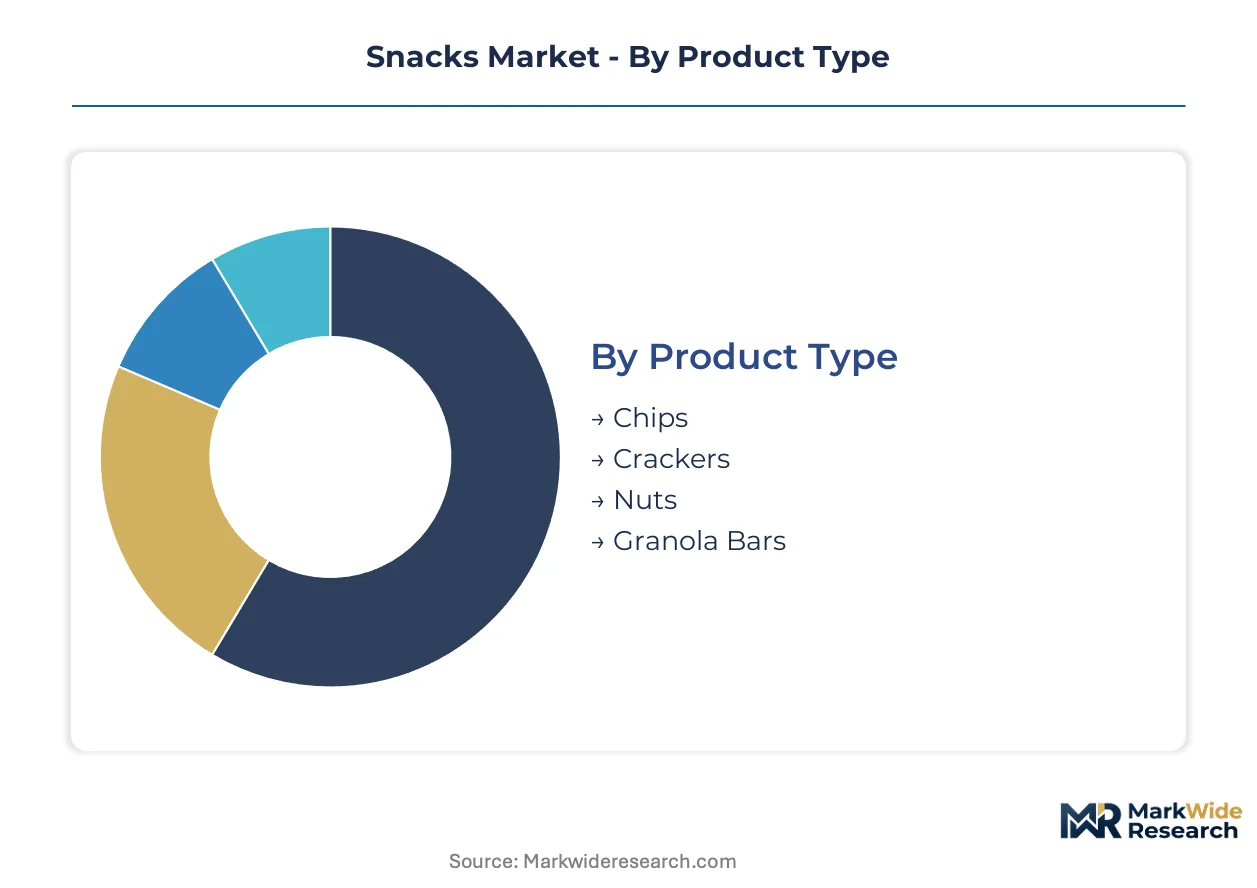
Understanding the Snacks Market through segmentation clarifies consumer preferences, regulatory impacts, and strategic opportunities across diverse product offerings. This detailed breakdown allows manufacturers to tailor product development and market entry strategies effectively, responding to specific demand drivers in various sub-markets.
Product Type:
The product type segmentation reveals a spectrum of maturity, ranging from established categories to rapidly expanding health-focused segments.
- Chips:These are thin, crisp slices of potato or other vegetables, typically fried or baked and seasoned; demand remains consistently high across North America and Western Europe, driven by their widespread availability and indulgent appeal.
- Granola Bars:Formulated from rolled oats, nuts, and sweeteners, often fortified with protein or fiber; consumer demand is expanding rapidly in countries like the United States and Germany, fueled by preferences for convenient and healthier snack options.
- Crackers:Baked, flat, and often savory items made from flour-based dough; these products serve as versatile accompaniments for meals and dips.
- Nuts:Edible seeds or fruits, frequently roasted or seasoned; they are valued for their natural protein content and satiety in various global markets.
Chips retain volume leadership; Granola Bars hold the steepest expansion curve.
Flavor Profile:
Flavor profile segmentation highlights the diverse taste preferences that influence product innovation and market penetration across different regions.
- Savory:Characterized by salty, umami, or spiced tastes, often derived from cheese, herbs, or meat extracts; this profile commands the largest market share in high-growth countries like India, reflecting strong regional culinary traditions.
- Sweet:Defined by high sugar content, including flavors such as chocolate, fruit, or caramel; these snacks are broadly popular among consumers seeking indulgent treats in markets like Brazil and the United Kingdom.
- Spicy:Incorporates piquant and hot elements, typically from chili peppers or other capsaicin-rich ingredients; this profile appeals strongly to consumers in Mexico and Thailand, where bold flavors are deeply embedded in local cuisine.
- Tangy:Features sharp, sour, or acidic notes, often from citrus fruits or vinegar; these flavors offer a refreshing contrast and are sought after by consumers desiring distinctive taste experiences.
Savory profiles dominate consumption patterns, while spicy options show significant regional expansion.
Packaging Type:
The packaging type segmentation illustrates the functional requirements and consumer convenience factors driving material choices in the snacks industry.
- Bags:Flexible, lightweight, and typically made from plastic films or laminates; these are the most common packaging for chips and other single-serve snacks, prized for their cost-effectiveness and portability.
- Pouches:Flexible, often resealable, and frequently designed to stand upright; this format is gaining traction for nuts and granola bars, driven by consumer demand for extended freshness and on-the-go convenience.
- Boxes:Rigid containers, usually constructed from paperboard or corrugated cardboard; these are utilized for multi-pack crackers and snack assortments, providing structural protection and branding space.
- Jars:Rigid containers, commonly glass or plastic, with screw-top lids; they are primarily used for bulk nuts, pretzels, or snack mixes, offering product visibility and reusability.
Flexible bags remain the most prevalent format, as pouches gain traction for their functional benefits.
Distribution Channel:
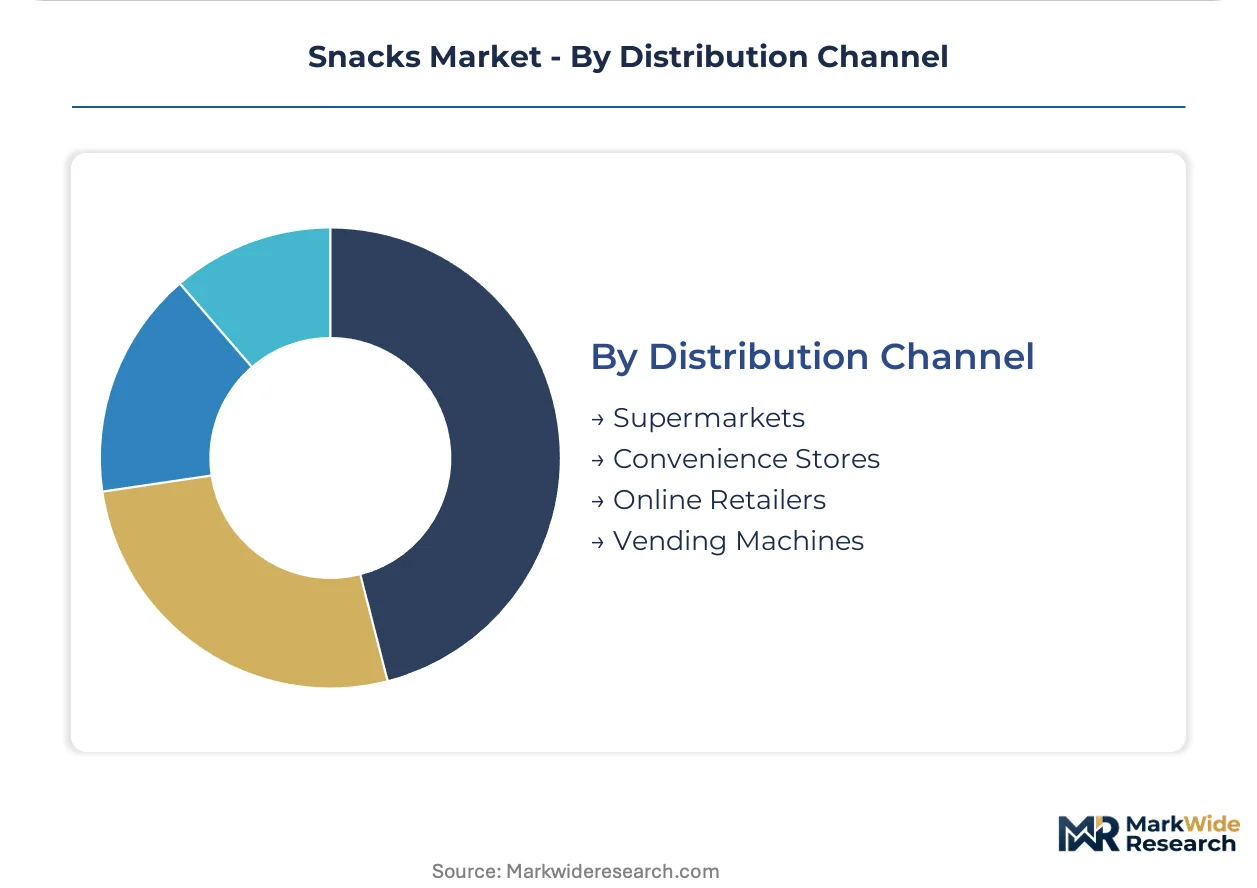
Distribution channel segmentation reveals the varied pathways through which snack products reach consumers, impacting market accessibility and brand visibility.
- Supermarkets:Large retail establishments offering a comprehensive range of snack products; these stores serve as the primary purchasing destination for household snack consumption in urban centers across France and Japan.
- Online Retailers:E-commerce platforms facilitating direct sales and home delivery services; this channel experiences dynamic growth for niche and health-focused snack brands, driven by digital convenience and broader product selection.
- Convenience Stores:Smaller retail outlets with extended operating hours, providing quick and easy access to snack items; they cater to immediate consumption needs in high-traffic areas within the United States and Canada.
- Vending Machines:Automated dispensing units offering pre-packaged snacks; these machines provide accessible purchase points in workplaces, educational institutions, and public transportation hubs.
Supermarkets maintain their foundational role, while online retail channels exhibit dynamic expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Snack product innovations from European manufacturers frequently target markets in North America and Asia, reflecting diverse consumer preferences. This cross-regional influence drives product diversification and ingredient sourcing strategies for major snack producers globally. Regulatory frameworks across these regions significantly shape product formulation and market entry.
United States
Consumer demand for healthier, protein-rich snack options drives innovation across the United States. The US Food and Drug Administration (FDA) enforces strict labeling standards for nutritional content and health claims. Food tech startups in California's Silicon Valley area develop personalized nutrition snacks, utilizing advanced ingredient science.
Germany
Demand for convenient and healthier snack options, particularly granola bars, is expanding within Germany. The Nutri-Score labeling system adopted in several European countries influences product reformulation efforts. Hamburg's food industry focuses on sustainable packaging solutions for various snack products, aligning with environmental goals.
India
Rising disposable incomes and rapid urbanization are expanding the consumer base for packaged and branded snacks in India. The Food Safety and Standards Authority of India (FSSAI) imposes strict rules on packaging and nutritional information. Mumbai's food processing sector adapts global snack brands to local taste preferences, emphasizing savory profiles.
Brazil
Sweet snacks and indulgent treats remain broadly popular among consumers seeking convenient options in Brazil. ANVISA, the national health surveillance agency, oversees food safety and ingredient usage for snack items. São Paulo's snack industry invests in new production lines for diversified product offerings, including plant-based alternatives.
Japan
Innovative flavor combinations and unique snack experiences continue to drive the Japanese market. The Ministry of Health, Labour and Welfare (MHLW) sets food additive and ingredient standards for snack manufacturers. Tokyo's research institutions collaborate on AI-driven flavor profiling for new snack development, shortening R&D cycles.
Snacks Market Key Industry Players
On the supply side, the industry is characterized by a mix of large, diversified food conglomerates and numerous niche, specialized snack producers. This structure creates a tiered market where global players compete on scale and brand recognition, while smaller entities focus on innovation and targeted consumer segments. Strategic acquisitions frequently occur to expand market share or integrate new product lines. Portfolio diversification also helps companies address evolving consumer preferences for healthier snack options.
At the scale-driven end, PepsiCo represents a global player leveraging extensive data infrastructure for flavor profiling and market insights. Mondelēz International exemplifies a multinational firm specializing in adapting core brands to local taste preferences across diverse geographies. Nestlé anchors the market with continuous research and development in healthier snack formulations, sustaining its market position through product evolution.
| Leading Market Players |
|---|
| Mars |
| Hershey |
| Nestlé |
| Calbee |
| Intersnack |
| PepsiCo |
| General Mills |
| Campbell's Company |
| Mondelēz International |
| Others |
Cost & Logistics Intelligence
Fluctuations in agricultural commodity prices, particularly for sugar and nuts from key producing regions, directly compress profit margins for snack manufacturers. This upstream volatility impacts pricing strategies across diverse product categories.
Pricing Analysis
The pricing gap between traditional, mass-market snacks and innovative, health-focused formulations is widening. Pricing stratifies across premium, standard, and economy tiers, with brand premium and quality grade driving differentiation. Pricing softness reflects intense competition within the standard segment, largely due to private label proliferation. Economy segment consumers exhibit the highest price sensitivity, while those seeking personalized nutrition solutions demonstrate lower elasticity.
Supply Chain Analysis
Food safety regulations, particularly those governing ingredient imports, limit the flow of certain raw materials into specific markets. Supply concentrates in Brazil for sugar, West Africa for cocoa, and Southeast Asia for palm oil. The industry relies heavily on these agricultural inputs and edible oils. Commodity price volatility presents a significant structural risk. Distribution runs through supermarkets and convenience stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Snacks Market presents a significant fragmentation opportunity, driven by the consumer shift towards personalized nutrition. This demand creates numerous niches for specialized product offerings.
For Market Incumbents: Pre-empt regulatory pressure for sugar and sodium reduction through proactive reformulation. Diversify portfolios by integrating healthier snack options and exploring strategic acquisitions of agile, niche brands. Invest in continuous R&D to maintain a competitive edge against emerging health-focused entrants. Leverage extensive data infrastructure for predictive analytics in new product development.
For New Entrants and Emerging Players: Plant-based protein snacks represent a highly penetrable entry point, particularly within the flexitarian consumer segment. Developing personalized nutrition offerings tailored to specific dietary needs also presents white space. A direct-to-consumer go-to-market strategy, leveraging e-commerce platforms and social media, effectively reaches targeted consumer groups.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional snack producers specializing in emerging health categories. The market exhibits strong long-term viability over the next 5-10 years, driven by continuous innovation in healthier formulations. Acquisition targets include niche brands with established direct-to-consumer channels or unique functional ingredient profiles. Watch for accelerated compliance deadlines on nutritional labeling as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Line Expansion | Introduce new plant-based protein snacks to capture flexitarian consumer demand. |
| Sustainable Packaging Adoption | Transition to recyclable or compostable materials, appealing to environmentally conscious buyers. |
| AI-Driven Flavor R&D | Utilize predictive analytics to accelerate development of novel and successful flavor combinations. |
| Emerging Market Penetration | Adapt core brands to local taste preferences in high-growth countries like India. |
| Direct-to-Consumer Channel Investment | Build e-commerce capabilities to reach targeted consumer segments with specialized products. |
Research Approach
Desk research of regulatory filings, industry association reports, and public company financial disclosures preceded structured interviews with snack brand managers, R&D directors, and retail buyers. This approach combined primary insights with extensive secondary validation. Bottom-up analysis of product segments and top-down market sizing ensured robust data triangulation.
Assumptions regarding stable macroeconomic conditions were held fixed, while consumer preference shifts and regulatory impacts were varied across the analysis window. Quantitative modeling projected market growth across product type, flavor profile, packaging type, distribution channel, and regional consumer behavior. Compound annual growth rates were derived from historical trends and projected future demand. Disposable income growth and evolving food labeling regulations served as key forecast inputs.
Practitioners should monitor geopolitical instability and significant global supply chain disruptions for early signals of market shifts. Forecasts reflect underlying assumptions about consumer behavior and regulatory stability. Material shifts in commodity prices or trade policies would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Instant Meat Marinated Snacks Market
Snacks
Packaged Rice Snacks Market
Snacks
Potato Chips Market
Snacks
Protein Crisps Market
Snacks
Asia-Pacific Snack Bar Market
Snacks
Asia-Pacific Popcorn Market
Snacks
Low Calorie Biscuits Market
Snacks
Extruded Snacks Market
Snacks
Fruit and Vegetable Chips Market
Snacks
Europe Popcorn Market
Snacks
Low-Fat Tortillas Market
Snacks
Jerky Snacks Market
Snacks
Plant-Based Snacks Market
Snacks
Grass-Fed Jerkies Market
Snacks
Germany Snack Bar Market
Snacks
Low Fat Protein Snacks Market