
 On-The-Go Breakfast Cereals Market | 2026-2036
On-The-Go Breakfast Cereals Market Size, Share, and Industry Trends Forecast 2026-2036
On-The-Go Breakfast Cereals Market Insights
Single-serve cup and pouch bundling is pivoting how consumers evaluate portability and portion control in morning routines. Kellogg Company leverages its manufacturing scale to dominate shelf-stable cereal cup production across North American convenience channels. General Mills anchors its competitive stance through R&D intensity in resealable packaging formats that extend product freshness without refrigeration. Nestlé differentiates via geographic dominance in European grab-and-go oatmeal segments, where hot-fill cup technology controls distribution costs.
On-the-go breakfast cereals comprise pre-portioned, shelf-stable grain formulations processed through extrusion, flaking, or baking, then packaged for consumption without traditional bowl-and-spoon preparation; products typically achieve moisture content below 10 percent to ensure ambient stability and target commuters, students, and shift workers seeking sub-60-second meal solutions. Granola bars occupy the largest margin pool due to premium ingredient positioning and established impulse-purchase placement at checkout counters. Ready-to-eat cereal in single-serve cups records the fastest structural expansion, driven by vending machine penetration and workplace micro-market installations. Breakfast cookies remain a mature sub-segment with limited innovation velocity, though health food stores sustain niche demand through clean-label reformulations.
The FDA enforces nutrition fact panel disclosures and added-sugar thresholds that compel reformulation across branded portfolios, while USDA organic certification standards shape ingredient sourcing decisions for premium-tier entrants. The EPA regulates packaging material recyclability, pressuring suppliers toward fiber-based alternatives that alter unit economics for single-serve formats. Stakeholders must monitor evolving state-level extended producer responsibility legislation and decide whether to internalize packaging redesign costs or pass through price adjustments to convenience store partners.
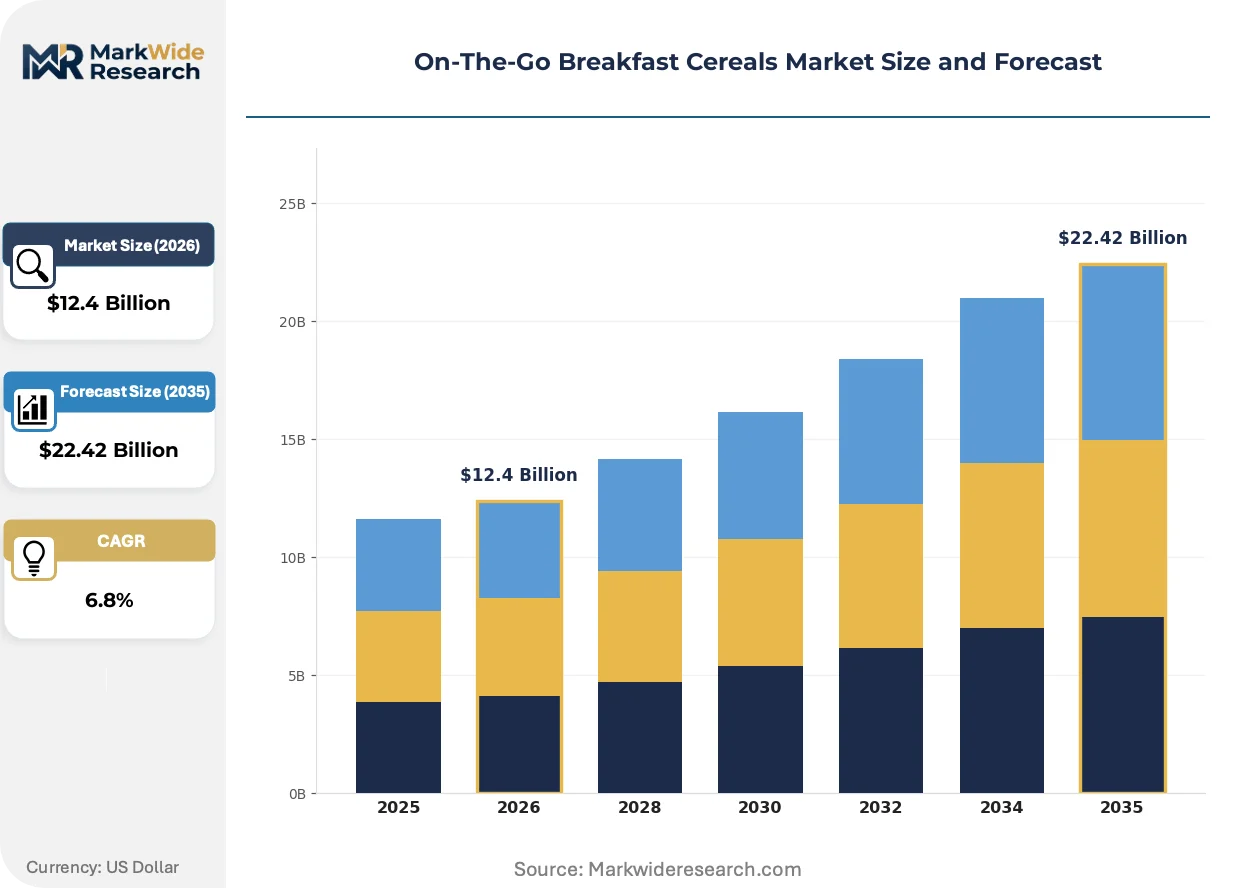
Market Dynamics
Single-serve packaging economics and FDA sugar disclosure mandates are compressing formulation cycles while expanding R&D budgets across branded portfolios. Portion-controlled formats now dominate convenience channel shelf resets.
Growth Catalysts
- Vending machine infrastructure:Workplace micro-market installations in the United States accelerate single-serve cup penetration without traditional retail slotting fees.
- USDA organic certification:Premium-tier entrants leverage certified sourcing to command shelf price premiums in natural food channels.
- Hot-fill cup technology:Ambient-stable oatmeal formats reduce cold-chain dependency, unlocking distribution cost advantages in European grab-and-go segments.
Market Restraints
- Oat and wheat input volatility:Commodity grain price swings compress margin predictability for extruded cereal formulations.
- Single-use packaging bans:Extended producer responsibility legislation in California and New York forces fiber-based redesign investments.
- Refrigerated protein bar substitution:Chilled alternatives capture commuter protein-seeking occasions with superior satiety claims.
Strategic Opportunities
- Indian urban transit corridors:Underpenetrated railway station kiosks present white-space for shelf-stable cup formats targeting 45-minute commutes.
- EU Green Deal packaging mandates:Regulatory tailwinds favor early movers with compostable film laminates in single-serve pouches.
- Direct-to-workplace subscription:Employer-sponsored breakfast programs bypass retail slotting constraints entirely.
Industry Challenges
- Food technologist scarcity:Reformulation expertise for reduced-sugar extrusion binds at premium compensation levels.
- Dual certification timelines:Simultaneous USDA organic and Non-GMO Project verification extends product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | On-The-Go Breakfast Cereals Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granola Bars, Breakfast Cookies, Ready-to-Eat Cereal, Oatmeal Cups Packaging Type: Single-Serve Packs, Multi-Serve Boxes, Pouches, Tubs Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Health Food Stores Consumer Type: Busy Professionals, Students, Parents, Health-Conscious Individuals |
| Companies Covered | Kellogg Company, General Mills, Nestlé, Post Holdings, PepsiCo, Quaker Oats Company, The Hain Celestial Group, Danone, WK Kellogg, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
On-The-Go Breakfast Cereals Market Trends and Innovations
Automation in packaging lines and reformulation chemistry is compressing product development cycles while enabling mass customization at unit volumes previously uneconomical for single-serve formats.
High-speed robotic cup filling and sealing equipment is automating changeover between SKUs, reducing downtime from 45 minutes to under 90 seconds. Mid-sized co-manufacturers in Ohio and Pennsylvania are adopting these systems to compete with integrated majors. The technology is automating small-batch production economics, eroding the volume advantage previously held by capital-intensive players.
REACH packaging substance restrictions are compelling migration from conventional polyethylene to fiber-based barrier coatings. European suppliers face reformulation deadlines for adhesives and inks in direct food contact layers. Breakfast cookie and granola bar segments absorb the highest compliance costs due to complex multi-layer film requirements.
Employer-subsidized micro-market purchasing is displacing individual convenience store transactions among white-collar shift workers. Food service management companies like Aramark and Compass Group are consolidating procurement decisions across thousands of client locations. This concentration is most visible in United States tech corridor campuses where subsidized pricing distorts brand loyalty metrics.
On-The-Go Breakfast Cereals Market Segmentation
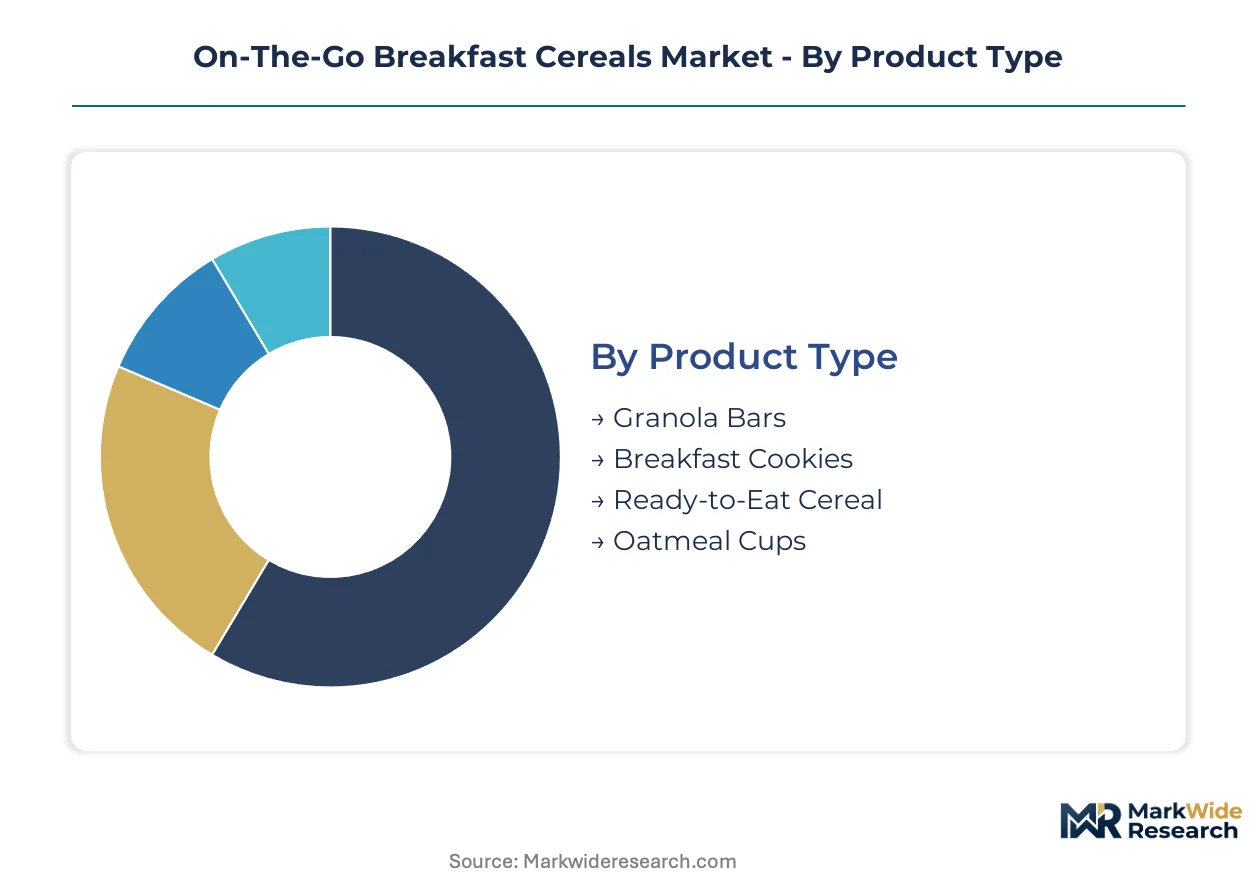
Portability requirements and consumption occasion fragmentation create distinct buyer clusters in on-the-go breakfast cereals. Each segmentation axis reveals how formulation, packaging, and channel strategies must align to capture specific commuter and workplace eating behaviors.
Product Type:
Texture stability and preparation time separate buyers into distinct consumption occasions.
- Granola Bars:Dense, baked oat and nut matrices achieve moisture content below 8 percent for ambient shelf stability. Demand concentrates in United States checkout lane impulse zones where 30-second purchase decisions dominate morning commuter traffic.
- Ready-to-Eat Cereal:Extruded and flaked grain formulations packaged in single-serve cups eliminate bowl-and-spoon requirements. Workplace micro-market installations in United States tech corridors accelerate penetration where refrigeration-free storage is mandatory.
- Breakfast Cookies:Soft-baked formats with extended shelf life through modified atmosphere packaging.
- Oatmeal Cups:Hot-fill processed oats enabling boiling water preparation without kitchen facilities.
Granola bars lead volumes today; ready-to-eat cereal is gaining share fastest.
Packaging Type:
Unit economics and portion control precision dictate procurement decisions across channel tiers.
- Single-Serve Packs:Individually wrapped portions with tamper-evident seals support vending machine compatibility and workplace micro-market distribution. United States convenience channel resets prioritize these formats for grab-and-go velocity.
- Pouches:Flexible film laminates with resealable zippers reduce per-unit material costs versus rigid containers. European railway kiosks and Indian urban transit corridors favor this format for lightweight portability during extended commutes.
- Multi-Serve Boxes:Secondary packaging aggregating individual units for pantry stocking and family consumption.
- Tubs:Rigid containers targeting bulk purchasing and extended household use cycles.
Single-serve packs dominate revenue contribution; pouches are climbing the fastest.
Distribution Channel:
Slotting economics and shopper mission type determine brand visibility and margin capture.
- Convenience Stores:High-velocity locations near transit hubs and employment centers command premium placement fees for eye-level single-serve positioning. United States urban corridors generate the highest transaction frequency for sub-60-second purchase occasions.
- Online Retailers:Subscription models and bulk purchasing platforms reduce per-unit delivery costs for pantry-loading behaviors. Direct-to-consumer channels bypass traditional slotting constraints entirely.
- Supermarkets:Center-store placement competing with traditional breakfast alternatives.
- Health Food Stores:Clean-label and certified organic assortments targeting ingredient-conscious segments.
Convenience stores anchor volume today; online retailers are expanding most quickly.
Consumer Type:
Time scarcity intensity and nutritional prioritization shape willingness-to-pay and format preferences.
- Busy Professionals:White-collar shift workers in United States tech and finance corridors prioritize sub-60-second consumption with minimal cleanup. Employer-subsidized micro-market purchasing displaces individual retail transactions in campus environments.
- Health-Conscious Individuals:Ingredient label scrutiny drives demand for reduced-sugar and high-fiber formulations. FDA disclosure mandates and USDA organic certification command price premiums in natural food channels.
- Students:Budget-constrained segments prioritizing shelf stability and dorm-room storage compatibility.
- Parents:Multi-unit purchasers balancing child acceptance with convenience requirements.
Busy professionals generate the highest per-capita spending; health-conscious individuals are deepening engagement fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ready-to-eat cereal manufacturing originated in Battle Creek, Michigan during the late nineteenth century, establishing production protocols that later diffused to European and Asian markets. The United States remains the largest single-country market for on-the-go breakfast cereals, though growth rates now favor emerging urban corridors in Asia and Latin America.
United States
Workplace micro-market installations and employer-subsidized breakfast programs drive single-serve cup penetration across tech corridor campuses. FDA nutrition labeling mandates compel reformulation toward reduced-sugar extruded cereals. Battle Creek, Michigan and Minneapolis-St. Paul anchor manufacturing clusters where automated cup-filling lines achieve 90-second SKU changeovers.
Germany
Railway station kiosk networks and autobahn service centers sustain demand for resealable pouch formats targeting long-distance commuters. REACH packaging substance restrictions accelerate migration from polyethylene to fiber-based barrier coatings. The Munich-Stuttgart corridor hosts co-manufacturing facilities specializing in organic-certified granola bar production for pan-European distribution.
India
Urban transit corridors and railway station food plazas present white-space for shelf-stable cup formats serving 45-minute commutes. FSSAI food safety standards shape ingredient sourcing and labeling requirements for multinational entrants. Maharashtra and Karnataka concentrate domestic manufacturing capacity near Mumbai and Bangalore logistics hubs.
United Kingdom
Convenience channel density in London and Southeast England supports grab-and-go velocity for single-serve packs. Extended producer responsibility legislation pressures suppliers toward recyclable fiber-based packaging redesigns. The East Midlands hosts extrusion and baking facilities supplying major supermarket private-label programs.
Brazil
Expanding urban middle-class breakfast routines shift toward portion-controlled formats in São Paulo and Rio de Janeiro metro areas. ANVISA food additive regulations govern preservative and sweetener approvals for reformulated products. The São Paulo state interior concentrates oat and wheat processing capacity serving South American export markets.
On-The-Go Breakfast Cereals Market Competitive Landscape
The competitive structure tilts toward diversified multinational food conglomerates with integrated manufacturing footprints and established convenience channel relationships. Three archetypes dominate: scale-driven cereal specialists with North American production networks, European health-food portfolio owners leveraging organic certification premiums, and diversified snack conglomerates cross-leveraging distribution infrastructure. Capacity expansion in automated cup-filling lines and strategic partnerships with workplace food service management companies constitute the dominant competitive moves reshaping market access.
Among North American integrated manufacturers, Kellogg Company and General Mills exemplify scale-driven archetypes with captive production of shelf-stable single-serve formats. Nestlé occupies a distinct position bridging European grab-and-go oatmeal segments with hot-fill cup technology advantages. These three entities anchor the competitive landscape through manufacturing scale and channel access rather than through differentiated product positioning alone.
| Leading Market Players |
|---|
| Kellogg Company |
| General Mills |
| Nestlé |
| Post Holdings |
| PepsiCo |
| Quaker Oats Company |
| The Hain Celestial Group |
| Danone |
| WK Kellogg |
| Others |
Pricing and Supply Chain Analysis
Employer-subsidized micro-market purchasing in United States tech corridors is consolidating procurement decisions into fewer hands, forcing suppliers to absorb fiber-based packaging redesign costs or surrender shelf positioning to co-manufacturers with automated cup-filling lines. This buyer concentration compresses margin pools while rewarding scale players who can internalize compliance investments without passing through price adjustments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates USDA organic certified offerings from conventional formulations and private-label alternatives. Price differentiation hinges on certification tier and volume scale, with organic premiums widening as dual certification timelines extend. Cost compression in the standard tier is intensifying because REACH packaging mandates force adhesive and ink reformulation. Health-conscious individuals in natural food channels exhibit lowest price sensitivity; students in dormitory storage scenarios exhibit highest.
Supply Chain Analysis
Oat and wheat input supply rests on agricultural production clusters in the United States, Canada, and Russia, with milling concentration in the Midwest and Prairie provinces. Raw material dependencies include extrusion-grade grain fractions, modified atmosphere packaging films, and hot-fill cup barrier coatings. Single-source vulnerability pervades the specialty film laminate segment where European suppliers face REACH substance restriction deadlines. Distribution runs through food service management companies consolidating procurement across workplace micro-market networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between California's extended producer responsibility legislation and India's FSSAI labeling requirements creates divergent compliance cost structures, rewarding geographic footprint flexibility.
For Market Incumbents: Extend automated cup-filling capacity in Battle Creek and Minneapolis-St. Paul manufacturing clusters to defend against mid-sized Ohio and Pennsylvania co-manufacturers eroding volume advantages. Deepen backward integration into extrusion-grade oat supply to offset commodity grain price volatility compressing margin predictability. For New Entrants and Emerging Players: Begin with white-space penetration in Indian railway station kiosks serving 45-minute urban commutes, where shelf-stable cup formats remain underdeveloped. Leverage direct-to-workplace subscription models bypassing retail slotting constraints entirely, anchoring initial revenue through employer-sponsored breakfast programs. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-sized co-manufacturers possessing robotic SKU changeover capability and food service management company relationships. Long-term viability favors targets with demonstrated reformulation chemistry expertise for reduced-sugar extrusion. Watch FDA added-sugar threshold enforcement as inflection indicator for portfolio restructuring urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Cup-Filling Line Deployment | Reduces SKU changeover from 45 minutes to 90 seconds, matching integrated major economics. |
| Fiber-Based Packaging Redesign | Anticipates California and New York extended producer responsibility legislation deadlines. |
| Direct-to-Workplace Subscription Launch | Bypasses convenience store slotting fees through Aramark and Compass Group procurement consolidation. |
| Dual Certification Investment | Captures USDA organic and Non-GMO Project premiums in natural food channel placement. |
| Hot-Fill Cup Technology Expansion | Reduces cold-chain dependency for European grab-and-go oatmeal segment penetration. |
Research Methodology
Coverage spans the United States, Germany, India, the United Kingdom, and Brazil, with primary inputs from each market cluster. The approach combines interviews with brand managers, category buyers at convenience retailers, supply planners, and channel sales heads with secondary validation from Nielsen retail audit data, customs records, FDA filings, and SEC 10-K disclosures. Bottom-up and top-down triangulation cross-checks manufacturer capacity announcements against channel inventory velocity.
Rate-of-change decomposition separates volume growth from price mix effects across the projection horizon. Segmentation dimensions modeled include product type, packaging format, distribution channel, and consumer archetype, with regional regulatory cluster as an additional industry-specific dimension. CAGRs derive from trend extrapolation adjusted for enforcement timelines of FDA nutrition labeling mandates and EU Green Deal packaging requirements.
Caveats apply where commodity grain price volatility or accelerated extended producer responsibility legislation enforcement could materially shift the outlook. Forecasts reflect assumptions about workplace micro-market installation rates and employer subsidy program expansion. A small set of named triggers—oat futures contract movements, FDA added-sugar threshold revisions, and fiber-based barrier coating cost curves—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Ready Meal Trays Market
Packaged Foods
China Packaged Food Products Market
Packaged Foods
Canned Soup Market
Packaged Foods
Dried Soup Market
Packaged Foods
Canned Fruits Market
Packaged Foods
United Arab Emirates Food Products Market
Packaged Foods
Pre-Packaged Sandwich Market
Packaged Foods
Global Breakfast Cereals Market
Packaged Foods
Club Store Packs Market
Packaged Foods
Microwavable Foods Market
Packaged Foods
Packaged Currants Market
Packaged Foods
Ready Meals Market
Packaged Foods
Organic Energy Bar Market
Packaged Foods
Non-Fried Instant Noodles Market
Packaged Foods
Dehydrated and Dried Beans Market
Packaged Foods
Instant Noodles Market