
 Europe Snack Bar Market | 2026-2036
Europe Snack Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Snack Bar Market Foresight
Premium clean-label specification tiers is bifurcating the Europe snack bar landscape into ingredient-provenance segments. Nestlé leverages its Swiss R&D footprint to sustain organic certification pipelines. General Mills anchors its position through whole-grain formulation leadership in Nordic markets. Mondelez International competes on chocolate-inclusion expertise across Continental Europe.
Europe snack bars comprise compressed cereal, nut, or protein matrices bound by syrups or hydrocolloids, typically shelf-stable at ambient conditions for 9-18 months and engineered for portable macronutrient delivery. Granola bars occupy mature volume positions with thin margins, while protein bars capture expanding margin pools in athletic and weight-management applications. Online retail channels demonstrate structural acceleration as health food stores consolidate in Benelux urban corridors.
EFSA nutrition and health claims regulation shapes permissible front-of-pack messaging, while EU Green Deal sustainability frameworks pressure ingredient sourcing transparency. REACH compliance governs packaging material migration limits into fatty matrices. Stakeholders must monitor ECHA substance restriction proposals for emulsifiers and monitor EFSA novel food approvals for emerging protein isolates.
Market Dynamics
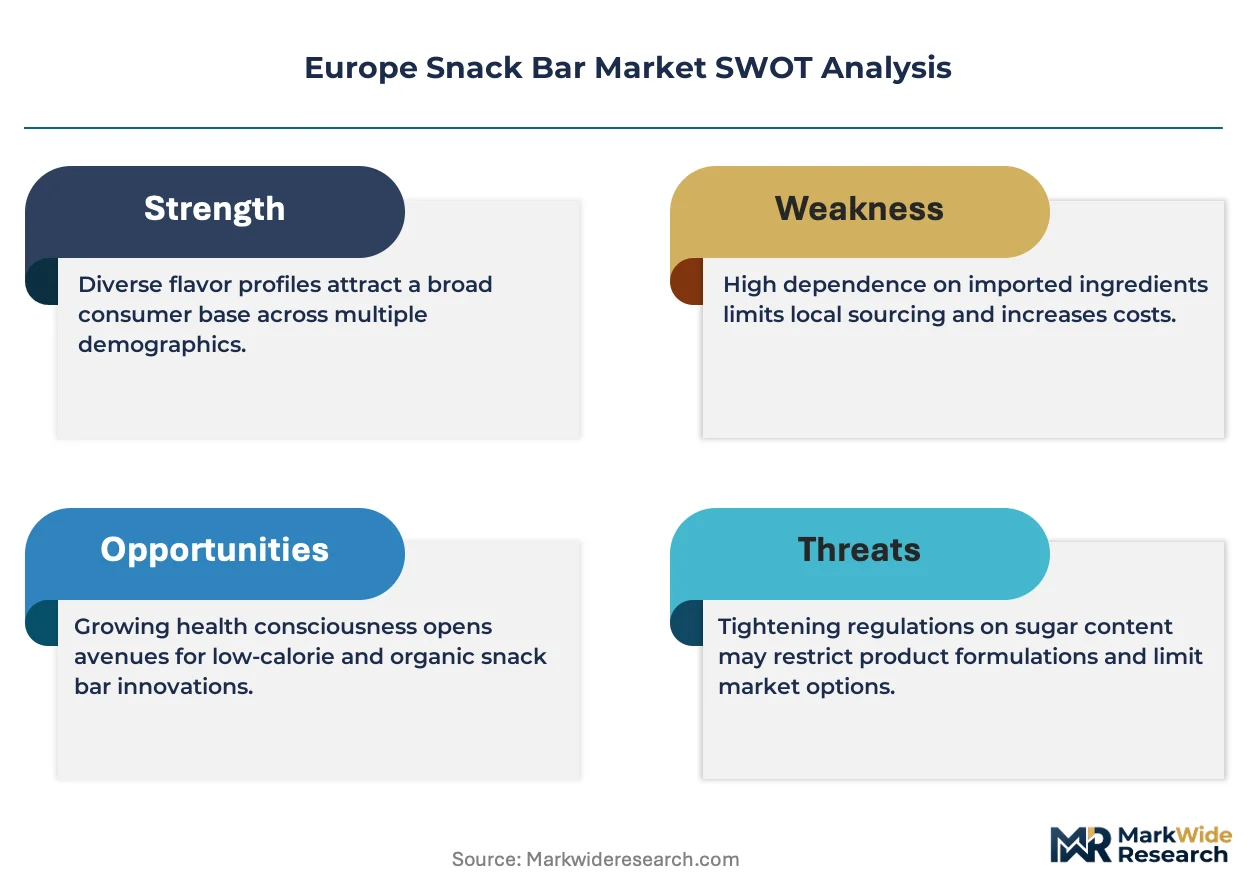
The EU Green Deal is forcing snack bar manufacturers to restructure ingredient sourcing and packaging specifications across Continental supply chains, creating a bifurcation between legacy formulations and certified-sustainable product lines.
Growth Catalysts
- EFSA nutrition claims framework:Permissible protein-content front-of-pack messaging is expanding addressable demand in German athletic nutrition channels.
- Urban fitness channel concentration:UK metropolitan gym networks and boutique studios are normalizing portable protein consumption as meal-replacement behavior.
- Benelux online retail acceleration:Direct-to-consumer subscription models are capturing repeat-purchase loyalty outside traditional grocery consolidation.
Market Restraints
- RoHS and REACH packaging compliance:Migration testing for fatty matrix contact is extending new-product development timelines by 8-14 months.
- Organic certification bottlenecks:Swiss and Austrian alpine ingredient suppliers face capacity constraints on pesticide-free nut and seed volumes.
- Sugar-reduction technical ceiling:Allulose and rare sugar approvals remain pending under EFSA novel food protocols, limiting reformulation options.
Strategic Opportunities
- Eastern European underpenetration:Poland and Romania display sub-12% per-capita snack bar consumption versus Western European baselines.
- CSRD sustainability reporting mandate:Scope 3 ingredient traceability requirements are creating first-mover advantages for vertically integrated supply chains.
- Plant-protein isolate convergence:Fava bean and lupin protein technologies are opening allergen-free formulation white space beyond soy and whey.
Industry Challenges
- Clean-label R&D talent scarcity:Formulation chemists with hydrocolloid and natural binding expertise command 40-60% salary premiums in Swiss and Dutch labor markets.
- Dual certification complexity:Simultaneous organic and carbon-neutral audits are fragmenting quality assurance bandwidth at mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Snack Bar Market |
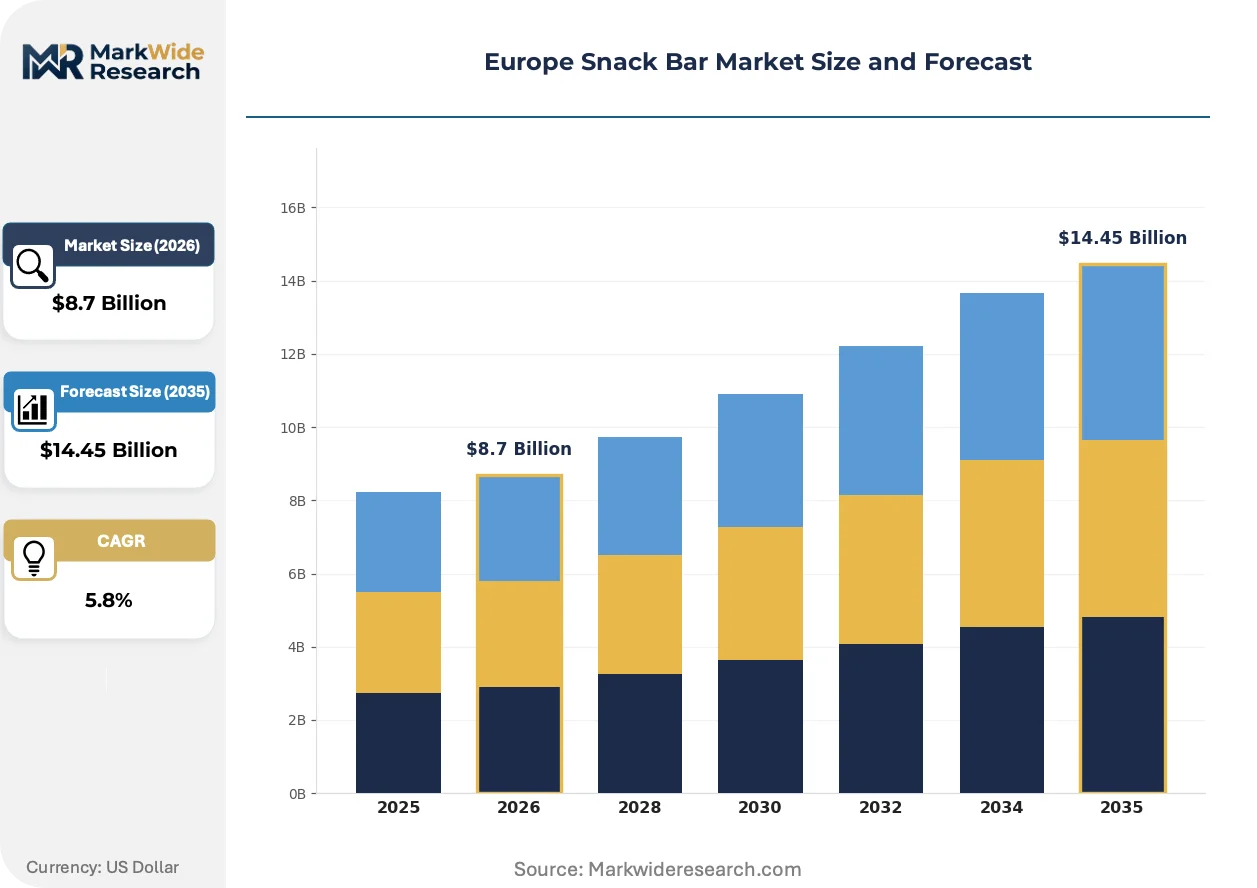
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Bars, Granola Bars, Energy Bars, Meal Replacement Bars Ingredients: Nuts, Fruits, Chocolate, Whole Grains Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Health Food Stores Consumer Demographics: Health Conscious, Athletes, Busy Professionals, Parents |
| Companies Covered | Nestlé, General Mills, Kellogg Company, Mondelez International, PepsiCo, Mars Incorporated, Intersnack Group, The Simply Good Foods Company, Danone, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Snack Bar Market Shifts & Advancements
Reformulation priorities are pivoting from macronutrient density to ingredient provenance transparency, with binding technologies and shelf-life extension methods under simultaneous pressure.
Precision fermentation-derived protein isolates are decomposing traditional commodity protein sourcing structures. Nordic and German plant-based specialists are adopting these inputs at pilot scale. The technology is decomposing established soy and whey supply contracts by enabling localized, traceable production with reduced agricultural land use.
EU Green Deal Farm-to-Fork sustainability targets are mandating 25% pesticide reduction and 20% fertilizer reduction by 2030. Snack bar ingredient procurement is contracting directly with regenerative agriculture cooperatives in France and Italy. Organic-certified cereal and nut volumes are experiencing allocation pressure as CPG manufacturers across categories compete for limited supply.
German and French millennials are prioritizing packaging material over ingredient list in split-second purchase decisions. Retail channels are responding with unpackaged bulk dispensing in urban zero-waste stores. This behavioral pivot is most visible in Berlin and Paris arrondissement-level grocery consolidation, where conventional wrapped bars face shelf-space compression.
Europe Snack Bar Market Segmentation
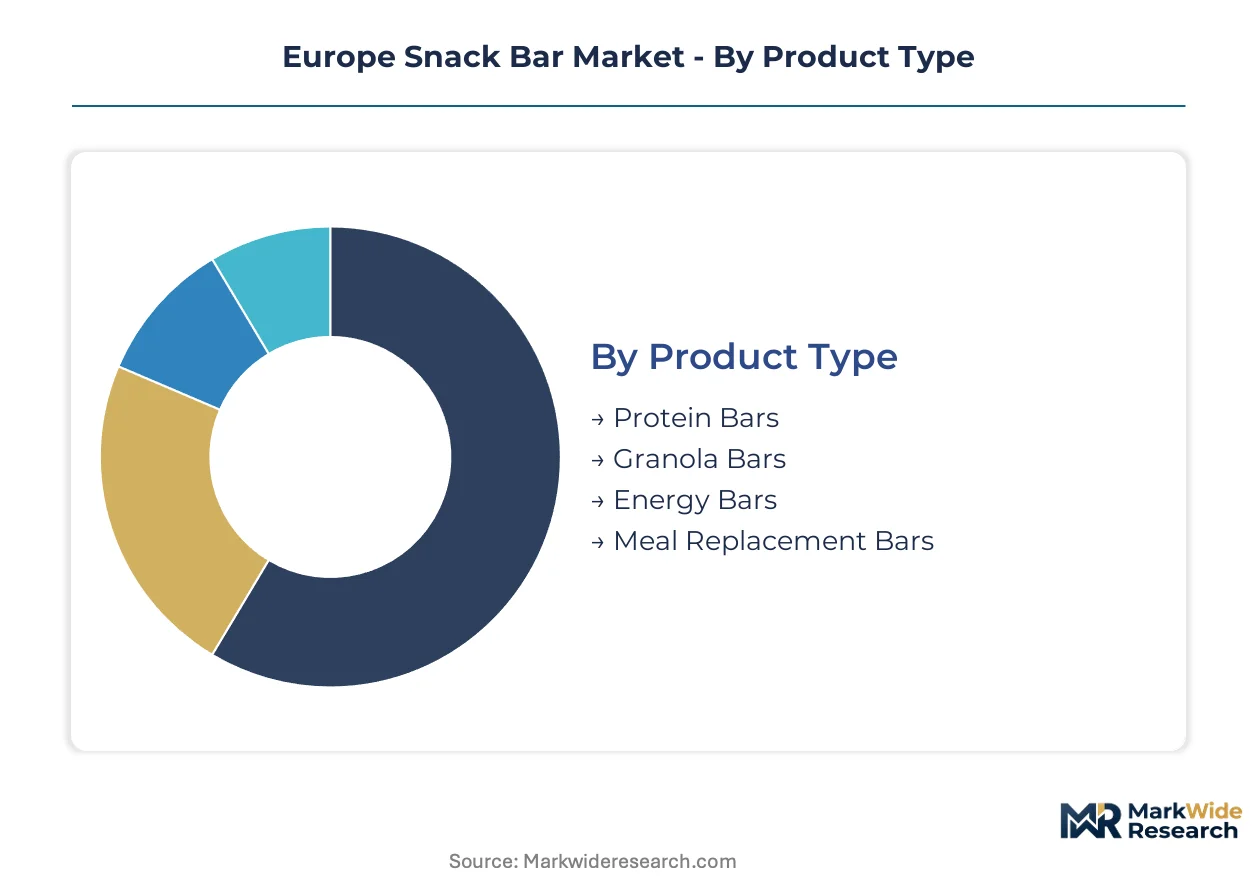
Snack bar segmentation in Europe reflects divergent sourcing economics and channel access. Product formulation choices determine margin structure, while distribution reach dictates which consumer cohorts manufacturers can profitably serve.
Product Type:
Substitution pressure from fresh food delivery and ready-to-drink nutrition is fragmenting the traditional bar format, forcing each segment to defend distinct consumption occasions.
- Protein Bars:Compressed matrices of whey, casein, or plant isolates bound by maltitol or glycerin, delivering 15-25g protein per 60g serving. Demand clusters in UK metropolitan gym networks and German athletic nutrition channels, driven by EFSA-permissible protein-content claims on front-of-pack labeling. Formulation chemists with hydrocolloid expertise command salary premiums in Swiss labor markets, constraining R&D bandwidth at mid-scale producers.
- Granola Bars:Baked oat and honey clusters with nut inclusions, occupying mature volume positions with compressed margins. German and French retail buyers treat these as commodity basket-fillers, pressuring suppliers toward private-label conversion. Shelf-space compression in conventional grocery is accelerating as zero-waste bulk formats gain traction in Berlin and Paris urban corridors.
- Energy Bars:Carbohydrate-dense formulations targeting endurance athletes, typically featuring glucose polymers and electrolyte fortification. Benelux cycling culture and Alpine skiing tourism sustain niche demand.
- Meal Replacement Bars:Macro-balanced formulations with vitamin and mineral fortification, competing with liquid meal alternatives. UK weight-management channels show strongest adoption among busy professionals seeking portable caloric control.
Granola bars retain volume leadership; protein bars hold the steepest expansion curve.
Ingredients:
Cost tier stratification separates premium provenance claims from commodity input sourcing, with certification premiums widening price bands.
- Nuts:Almond, cashew, and hazelnut inclusions anchor clean-label positioning. Swiss and Austrian alpine suppliers face pesticide-free capacity constraints, creating allocation bottlenecks for organic-certified production lines. REACH migration testing for oil contact extends development timelines.
- Fruits:Dried berry and citrus inclusions provide natural sweetness and antioxidant marketing hooks. Mediterranean sourcing from Italy and Spain dominates conventional supply; organic volumes experience competition from adjacent CPG categories.
- Chocolate:Cocoa mass and coating layers differentiate indulgence-positioned bars. Belgian and Swiss chocolate expertise supports premium tier pricing, though EU Green Deal deforestation regulations are restructuring West African sourcing contracts.
- Whole Grains:Oat, quinoa, and ancient grain flours supply fiber claims and texture bulk. Nordic markets show strongest per-capita consumption, with General Mills leveraging formulation leadership in this geography.
Whole grains dominate volume throughput; nuts command the widest certification premiums.
Distribution Channel:
Channel concentration is accelerating in digital pathways while physical retail consolidates around convenience and health-specialist formats.
- Supermarkets:Hypermarket and grocery multiples control mainstream volume, but shelf-space compression is favoring SKU consolidation toward top-performing brands. French and German retail buyers are reducing facings for conventional wrapped bars.
- Convenience Stores:Impulse-oriented locations in transport hubs and urban centers capture grab-and-go consumption. Premium pricing tolerance is lower than in health-specialist channels.
- Online Retail:Direct-to-consumer subscription models are capturing repeat-purchase loyalty outside traditional grocery consolidation. Benelux urban corridors show strongest penetration, with precision targeting of athletic and weight-management cohorts.
- Health Food Stores:Specialist retailers in urban clusters validate premium positioning through curated assortment. Store consolidation is reducing independent door count in Netherlands and Belgium.
Supermarkets retain volume leadership; online retail is climbing the fastest.
Consumer Demographics:
Application-specific need states are hardening into distinct product-positioning territories, with limited cross-purchase between segments.
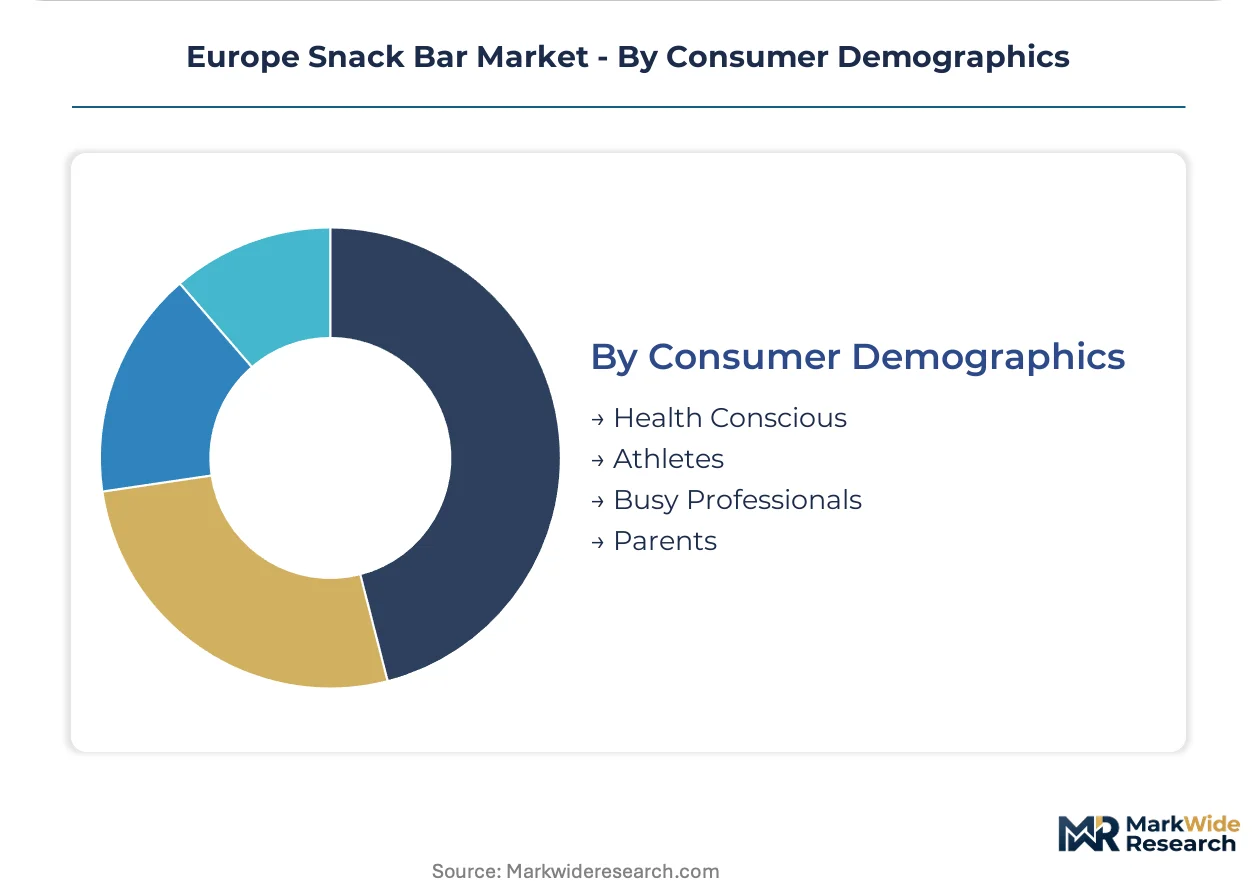
- Health Conscious:Clean-label seekers prioritizing ingredient provenance over macronutrient ratios. German and French millennials lead this behavioral pivot, with packaging material assessments preceding ingredient list review in purchase decisions.
- Athletes:Performance-oriented consumers demanding validated protein content and rapid glycemic response. UK gym network normalization of portable protein consumption is expanding addressable demand.
- Busy Professionals:Time-constrained urban workers seeking meal-replacement efficiency. London and Paris financial districts show highest per-capita consumption.
- Parents:Family purchasers balancing nutritional acceptability with child palatability. Lunchbox-compatible formats face sugar-reduction technical constraints pending EFSA novel food approvals.
Health conscious consumers retain volume leadership; athletes hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented Swiss and Belgian chocolate specialists supply premium coating inputs to German and French formulators, while Mediterranean fruit and nut suppliers from Italy and Spain anchor southern sourcing corridors. Import dependency for organic-certified alpine ingredients creates allocation bottlenecks during peak procurement cycles.
Germany
Athletic nutrition channels in Munich and Hamburg drive protein bar adoption among millennial fitness cohorts. EFSA-permissible protein-content front-of-pack messaging expands addressable demand under current nutrition claims frameworks. Berlin's zero-waste retail corridors are compressing conventional wrapped bar shelf space as unpackaged bulk formats gain traction.
United Kingdom
Metropolitan gym networks in London and Manchester normalize portable protein consumption as meal-replacement behavior. REACH compliance for fatty matrix packaging contact extends new-product development timelines. Birmingham's logistics clusters support direct-to-consumer subscription fulfillment accelerating repeat-purchase loyalty outside grocery consolidation.
France
Paris arrondissement-level grocery consolidation favors packaging material assessments over ingredient list review in split-second purchase decisions. EU Green Deal Farm-to-Fork pesticide reduction targets restructure procurement contracts toward regenerative agriculture cooperatives. Lyon and Marseille urban corridors lead zero-waste store expansion for unpackaged bulk dispensing.
Switzerland
Swiss R&D footprints sustain organic certification pipelines for premium clean-label tiers. Alpine nut and seed suppliers face pesticide-free capacity constraints creating allocation pressure for certified production lines. Zurich and Geneva clusters concentrate formulation chemists commanding salary premiums for hydrocolloid expertise.
Netherlands
Benelux online retail acceleration captures repeat-purchase loyalty through precision targeting of athletic and weight-management cohorts. CSRD sustainability reporting mandates create first-mover advantages for vertically integrated supply chains with Scope 3 ingredient traceability. Rotterdam's port logistics anchor continental distribution for imported protein isolates.
Europe Snack Bar Market Competitive Landscape
Listed leaders compete with private specialists across certification tier access, creating a bifurcated structure where scale advantages in conventional grocery face agility premiums in direct-to-consumer channels. The vendor base clusters around three archetypes: diversified CPG conglomerates with R&D centralization, mid-scale organic specialists with alpine sourcing relationships, and private-label converters serving retail consolidation. Dominant competitive moves include backward integration into nut and seed supply and strategic partnerships with precision fermentation protein developers.
Within the diversified CPG tier, Nestlé and General Mills exemplify scale-driven positioning, while Mondelez International occupies a specialized niche around chocolate-inclusion expertise. These entities represent contrasting approaches to the clean-label transition—Swiss-headquartered Nestlé leverages centralized R&D certification pipelines, Minneapolis-based General Mills anchors whole-grain formulation leadership in Nordic markets, and Illinois-incorporated Mondelez competes on indulgence-positioned product development across Continental Europe.
| Leading Market Players |
|---|
| Nestlé |
| General Mills |
| Kellogg Company |
| Mondelez International |
| PepsiCo |
| Mars Incorporated |
| Intersnack Group |
| The Simply Good Foods Company |
| Danone |
| Others |
Supply & Pricing Matrix
EU Green Deal sustainability certification gates both supplier qualification and price differentiation simultaneously, forcing manufacturers to absorb organic premium costs or pass them to packaging-sensitive millennials in Berlin and Paris. REACH compliance for fatty matrix contact extends development timelines, compressing margins on reformulated lines while EFSA novel food approval delays for rare sugars limit low-cost sugar-reduction pathways.
Pricing Analysis
Health-conscious millennials anchor a three-tier pricing structure across premium, standard, and economy levels in Europe snack bar markets. Price differentiation rests on organic certification grade and clean-label ingredient provenance, with Swiss and Austrian alpine sourcing commanding widest premiums. Pricing pressure stems from private-label conversion in German and French grocery consolidation, where retail buyers treat granola bars as commodity basket-fillers. Parents purchasing lunchbox-compatible formats show highest price sensitivity; athletes in UK gym networks demonstrate lowest sensitivity to protein-content premiums.
Supply Chain Analysis
Alpine nut and seed harvests from Switzerland, Austria, and southern Germany create seasonal chokepoints that constrain organic-certified production line allocation. Formulation inputs draw from Mediterranean dried fruit corridors in Italy and Spain, West African cocoa mass regulated under EU deforestation due diligence, and emerging precision fermentation protein isolates from Nordic pilot facilities. Single-source vulnerability concentrates in pesticide-free alpine suppliers facing Farm-to-Fork pesticide reduction mandates. Distribution runs through Rotterdam port logistics for imported isolates, Benelux direct-to-consumer subscription fulfillment, and consolidated French and German grocery multiples.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label fragmentation across ingredient-provenance tiers creates niche entry points as millennial packaging assessments precede ingredient list review in split-second purchase decisions.
For Market Incumbents: Compound scale advantages in certification pipelines by deepening backward integration into Swiss and Austrian alpine nut supply. Nestlé's centralized R&D model offers template for sustaining organic certification bandwidth. Defend against precision fermentation protein disruptors by locking long-term offtake with regenerative agriculture cooperatives in France and Italy. For New Entrants and Emerging Players: Differentiate on unpackaged bulk dispensing formats in Berlin and Paris zero-waste corridors where conventional wrapped bars face shelf-space compression. Target Poland and Romania's sub-12% per-capita consumption baselines with localized production avoiding REACH migration testing delays. Lead with direct-to-consumer subscription models capturing repeat-purchase loyalty outside grocery consolidation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision fermentation protein isolate production as pilot-scale Nordic facilities seek scale-up financing. Mid-scale organic specialists with alpine sourcing relationships represent acquisition targets with defensible certification moats. Watch EFSA novel food approval velocity for allulose and rare sugars as margin structure inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alpine Nut Supply | Captive supply of pesticide-free ingredients insulates against Farm-to-Fork allocation bottlenecks in Switzerland and Austria. |
| Precision Fermentation Protein Partnership | Technology licensing from Nordic pilot facilities decomposes traditional soy and whey commodity sourcing structures. |
| Direct-to-Consumer Subscription Launch | Benelux urban corridor penetration captures repeat-purchase loyalty outside consolidating French and German grocery channels. |
| Zero-Waste Bulk Format Introduction | Unpackaged dispensing aligns with Berlin and Paris millennial packaging assessments preceding ingredient list review. |
| CSRD Scope 3 Traceability Investment | Vertically integrated supply chains create first-mover advantage under mandatory sustainability reporting frameworks. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with category buyers at French and German grocery multiples, brand managers at diversified CPG conglomerates, formulation chemists in Swiss R&D clusters, and procurement leads at alpine nut cooperatives; and secondary validation through EFSA novel food approval databases, EU Green Deal Farm-to-Fork implementation reports, REACH substance restriction proposals, Nielsen retail audit data for Benelux and UK channels, and customs records for protein isolate imports. Bottom-up volume builds by product type and ingredient tier triangulated against top-down macroeconomic consumption elasticity models.
Across the analysis window, the forecasting framework modeled protein bar, granola bar, energy bar, and meal replacement bar segments against nut, fruit, chocolate, and whole grain ingredient tiers, further dimensionalized by supermarket, convenience store, online retail, and health food store channel access. CAGRs derived from historical consumption elasticities applied to projected urban fitness channel expansion and zero-waste retail penetration curves. Forecast inputs incorporated EFSA nutrition claims framework expansion scenarios and CSRD Scope 3 traceability compliance cost pass-through assumptions.
Decision-makers should treat outputs as directional under base assumptions of sustained EU Green Deal implementation velocity and stable EFSA approval timelines; material deviation in regulatory enforcement or novel food authorization velocity would warrant model refresh. Practitioners should keep alternative scenarios live as precision fermentation protein cost curves and alpine organic certification capacity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
India Snack Bar Market
Snacks
Roasted Snacks Market
Snacks
South Africa Savory Snacks Market
Snacks
Nuts and Seeds (Savory Snacks) Market
Snacks
Cereal Bars Market
Snacks
Middle East and Africa Snack Food Market
Snacks
Salty Puffed Snacks Market
Snacks
UK Snack Market
Snacks
Europe Cereal Bar Market
Snacks
Low Sodium Snacks Market
Snacks
Fried Potato Chips Market
Snacks
Global Vegetable Chips Market
Snacks
South America Snack Bar Market
Snacks
Saudi Arabia Snack Bar Market
Snacks
South America Frozen Snacks Market
Snacks
North America Fruit Snacks Market