
 Middle East and Africa Pea Starch Market | 2026-2036
Middle East and Africa Pea Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Pea Starch Market Foresight
EU Green Deal alignment requirements for imported food ingredients are shifting compliance burdens onto Middle East and Africa suppliers seeking European market access. Roquette Frères leverages its French manufacturing base to pre-certify pea starch shipments for re-export through Moroccan and UAE distribution hubs. Ingredion Incorporated competes by sustaining dual-spec production lines that satisfy both Gulf Standards Organization and EFSA purity criteria. AGT Food and Ingredients Inc. anchors its regional position through Saskatoon-based pulse processing expertise adapted for halal-certified supply chains.
Pea starch is the carbohydrate fraction extracted from Pisum sativum seeds, typically comprising 35-40% amylose and 60-65% amylopectin, obtained via wet milling and subsequent purification to achieve neutral flavor and white coloration for industrial applications. Native pea starch dominates current formulation volumes due to its lower processing cost and clean-label appeal among Gulf food manufacturers reformulating away from chemically modified alternatives. Modified pea starch captures expanding share in pharmaceutical tablet binding and textile sizing, where cross-linked and oxidized variants deliver superior film-forming and adhesive performance under high-humidity conditions prevalent in Sub-Saharan manufacturing environments.
SFDA's updated food additive standards, South Africa's Department of Health labeling directives, and Egypt's EOS quality conformity requirements collectively shape product registration timelines and purity thresholds across the region. EMA-equivalent standards for pharmaceutical-grade excipients further bifurcate the supply base between food-grade and USP/NF-compliant production streams. Stakeholders must monitor how GCC harmonization of import specifications affects cross-border inventory pooling between Dubai Jebel Ali and Durban port free zones.
Market Dynamics
Clean-label reformulation mandates across Gulf food manufacturing are compressing formulation windows and forcing rapid substitution of chemically modified starches with native pea alternatives. This regulatory pressure is redrawing procurement relationships between ingredient suppliers and processed food producers.
Growth Catalysts
- SFDA Labeling Directives:Saudi Arabia's tightened additive disclosure rules are accelerating plant-based starch adoption in sauces, dressings, and bakery segments.
- Pulse Processing Scale-Up:Wet milling capacity expansions in Saskatchewan and France are securing feedstock reliability for regional distributors.
- South Africa's Processed Food Sector:Sauce and convenience food manufacturers are displacing modified corn starch with pea-derived alternatives to meet retailer clean-label requirements.
Market Restraints
- Yellow Pea Price Volatility:Canadian prairie weather variability and export competition from Asian markets are creating input cost instability for starch processors.
- Dual-Specification Production Burden:Manufacturers must maintain parallel food-grade and pharmaceutical-grade lines to satisfy divergent Gulf Standards Organization and EMA-equivalent purity thresholds.
- Tapioca Starch Substitution:Southeast Asian cassava-derived alternatives are capturing share in cost-sensitive textile sizing and paper coating applications.
Strategic Opportunities
- Egyptian Food Manufacturing:EOS conformity requirements are creating first-mover advantage for suppliers establishing local technical service presence.
- Pharmaceutical Excipient Grade:USP/NF-compliant pea starch for tablet binding remains underpenetrated across Sub-Saharan generic drug production.
- Halal Supply Chain Certification:Dedicated processing streams and segregated logistics are opening premium positioning in GCC markets.
Industry Challenges
- Cross-Border Inventory Pooling Complexity:GCC harmonization delays are fragmenting stock management between Dubai Jebel Ali and Durban free zones.
- Dual Certification Timeline Compression:Parallel registration with SFDA, South Africa's Department of Health, and Egypt's quality authorities is extending product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Pea Starch Market |
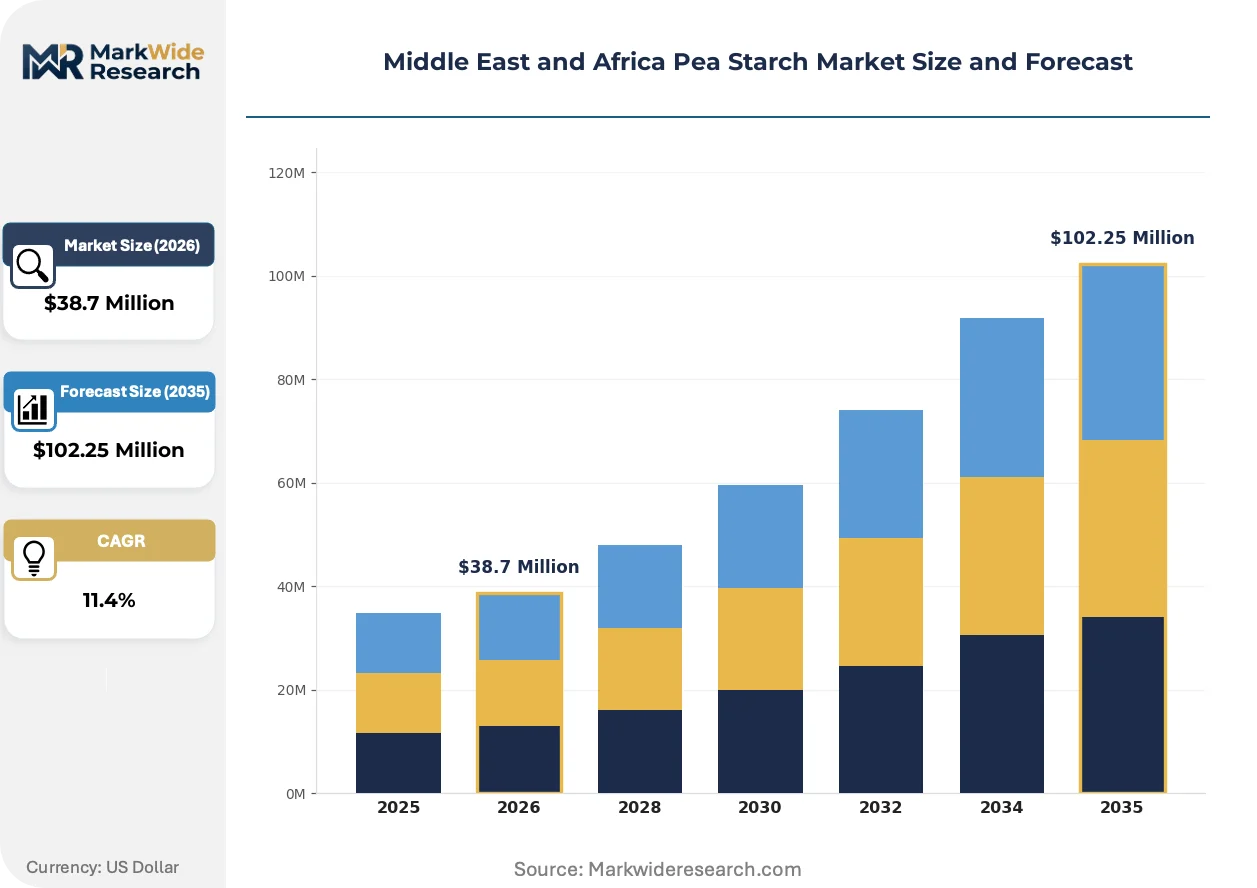
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $102.25 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Native Pea Starch, Modified Pea Starch, Pre-gelatinized Pea Starch, Organic Pea Starch Application: Food & Beverage, Personal Care, Pharmaceuticals, Textiles End User: Food Manufacturers, Cosmetic Companies, Pharmaceutical Companies, Textile Producers Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Roquette Frères, Ingredion Incorporated, Groupe Emsland, COSUCRA - Groupe Warcoing, The Scoular Company, Yantai Shuangta Food Co. Ltd, Puris, AGT Food and Ingredients Inc., Vestkorn Milling AS, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Pea Starch Market Shifts & Advancements
Wet milling technology advances and regulatory disclosure tightening are converging to reshape ingredient selection criteria across Middle East and Africa food manufacturing. Formulators now prioritize traceability and minimal processing claims.
Cross-linked and oxidized pea starch variants are consolidating technical specifications for pharmaceutical tablet binding and textile sizing in high-humidity Sub-Saharan environments. Generic drug manufacturers in Nigeria and Kenya are adopting these modified grades at accelerating pace. The technology is consolidating supplier relationships around fewer vendors capable of dual food-pharma certification.
EU Green Deal alignment requirements for imported food ingredients are extending compliance burdens onto Middle East and Africa suppliers seeking European market access. Roquette Frères and Ingredion Incorporated are pre-certifying shipments through French and US manufacturing bases respectively. Egyptian and Moroccan processors are responding by upgrading laboratory capabilities to document carbon intensity and deforestation-free sourcing.
Direct procurement relationships between Gulf food manufacturers and Saskatchewan-based pulse processors are compressing traditional distributor margins. Large Saudi and UAE bakery and sauce producers are negotiating volume contracts that bypass regional traders. This channel disintermediation is most visible in Riyadh and Jeddah industrial zones where procurement teams now manage ocean freight and customs clearance internally.
Middle East and Africa Pea Starch Market Segmentation
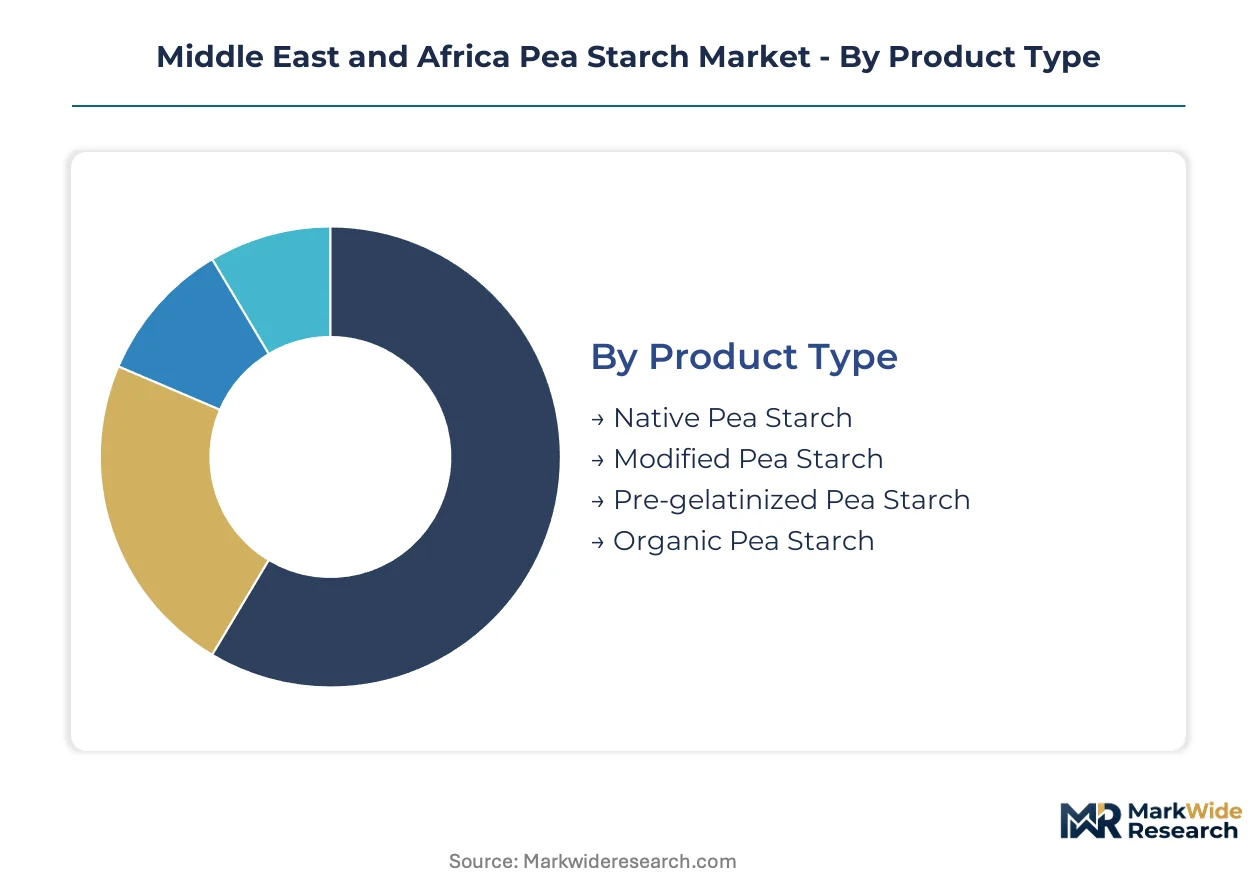
Segmentation in the Middle East and Africa pea starch market reveals divergent capital requirements across processing technologies and end-use specifications. Gulf food manufacturers prioritize native grades for clean-label compliance, while pharmaceutical and textile buyers demand modified variants with certified performance under humid Sub-Saharan conditions.
Product Type:
Capital intensity varies sharply across processing tiers, with wet milling infrastructure for native grades requiring moderate investment while pharmaceutical-grade modification lines demand specialized cross-linking and oxidation equipment.
- Native Pea Starch:Extracted through standard wet milling to achieve 35-40% amylose content and neutral flavor profile. Saudi Arabia's SFDA labeling directives are accelerating displacement of chemically modified corn and potato alternatives in Riyadh and Jeddah sauce manufacturing. Most installed capacity flows through Native Pea Starch. Expansion is steepest in Modified Pea Starch.
- Modified Pea Starch:Cross-linked and oxidized variants deliver superior film-forming under high-humidity conditions prevalent in Nigerian and Kenyan pharmaceutical tablet binding. EMA-equivalent purity thresholds bifurcate production streams between food-grade and USP/NF-compliant lines.
- Pre-gelatinized Pea Starch:Cold-water soluble grades serve instant soup and bakery premix applications across South Africa's convenience food sector.
- Organic Pea Starch:Certified organic supply chains command premium positioning in UAE and Qatar retail channels with halal-aligned traceability requirements.
Most installed capacity flows through Native Pea Starch. Expansion is steepest in Modified Pea Starch.
Application:
Application segmentation tracks divergent formulation requirements across moisture stability, binding strength, and regulatory disclosure thresholds.
- Food & Beverage:Clean-label reformulation in GCC sauces, dressings, and bakery applications drives volume concentration. South African processed food manufacturers displace modified corn starch to meet retailer disclosure requirements.
- Pharmaceuticals:USP/NF-compliant tablet binding remains underpenetrated across Sub-Saharan generic drug production. Nigerian and Kenyan manufacturers are adopting modified grades at accelerating pace.
- Textiles:Sizing applications in high-humidity Sub-Saharan environments favor cross-linked variants with adhesive stability.
- Personal Care:Film-forming properties in creams and lotions serve UAE and Saudi cosmetic formulators seeking plant-derived alternatives.
Volume concentration sits with Food & Beverage. Technical specification margins are climbing fastest in Pharmaceuticals.
End User:
End user segmentation reflects procurement sophistication tiers, from integrated Gulf food manufacturers managing direct ocean freight to fragmented textile mills relying on distributor networks.
- Food Manufacturers:Large Saudi and UAE bakery and sauce producers negotiate volume contracts bypassing regional traders. Direct procurement relationships compress traditional distributor margins.
- Pharmaceutical Companies:Sub-Saharan generic drug manufacturers face dual certification timelines with SFDA and national regulators.
- Textile Producers:Cost-sensitive sizing applications face substitution pressure from Southeast Asian tapioca alternatives.
- Cosmetic Companies:Premium positioning in GCC markets requires halal-certified supply chain segregation.
Procurement scale concentrates with Food Manufacturers. Technical service requirements are expanding most quickly among Pharmaceutical Companies.
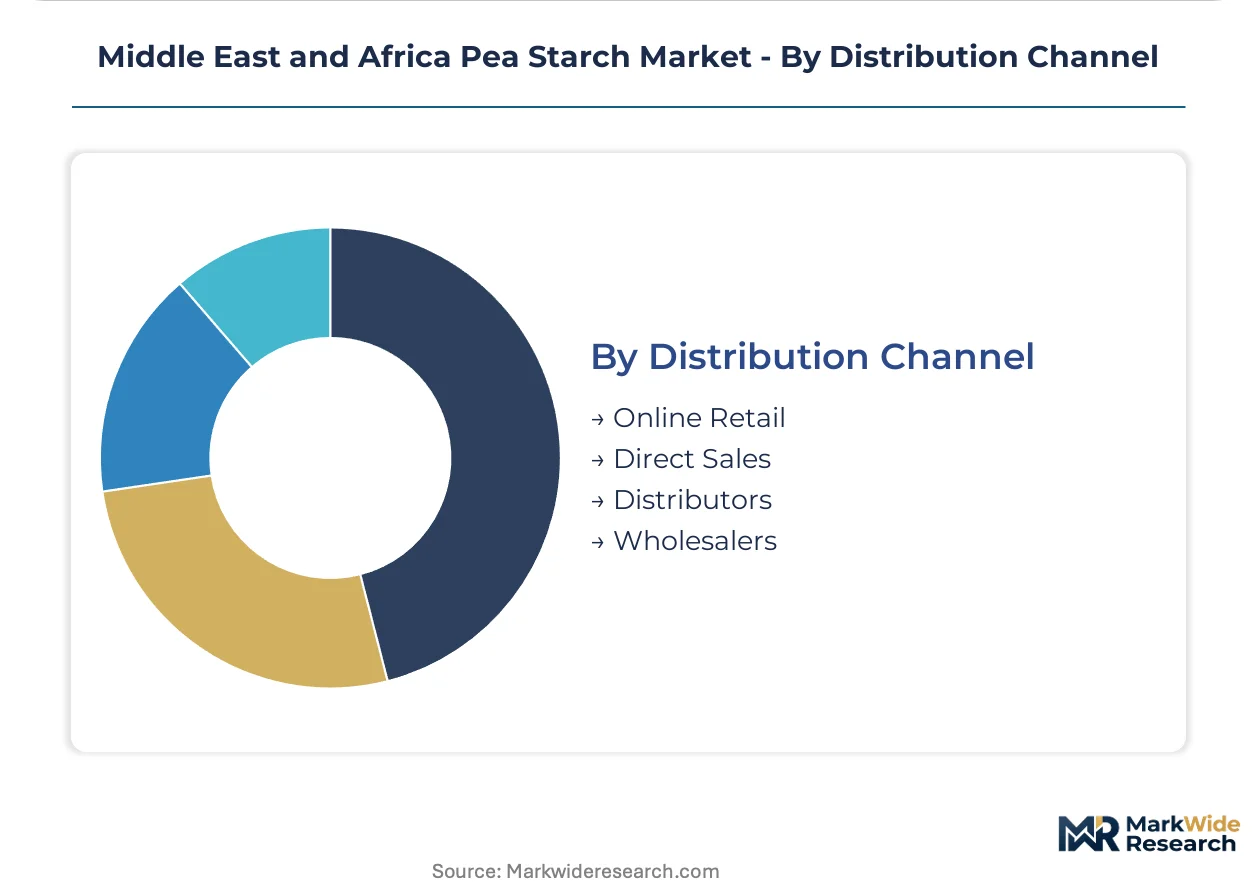
Distribution Channel:
Channel segmentation tracks disintermediation pressure as large buyers internalize logistics and customs clearance functions.
- Direct Sales:Volume contracts between Saskatchewan pulse processors and Riyadh industrial zone manufacturers eliminate margin layers.
- Distributors:Roquette Frères and Ingredion leverage Moroccan and UAE hubs for re-export pre-certification.
- Wholesalers:Fragmented textile and smaller food manufacturing buyers in Egypt and South Africa rely on regional stockholding.
- Online Retail:Niche organic and specialty grades serve research-scale pharmaceutical and cosmetic formulators.
Transaction value concentrates through Direct Sales. Channel development investment is flowing fastest into Distributor technical service capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pea starch processing originated in European wet milling facilities before Gulf food manufacturers began importing for clean-label reformulation. Regional demand now concentrates in Saudi Arabia, South Africa, UAE, Egypt, and Nigeria.
Saudi Arabia
Sauce and bakery manufacturers in Riyadh and Jeddah industrial zones drive native pea starch procurement for additive-free formulations. SFDA tightened labeling disclosure rules in 2023, forcing reformulation away from chemically modified corn alternatives. Direct contracts with Saskatchewan pulse processors now bypass traditional distributors.
South Africa
Processed food producers in Gauteng and Western Cape provinces displace modified potato starch in convenience meals and dressings. The Department of Health's updated labeling directives align retailer procurement with clean-label ingredient disclosure. Durban port free zone operators manage inventory pooling for re-export to Sub-Saharan markets.
United Arab Emirates
Dubai Jebel Ali free zone anchors regional distribution for re-export across GCC states and East Africa. MOHAP food safety standards require additive traceability documentation for imported starch shipments. Abu Dhabi and Sharjah food manufacturing clusters specialize in halal-certified bakery premix applications.
Egypt
Domestic sauce and processed dairy manufacturers in Cairo and Alexandria industrial zones adopt pea starch to meet EOS quality conformity requirements. The country's national food regulator tightened import purity thresholds for food additives in 2024. Local technical service presence creates first-mover positioning for compliant suppliers.
Nigeria
Generic pharmaceutical manufacturers in Lagos and Kano industrial zones adopt modified pea starch grades for tablet binding applications. The country's national pharmaceutical regulator enforces EMA-equivalent excipient standards for drug production. Cross-linked variants address high-humidity stability requirements prevalent in local manufacturing environments.
Middle East and Africa Pea Starch Market Competitive Landscape
The competitive structure tilts toward integrated ingredient conglomerates with dual-certification capabilities. Wet milling specialists and pulse processors occupy distinct tiers based on pharmaceutical-grade modification capacity. Market participants cluster around three archetypes: French and North American conglomerates with Gulf distribution hubs, Canadian pulse processors with direct procurement relationships, and European specialists in modified starch variants. Capacity expansion and halal supply chain certification represent the dominant competitive moves reshaping procurement relationships.
Among French-based ingredient conglomerates, Roquette Frères exemplifies the integrated archetype with pre-certification infrastructure for EU Green Deal alignment. Ingredion Incorporated represents North American conglomerate positioning through dual-spec production lines satisfying both Gulf Standards Organization and EFSA criteria. AGT Food and Ingredients Inc. anchors the Canadian pulse processor tier with Saskatoon-based wet milling expertise adapted for regional halal-certified supply chains.
| Leading Market Players |
|---|
| Roquette Frères |
| Ingredion Incorporated |
| Groupe Emsland |
| COSUCRA - Groupe Warcoing |
| The Scoular Company |
| Yantai Shuangta Food Co. Ltd |
| Puris |
| AGT Food and Ingredients Inc. |
| Vestkorn Milling AS |
| Others |
Supply & Pricing Matrix
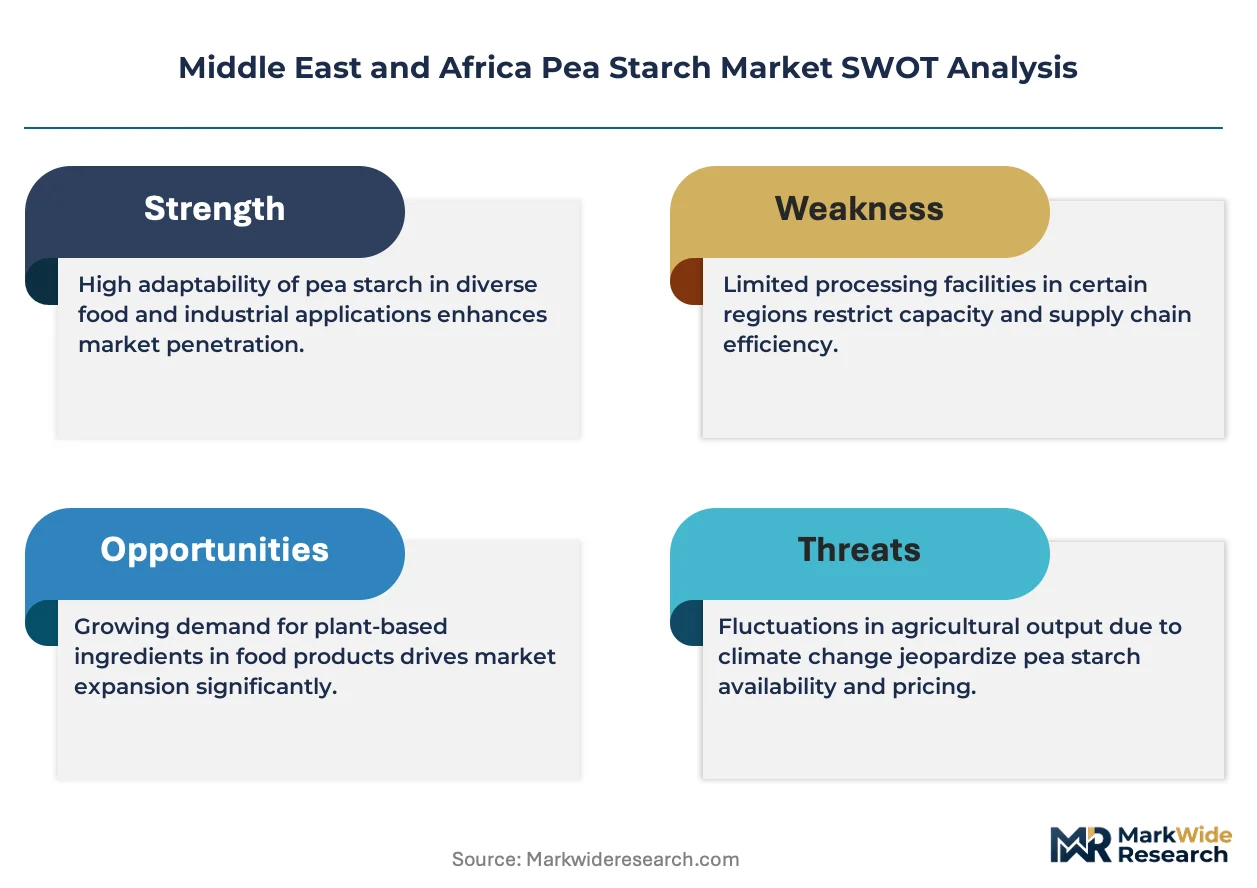
Canadian yellow pea futures volatility transmits through wet milling economics into three-tier pricing structure across premium, standard, and economy levels. Gulf food manufacturers absorbing SFDA compliance costs face compressed margins when contracting with Saskatchewan processors for native starch grades.
Pricing Analysis
Contract-based long-term offtake dominates procurement between Riyadh industrial zone buyers and Canadian pulse processors, with price differentiation resting on halal certification tier and volume scale. Pricing pressure stems from tapioca starch substitution in Egyptian textile sizing, where cost-sensitive mills prioritize Southeast Asian cassava derivatives. Small-scale Egyptian and South African food manufacturers exhibit highest price sensitivity, while Saudi pharmaceutical companies accept premium modified grades for EMA-equivalent compliance.
Supply Chain Analysis
Dual-sourcing requirements from Gulf Standards Organization compel Saudi and UAE manufacturers to qualify both French and Canadian suppliers simultaneously. Supply concentrates in Canada, France, and Morocco, with raw material dependencies on prairie yellow pea cultivation, wet milling capacity, and halal logistics infrastructure. Single-source vulnerability persists in pharmaceutical-grade modification equipment, where cross-linking technology providers remain concentrated in European manufacturing bases. Distribution runs through Dubai Jebel Ali and Durban port free zones for regional re-export pooling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa pea starch market functions as a stable compounder, with clean-label regulatory mandates across GCC states generating sustained displacement demand for chemically modified alternatives.
For Market Incumbents: Anticipate margin compression from direct procurement relationships between Riyadh sauce manufacturers and Saskatchewan processors by securing captive supply of halal-certified wet milling capacity. Defend positioning through dual food-pharma certification investments that extend product registration timelines for competitors. For New Entrants and Emerging Players: E-commerce platforms serving research-scale pharmaceutical formulators in Lagos and Nairobi offer lowest customer acquisition friction. Target USP/NF-compliant modified grades for Nigerian generic drug manufacturers, where EMA-equivalent excipient standards remain underpenetrated and technical service gaps persist. For Investors and Strategic Acquirers: Roll-up economics work for regional distributors with Gulf Standards Organization pre-certification capabilities because compliance timeline fragmentation prevents new entrants from achieving scale rapidly. Monitor SFDA-Egypt EOS harmonization progress as inflection signal for cross-border inventory pooling viability.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Supply Chain Certification | Segregated logistics unlock premium positioning in Saudi Arabia and UAE retail channels. |
| Dual-Specification Production Lines | Parallel food-grade and pharmaceutical-grade capacity satisfies divergent Gulf and EMA purity thresholds. |
| Direct Procurement Relationships | Volume contracts with Saskatchewan processors compress traditional distributor margins in Riyadh industrial zones. |
| Modified Starch Capacity Expansion | Cross-linking and oxidation equipment addresses high-humidity tablet binding demand in Nigerian pharmaceutical manufacturing. |
| Local Technical Service Presence | Egyptian EOS conformity requirements reward first-mover suppliers with accelerated product registration timelines. |
Research Methodology
Coverage spans Middle East and Africa, with primary inputs from each regional cluster through structured interviews with wet milling plant managers, procurement leads at Saudi sauce manufacturers, Egyptian regulatory affairs specialists, and Nigerian pharmaceutical quality directors. Secondary validation drew from SFDA additive disclosure filings, EOS quality conformity documentation, Gulf Standards Organization import specifications, and customs trade records for yellow pea derivatives. Bottom-up volume modeling and top-down value triangulation reconciled segment-level outputs.
Granularity-level modeling tracked product type, application, end user, and distribution channel dimensions across the projection horizon. CAGRs were derived from regression analysis against historical clean-label reformulation penetration rates and pharmaceutical excipient adoption curves. Forecast inputs incorporated prairie weather variability indices for yellow pea yield estimation and GCC regulatory harmonization scenario weights.
The model assumes a particular technology adoption path; alternative pathways for modified starch cross-linking would alter the outlook if pharmaceutical manufacturers accelerate USP/NF-compliant grade substitution. Deviation in Canadian export policy or prairie drought frequency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Mineral Premix Market
Ingredients
North America Potato Starch Market
Ingredients
Sunflower Meal Market
Ingredients
India Bakery Ingredients Market
Ingredients
Oak Extract Market
Ingredients
Aroma Ingredients Market
Ingredients
Global Hydrolyzed Wheat Protein Market
Ingredients
Casein Glycomacropeptide Market
Ingredients
Global Organic Personal Care Ingredients Market
Ingredients
Astragalus Root Extract Market
Ingredients
South America Agar Market
Ingredients
Middle East Feed Palatability Enhancers Market
Ingredients
Europe Vanilla Beans and Extract Market
Ingredients
Mustard Oil Market
Ingredients
Pea Starch Market
Ingredients
Europe Fruit and Vegetable Ingredients Market