
 Thailand Snack Bar Market | 2026-2036
Thailand Snack Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Snack Bar Market Analytics
Single-serve multipack bundling is rebalancing purchase patterns across Thai retail channels. Mondelez International leverages its distribution depth in modern trade outlets. Nestlé S.A. anchors its portfolio through dairy-integrated bar formulations. Kellogg Company competes via cereal-based snack bar lines adapted to local taste profiles.
Thailand snack bars comprise shelf-stable, ready-to-eat pressed or extruded food products typically containing grains, proteins, fruits, or nuts, manufactured through cold-forming or baking processes to achieve portable caloric density. These products serve as meal replacements, energy supplements, or on-the-go nutrition for time-constrained consumers. Granola bars occupy the mature core of the product type dimension with established production infrastructure. Protein bars capture accelerated demand among fitness-oriented consumer demographics in urban centers. The ingredient dimension sees gluten-free and high-protein variants commanding premium shelf positioning and margin expansion.
Thailand's FDA enforces prepackaged food labeling requirements that mandate nutritional disclosure and allergen warnings, directly influencing formulation decisions and packaging design for domestic manufacturers. The Ministry of Public Health's sodium and sugar reduction campaigns reshape permissible ingredient thresholds for health-positioned products. Stakeholders must monitor evolving enforcement patterns around health claims and imported product registration to calibrate market entry and portfolio refresh cycles.
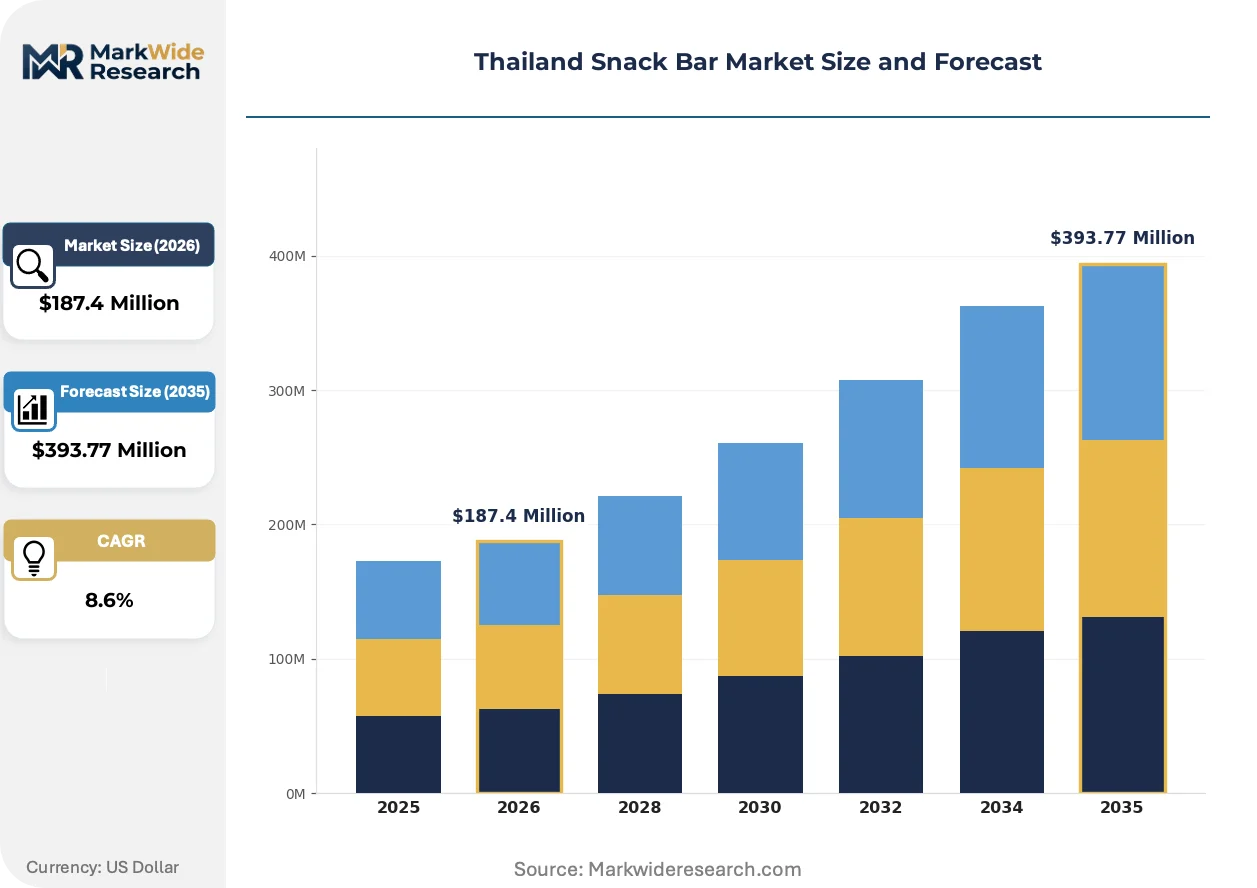
Market Dynamics
Thailand's FDA nutrition labeling mandates are compressing formulation cycles, forcing manufacturers to re-engineer recipes around disclosed sugar and sodium thresholds while maintaining sensory appeal in convenience store channels.
Growth Catalysts
- Urban Fitness Culture:Protein bar demand accelerates among Bangkok and Chiang Mai gym-goers seeking post-workout recovery formats, pulling specialized SKUs into 7-Eleven and Lawson shelves.
- Thailand FDA Labeling Compliance:Prepackaged food disclosure rules create competitive moats for domestic manufacturers with established regulatory affairs capabilities, filtering out informal competitors.
- Cold-Forming Equipment Upgrades:Extrusion technology investments at Rayong and Pathum Thani production facilities enable cleaner-label binding without synthetic stabilizers.
Market Restraints
- Imported Whey Protein Concentration:Over 70% of high-quality dairy protein inputs originate from New Zealand and US suppliers, exposing margins to currency volatility and shipping cost spikes.
- Palm Oil Price Volatility:Binding agents and coating fats face input cost pressure from global vegetable oil market swings, compressing gross margins on economy-tier granola bars.
- Modern Trade Slotting Fees:CP All and Tesco Lotus demand escalating promotional allowances for shelf placement, eroding profitability for sub-scale regional brands.
Strategic Opportunities
- Chiang Rai and Udon Thani Penetration:Upcountry provinces show underdeveloped snack bar availability relative to Bangkok saturation, presenting first-mover expansion potential through local distributor partnerships.
- Ministry of Public Health Sugar Reduction Incentives:Manufacturers achieving reformulation targets gain preferential placement in government workplace wellness programs and school canteen tenders.
- E-Commerce Subscription Models:Shopee and Lazada recurring delivery bundles bypass traditional trade gatekeepers, enabling direct consumer relationships with fitness-oriented micro-segments.
Industry Challenges
- Food Technologist Talent Scarcity:Formulation chemistry expertise combining Thai ingredient knowledge with Western bar-texture standards commands premium compensation, constraining R&D team scaling.
- Halal Certification Timelines:Central Islamic Council of Thailand approval processes extend 8-14 months for export-bound production lines, delaying Middle East market entry.
- Legacy Distributor Integration:Family-owned provincial wholesalers resist digital inventory tracking systems, fragmenting demand signal visibility for upstream production planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Snack Bar Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granola Bars, Protein Bars, Fruit Bars, Nut Bars Ingredient: Organic, Gluten-Free, Vegan, High-Protein Sales Channel: Online, Supermarkets, Convenience Stores, Health Food Stores Consumer Demographics: Students, Working Professionals, Health Enthusiasts, Families |
| Companies Covered | Mondelez International, Inc., Kellogg Company, Nestlé S.A., Hershey Company, The Quaker Oats Company, Mars, Incorporated, PepsiCo, Inc., Anna Thai Snack All, General Mills Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Snack Bar Market Evolving Landscape
Reformulation science and channel digitization are converging to reshape how Thai consumers encounter functional snacking, with texture innovation and transparency claims displacing legacy marketing approaches.
Pea protein isolate is absorbing share from conventional dairy-based formulations in Thailand's protein bar segment, enabling vegan positioning without sacrificing amino acid completeness. Boutique fitness studios in Sukhumvit and Ari districts specify plant-based options in their retail partnerships, compressing the adoption cycle that soy proteins required a decade prior. The ingredient shift is absorbing margin pressure from imported whey tariffs while opening export pathways to Buddhist-majority neighboring markets with dairy avoidance preferences.
Thailand's FDA prepackaged food labeling requirements now mandate front-of-pack sugar and sodium disclosure, forcing manufacturers to reformulate or accept degraded shelf positioning. Domestic brands with in-house analytical laboratories accelerate reformulation cycles, while import-reliant competitors face registration delays and reformulation costs. The regulation most acutely affects cereal-based bars positioned to children, where permissible sweetness thresholds have tightened substantially.
Convenience store chains now command exclusive flavor development and packaging formats, reversing the traditional manufacturer-led innovation model. CP All and Lawson Thailand specify Thai tea, durian, and tom yum flavor profiles unavailable through standard global portfolios, compelling multinational suppliers to establish Bangkok-based sensory labs. This channel-driven customization concentrates in Greater Bangkok before diffusing to Phuket and Chiang Mai provincial outlets over 18-24 month cycles.
Thailand Snack Bar Market Segmentation
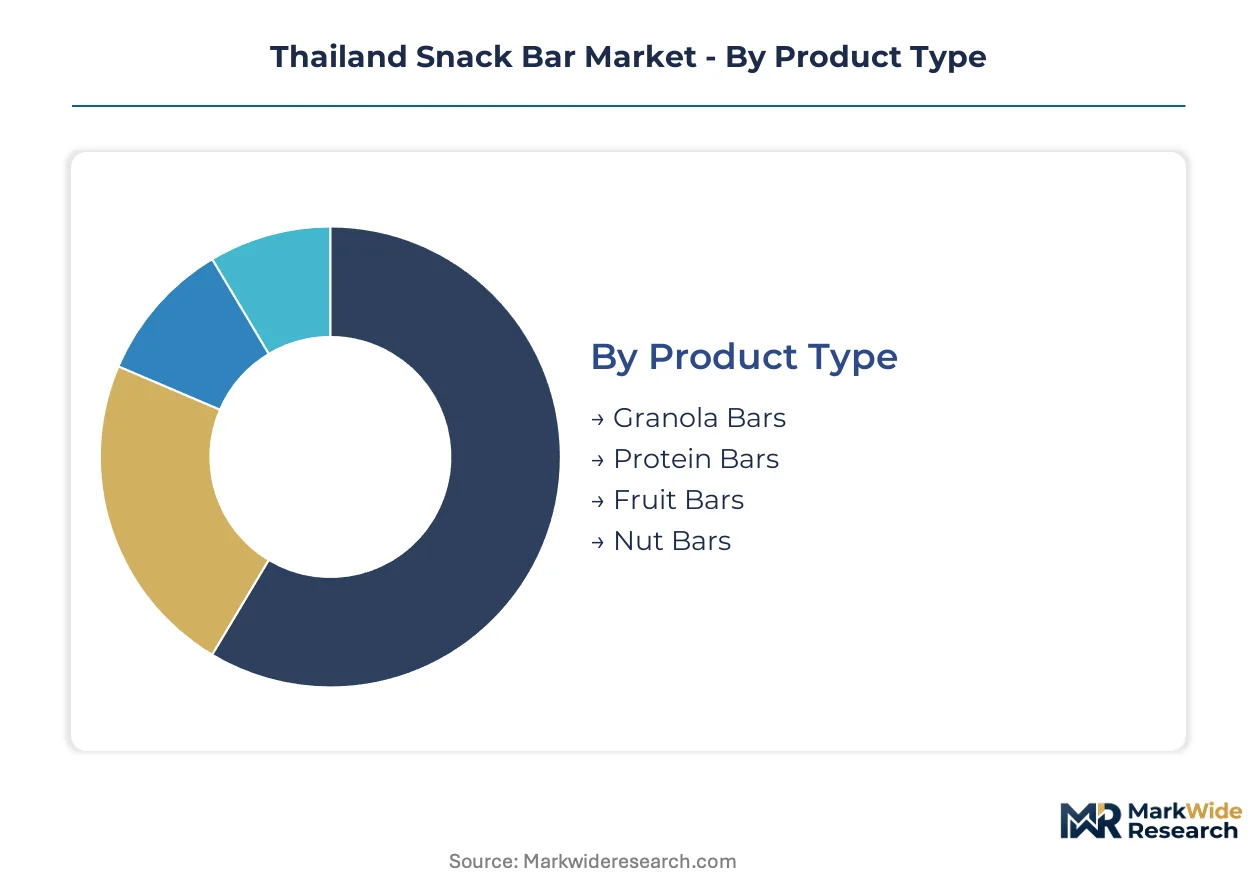
Thailand's snack bar market fragments across four distinct dimensions, each revealing divergent margin structures and channel access patterns. Manufacturers must calibrate portfolio depth against production complexity and distributor relationships unique to each segment cluster.
Product Type:
Standardization dominates the mass-market core, while protein-enriched formats command premium customization investments and specialized extrusion capabilities.
- Granola Bars:Oat-based pressed formulations with honey or syrup binding represent Thailand's most mature production infrastructure. Demand concentrates in Greater Bangkok convenience stores where CP All and Lawson Thailand specify Thai tea and durian flavor exclusives, forcing manufacturers to maintain Bangkok-based sensory labs.
- Protein Bars:Cold-formed extruded products delivering 15-25g protein per serving absorb the steepest capacity expansion at Rayong and Pathum Thani facilities. Bangkok and Chiang Mai gym chains pull specialized SKUs into premium shelf positions, with boutique fitness studios in Sukhumvit and Ari districts specifying pea protein isolate formulations.
- Fruit Bars:Dehydrated fruit pulp and fiber matrices bound with rice syrup serve school canteen tenders and government workplace wellness programs.
- Nut Bars:Almond, cashew, and macadamia-dominant formulations face raw material cost pressure from imported nut tariffs.
Most installed capacity flows through Granola Bars. Expansion is steepest in Protein Bars.
Ingredient:
Cost tier stratification separates premium-positioned certification claims from economy-tier conventional formulations.
- Organic:Certified organic grain and fruit inputs require Ministry of Agriculture supply chain verification, limiting viable sourcing to northern Thailand contract farming networks.
- Gluten-Free:Oat and rice flour substitutions with certified absence thresholds command 15-25% shelf price premiums in Tesco Lotus health aisles.
- Vegan:Pea protein isolate and brown rice protein combinations enable Buddhist-majority export pathways to neighboring markets with dairy avoidance preferences.
- High-Protein:Whey concentrate and isolate formulations depend on New Zealand and US import supply, exposing margins to currency volatility.
Volume concentrates in High-Protein formulations. Margin expansion is strongest in Vegan.
Sales Channel:
Geographic penetration depth varies sharply between modern trade gatekeepers and emerging direct-to-consumer pathways.
- Online:Shopee and Lazada subscription bundles bypass slotting fee structures, enabling recurring revenue capture from fitness micro-segments in Phuket and Chiang Rai provinces.
- Supermarkets:Tesco Lotus and Big C demand escalating promotional allowances, eroding profitability for sub-scale regional brands competing on shelf positioning.
- Convenience Stores:CP All's 7-Eleven network and Lawson Thailand command exclusive flavor development, reversing manufacturer-led innovation cycles.
- Health Food Stores:Bangkok's Ari and Thonglor district boutiques curate imported and domestic premium assortments with personalized staff recommendations.
Revenue share peaks in Convenience Stores. Growth velocity is highest in Online.
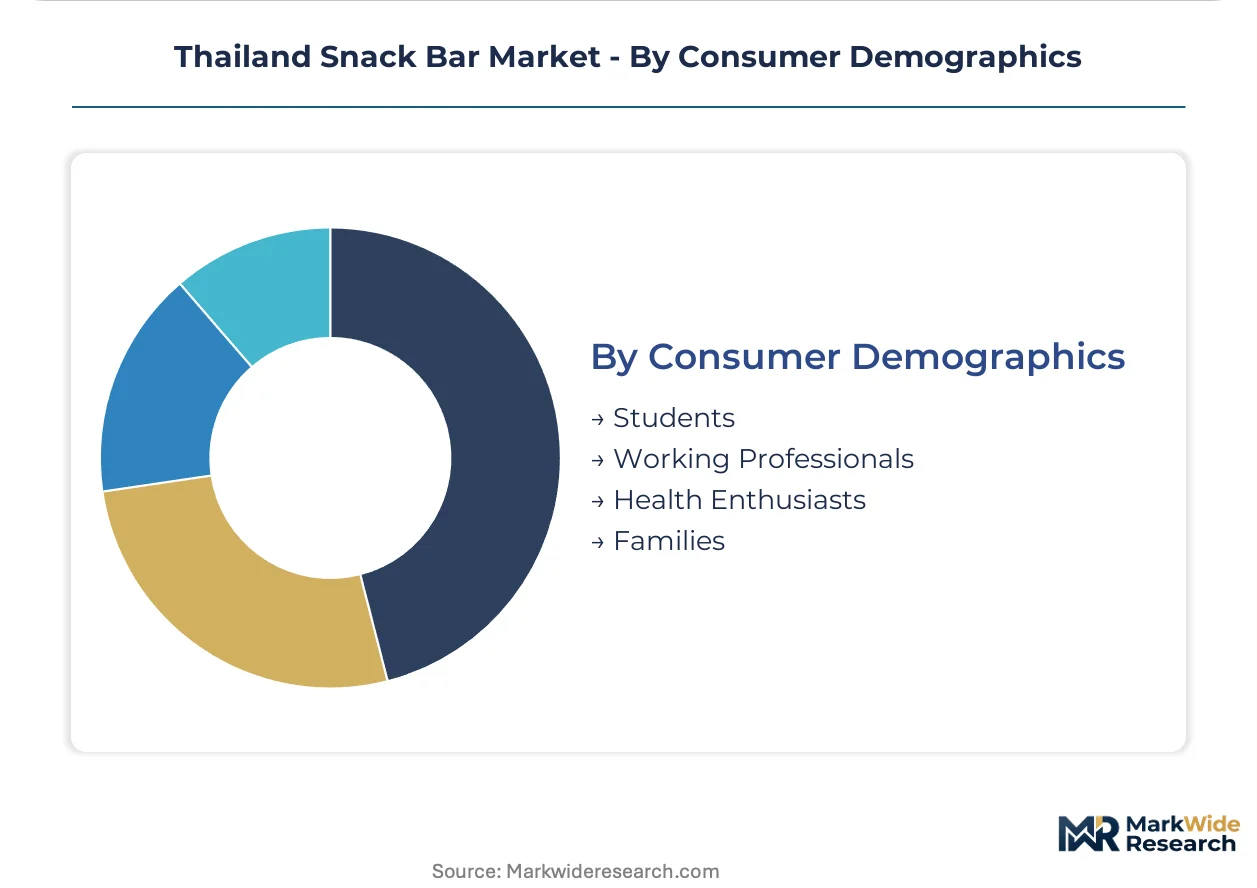
Consumer Demographics:
Application occasion separates meal replacement demand from discretionary snacking behaviors.
- Students:Price-sensitive trial driven by school canteen availability and peer influence in university districts around Kasetsart and Chulalongkorn.
- Working Professionals:Time-constrained Bangkok office workers in Silom and Sathorn districts seek portable caloric density for commute consumption.
- Health Enthusiasts:Post-workout recovery occasions in boutique fitness studios specify clean-label ingredient transparency and macro disclosure compliance.
- Families:Multi-serve purchasing for household pantry stocking concentrates in supermarket channels with promotional bundling sensitivity.
Transaction frequency is highest among Working Professionals. Average basket value leads in Health Enthusiasts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's snack bar industry traces its modern roots to 1990s multinational FMCG entry, when global confectionery and cereal giants established Bangkok-based production and distribution infrastructure to serve Southeast Asian markets. Domestic manufacturing capabilities expanded through the 2000s as local contract packers developed extrusion and cold-forming expertise. Today regional demand patterns reflect divergent urbanization trajectories, regulatory frameworks, and fitness culture maturation across neighboring markets.
Greater Bangkok Metropolitan Region
Bangkok's 10-million-plus population generates the highest per-capita snack bar consumption in Thailand, driven by Silom and Sathorn district office workers seeking commute-friendly meal replacements. Thailand's FDA prepackaged food labeling requirements mandate nutritional disclosure that domestic manufacturers navigate faster than import-dependent competitors. Pathum Thani province hosts the densest concentration of extrusion production facilities, where cold-forming equipment upgrades enable cleaner-label binding systems.
Chiang Mai and Northern Thailand
Chiang Mai's boutique fitness studio ecosystem in Nimmanhaemin and Santitham districts accelerates protein bar adoption among wellness-oriented consumers. The Ministry of Public Health's sugar reduction campaigns receive stronger compliance uptake in this region due to proximity to organic contract farming networks in Chiang Rai. Local distributor partnerships in Udon Thani and Lampang remain underdeveloped relative to Bangkok saturation, presenting first-mover expansion potential for brands establishing provincial wholesale relationships.
Phuket and Southern Coastal Provinces
Phuket's tourism-dependent economy creates seasonal demand spikes for portable nutrition among hospitality workers and international visitors. Central Islamic Council of Thailand halal certification processes extend 8-14 months for export-bound production, delaying Middle East market entry for manufacturers based in this region. Songkhla province's port infrastructure supports ingredient import logistics for whey protein concentrate sourced from New Zealand and US suppliers.
Rayong and Eastern Economic Corridor
Rayong province anchors Thailand's most advanced snack bar manufacturing cluster, with extrusion technology investments enabling specialized protein bar production at scale. The Eastern Economic Corridor's tax incentive structures attract packaging material suppliers and flavor houses co-locating with finished goods producers. Chonburi province's proximity to Laem Chabang port facilitates distribution to Cambodia and Vietnam markets where Buddhist-majority populations favor dairy-avoidance formulations.
Thailand Snack Bar Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification and channel access dimensions, with three-tier competitive separation visible in Thailand's snack bar market. Consolidation pressure concentrates among multinational FMCG portfolios with established modern trade slotting fee capacity, while domestic specialists defend position through regulatory affairs speed and flavor localization. Two strategic archetypes dominate: global diversified nutrition conglomerates leveraging distribution depth, and regional specialists exploiting Ministry of Public Health reformulation incentives. Competitive moves center on exclusive flavor development partnerships with convenience store chains and cold-forming equipment upgrades at Rayong and Pathum Thani production facilities.
Among global diversified players, Mondelez International, Inc., Nestlé S.A., and Kellogg Company exemplify the scale-driven archetype with Bangkok-based sensory labs and modern trade penetration. These entities represent the premium-tier positioning that commands exclusive Thai tea, durian, and tom yum flavor specifications from CP All and Lawson Thailand. Domestic specialists including Anna Thai Snack All occupy positions within the regulatory-responsive tier, where Thailand FDA compliance capabilities and local distributor relationships provide defensive moats against import-reliant competitors.
| Leading Market Players |
|---|
| Mondelez International, Inc. |
| Kellogg Company |
| Nestlé S.A. |
| Hershey Company |
| The Quaker Oats Company |
| Mars, Incorporated |
| PepsiCo, Inc. |
| Anna Thai Snack All |
| General Mills Inc. |
| Others |
Value Network & Pricing Analysis
Thailand's Ministry of Public Health sugar reduction mandates gate qualified supply access and premium-tier pricing power, forcing manufacturers to reformulate around disclosed thresholds or accept degraded shelf positioning in CP All and Lawson Thailand networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified organic and high-protein formulations from conventional granola bars. Price differentiation hinges on Thailand FDA compliance speed and exclusive flavor development partnerships with convenience store chains. Cost compression in economy-tier granola bars is intensifying because palm oil price volatility feeds directly into binding agent expenses. Students and price-sensitive families in provincial markets exhibit highest price sensitivity, while health enthusiasts in Bangkok's boutique fitness studios absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Direct-to-retail channels through CP All and Lawson Thailand handle hyperscale demand from Greater Bangkok convenience stores, while e-commerce subscription models bypass traditional trade gatekeepers entirely. Raw material sourcing draws from New Zealand and US suppliers for whey protein concentrate, northern Thailand contract farming networks for organic grain inputs, and Malaysian palm oil processors for binding fats. Single-source vulnerability concentrates in imported dairy protein supply, exposing margins to currency volatility and shipping cost spikes. Distribution runs through modern trade slotting fee structures that erode profitability for sub-scale regional brands competing against multinational FMCG portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's snack bar market compounds steadily as urban fitness culture in Bangkok and Chiang Mai institutionalizes protein bar consumption into daily nutrition routines.
For Market Incumbents: Anchor defensive positioning through backward integration into pea protein isolate production and cold-forming equipment upgrades at Rayong facilities. Accelerate Thailand FDA registration capabilities to outpace import-reliant competitors facing reformulation delays. Prioritize exclusive flavor development partnerships with CP All and Lawson Thailand to lock in premium shelf positioning against emerging plant-based entrants. For New Entrants and Emerging Players: Provincial distributors in Chiang Rai and Udon Thani present first-mover expansion potential through local wholesale relationships underserved by Bangkok-centric supply chains. Target health food store boutiques in Ari and Thonglor districts with vegan-certified formulations that bypass multinational slotting fee barriers. Deploy Shopee and Lazada subscription bundles to capture fitness micro-segments in Phuket with direct consumer relationships. For Investors and Strategic Acquirers: Roll-up economics work for domestic specialists with established Thailand FDA compliance capabilities because regulatory affairs speed creates acquisition premiums against import-dependent competitors. Target mid-tier manufacturers with in-house analytical laboratories and northern Thailand organic sourcing contracts. Monitor Ministry of Public Health enforcement patterns around sugar disclosure thresholds as inflection indicators for portfolio refresh cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Pea Protein Isolate Sourcing | Absorbs margin pressure from imported whey tariffs while opening Buddhist-majority export pathways. |
| Cold-Forming Equipment Upgrade | Rayong and Pathum Thani facilities enable cleaner-label binding without synthetic stabilizers. |
| Exclusive Flavor Development | Thai tea, durian, and tom yum specifications from CP All reverse manufacturer-led innovation cycles. |
| E-Commerce Subscription Launch | Shopee and Lazada recurring bundles bypass slotting fees to capture fitness micro-segments. |
| Halal Certification Investment | Central Islamic Council of Thailand approval unlocks Middle East export market access. |
Research Methodology
Bottom-up convenience store and gym channel modeling reconciled against top-down extrusion capacity tracking forms the analytical core. Primary interviews with Thailand-based food technologists, CP All category buyers, boutique fitness studio owners, and Ministry of Public Health regulatory officers combined with secondary validation from Thailand FDA prepackaged food registration databases, customs import records for whey protein concentrate, Nielsen retail audit data, and Ministry of Agriculture organic certification registries.
Input-output matrices map protein bar, granola bar, fruit bar, and nut bar production volumes against ingredient sourcing patterns and channel throughput across the analysis window. Segmentation dimensions include product type, ingredient certification tier, sales channel, and consumer demographic application occasion. CAGRs derive from installed capacity expansion trajectories at Rayong and Pathum Thani facilities cross-referenced with urban fitness culture penetration rates in Bangkok and Chiang Mai.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Thailand FDA enforcement escalation, palm oil price volatility, and provincial distributor digital integration timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Europe Cereal Bar Market
Snacks
Middle East and Africa Frozen Snacks Market
Snacks
Spain Snack Bar Market
Snacks
North America Potato Chips Market
Snacks
Qatar Potato Chips Market
Snacks
Low Calorie Cookies Market
Snacks
Super Low Calorie Snacks Market
Snacks
Europe Snack Bar Market
Snacks
Baked Savoury Snacks Market
Snacks
Low Calorie Crackers Market
Snacks
Italy Snack Bar Market
Snacks
Brazil Snack Bar Market
Snacks
Savory Snacks Market
Snacks
Fried Potato Chips Market
Snacks
Germany Energy Bar Market
Snacks
Europe Snacks Food Market