
 United Kingdom Electric Vehicle Battery Materials Market | 2026-2036
United Kingdom Electric Vehicle Battery Materials Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Electric Vehicle Battery Materials Market Insights
The UK zero-emission vehicle mandate is consolidating demand for locally processed battery materials among domestic automakers. Envision AESC UK Ltd anchors cell production through its Sunderland gigafactory operations. Johnson Matthey sustains cathode active material development from its Oxfordshire R&D base. Nyobolt Ltd differentiates through ultra-fast charging anode technologies targeting premium electric vehicle platforms.
United Kingdom electric vehicle battery materials encompass refined active materials, electrolytes, separators, and current collectors engineered to specific energy density, cycle life, and thermal stability parameters for lithium-ion and emerging solid-state cell architectures. These materials determine pack performance, safety thresholds, and recyclability profiles for passenger and commercial vehicle electrification. Lithium-ion formulations dominate current procurement volumes, while solid-state material categories represent the fastest-growing technology segment as OEMs target higher energy density thresholds. Advanced battery manufacturing processes command concentrated margin pools, whereas conventional battery material supply lines face pricing pressure from commoditized graphite and nickel-cobalt intermediates.
The UK Department for Transport, the Environment Agency, and BSI standards frameworks govern material sourcing disclosures, carbon intensity benchmarking, and end-of-life recycling obligations for battery supply chains entering domestic vehicle production. These regulatory layers compel material suppliers to demonstrate provenance transparency and closed-loop recovery capabilities as conditions for qualifying contracts. Stakeholders must track how evolving extended producer responsibility rules and critical mineral security partnerships reshape acceptable feedstock origins and processing locations.
Market Dynamics
The UK zero-emission vehicle mandate is compressing timelines for domestic cathode and anode material qualification. Battery Industrialisation Centre investments in Coventry and Sunderland gigafactory corridors are concentrating supplier development around Midlands and North East clusters.
Growth Catalysts
- Zero-Emission Vehicle Mandate:The UK Department for Transport requires automakers to escalate zero-emission sales percentages annually. This regulatory floor guarantees offtake volume for qualified domestic material processors.
- Midlands Battery Cluster:Concentrated R&D infrastructure around Coventry and Birmingham draws cathode active material developers seeking proximity to cell prototyping facilities. Geographic density accelerates iteration cycles between material suppliers and cell manufacturers.
- Solid-State Material Pipelines:Emerging sulfide-based electrolyte formulations promise energy density thresholds beyond conventional lithium-ion. UK-based anode specialists are positioning sulfide-compatible silicon architectures for next-generation cell qualification.
Market Restraints
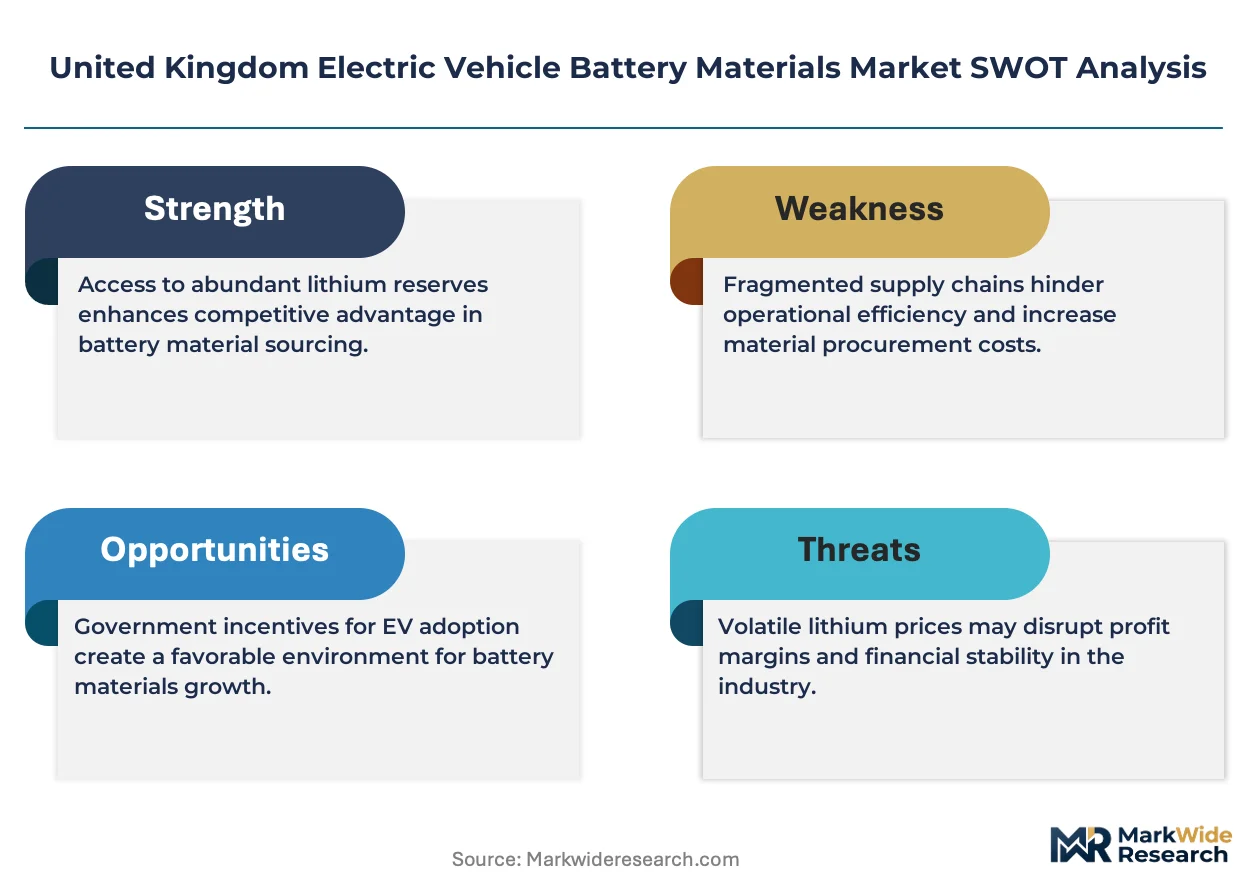
- Graphite Supply Concentration:Spherical purified graphite for anode production concentrates in Chinese processing facilities. UK battery makers face feedstock vulnerability from single-source geography dependency.
- Nickel-Cobalt Price Volatility:Cathode precursor costs fluctuate with London Metal Exchange pricing and Indonesian nickel export policies. Margin compression hits NMC chemistry suppliers disproportionately.
- Extended Producer Responsibility Friction:UK Environment Agency recycling quotas require provenance documentation many non-EU suppliers cannot furnish. Compliance gaps disqualify otherwise competitive feedstock bids.
Strategic Opportunities
- Scottish Critical Mineral Refining:Underdeveloped hydrometallurgical capacity in Scotland offers greenfield sites for lithium hydroxide and nickel sulfate processing. Proximity to European offtake contracts reduces logistics exposure.
- Solid-State Electrolyte Convergence:Oxide and sulfide electrolyte technologies are merging with silicon-dominant anode architectures. UK material houses can capture interface engineering value at this convergence point.
- Direct Recycling Pathways:UK Battery Industrialisation Centre funding streams prioritize closed-loop recovery technologies. Black mass-to-precursor refining represents uncaptured margin pool versus pyrometallurgical export.
Industry Challenges
- Electrochemical Engineer Scarcity:UK universities produce insufficient talent versed in solid-electrolyte interphase optimization and cell-scale thermal modeling. Recruitment competition from European gigafactory projects intensifies salary inflation.
- BSI Certification Timelines:Material qualification under UK-specific battery safety standards requires 18-24 month validation cycles. Product-market mismatch risk rises for technologies with compressed development windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Electric Vehicle Battery Materials Market |
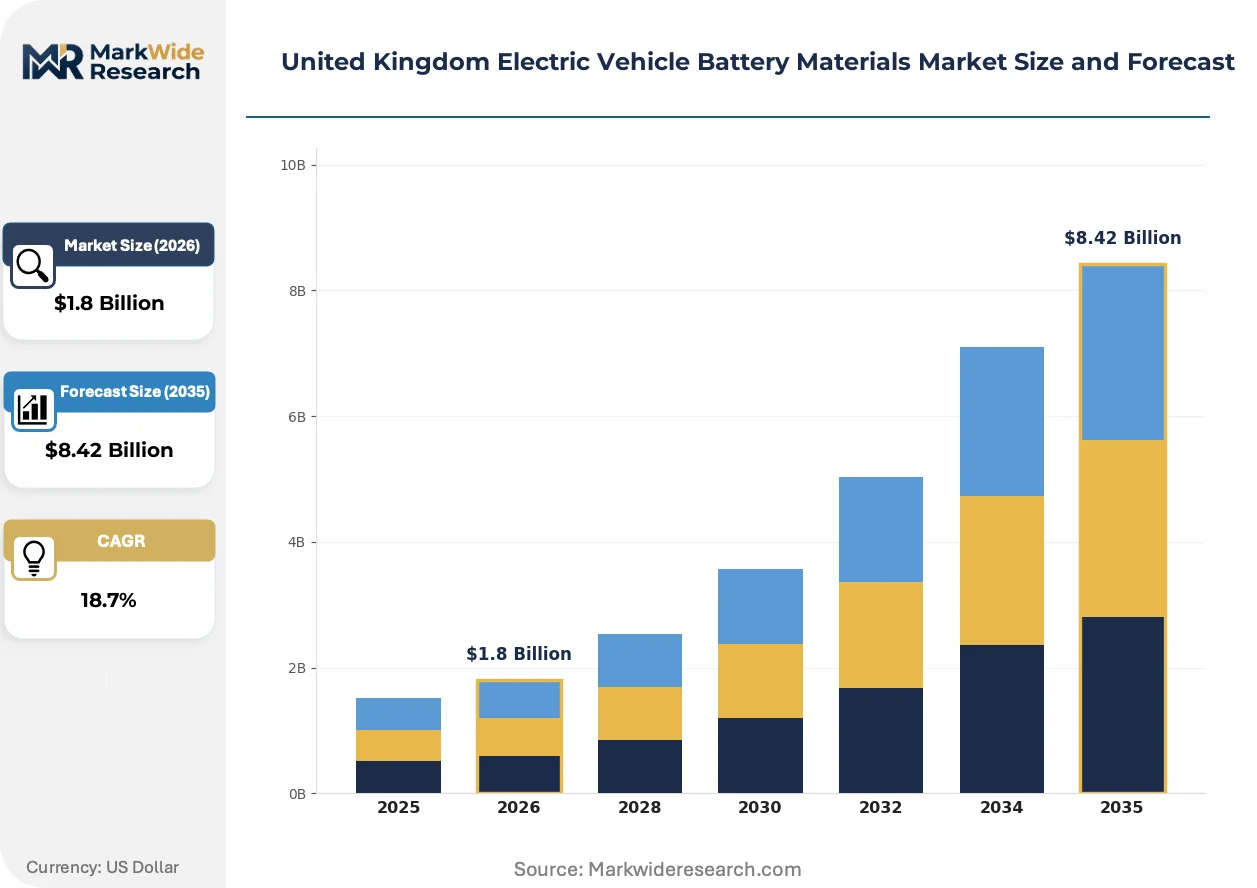
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Lithium-ion, Nickel-cobalt, Graphite, Solid-state End User: OEMs, Aftermarket Providers, Fleet Operators, Battery Manufacturers Technology: Conventional Batteries, Advanced Batteries, Fast Charging Systems, Recycling Technologies Application: Passenger Vehicles, Commercial Vehicles, Two-wheelers, Energy Storage Systems |
| Companies Covered | Envision AESC UK Ltd, Agratas Energy Storage Solutions, Nissan Motor Manufacturing (UK) Ltd, AMTE Power plc, Nyobolt Ltd, Tesla Inc., BMW, Johnson Matthey, Glencore, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Electric Vehicle Battery Materials Market Trends and Innovations
Silicon-dominant anode architectures are displacing conventional graphite formulations across UK premium electric vehicle platforms. Regulatory carbon intensity benchmarking and supply chain transparency mandates are reshaping material sourcing protocols.
Silicon-carbon composite anodes are integrating into high-energy cell designs targeting 300 Wh/kg pack-level densities. Jaguar Land Rover and premium OEM engineering teams are accelerating qualification timelines for silicon loadings above 10% by weight. This material transition is compressing graphite anode market share in segments where charge rate and range dominate purchasing decisions.
UK Battery Regulations 2023 impose mandatory carbon footprint declarations and recycled content thresholds for cells entering domestic vehicle production. The Environment Agency enforcement framework requires quarterly supply chain disclosure submissions from material processors. Cathode active material suppliers with EU-established recycling partnerships are adapting documentation systems to satisfy parallel UK compliance architecture.
Fleet operators and leasing companies are consolidating material procurement through long-term offtake agreements with cell manufacturers. Direct contracting between Royal Mail, Amazon Logistics UK, and gigafactory operators bypasses traditional tiered supplier relationships. This channel compression is most visible in commercial vehicle electrification, where total cost of ownership transparency favors volume-commitment pricing over spot market flexibility.
United Kingdom Electric Vehicle Battery Materials Market Segmentation
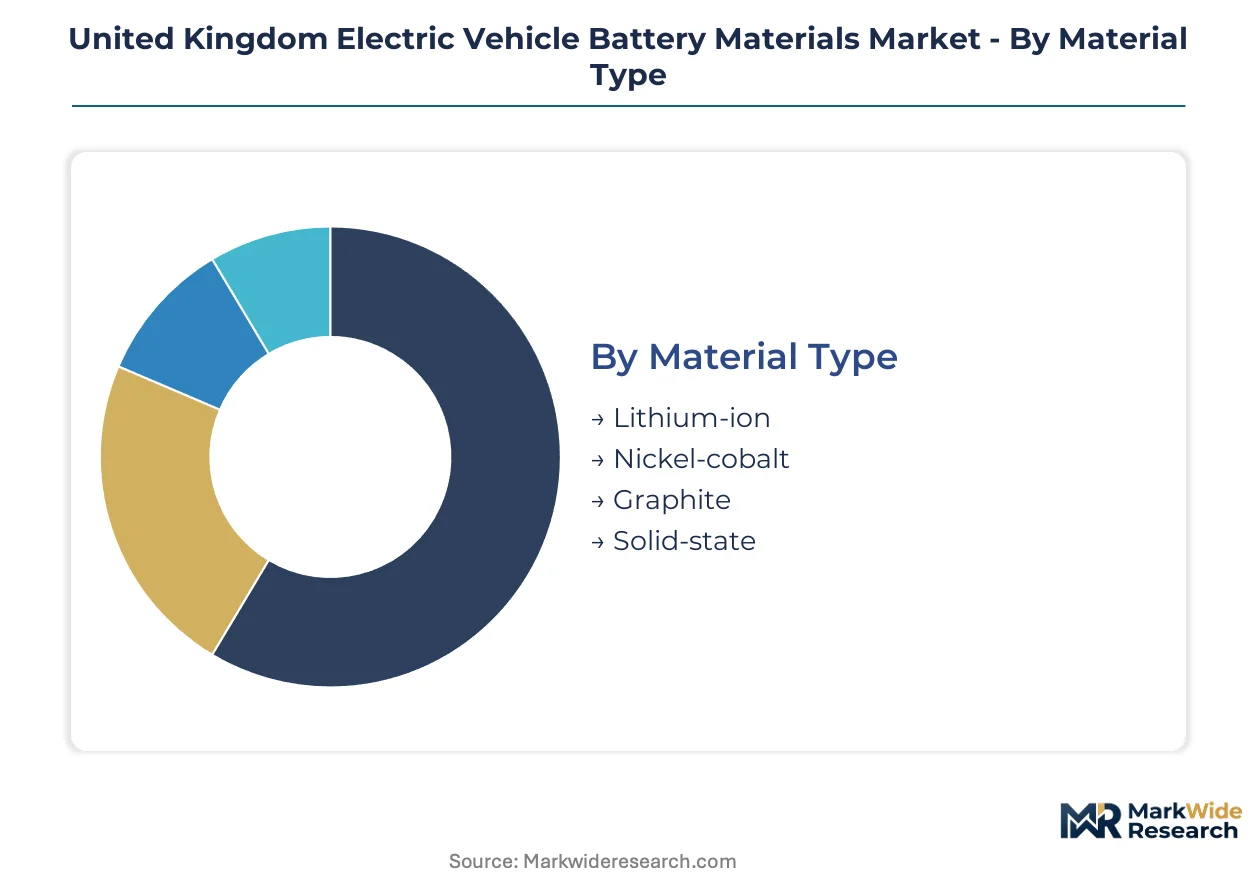
Segmentation of the United Kingdom electric vehicle battery materials market reveals how procurement priorities diverge across cell chemistry, customer type, and application requirements. Understanding these divisions exposes where margin pools concentrate and which technology transitions will reshape supplier competitive positions.
Material Type:
Buyers in this category separate by energy density requirements versus cost sensitivity and supply security tolerance.
- Lithium-ion:Mature cathode-anode pairings with standardized NMC and LFP formulations dominate current UK gigafactory offtake. Midlands battery cluster procurement favors these chemistries for their established qualification pathways and immediate production scalability.
- Solid-state:Sulfide and oxide electrolyte architectures promise energy densities exceeding conventional lithium-ion thresholds. North East R&D corridors are concentrating development spend here as Jaguar Land Rover and premium OEMs target next-generation pack performance.
- Nickel-cobalt:Cathode precursor supply chains face London Metal Exchange price volatility and Indonesian export policy exposure.
- Graphite:Spherical purified anode material concentrates in Chinese processing facilities, creating single-source geography vulnerability for UK cell makers.
Lithium-ion leads volumes today; solid-state is gaining share fastest.
End User:
Procurement scale and contract structure differentiate buyers, from multi-gigawatt annual offtake to fragmented replacement demand.
- OEMs:Automotive manufacturers like Jaguar Land Rover and commercial vehicle builders negotiate direct cathode active material supply agreements. Their zero-emission mandate compliance timelines compress supplier qualification cycles to 18-24 months under BSI standards.
- Battery Manufacturers:Cell producers including Envision AESC UK Ltd anchor material demand through Sunderland gigafactory operations. Their procurement concentrates around Midlands and North East corridors for logistics efficiency.
- Fleet Operators:Royal Mail and Amazon Logistics UK are consolidating material exposure through direct cell manufacturer offtake agreements, bypassing traditional tiered supply relationships.
- Aftermarket Providers:Replacement cell and module suppliers serve secondary vehicle markets and energy storage retrofits with smaller batch requirements.
OEMs lead volumes today; fleet operators are gaining share fastest.
Technology:
Margin capture potential separates segments, from commoditized conventional production to interface-engineered advanced architectures.
- Advanced Batteries:Silicon-dominant anode architectures and high-nickel cathode formulations target 300 Wh/kg pack-level densities. Nyobolt Ltd and Oxfordshire R&D bases are accelerating qualification for loadings above 10% silicon by weight.
- Fast Charging Systems:Ultra-fast charging anode technologies reduce lithium plating risks and thermal runaway thresholds. Premium electric vehicle platforms are prioritizing these materials where charge rate dominates purchasing decisions.
- Conventional Batteries:Standard graphite-NMC cell production faces pricing pressure from commoditized material supply lines and thin margin pools.
- Recycling Technologies:Black mass-to-precursor refining and hydrometallurgical recovery are capturing UK Battery Industrialisation Centre funding for closed-loop material recovery.
Conventional batteries lead volumes today; advanced batteries are expanding most quickly.
Application:
Total cost of ownership transparency and range requirements shape material specification intensity across vehicle categories.
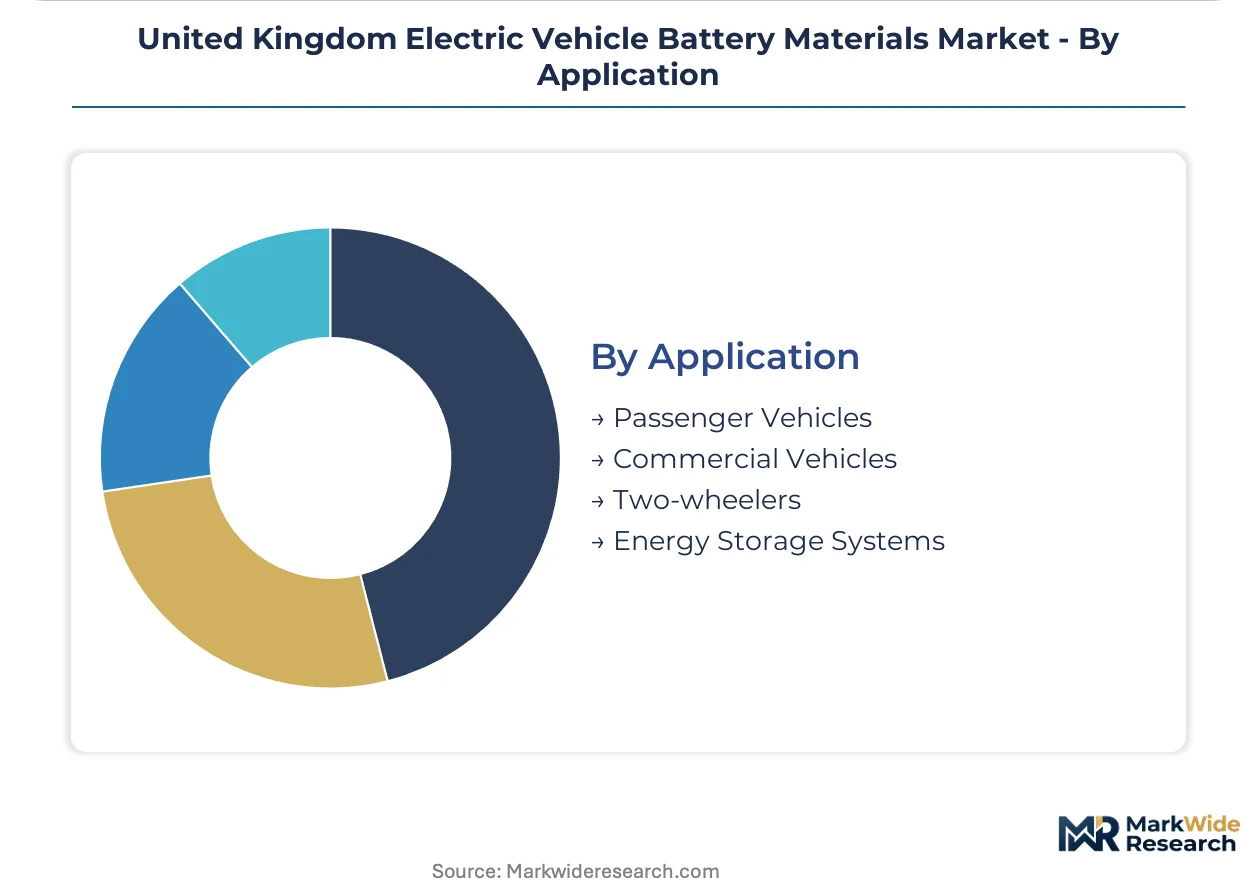
- Passenger Vehicles:Premium and mass-market electric cars drive cathode active material demand for energy density optimization. UK zero-emission vehicle mandate compliance concentrates procurement volume here.
- Commercial Vehicles:Van and truck electrification favors LFP chemistries for cycle life and thermal stability under heavy-duty duty cycles. Fleet operators are consolidating material procurement through volume-commitment pricing structures.
- Energy Storage Systems:Stationary battery installations prioritize cost-per-kWh over energy density, drawing different material specifications than mobility applications.
- Two-wheelers:Electric motorcycles and scooters represent emerging demand with localized battery pack assembly requirements.
Passenger vehicles lead volumes today; commercial vehicles are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Battery material processing in the United Kingdom traces its industrial lineage to nineteenth-century electrochemical manufacturing in the Midlands, where Johnson Matthey established precious metal refining operations that later pivoted toward catalyst and battery precursor chemistry.
Midlands
Coventry and Birmingham anchor the UK's primary battery material R&D corridor. The Battery Industrialisation Centre draws cathode active material developers seeking proximity to cell prototyping facilities. BSI standards frameworks govern material qualification timelines here, compressing supplier development cycles to 18-24 months.
North East
Sunderland's gigafactory corridor concentrates demand for anode and cathode materials through Envision AESC UK Ltd operations. The UK Department for Transport zero-emission vehicle mandate guarantees offtake volume for qualified processors locating near cell production. Newcastle University materials science programs feed specialized electrochemical engineering talent into regional suppliers.
Scotland
Underdeveloped hydrometallurgical capacity around Grangemouth and the Central Belt offers greenfield sites for lithium hydroxide refining. The Scottish Government's energy transition funding prioritizes critical mineral processing infrastructure. Proximity to European offtake contracts reduces logistics exposure for operators establishing precursor production.
South East
Oxfordshire hosts Johnson Matthey's cathode active material development base and Nyobolt Ltd's ultra-fast charging anode research. The concentration of premium OEM engineering teams around Milton Keynes and Oxford accelerates qualification timelines for silicon-dominant architectures. UK Environment Agency recycling quotas shape supplier documentation requirements for materials entering domestic vehicle production.
Wales
Deeside and South Wales valleys retain chemical processing infrastructure from historical industrial operations, now repurposed for battery material pilot lines. Welsh Government advanced manufacturing grants support sulfide electrolyte development for solid-state cell architectures. The region's port infrastructure offers Atlantic-facing logistics alternatives to English Channel congestion.
United Kingdom Electric Vehicle Battery Materials Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology sophistication, with interface-engineered material specialists commanding valuation multiples unavailable to conventional graphite and nickel-cobalt intermediates. The UK market structures around three tiers: gigafactory-anchored cell producers, R&D-intensive material developers, and diversified chemical conglomerates with battery verticals. Strategic moves concentrate on geographic co-location with Midlands and North East clusters, plus qualification acceleration under compressed BSI certification timelines.
Within the R&D-intensive tier, Nyobolt Ltd and Johnson Matthey exemplify archetypes differentiated by anode specialization versus cathode breadth. Envision AESC UK Ltd anchors the cell-producer tier through Sunderland manufacturing scale. Agratas Energy Storage Solutions occupies a position bridging material development and downstream integration. These three represent distinct competitive postures: ultra-fast charging technology focus, established precious metal chemistry lineage, and Asian-backed gigafactory operational capability.
| Leading Market Players |
|---|
| Envision AESC UK Ltd |
| Agratas Energy Storage Solutions |
| Nissan Motor Manufacturing (UK) Ltd |
| AMTE Power plc |
| Nyobolt Ltd |
| Tesla Inc. |
| BMW |
| Johnson Matthey |
| Glencore |
| Others |
Pricing and Supply Chain Analysis
Captive sourcing of cathode active materials through Midlands-based processing facilities anchors both supply security and pricing power for UK cell manufacturers qualifying under BSI standards. This integration choice insulates qualified suppliers from London Metal Exchange volatility while exposing non-integrated competitors to margin compression from Indonesian nickel export policy shifts.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between gigafactory operators and qualified material processors, with price differentiation hinging on carbon intensity certification grades and volume scale commitments. Pricing pressure stems from Chinese spherical graphite processing concentration, which forces UK anode buyers to absorb logistics premiums or accept single-source vulnerability. Fleet operators consolidating through direct cell manufacturer contracts exhibit highest price sensitivity, whereas premium OEMs prioritizing silicon-dominant anode performance tolerate elevated material costs for range and charge rate advantages.
Supply Chain Analysis
Dual-sourcing requirements from the UK Environment Agency and Battery Industrialisation Centre procurement standards compel cell manufacturers to qualify multiple cathode precursor suppliers despite geographic concentration. Raw material dependencies center on Indonesian nickel sulfate, Chilean lithium hydroxide, and Chinese spherical purified graphite, creating tariff exposure from evolving critical mineral security partnerships. Distribution runs through Midlands and North East corridor consolidation, with qualified material processors co-locating near Envision AESC UK Ltd and emerging gigafactory sites to compress logistics costs and BSI certification timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scottish greenfield hydrometallurgical capacity offers cost arbitrage against Midlands-established processing, with lower land and energy costs offsetting European logistics exposure for lithium hydroxide and nickel sulfate refining.
For Market Incumbents: Deepen backward integration into black mass-to-precursor recycling pathways to capture UK Battery Industrialisation Centre funding streams and insulate against Chinese graphite supply concentration. Lock in extended producer responsibility compliance documentation systems ahead of tightening Environment Agency provenance requirements, as qualification gaps now disqualify otherwise competitive feedstock bids from non-EU suppliers. For New Entrants and Emerging Players: The premium-to-economy tier price-point gap in solid-state electrolyte materials offers entry traction for sulfide-compatible silicon anode specialists targeting Jaguar Land Rover qualification pipelines. Scottish critical mineral refining infrastructure remains underpenetrated by cathode active material developers, presenting greenfield co-location opportunities near Grangemouth with proximity to European offtake contracts. For Investors and Strategic Acquirers: Roll-up economics work for R&D-intensive material houses because BSI certification timelines compress acquisition premiums for qualified suppliers versus greenfield development costs. Target interface-engineering specialists bridging silicon anode and sulfide electrolyte convergence, with inflection signaled by OEM platform engineering team expansion at Oxfordshire and North East R&D corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycling | Captures UK Battery Industrialisation Centre funding for closed-loop black mass refining. |
| Scottish Greenfield Refining | Exploits underdeveloped hydrometallurgical capacity near European offtake contracts. |
| Solid-State Electrolyte Convergence | Positions material houses at silicon anode-sulfide electrolyte interface engineering value. |
| Dual-Sourcing Qualification | Satisfies Environment Agency procurement standards and insures against single-source risk. |
| Carbon Intensity Certification | Meets UK Battery Regulations 2023 mandatory declarations for domestic vehicle production. |
Research Methodology
Coverage spans UK Midlands, North East, Scotland, South East, and Wales regional clusters, with primary inputs from each corridor's material processors and cell manufacturers. The analysis combines primary interviews with cathode active material R&D directors, gigafactory procurement leads, Battery Industrialisation Centre program managers, and Environment Agency compliance officers with secondary validation from UK Department for Transport policy filings, BSI standards documentation, and London Metal Exchange pricing archives. Bottom-up cell chemistry demand modeling triangulates against top-down automotive production forecasts.
Rate-of-change decomposition separates volume growth from value capture across material type, end user, technology tier, and application segments throughout the forecast period. The analytical framework models passenger vehicle, commercial vehicle, energy storage, and two-wheeler application splits alongside lithium-ion, solid-state, and emerging chemistry transitions. CAGRs derive from segment-level elasticity analysis against zero-emission vehicle mandate compliance trajectories and gigafactory capacity buildout schedules.
Caveats apply where Indonesian nickel export policy shifts or Chinese graphite processing restrictions could materially shift the outlook. Forecasts reflect assumptions regarding BSI certification timeline compression and Scottish infrastructure funding continuity. Deviation in critical mineral security partnership terms would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
France EV Battery Pack Market
EV Batteries
United Kingdom Electric Vehicle Battery Manufacturing Market
EV Batteries
India EV Battery Pack Market
EV Batteries
Electric Vehicle Battery Conditioners Market
EV Batteries
EV Battery Heating System Market
EV Batteries
China Electric Vehicle Battery Market
EV Batteries
North America Electric Vehicle VRLA Batteries Market
EV Batteries
United States Electric Vehicle Battery Manufacturing Market
EV Batteries
South America Electric Vehicle Battery Anode Market
EV Batteries
Europe Electric Vehicle VRLA Batteries Market
EV Batteries
Japan EV Battery Pack Market
EV Batteries
China Electric Vehicle Battery Materials Market
EV Batteries
UK EV Battery Pack Market
EV Batteries
Europe Electric Bus Battery Pack Market
EV Batteries
Asia-Pacific EV Battery Pack Market
EV Batteries
Canada EV Battery Pack Market