
 Curved Lipo Battery Market | 2026-2036
Curved Lipo Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Curved Lipo Battery Market Insights
Market Context
Silicon-dominant anodes is consolidating around pouch architectures that tolerate mechanical bending without capacity fade. Samsung SDI leverages its display-battery integration expertise to anchor premium wearable supply chains in East Asia. LG Energy Solution specializes in multi-layer stacking processes that reduce internal stress during repeated flex cycling. CATL competes on manufacturing scale, extending cylindrical expertise into curved pouch formats for emerging mobility applications.
Technical Definition and Segment Structure
A curved lipo battery is a lithium-ion polymer cell manufactured with a non-planar geometry, typically employing gel electrolyte suspended in a laminated aluminum-polymer pouch that permits bending radii between 15mm and 40mm while maintaining nominal voltage delivery between 3.7V and 4.35V per cell. The 4S and 6S product types dominate current revenue as drone and RC vehicle OEMs specify higher series configurations for voltage-hungry brushless motors. Portable Electronics application demand is accelerating fastest among the four tracked categories, driven by foldable smartphone and AR headset programs that require batteries conforming to ergonomic housings. The 5000mAh capacity tier captures disproportionate margin attention from electric bike assemblers seeking range extension without frame redesign.
Regulatory Frame and Outlook
China's NMPA and SAMR enforce GB 31241 standards that now incorporate flex-fatigue testing protocols for non-rigid cell geometries, while South Korea's MFDS mandates thermal runaway containment documentation for curved configurations in medical wearables. The EU's REACH and RoHS frameworks restrict cobalt sourcing and phthalate content in polymer electrolyte binders, forcing reformulation investments across Asian cell suppliers. Stakeholders must monitor how solid-state electrolyte patents intersect with existing curved-manufacturing equipment before committing to next-generation capacity.
Market Dynamics
GB 31241 flex-fatigue testing mandates from China's SAMR are forcing cell suppliers to redesign lamination protocols, while Seoul-Suwon manufacturing concentration creates procurement bottlenecks for wearable OEMs seeking curved form factors.
Growth Catalysts
- Foldable smartphone programs:AR headset and foldable phone manufacturers specify non-planar cells that conform to ergonomic housings, pulling capacity from traditional planar suppliers.
- REACH cobalt restrictions:EU RoHS and REACH frameworks on cobalt sourcing accelerate investment in nickel-manganese-alternative cathode chemistries compatible with curved geometries.
- Drone motor voltage requirements:Brushless motor specifications in RC vehicles and commercial drones drive 4S and 6S series configuration demand.
Market Restraints
- Aluminum-polymer laminate supply:Pouch substrate availability concentrates among Japanese and Korean metallizers, exposing assemblers to input cost volatility.
- Flex-cycle degradation physics:Gel electrolyte migration during repeated 15-40mm radius bending creates capacity fade mechanisms that planar cells avoid.
- MFDS thermal documentation:South Korea's medical wearable certification requires extended runaway containment testing that extends qualification timelines.
Strategic Opportunities
- Electric bike frame integration:5000mAh curved cells enable range extension without structural redesign, opening two-wheeler OEM procurement channels.
- India PLI scheme localization:India's production-linked incentive scheme for advanced cell chemistry invites curved-format manufacturing investment for domestic wearable assembly.
- Solid-state electrolyte convergence:Ceramic-polymer hybrid electrolytes promise enhanced mechanical tolerance, potentially eliminating flex-fatigue failure modes.
Industry Challenges
- Multi-layer stacking expertise:Cell assemblers face acute shortages of process engineers capable of managing stress-reduction lamination at volume.
- GB standard recertification:China's revised flex-testing protocols force existing product lines through costly requalification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Curved Lipo Battery Market |
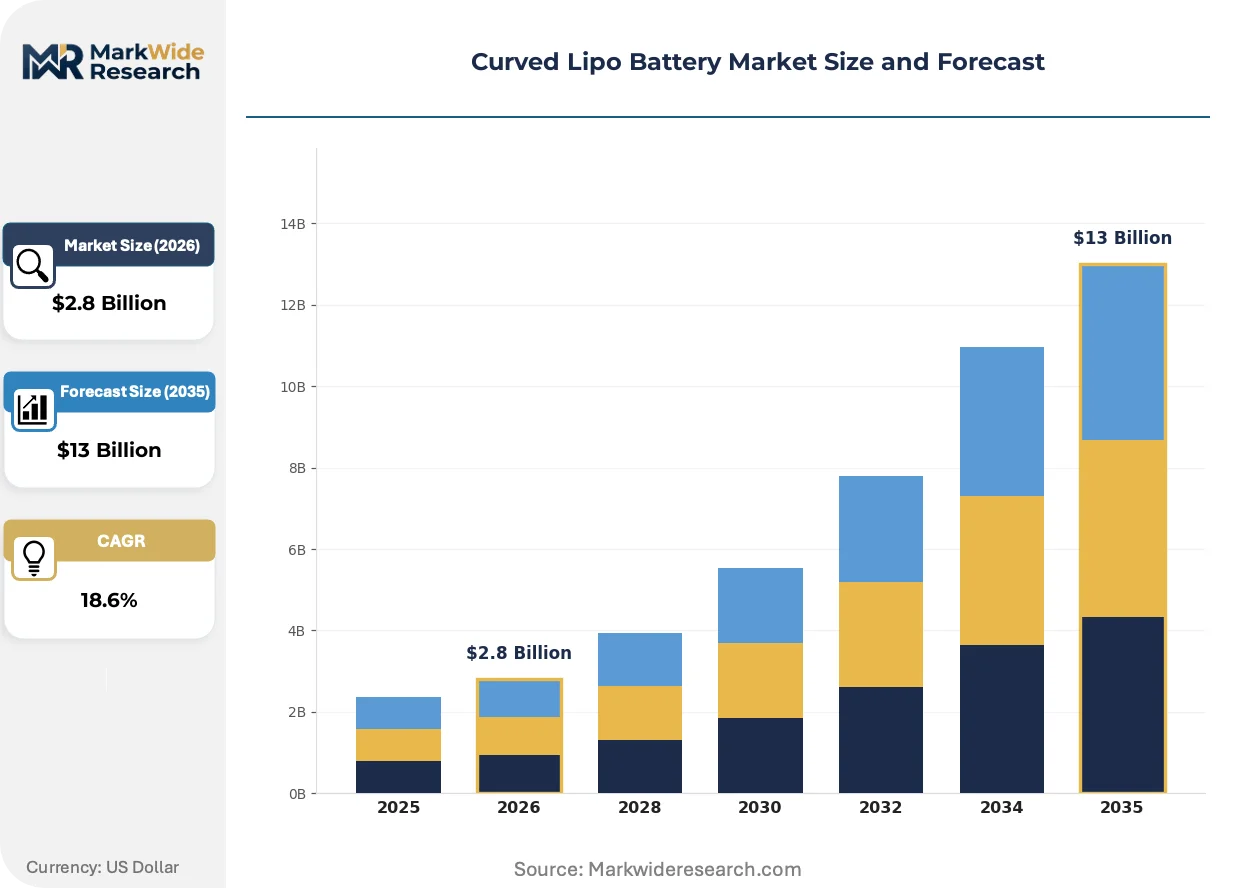
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3S, 4S, 6S, 10S Application: Drones, RC Vehicles, Electric Bikes, Portable Electronics Capacity: 1000mAh, 2000mAh, 3000mAh, 5000mAh End User: Aerospace, Hobbyists, Electric Vehicle Manufacturers, Consumers |
| Companies Covered | CATL, EVE Energy, Samsung SDI, Lishen Battery, SK On, LG Energy Solution, BYD, ProLogium, Panasonic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Curved Lipo Battery Market Trends and Innovations
Silicon-dominant anode chemistries and solid-state electrolyte research are compressing traditional manufacturing assumptions, while procurement patterns shift toward display-battery integration partnerships.
Silicon-dominant anode architectures tolerate mechanical bending without the graphite particle fracture that causes planar cell degradation. Wearable device manufacturers specify silicon-anode curved cells for premium product tiers. This chemistry is decentralizing capacity planning away from cylindrical specialists toward pouch-cell assemblers with lamination expertise.
China's NMPA enforcement of GB 31241 flex-fatigue protocols creates compliance differentiation between qualified and unqualified suppliers. Cell manufacturers must document 500-cycle bend testing with less than 20% capacity degradation. Medical wearable producers in South Korea face the tightest certification timelines as MFDS cross-references Chinese test standards.
Display-battery integration contracts now dominate premium wearable procurement, with OEMs specifying combined module sourcing rather than discrete cell purchasing. Traditional battery distributors lose share to display panel suppliers offering bonded curved cell assemblies. This consolidation is most advanced in Seoul-Suwon manufacturing corridors where Samsung SDI and LG Display co-locate production.
Curved Lipo Battery Market Segmentation
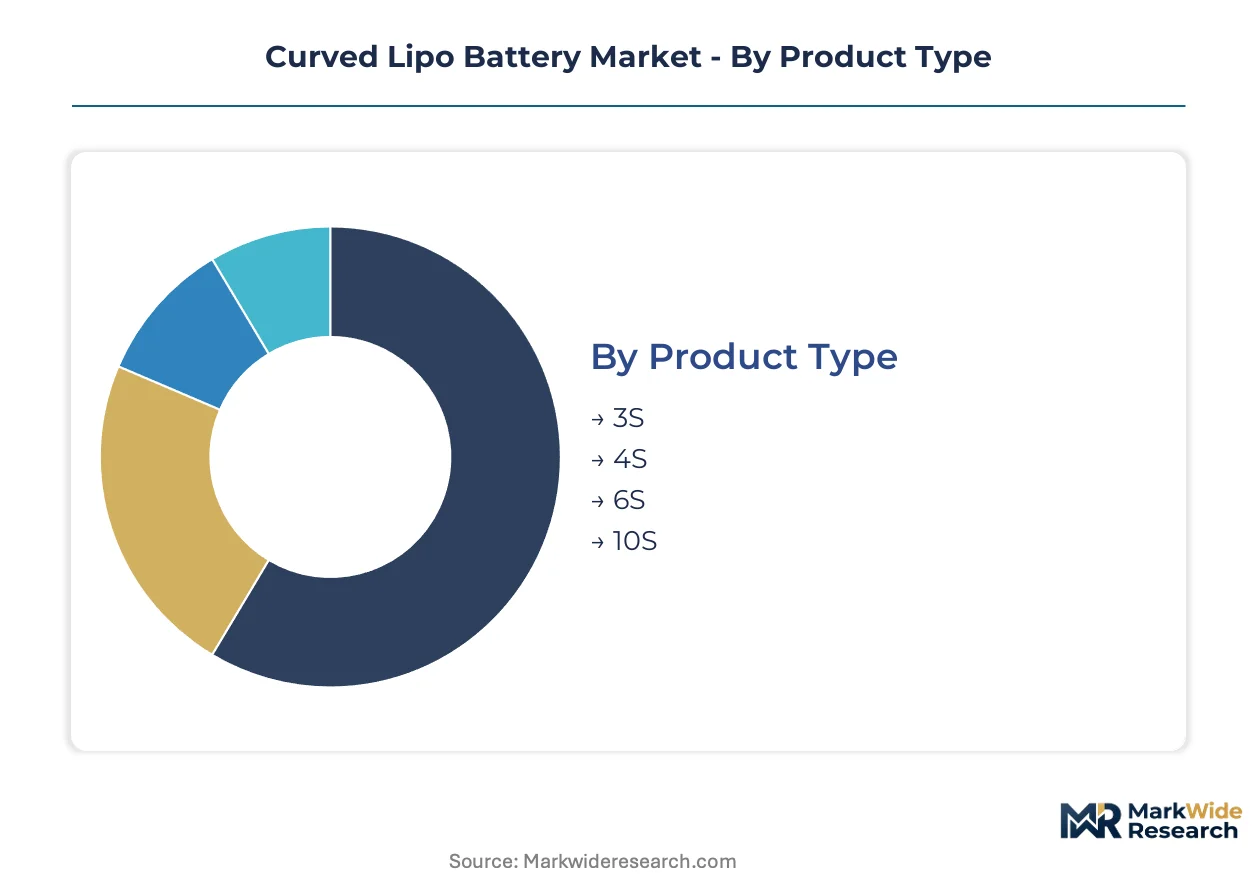
Curved lipo battery procurement follows distinct technical specifications across voltage, capacity, and end-use requirements. Manufacturers configure production lines around specific series configurations and application tolerances rather than commoditized output.
Product Type:
Upgrade cycles in brushless motor systems drive replacement demand toward higher series configurations as power density requirements intensify.
- 4S:Four-cell series configuration delivers nominal voltage around 14.8V, matching the sweet spot for commercial drone flight controllers and mid-tier RC powertrains. Demand concentrates in Shenzhen assembly corridors where UAV OEMs specify this voltage tier for payload-optimized platforms.
- 6S:Six-cell architecture pushes nominal voltage to 22.2V, enabling heavier lift capacity for cinematography drones and racing-grade RC vehicles. South Korean brushless motor manufacturers specify 6S packs for premium tier integration.
- 3S:Entry-level series configuration serves hobbyist RC segments with lower voltage tolerance and cost-sensitive procurement patterns.
- 10S:High-voltage tier supports specialized industrial UAV applications requiring extended range without parallel pack complexity.
4S sits at the top of the volume ranking, with 6S climbing the fastest as commercial drone specifications migrate upward.
Application:
Cost tier differentiation separates premium ergonomic integration from commodity power replacement markets.
- Portable Electronics:Foldable smartphones and AR headsets require sub-20mm bending radii with gel electrolyte stability across temperature cycling. Samsung Display and LG Display procurement teams specify curved cells bonded directly to flexible OLED substrates, eliminating discrete battery compartments.
- Drones:Commercial UAV platforms prioritize energy density per gram over cycle longevity, accepting 300-500 cycle lifespans for 30-minute flight endurance. Chinese DJI and Autel supply chains dominate procurement volume.
- Electric Bikes:Frame-integrated curved formats enable downtube battery placement without structural tube redesign, appealing to European OEMs facing ergonomic compliance pressures.
- RC Vehicles:Hobbyist segment tolerates shorter cycle life and wider voltage variance, purchasing through distributor channels rather than direct OEM specification.
Portable Electronics commands premium pricing per watt-hour, with Electric Bikes expanding most quickly as two-wheeler electrification accelerates.
Capacity:
Volume concentration in mid-tier capacities reflects the dominance of consumer drone and portable electronics procurement.
- 5000mAh:High-density tier enables 45-60 minute flight endurance for professional cinematography drones or 80km+ range for compact electric bikes. European e-bike assemblers specify this capacity for frame-integrated curved packs that avoid external battery mounting.
- 3000mAh:Balanced capacity-to-weight ratio serves prosumer drone segments where 25-30 minute flight time meets regulatory visual-line-of-sight constraints. Chinese UAV OEMs standardize on this tier for mid-price platform differentiation.
- 2000mAh:Compact format supports wearable AR glasses and slim foldable phone designs where thickness constraints override endurance requirements.
- 1000mAh:Entry capacity serves micro-drones and disposable electronics with limited cycle life expectations.
3000mAh maintains volume leadership, while 5000mAh gains share fastest as electric bike procurement scales.
End User:
Customer type determines certification burden and margin structure across military-grade, commercial, and consumer procurement channels.
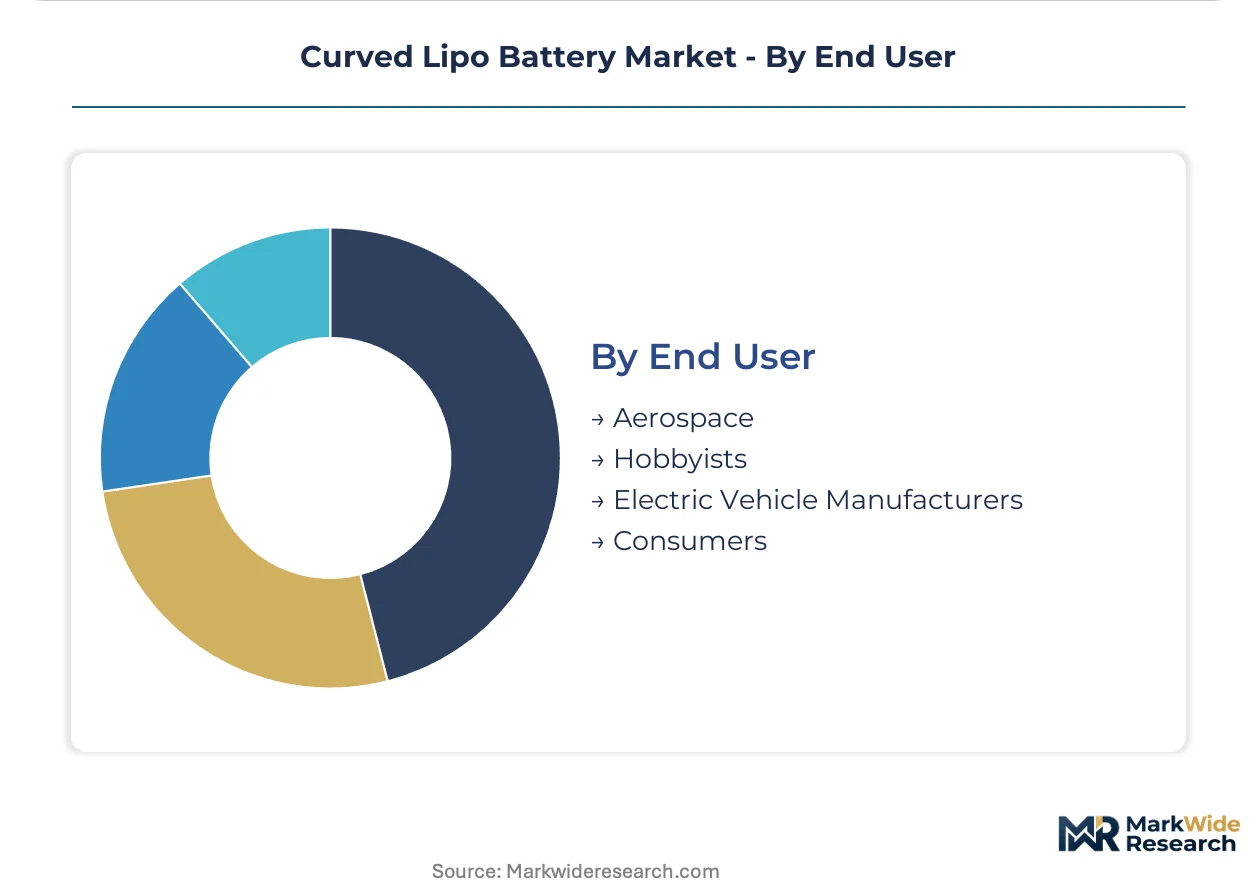
- Consumers:Mass-market wearable and smartphone OEMs specify curved cells through display-battery integration contracts, consolidating procurement around Seoul-Suwon manufacturing corridors. Samsung SDI and LG Energy Solution anchor this channel with bonded module offerings.
- Electric Vehicle Manufacturers:Two-wheeler and micro-mobility assemblers seek frame-conforming geometries that bypass planar battery box constraints. Indian OEMs under PLI scheme localization pressure evaluate curved pouch formats for domestic scooter production.
- Hobbyists:Price-sensitive RC and drone enthusiasts purchase through distributor channels with minimal technical support requirements.
- Aerospace:Specialized UAV and satellite applications require extended thermal cycling documentation and MFDS-equivalent certification for curved geometries.
Consumers represent the largest addressable base, with Electric Vehicle Manufacturers showing the steepest expansion trajectory as micro-mobility formats proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Seoul-Suwon manufacturing corridor anchors global curved lipo battery procurement, with South Korean display-battery integration contracts setting technical specifications for premium wearable supply chains worldwide.
China
Foldable smartphone OEMs in Shenzhen and Dongguan drive demand for sub-20mm bending radius cells. NMPA and SAMR enforce GB 31241 flex-fatigue testing protocols that mandate 500-cycle bend documentation. The Yangtze River Delta cluster around Shanghai concentrates pouch-cell lamination capacity for domestic and export markets.
South Korea
Samsung Display and LG Display procurement teams specify bonded curved cell assemblies for flexible OLED substrates. MFDS mandates thermal runaway containment documentation for medical wearable configurations. The Seoul Capital Area and Suwon form the densest concentration of display-battery integration manufacturing globally.
Japan
Aluminum-polymer laminate metallizers in Osaka and Nagoya supply critical pouch substrates to regional cell assemblers. METI oversees battery safety standards that align with international flex-testing protocols. The Kansai region maintains specialized expertise in stress-reduction lamination processes.
United States
Commercial UAV manufacturers in California and Texas specify 4S and 6S curved packs for cinematography and inspection platforms. FAA drone regulations influence battery certification requirements for flight endurance applications. The Pacific Northwest hosts emerging solid-state electrolyte research programs intersecting with curved manufacturing.
India
Domestic wearable assembly operations in Maharashtra and Karnataka evaluate curved pouch formats under PLI scheme localization pressure. BIS standards for lithium-ion safety are tightening to accommodate non-planar geometries. Tamil Nadu cell manufacturing investments target supply to two-wheeler OEMs seeking frame-integrated battery solutions.
Curved Lipo Battery Market Competitive Landscape
Global majors compete with regional champions across display integration expertise and lamination process specialization. The market structure consolidates around three tiers: scale-driven cylindrical specialists extending into curved formats, pouch-cell assemblers with multi-layer stacking expertise, and display panel suppliers offering bonded module sourcing. Dominant competitive moves include strategic partnerships between cell manufacturers and display OEMs, plus capacity expansion targeting electric bike and micro-mobility procurement channels.
Among East Asian battery conglomerates, CATL, Samsung SDI, and LG Energy Solution occupy positions across different strategic archetypes. CATL represents the scale-driven extension from cylindrical expertise into curved pouch formats. Samsung SDI exemplifies display-battery integration capabilities anchored in Seoul-Suwon manufacturing corridors. LG Energy Solution sits within the multi-layer stacking specialization tier, with process expertise in stress-reduction lamination.
| Leading Market Players |
|---|
| CATL |
| EVE Energy |
| Samsung SDI |
| Lishen Battery |
| SK On |
| LG Energy Solution |
| BYD |
| ProLogium |
| Panasonic |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between GB 31241-qualified and unqualified suppliers manifests in both pricing power and lamination protocol investments. Buyers seeking medical wearable certification in South Korea face extended qualification timelines that compress margins for unprepared assemblers while rewarding pre-qualified incumbents.
Pricing Analysis
Aluminum-polymer laminate pass-through from Japanese and Korean metallizers drives cost volatility at the cell level. Pricing stratifies across medical-grade, consumer electronics, and hobbyist tiers based on flex-cycle documentation depth and thermal runaway testing investment. Cost compression in the 3S hobbyist segment intensifies as Shenzhen distributors compete on spot availability. Drone OEMs in California and Texas show least price sensitivity, prioritizing energy density per gram over unit cost.
Supply Chain Analysis
Freight costs from Osaka and Nagoya metallizers to Seoul-Suwon lamination facilities feed into landed cost calculations for premium tier cells. Supply draws from Japan for pouch substrates, South Korea for display-battery integration, and China for gel electrolyte precursors. Single-source vulnerability concentrates in aluminum-polymer laminate metallization. Distribution runs through bonded module contracts with display OEMs rather than discrete cell channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in curved lipo batteries rests on silicon-anode chemistry cost-down curves and the premium-tier shift toward display-battery integration contracts.
For Market Incumbents: Cement multi-layer stacking expertise through captive process engineering development in Seoul-Suwon corridors. Acquire stress-reduction lamination specialists before solid-state electrolyte patents disrupt existing equipment. Defend against cylindrical specialists extending into curved pouch formats by locking display OEMs into bonded module exclusivity. For New Entrants and Emerging Players: Indian electric bike assemblers under PLI scheme pressure represent the most penetrable buyer archetype for frame-integrated curved formats. Target Tamil Nadu manufacturing investments supplying two-wheeler OEMs seeking downtube battery placement without structural redesign. Pursue technical partnerships with domestic wearable assembly operations in Maharashtra bypassing display-battery integration incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with pouch-cell assemblers possessing lamination expertise but lacking display integration partnerships. Long-term viability hinges on solid-state electrolyte convergence eliminating flex-fatigue failure modes. Watch ceramic-polymer hybrid patent filings as inflection indicator for next-generation capacity obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Display-Battery Integration Partnership | Samsung Display procurement teams now specify bonded curved cell assemblies eliminating discrete battery compartments. |
| Silicon-Anode Chemistry Scale-Up | Pouch-cell assemblers with lamination expertise capture premium wearable tier specifications from cylindrical specialists. |
| GB 31241 Recertification Investment | Qualified suppliers command margin premiums as NMPA flex-fatigue protocols force costly requalification cycles. |
| India PLI Localization Facility | Tamil Nadu cell manufacturing targets domestic two-wheeler OEM procurement under BIS tightening for non-planar geometries. |
| Solid-State Electrolyte R&D Program | Ceramic-polymer hybrid research promises mechanical tolerance eliminating 15-40mm radius bending degradation physics. |
Research Methodology
Direct dialogue with cell manufacturing executives, display panel procurement leads, drone OEM platform engineers, and electric bike frame designers grounded qualitative findings. Secondary validation drew from SAMR GB standard filings, MFDS medical device registrations, PLI scheme disbursement records, and pouch-cell trade flow data. Bottom-up capacity modeling and top-down demand triangulation cross-checked volume estimates across the analysis window.
Segment-level outputs for product type, application, capacity tier, and end user category fed into analytical framework calculations throughout the forecast period. CAGRs derived from production capacity buildout timelines, OEM specification migration patterns, and regulatory phase-in schedules. Forecast inputs incorporated silicon-anode chemistry adoption curves and solid-state electrolyte patent expiration trajectories.
Underlying measurement precision varies by segment; portable electronics and drone applications carry tighter precision than hobbyist RC channels given specification transparency. Forecasts reflect assumptions on display-battery integration contract penetration and cobalt-alternative cathode chemistry viability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
North America Electric Vehicle Battery Anode Market
EV Batteries
Asia Pacific Electric Vehicle Battery Manufacturing Market
EV Batteries
India EV Battery Pack Market
EV Batteries
Cold-Climate Optimized EV Battery Systems Market
EV Batteries
European EV Battery Systems Market
EV Batteries
ASEAN Electric Vehicle VRLA Batteries Market
EV Batteries
ASEAN Countries Electric Vehicle Battery Manufacturing Market
EV Batteries
North America Electric Vehicle Battery Manufacturing Market
EV Batteries
China EV Battery Pack Market
EV Batteries
Solar DC Coupled Battery Market
EV Batteries
Italy Electric Vehicle Battery Manufacturing Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
United States Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Electronic Vehicle (EV) Cells Market
EV Batteries
China Electric Vehicle Battery Market
EV Batteries
North America Electric Vehicle VRLA Batteries Market