
 VRLA Batteries Market | 2026-2036
VRLA Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
VRLA Batteries Market Insights
Remote battery monitoring and predictive maintenance subscriptions is realigning how VRLA systems are procured and monetized across industrial accounts. Clarios leverages its service-network density to lock in multi-year fleet management contracts with telecom operators. EnerSys sustains technology leadership through R&D intensity in electrolyte formulations for high-temperature climates. East Penn Manufacturing anchors North American supply security with captive lead recycling and regional foundry control.
Valve-regulated lead-acid batteries employ immobilized electrolyte—either gelled sulfuric acid or absorbed in fiberglass mat separators—to enable sealed, position-independent operation with minimal gas venting, serving critical backup power functions where maintenance access proves difficult or hazardous. Absorbent Glass Mat variants command premium positioning in data center and telecommunications installations due to superior cycle stability and faster recharge rates compared to conventional sealed designs. Gel configurations dominate renewable energy storage applications where deep-discharge tolerance and thermal resilience offset higher unit costs.
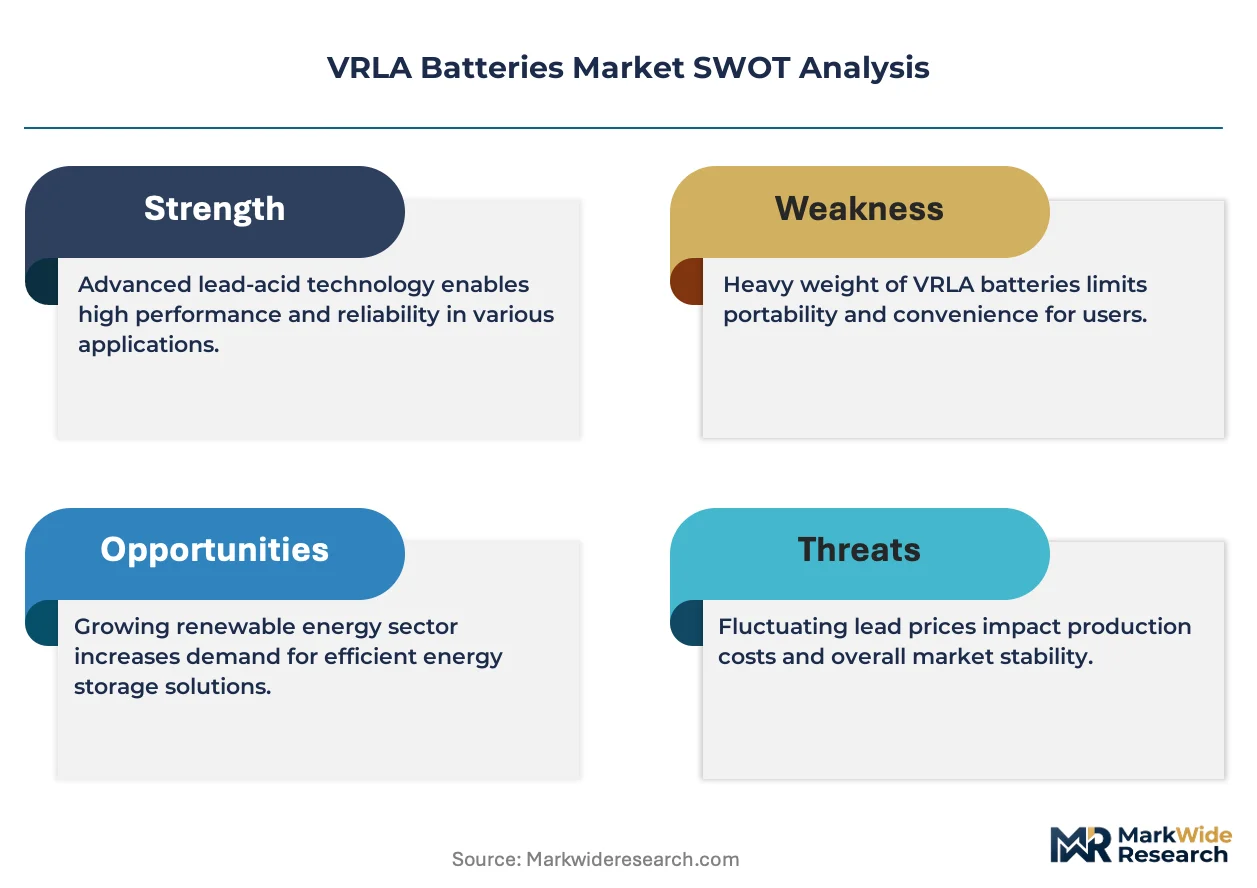
EPA hazardous waste regulations and OSHA workplace exposure standards govern VRLA manufacturing, recycling, and installation protocols across the United States, while China's MIIT enforces GB standards for battery performance and carbon-intensity disclosures. India's BIS certification requirements and CEA grid-interconnection rules shape product eligibility for telecom and utility procurement tenders. Stakeholders must track evolving recyclate-content mandates and carbon-border adjustment mechanisms to anticipate sourcing cost shifts and qualification barriers.
Market Dynamics
Telecom tower electrification and data center uptime requirements are compressing procurement cycles for VRLA systems, forcing suppliers to bundle predictive maintenance software with hardware contracts to secure multi-year fleet relationships.
Growth Catalysts
- India's telecom tower electrification programs:Tower operators under the Digital India initiative require reliable backup power for rural connectivity expansion, driving standardized VRLA procurement at scale.
- GB standards compliance in China:MIIT's dual carbon disclosure mandates and battery recycling protocols are filtering out non-compliant manufacturers, consolidating demand among certified suppliers.
- Absorbent Glass Mat technology maturation:Superior cycle stability and faster recharge rates in AGM configurations are displacing conventional sealed designs in critical infrastructure applications.
Market Restraints
- Lead price volatility:Primary lead smelter concentration in China and Australia creates input cost instability that compresses margin buffers for non-integrated manufacturers.
- Stationary lithium-ion substitution:Declining lithium battery costs and longer cycle life are eroding VRLA's historical cost advantage in grid-scale storage applications.
- EPA hazardous waste classification:Stringent RCRA disposal protocols in the United States elevate end-of-life handling costs and complicate cross-state logistics for battery recyclers.
Strategic Opportunities
- Remote monitoring subscription models:Industrial accounts in Germany and Japan are accepting recurring-fee structures for predictive maintenance, decoupling vendor revenue from unit sales cycles.
- CEA grid-interconnection rules in India:Mandatory backup power duration specifications for telecom infrastructure create qualified supplier lists that favor established VRLA manufacturers with BIS certification.
- Gel-electrolyte renewable integration:Deep-discharge tolerance in gel configurations is opening solar-plus-storage microgrid deployments across Southeast Asian island electrification projects.
Industry Challenges
- Electrochemical engineering talent scarcity:Specialized expertise in lead-acid electrolyte formulation for high-temperature climates is concentrating at a handful of legacy research centers, constraining product development velocity.
- Multi-standard certification timelines:Simultaneous compliance with IEC 60896, JIS C 8702, and UL 1989 testing protocols extends product qualification cycles by 18-24 months for global suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VRLA Batteries Market |
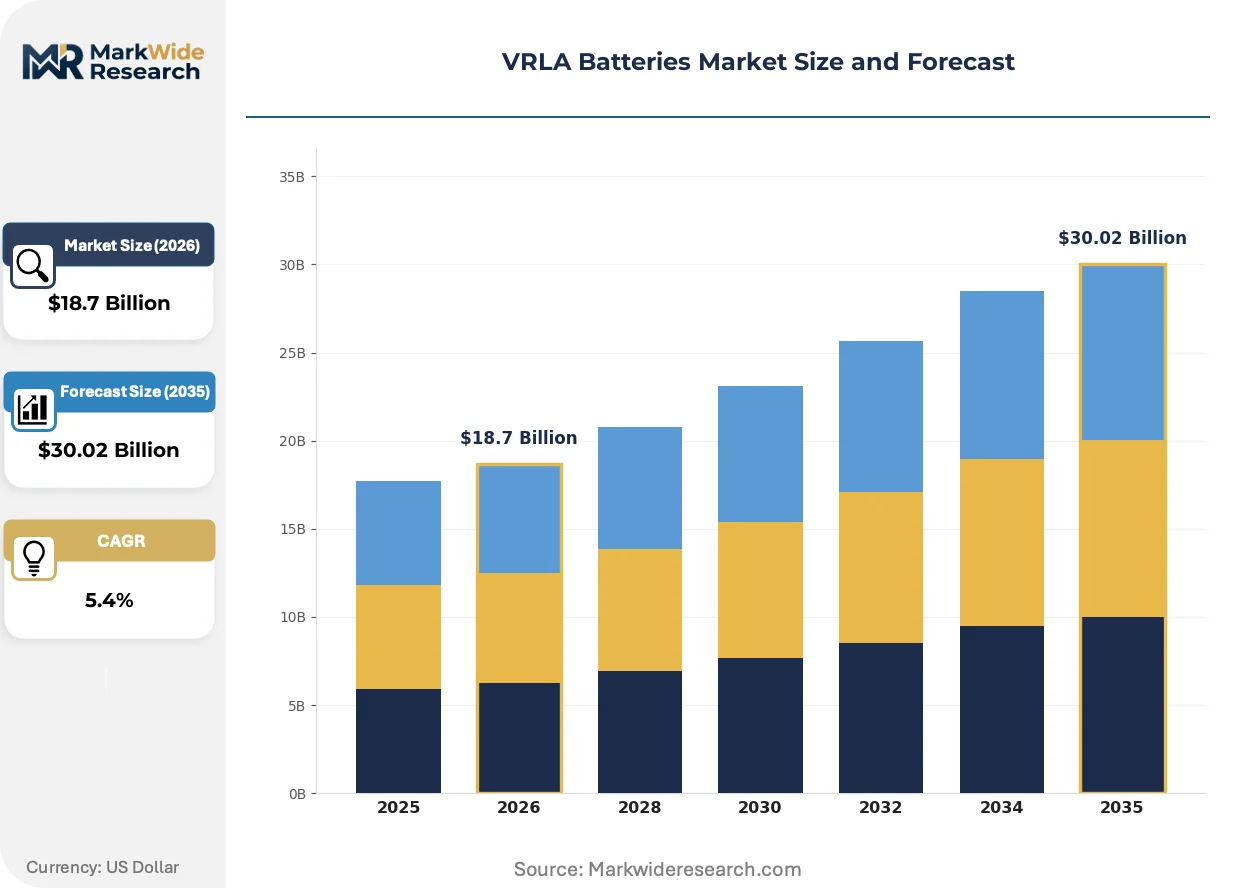
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sealed Lead Acid, Gel, Absorbent Glass Mat, Maintenance-Free End User: Automotive, Telecommunications, Uninterruptible Power Supply, Renewable Energy Application: Energy Storage Systems, Backup Power, Household Appliances, Electric Vehicles Installation: Indoor, Outdoor, Portable, Stationary |
| Companies Covered | Clarios, EnerSys, GS Yuasa Corporation, Leoch International Technology, Exide Technologies, East Penn Manufacturing, Amara Raja Energy and Mobility, HOPPECKE Battery GmbH, C&D Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VRLA Batteries Market Trends and Innovations
Digitalization of battery health monitoring and predictive analytics is restructuring how industrial buyers evaluate total cost of ownership, shifting procurement criteria from upfront capital expense toward lifecycle reliability guarantees.
Containerized VRLA energy storage systems with integrated battery management electronics are modularizing deployment architectures for data center and telecom applications. Hyperscale operators in Northern Virginia and Frankfurt are specifying plug-and-play skid-mounted configurations that reduce on-site installation labor by half. This standardization is modularizing supplier competition around software-enabled service layers rather than cell manufacturing scale alone.
China's MIIT enforcement of GB/T 36276 performance standards and carbon-intensity disclosures is tightening manufacturing compliance requirements across the supply base. Domestic producers must now document recyclate content and energy consumption per production unit, creating qualification barriers for export-oriented competitors. Battery assemblers in Jiangsu and Guangdong provinces are responding by integrating captive lead recycling to secure carbon accounting transparency.
Telecom infrastructure operators are consolidating vendor relationships around fleet management contracts that bundle hardware, installation, and predictive replacement scheduling. India's Bharti Infratel and American Tower Corporation are shifting from transactional procurement to outcome-based agreements where suppliers guarantee uptime availability. This reconfiguration is most visible in India's tower electrification programs, where multi-year service contracts now dominate RFP structures over standalone battery purchases.
VRLA Batteries Market Segmentation
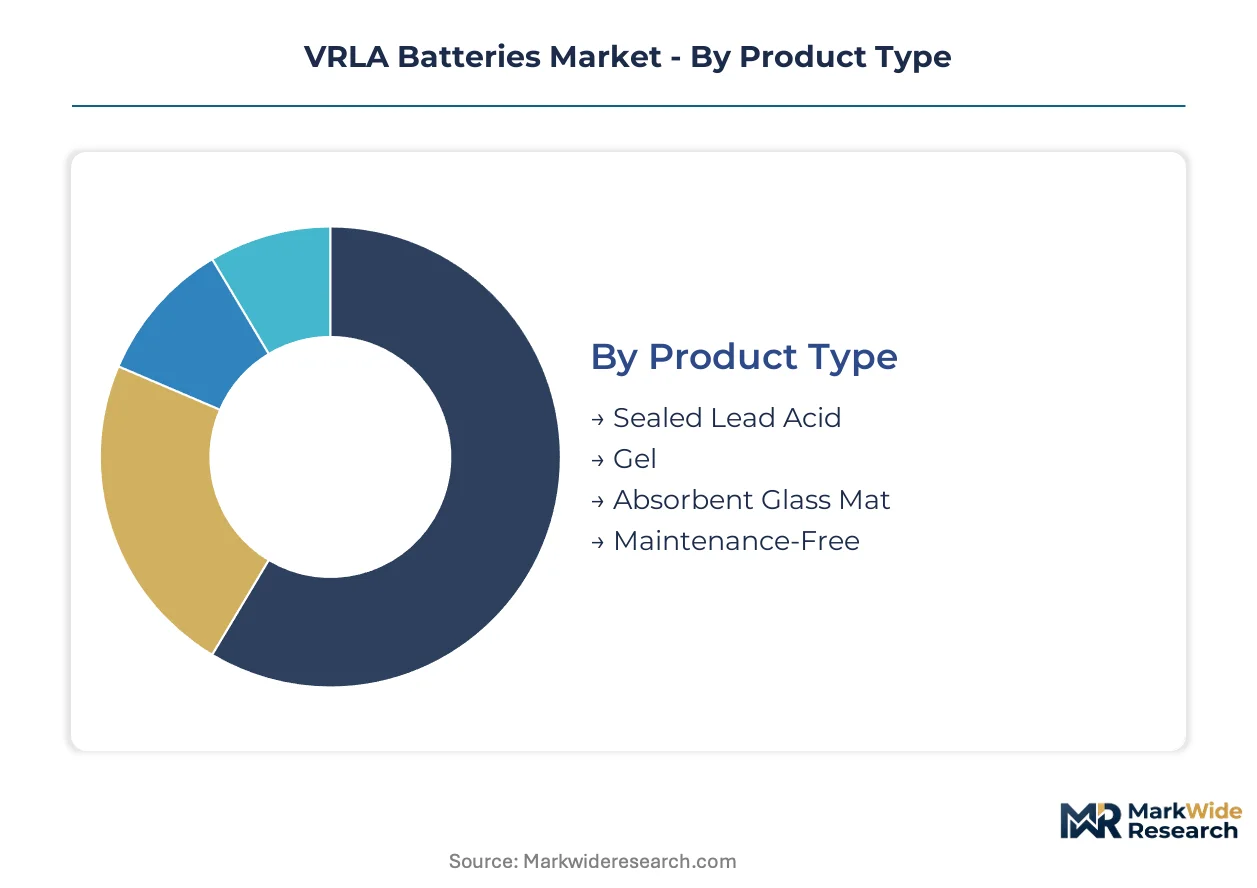
Segmentation in VRLA batteries reveals how immobilized electrolyte technologies map to distinct duty cycles and replacement cadences. Procurement patterns diverge sharply between telecom operators seeking 10-year service life guarantees and automotive buyers prioritizing cold-crank performance over longevity.
Product Type:
Upgrade and replacement cycles vary dramatically across electrolyte immobilization methods, with Absorbent Glass Mat systems commanding premium positioning for infrastructure applications demanding extended float life.
- Absorbent Glass Mat:Electrolyte suspended in fiberglass mat separators enables superior oxygen recombination efficiency and faster recharge rates. Data center operators in Northern Virginia and Frankfurt specify AGM configurations for their 15-year design life and reduced thermal runaway risk under continuous float conditions.
- Gel:Silica-thickened electrolyte provides deep-discharge tolerance and thermal resilience for cyclic applications. Solar-plus-storage microgrids across Southeast Asian island electrification projects favor gel configurations despite 20-30% unit cost premiums over AGM alternatives.
- Sealed Lead Acid:Conventional valve-regulated construction with liquid electrolyte retention serves price-sensitive automotive starting applications where shallow discharge dominates duty profiles.
- Maintenance-Free:Calcium-alloy grid formulations minimize water loss during float operation, targeting residential backup power installations with limited technical access for electrolyte topping.
Absorbent Glass Mat sits at the top of the volume ranking, with Gel climbing the fastest as renewable integration accelerates cyclic duty requirements.
End User:
Cost tier stratification separates mission-critical infrastructure buyers willing to pay lifecycle reliability premiums from automotive OEMs optimizing for unit economics at scale.
- Telecommunications:Tower operators under India's Digital India initiative require standardized VRLA procurement for rural connectivity expansion, with Bharti Infratel and American Tower Corporation consolidating around multi-year fleet management contracts.
- Uninterruptible Power Supply:Hyperscale data center operators specify containerized VRLA systems with integrated battery management electronics, modularizing deployment architectures around plug-and-play skid-mounted configurations.
- Automotive:Start-stop vehicle electrification drives demand for enhanced flooded and AGM variants, though lithium-ion displacement pressures VRLA share in mild-hybrid architectures.
- Renewable Energy:Grid-interconnection rules from India's CEA mandate backup power duration specifications that favor established VRLA manufacturers with BIS certification for solar-storage hybrid installations.
Telecommunications commands the largest installed base, while Renewable Energy applications are expanding most quickly as island electrification programs proliferate.
Application:
Volume concentration in backup power installations reflects the inherent suitability of VRLA chemistry for standby duty with infrequent deep cycling.
- Backup Power:Float-service operation in telecom shelters, data center power halls, and medical facilities constitutes the core demand driver, with EPA hazardous waste regulations elevating end-of-life handling costs for US-based operators.
- Energy Storage Systems:Grid-scale deployments face accelerating lithium-ion substitution as stationary battery costs decline, though VRLA retains share in behind-the-meter commercial installations where fire safety codes restrict lithium chemistry.
- Household Appliances:Security systems, garage door openers, and emergency lighting represent fragmented demand with low technical specification thresholds and high price elasticity.
- Electric Vehicles:Auxiliary power for lighting and accessories in electric two-wheelers and low-speed electric vehicles persists in price-sensitive emerging markets, though traction battery applications have largely transitioned to lithium.
Backup Power dominates current procurement volumes, with Energy Storage Systems gaining share fastest where safety regulations constrain lithium deployment.
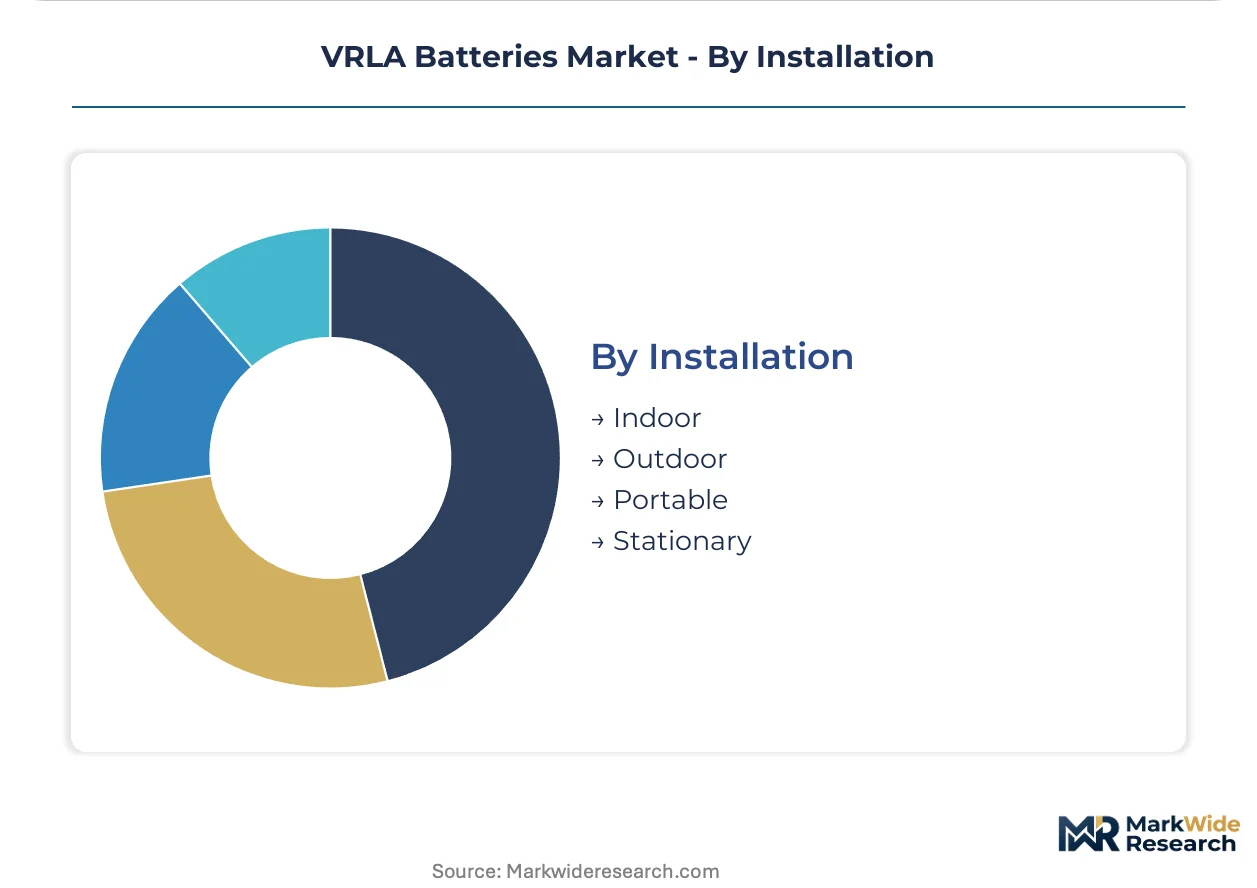
Installation:
Customer type differentiation separates industrial accounts accepting predictive maintenance subscriptions from consumer markets prioritizing upfront capital minimization.
- Stationary:Fixed rack-mounted installations in climate-controlled environments enable maximum service life realization, with remote monitoring subscriptions from German and Japanese industrial accounts decoupling vendor revenue from unit sales cycles.
- Outdoor:Telecom tower shelters and renewable energy sites expose batteries to temperature extremes, driving demand for gel configurations with enhanced thermal resilience and accelerated replacement schedules.
- Indoor:Data center white space installations prioritize fire suppression compatibility and minimal gas venting, favoring AGM chemistry with UL 1989 certification for restricted ventilation environments.
- Portable:Recreational vehicles, marine applications, and mobile medical equipment require position-independent operation with vibration tolerance, serving niche volumes with specialized packaging requirements.
Stationary installations anchor procurement volumes, with Outdoor configurations climbing fastest as rural telecom electrification extends beyond climate-controlled infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping VRLA battery production footprints as manufacturers migrate toward jurisdictions with lower carbon-accounting burdens and streamlined certification protocols. Compliance cost differentials between China's MIIT disclosure mandates and India's BIS certification timelines are accelerating capacity relocation decisions.
China
MIIT's GB/T 36276 performance standards and dual carbon disclosure requirements are filtering domestic manufacturers for recyclate-content transparency. Battery assemblers in Jiangsu and Guangdong provinces are integrating captive lead recycling to secure carbon accounting compliance. The Pearl River Delta cluster is consolidating around vertically integrated producers with documented energy consumption per production unit.
India
Digital India telecom tower electrification programs are driving standardized VRLA procurement at scale for rural connectivity expansion. CEA grid-interconnection rules mandate backup power duration specifications that create qualified supplier lists favoring BIS-certified manufacturers. Tamil Nadu and Gujarat industrial corridors are attracting contract assembly investments to serve tower operator fleet management contracts.
United States
EPA hazardous waste regulations under RCRA elevate end-of-life handling costs and complicate cross-state logistics for battery recyclers. Data center operators in Northern Virginia specify containerized VRLA systems with UL 1989 certification for restricted ventilation environments. OSHA workplace exposure standards govern manufacturing protocols across domestic production facilities.
Germany
Industrial accounts are accepting recurring-fee structures for predictive maintenance subscriptions, decoupling vendor revenue from unit sales cycles. ECHA REACH compliance requirements for lead substance registration shape import qualification barriers for non-EU suppliers. The Ruhr industrial region maintains specialized electrochemical engineering expertise for high-temperature electrolyte formulations.
Japan
METI industrial efficiency standards and JIS C 8702 testing protocols extend product qualification timelines for global suppliers seeking market access. Remote monitoring subscription models are penetrating industrial accounts in Kanto and Kansai regions. Osaka-based research centers concentrate specialized expertise in lead-acid electrochemistry for climate-adapted battery designs.
VRLA Batteries Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated producers commanding infrastructure procurement while OEM suppliers serve automotive replacement markets. The vendor base organizes around three strategic archetypes: vertically integrated lead recyclers with captive foundry control, technology specialists with electrolyte formulation IP, and service-network operators bundling predictive maintenance software. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers secure multi-year fleet relationships with telecom tower operators.
Among North American integrated producers, East Penn Manufacturing exemplifies the captive recycling archetype with regional foundry control, while Clarios represents the service-network density model through multi-year fleet management contract structures. EnerSys occupies a position within the technology specialist tier, sustaining R&D intensity in electrolyte formulations. These three anchors illustrate how competitive positioning separates around supply security, software-enabled services, and climate-adapted product engineering rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Clarios |
| EnerSys |
| GS Yuasa Corporation |
| Leoch International Technology |
| Exide Technologies |
| East Penn Manufacturing |
| Amara Raja Energy and Mobility |
| HOPPECKE Battery GmbH |
| C&D Technologies |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists with multi-decade foundry legacies anchor pricing discipline through captive lead recycling, while private-equity-rolled-up service networks compete via subscription bundling that shifts revenue recognition from hardware margins to recurring maintenance fees.
Pricing Analysis
Capacity additions in China's Jiangsu and Guangdong provinces are reshaping price floors for standard AGM configurations, compressing margins for non-integrated assemblers. Three-tier pricing structure across premium, standard, and economy levels separates UL 1989-certified data center grades from BIS-compliant telecom tiers and unbranded automotive replacement units. Price differentiation hinges on certification tier and after-sales service bundling. Cost compression in economy-tier sealed lead-acid units is intensifying because of primary lead smelter concentration in China and Australia. Automotive OEMs exhibit highest price sensitivity; hyperscale data center operators accept lifecycle reliability premiums.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for containerized VRLA systems, while distributor networks serve fragmented automotive aftermarket demand. Supply concentrates in China, India, and the United States for cell assembly and in Australia and China for primary lead smelting. Raw material flows draw from lead ore concentrates, fiberglass mat separators, and silica gelling agents. Single-source vulnerability in primary lead smelting creates exposure to input cost volatility. Distribution runs through authorized service networks for fleet management contracts and open distribution for replacement markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through predictive maintenance subscription penetration and premium-tier AGM displacement of conventional sealed designs in data center applications.
For Market Incumbents: To counter stationary lithium-ion substitution in grid-scale storage, Clarios and EnerSys should deepen backward integration into captive lead recycling to secure carbon accounting transparency under China's MIIT disclosure mandates. Capacity additions in India's Tamil Nadu and Gujarat corridors can anchor multi-year fleet contracts with Bharti Infratel and American Tower Corporation under CEA grid-interconnection rules. For New Entrants and Emerging Players: Launch via remote monitoring subscription models targeting German and Japanese industrial accounts that have accepted recurring-fee structures for predictive maintenance. Island electrification programs across Southeast Asia represent the most penetrable geography, with gel-electrolyte solar-plus-storage microgrids offering qualified entry points without incumbent fleet lock-in. For Investors and Strategic Acquirers: Valuations sit cheapest among technology specialists with electrolyte formulation IP stranded by electrochemical engineering talent scarcity. Long-term viability centers on software-enabled service layers decoupling revenue from unit sales cycles. The signal to watch is BIS certification queue lengths in India as proxy for qualified supplier list access.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Lead Recycling Integration | Secures MIIT carbon disclosure compliance for Jiangsu and Guangdong assemblers. |
| Predictive Maintenance Platform Launch | Enables recurring-fee revenue from German industrial accounts accepting subscription structures. |
| BIS Certification Investment | Unlocks qualified supplier list access under India's CEA grid-interconnection rules. |
| Gel-Electrolyte Product Line Expansion | Targets deep-discharge tolerance requirements in Southeast Asian island electrification projects. |
| Containerized System Modularization | Reduces on-site installation labor for Northern Virginia hyperscale data center operators. |
Research Methodology
Bottom-up telecom tower and data center modeling reconciled against top-down lead smelter capacity tracking forms the analytical core of this study. Primary interviews with tower operations directors, data center procurement managers, battery plant engineers, and aftermarket distribution heads combined with secondary validation from MIIT GB standard filings, EPA RCRA compliance databases, BIS certification registries, and customs trade records. Triangulation across stakeholder inputs and documentary sources ensures segmentation integrity across electrolyte immobilization methods and installation configurations.
Input-output matrices map end-use demand from telecommunications, UPS, automotive, and renewable energy segments against production capacity by country cluster. Modeled dimensions span product type, end user, application, and installation environment. CAGRs derive from segment-level volume trajectories and value-per-unit trends across the projection horizon. Forecast inputs incorporate lead price volatility assumptions and lithium-ion substitution elasticity in grid-scale storage applications.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lead price spike scenarios or accelerated lithium cost parity. Periodic stress-testing of base assumptions is recommended, particularly around China's dual carbon enforcement intensity and India's BIS certification timeline extensions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Modular Battery Market
Batteries
Global Solar Battery Charger Market
Batteries
Modular Battery Pack Market
Batteries
Vanadium Redox Batteries Market
Batteries
Asia Pacific Electric Vehicle Battery Electrolyte Market
Batteries
Aluminum Based Battery Market
Batteries
Water-Based Zinc-Ion Battery Market
Batteries
Lithium-Fluorinated Graphite Batteries Market
Batteries
Zinc-Manganese Oxide Printed Battery Market
Batteries
Deep Cycle Battery Market
Batteries
Echelon Utilization of Power Battery Market
Batteries
United States SLI Battery Market
Batteries
North America Lead Acid Battery Market
Batteries
India Electric Vehicle Battery Manufacturing Equipment Market
Batteries
Second-Life Automotive Battery Module Systems Market
Batteries
Global Primary Cells Market