
 South Korea Electric Vehicle Battery Market | 2026-2036
South Korea Electric Vehicle Battery Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Electric Vehicle Battery Market Insights
A widening capital-intensity gap between integrated cell producers and pure-play material suppliers is redrawing competitive boundaries in the South Korea Electric Vehicle Battery Market. LG Energy Solution leverages captive cathode production to sustain margin control across the value chain. Samsung SDI anchors its position through premium NMC chemistry specialization for luxury EV platforms. SK On competes aggressively on manufacturing scale, securing multi-year supply agreements with Hyundai Motor Group.
South Korea Electric Vehicle Battery denotes electrochemical energy storage systems—typically lithium-ion cells with nickel-manganese-cobalt or lithium-iron-phosphate cathodes, graphite or silicon-composite anodes, and organic liquid electrolytes—engineered to deliver sustained DC power for electric traction motors in automotive applications. Lithium-ion products dominate installed capacity, though solid-state prototypes promise higher energy density and improved thermal stability. NMC chemistry captures premium passenger vehicle contracts where range optimization commands price premiums, while LFP formulations gain ground in commercial buses where cycle life and cost efficiency outweigh energy density requirements. Fast charging technology leads infrastructure deployment, though ultra-fast charging protocols represent the fastest-growing R&D investment category.
MFDS battery safety standards, K-Battery Day industrial policy frameworks, and METI-aligned export certification requirements collectively shape product qualification timelines and cross-border market access for Korean manufacturers. MFDS thermal runaway testing protocols force design modifications that extend development cycles but reduce liability exposure. Stakeholders must track solid-state pilot production yields and cathode material import dependency ratios as decisive variables for capacity planning and supply security.
Market Dynamics
Capital-intensity asymmetry between integrated cell manufacturers and cathode material suppliers is restructuring competitive boundaries across the South Korea Electric Vehicle Battery Market. LG Energy Solution's captive cathode production and Samsung SDI's premium chemistry specialization exemplify divergent strategic responses to this pressure.
Growth Catalysts
- K-Battery Day industrial policy:Government-backed funding mechanisms accelerate domestic gigafactory construction and R&D tax incentives for next-generation cell architectures.
- Hyundai Motor Group electrification roadmap:Aggressive EV output targets from Korea's largest automaker generate multi-year offtake commitments for domestic cell producers.
- Silicon-composite anode adoption:Advanced anode materials enable energy density improvements that satisfy premium passenger vehicle range requirements without pack size expansion.
Market Restraints
- Critical mineral import dependency:Cobalt and lithium raw material sourcing concentrates in African and South American geographies, exposing Korean cathode producers to geopolitical supply disruptions.
- MFDS thermal runaway testing protocols:Extended certification timelines for new cell designs compress product launch windows and elevate compliance engineering costs.
- Solid-state battery timeline uncertainty:Prototype-to-production yield gaps delay commercialization schedules, constraining near-term technology differentiation options.
Strategic Opportunities
- Commercial bus electrification:LFP chemistry formulations address cycle life and cost efficiency priorities in municipal and intercity fleet procurement specifications.
- Ultra-fast charging infrastructure deployment:Seoul-Incheon manufacturing corridor proximity enables integrated cell-to-charger system development for 350kW+ protocols.
- Seoul metropolitan cluster expansion:Concentrated cathode active material demand in the capital region supports localized precursor processing facility investments.
Industry Challenges
- Electrochemical engineering talent scarcity:Solid-state and silicon-anode specialist recruitment lags behind domestic gigafactory staffing requirements.
- Multi-site production integration:Coordination complexity between cathode precursor, cell assembly, and pack integration facilities strains quality control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Electric Vehicle Battery Market |
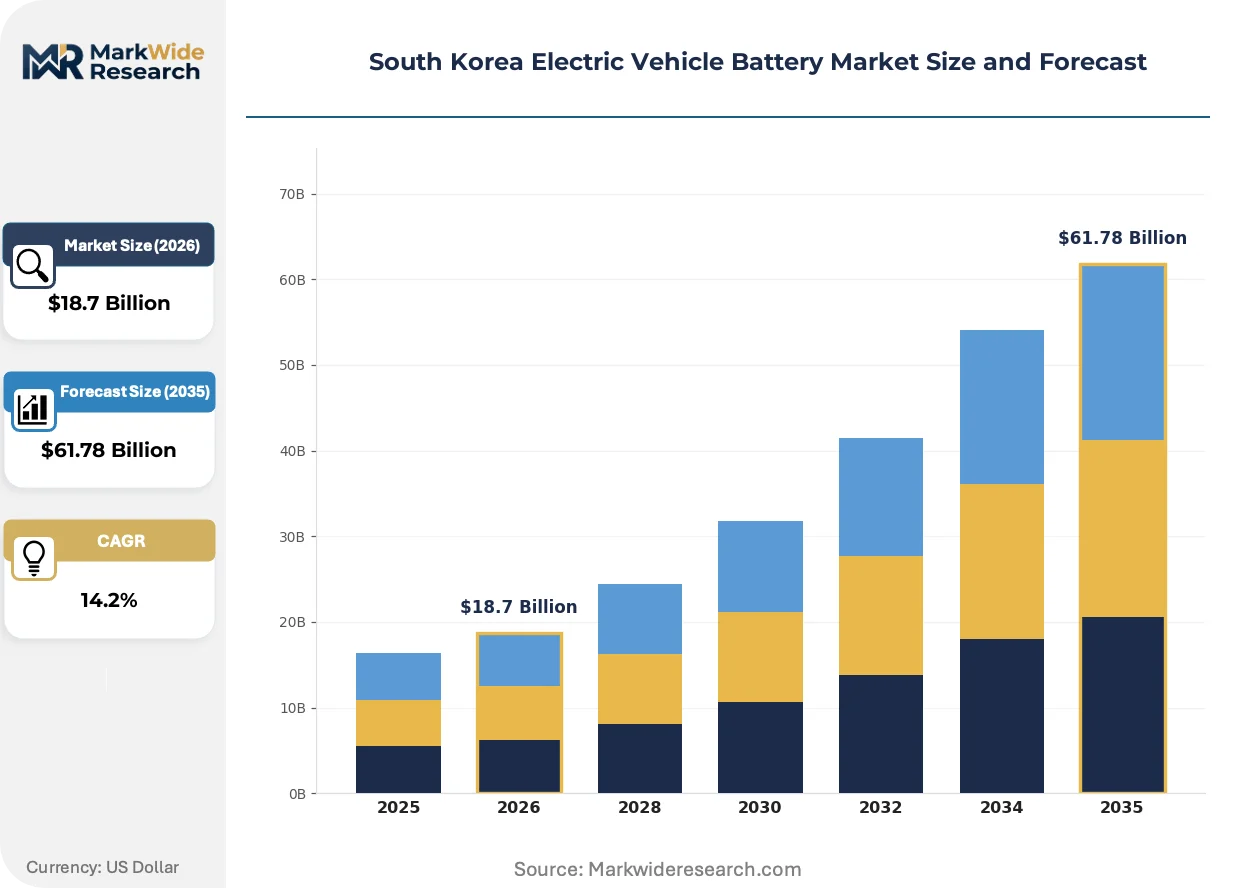
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel-metal Hydride, Solid-state, Lead-acid End User: Passenger Vehicles, Commercial Vehicles, Two-wheelers, Buses Technology: Fast Charging, Ultra-Fast Charging, Wireless Charging, Regenerative Braking Battery Chemistry: LFP, NMC, NCA, Others |
| Companies Covered | LG Energy Solution, Samsung SDI, SK On, Hyundai Motor Group, POSCO Future M, ECOPRO BM, Panasonic Corporation, Contemporary Amperex Technology, BYD Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Electric Vehicle Battery Market Trends and Innovations
Solid-state prototyping activity and cathode chemistry diversification are compressing traditional lithium-ion dominance windows. Korean manufacturers balance near-term NMC optimization against longer-term architecture transitions.
Solid-state battery prototypes are miniaturizing from laboratory cells toward pilot production formats. Samsung SDI and SK On are advancing oxide and sulfide electrolyte formulations for luxury EV platforms with 2027-2028 target production. This technology trajectory is miniaturizing the gap between theoretical energy density advantages and manufacturable cell geometries, forcing incumbent liquid electrolyte producers to accelerate silicon-anode integration as a defensive bridge solution.
MFDS battery safety certification requirements have tightened thermal runaway propagation testing standards for passenger vehicle applications. Cell producers must now demonstrate 15-minute flame resistance and non-propagation across module boundaries before market authorization. Premium NMC formulations for luxury EV platforms face the most stringent validation timelines, compressing development cycles and elevating engineering resource allocation to compliance functions.
Fleet procurement specifications are consolidating around total-cost-of-ownership metrics rather than upfront capital expenditure. Municipal bus operators and logistics providers in the Seoul metropolitan area now prioritize cycle life and residual value guarantees over energy density specifications. This specification pivot elevates LFP chemistry competitiveness in commercial vehicle segments where Korean cell producers had previously ceded position to Chinese suppliers.
South Korea Electric Vehicle Battery Market Segmentation
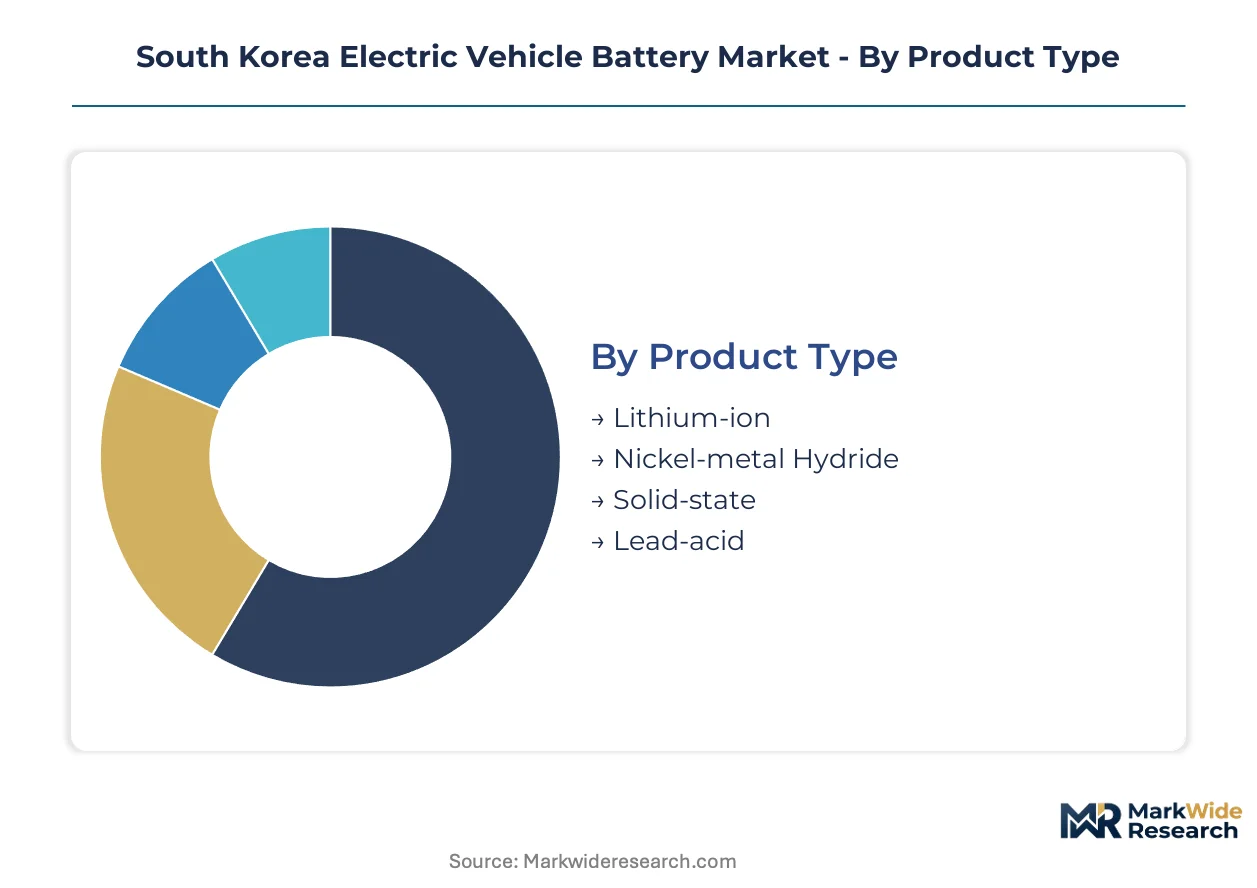
Segmentation in the South Korea Electric Vehicle Battery Market reveals how technology choices cascade through procurement channels. Product specifications determine qualification pathways under MFDS safety protocols, while end-use requirements shape chemistry selection and charging infrastructure deployment.
Product Type:
Cell format selection channels through distinct procurement pathways—automotive OEMs source cylindrical and prismatic cells through multi-year supply agreements, while aftermarket replacement flows concentrate through dealer networks and independent service channels.
- Lithium-ion:Nickel-manganese-cobalt and lithium-iron-phosphate cathodes paired with graphite or silicon-composite anodes deliver energy densities between 150-300 Wh/kg. Hyundai Motor Group's EV platform rollout in Seoul-Incheon manufacturing corridors sustains dominant procurement volumes for this segment.
- Solid-state:Oxide and sulfide electrolyte formulations replace liquid electrolytes to achieve theoretical energy density above 400 Wh/kg with improved thermal stability. Samsung SDI's pilot production targeting luxury EV platforms concentrates early demand within premium passenger vehicle channels.
- Nickel-metal Hydride:Mature chemistry serving hybrid electric vehicle auxiliary power units with established recycling infrastructure.
- Lead-acid:Limited to low-voltage auxiliary systems and aftermarket replacement in legacy vehicle fleets.
By volume, lithium-ion leads. By growth pace, solid-state is climbing the fastest.
End User:
Application-specific requirements create tiered pricing structures across vehicle categories. Premium passenger vehicles absorb advanced chemistry costs, while commercial fleets prioritize total-cost-of-ownership metrics.
- Passenger Vehicles:Range optimization drives NMC chemistry adoption in premium segments, with LFP gaining share in mass-market models. Seoul metropolitan area private ownership trends sustain the largest demand concentration.
- Buses:Municipal procurement specifications emphasize cycle life and residual value guarantees. LFP chemistry dominates Seoul metropolitan fleet electrification programs due to cost efficiency and durability requirements.
- Commercial Vehicles:Logistics operators in Incheon port corridors prioritize fast-charging compatibility for route optimization.
- Two-wheelers:Compact form factor requirements favor cylindrical cell formats with standardized voltage platforms.
Passenger vehicles command the revenue share. Buses are expanding most quickly.
Technology:
Charging protocol selection follows infrastructure deployment geography. Seoul-Incheon corridor density enables premium technology adoption, while peripheral regions lag in ultra-fast charging availability.
- Fast Charging:50-150 kW DC protocols dominate current infrastructure deployment. Highway corridor installations between Seoul and Busan sustain primary demand concentration.
- Ultra-Fast Charging:350 kW+ protocols enable 10-80% state-of-charge replenishment in under 20 minutes. SK On's integrated cell-to-charger system development targets premium passenger vehicle platforms.
- Wireless Charging:Inductive pad systems for fleet depot applications reduce connector wear in high-cycle commercial operations.
- Regenerative Braking:Energy recovery integration standard across all battery-electric platforms, with optimization varying by vehicle mass and duty cycle.
Fast charging holds the installed base. Ultra-fast charging shows the steepest expansion trajectory.
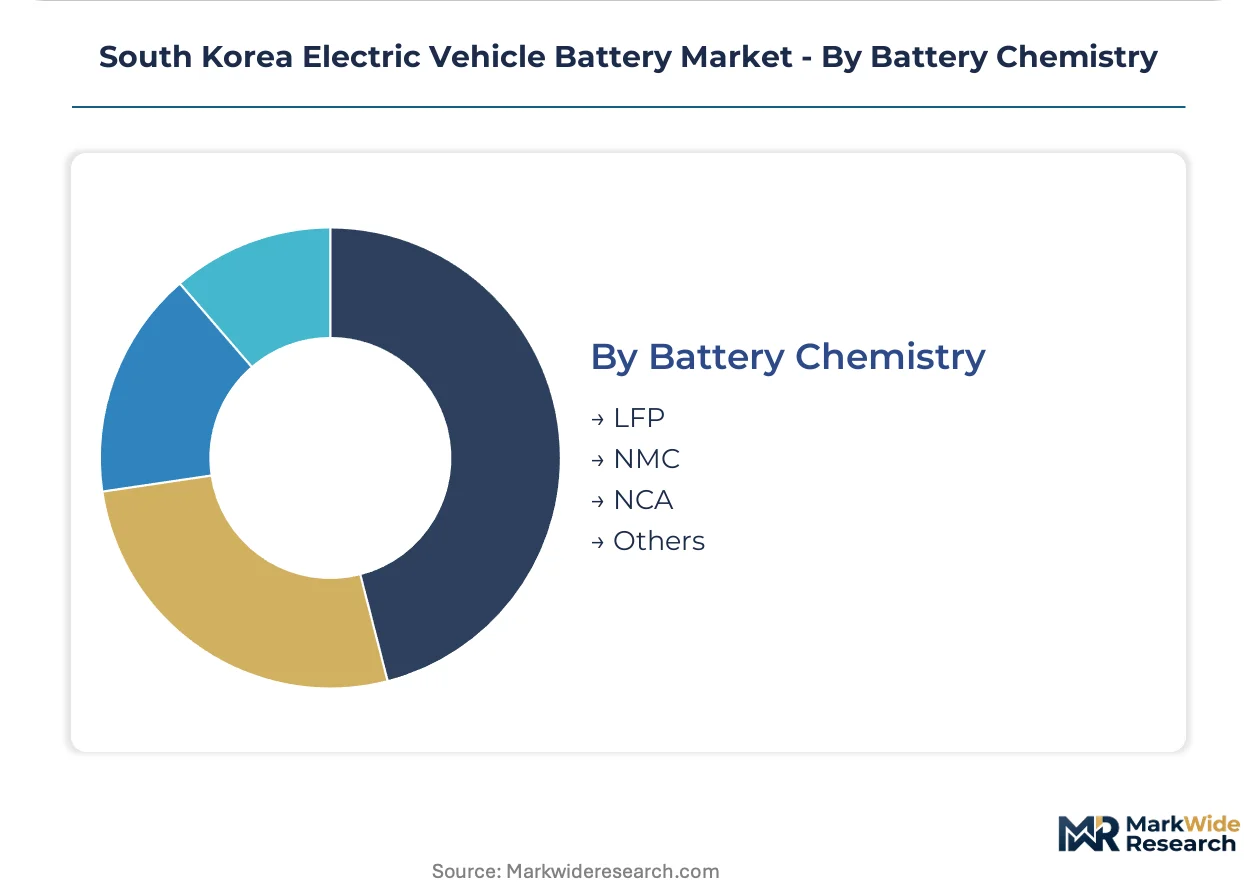
Battery Chemistry:
Cathode formulation selection reflects the tension between energy density requirements and raw material cost exposure. Korean producers balance nickel content reduction against range performance.
- NMC:Nickel-manganese-cobalt layered oxide cathodes optimize volumetric energy density for premium passenger vehicle range targets. High-nickel variants face thermal runaway testing intensity under MFDS protocols.
- LFP:Lithium iron phosphate olivine structure delivers superior cycle life and thermal stability at lower material cost. Municipal bus procurement in Seoul metropolitan clusters drives accelerating adoption.
- NCA:Nickel-cobalt-aluminum chemistry serves niche high-performance applications with elevated energy density requirements.
- Others:Sodium-ion and lithium-manganese-rich formulations occupy experimental and specialty vehicle segments.
NMC retains the revenue lead. LFP is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan Seoul commands price-inelastic demand for premium NMC cells, while provincial bus fleets exhibit acute cost sensitivity to LFP procurement. This elasticity gradient concentrates high-margin production in capital-region corridors and cost-optimized capacity in peripheral industrial zones.
Seoul Capital Area
Private EV ownership and luxury passenger vehicle demand anchor premium cell procurement volumes. MFDS thermal runaway certification requirements compress development timelines for high-nickel NMC formulations. Pangyo and Songdo tech clusters concentrate solid-state R&D pilot facilities alongside cathode precursor engineering centers.
Busan-Ulsan
Hyundai Motor Group's integrated vehicle manufacturing generates multi-year offtake commitments for cylindrical and prismatic cell formats. K-Battery Day policy incentives accelerate gigafactory construction in adjacent industrial zones. Ulsan petrochemical infrastructure supports electrolyte solvent and separator film production integration.
Daegu-Gyeongbuk
Municipal bus electrification programs drive LFP chemistry demand from provincial fleet operators. Regional procurement specifications prioritize cycle life guarantees over energy density metrics. Gumi industrial complex hosts cathode active material processing facilities serving mid-tier cell producers.
Daejeon-Sejong
Public research institutions and national battery testing laboratories concentrate regulatory compliance expertise. K-Battery Day funding mechanisms support next-generation cell architecture development in Sejong administrative city. Daejeon technology parks anchor silicon-anode and solid-state electrolyte pilot production.
Gwangju-Honam
Commercial vehicle electrification for port logistics and intercity freight creates fast-charging infrastructure demand. Regional cell assembly facilities target cost-sensitive fleet procurement with standardized LFP modules. Gwangju metropolitan area supports secondary battery recycling and materials recovery operations.
South Korea Electric Vehicle Battery Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where premium chemistry specialists coexist with scale-driven mass-market suppliers. The market consolidates around three dominant archetypes: integrated conglomerates with captive material supply, pure-play cell manufacturers with OEM anchor contracts, and cathode material specialists feeding multiple cell producers. Competitive moves concentrate on backward integration into precursor processing and multi-site capacity expansion to secure offtake agreements.
Among Korea-based integrated producers, LG Energy Solution, Samsung SDI, and SK On occupy distinct positioning vectors within the cell manufacturing tier. LG Energy Solution exemplifies the vertically integrated archetype through captive cathode production. Samsung SDI represents premium chemistry specialization for luxury vehicle platforms. SK On anchors the scale-competitive segment through aggressive manufacturing footprint expansion and multi-year supply agreements with domestic automakers.
| Leading Market Players |
|---|
| LG Energy Solution |
| Samsung SDI |
| SK On |
| Hyundai Motor Group |
| POSCO Future M |
| ECOPRO BM |
| Panasonic Corporation |
| Contemporary Amperex Technology |
| BYD Company |
| Others |
Pricing and Supply Chain Analysis
MFDS thermal runaway certification protocols gate both supplier qualification and price tiering simultaneously, compressing development timelines for high-nickel NMC cells while elevating compliance engineering costs that pass through to premium passenger vehicle OEMs. This regulatory threshold fragments the supplier base into certified premium-tier producers and cost-optimized LFP specialists serving municipal bus fleets.
Pricing Analysis
After-sales service contracts and residual value guarantees drive lifetime value capture across Korean cell producers. Three-tier pricing structure across premium NMC, standard LFP, and economy refurbished modules separates Hyundai Motor Group luxury platforms from municipal bus procurement and secondary battery applications. Price differentiation rests on MFDS certification tier and cathode material nickel content. Cost compression in standard-tier LFP modules is intensifying because Chinese suppliers compete aggressively on Seoul metropolitan bus tenders. Municipal fleet operators exhibit acute price sensitivity, while luxury passenger vehicle OEMs absorb premium chemistry premiums for range optimization.
Supply Chain Analysis
Strategic stockpiling of cobalt and lithium precursors dominates inventory strategy among Korean cathode producers confronting African and South American supply concentration. Raw material sourcing draws from the Democratic Republic of Congo for cobalt, Chile and Argentina for lithium carbonate, and Indonesia for nickel matte. Electrolyte solvents and separator films hinge on petrochemical feedstocks from Ulsan industrial complexes. Single-source vulnerability concentrates in high-purity cobalt hydroxide shipments through Durban port corridors. Distribution runs through integrated cell-to-pack facilities in Seoul-Incheon corridors with direct OEM line-feed arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Korean EV battery manufacturing exhibits defensive moat characteristics anchored in MFDS regulatory entrenchment, where certification timelines and testing facility access create switching costs that lock in incumbent cell producers.
For Market Incumbents: Fortify captive cathode precursor production to defend margin position against Chinese LFP cost pressure. Accelerate silicon-anode pilot yields to bridge solid-state commercialization gaps. Secure multi-year offtake extensions with Hyundai Motor Group before SK On capacity expansion saturates domestic demand. For New Entrants and Emerging Players: Second-life battery refurbishment services represent an underserved layer where incumbents under-serve municipal fleet operators seeking residual value guarantees. Target Gwangju-Honam commercial vehicle electrification programs with standardized LFP module swap systems. Pursue joint development agreements with Daejeon-Sejong research institutions to access MFDS pre-certification testing pathways. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across solid-state pilot production lines, favoring selective exposure over broad sector allocation. Five-to-ten year viability centers on cathode material specialists with demonstrated precursor processing yields and MFDS certification track records. Monitor solid-state electrolyte pilot production yield rates as the decisive inflection signal for technology transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Precursor Backward Integration | Captive nickel sulfate production reduces exposure to DRC cobalt price volatility for LG Energy Solution. |
| Solid-State Pilot Production Scale-Up | Samsung SDI's oxide electrolyte line advances toward luxury EV platform qualification under MFDS protocols. |
| LFP Chemistry Commercial Vehicle Expansion | SK On targets Seoul metropolitan bus procurement with cycle life guarantees displacing Chinese imports. |
| Ultra-Fast Charging Infrastructure Partnership | Integrated cell-to-charger development enables 350kW protocol deployment along Seoul-Busan highway corridors. |
| Silicon-Composite Anode R&D Investment | Energy density bridging solution defends liquid electrolyte market share against solid-state timeline uncertainty. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with cathode material procurement directors, MFDS certification engineers, OEM platform battery architects, and municipal fleet procurement managers; and secondary validation against K-Battery Day policy filings, MFDS thermal runaway test result disclosures, Hyundai Motor Group supplier announcements, and Seoul metropolitan area EV registration databases. Bottom-up cell production capacity estimates triangulated against top-down vehicle electrification targets across the analysis window.
Across the projection horizon, the analytical framework modeled volume and value outputs through segmentation dimensions spanning battery chemistry, cell format, end-use application, charging technology, and regional production cluster. CAGRs were derived from production capacity buildout schedules, OEM offtake commitment timelines, and fleet electrification procurement patterns. Forecast inputs incorporated silicon-anode adoption curves and solid-state pilot production yield trajectories.
Underlying assumptions cover MFDS certification timeline stability and cobalt-lithium price corridor persistence, with deviation risk concentrated in geopolitical supply disruptions and solid-state technology acceleration. Forecasts reflect these assumptions with explicit sensitivity bands for raw material cost shocks. Revision becomes warranted when solid-state pilot yields cross commercial viability thresholds or when K-Battery Day funding mechanisms shift toward alternative chemistry architectures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
Europe Electric Bus Battery Pack Market
EV Batteries
China EV Battery Pack Market
EV Batteries
United States Electric Vehicle Battery Anode Market
EV Batteries
United States Electric Vehicle Battery Manufacturing Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Japan EV Battery Pack Market
EV Batteries
France EV Battery Pack Market
EV Batteries
Europe LFP Battery Pack Market
EV Batteries
South America Hybrid Electric Vehicle Battery Market
EV Batteries
US EV Battery Pack Market
EV Batteries
Europe Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
European EV Battery Systems Market
EV Batteries
Electric Vehicle Battery Conditioners Market
EV Batteries
Spain Rechargeable Battery Market
EV Batteries
Italy Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
North America Electric Vehicle Battery Manufacturing Market