
 China Electric Vehicle Battery Market | 2026-2036
China Electric Vehicle Battery Market Size, Share, and Industry Trends Forecast 2026-2036
China Electric Vehicle Battery Market Intelligence
Fleet operators and logistics consortia are reorganizing procurement priorities toward higher-cycle-life chemistries. CATL leverages integrated cell-to-pack architectures to sustain manufacturing scale across multiple OEM supply agreements. BYD anchors vertical control through in-house production of lithium iron phosphate cells and captive vehicle deployment. Gotion competes on cost-optimized module designs for commercial vehicle platforms.
China electric vehicle batteries store electrochemical energy in lithium-ion cells with nominal voltages typically ranging from 3.2V to 3.7V per cell, assembled through winding or stacking processes into modules and thermal-managed packs for traction power. Lithium-ion chemistry dominates installed capacity due to mature supply chains and energy density thresholds above 250 Wh/kg at cell level. Solid-state configurations attract R&D capital as structural replacements for liquid electrolyte systems, though cell production stage margins remain concentrated where cathode active material costs determine pack economics. Passenger vehicles channel the largest volume throughput, while commercial vehicle usage types command premium pricing for extended cycle warranties.
MIIT sets mandatory energy density floors and recycling accountability rules under national new energy vehicle policy. GB standards enforce thermal runaway propagation limits and nail penetration test protocols. SAMR monitors market concentration under anti-monopoly frameworks as cell supply consolidates. Stakeholders must weigh NMPA certification timelines against solid-state pilot production commitments when allocating capital across manufacturing stages.
Market Dynamics
CATL and BYD are compressing cell-to-pack timelines while MIIT energy density mandates force cathode material upgrades across tier-one suppliers. This dual pressure from manufacturing scale and regulatory floors defines current competitive positioning.
Growth Catalysts
- MIIT Energy Density Mandates:Minimum thresholds for NEV subsidies push cathode active material upgrades toward nickel-rich chemistries. Pack assemblers must qualify new cell architectures to maintain incentive eligibility.
- Fleet Operator Procurement:Ride-hailing platforms and logistics consortia are consolidating battery orders into multi-year supply agreements. This demand concentration justifies dedicated production lines for high-cycle-life configurations.
- Yangtze River Delta Cluster:Shanghai-Ningbo manufacturing corridor concentrates cathode precursor refining, cell winding, and module assembly within 200-kilometer radius. Logistics costs compress while technical labor pools deepen.
Market Restraints
- Lithium Carbonate Volatility:Cathode material costs swing with spodumene concentrate auction prices from Australian hard-rock mines. Cell producers cannot fully pass input spikes to locked OEM contracts.
- Cell-Grade Supply Concentration:Qualified separator and electrolyte additive output clusters in Jiangsu and Fujian provinces. Disruption at single facilities propagates through multiple pack assembler schedules.
- Thermal Runaway Physics:Liquid electrolyte systems carry inherent propagation risk regardless of management system sophistication. Solid-state alternatives remain pre-commercial for mass automotive deployment.
Strategic Opportunities
- Commercial Vehicle Platforms:Heavy-duty trucks and municipal buses operate on fixed routes enabling battery swapping infrastructure. Operators amortize pack costs through energy-service agreements rather than capital purchase.
- Recycling Accountability Rules:MIIT traceability requirements create closed-loop revenue streams for black mass processing and cathode precursor recovery. Early compliance builds feedstock access for second-life material.
- Solid-State Pilot Lines:Sulfide and oxide electrolyte deposition equipment investments position suppliers for post-lithium-ion technology transitions. Pilot output qualifies for NMPA certification pathways ahead of volume mandates.
Industry Challenges
- Electrolyte Formulation Talent:Fluorinated additive synthesis and ionic conductivity optimization require specialized chemists concentrated at top-tier research institutes. Compensation inflation strains mid-cap cell producers.
- NMPA Certification Timelines:Thermal runaway propagation testing and nail penetration protocols extend qualification cycles for new cell geometries. Delayed approvals stall OEM platform launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Electric Vehicle Battery Market |
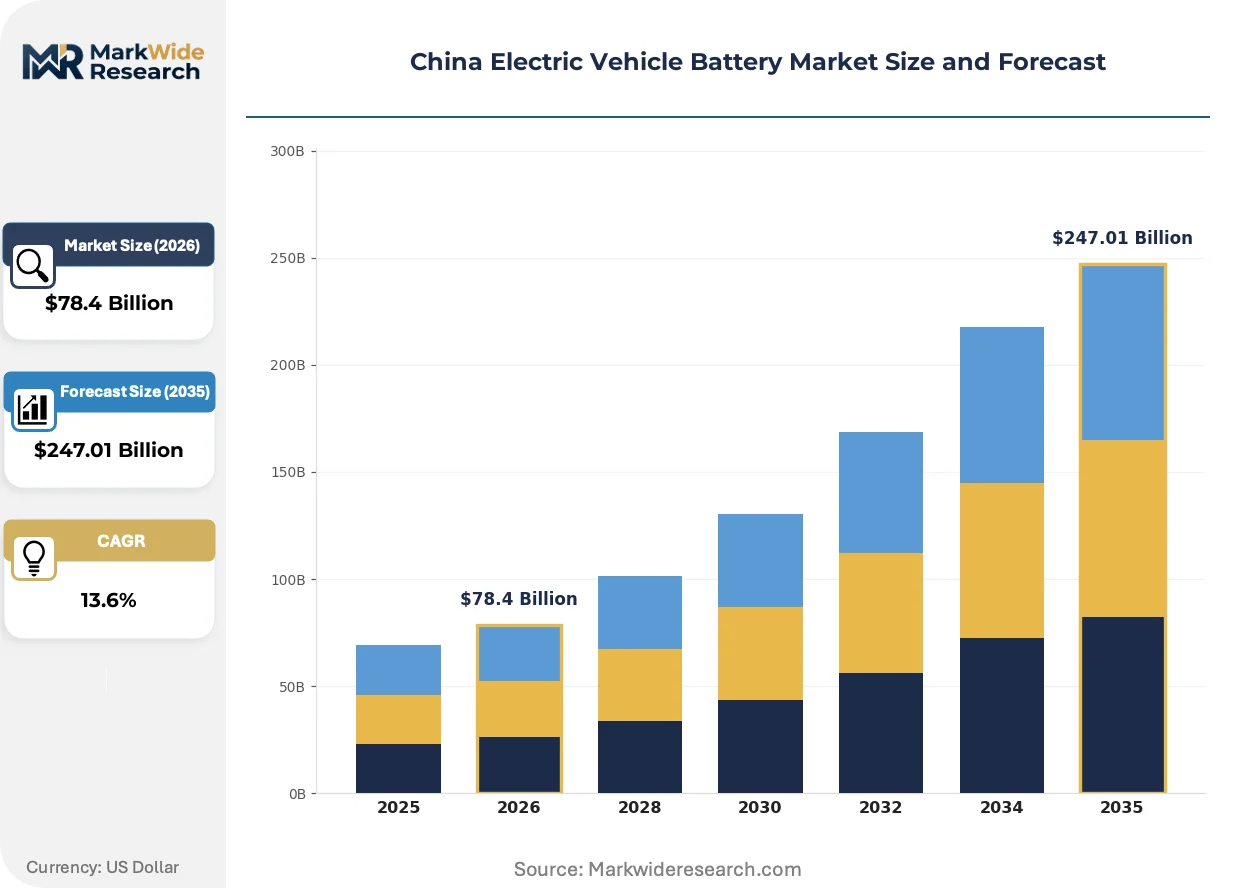
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $247.01 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-Ion, Lead-Acid, Nickel-Metal Hydride, Solid-State Usage Type: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Industrial Applications Manufacturing Stage: Cell Production, Module Assembly, Pack Development, Recycling Power Rating: High Power, Medium Power, Low Power, Ultra High Power |
| Companies Covered | CATL, BYD, CALB, Gotion, EVE Energy, Sunwoda, SVOLT Energy Technology, Lishen Battery, China Aviation Battery, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Electric Vehicle Battery Market Strategic Shifts & Innovations
Cell architecture evolution and regulatory tightening are compressing traditional module-pack hierarchies while fleet procurement models rewrite supplier relationships. Three forces dominate current market restructuring.
Cell-to-pack technology is eliminating module housings and busbar assemblies by bonding cells directly into structural battery enclosures. CATL and BYD deploy this architecture across multiple OEM platforms to reduce part count and improve volumetric energy density. The approach is miniaturizing thermal management hardware while shifting engineering liability from automakers to cell suppliers.
GB standards enforcement through NMPA certification is mandating five-minute thermal runaway propagation limits and multi-point temperature monitoring. Cell producers must redesign venting pathways and separator shutdown mechanisms to qualify for NEV subsidy lists. Commercial vehicle platforms face the steepest compliance costs due to larger pack sizes and duty-cycle severity.
Fleet operators are consolidating procurement through energy-service contracts that separate pack ownership from vehicle acquisition. Logistics consortia and ride-hailing platforms in the Yangtze River Delta now specify cycle-life guarantees rather than capital expenditure limits. This unbundling is compressing supplier margins while extending contract durations and performance accountability periods.
China Electric Vehicle Battery Market Segmentation
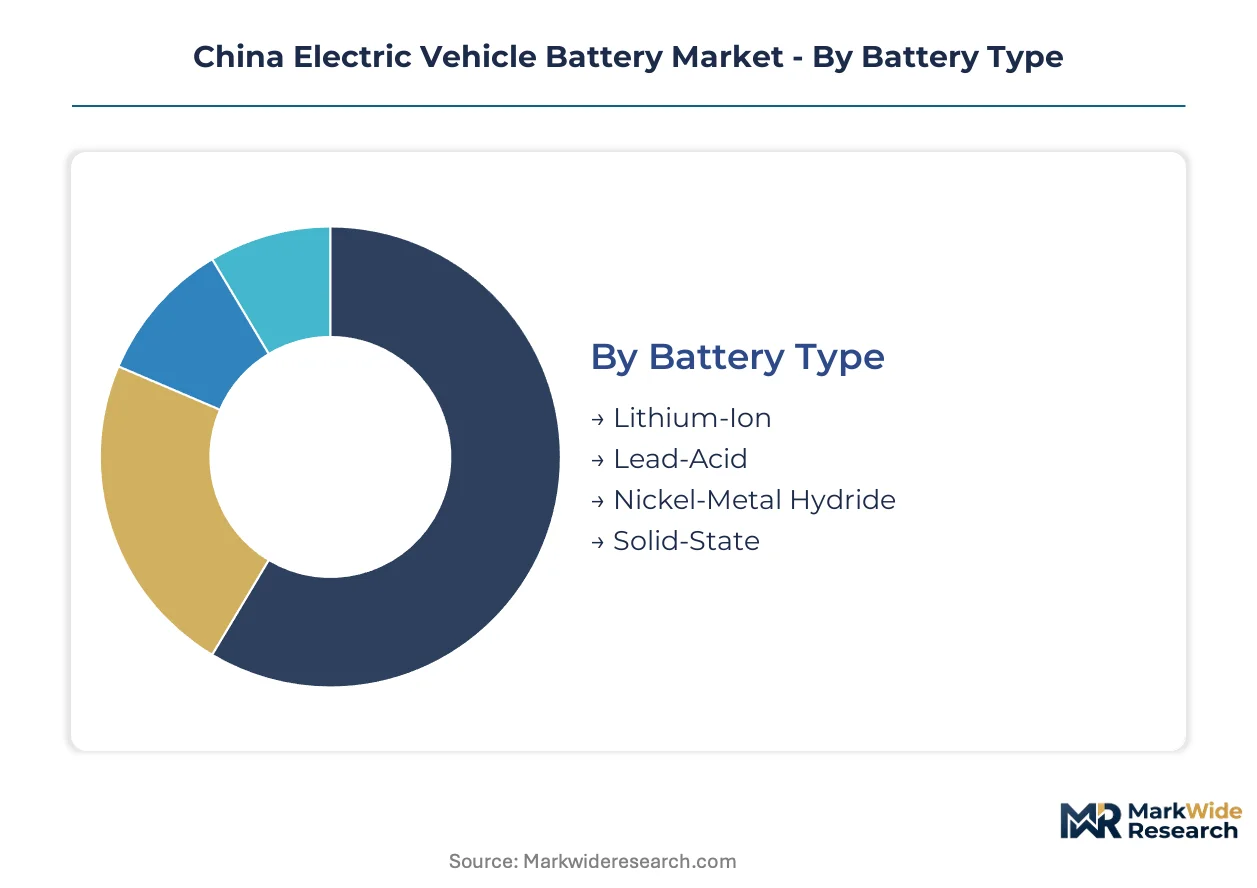
Segmentation reveals how cell chemistry, vehicle application, and production stage interact to determine margin capture. Procurement channels diverge sharply between passenger OEMs seeking energy density and fleet operators prioritizing cycle life.
Battery Type:
Channel distribution splits between automaker direct contracts for advanced chemistries and aftermarket distributors for legacy formulations.
- Lithium-Ion:NMC and LFP variants constitute the dominant installed chemistry, with nickel-rich cathodes serving premium passenger platforms and iron phosphate dominating commercial vehicle bids. Yangtze River Delta cell producers supply both channels under MIIT energy density mandates.
- Solid-State:Sulfide and oxide electrolyte configurations remain pre-commercial, attracting pilot line investment from tier-one suppliers seeking NMPA certification ahead of volume thresholds. Early samples qualify for subsidy list pre-positioning.
- Lead-Acid:Starter battery replacement market persists in legacy vehicle fleets and industrial equipment.
- Nickel-Metal Hydride:Hybrid vehicle auxiliary power units retain niche demand from specific OEM platforms.
Lithium-ion dominates installed base. Solid-state is where expansion concentrates.
Usage Type:
Cost tier stratification separates premium passenger specifications from price-sensitive commercial vehicle procurement.
- Passenger Vehicles:OEM platforms specify cell-to-pack architectures with volumetric density above 250 Wh/kg, sourced through multi-year framework agreements. CATL and BYD anchor supply through integrated manufacturing.
- Commercial Vehicles:Heavy-duty trucks and municipal buses demand extended cycle warranties and enable battery swapping infrastructure. Fixed-route operations support energy-service contracting models.
- Two-Wheelers:Cost-optimized LFP cells serve delivery fleet electrification and consumer replacement markets.
- Industrial Applications:Forklift and stationary storage applications prioritize capital expenditure minimization over energy density.
Passenger vehicles anchor volume throughput. Commercial vehicles command premium pricing tiers.
Manufacturing Stage:
Margin concentration varies by production step, with cathode active material and cell winding capturing value ahead of downstream assembly.
- Cell Production:Electrode coating, winding, and formation stages concentrate technical capability and capital intensity. Separator and electrolyte additive supply bottlenecks in Jiangsu and Fujian propagate through qualified output.
- Module Assembly:Tier-two suppliers compete on busbar design and thermal interface optimization for specific OEM platforms.
- Pack Development:System integrators incorporate battery management systems and structural enclosures, with liability shifting from automakers to cell suppliers under cell-to-pack architectures.
- Recycling:MIIT traceability requirements drive black mass processing and cathode precursor recovery investments.
Cell production captures margin concentration. Recycling is climbing the fastest as compliance obligations mature.
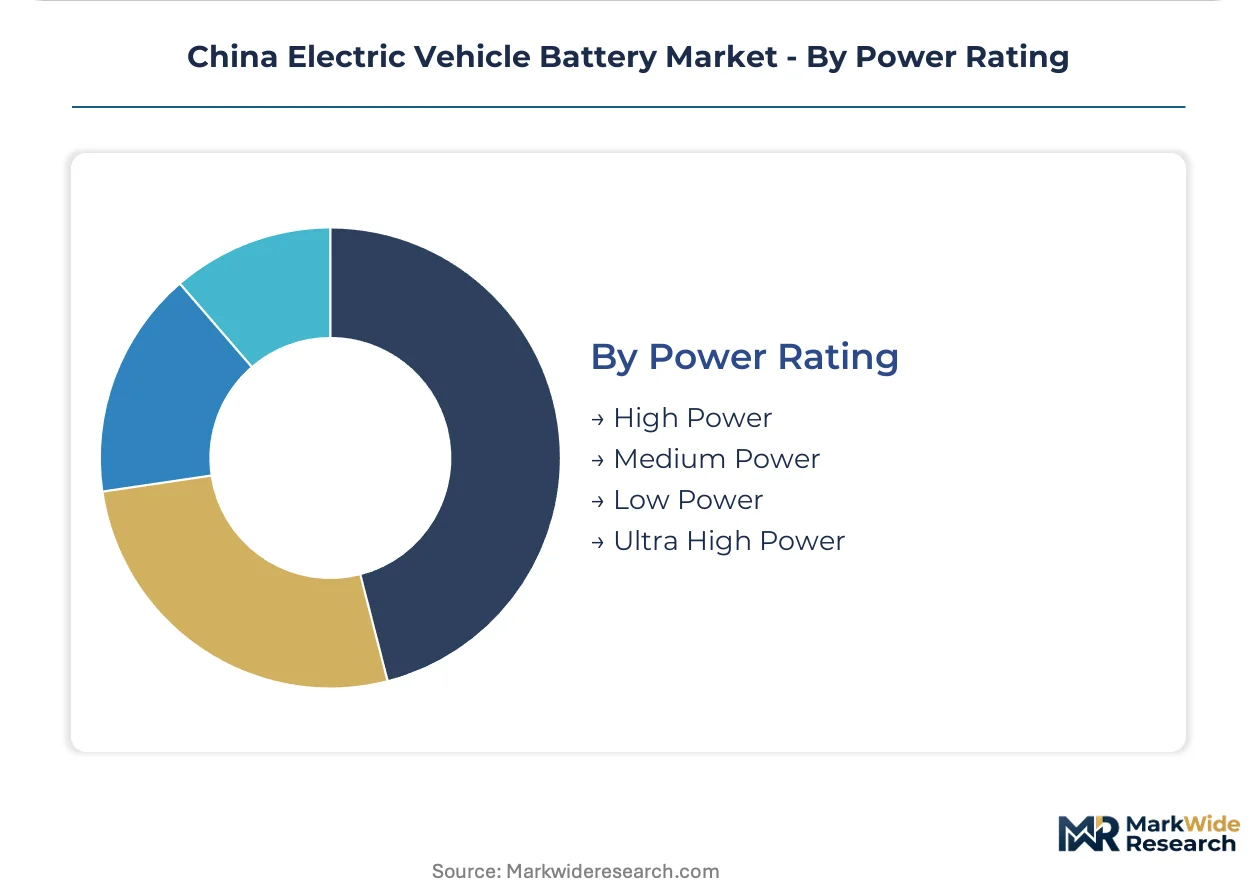
Power Rating:
Application requirements dictate power-to-energy ratio tradeoffs across vehicle and industrial segments.
- High Power:Performance electric vehicles and hybrid platforms demand rapid discharge capability with minimal thermal degradation.
- Medium Power:Standard passenger vehicle platforms balance acceleration response with range optimization.
- Low Power:Urban commuting and two-wheeler applications prioritize cost reduction over specific power metrics.
- Ultra High Power:Motorsport and specialty commercial applications require bespoke thermal management and limited production runs.
Medium power ratings serve the broadest addressable demand. Ultra high power occupies the steepest expansion trajectory in niche segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
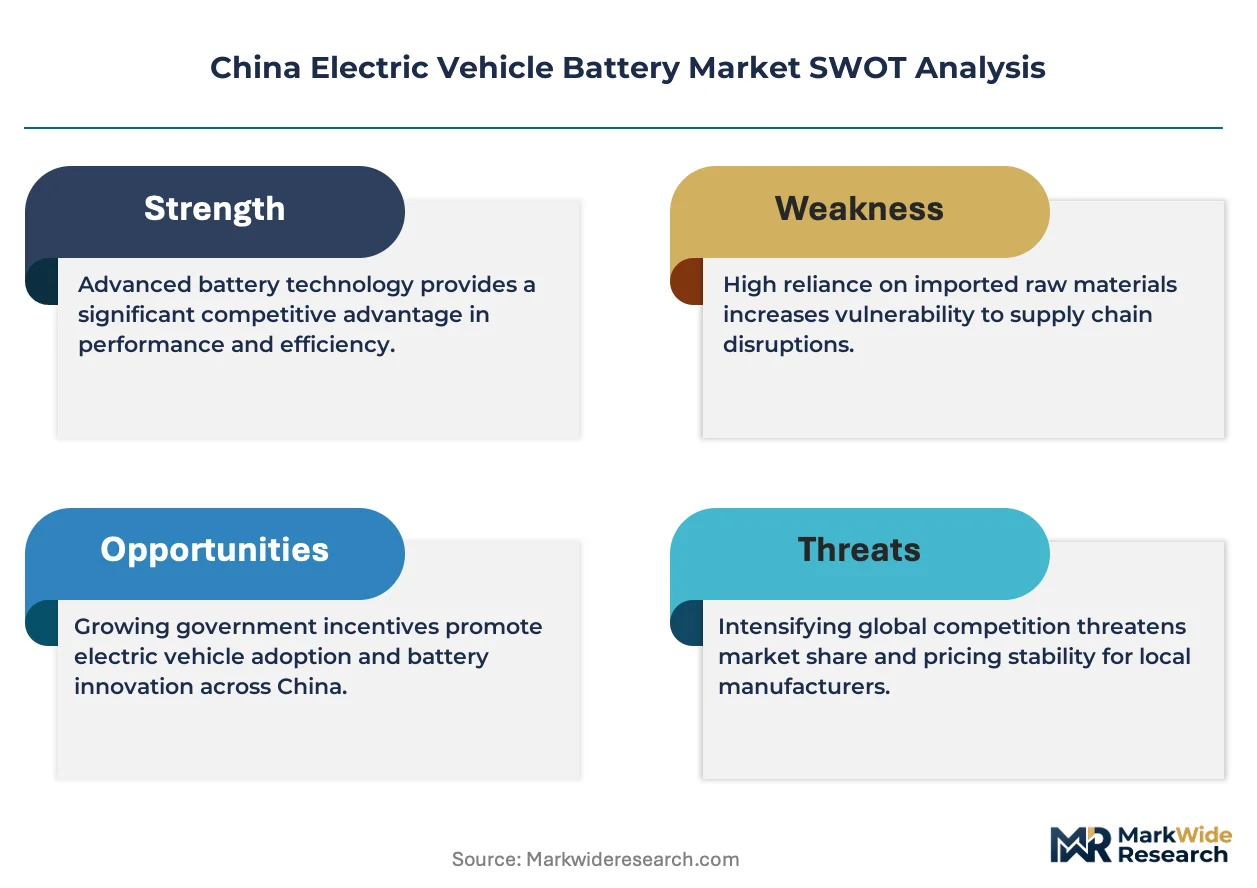
The Ningbo-Zhoushan Port anchors East China's cathode precursor import capacity, processing Australian spodumene concentrate and Indonesian nickel matte for Yangtze River Delta cell plants. This maritime infrastructure underwrites the region's battery manufacturing dominance.
Yangtze River Delta
Shanghai-Ningbo corridor concentrates cell winding and module assembly within 200 kilometers. MIIT energy density mandates force cathode active material upgrades across tier-one suppliers. Ningbo hosts separator film production facilities serving CATL and BYD supply agreements.
Pearl River Delta
Shenzhen-Dongguan electronics manufacturing base feeds battery management system component demand. SAMR monitors market concentration as cell supply consolidates among regional assemblers. Guangzhou anchors commercial vehicle platform deployment with dedicated swapping infrastructure.
Beijing-Tianjin-Hebei
Capital region fleet electrification drives procurement of long-range packs for ride-hailing platforms. NMPA battery safety certification timelines extend qualification cycles for new cell geometries. Tianjin port handles electrolyte additive imports from Japanese specialty chemical suppliers.
Sichuan-Chongqing
Western lithium belt hosts spodumene mining and salt lake brine extraction for regional cathode plants. MEE environmental compliance rules tighten wastewater discharge standards for precursor refining. Chengdu assembles cells for two-wheeler and industrial storage applications.
Shandong Peninsula
Qingdao and Yantai ports facilitate nickel intermediate imports from Indonesian processing facilities. GB standards enforcement through provincial quality inspection bureaus propagates thermal runaway testing protocols. Weihai hosts electrode coating equipment manufacturing for domestic cell lines.
China Electric Vehicle Battery Market Key Industry Players
Concentration sits with integrated cell-to-pack specialists and captive vehicle producers. The vendor base compresses around three strategic archetypes: vertically integrated automakers controlling upstream cell production, independent cell suppliers serving multiple OEM frameworks, and module assemblers competing on cost-optimized busbar designs. Dominant competitive moves include backward integration into cathode precursor refining and capacity expansion across Yangtze River Delta manufacturing corridors.
Among China-based producers, CATL, BYD, and Gotion occupy distinct archetype positions. CATL exemplifies the independent cell supplier model through multi-OEM framework agreements. BYD represents captive vertical integration with in-house lithium iron phosphate production and proprietary vehicle deployment. Gotion sits within the cost-optimized tier, supplying commercial vehicle platforms with standardized module architectures. These three anchors illustrate how competitive positioning splits between energy density leadership, supply chain control, and commercial vehicle cost engineering.
| Leading Market Players |
|---|
| CATL |
| BYD |
| CALB |
| Gotion |
| EVE Energy |
| Sunwoda |
| SVOLT Energy Technology |
| Lishen Battery |
| China Aviation Battery |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between Yangtze River Delta cell producers and fleet operators lock in cathode precursor supply visibility while fixing lithium carbonate exposure at quarterly reset clauses. This contract structure binds price predictability to raw material access across multi-year procurement horizons.
Pricing Analysis
Volume-discount tiering separates CATL and BYD framework agreements from spot-market module transactions. Three-tier pricing structure across premium, standard, and economy levels stratifies by NMPA certification grade and cycle-life warranty duration. Cost compression in commercial vehicle LFP cells is intensifying because Gotion and second-tier suppliers compete on busbar-optimized designs. Fleet operators exhibit highest price sensitivity through energy-service contracting, while passenger OEMs absorb premium nickel-rich cathode costs for energy density leadership.
Supply Chain Analysis
Australia and Indonesia anchor spodumene concentrate and nickel matte production feeding Ningbo-Zhoushan Port refining operations. Jiangsu and Fujian provinces concentrate qualified separator film and fluorinated electrolyte additive output. Single-source vulnerability propagates from Jiangsu separator facilities through multiple pack assembler schedules. Distribution runs through Yangtze River Delta manufacturing corridors direct to OEM assembly plants and fleet operator swapping stations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MIIT energy density mandates and solid-state pilot commitments create dual-technology inflection, compressing lithium-ion margin windows while opening certification pathways for next-generation architectures.
For Market Incumbents: Shield cathode precursor supply through backward integration into Australian spodumene offtake and Indonesian nickel processing. Accelerate NMPA certification timelines for cell-to-pack geometries to defend against solid-state pilot lines qualifying ahead of volume thresholds. Capacity addition in Sichuan-Chongqing lithium belt secures regional feedstock independence from coastal import congestion. For New Entrants and Emerging Players: Lead with commercial vehicle battery swapping infrastructure in fixed-route municipal bus and heavy-duty truck segments. Target energy-service contracting models that unbundle pack ownership from vehicle acquisition, bypassing capital-intensive OEM qualification cycles. White-space exists in black mass recycling and cathode precursor recovery under MIIT traceability mandates. For Investors and Strategic Acquirers: Capital is best deployed toward solid-state pilot line specialists with NMPA certification pathway positioning. Long-term viability across the analysis window hinges on electrolyte deposition equipment ownership and sulfide electrolyte synthesis capability. Watch for thermal runaway propagation test protocol amendments as inflection signal for cell geometry redesign cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Pack Architecture Deployment | Eliminates module housings and shifts engineering liability from automakers to CATL and BYD. |
| Cathode Precursor Backward Integration | Locks spodumene concentrate supply through Australian hard-rock mine offtake agreements. |
| Solid-State Pilot Line Investment | Positions suppliers for NMPA certification ahead of MIIT volume mandates for post-lithium-ion transition. |
| Battery Swapping Infrastructure Buildout | Enables energy-service contracting models for commercial vehicle fleet operators in Yangtze River Delta. |
| Black Mass Recycling Compliance | Builds closed-loop feedstock access for second-life cathode material under MIIT traceability rules. |
Research Approach
Findings reconcile primary fieldwork against secondary review of MIIT policy filings, NMPA certification databases, and Yangtze River Delta customs trade records. Cell producer procurement directors, fleet operator energy managers, and cathode precursor refining executives provided operational data. OEM platform engineers and separator film technical directors supplied manufacturing-stage intelligence. Bottom-up cell shipment tallies triangulate against top-down NEV subsidy registry analysis.
Segmentation dimensions modeled span battery chemistry, vehicle usage type, manufacturing stage, and power rating across the projection horizon. CAGRs derive from installed capacity buildout trajectories and fleet electrification procurement schedules. Inputs incorporate MIIT energy density mandate compliance timelines and NMPA thermal runaway test protocol evolution throughout the forecast period.
The analysis sits within stated boundaries; outcomes outside sustained lithium carbonate price stability or accelerated solid-state commercialization would require recalibration. Forecasts reflect assumptions on cathode active material cost pass-through elasticity and separator supply concentration persistence. Recalibration cycles align with material shifts in MIIT subsidy eligibility thresholds and GB standards enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
South Korea Electric Vehicle Battery Market
EV Batteries
United States Electric Vehicle Battery Manufacturing Market
EV Batteries
Electric Vehicle Battery Market
EV Batteries
Canada EV Battery Pack Market
EV Batteries
Traction Battery Market
EV Batteries
China Electric Vehicle Battery Materials Market
EV Batteries
Europe Electric Vehicle Battery Electrolyte Market
EV Batteries
Cobalt Powder for EV Battery Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Manufacturing Market
EV Batteries
Auto Storage Battery Market
EV Batteries
Automotive Rechargeable Battery Market
EV Batteries
Middle-East and Africa Electric Vehicle Battery Anode Market
EV Batteries
India EV Battery Pack Market
EV Batteries
Europe Electric Bus Battery Pack Market
EV Batteries
UK EV Battery Pack Market
EV Batteries
United States Electric Vehicle Battery Materials Market