
 Italy Electric Vehicle Battery Manufacturing Equipment Market | 2026-2036
Italy Electric Vehicle Battery Manufacturing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Electric Vehicle Battery Manufacturing Equipment Market Insights
High-precision assembly tolerances is unwinding legacy equipment depreciation cycles across Italian battery production lines. Manz AG leverages its laser-welding automation to anchor European cathode-film processing demand. Sovema Group sustains its position through specialized formation-and-testing systems for pouch-cell architectures. Durr AG competes on dry-electrode coating equipment, a process route that reduces solvent handling costs for domestic manufacturers.
Italy Electric Vehicle Battery Manufacturing Equipment encompasses machinery for electrode coating, cell stacking, electrolyte filling, formation cycling, and end-of-line validation, with critical specifications including micron-level alignment accuracy and cleanroom-compatible enclosures. The primary purpose is enabling repeatable, high-throughput production of lithium-ion and solid-state cells for automotive traction batteries. Assembly Equipment occupies the largest margin pool due to its integration complexity across stacking and welding subsystems, while Testing Equipment records the fastest expansion as Italian OEMs tighten in-process quality gates. Solid-state technology segments attract premium equipment pricing despite longer qualification timelines, reflecting automaker risk mitigation against thermal-runaway liabilities.
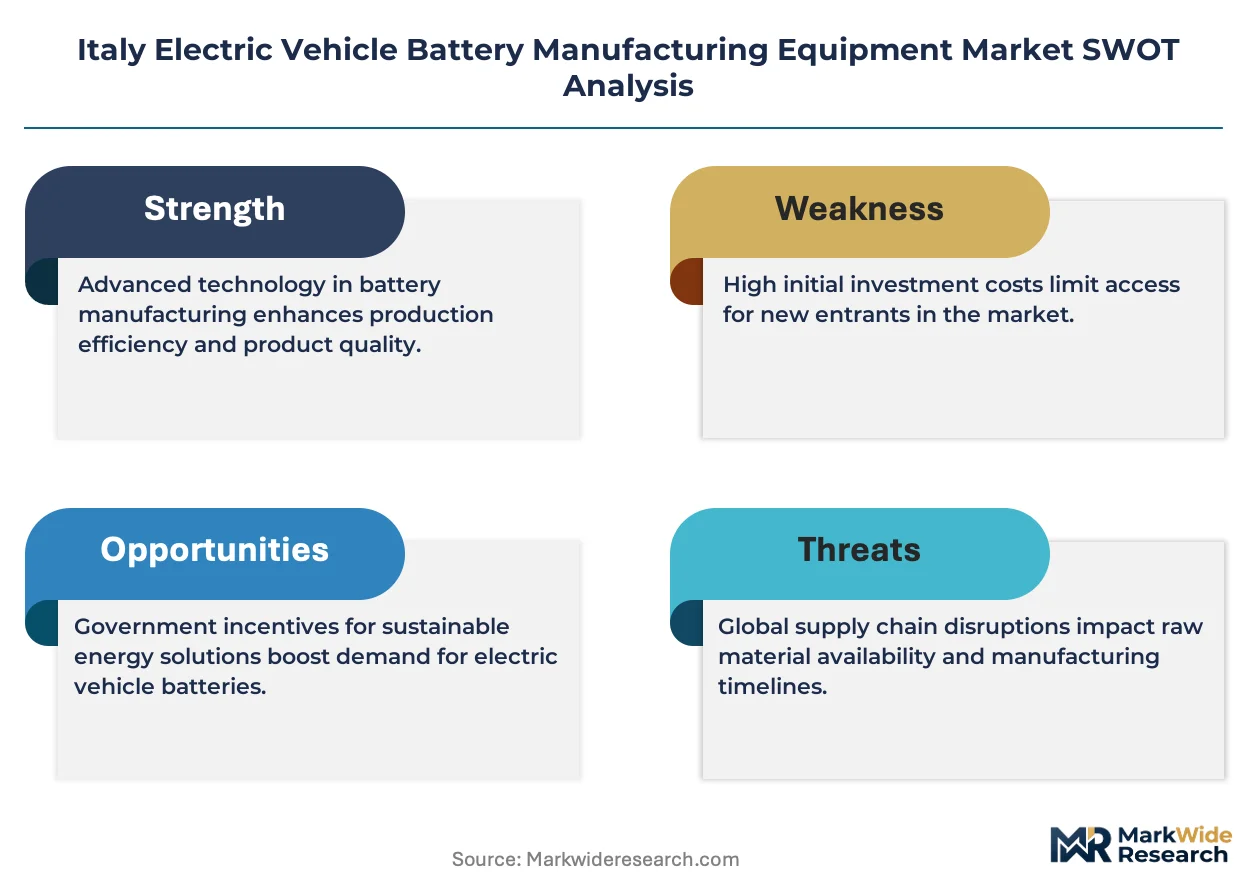
Italy's national alignment with EU Battery Regulation, CE marking requirements, and REACH chemical compliance frameworks compels equipment vendors to certify solvent-recovery systems and document supply-chain due diligence. The Italian Ministry of Enterprise and Made in Italy (MIMIT) coordinates with ECHA guidelines to localize cathode-active-material processing equipment. Stakeholders must monitor how Rome's implementation of EU critical-raw-materials stockpiling mandates reshapes equipment sizing for precursor-handling lines.
Market Dynamics
The EU Battery Regulation's recycled-content mandates and carbon-footprint declarations are forcing Italian equipment vendors to redesign coating and formation systems for traceable, low-solvent production pathways. This regulatory compression is accelerating depreciation cycles across Turin and Milan production corridors.
Growth Catalysts
- CE marking alignment:Equipment vendors certifying cleanroom-compatible enclosures gain preferential access to Stellantis gigafactory-adjacent tooling ecosystems in Piedmont.
- Solid-state chemistry transition:Automaker risk mitigation against thermal-runaway liabilities drives premium equipment pricing for dry-electrode coating and solid-electrolyte handling systems.
- Turin-Milan corridor concentration:Domestic OEM scaling of pouch-cell and prismatic-cell lines creates localized demand spikes for laser-welding automation and formation-cycling infrastructure.
Market Restraints
- Specialized component import dependence:High-precision motion controllers and vacuum-chamber subsystems concentrate supply in German and Japanese vendor bases, exposing Italian integrators to currency volatility and extended lead times.
- REACH solvent-recovery compliance:Wet-electrode coating equipment faces retrofit costs or replacement cycles to meet ECHA documentation requirements for NMP solvent handling and recovery.
- Qualification timeline compression:Solid-state cell architectures require 18-24 month equipment validation cycles versus 8-12 months for conventional lithium-ion, delaying revenue recognition for domestic machinery vendors.
Strategic Opportunities
- Southern Italy industrial corridor development:MIMIT incentives for cathode-active-material processing equipment localization target Sicily and Calabria for precursor-handling line expansion beyond Northern concentration.
- Second-life battery disassembly equipment:EU Battery Regulation end-of-life mandates create emerging demand for automated dismantling and black-mass recovery systems serving Italian recycling operators.
- AI-driven predictive maintenance convergence:Machine-vision integration with formation-cycling data streams enables Italian vendors to offer throughput-guarantee service models displacing traditional maintenance contracts.
Industry Challenges
- Mechatronics talent scarcity:Micron-level alignment engineering and cleanroom automation programming skills concentrate in Emilia-Romagna and Lombardy, constraining vendor expansion capacity.
- Legacy PLC integration friction:Brownfield electrode-coating lines running on 1990s control architectures require custom gateway development to interface with modern MES and quality-gate systems.
- Dual certification burden:Equipment vendors must simultaneously satisfy ATEX explosion-protection directives for solvent-handling zones and IEC 61508 functional-safety standards for formation-cycling operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Electric Vehicle Battery Manufacturing Equipment Market |
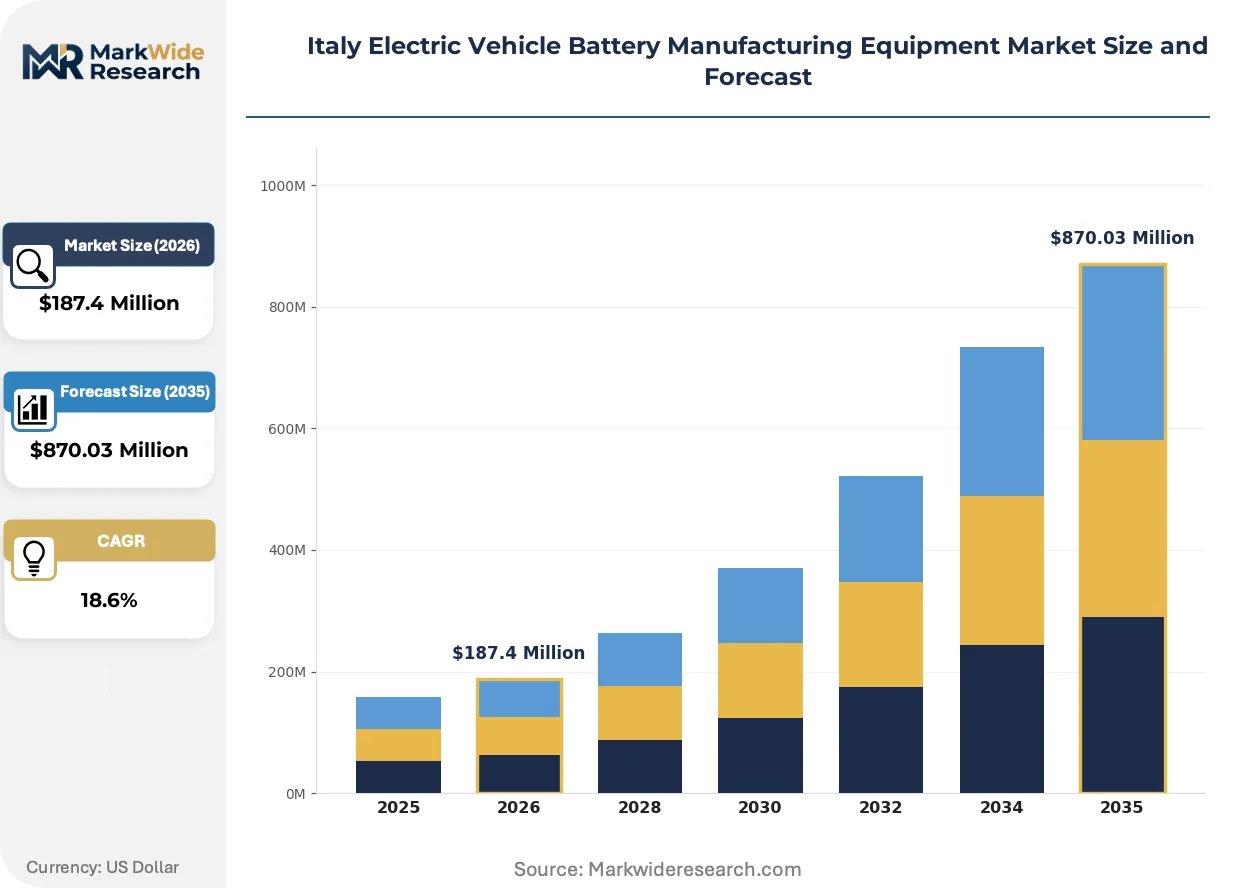
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Assembly Equipment, Testing Equipment, Charging Stations, Recycling Systems Technology: Lithium-ion, Solid-state, Lead-acid, Nickel-metal Hydride Capacity: Low Capacity, Medium Capacity, High Capacity, Ultra High Capacity End User: OEMs, Aftermarket Suppliers, Research Institutions, Battery Manufacturers |
| Companies Covered | Manz AG, Sovema Group, Durr AG, Hitachi Ltd, Xiamen Tmax Battery Equipments Limited, Hitachi High-Tech Corporation, Lead Intelligent Equipment Co., Ltd., ANDRITZ Schuler GmbH, Bühler Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Electric Vehicle Battery Manufacturing Equipment Market Trends and Innovations
Dry-electrode coating technology is compressing solvent-handling infrastructure requirements while AI-driven process control is embedding quality prediction directly into stacking and welding subsystems. Equipment footprints are shrinking to accommodate gigafactory density constraints.
Laser-welding automation for cathode-film processing is miniaturizing beam-delivery optics and solid-state laser sources to enable inline integration within compact cleanroom cells. Italian pouch-cell specialists in Milan are adopting these systems at 18-month replacement cycles versus historical 7-year depreciation schedules. The technology is miniaturizing equipment footprints by 40% while maintaining sub-10-micron alignment tolerances, allowing Stellantis suppliers to triple line density within existing facility envelopes.
ECHA's REACH enforcement on N-methyl-2-pyrrolidone solvent recovery is mandating closed-loop distillation systems on all new electrode-coating equipment purchases. Italian vendors must document supply-chain due diligence for precursor chemicals through tier-three suppliers. Wet-coating equipment segments face 15-20% cost inflation from stainless-steel reactor upgrades and continuous emissions monitoring integration, pushing domestic manufacturers toward dry-coating process routes.
Buyer consolidation around Stellantis and its tier-one cell suppliers is consolidating procurement authority into centralized technical committees in Turin. Equipment vendors now compete through total-cost-of-ownership guarantees rather than unit pricing, with performance bonds tied to line OEE thresholds. This shift is most visible in the Po Valley manufacturing belt, where three OEMs now specify identical formation-cycling platforms to simplify spare-pool management and operator cross-training protocols.
Italy Electric Vehicle Battery Manufacturing Equipment Market Segmentation
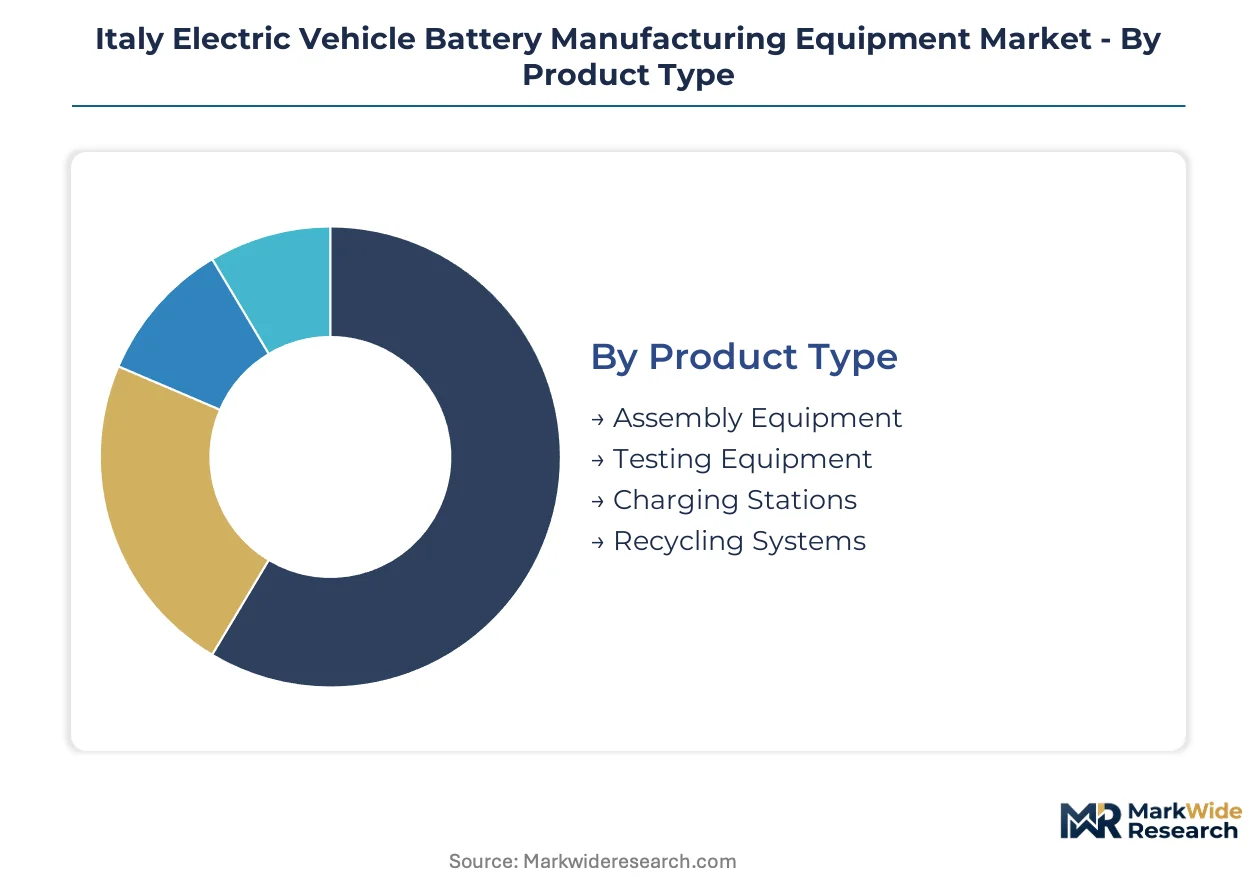
Equipment segmentation in the Italian battery manufacturing sector reveals how margin pools concentrate around integration complexity and regulatory compliance. Turin and Milan corridors drive divergent demand profiles across each category.
Product Type:
Assembly Equipment commands the deepest margin pools due to multi-subsystem integration requirements across stacking and welding operations.
- Assembly Equipment:Encompasses electrode stacking, tab welding, and cell sealing systems requiring sub-10-micron alignment precision. Stellantis suppliers in Piedmont are tripling line density within existing cleanroom footprints through miniaturized laser-welding automation.
- Testing Equipment:Formation cycling and end-of-line validation systems with embedded machine-vision quality prediction. Italian OEMs are tightening in-process quality gates fastest in this segment, compressing replacement cycles to 18 months.
- Charging Stations:Grid-integration hardware for production-floor fleet electrification serving battery plant logistics.
- Recycling Systems:Automated dismantling and black-mass recovery equipment responding to EU Battery Regulation end-of-life mandates.
The dominant share belongs to Assembly Equipment, while Testing Equipment is closing the gap fastest.
Technology:
Process chemistry determines equipment qualification timelines and capital deployment patterns across Italian production corridors.
- Lithium-ion:Wet-electrode coating and electrolyte filling systems dominate current installed base. REACH compliance on N-methyl-2-pyrrolidone recovery is forcing 15-20% cost inflation through stainless-steel reactor upgrades.
- Solid-state:Dry-electrode coating and solid-electrolyte handling command premium pricing despite 18-24 month validation cycles. Automaker risk mitigation against thermal-runaway liabilities sustains vendor margins.
- Lead-acid:Mature formation infrastructure serving industrial battery niches with minimal growth traction.
- Nickel-metal Hydride:Legacy hybrid vehicle supply chain equipment with declining replacement demand.
Lithium-ion retains the largest installed base, though Solid-state is gaining share fastest through Stellantis supplier qualification programs.
Capacity:
Production scale tiers align with facility investment waves across Northern Italy's emerging gigafactory ecosystem.
- High Capacity:GWh-scale lines serving Stellantis and tier-one cell suppliers in Turin-Milan corridor. Equipment footprints are shrinking 40% to accommodate gigafactory density constraints while maintaining throughput.
- Medium Capacity:Pilot and scale-up lines for next-generation chemistry validation. Research institutions in Lombardy deploy these for solid-state process development.
- Low Capacity:Laboratory and prototype equipment with limited commercial scale.
- Ultra High Capacity:Next-generation terafactory-scale tooling still in vendor development pipelines.
High Capacity equipment absorbs the majority of current capital deployment, while Medium Capacity lines are expanding most quickly for solid-state qualification.
End User:
Procurement authority concentration shapes vendor competitive dynamics and contract structures across the Italian market.
- OEMs:Stellantis technical committees in Turin centralize specification authority, shifting vendor competition toward total-cost-of-ownership guarantees tied to line OEE thresholds.
- Battery Manufacturers:Domestic cell producers building gigafactory-adjacent tooling ecosystems with standardized formation-cycling platforms to simplify spare-pool management.
- Aftermarket Suppliers:Second-life battery processing equipment demand emerging from EU Battery Regulation recycling mandates.
- Research Institutions:Pilot-line equipment for cathode-active-material processing development, particularly in Emilia-Romagna mechatronics clusters.
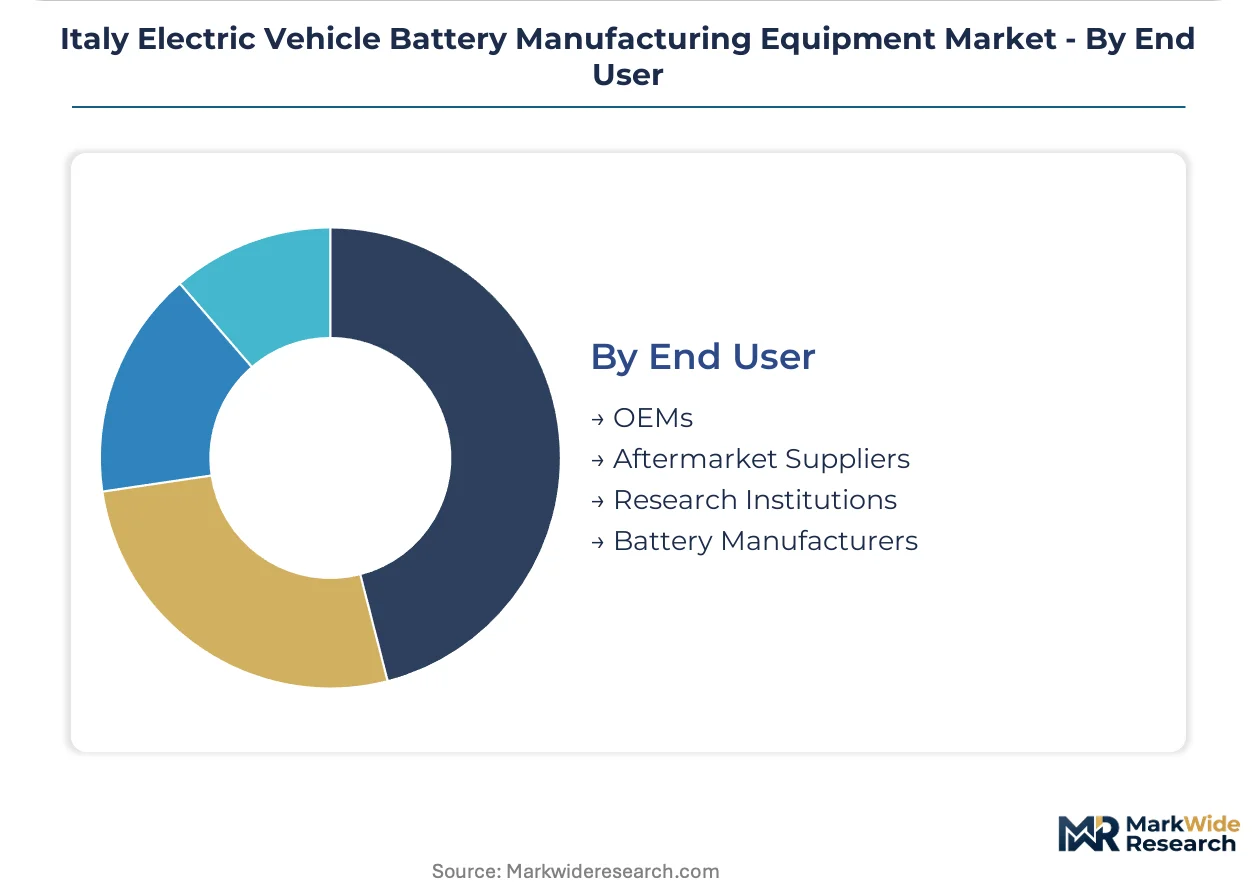
OEMs control the largest procurement volume, while Battery Manufacturers are scaling fastest as domestic cell production capacity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's battery equipment trade balance tilts toward import dependence for high-precision motion controllers and vacuum subsystems, while domestic integrators build exportable expertise in formation-cycling platforms and laser-welding automation serving Southern European cell producers.
Lombardy
Milan anchors pouch-cell tooling demand from Stellantis tier-one suppliers deploying miniaturized cleanroom automation. CE marking alignment for cleanroom-compatible enclosures accelerates vendor certification timelines under EU machinery directives. Research institutions in the Po Valley deploy medium-capacity pilot lines for solid-state process development, compressing equipment validation cycles.
Piedmont
Turin concentrates procurement authority through Stellantis technical committees specifying total-cost-of-ownership guarantees tied to line OEE thresholds. The EU Battery Regulation's carbon-footprint declarations reshape coating equipment specifications for gigafactory-adjacent tooling ecosystems. Domestic suppliers triple line density within existing facility envelopes through laser-welding automation miniaturization.
Emilia-Romagna
Mechatronics engineering talent clusters here constrain vendor expansion capacity across micron-level alignment disciplines. REACH solvent-recovery compliance forces wet-electrode coating retrofits or replacement cycles for legacy installed base. Bologna-Modena industrial corridors host specialized programming expertise for cleanroom automation integration.
Sicily
MIMIT incentives target cathode-active-material processing equipment localization beyond Northern concentration. ECHA documentation requirements for precursor-handling lines reshape equipment sizing for critical-raw-materials stockpiling mandates. Catania-Palermo corridors attract precursor-handling line investments serving Mediterranean battery supply chains.
Italy Electric Vehicle Battery Manufacturing Equipment Market Competitive Landscape
Listed leaders compete with private specialists across equipment integration complexity, with publicly traded German and Swiss automation conglomerates facing off against Italian family-owned tooling fabricators. The vendor base stratifies into three tiers: multinational system integrators commanding turnkey line contracts, regional specialists dominating formation-and-testing subsystems, and emerging Asian equipment exporters penetrating cost-sensitive segments. Two archetypes dominate: precision-mechanics specialists from Central Europe and battery-process integrators from East Asia. Competitive moves concentrate on geographic licensing partnerships and backward integration into control software stacks.
Among German-listed automation conglomerates, Manz AG and Durr AG exemplify the precision-mechanics archetype, occupying positions in laser-welding and dry-electrode coating segments respectively. Sovema Group, a private Italian specialist, anchors the regional-integrator tier through formation-system expertise. These three represent divergent strategic postures: multinational scale versus domestic process intimacy versus hybrid Asia-Europe sourcing models.
| Leading Market Players |
|---|
| Manz AG |
| Sovema Group |
| Durr AG |
| Hitachi Ltd |
| Xiamen Tmax Battery Equipments Limited |
| Hitachi High-Tech Corporation |
| Lead Intelligent Equipment Co., Ltd. |
| ANDRITZ Schuler GmbH |
| Bühler Group |
| Others |
Pricing and Supply Chain Analysis
Dry-electrode coating substitution for wet-coating processes simultaneously shifts equipment sourcing toward German and Swiss precision-mechanics vendors while compressing pricing premiums previously commanded by solvent-recovery system integrators. This chemistry transition rewires both supply geography and buyer negotiation leverage across Italian production corridors.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on CE marking alignment and cleanroom certification grade, with Stellantis technical committees demanding total-cost-of-ownership guarantees. Cost compression in standard-tier formation equipment is intensifying because of Asian vendor penetration. Aftermarket service bundling separates premium pricing from standard tiers, while unbranded component suppliers face acute price sensitivity.
Supply Chain Analysis
Extended lead times for high-precision motion controllers and vacuum-chamber subsystems signal supply chain stress across Italian integrators. Manufacturing concentrates in Germany, Japan, and South Korea for these critical components. Raw material dependencies span rare-earth magnets, precision-ground ball screws, and ceramic-coated vacuum chambers. Single-source vulnerability runs through Japanese motion-control specialists. Distribution runs through regional system integrators serving Turin-Milan gigafactory clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Italy battery equipment market sits at a platform-economics inflection where interoperability between formation-cycling data streams and MES layers determines vendor survival. Stellantis supplier qualification programs are consolidating procurement authority into unified technical ecosystems.
For Market Incumbents: Compound defensive positioning through backward integration into control software stacks and captive service networks. Laser-welding specialists must lock in long-term platform engineering contracts with Stellantis before Asian vendors achieve CE marking parity. Dry-electrode coating expertise represents the priority certification investment. For New Entrants and Emerging Players: Differentiate on AI-driven predictive maintenance convergence serving medium-capacity pilot lines in Lombardy research institutions. Southern Italy cathode-active-material processing equipment offers the most penetrable geography. A throughput-guarantee service model displaces traditional maintenance contracts as the go-to-market angle. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision-mechanics specialists with cleanroom automation programming capabilities. Long-term viability over the next decade hinges on solid-state chemistry qualification timelines. Acquisition targets should demonstrate tier-three supply-chain due diligence documentation. The signal to watch is Stellantis technical committee specification shifts toward dry-coating process routes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Control Software | Enables Italian vendors to displace German system integrators in Stellantis formation-cycling contracts. |
| CE Marking Alignment Investment | Accelerates vendor access to Turin-Milan gigafactory-adjacent tooling ecosystems under EU machinery directives. |
| AI-Driven Predictive Maintenance Platform | Allows equipment vendors to offer throughput-guarantee service models replacing traditional maintenance contracts. |
| Southern Italy Manufacturing Localization | Captures MIMIT incentives for cathode-active-material processing equipment beyond Northern concentration. |
| Solid-State Chemistry Qualification Partnership | Positions vendors for premium equipment pricing as automakers mitigate thermal-runaway liabilities. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with equipment procurement managers at Stellantis tier-one suppliers, cleanroom automation programming specialists in Emilia-Romagna, formation-system engineering leads, and MIMIT industrial policy officials. Secondary validation drew from EU Battery Regulation implementation documents, ECHA REACH enforcement guidelines, SEC filings of listed German automation conglomerates, and Italian customs trade data. Bottom-up equipment shipment tallies and top-down gigafactory investment pipeline estimates were triangulated.
Across the analysis window, the forecasting framework models equipment demand by product type, technology chemistry, capacity tier, and end-user procurement authority concentration. CAGRs were derived from segment-level investment trajectories and replacement cycle compression patterns. Forecast inputs include Stellantis gigafactory construction timelines and EU recycled-content mandate phase-in schedules.
The analysis sits within stated boundaries; outcomes outside continued Stellantis domestic cell production scaling or accelerated solid-state commercialization would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and supplier qualification timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
Europe Electric Bus Battery Pack Market
EV Batteries
Europe Electric Vehicle Solid State Battery Market
EV Batteries
Traction Battery Market
EV Batteries
India Electric Vehicle Battery Manufacturing Market
EV Batteries
United Kingdom Electric Vehicle Battery Manufacturing Market
EV Batteries
South America Electric Vehicle Battery Anode Market
EV Batteries
United States Electric Vehicle Battery Anode Market
EV Batteries
China Electric Vehicle Battery Materials Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Materials Market
EV Batteries
Middle-East and Africa Electric Vehicle Battery Anode Market
EV Batteries
Cold-Climate Optimized EV Battery Systems Market
EV Batteries
Canada Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Electric Vehicle Traction Batteries Market
EV Batteries
South America Electric Vehicle Battery Manufacturing Market
EV Batteries
South America Electric Vehicle VRLA Batteries Market
EV Batteries
European EV Battery Systems Market