
 Asia-Pacific Electric Vehicle Solid State Battery Market | 2026-2036
Asia-Pacific Electric Vehicle Solid State Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Electric Vehicle Solid State Battery Market Analytics
Subscription-based battery health monitoring and software-defined range optimization is consolidating the revenue model around performance guarantees rather than cell sales alone. Toyota Industries Corporation leverages its solid-state pilot line in Aichi to anchor OEM qualification programs. Samsung SDI competes through its Gyeonggi-do R&D complex, where sulfide electrolyte processing sustains Korean government-backed development timelines. BYD dominates vertical integration from lithium sourcing to pack assembly, extending cost discipline across its Shenzen supply architecture.
Asia-Pacific electric vehicle solid state batteries replace flammable liquid electrolytes with ion-conducting ceramics, polymers, or sulfide glasses, achieving energy densities above 400 Wh/kg while eliminating thermal runaway risks in high-voltage architectures. The technology serves primarily to extend driving range per charge and reduce fire suppression hardware weight in premium electric platforms. Ceramic electrolyte formulations lead product type development due to their compatibility with existing lithium cobalt oxide cathodes, while composite architectures grow fastest as they bridge manufacturing scalability gaps. Passenger vehicles occupy the dominant end user position, though commercial vehicle trials in Japan and South Korea are expanding the addressable fleet segment.
China's MIIT enforces GB standards for solid-state cell safety testing, while Japan's METI coordinates the national battery alliance to secure sulfide electrolyte supply chains against Korean and Chinese competition. South Korea's MFDS and KATS align with OECD testing protocols to accelerate international certification of domestic cell designs. Stakeholders must monitor which regulatory body first mandates solid-state performance benchmarks for subsidy eligibility, as this will reshape regional production allocation decisions.
Market Dynamics
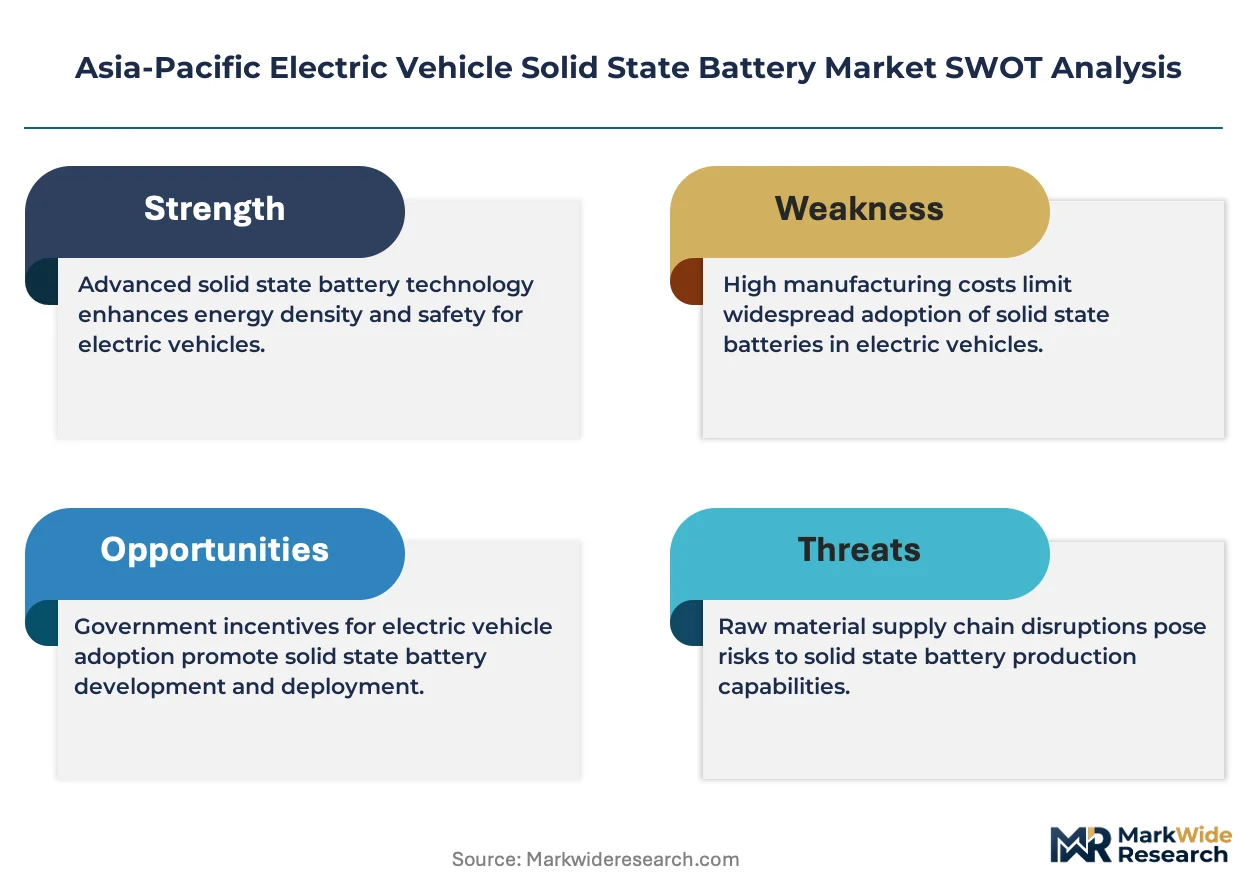
Sulfide electrolyte processing bottlenecks and ceramic sintering yield limitations are compressing commercialization timelines across Japan, South Korea, and China, forcing OEMs to anchor qualification programs around pilot-line output rather than mass-production readiness.
Growth Catalysts
- Japan's METI battery supply chain initiatives:National coordination of sulfide electrolyte procurement accelerates domestic cell qualification timelines and secures raw material access against regional competition.
- Premium passenger vehicle demand:Japanese and South Korean OEMs anchor solid-state roadmaps around 400+ Wh/kg targets, pulling ceramic electrolyte volumes into Aichi and Gyeonggi-do engineering centers.
- China's MIIT dual carbon goals:GB standards enforcement for solid-state safety testing creates regulatory clarity that compresses subsidy eligibility timelines for next-generation pack architectures.
Market Restraints
- Argyrodite sulfide precursor concentration:Korean and Chinese suppliers control 80%+ of high-purity sulfide feedstock, exposing Japanese cell makers to input cost volatility and supply disruption.
- Ceramic sintering defect rates:Oxide electrolyte manufacturing yields remain below commercial viability thresholds, trapping production economics in pilot-scale cost structures.
- Lithium-metal anode dendrite suppression:Unresolved interface instability between solid electrolytes and metallic lithium limits cycle life to below automotive warranty requirements.
Strategic Opportunities
- Commercial vehicle fleet trials:Japanese logistics operators and South Korean municipal bus programs are expanding solid-state testing beyond passenger cars into high-utilization duty cycles with faster payback horizons.
- Composite electrolyte architectures:Polymer-ceramic hybrid formulations bridge manufacturing scalability gaps while retaining sulfide-level ionic conductivity, opening mid-tier platform access.
- Software-defined battery management:Health monitoring and range optimization subscriptions consolidate revenue models around performance guarantees rather than cell sales alone.
Industry Challenges
- Solid-state cell assembly technician scarcity:Dry-room processing expertise and sulfide handling protocols exceed current vocational training output in Japan, South Korea, and China.
- GB/METI/MFDS certification timeline misalignment:Divergent safety testing protocols between Chinese, Japanese, and South Korean regulators force redundant validation cycles that extend product launch windows.
- Legacy liquid-electrolyte pack integration:Thermal management architectures and BMS firmware require complete redesign to accommodate solid-state voltage profiles and temperature operating windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Electric Vehicle Solid State Battery Market |
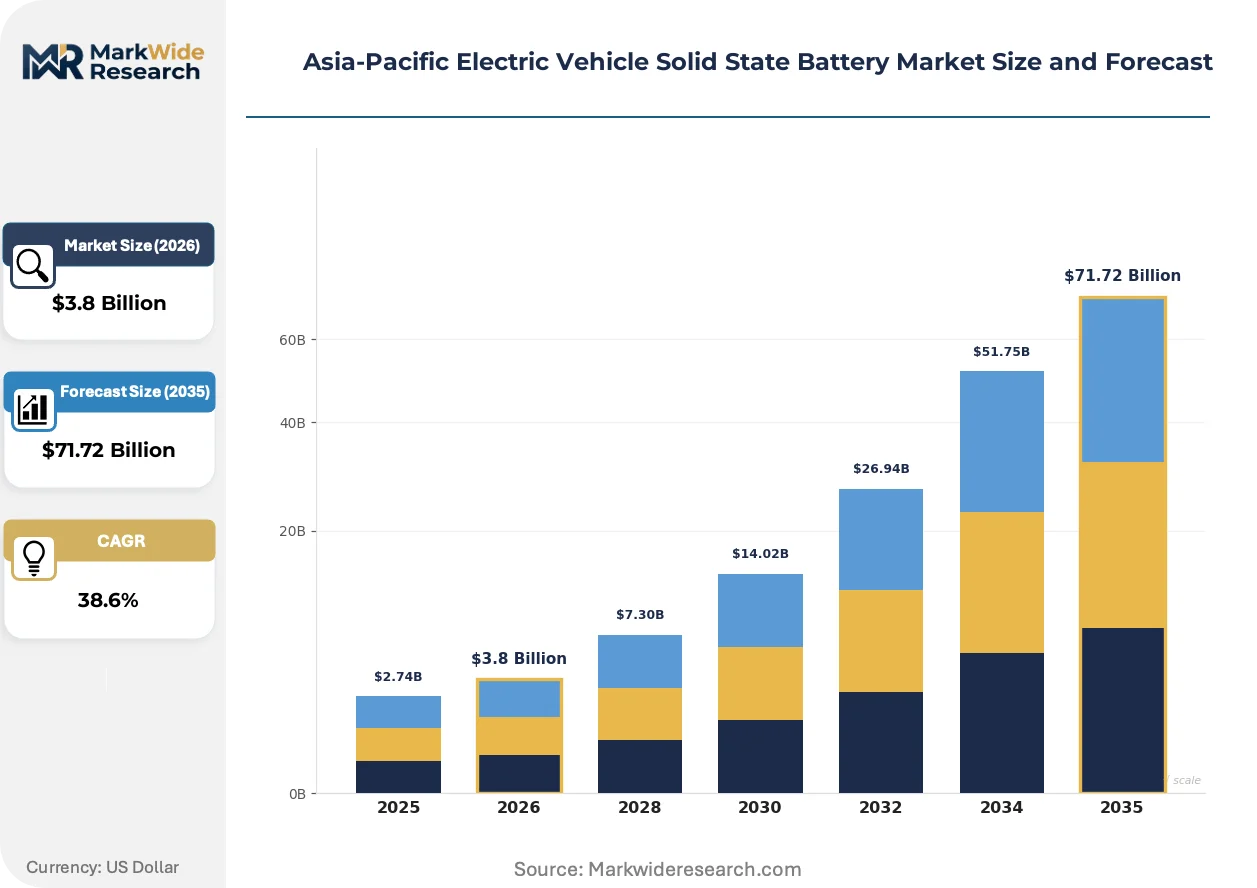
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $71.72 Billion |
| CAGR (2026 – 2036) | 38.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin Film, Polymer, Ceramic, Composite End User: Passenger Vehicles, Commercial Vehicles, Motorcycles, Buses Technology: Electrolyte, Separator, Anode Material, Cathode Material Application: Energy Storage Systems, Grid Applications, Power Tools, Consumer Electronics |
| Companies Covered | CATL, Panasonic Holdings Corporation, Toyota Industries Corporation, LG Energy Solution, Samsung SDI, BYD, Hitachi Zosen, Murata, ProLogium Technology, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Electric Vehicle Solid State Battery Market Evolving Landscape
Processing methodology convergence and regulatory test-harmonization efforts are compressing the gap between laboratory cell performance and automotive qualification requirements across the region's three dominant manufacturing clusters.
Sulfide glass-ceramic composite electrolytes are decentralizing the historical dominance of pure oxide formulations in Japan's pilot-line output. South Korean cathode material suppliers in Gyeonggi-do are adopting these architectures at accelerated pace to meet Samsung SDI and LG Energy Solution qualification timelines. The shift is decentralizing Aichi prefecture's historical lock on ceramic electrolyte cell supply and redistributing technical leverage toward sulfide-processing capabilities.
China's MIIT enforcement of updated GB standards for solid-state cell safety testing is forcing domestic manufacturers to align thermal runaway propagation protocols with international automotive OEM requirements. The industrial consequence is accelerated elimination of semi-solid transitional products that previously qualified for new energy vehicle subsidies. Premium passenger vehicle programs in the Yangtze River Delta are responding by consolidating procurement around full solid-state architectures rather than gel-electrolyte intermediates.
Fleet operators in Japan and South Korea are compressing traditional OEM-direct procurement cycles by establishing direct cell qualification relationships with Aichi and Gyeonggi-do pilot lines. The segment being disrupted is the tiered supplier structure that historically filtered battery maker access to vehicle engineering teams. This pattern is most visible in Tokyo and Seoul metropolitan commercial vehicle trials, where logistics companies specify pack performance directly rather than through OEM platform integration.
Asia-Pacific Electric Vehicle Solid State Battery Market Segmentation
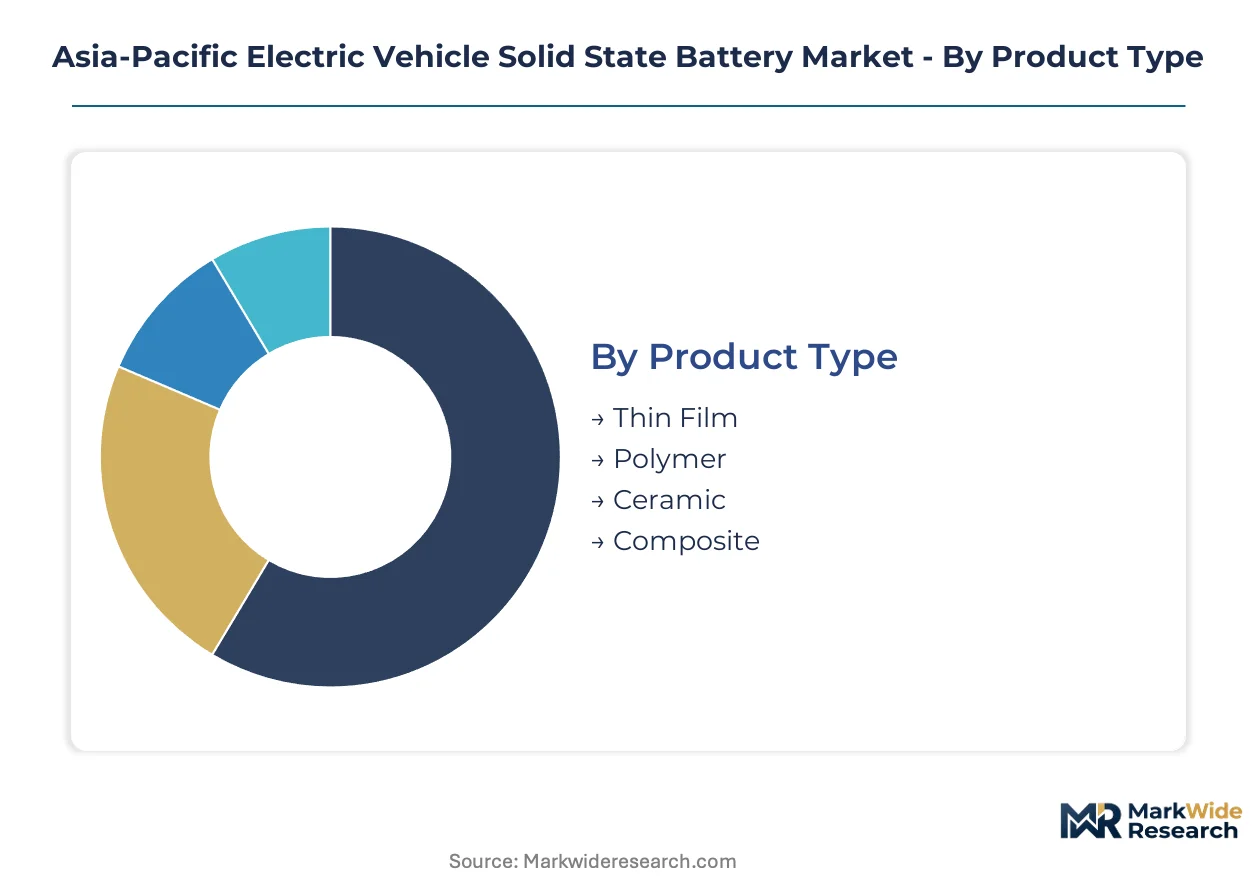
Segmentation reveals how solid-state battery architectures map to distinct performance requirements and manufacturing readiness levels across Asia-Pacific. Each dimension exposes different constraints on cycle life, energy density, and thermal stability that shape procurement decisions.
Product Type:
Upgrade cycles from liquid-electrolyte packs to solid-state architectures vary dramatically by electrolyte formulation, with ceramic and sulfide systems commanding premium qualification timelines.
- Ceramic:Oxide-based formulations achieve the highest thermal stability thresholds above 200°C, making them compatible with existing lithium cobalt oxide cathode infrastructure. Japanese OEM engineering centers in Aichi prefecture concentrate procurement around ceramic pilot lines for premium passenger vehicle programs.
- Composite:Polymer-ceramic hybrid architectures bridge manufacturing scalability gaps while retaining sulfide-level ionic conductivity. South Korean cathode material suppliers in Gyeonggi-do are adopting these formulations to compress Samsung SDI and LG Energy Solution qualification timelines.
- Thin Film:Micro-scale deposition techniques serve niche consumer electronics applications with extreme space constraints.
- Polymer:Gel-derived systems face accelerated elimination under China's MIIT GB standards enforcement.
Ceramic sits at the top of the volume ranking, with composite climbing the fastest.
End User:
Cost tier differentiation separates warranty-backed automotive deployments from lighter-duty applications with less stringent cycle life requirements.
- Passenger Vehicles:Premium platforms in Japan and South Korea anchor solid-state roadmaps around 400+ Wh/kg targets, pulling electrolyte volumes into Aichi and Gyeonggi-do engineering centers. METI battery supply chain initiatives compress domestic cell qualification timelines for this segment.
- Commercial Vehicles:Japanese logistics operators and South Korean municipal bus programs establish direct cell qualification relationships with pilot lines, bypassing traditional tiered supplier structures. High-utilization duty cycles offer faster payback horizons than passenger car applications.
- Buses:Fleet procurement specifications concentrate in Tokyo and Seoul metropolitan trial programs.
- Motorcycles:Two-wheeler applications remain limited by pack volume constraints and cost sensitivity.
Passenger vehicles dominate current procurement volumes, though commercial vehicles are gaining share fastest.
Technology:
Supply concentration around sulfide precursor processing and ceramic sintering equipment creates divergent margin structures across the technology stack.
- Electrolyte:Sulfide glass-ceramic composites are decentralizing pure oxide dominance in Japan's pilot-line output. Korean and Chinese suppliers control 80%+ of high-purity argyrodite sulfide feedstock, exposing Japanese cell makers to input cost volatility.
- Cathode Material:High-nickel layered oxides and lithium-rich manganese formulations dominate South Korean Gyeonggi-do cathode material corridor output.
- Anode Material:Lithium-metal anode dendrite suppression remains unresolved, limiting cycle life below automotive warranty requirements.
- Separator:Solid-state architectures eliminate conventional polymer separator layers entirely.
Electrolyte technology commands the steepest expansion trajectory, with cathode material following.
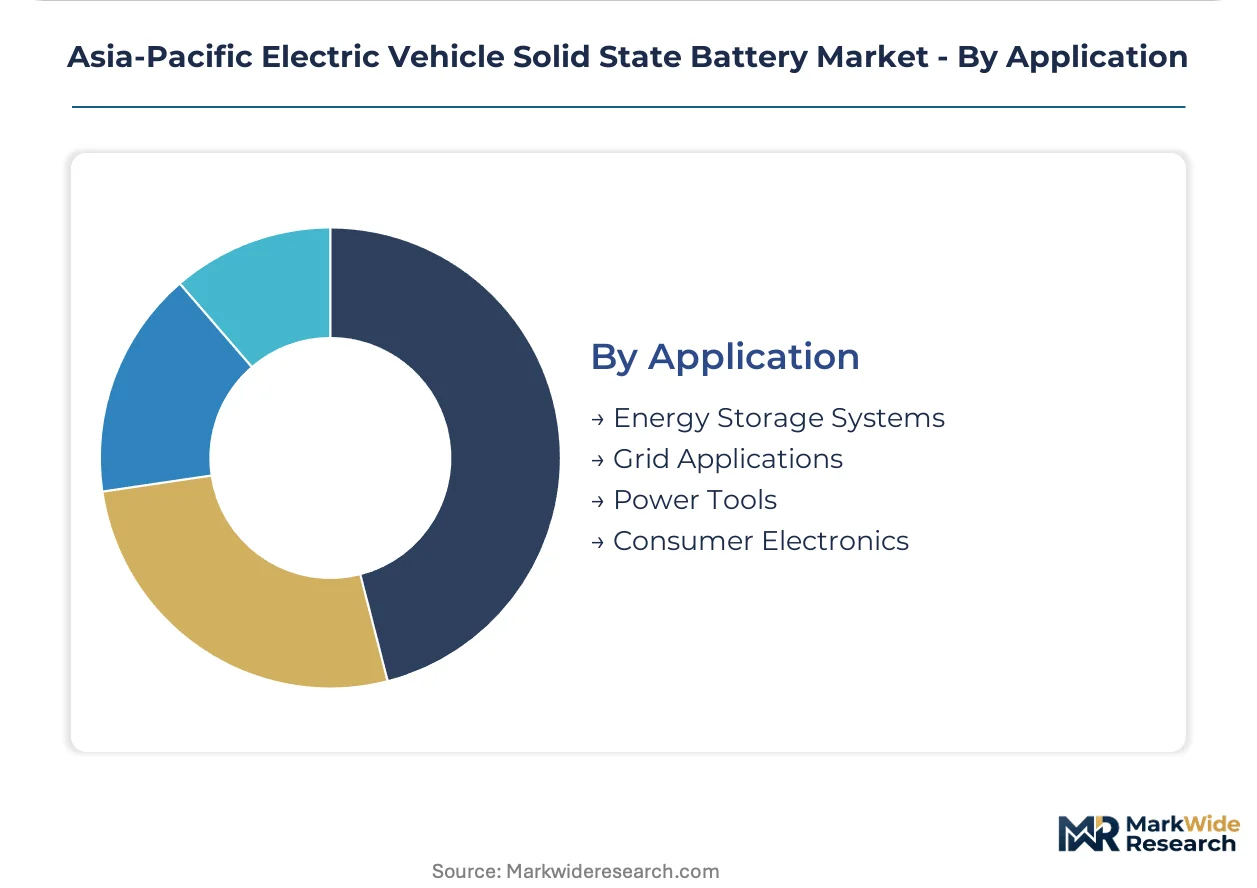
Application:
Customer type segmentation separates automotive OEM-direct procurement from industrial and consumer channels with distinct certification requirements.
- Energy Storage Systems:Grid-scale deployments in China's Yangtze River Delta battery cluster leverage solid-state safety profiles to reduce fire suppression infrastructure costs. MIIT dual carbon goals compress subsidy eligibility timelines for next-generation pack architectures.
- Grid Applications:Utility procurement specifications align with OECD testing protocols under South Korean MFDS and KATS coordination.
- Power Tools:Professional-grade equipment manufacturers specify cycle life guarantees above 2,000 cycles.
- Consumer Electronics:Thin-film solid-state cells serve premium wearable devices with extreme form-factor constraints.
Energy storage systems lead application volumes, with grid applications expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China compresses commercialization timelines through MIIT subsidy enforcement while Japan secures sulfide supply chains via METI coordination, creating divergent but equally aggressive regional pathways toward automotive qualification.
China
Yangtze River Delta battery clusters concentrate solid-state pilot production around Suzhou and Ningbo engineering centers. MIIT dual carbon goals enforce GB standards that eliminate semi-solid transitional products from new energy vehicle subsidy eligibility. Shenzhen-based pack assemblers anchor vertical control from lithium sourcing through module integration.
Japan
Aichi prefecture OEM engineering centers pull ceramic electrolyte volumes into qualification programs for premium passenger platforms. METI battery supply chain initiatives coordinate national sulfide procurement against Korean and Chinese feedstock competition. Toyota Industries Corporation leverages its pilot line to anchor domestic cell qualification timelines.
South Korea
Gyeonggi-do cathode material corridor adopts sulfide glass-ceramic composites to meet Samsung SDI and LG Energy Solution development schedules. MFDS and KATS align with OECD testing protocols to accelerate international certification of domestic cell designs. Seoul metropolitan bus programs establish direct pilot-line relationships that bypass traditional tiered supplier structures.
Taiwan
ProLogium Technology anchors the island's solid-state development around composite electrolyte architectures. The Hsinchu semiconductor equipment base supplies precision deposition tools for thin-film processing. Kaohsiung industrial zones host pilot-scale sulfide handling facilities serving regional automotive qualification programs.
Asia-Pacific Electric Vehicle Solid State Battery Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertical integration determining access to sulfide precursor supply and ceramic sintering capacity. The structure concentrates around three archetypes: diversified industrial conglomerates with captive automotive relationships, pure-play battery specialists pursuing technology licensing revenue, and cathode material suppliers extending downstream into electrolyte formulation. Competitive moves center on pilot-line capacity expansion ahead of mass-production readiness and strategic partnerships to secure argyrodite sulfide feedstock against regional supply concentration.
Within the diversified conglomerate tier, Toyota Industries Corporation and Panasonic Holdings Corporation exemplify players leveraging existing OEM relationships to anchor qualification programs. Samsung SDI occupies a position bridging Korean government-backed development timelines with sulfide processing capabilities. CATL represents the scale-driven archetype, with BYD anchoring backward integration from lithium sourcing through pack assembly.
| Leading Market Players |
|---|
| CATL |
| Panasonic Holdings Corporation |
| Toyota Industries Corporation |
| LG Energy Solution |
| Samsung SDI |
| BYD |
| Hitachi Zosen |
| Murata |
| ProLogium Technology |
| Others |
Value Network & Pricing Analysis
Sulfide glass-ceramic composite processing transitions are redistributing cost economics across Asia-Pacific manufacturing clusters while concentrating feedstock leverage among Korean and Chinese argyrodite suppliers. This technology shift simultaneously elevates pilot-line qualification premiums and exposes Japanese cell makers to input cost volatility.
Pricing Analysis
Capacity additions in South Korea's Gyeonggi-do corridor are reshaping price floors for sulfide electrolyte cells. Three-tier pricing structure across premium ceramic, mid-grade composite, and economy polymer tiers reflects certification grade and volume scale differentiation. Cost compression in the polymer tier is intensifying because MIIT GB standards enforcement eliminates semi-solid subsidy eligibility. Fleet operators show highest price sensitivity, while premium passenger OEMs absorb qualification premiums.
Supply Chain Analysis
End-of-life cell refurbishment flows remain undeveloped across Asia-Pacific, locking value into virgin material procurement. Supply concentrates in China, South Korea, and Japan, with Korean and Chinese suppliers controlling argyrodite sulfide precursor, ceramic sintering equipment, and high-nickel cathode material. Single-source vulnerability in sulfide feedstock exposes Japanese producers to supply disruption. Distribution runs through OEM-direct qualification programs and tiered supplier structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between China's MIIT-subsidized qualification timelines and Japan's METI-coordinated supply chain premiums. The cost differential in sulfide precursor access versus ceramic pilot-line output creates divergent margin structures.
For Market Incumbents: Lock in argyrodite sulfide supply agreements with Korean or Chinese feedstock producers before qualification volumes scale. Anchor ceramic pilot-line capacity in Aichi or Gyeonggi-do to defend against composite electrolyte displacement. METI battery supply chain initiatives offer a coordination lever against raw material cost volatility.
For New Entrants and Emerging Players: Commercial vehicle fleet operators represent an underserved buyer archetype with direct pilot-line procurement appetite. Municipal bus programs in Seoul and logistics operators in Tokyo offer the most penetrable entry points. Pursue performance-guarantee subscription models rather than cell-only sales to bypass OEM tiered supplier barriers.
For Investors and Strategic Acquirers: Valuations sit cheapest among cathode material suppliers extending downstream into electrolyte formulation. Five-to-ten year viability hinges on sulfide processing capability maturation ahead of ceramic sintering yield breakthroughs. Monitor which regulator first mandates solid-state performance benchmarks for subsidy eligibility as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Sulfide Supply Agreement | Secures argyrodite feedstock access against Korean and Chinese concentration. |
| Pilot-Line Capacity Expansion | Accelerates OEM qualification timelines in Aichi and Gyeonggi-do clusters. |
| Composite Electrolyte Licensing | Bridges manufacturing scalability gaps for mid-tier platform access. |
| Software-Defined Battery Platform | Consolidates revenue around performance guarantees rather than cell sales. |
| Commercial Vehicle Fleet Partnership | Bypasses tiered supplier structures through direct pilot-line relationships. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged solid-state cell engineering directors, OEM platform procurement managers, cathode material R&D leads, and METI/MIIT policy coordinators. Secondary validation drew from MIIT GB standards filings, METI battery alliance disclosures, MFDS testing protocols, and vehicle production registration databases. Bottom-up cell shipment estimates and top-down automotive battery demand models were cross-referenced for triangulation.
Segment-weighting applied electrolyte technology, end-user category, and regional production cluster as primary dimensions across the projection horizon. CAGRs were derived from fitted growth curves against qualification timeline milestones. Forecast inputs incorporated pilot-line capacity expansion schedules, sulfide precursor supply concentration indices, and regulatory benchmark adoption probabilities.
Underlying measurement precision varies by segment; ceramic electrolyte forecasts carry tighter precision than composite architectures given more mature pilot-line visibility. Forecasts reflect assumptions about dendrite suppression breakthrough timelines and sulfide handling protocol standardization. Practitioners should monitor GB/METI/MFDS certification harmonization progress and argyrodite spot market volatility for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
South America Hybrid Electric Vehicle Battery Market
EV Batteries
Europe Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
China Electric Vehicle Battery Materials Market
EV Batteries
Asia-Pacific Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
North America LFP Battery Pack Market
EV Batteries
Europe Electric Vehicle Battery Manufacturing Market
EV Batteries
Electric Vehicle Traction Batteries Market
EV Batteries
EV Battery Cells Market
EV Batteries
United States Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
United States Electric Vehicle Battery Anode Market
EV Batteries
Spain Rechargeable Battery Market
EV Batteries
South America Electric Vehicle Battery Anode Market
EV Batteries
Canada EV Battery Pack Market
EV Batteries
ASEAN Electric Vehicle VRLA Batteries Market
EV Batteries
South Korea Electric Vehicle Battery Market
EV Batteries
Electric Vehicle Battery Conditioners Market