
 Canada Electric Vehicle Battery Manufacturing Equipment Market | 2026-2036
Canada Electric Vehicle Battery Manufacturing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Electric Vehicle Battery Manufacturing Equipment Market Insights
Canadian cathode active material producers is realigning supply chains toward North American EV battery output. Siemens anchors automation portfolios across Ontario assembly corridors with integrated digital twin platforms for cell manufacturing. Linamar Corporation leverages its automotive component heritage to diversify into battery structural enclosures and thermal management systems. Xiamen Tmax Battery Equipments Limited competes on electrode coating precision, shipping modular lines to Canadian battery startups seeking faster commissioning cycles.
Canada electric vehicle battery manufacturing equipment encompasses machinery for electrode coating, cell stacking, electrolyte filling, formation cycling, and module-to-pack assembly, operating at precision tolerances below 50 microns for lithium-ion cell consistency. This equipment enables domestic production of battery cells and packs for electric vehicle propulsion systems, reducing import dependency from Asian supply chains. Cell production equipment captures the largest capital allocation as gigafactory buildouts prioritize in-house electrode manufacturing over outsourced cell supply. Solid-state technology lines represent the fastest-growing manufacturing process segment, though most near-term orders concentrate on lithium-ion electrode coating and formation equipment where yield optimization drives equipment replacement cycles.
Health Canada and the Canadian Environmental Protection Act shape chemical handling standards for electrode solvent recovery systems, while Natural Resources Canada's Critical Minerals Strategy influences domestic cathode precursor sourcing requirements for equipment buyers seeking federal funding. The investment tax credit for clean technology manufacturing administered by the Canada Revenue Agency directly reduces capital expenditure thresholds for battery equipment procurement, redirecting demand toward qualifying Canadian-assembled machinery. Stakeholders must monitor how provincial permitting timelines for industrial electricity upgrades affect equipment installation schedules at planned Ontario battery facilities.
Market Dynamics
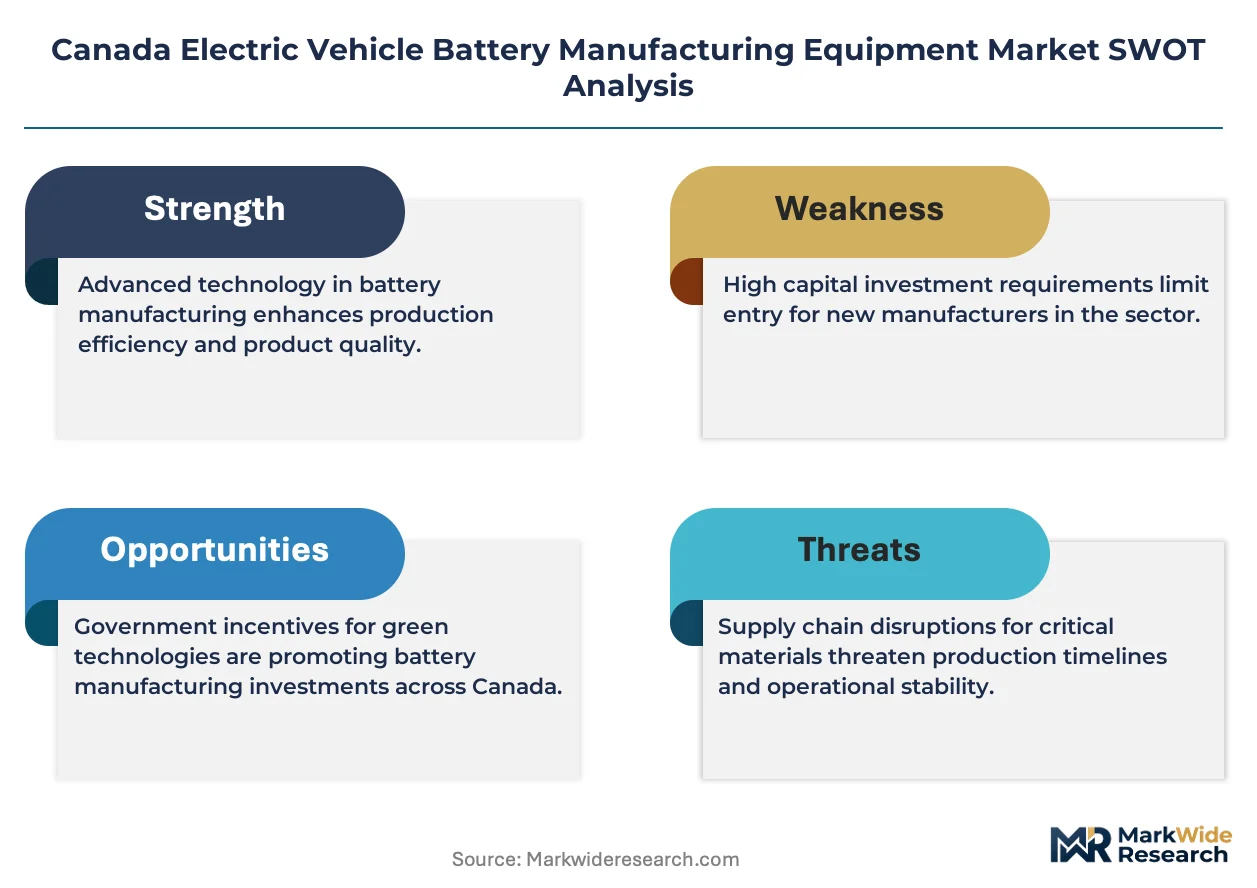
Federal investment tax credits for clean technology manufacturing are compressing capital deployment timelines for electrode coating and cell formation equipment across Ontario's emerging battery corridor.
Growth Catalysts
- Clean Technology Manufacturing ITC:The Canada Revenue Agency's refundable tax credit covers up to thirty percent of capital costs for qualifying battery production equipment, directly lowering procurement thresholds for gigafactory developers in Windsor and St. Thomas.
- Critical Minerals Strategy alignment:Domestic cathode precursor sourcing requirements tied to federal funding programs are mandating in-house electrode manufacturing capacity that equipment suppliers must provision.
- Cell formation yield optimization:Precision cycling equipment capable of sub-fifty-micron tolerance control is displacing older imported lines as Canadian producers prioritize consistency over initial capital savings.
Market Restraints
- High-purity lithium chemical input volatility:Spodumene concentrate and lithium hydroxide price swings transmit directly into electrode coating line operating economics, compressing equipment payback periods during commodity spikes.
- Asian equipment supply concentration:Korean and Japanese vendors still dominate precision winding and electrolyte filling machinery, exposing Canadian buyers to extended lead times and currency hedging costs.
- Solid-state manufacturing readiness gap:Current electrode coating infrastructure lacks compatibility with sulfide-based solid electrolyte processing, forcing premature obsolescence risk on lithium-ion focused capital plans.
Strategic Opportunities
- Quebec lithium conversion integration:Equipment suppliers can co-locate electrode manufacturing lines with emerging hard-rock lithium refineries in Abitibi-Témiscamingue, reducing transport costs for cathode active material producers.
- Second-life battery disassembly automation:Module-to-pack assembly equipment originally deployed for production can pivot to automated disassembly lines serving the growing stationary storage refurbishment segment.
- Provincial industrial electricity rate structures:Ontario's reduced electricity rates for large industrial consumers operating overnight shifts create arbitrage opportunities for formation cycling equipment with flexible load profiles.
Industry Challenges
- Electrochemical engineering talent scarcity:Canadian universities produce insufficient cell design and manufacturing process engineers to staff planned gigafactory operations, forcing equipment buyers to import expertise at premium compensation.
- Health Canada chemical handling compliance:N-Methyl-2-pyrrolidone solvent recovery systems must meet stringent Canadian Environmental Protection Act emissions thresholds, extending equipment commissioning timelines by four to eight months.
- Legacy automotive supplier integration friction:Battery line automation protocols from Siemens and Rockwell Automation require extensive retrofitting to interface with existing stamping and welding equipment at repurposed assembly plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Electric Vehicle Battery Manufacturing Equipment Market |
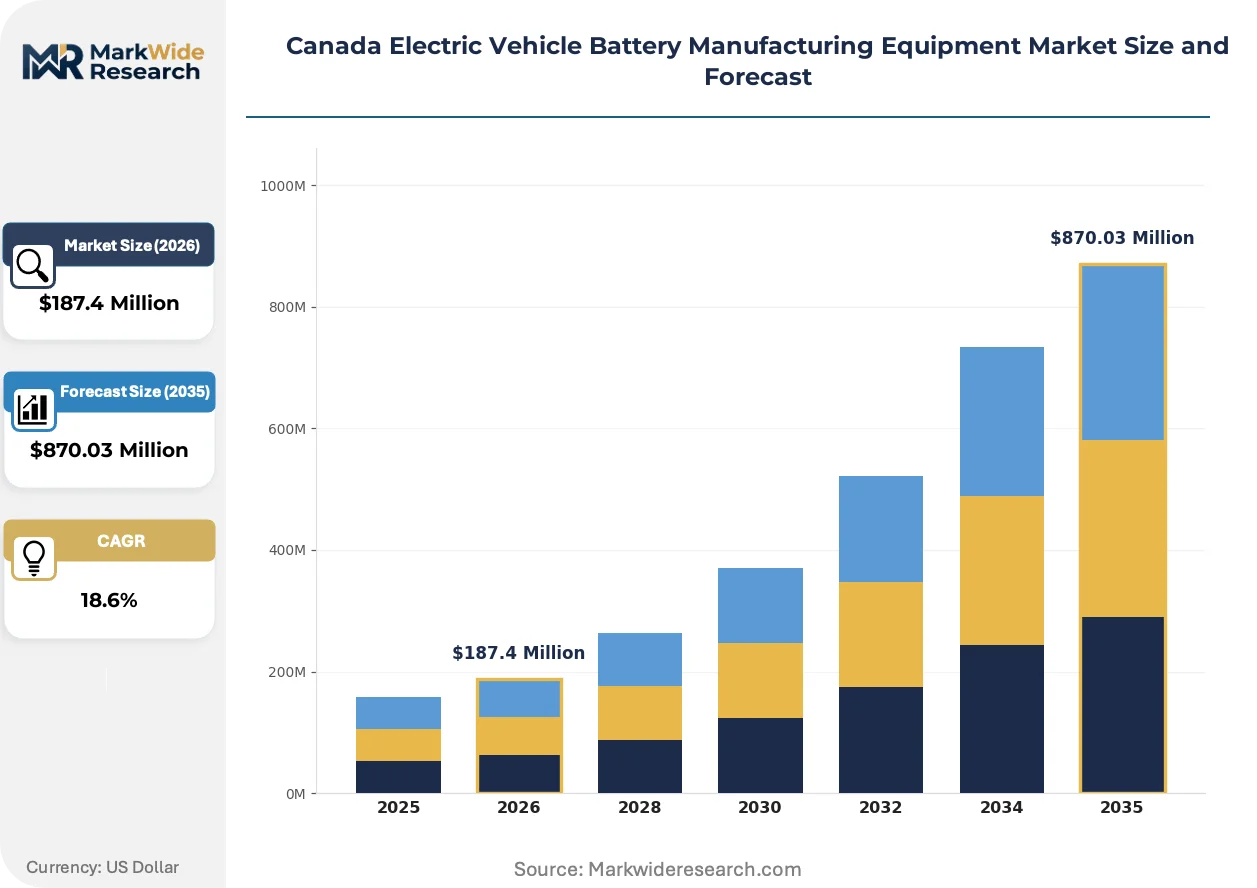
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Assembly Machines, Testing Equipment, Packaging Systems, Inspection Tools Manufacturing Process: Cell Production, Electrode Coating, Module Assembly, Pack Formation End User: Automakers, Battery Manufacturers, Component Suppliers, Research Institutions Technology: Lithium-ion, Solid-state, Nickel-cobalt, Lead-acid |
| Companies Covered | Xiamen Lith Machine Limited, IPG Photonics Corporation, Durr AG, Hitachi Ltd, Xiamen Tmax Battery Equipments Limited, Siemens, Linamar Corporation, Volkswagen, Northvolt, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Electric Vehicle Battery Manufacturing Equipment Market Trends and Innovations
Digital twin platforms are compressing equipment commissioning cycles while solid-state pilot lines and automated quality inspection systems reshape capital allocation priorities across Canadian battery manufacturing.
Dry electrode coating technology eliminates solvent-based slurry processing through electrostatic powder deposition onto current collectors. Windsor-area gigafactory developers are piloting this approach to reduce drying oven footprint and energy consumption. The technology is integrating formation cycling equipment with real-time thickness measurement feedback loops that adjust coating parameters without line stoppage.
Canada's Clean Technology Manufacturing investment tax credit administered by the Canada Revenue Agency now requires domestic assembly or substantial transformation for full credit eligibility. Equipment vendors are establishing Ontario final assembly facilities to qualify machinery for the refundable tax credit. Cell stacking and module assembly equipment categories face the tightest compliance scrutiny given their higher capital intensity.
Automotive OEMs are consolidating equipment procurement under single-source automation integrators rather than sourcing discrete machines from multiple vendors. This behavior concentrates specification-setting power with Siemens and Rockwell Automation in Ontario's battery corridor. The shift is most visible at St. Thomas and Windsor gigafactory sites where turnkey line responsibility reduces interface risk for first-time domestic cell producers.
Canada Electric Vehicle Battery Manufacturing Equipment Market Segmentation
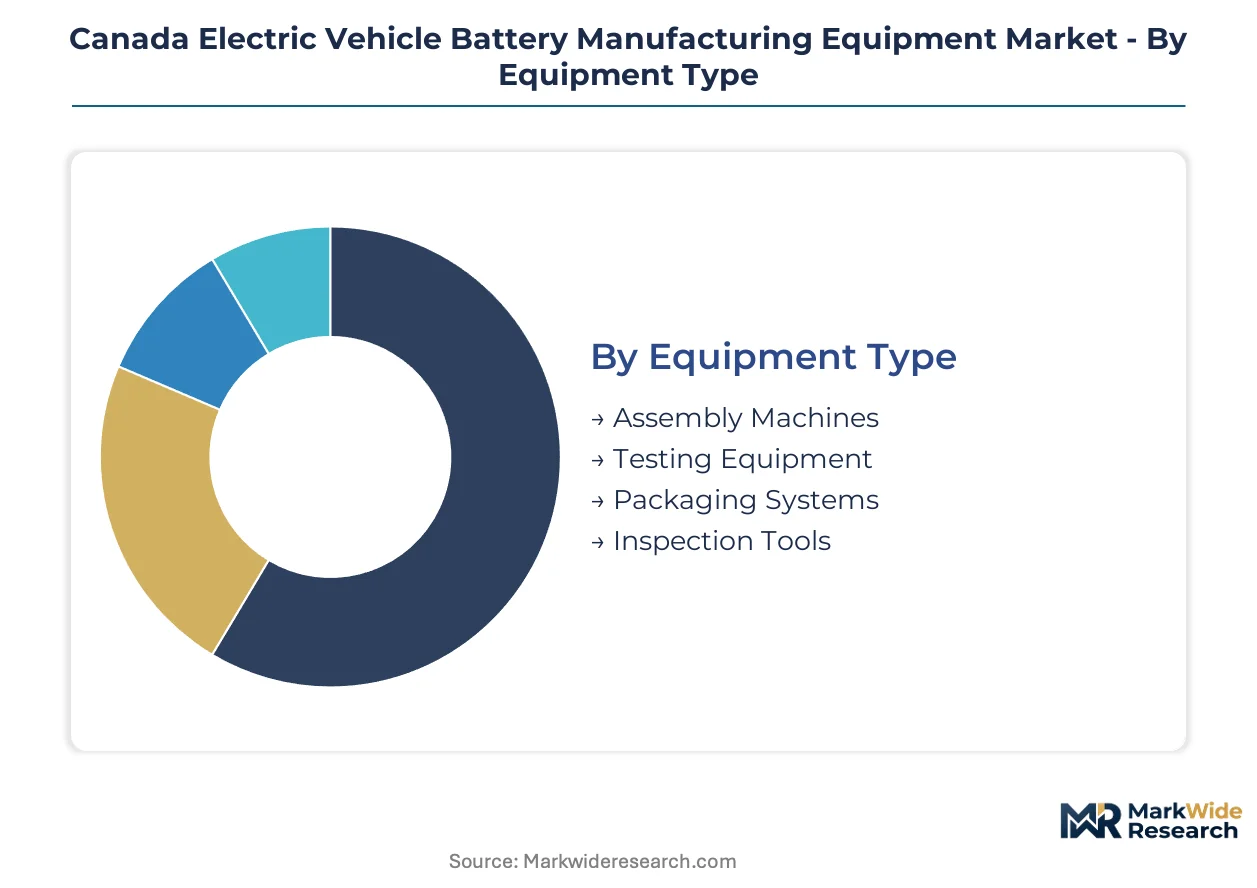
Equipment segmentation in Canada's EV battery manufacturing market reveals how capital allocation priorities shift across production stages. Buyers configure procurement portfolios around yield optimization, regulatory compliance, and technology transition timelines.
Equipment Type:
Upgrade cycles for precision machinery are shortening as electrode coating tolerances tighten below fifty microns, forcing replacement decisions that favor integrated automation over standalone units.
- Assembly Machines:Robotic stacking and winding systems handle electrode-separator laminates with positioning accuracy under twenty-five microns. Windsor gigafactory developers specify these for cathode active material handling where Health Canada chemical exposure standards mandate enclosed cell architectures.
- Testing Equipment:Formation cycling and electrochemical impedance spectroscopy systems validate cell consistency across temperature ranges. Ontario battery startups prioritize in-line testing modules that reduce offline quality verification bottlenecks during ramp-up phases.
- Packaging Systems:Vacuum-sealing and dry room enclosure equipment maintains moisture levels below one hundred parts per million for lithium-ion cell integrity.
- Inspection Tools:Automated optical and X-ray systems detect electrode coating defects at production speeds exceeding fifty meters per minute.
Assembly machines sit at the top of the volume ranking, with testing equipment climbing the fastest as yield-focused producers expand in-process verification capacity.
Manufacturing Process:
Process-stage segmentation reflects how federal clean technology tax credits concentrate capital in electrode manufacturing over downstream module work.
- Cell Production:Electrode calendering, slitting, and stacking lines convert coated foils into wound or stacked jellyroll configurations. St. Thomas facility developers source these systems with integrated solvent recovery to meet Canadian Environmental Protection Act emissions thresholds for N-Methyl-2-pyrrolidone handling.
- Electrode Coating:Slot-die and comma-bar coating systems deposit cathode and anode slurries onto aluminum and copper current collectors. Quebec lithium conversion projects are driving demand for coating lines co-located with hard-rock refinery output in Abitibi-Témiscamingue.
- Module Assembly:Cell grouping, busbar welding, and housing integration systems package cells into replaceable units.
- Pack Formation:Thermal management integration and battery management system commissioning equipment assembles modules into vehicle-ready propulsion systems.
Cell production commands the largest capital share, with electrode coating expanding most quickly as domestic cathode precursor requirements take effect.
End User:
Customer-type segmentation tracks how first-time domestic cell producers differ from established automotive suppliers in equipment specification priorities.
- Automakers:Vertically integrated OEMs specify turnkey lines with single-source automation responsibility to reduce interface risk at repurposed Ontario assembly plants. These buyers prioritize digital twin commissioning platforms that compress timeline uncertainty.
- Battery Manufacturers:Dedicated cell producers concentrate procurement on electrode coating and formation cycling where yield optimization drives equipment replacement cycles ahead of depreciation schedules.
- Component Suppliers:Tier-one automotive suppliers diversify into battery structural enclosures and thermal management systems.
- Research Institutions:Universities and national laboratories pilot solid-state and next-generation chemistries at bench and pilot scale.
Automakers lead absolute procurement volume, with battery manufacturers gaining share fastest as independent cell production capacity multiplies across the Windsor-to-Toronto corridor.
Technology:
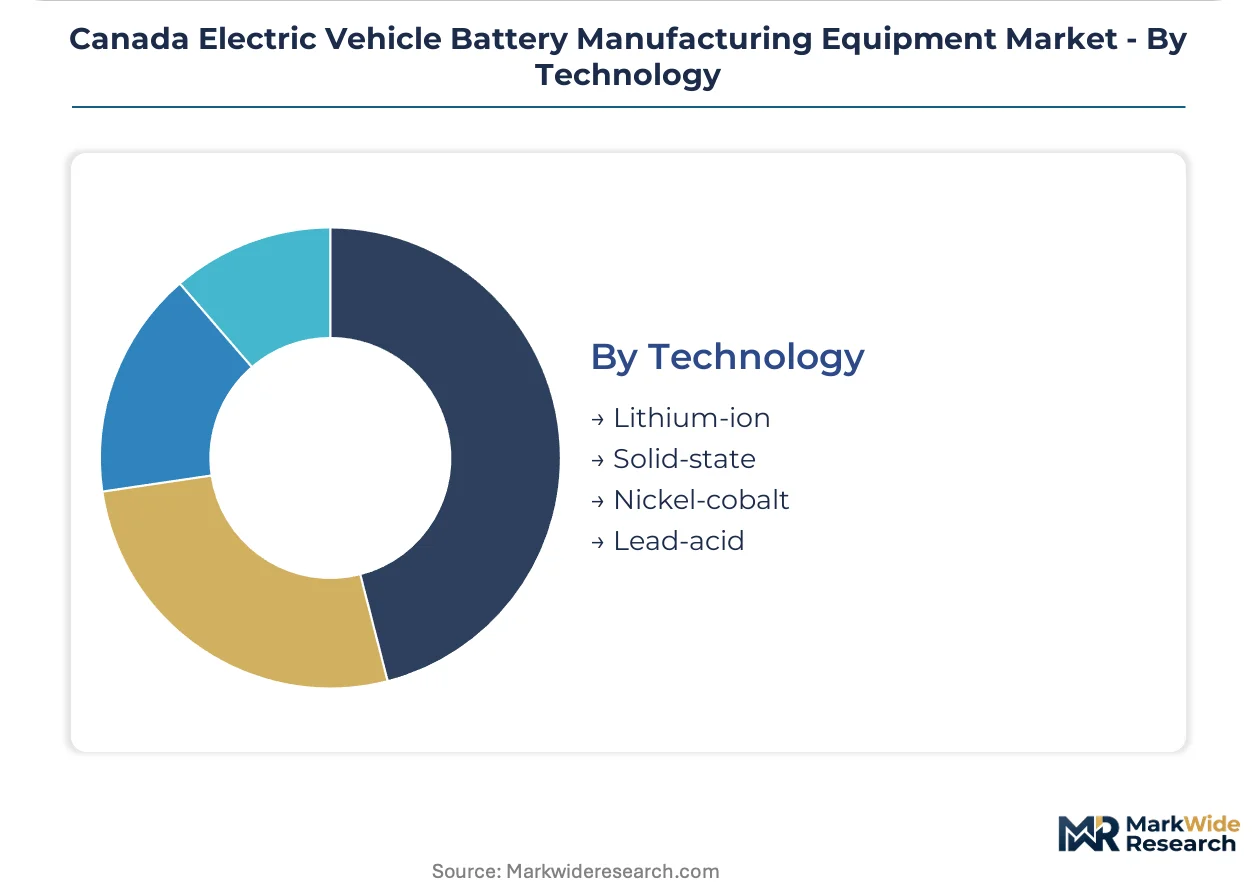
Technology segmentation captures the tension between near-term lithium-ion equipment deployment and emerging solid-state manufacturing requirements.
- Lithium-ion:Conventional graphite-anode and layered-oxide-cathode cell manufacturing dominates current equipment orders. Ontario gigafactory developers specify these lines with upgrade pathways to silicon-anode compatibility.
- Solid-state:Sulfide-based and oxide-based electrolyte processing requires dry room infrastructure and precision lamination equipment incompatible with liquid electrolyte lines. Federal funding programs are accelerating pilot line investments despite manufacturing readiness gaps.
- Nickel-cobalt:High-nickel cathode production equipment addresses energy density requirements for premium vehicle segments.
- Lead-acid:Mature battery technology equipment serves stationary storage and automotive auxiliary power applications with limited growth trajectory.
Lithium-ion retains dominant equipment share, with solid-state posting the steepest expansion trajectory as technology transition timelines compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is concentrating battery equipment procurement in jurisdictions where Ottawa's investment tax credits offset Health Canada compliance costs most efficiently. Canadian producers exploit this cost-of-compliance gap to outbid US and Mexican sites for North American gigafactory investments.
Ontario
Windsor-to-Toronto corridor developers prioritize electrode coating lines with integrated solvent recovery to meet Canadian Environmental Protection Act thresholds for N-Methyl-2-pyrrolidone handling. The Canada Revenue Agency's clean technology ITC covers thirty percent of qualifying capital costs for St. Thomas and Windsor gigafactory projects. Siemens anchors automation portfolios across this corridor with digital twin platforms compressing commissioning cycles for first-time domestic cell producers.
Quebec
Hard-rock lithium refineries in Abitibi-Témiscamingue are driving co-location demand for cathode active material coating equipment near conversion facilities. Natural Resources Canada's Critical Minerals Strategy mandates domestic precursor sourcing that equipment buyers must satisfy to access federal funding. Montreal-area engineering firms are supplying formation cycling systems to bridge the electrochemical talent gap plaguing Ontario operations.
British Columbia
Vancouver-based battery startups are importing modular electrode stacking equipment with faster commissioning timelines than turnkey Asian lines. Health Canada chemical handling standards for electrolyte filling systems extend permitting timelines by four to eight months relative to Ontario benchmarks. The province's clean technology tax credit stacking with federal programs reduces effective equipment procurement costs for pilot-scale solid-state lines.
Alberta
Calgary-area energy transition funds are deploying capital into battery testing equipment serving oilfield electrification and grid storage applications. The province's industrial electricity rate structures lack Ontario's overnight arbitrage opportunities for formation cycling load management. Edmonton research institutions are piloting dry electrode coating technology with federal innovation grants targeting solvent-free manufacturing pathways.
Canada Electric Vehicle Battery Manufacturing Equipment Market Competitive Landscape
German automation conglomerates anchor the premium equipment tier; Chinese specialists hold the modular mid-market segment with faster delivery cycles. The vendor structure concentrates around three strategic archetypes: integrated automation platforms, precision coating specialists, and automotive-tier diversifiers. Capacity expansion and qualification for Canadian domestic assembly content dominate competitive positioning as Ottawa's ITC eligibility rules tighten.
Among German-based fabricators, Durr AG and Siemens occupy positions within the integrated automation tier, exemplifying the specification-setting power consolidated around turnkey line responsibility. Xiamen Tmax Battery Equipments Limited represents the Chinese specialist archetype competing on electrode coating precision and commissioning speed. Linamar Corporation anchors the automotive-tier diversifier category, leveraging component heritage into battery structural and thermal systems.
| Leading Market Players |
|---|
| Xiamen Lith Machine Limited |
| IPG Photonics Corporation |
| Durr AG |
| Hitachi Ltd |
| Xiamen Tmax Battery Equipments Limited |
| Siemens |
| Linamar Corporation |
| Volkswagen |
| Northvolt |
| Others |
Pricing and Supply Chain Analysis
N-Methyl-2-pyrrolidone solvent recovery system costs cascade through electrode coating equipment pricing tiers, with Health Canada compliance premiums separating domestic-assembled machinery from direct Asian imports eligible for reduced Canada Revenue Agency clean technology tax credits.
Pricing Analysis
Distributor margins for Korean and Japanese precision winding equipment compress pricing flexibility at the turnkey line layer, where Siemens and Rockwell Automation specification-setting power enables premium capture. Contract-based long-term offtake dominates gigafactory procurement, with price differentiation resting on Health Canada certification tier and domestic assembly content qualification for federal ITC eligibility. Cost compression in mid-market modular equipment is intensifying as Chinese specialists accelerate commissioning speed. Battery startups exhibit highest price sensitivity, while vertically integrated automakers prioritize yield consistency over initial capital outlay.
Supply Chain Analysis
Regional distribution centers in Vancouver and Toronto buffer extended lead times from Asian equipment hubs, though hub-and-spoke patterns remain tethered to Korean and Japanese precision machinery concentration. Electrode coating lines draw from spodumene concentrate processed at Quebec hard-rock refineries and cathode active material precursors imported from China and South Korea. Single-source vulnerability in electrolyte filling machinery exposes Canadian buyers to currency hedging costs. Distribution runs through automation integrators consolidating discrete machine procurement under turnkey line responsibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with sub-fifty-micron tolerance specifications displacing price-driven procurement as domestic gigafactory operators prioritize yield optimization over initial capital savings.
For Market Incumbents: Deepen backward integration into cathode active material coating equipment assembly within Ontario to secure full Canada Revenue Agency ITC eligibility as domestic content rules tighten. Anchor automation portfolios with digital twin commissioning platforms that compress timeline risk for first-time domestic cell producers facing electrochemical engineering talent scarcity.
For New Entrants and Emerging Players: Enter via Quebec lithium conversion corridor co-location opportunities, where Natural Resources Canada Critical Minerals Strategy mandates create captive demand for electrode manufacturing lines near Abitibi-Témiscamingue refineries. Target solid-state pilot line equipment as the most penetrable segment, leveraging federal innovation grant stacking with provincial clean technology credits.
For Investors and Strategic Acquirers: Roll-up economics work for precision coating specialists with Health Canada solvent recovery certification because regulatory compliance barriers protect margin structures from commoditization. Long-term viability hinges on technology transition optionality toward sulfide-based solid electrolyte processing. Watch Health Canada chemical handling standard revisions as the inflection signal for equipment replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Assembly Footprint Expansion | Qualifies machinery for Canada Revenue Agency clean technology ITC eligibility thresholds. |
| Solvent Recovery System Integration | Meets Canadian Environmental Protection Act N-Methyl-2-pyrrolidone emissions standards. |
| Digital Twin Platform Deployment | Compresses commissioning cycles for first-time domestic cell producers in Ontario corridor. |
| Solid-State Pilot Line Investment | Positions equipment portfolios for sulfide electrolyte processing technology transition. |
| Quebec Lithium Corridor Co-location | Reduces transport costs for cathode active material producers near Abitibi-Témiscamingue refineries. |
Research Methodology
Multiple input streams — primary interviews with gigafactory procurement directors, electrode coating equipment engineers, and Health Canada regulatory compliance officers; secondary validation through Natural Resources Canada Critical Minerals Strategy documentation, Canada Revenue Agency ITC administrative guidance, and Ontario Ministry of Economic Development gigafactory permitting records — were reconciled through bottom-up equipment procurement volume assessment and top-down capital expenditure triangulation.
Historical capital deployment patterns were cross-referenced against panel input from automation integrators and cathode active material producers across the projection horizon. Segmentation dimensions modeled include equipment type, manufacturing process stage, end-user category, and technology chemistry. CAGRs were derived from equipment replacement cycle analysis and federal incentive program uptake trajectories, with formation cycling capacity expansion and solvent recovery compliance timelines as battery-specific forecast inputs.
Inputs from federal regulatory filings and provincial industrial development agencies were available through the study window; gaps in private gigafactory capital commitment schedules introduce uncertainty bands around near-term procurement volume estimates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
South Korea Electric Vehicle Battery Market
EV Batteries
China EV Battery Pack Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Manufacturing Market
EV Batteries
Cold-Climate Optimized EV Battery Systems Market
EV Batteries
South America Electric Vehicle Battery Anode Market
EV Batteries
Asia-Pacific EV Battery Pack Market
EV Batteries
China Hybrid Electric Vehicle Battery Market
EV Batteries
Europe Electric Bus Battery Pack Market
EV Batteries
Middle-East Electric Vehicle Battery Market
EV Batteries
Curved Lipo Battery Market
EV Batteries
Italy Electric Vehicle Battery Electrolyte Market
EV Batteries
Automotive Rechargeable Battery Market
EV Batteries
Auto Storage Battery Market
EV Batteries
Germany Electric Vehicle Battery Manufacturing Market
EV Batteries
Italy Electric Vehicle Battery Manufacturing Market
EV Batteries
Germany EV Battery Pack Market