
 Cobalt Powder for EV Battery Market | 2026-2036
Cobalt Powder for EV Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Cobalt Powder for EV Battery Market Insights
UN 38.3 lithium battery transport certification is collapsing the supplier base for cobalt powder destined for EV applications, as smaller refiners lack capital for thermal runaway testing infrastructure. Umicore leverages its European precursor network to sustain qualification pipelines for European OEMs. Huayou Cobalt anchors raw material access through Congolese mining partnerships and Indonesian intermediate processing. POSCO Future M competes via integrated cathode-active-material output in South Korea's battery cluster.
Cobalt powder for EV battery denotes refined particulate cobalt compounds, typically 99.8% purity with D50 particle size below 10 micrometers, produced through hydrometallurgical leaching and re-precipitation for cathode precursor fabrication. Its primary purpose is enabling nickel-cobalt-manganese layered oxide cathodes that deliver the energy density required for 300-plus mile electric vehicle ranges. Cobalt sulfate commands the dominant product position due to direct compatibility with NCM precursor co-precipitation, while cobalt hydroxide gains share in high-nickel low-cobalt formulations where sulfur contamination must be minimized. The electric vehicles application segment absorbs the majority of volume, though energy storage systems represent a faster-growing outlet as grid-scale lithium-ion installations expand.
FDA maintains oversight of cobalt exposure limits in occupational settings affecting U.S. powder handling facilities, while EPA tailings regulations constrain domestic refining expansion. REACH registration requirements in Europe mandate full substance dossiers for cobalt compounds imported above one-tonne thresholds, directly shaping which non-EU suppliers achieve market access. China's MIIT battery industry standards specify cobalt content thresholds and recycling recovery rates that influence precursor procurement policies. Stakeholders must track how Indonesia's nickel-cobalt processing investments alter feedstock cost structures and which cathode chemistries OEMs select for next-generation platform architectures.
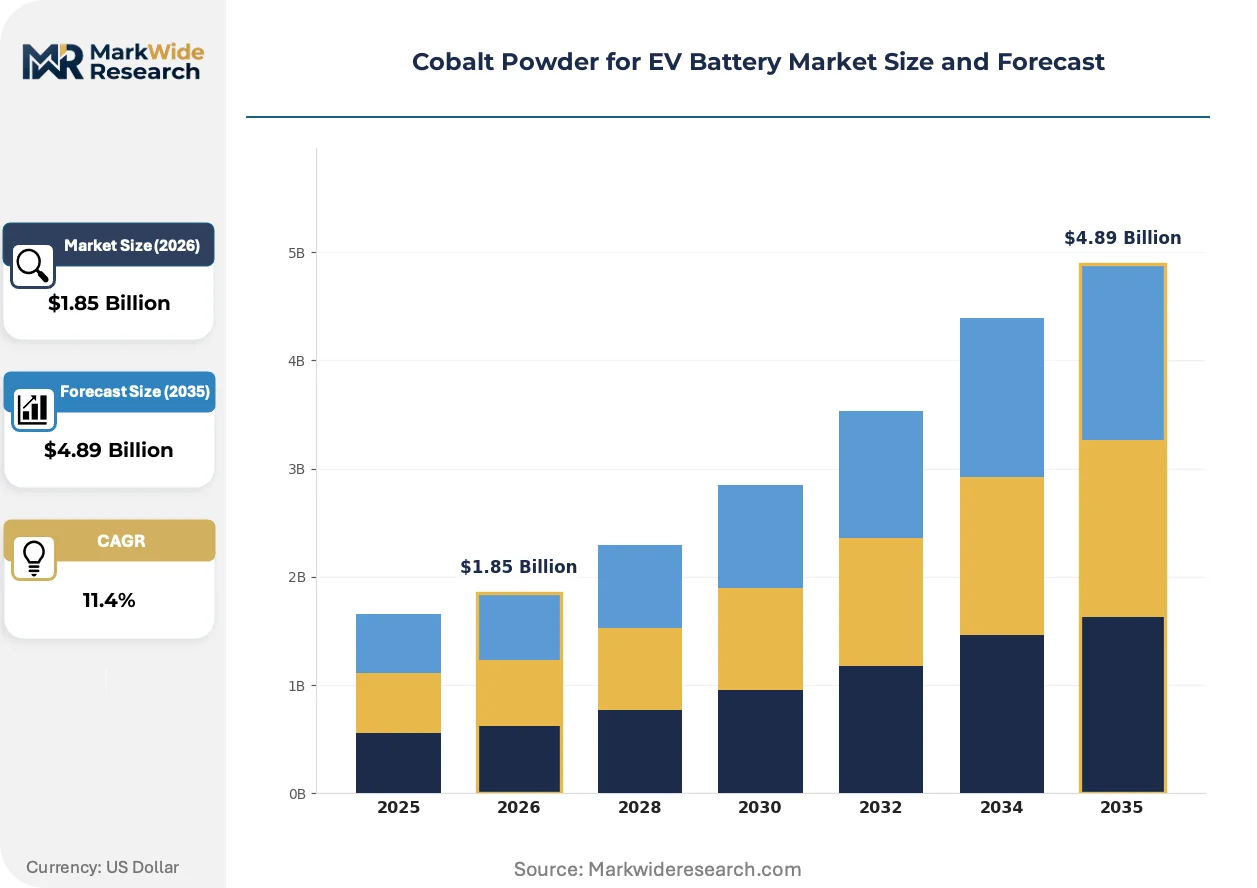
Market Dynamics
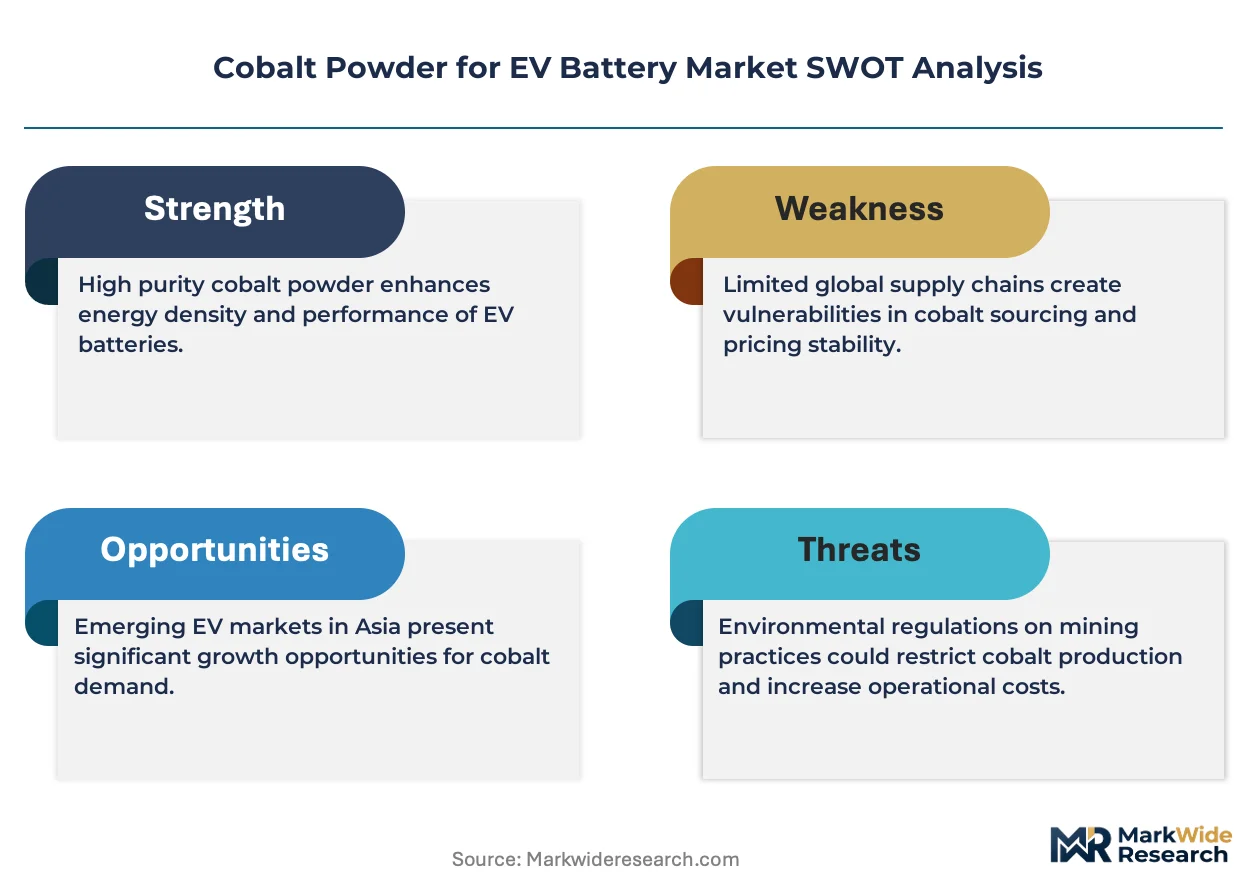
Cathode chemistry roadmaps are compressing cobalt intensity per kilowatt-hour faster than absolute demand growth, creating a structural squeeze on powder refiners dependent on legacy NCM formulations. This technology-forced efficiency gain reshapes procurement volumes and qualification timelines simultaneously.
Growth Catalysts
- EU Battery Passport mandates:Full supply chain traceability requirements under the EU Green Deal are locking in qualified cobalt suppliers with existing disclosure infrastructure, advantaging integrated refiners over merchant traders.
- High-nickel cathode proliferation:NCM 811 and 9-series formulations still require cobalt stabilization at reduced loadings, preserving powder demand even as chemistry efficiency improves.
- Indonesian intermediate processing investments:Hydrometallurgical refining capacity expansion in Sulawesi and Halmahera is diversifying feedstock origins beyond the DRC, improving supply security for Asian cell manufacturers.
Market Restraints
- Artisanal mining concentration:Roughly two-thirds of global cobalt ore originates from the DRC's informal extraction sector, embedding ESG compliance costs and reputational risk into every supply chain tier.
- Sulfate-to-hydroxide conversion costs:High-nickel low-cobalt cathodes require sulfur-free hydroxide precursors, forcing capital-intensive process retooling at refiners optimized for sulfate output.
- LFP chemistry substitution:Iron-phosphate batteries are capturing volume in entry-level and commercial vehicle segments where energy density requirements permit cobalt-free formulations.
Strategic Opportunities
- Energy storage system qualification:Grid-scale lithium-ion installations are adopting NCM cathodes for duration-critical applications, opening a volume outlet with less stringent automotive-grade certification barriers.
- Closed-loop recycling mandates:China's MIIT standards for cobalt recovery rates above specified thresholds are creating captive recycling demand that integrated refiners can capture through precursor-to-powder circularity.
- Solid-state battery pre-qualification:Sulfide and oxide electrolyte architectures under development by South Korean and Japanese manufacturers specify high-purity cobalt sulfides for catholyte interfaces, positioning early movers for next-generation chemistry supply.
Industry Challenges
- UN 38.3 thermal runaway certification timelines:Cell-level safety testing for lithium battery transport approval requires 6-12 month validation cycles that delay new powder supplier qualification.
- Hydrometallurgical wastewater treatment capex:Indonesian and Congolese environmental regulations are tightening effluent standards for cobalt refining, requiring membrane filtration and zero-liquid-discharge infrastructure investments that compress merchant refiner margins.
- REACH substance dossier completeness:European Chemicals Agency registration requirements for cobalt compounds imported above one-tonne thresholds demand full toxicological data packages that smaller non-EU refiners cannot assemble.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cobalt Powder for EV Battery Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cobalt Sulfate, Cobalt Hydroxide, Cobalt Carbonate, Cobalt Oxide Application: Positive Electrode, Lithium-Ion Batteries, Energy Storage Systems, Electric Vehicles End User: Automotive Manufacturers, Battery Producers, Industrial Users, Research Institutions Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Umicore, Freeport Cobalt, Hanrui Cobalt, Green Eco-Manufacturer, Huayou Cobalt, CATL, LG Energy Solution, POSCO Future M, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cobalt Powder for EV Battery Market Trends and Innovations
Particle engineering and supply chain digitization are converging to redefine how cobalt powder specifications align with cell manufacturing yield targets. These developments compress the traditional specification-setting process between refiners and cathode precursor operations.
Single-crystal NCM cathode materials are displacing polycrystalline equivalents in premium automotive applications. CATL and BYD's cell operations specify cobalt powders with tighter D50 distributions below 5 micrometers to enable uniform single-crystal growth during precursor sintering. This particle size compression is displacing legacy spray-dried powder specifications that dominated NCM 523 and 622 generations, forcing refiners to invest in controlled precipitation reactors and classification systems.
China's MIIT battery industry standards now specify cobalt content disclosure thresholds and recycling recovery rate minimums that influence precursor procurement policies. These rules compress the qualified supplier base to integrated operations with verified circularity infrastructure. Domestic cell manufacturers are responding by consolidating purchase orders toward refiners with in-house recycling or long-term offtake agreements with certified recyclers.
Automotive OEMs are compressing supplier tiers through direct cobalt powder qualification programs that bypass traditional precursor intermediaries. BMW and Volkswagen's cell supply agreements now include raw material traceability requirements that extend to powder refiner audits. This disintermediation is most visible in European battery plant investments where OEMs specify qualified powder suppliers in joint venture cathode active material facilities.
Cobalt Powder for EV Battery Market Segmentation
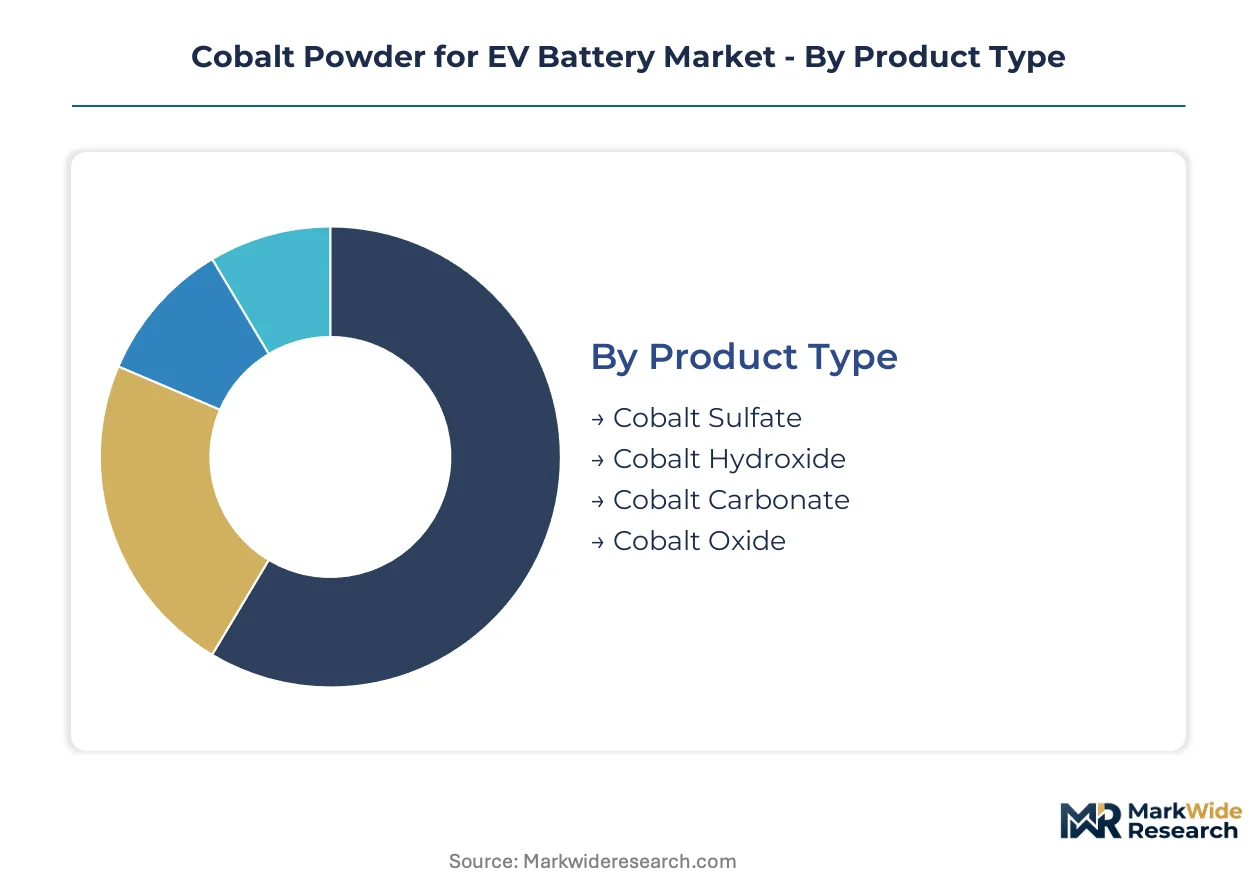
Cobalt powder segmentation reveals how cathode chemistry roadmaps and qualification barriers reshape procurement patterns across supplier tiers. Product specifications and channel structures diverge sharply between automotive-grade and industrial-grade demand pools.
Product Type:
Cobalt sulfate dominates export-oriented supply chains serving precursor manufacturers in China and South Korea. Domestic refiners in the DRC and Indonesia increasingly favor hydroxide output for integrated processing advantages.
- Cobalt Sulfate:Heptahydrate crystalline form at 20.5% minimum cobalt content serves NCM 523 and 622 precursor co-precipitation. Demand concentrates in Jiangsu province cathode plants supplying CATL and BYD, constrained by sulfur contamination limits in high-nickel formulations.
- Cobalt Hydroxide:Intermediate product from laterite leaching circuits enables sulfur-free precursor production for NCM 811 and 9-series cathodes. Indonesian HPAL operations in Sulawesi are expanding hydroxide output to serve Korean cell manufacturers' high-nickel specifications.
- Cobalt Carbonate:Ceramic-grade powder finds limited EV battery application outside specialty solid-state electrolyte research programs.
- Cobalt Oxide:Tricobalt tetroxide serves niche lithium cobalt oxide cathode segments in consumer electronics with minimal EV penetration.
Cobalt sulfate commands the established base. The steepest expansion runs through cobalt hydroxide as high-nickel cathodes displace legacy formulations.
Application:
Automotive-grade qualification timelines stretch 18-24 months versus 6-12 months for stationary storage, segmenting supplier access by technical capability depth.
- Positive Electrode:Cathode active material fabrication absorbs refined cobalt powder through precursor co-precipitation and solid-state sintering. European battery passport traceability requirements now extend to powder batch documentation, advantaging integrated refiners with in-house analytics.
- Electric Vehicles:NCM layered oxide cathodes for 300-plus mile range platforms specify 99.8% purity with sub-10 micrometer D50 particle size. OEM direct qualification programs at BMW and Volkswagen are compressing traditional precursor intermediary tiers.
- Lithium-Ion Batteries:Consumer electronics and power tool segments tolerate broader particle distributions with reduced purity thresholds.
- Energy Storage Systems:Grid-scale installations are adopting NCM cathodes for duration-critical applications with less stringent automotive-grade certification barriers.
Electric vehicle applications anchor volume concentration. Energy storage systems are climbing the fastest as grid-scale lithium-ion deployments accelerate.
End User:
Procurement scale and specification stringency create three distinct customer tiers with diverging supplier qualification pathways.
- Automotive Manufacturers:OEM cell supply agreements now specify raw material traceability to refiner level. Direct powder qualification programs at European battery joint ventures are disintermediating traditional precursor suppliers.
- Battery Producers:CATL, BYD, LG Energy Solution, and Samsung SDI consolidate purchase orders toward refiners with verified circularity infrastructure under China's MIIT recovery rate standards.
- Industrial Users:Superalloy and catalyst manufacturers compete for powder supply with less stringent purity requirements but smaller volume scale.
- Research Institutions:Solid-state battery programs at South Korean and Japanese manufacturers specify high-purity cobalt sulfides for catholyte interface development.
Battery producers dominate procurement volume. Research institutions are expanding most quickly as next-generation chemistry pre-qualification intensifies.
Distribution Channel:
Channel structure reflects the tension between qualification depth requirements and working capital efficiency across the supply chain.
- Direct Sales:Long-term offtake agreements link Congolese mining operations through Indonesian intermediate processing to Asian precursor manufacturers. Huayou Cobalt and Umicore sustain direct relationships with cell producers to manage specification drift.
- Distributors:Regional chemical distributors serve smaller precursor operations and research institutions with standard-grade powder and shorter lead times.
- Online Retail:Limited to laboratory-scale quantities and specialty particle sizes for academic and pilot-scale research.
- Wholesalers:Merchant traders face compression as EU battery passport rules and REACH registration requirements filter out non-integrated suppliers.
Direct sales channels capture the majority of volume flow. Distributor networks are gaining share fastest among mid-tier precursor operations seeking supply security.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam-Antwerp port complex underwrites European cobalt powder flows through integrated precursor handling facilities that connect Congolese feedstock to German cathode plants.
China
Jiangsu and Zhejiang provinces concentrate precursor manufacturing for CATL and BYD cell operations. MIIT battery industry standards mandate cobalt content disclosure thresholds and recycling recovery rates that compress qualified supplier lists to integrated refiners. Ningbo and Changzhou host hydrometallurgical clusters where Huayou Cobalt and Hanrui Cobalt operate captive refining-to-precursor pipelines.
Belgium
Umicore's Hoboken refinery anchors European cobalt sulfate supply through REACH-registered substance dossiers. ECHA registration requirements for cobalt compounds above one-tonne thresholds filter out non-integrated suppliers. The Port of Antwerp handles intermediate cobalt hydroxide from Indonesian HPAL operations for distribution to German and Hungarian battery joint ventures.
South Korea
POSCO Future M's Gwangyang cathode complex drives powder demand for NCM 811 formulations serving Samsung SDI and LG Energy Solution. MFDS chemical safety standards align with EU battery passport traceability requirements. The Busan-Ulsan industrial corridor hosts qualification laboratories that compress UN 38.3 thermal runaway certification timelines for qualified refiners.
Indonesia
The Sulawesi and Halmahera nickel-cobalt processing belt diversifies feedstock origins beyond DRC concentration. MEE environmental regulations tighten hydrometallurgical wastewater standards for HPAL operations, requiring zero-liquid-discharge infrastructure. Morowali Industrial Park hosts intermediate processing investments that supply hydroxide to Korean and Chinese precursor manufacturers.
United States
Domestic refining expansion faces EPA tailings regulations that constrain greenfield hydrometallurgical capacity. FDA maintains occupational exposure limits for powder handling facilities in Michigan and Ohio automotive supplier zones. The Midwest battery belt around Detroit lacks integrated cobalt refining, forcing precursor dependence on Belgian and Canadian import channels.
Cobalt Powder for EV Battery Market Competitive Landscape
Listed leaders compete with private specialists across capital access and qualification infrastructure. The supplier base concentrates around integrated refiners with in-house precursor networks, while merchant traders face compression from EU battery passport rules. Three archetypes dominate: mining-integrated Congolese-Indonesian operators, European precursor-network incumbents, and Asian cell manufacturer affiliates. Competitive moves center on backward integration into mining partnerships and capacity expansion in Indonesian intermediate processing.
Within the integrated refiner tier, Umicore exemplifies European qualification infrastructure through REACH-registered operations, while Huayou Cobalt anchors mining-integrated supply through Congolese partnerships and Indonesian HPAL investments. POSCO Future M occupies a position as cell manufacturer affiliate with captive cathode-active-material output. These three represent the archetype spectrum from European regulatory compliance to Asian scale integration.
| Leading Market Players |
|---|
| Umicore |
| Freeport Cobalt |
| Hanrui Cobalt |
| Green Eco-Manufacturer |
| Huayou Cobalt |
| CATL |
| LG Energy Solution |
| POSCO Future M |
| BASF SE |
| Others |
Pricing and Supply Chain Analysis
Sixty-day Rotterdam-Antwerp inventory cycles concentrate pricing power with integrated refiners possessing captive hydroxide streams, while merchant traders face margin compression from EU battery passport compliance costs and REACH registration thresholds. This lead-time asymmetry rewards Huayou Cobalt and Umicore with contract premiums while forcing spot-market participants into price-taker positions.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement contracts. Premium tiers attach to automotive-grade UN 38.3 certification and OEM direct qualification, while standard tiers serve precursor intermediaries and economy tiers cover industrial-grade applications. Price differentiation hinges on particle size distribution precision and sulfur contamination thresholds. Cost compression in hydroxide conversion is intensifying because Indonesian HPAL capacity expansion adds supply volume. Battery producers exhibit lowest price sensitivity due to qualification lock-in, while research institutions and industrial users drive spot-market volatility.
Supply Chain Analysis
Durban-Cape Town port congestion intermittently chokes Congolese feedstock flows to Asian refiners, amplifying working capital requirements for inventory-holding intermediaries. Supply concentrates in the Democratic Republic of Congo, Indonesia, and China, with laterite ore and sulfide concentrate drawing from distinct geological formations. Raw material dependencies center on cobalt ore, sulfuric acid for leaching circuits, and natural gas for calcination energy. Single-source vulnerability runs through artisanal mining concentration in the DRC's copperbelt. Distribution runs through long-term offtake agreements linking mining concessions to precursor manufacturers, with spot markets serving only marginal volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cobalt powder procurement is shifting toward platform-economics dynamics as OEM direct qualification programs disintermediate precursor suppliers and create winner-take-most concentration around integrated refiners with verified circularity infrastructure.
For Market Incumbents: Consolidate through backward integration into Indonesian HPAL operations and Congolese mining partnerships to secure feedstock cost structures against merchant trader competition. Lock in OEM direct qualification pipelines by investing in European REACH-registered substance dossiers and UN 38.3 thermal runaway testing infrastructure. The priority lever rests on capturing closed-loop recycling mandates under China's MIIT recovery rate standards through precursor-to-powder circularity investments. For New Entrants and Emerging Players: Differentiate on solid-state battery pre-qualification by supplying high-purity cobalt sulfides for sulfide electrolyte catholyte interfaces under development by South Korean and Japanese manufacturers. Target energy storage system qualification as the most penetrable segment, where grid-scale NCM adoption faces less stringent automotive-grade certification barriers. Pursue research institution partnerships as a go-to-market angle to build specification credibility before automotive-tier qualification. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because EU battery passport traceability requirements and REACH registration thresholds are collapsing the qualified supplier base to integrated operations with in-house analytics and disclosure infrastructure. Acquisition targets should exhibit captive refining-to-precursor pipelines or verified recycling offtake agreements. The signal to watch is cathode chemistry roadmaps compressing cobalt intensity per kilowatt-hour faster than absolute demand growth, which would accelerate refiner consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Indonesian HPAL Operations | Morowali Industrial Park investments diversify feedstock origins beyond DRC concentration for supply security. |
| REACH-Registered Substance Dossier Investment | ECHA compliance filters out non-integrated suppliers and locks in European OEM qualification pipelines. |
| Closed-Loop Recycling Infrastructure Buildout | China's MIIT recovery rate standards create captive demand for integrated refiners with verified circularity. |
| Solid-State Battery Pre-Qualification Programs | Sulfide electrolyte catholyte specifications position early movers for next-generation chemistry supply. |
| OEM Direct Qualification Pipeline Development | BMW and Volkswagen cell supply agreements now specify raw material traceability to refiner level. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with cobalt refinery operations managers, cathode precursor procurement leads at CATL and BYD, and ESG compliance officers at European OEMs; and secondary validation through customs trade data, SEC 10-K filings from listed refiners, and MIIT battery industry standard disclosures. Bottom-up triangulation across refinery capacity utilization and precursor demand forecasts was cross-checked against top-down market sizing from trade flow analysis.
Across the modeling period, the analytical framework segmented volume and value outputs by product type, application, end-user tier, and regional production hub. CAGRs were derived from regression analysis of historical trade flows and forward projection of cathode chemistry adoption curves. Key inputs included NCM formulation roadmaps from cell manufacturer technical disclosures and Indonesian HPAL capacity expansion timelines from project development databases.
Material uncertainties — artisanal mining ESG disclosure failures, LFP chemistry substitution acceleration, and solid-state battery commercialization delays — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and OEM platform architecture decisions. Practitioners should keep alternative scenarios live as EU battery passport implementation timelines and Indonesian environmental regulation tightening evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
Germany Electric Vehicle Battery Manufacturing Market
EV Batteries
Electric Vehicle Battery Conditioners Market
EV Batteries
China EV Battery Pack Market
EV Batteries
Middle-East Electric Vehicle Battery Market
EV Batteries
Automotive Rechargeable Battery Market
EV Batteries
United Kingdom Electric Vehicle Battery Materials Market
EV Batteries
Europe Electric Vehicle Solid State Battery Market
EV Batteries
India Electric Vehicle Battery Manufacturing Market
EV Batteries
Curved Lipo Battery Market
EV Batteries
Canada EV Battery Pack Market
EV Batteries
United States Electric Vehicle Battery Anode Market
EV Batteries
EV Battery Cells Market
EV Batteries
Asia Pacific Electric Vehicle Battery Manufacturing Market
EV Batteries
Electric Vehicle Traction Batteries Market
EV Batteries
South America Electric Vehicle Battery Anode Market
EV Batteries
Spain Rechargeable Battery Market