
 Roof Vents Market | 2026-2036
Roof Vents Market Size, Share, and Industry Trends Forecast 2026-2036
Roof Vents Market Analytics
Multi-source procurement for stamped metal components is pivoting toward captive fabrication among tier-one suppliers. GAF leverages backward integration into aluminum extrusion to secure supply continuity for ridge vent programs. CertainTeed anchors its position through dedicated coil-coating partnerships that guarantee color-matched accessory lines. Kingspan Group competes via insulated panel-vent bundling that reduces field-installation complexity for commercial contractors.
Roof vents are mechanical or passive devices installed at roof peaks, ridges, or soffits to exhaust hot attic air and intake cooler ambient air, typically engineered with UV-stabilized polypropylene housings or galvanized steel flanges rated for wind uplift. Their primary purpose is moisture control and thermal load reduction in enclosed roof assemblies. Static vents dominate residential new construction due to zero operating cost and minimal maintenance, while turbine vents capture disproportionate growth in agricultural warehousing where natural convection alone proves insufficient. Metal material grades command premium positioning in commercial applications where fire-resistance ratings and hail-impact certification determine specification eligibility.
FEMA building codes in coastal US zones mandate wind-resistant vent designs, while EPA ENERGY STAR requirements filter product eligibility for utility rebate programs. OSHA fall-protection standards during rooftop installation influence contractor preferences for lighter, tool-free mounting systems. Buyers must track evolving ASHRAE ventilation standards and state-level stretch codes that will redefine minimum airflow requirements before the next replacement cycle.
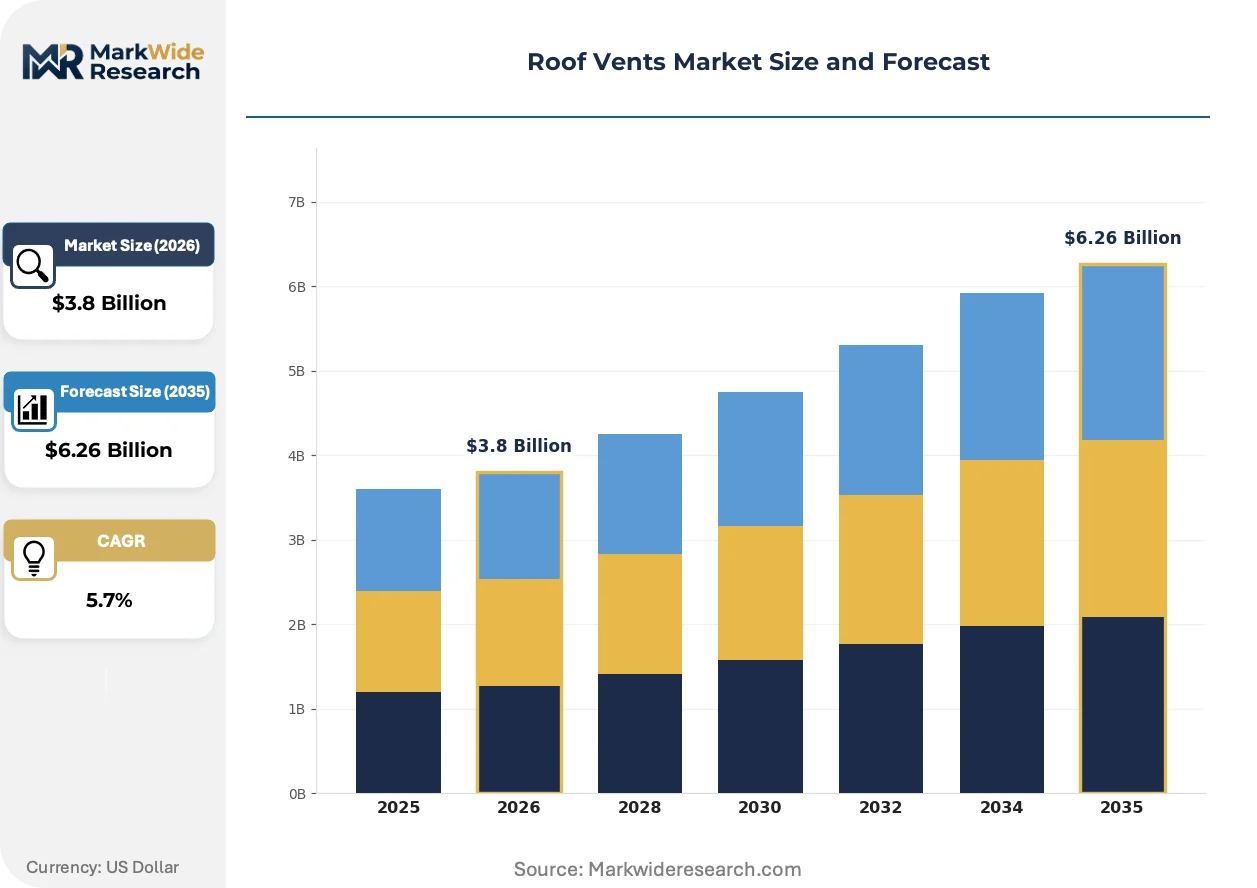
Market Dynamics
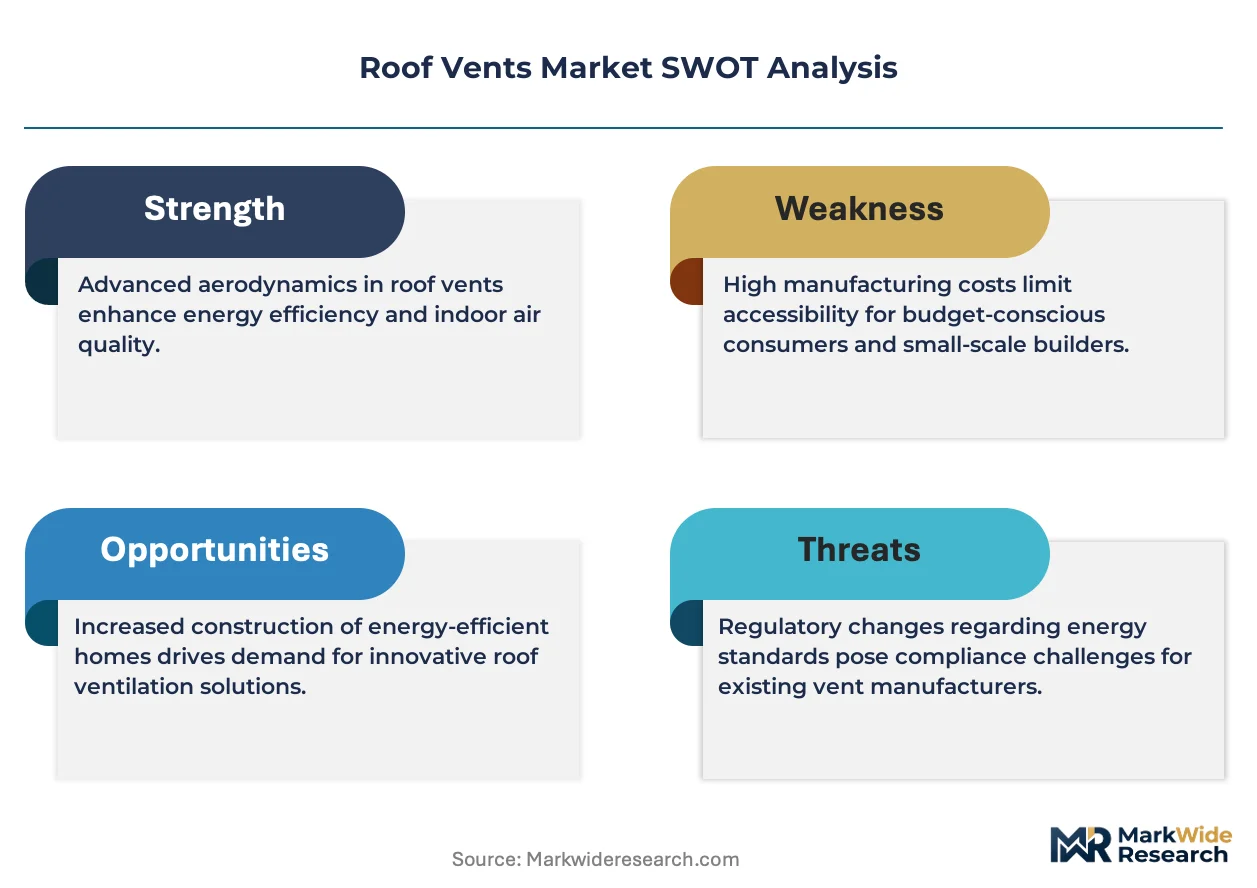
Residential retrofit cycles are compressing replacement timelines as ENERGY STAR certification requirements from the EPA filter into state-level rebate programs, forcing manufacturers to redesign product lines for whole-home ventilation compliance.
Growth Catalysts
- EPA ENERGY STAR Mandates:Whole-home ventilation certification requirements are expanding product eligibility for utility rebate programs across Sun Belt states, accelerating replacement demand.
- Agricultural Warehousing Expansion:Turbine vent adoption is surging in climate-controlled storage facilities where natural convection fails to manage moisture loads in high-humidity grain environments.
- Stamped Metal Supply Reconfiguration:Tier-one suppliers are deploying backward integration into aluminum extrusion to eliminate procurement bottlenecks for ridge vent housing production.
Market Restraints
- Aluminum Price Volatility:Extrusion-grade aluminum input costs fluctuate with energy-intensive smelting economics, compressing margin buffers for mid-tier manufacturers.
- Coastal Supply Concentration:Wind-resistant vent fabrication capacity clusters in hurricane-prone US zones, creating geographic vulnerability to seasonal demand spikes.
- Static Vent Performance Ceiling:Zero-operating-cost designs face technical limits in attic temperature reduction compared to powered alternatives, constraining premium positioning.
Strategic Opportunities
- Commercial Bundling Models:Insulated panel-vent combinations reduce field-installation complexity for contractor buyers, creating attach-rate expansion in warehouse construction.
- Tool-Free Mounting Systems:OSHA fall-protection compliance is driving specification preference for lighter rooftop installation hardware among roofing contractors.
- Color-Matched Accessory Lines:Dedicated coil-coating partnerships enable aesthetic integration with asphalt shingle palettes, penetrating premium residential retrofit segments.
Industry Challenges
- ASHRAE Standard Revision Lag:Minimum airflow requirement updates face multi-year adoption timelines across state building codes, freezing specification uncertainty.
- Fire-Resistance Certification Complexity:Commercial metal grade testing for hail-impact and flame-spread ratings extends product development cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roof Vents Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static Vents, Exhaust Vents, Intake Vents, Turbine Vents Material: Plastic, Metal, Composite, Vinyl Application: Residential, Commercial, Industrial, Agricultural Installation Type: New Construction, Retrofit, DIY, Professional |
| Companies Covered | GAF, Air Vent, Tamko Building Products, CertainTeed, BroanNuTone, Kingspan Group, Atlas Roofing Corporation, Aldes Ventilation, Elta Fans, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roof Vents Market Evolving Landscape
Product specification is pivoting from passive hardware to integrated attic climate systems as buyers demand measurable cooling-load reduction documentation.
UV-stabilized polypropylene composite housings are rewriting material selection criteria for ridge vent durability. Large-scale agricultural storage operators in the US grain belt are specifying these polymers for hail-impact resistance at 40% weight reduction versus galvanized steel. The shift is compressing metal-flange premium positioning to fire-rated commercial segments exclusively.
OSHA fall-protection standards governing rooftop work are tightening contractor equipment preferences. Tool-free mounting systems that eliminate pneumatic fastening requirements are capturing specification share among commercial roofing crews. The regulatory pressure is most acute in Texas and Florida where high-velocity wind zones already mandate enhanced uplift resistance testing.
Residential buyers are unbundling ventilation from reroofing project scopes. Homeowners now procure attic exhaust systems through standalone energy audit channels rather than contractor package offerings. The pattern concentrates in Arizona and Nevada markets where utility demand-response programs monetize cooling-load reduction separately from construction activity.
Roof Vents Market Segmentation
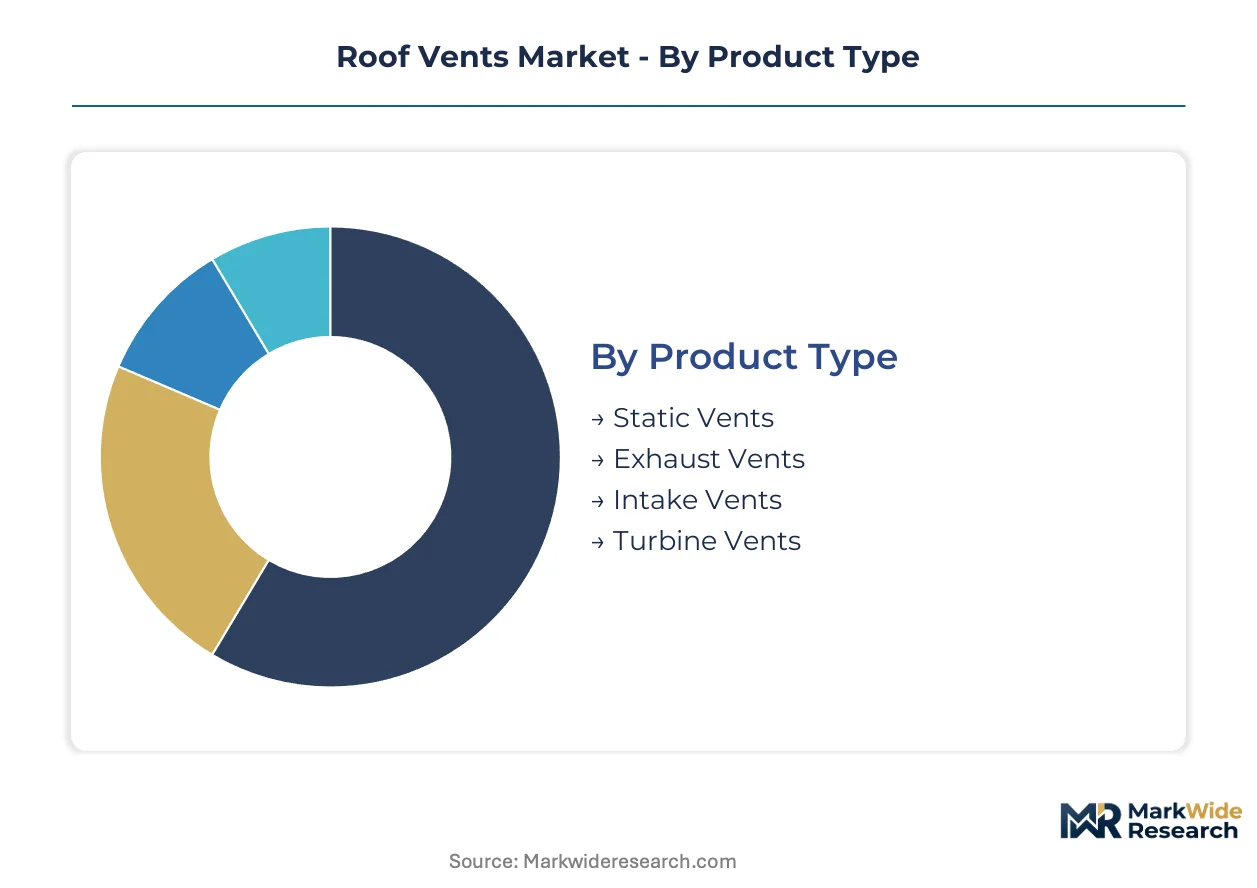
Roof vent manufacturers configure production lines around material-grade certifications and end-use fire ratings rather than universal SKUs. Specification divergence between residential retrofit channels and commercial new construction forces parallel inventory strategies that fragment procurement economics.
Product Type:
Supply concentration for ridge vent housings tilts toward extrusion-grade aluminum fabrication, while turbine assemblies cluster with sheet-metal stampers serving agricultural buyers.
- Static Vents:Passive designs with zero moving parts rely on natural convection through UV-stabilized polypropylene or galvanized steel housings. Residential new construction in Sun Belt states specifies these for ENERGY STAR compliance without electrical hookup costs.
- Exhaust Vents:Powered units with thermostatically controlled fans actively expel attic air through roof deck penetrations. Demand concentrates in Texas and Florida retrofits where cooling-load reduction qualifies for utility rebate programs.
- Turbine Vents:Wind-driven rotary extractors serve grain storage warehouses in high-humidity US agricultural zones.
- Intake Vents:Soffit-mounted designs balance exhaust airflow in balanced attic ventilation systems.
Static vents absorb the bulk of installed capacity; turbine vents are expanding most quickly.
Material:
Cost tier stratification separates commodity-grade polymers from certified metal grades requiring extended fire-resistance testing cycles.
- Metal:Galvanized steel and aluminum extrusions carry ASTM E108 fire ratings and Miami-Dade wind uplift certification. Commercial specifications in Florida and Texas mandate these for code compliance in high-velocity hurricane zones.
- Plastic:UV-stabilized polypropylene composites deliver hail-impact resistance at reduced weight for residential ridge applications. Arizona and Nevada retrofits favor these for tool-free installation compatibility.
- Composite:Hybrid formulations blend polymer housings with metal flanges for mid-tier pricing.
- Vinyl:Injection-molded soffit vents target DIY replacement channels with color-matched aesthetics.
Metal grades dominate commercial specification value; plastic alternatives are gaining share fastest in residential retrofit.
Application:
Volume concentration tracks reroofing cycles in single-family housing, while margin concentration sits with agricultural warehousing requiring moisture-control engineering.
- Residential:Single-family and multi-family attic ventilation drives replacement demand through energy audit channels. Standalone procurement in Arizona and Nevada utility territories separates ventilation from roofing contractor packages.
- Agricultural:Climate-controlled grain storage facilities specify turbine arrays for humidity management. The US grain belt concentrates demand among large-scale cooperatives operating high-throughput elevators.
- Commercial:Warehouse and retail flat-roof assemblies bundle vents with insulated metal panels.
- Industrial:Manufacturing facilities require explosion-rated exhaust configurations for process ventilation.
Residential applications anchor volume throughput; agricultural end-uses show the steepest expansion trajectory.
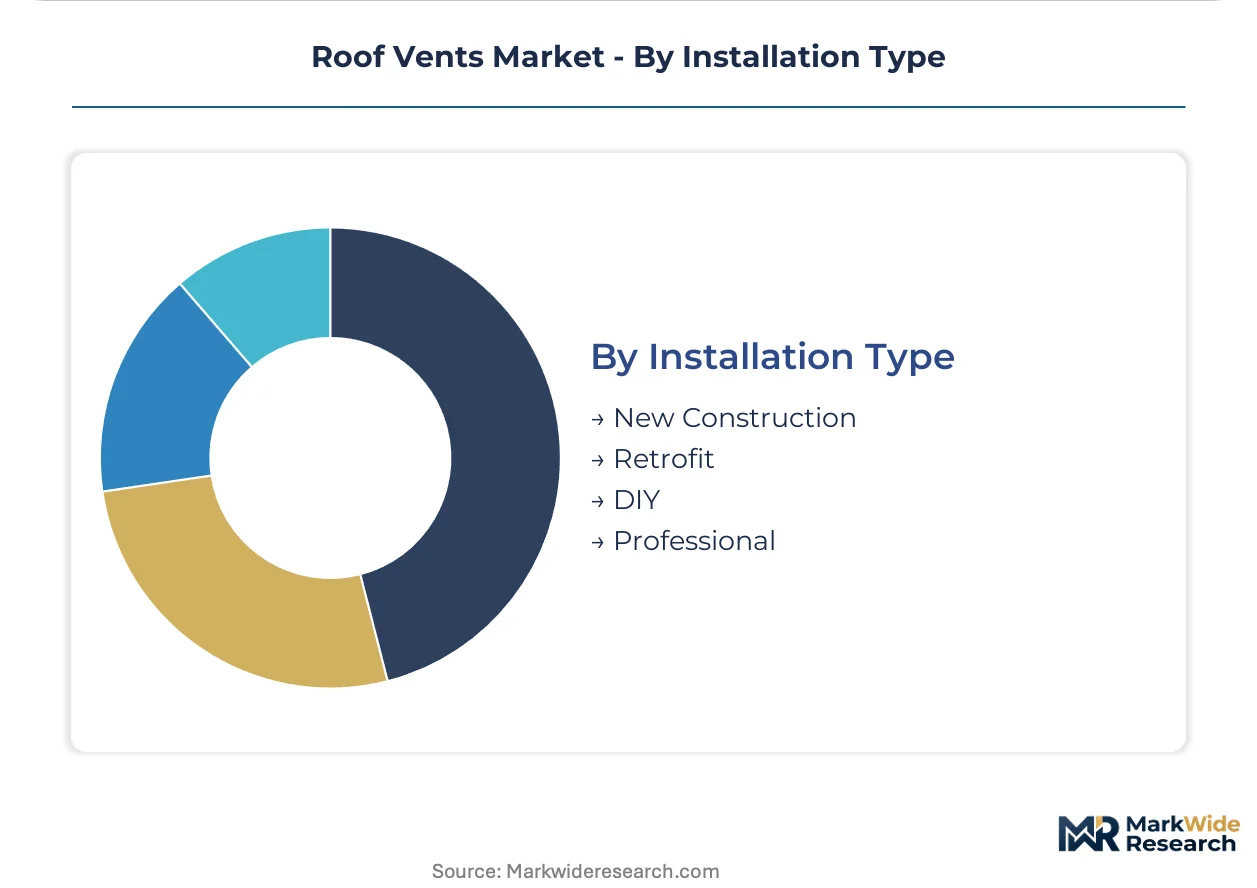
Installation Type:
Customer type bifurcation separates professional roofing crews from homeowner DIY purchases, with OSHA compliance driving specification divergence.
- Professional:Licensed roofing contractors specify tool-free mounting systems satisfying OSHA fall-protection standards. Texas and Florida crews prioritize lightweight housings reducing rooftop exposure time.
- Retrofit:Standalone attic ventilation projects outside reroofing scopes concentrate in utility demand-response territories. Arizona and Nevada homeowners procure through energy audit channels rather than construction trades.
- New Construction:Builder-grade specifications default to static vent bundles with asphalt shingle packages.
- DIY:Big-box retail channels serve homeowner self-installation with vinyl soffit and gable-end kits.
Professional installation captures premium pricing; retrofit channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extrusion-grade aluminum supply from domestic smelters anchors geographic demand concentration. EPA ENERGY STAR rebate programs and FEMA wind-resistance codes reshape procurement patterns across distinct climate zones.
United States
Sun Belt states drive retrofit volume through utility demand-response programs monetizing cooling-load reduction. FEMA coastal building codes mandate Miami-Dade certified wind-resistant designs for hurricane zones. Houston and Dallas fabrication clusters concentrate ridge vent production for residential contractor networks.
Canada
Cold-climate attic moisture management extends replacement cycles in Prairie provinces. National Building Code of Canada ventilation standards filter into provincial energy efficiency programs. Toronto and Vancouver distribution hubs serve cross-border supply chains for northern tier US markets.
Germany
Passive house construction standards elevate mechanical ventilation specification in multi-family housing. EU Energy Performance of Buildings Directive compliance deadlines accelerate building envelope upgrades. Bavarian and Baden-Württemberg industrial zones host metal fabrication for fire-rated commercial vent systems.
China
Rapid urbanization in Yangtze River Delta megacities expands commercial warehouse construction requiring integrated panel-vent bundles. GB standards for building ventilation establish minimum airflow requirements for industrial facilities. Shenzhen and Guangzhou manufacturing bases export stamped metal components to Southeast Asian construction markets.
Australia
Bushfire-prone regions in New South Wales and Victoria specify ember-resistant metal vent designs under AS 3959 construction standards. Residential solar PV penetration creates attic heat-load management challenges driving retrofit demand. Melbourne and Sydney distribution networks serve dispersed coastal and inland markets.
Roof Vents Market Competitive Landscape
Backward integration into aluminum extrusion dominates the current landscape among tier-one suppliers seeking supply continuity. The vendor base stratifies across three tiers: integrated building materials conglomerates with captive metal fabrication, specialized ventilation component manufacturers, and regional sheet-metal stampers serving agricultural buyers. Two archetypes command premium positioning: conglomerates bundling vents with roofing systems, and specialists engineering tool-free mounting for OSHA compliance. Competitive moves cluster on captive supply of stamped components and coil-coating partnerships guaranteeing color-matched accessory lines.
Among North American building materials conglomerates, GAF and CertainTeed exemplify the integrated archetype through backward integration into aluminum supply chains. Kingspan Group occupies a position bridging commercial insulated panel systems with ventilation hardware. These three anchors represent distinct strategic vectors: captive metal fabrication, dedicated coating partnerships, and panel-vent bundling for contractor efficiency.
| Leading Market Players |
|---|
| GAF |
| Air Vent |
| Tamko Building Products |
| CertainTeed |
| BroanNuTone |
| Kingspan Group |
| Atlas Roofing Corporation |
| Aldes Ventilation |
| Elta Fans |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap metal fabricators in the US Sun Belt anchor production capacity for ridge vent housings, linking generational ownership patterns to disciplined pricing power in extrusion-grade aluminum procurement. Their consolidation resistance has preserved margin structures even as commodity input costs fluctuate, though private-equity-rolled-up specialists in Texas and Florida are beginning to compress aftermarket pricing through captive coil-coating operations.
Pricing Analysis
Warranty and installation-service bundling separates premium roofing contractor channels from unbundled DIY retail, with Miami-Dade wind certification acting as the primary price differentiation driver alongside ENERGY STAR rebate eligibility. Three-tier pricing structure across premium, standard, and economy levels stratifies by metal grade and fire-resistance testing investment, with cost compression in mid-tier plastic alternatives intensifying due to UV-stabilized polypropylene oversupply. Residential retrofit buyers through energy audit channels show lowest price sensitivity, while big-box DIY purchasers drive economy-tier volume.
Supply Chain Analysis
Extrusion-grade aluminum supply rests on domestic US smelters, Chinese semi-finished exports, and Canadian rolling mills, with galvanized steel coil feeding from Mexican and South Korean producers. UV-stabilized polypropylene resin draws from Gulf Coast petrochemical complexes, while stamped metal components hinge on regional fabrication clusters in Houston and Dallas. Single-source vulnerability concentrates in Miami-Dade certified wind-resistant vent production, where coastal fabrication capacity faces seasonal demand spikes. Distribution runs through roofing contractor networks, big-box retail, and direct-to-builder supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where EPA ENERGY STAR compliance costs and fire-resistance certification complexity force sub-scale fabricators toward exit or acquisition. Backward integration pressure and rebate program eligibility requirements are accelerating this structural thinning.
For Market Incumbents: Cement supply continuity through captive aluminum extrusion capacity in Texas and Florida, insulating ridge vent programs from commodity volatility. Deepen coil-coating partnerships to guarantee color-matched accessory lines against emerging competitors. Threat substitution from UV-stabilized polypropylene alternatives demands accelerated metal-grade certification investment to preserve commercial specification share. For New Entrants and Emerging Players: E-commerce direct channels targeting Arizona and Nevada energy audit territories offer the most penetrable entry vector, bypassing established roofing contractor networks. Agricultural warehousing turbine vent segments present white-space opportunity where natural convection engineering expertise remains scarce. Tool-free mounting system development for OSHA compliance captures specification preference among commercial roofing crews. For Investors and Strategic Acquirers: EPA ENERGY STAR program expansion into additional Sun Belt states is the leading indicator that rebate-driven replacement demand will concentrate among certified manufacturers. Long-term viability favors vertically integrated producers with captive metal fabrication and established utility program relationships. Acquisition targets should display Miami-Dade certification portfolios and coil-coating infrastructure. Watch state-level stretch code adoption timelines as the inflection signal for specification requirement shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | GAF's captive supply chain eliminates procurement bottlenecks for ridge vent housing production. |
| Coil-Coating Partnership Expansion | CertainTeed's dedicated partnerships guarantee color-matched accessory lines for premium residential retrofits. |
| Panel-Vent Bundling for Commercial | Kingspan's integrated offerings reduce field-installation complexity for warehouse contractors. |
| Tool-Free Mounting System Development | OSHA fall-protection compliance drives specification preference among Texas and Florida roofing crews. |
| Utility Rebate Program Certification | EPA ENERGY STAR eligibility unlocks demand-response monetization in Arizona and Nevada markets. |
Research Methodology
SEC 10-K filings, EPA ENERGY STAR certification databases, and Miami-Dade County product approval records formed the secondary backbone, supplemented by customs data tracking aluminum extrusion and galvanized steel coil imports. Primary interviews with roofing contractor purchasing managers, building materials distribution executives, and utility demand-response program administrators validated secondary findings. Bottom-up and top-down triangulation cross-checked manufacturer shipment data against regional construction permit flows and reroofing cycle estimates.
Bottom-up modeling anchored volume projections to segment-level replacement rates and new construction attachment ratios, while top-down validation tested aggregate figures against macro construction spending patterns across the analysis window. Segmentation dimensions included product type, material grade certification, end-use application, and installation channel. CAGRs derived from fitted trend analysis incorporating ENERGY STAR program expansion schedules and ASHRAE standard revision timelines. Industry-specific inputs comprised FEMA wind zone building code adoption curves and agricultural warehousing construction permits in the US grain belt.
The model holds under stable regulatory compliance timelines and intact rebate program funding; deviation in ASHRAE standard adoption schedules or aluminum smelting energy cost spikes would shift trajectory. Forecasts embed assumptions regarding ENERGY STAR eligibility expansion and state stretch code harmonization. A small set of named triggers—EPA program restructuring, hurricane season severity affecting coastal fabrication, and polypropylene resin supply disruptions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
Tunnel and Metro Fans Market
HVAC Systems
Thermostatic Faucet Market
HVAC Systems
Reverse Flame Steam Boiler Market
HVAC Systems
Aeration System Market
HVAC Systems
Global Commercial Insulation Market
HVAC Systems
Air Pressure Booster System Market
HVAC Systems
Corrugated Air Duct Market
HVAC Systems
Ductless HVAC System Market
HVAC Systems
South Korea Commercial HVAC Market
HVAC Systems
Cold Insulation Market
HVAC Systems
North America Building Thermal Insulation Market
HVAC Systems
Industrial Exhaust Fan Market
HVAC Systems
Residential Hydronic Underfloor Heating Market
HVAC Systems
Global Chilled Beam System Market
HVAC Systems
HVAC Insulation Market
HVAC Systems
Spray Booth Ventilation System Market