
 Gas Wall Hung Boilers Market | 2026-2036
Gas Wall Hung Boilers Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Wall Hung Boilers Market Insights
Capital-intensity divergence between mass-market assemblers and precision-engineering specialists is bifurcating competitive dynamics in the Gas Wall Hung Boilers Market. Bosch Thermotechnology leverages captive heat-exchanger manufacturing to sustain margin resilience across European replacement cycles. Viessmann anchors premium positioning through in-house stainless-steel combustion technology. Rinnai Corporation competes aggressively in Asia-Pacific residential markets with compact condensing architectures.
Gas wall hung boilers are self-contained, wall-mounted heating appliances that generate hot water for space heating and domestic use through natural gas combustion, typically achieving efficiency ratings above 90% through condensing technology that recovers latent heat from flue gases. Their primary purpose is to deliver decentralized, on-demand thermal energy in residential and light commercial buildings where floor space constraints preclude floor-standing units. Combi boilers dominate new residential installations by eliminating separate hot-water cylinder requirements, while high-efficiency condensing models command the fastest growth trajectory as regulatory minimums tighten across mature markets. System boilers retain structural importance in larger homes with high simultaneous hot-water demand, where separate storage vessels remain necessary.
EU Ecodesign and Energy Labelling regulations, enforced by national market surveillance authorities in Germany, Italy, and France, mandate minimum seasonal efficiency thresholds that progressively phase out non-condensing boiler sales. The US Department of Energy and EPA set parallel efficiency and emissions standards through ENERGY STAR certification and regional NOx limits. China's GB standards and MIIT directives impose analogous efficiency tiers for domestic gas appliances. Stakeholders must monitor hydrogen-readiness certifications and blending compatibility as decarbonization pathways reshape burner engineering requirements and product lifecycle planning.
Market Dynamics
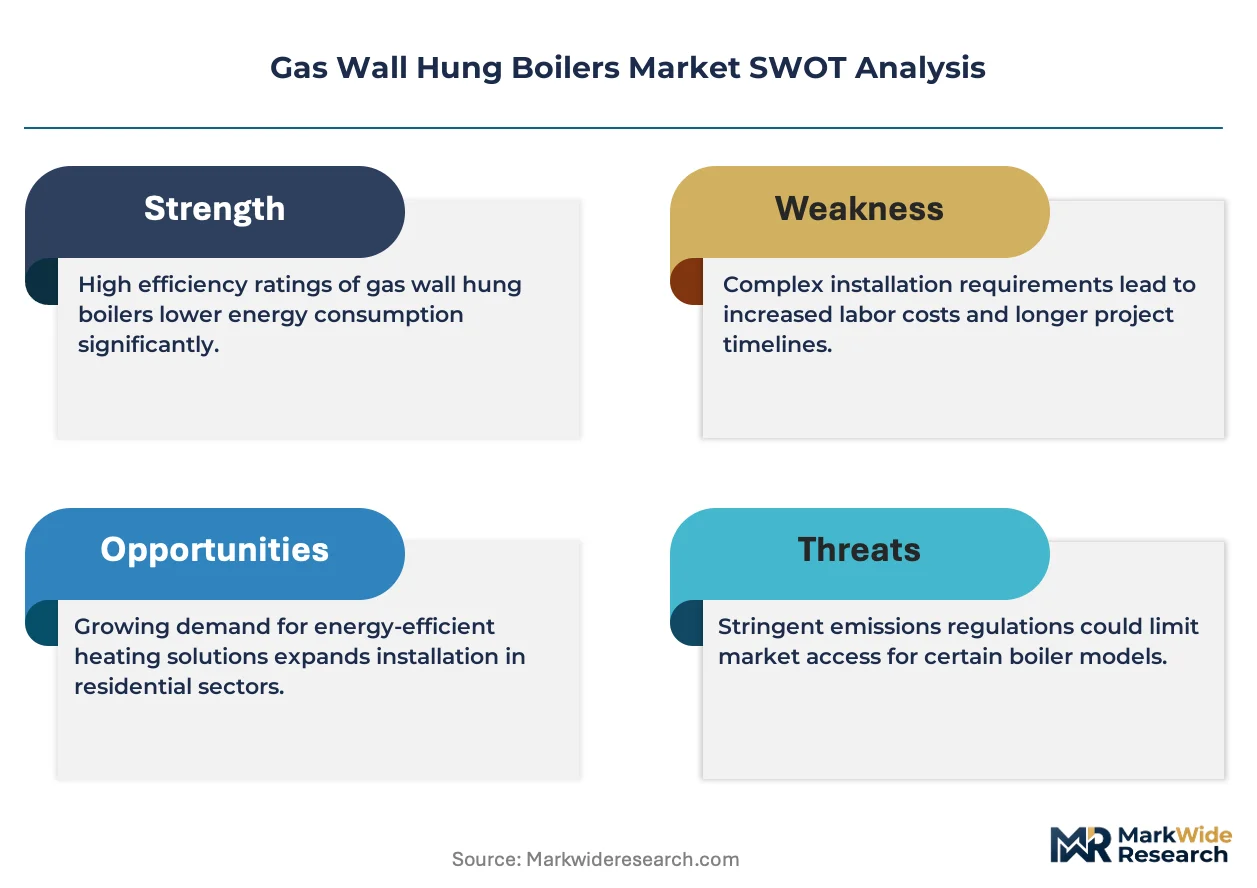
EU Ecodesign efficiency thresholds are forcing a wholesale replacement cycle across Europe's installed base of non-condensing boilers, compressing product lifecycles and rewiring manufacturer R&D priorities toward hydrogen-ready burner architectures.
Growth Catalysts
- Regulatory Phase-Out Mandates:EU Ecodesign Directive 2009/125/EC progressively bans non-condensing boiler sales, creating guaranteed replacement demand across Germany, Poland, and Italy as enforcement tightens through national market surveillance authorities.
- Residential Retrofit Programs:Northern European housing stock modernization initiatives concentrate demand for high-efficiency condensing units, with combi boilers eliminating separate hot-water cylinder requirements in space-constrained urban dwellings.
- Heat Pump Hybridization:Bivalent system configurations pairing gas wall hung boilers with electric heat pumps are gaining traction in cold-climate zones where standalone electrification proves insufficient for peak winter loads.
Market Restraints
- Copper and Stainless Steel Volatility:Heat-exchanger material costs fluctuate with commodity markets, squeezing assembler margins when long-term procurement contracts cannot absorb spot price spikes.
- Natural Gas Infrastructure Lock-In:Pipeline network dependency in Eastern European markets creates stranded asset risk as hydrogen blending timelines remain uncertain and grid conversion capital requirements mount.
- Electrification Substitution:Air-source heat pumps achieve cost parity in moderate climates, displacing gas boiler installations in new-build residential construction across France and the Netherlands.
Strategic Opportunities
- Hydrogen-Ready Certification Gap:Early movers securing H2-ready burner approvals under developing EU standardization frameworks will capture premium positioning ahead of mandatory blending mandates.
- Service Contract Monetization:Predictive maintenance platforms leveraging IoT combustion diagnostics enable recurring revenue streams from installed base management, shifting value capture from hardware to lifecycle services.
- Compact Condensing Architectures:Asian residential markets with severe space constraints present white space for ultra-compact wall hung units adapted to smaller dwelling footprints and lower flow-rate requirements.
Industry Challenges
- Combustion Engineering Talent Scarcity:Specialized expertise in low-NOx burner design and hydrogen flame stabilization is concentrating at a handful of European engineering centers, constraining product development velocity.
- Multi-Fuel Certification Complexity:Hydrogen, biomethane, and natural gas blending compatibility testing extends type-approval timelines, delaying market entry and inflating R&D overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Wall Hung Boilers Market |
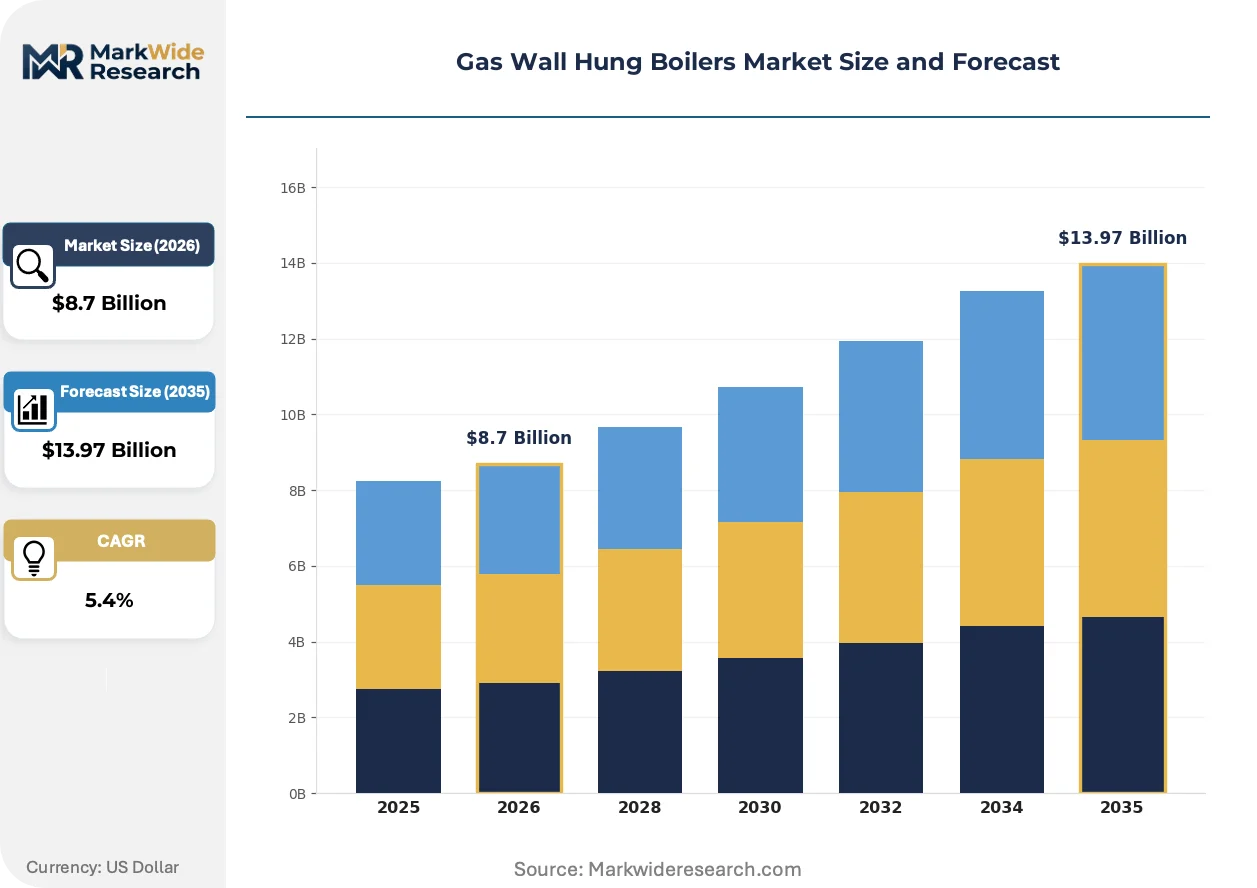
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Combi Boilers, System Boilers, Conventional Boilers, High-Efficiency Boilers End User: Residential, Commercial, Industrial, Government Installation Type: New Installation, Replacement Installation, Retrofits, Upgrades Fuel Type: Natural Gas, Propane, Biogas, Others |
| Companies Covered | Vaillant Group, Bosch Thermotechnology, Viessmann, BDR Thermea Group, Ariston Thermo Group, Rinnai Corporation, Ferroli, KD Navien, Immergas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Wall Hung Boilers Market Trends and Innovations
Condensing technology maturation is compressing efficiency differentiation, pushing competitive advantage toward smart control integration and fuel-flexibility engineering as primary value levers.
Modular heat-exchanger architectures are decomposing traditional monolithic casting designs into standardized, replaceable sub-assemblies. German and Austrian OEMs are adopting these platforms to reduce field service costs and extend product service life. This decomposition is compressing aftermarket parts margins while enabling faster model refresh cycles.
REACH Regulation substance restrictions on chromium VI in surface treatments are forcing heat-exchanger coating substitutions across EU-manufactured units. Industrial consequence includes accelerated qualification timelines for alternative corrosion protection technologies. Premium stainless-steel models are absorbing compliance costs through material specification upgrades.
Digital procurement platforms are fragmenting traditional wholesale distribution in residential replacement markets. Installers in the UK and Netherlands now source equipment through direct-to-trade e-commerce channels, disintermediating regional distributors. This channel shift concentrates price transparency and compresses regional margin buffers.
Gas Wall Hung Boilers Market Segmentation
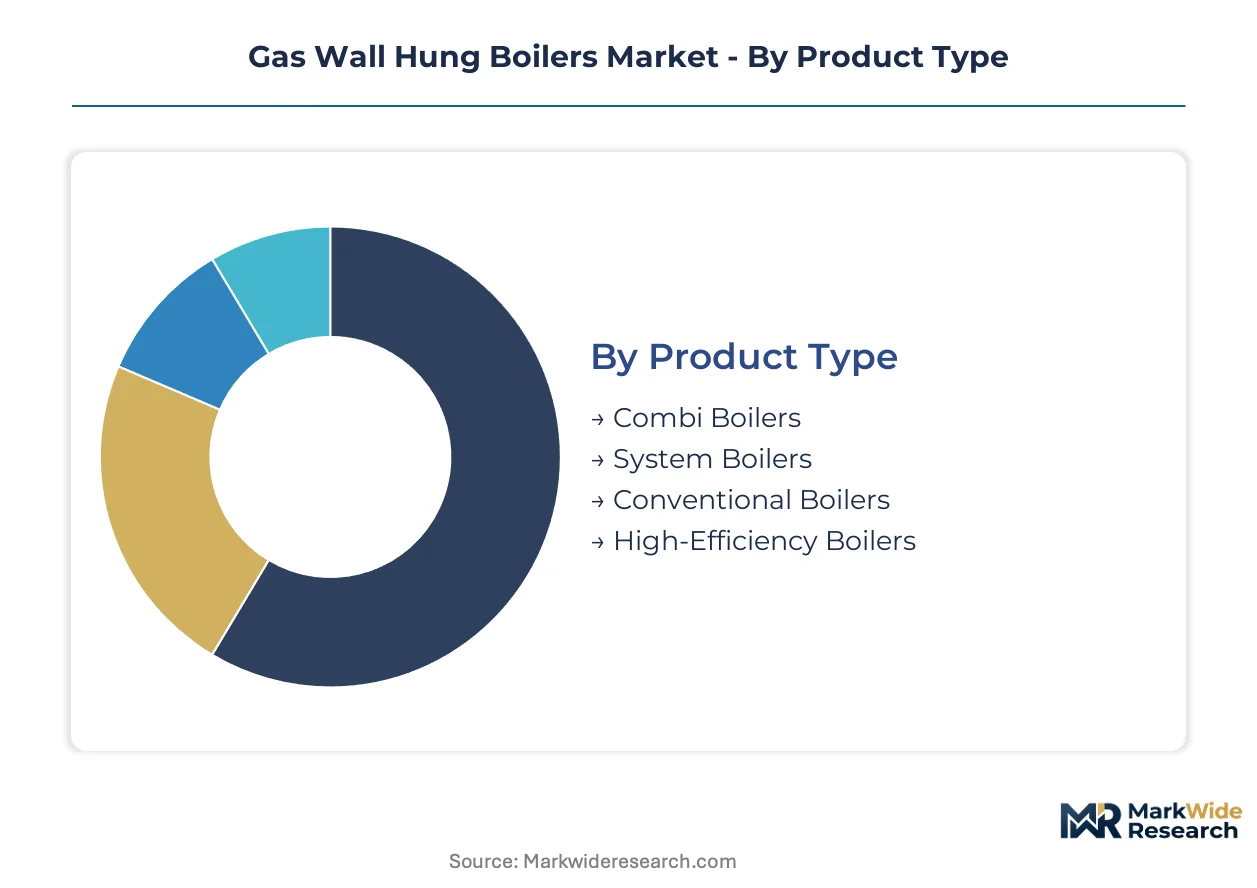
Segmentation in the Gas Wall Hung Boilers Market reveals distinct channel pathways: combi boilers flow through retail and direct-to-installer platforms for residential replacement, while system and conventional units concentrate in project-specified commercial contracts. Understanding these flow patterns clarifies where margin compression versus premium capture occurs.
Product Type:
Channel mix varies sharply by product architecture. Combi boilers dominate e-commerce and wholesale distributor volumes for residential retrofit. System and conventional units concentrate in specification-driven commercial project channels where engineering consultants influence selection.
- Combi Boilers:Integrated space-heating and instantaneous hot-water systems eliminate cylinder requirements through plate heat-exchanger technology. Demand concentrates in UK and German urban residential retrofits where EU Ecodesign enforcement accelerates non-condensing replacement cycles.
- System Boilers:Units with built-in expansion vessels and pumps designed for separate hot-water storage cylinders. Expansion concentrates in larger French and Italian residential properties with high simultaneous hot-water demand where flow rates exceed combi capacity.
- Conventional Boilers:Heat-only units requiring external system components including pumps and expansion vessels. Channel flow remains concentrated in legacy commercial installations.
- High-Efficiency Boilers:Condensing units recovering latent heat from flue gases through secondary heat-exchangers. Premium positioning in Northern European energy renovation programs.
Combi boilers dominate installed base. High-efficiency condensing architectures are where expansion concentrates fastest.
End User:
Cost tier stratification separates mass-market residential volumes from premium commercial and industrial specifications. Residential procurement emphasizes first-cost sensitivity and installation speed. Commercial and government segments prioritize lifecycle efficiency and maintenance contract integration.
- Residential:Single-family and multi-family dwellings with decentralized heating requirements. Channel flow through installer networks and direct-to-trade digital platforms in UK and Netherlands markets.
- Commercial:Offices, retail, and hospitality with higher duty cycles and redundancy requirements. Specification influence from M&E consultants concentrates demand in German and French project markets.
- Industrial:Light manufacturing and process heat applications with custom burner configurations. Niche positioning through specialized system integrators.
- Government:Public housing and institutional buildings subject to public procurement efficiency mandates. Tender-based volume concentration in municipal retrofit programs.
Residential captures volume concentration. Commercial and government segments concentrate margin expansion through service bundling.
Installation Type:
Application context determines technical specification depth and channel engagement intensity. Replacement installations demand rapid deployment with minimal disruption. New installations and retrofits allow extended engineering and commissioning cycles.
- New Installation:First-fit in residential construction and commercial developments. Channel flow through developer procurement teams and M&E contractors with specification influence from architects.
- Replacement Installation:Direct swap of failed or end-of-life units in existing buildings. Emergency response requirements concentrate demand in installer service networks with same-day availability.
- Retrofits:System upgrades integrating with renewable heat sources or building energy renovations. Engineering-intensive channel through specialized contractors in German KfW-funded programs.
- Upgrades:Efficiency improvements and control system modernizations of functional units. Preventive replacement channel through manufacturer service contracts.
Replacement installations dominate transaction frequency. Retrofits represent the steepest expansion trajectory as building renovation rates accelerate.
Fuel Type:
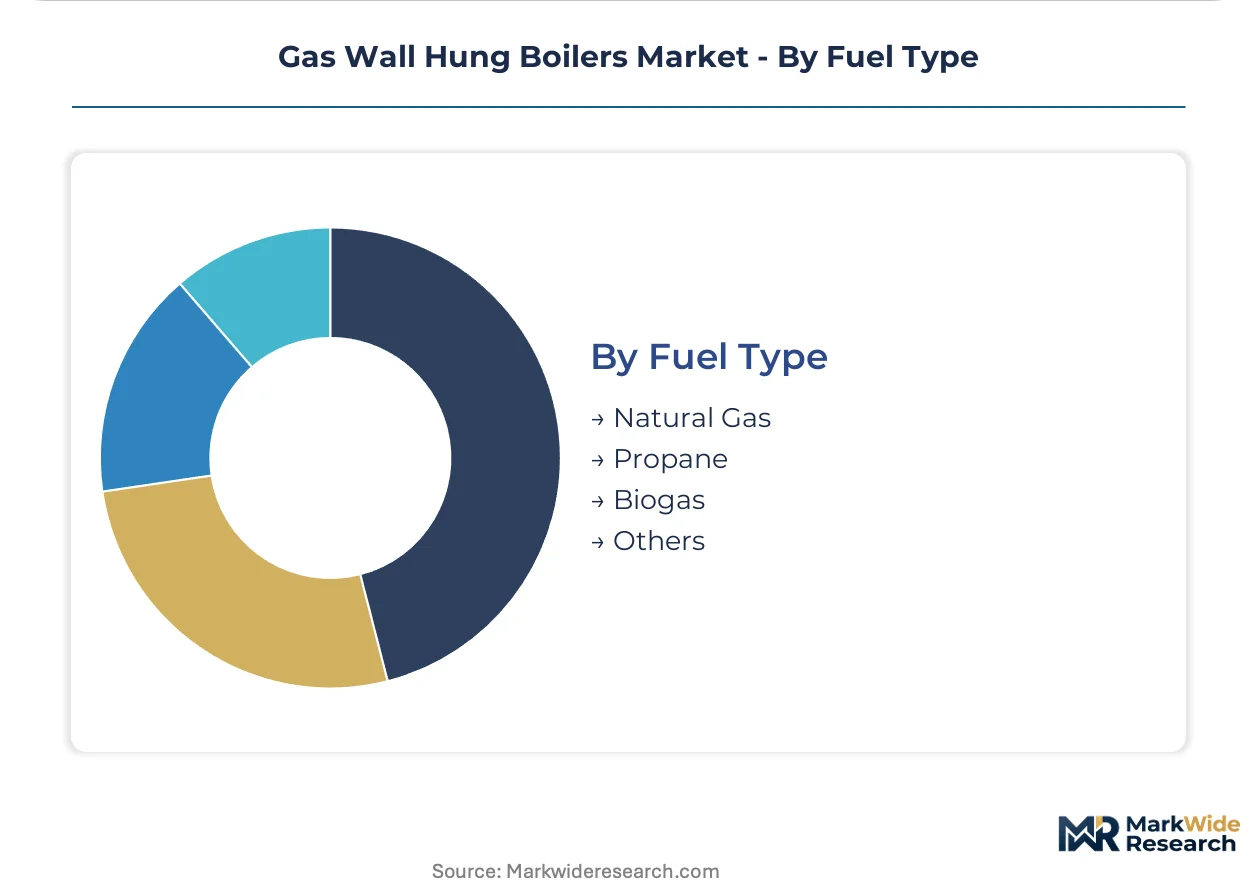
Supply concentration and infrastructure lock-in shape geographic deployment patterns. Natural gas networks enable mass-market penetration. Alternative fuels concentrate in specific regional infrastructure configurations and policy incentive zones.
- Natural Gas:Methane-based combustion with established distribution infrastructure across European urban centers. Volume concentration in grid-connected German, Italian, and Polish markets.
- Propane:Liquefied petroleum gas for rural and off-grid locations beyond pipeline reach. Demand clusters in French and Spanish rural residential markets.
- Biogas:Upgraded biomethane from anaerobic digestion with carbon-neutral combustion credentials. Deployment concentrates in German and Danish agricultural regions with local biogas production.
- Others:Hydrogen blends and synthetic methane in pilot programs. Early-stage positioning in Dutch and UK hydrogen trial zones.
Natural gas anchors installed base. Biogas and hydrogen-ready alternatives are where technology transition investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Poland and Romania exhibit acute price sensitivity as non-condensing replacement cycles accelerate, while German and Dutch purchasers absorb premium pricing for hydrogen-ready certification. This elasticity divergence fragments manufacturer pricing power across adjacent markets.
Germany
Residential housing stock modernization drives replacement demand across the Ruhr industrial belt and Bavarian suburbs. The Federal Office for Economic Affairs and Export Control enforces EU Ecodesign compliance through tightened seasonal efficiency thresholds. Stuttgart engineering clusters concentrate hydrogen-ready burner development programs ahead of blending mandates.
United Kingdom
Combi boiler penetration peaks in London and Southeast England terraced housing where cylinder elimination saves space. The Department for Business, Energy and Industrial Strategy administers Boiler Upgrade Scheme incentives for high-efficiency replacements. Manchester installer networks pilot predictive maintenance platforms leveraging IoT combustion diagnostics.
Poland
Coal-to-gas heating transitions accelerate in Krakow and Upper Silesia urban agglomerations as smog reduction policies bite. The Energy Regulatory Office monitors natural gas distribution infrastructure expansion into previously coal-dependent districts. Warsaw wholesale distributors stock volume-focused condensing models for price-sensitive retrofit contractors.
Italy
System boiler demand concentrates in Lombardy and Emilia-Romagna multi-family dwellings with high simultaneous hot-water requirements. The Ministry of Ecological Transition implements Superbonus 110% tax credits for building energy renovations including boiler replacements. Bologna engineering consultancies specify bivalent heat-pump hybrid configurations for cold-climate Alpine foothill zones.
China
Compact condensing architectures penetrate Beijing-Tianjin-Hebei and Yangtze River Delta residential markets with severe space constraints. The Ministry of Industry and Information Technology imposes GB standard efficiency tiers for domestic gas appliances. Shanghai manufacturing clusters adapt European burner technologies for lower flow-rate requirements in smaller dwelling footprints.
Gas Wall Hung Boilers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Gas Wall Hung Boilers Market. German and Japanese conglomerates with captive heat-exchanger manufacturing control premium positioning, while mid-scale Italian and Korean assemblers compete on volume flexibility. Three archetypes dominate: vertically integrated technology owners, regional volume specialists, and emerging-market cost optimizers. Capacity expansion in hydrogen-ready burner platforms and strategic partnerships for IoT-enabled service contracts constitute the dominant competitive moves.
Within the integrated technology tier, Bosch Thermotechnology and Viessmann exemplify engineering-intensive positioning through in-house combustion system development. Rinnai Corporation anchors Asia-Pacific market presence with compact architectural specialization. These three occupy positions spanning European regulatory compliance leadership and Asian residential space-constraint adaptation.
| Leading Market Players |
|---|
| Vaillant Group |
| Bosch Thermotechnology |
| Viessmann |
| BDR Thermea Group |
| Ariston Thermo Group |
| Rinnai Corporation |
| Ferroli |
| KD Navien |
| Immergas |
| Others |
Pricing and Supply Chain Analysis
Long-term procurement contracts for copper and stainless steel heat-exchanger materials lock in both supply access and price visibility for German and Italian OEMs, insulating margin resilience against commodity volatility while constraining flexibility for spot-market assemblers in Poland and Romania.
Pricing Analysis
After-sales service contracts and predictive maintenance subscriptions drive lifetime value capture beyond hardware margins. Three-tier pricing structure across premium hydrogen-ready, standard condensing, and economy non-condensing levels segments buyer willingness-to-pay. Cost compression in economy tiers is intensifying because Polish and Romanian distributors prioritize volume procurement over efficiency certification. Residential retrofit contractors exhibit acute price sensitivity, while commercial M&E consultants absorb premium pricing for lifecycle efficiency guarantees.
Supply Chain Analysis
China and Germany anchor heat-exchanger fabrication and precision burner assembly respectively, with Italy contributing control system electronics. Raw material flows draw from Chilean copper concentrate, German stainless-steel sheet, and Taiwanese semiconductor components for IoT modules. Single-source vulnerability concentrates in European stainless-steel combustion chamber supply. Distribution runs through wholesale distributor networks in mature markets and direct-to-installer digital platforms in the UK and Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where EU Ecodesign certification timelines and hydrogen-ready type-approval processes create structural barriers that delay competitive entry.
For Market Incumbents: Shield installed base relationships through predictive maintenance platform deployment and captive heat-exchanger manufacturing expansion in Germany. Electrification substitution from air-source heat pumps threatens residential new-build volumes, demanding accelerated hydrogen-ready burner R&D to extend gas infrastructure relevance. For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Italy or Poland opens access to EU replacement demand without full R&D infrastructure. White space concentrates in Asian compact condensing architectures for space-constrained dwellings and biogas-compatible burner systems for German agricultural regions. Channel entry through direct-to-installer e-commerce platforms bypasses entrenched wholesale relationships. For Investors and Strategic Acquirers: Capital is best deployed toward engineering-intensive specialists with hydrogen-ready certification pipelines and IoT-enabled service contract revenue streams. Long-term viability hinges on fuel-flexibility engineering capabilities rather than pure manufacturing scale. Watch hydrogen blending mandate announcements from Dutch and German energy regulators as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Certification Investment | Early movers securing EU standardization approvals capture premium positioning ahead of mandatory blending timelines. |
| Predictive Maintenance Platform Launch | IoT combustion diagnostics shift value capture from hardware sales to recurring lifecycle service revenues. |
| Backward Integration into Heat-Exchanger Manufacturing | Captive stainless-steel production insulates margin resilience against commodity volatility and REACH compliance costs. |
| Compact Condensing Architecture Development | Ultra-compact units adapted for Asian dwelling footprints unlock penetration in space-constrained urban markets. |
| Biogas Compatibility Engineering | Burner systems certified for upgraded biomethane capture carbon-neutral positioning in German agricultural zones. |
Research Methodology
A spread of perspectives from OEM product managers, installer network heads, M&E consulting engineers, and national market surveillance authorities converged on the working assumptions underpinning this analysis. Primary fieldwork combined structured interviews with secondary validation against EU Ecodesign enforcement data, GB standard efficiency filings, and customs trade records for heat-exchanger material flows. Bottom-up unit economics triangulated against top-down regulatory replacement cycle modeling.
Segmentation dimensions modeled span product architecture, end-user cost tier, installation context, and fuel type compatibility across the projection horizon. CAGRs were derived from replacement cycle velocity analysis and efficiency mandate phase-out schedules. Industry-specific inputs include hydrogen blending timeline scenarios and residential renovation program funding allocations.
Decision-makers should treat outputs as directional under base assumptions of steady EU Ecodesign enforcement and natural gas infrastructure persistence; material deviation would warrant model refresh. Hydrogen mandate acceleration or heat pump cost parity breakthroughs represent specific risk factors that could revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
Europe HVAC Services Market
HVAC Systems
Global Tunnel and Metro Ventilation Market
HVAC Systems
Ductless HVAC System Market
HVAC Systems
Split Air Conditioning Systems Market
HVAC Systems
HVAC Insulation Market
HVAC Systems
Global Building Thermal Insulation Material Market
HVAC Systems
Saudi Arabia Building Thermal Insulation Market
HVAC Systems
UK Commercial Boiler Market
HVAC Systems
Corrugated Air Duct Market
HVAC Systems
North America and GCC HVAC Insulation Market
HVAC Systems
North America Scrubber System Market
HVAC Systems
Tunnel and Metro Ventilation Fans Market
HVAC Systems
HVAC Blower and Fan Systems Market
HVAC Systems
HVAC and Fire Protection Insulation Market
HVAC Systems
Tunnel and Metro Fans Market
HVAC Systems
Europe Residential Heat Pump Market