
 Global Endodontics Market | 2026-2036
Global Endodontics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Endodontics Market Foresight
Capital-intensity divergence between automated rotary system manufacturers and manual instrument suppliers is redrawing competitive boundaries. Dentsply Sirona leverages integrated CAD/CAM workflows to dominate high-value segments. Envista sustains R&D intensity across nickel-titanium alloy formulations. Ultradent Products specializes in irrigant chemistry, occupying a defensible niche.
Endodontics encompasses the diagnosis and treatment of dental pulp and periapical tissue pathologies, employing nickel-titanium rotary files with taper designs of 0.04–0.12 and apex locators measuring impedance at frequencies up to 400 kHz to ensure working-length accuracy. The discipline serves to preserve natural dentition and prevent systemic infection. Rotary systems lead product type value generation due to instrument longevity and reduced chair time, while irrigation systems capture expanding margin pools as clinicians adopt adjunctive antimicrobial protocols. Specialty dental clinics anchor end-user demand, though academic and research institutes are accelerating validation of novel reciprocating motion technologies.
FDA 510(k) clearance pathways govern nickel-titanium file market entry in the United States, while the EU MDR imposes strengthened clinical evidence requirements for reusable endodontic devices. ISO 3630-1 standards define dimensional tolerances for endodontic instruments, directly shaping manufacturer quality systems and batch-release protocols. Stakeholders must monitor evolving biocompatibility testing mandates and reciprocating system reimbursement decisions across national health frameworks.
Market Dynamics
The EU Medical Device Regulation's tightened biocompatibility mandates for nickel-titanium instruments are forcing manufacturers to revalidate entire product portfolios while specialty clinics simultaneously demand precision-engineered rotary systems that reduce procedural chair time.
Growth Catalysts
- Reciprocating Motion Technology:Single-file reciprocating systems reduce instrument fatigue and fracture risk, accelerating adoption across academic dental institutes validating clinical outcomes.
- China's Dental Infrastructure Investment:Provincial health authorities are expanding practitioner training programs and equipping public hospitals with advanced endodontic suites.
- ISO 3630-1 Standardization:Harmonized dimensional tolerances for endodontic instruments enable manufacturers to streamline batch-release protocols and cross-border certification.
Market Restraints
- Nickel-Titanium Alloy Supply Concentration:Premium-grade nitinol wire production clusters in a limited number of specialized metallurgical facilities, exposing instrument manufacturers to input volatility.
- EU MDR Clinical Evidence Requirements:Strengthened documentation demands for reusable endodontic devices extend regulatory timelines and inflate compliance expenditure for mid-tier suppliers.
- Thermomechanical Processing Limitations:Conventional heat treatment methods constrain the achievable fatigue resistance in rotary file designs, capping performance differentiation.
Strategic Opportunities
- Brazil's Underserved Municipal Networks:Public oral health programs in São Paulo and Minas Gerais states present volume procurement channels for cost-optimized manual instrument portfolios.
- Irrigant-Antibiotic Convergence:Adjunctive antimicrobial protocols combining sodium hypochlorite with novel delivery vehicles open margin expansion for chemistry specialists.
- India's PLI Scheme for Medical Devices:Production-linked incentives for domestic manufacturing of precision surgical instruments reduce landed cost disadvantages for regional assembly operations.
Industry Challenges
- Microscopic Fracture Detection Skill Gap:Clinicians require specialized training to interpret scanning electron microscopy images for instrument failure analysis, creating bottlenecks in quality assurance workflows.
- CAD/CAM Integration Complexity:Legacy practice management systems in established dental clinics resist seamless data exchange with digital apex locators and cone-beam computed tomography platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Endodontics Market |
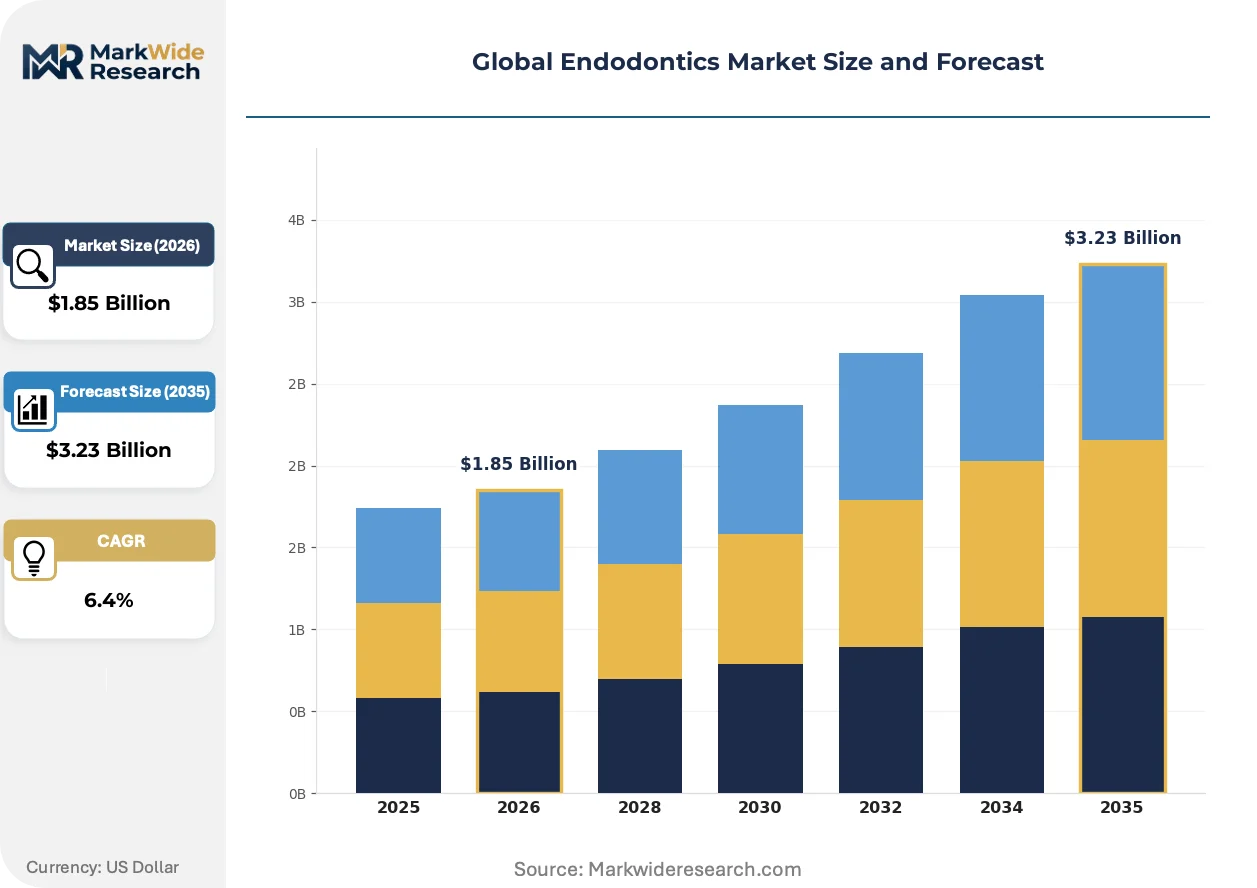
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endodontic Files, Apex Locators, Root Canal Sealers, Irrigation Systems, Obturation Systems, Ultrasound Devices Therapy Area: Pulpitis, Apical Periodontitis, Dental Trauma, Periapical Abscess, Root Resorption, Cracked Tooth End User: Specialty Dental Clinics, General Dentistry Practices, Academic & Research Institutes, Hospitals, Dental Laboratories Delivery Mode: Manual Instruments, Rotary Systems, Reciprocating Systems, Thermal Techniques |
| Companies Covered | Dentsply Sirona, Envista, Ultradent Products, Ivoclar Vivadent, Coltene Group, Septodont Holding, Brasseler USA, FKG Dentaire, Henry Schein, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Endodontics Market Shifts & Advancements
Digital measurement technologies and advanced metallurgy are compressing procedural timelines while regulatory harmonization efforts reshape competitive entry barriers across national frameworks.
Heat-treated nickel-titanium alloys with controlled austenite finish temperatures deliver superior cyclic fatigue resistance in curved canal morphologies. Specialty dental clinics in Germany and the United States are phasing in these next-generation rotary files at replacement cycle rates of eighteen to twenty-four months. This metallurgical advance is displacing conventional superelastic nitinol formulations in premium system configurations.
The EU MDR's post-market surveillance requirements mandate systematic clinical follow-up data for reusable endodontic devices. Manufacturers must now maintain vigilance systems that capture real-world performance metrics across distributed clinical settings. Rotary file suppliers with established European notified body relationships are accelerating compliance investments while smaller competitors defer market entry.
Consolidated buying groups representing multi-clinic dental networks are unbundling instrument procurement from legacy distributor arrangements. These entities now negotiate direct supply contracts with manufacturers for high-volume rotary and irrigation system categories. The United States exhibits the most pronounced channel compression, with regional dental service organizations capturing procurement authority from independent practitioners.
Global Endodontics Market Segmentation
Endodontic device procurement decisions hinge on regulatory classification tiers, reimbursement codes, and clinical workflow integration. Manufacturers must align product architecture with distinct approval pathways across FDA 510(k), EU MDR, and NMPA frameworks to capture addressable demand.
Product Type:
FDA 510(k) clearance complexity varies sharply across instrument categories, with nickel-titanium rotary files facing heightened biocompatility scrutiny while obturation systems navigate thermal safety thresholds.
- Endodontic Files:Nickel-titanium alloys with controlled austenite finish temperatures deliver superior cyclic fatigue resistance in curved canal morphologies. Specialty dental clinics in Germany and the United States are phasing in these heat-treated formulations at replacement cycle rates of eighteen to twenty-four months.
- Irrigation Systems:Adjunctive antimicrobial protocols combining sodium hypochlorite with novel delivery vehicles are opening margin expansion for chemistry specialists. Academic and research institutes in China are validating ultrasonic-activated irrigation against conventional needle delivery.
- Apex Locators:Digital impedance measurement devices operating at frequencies up to 400 kHz ensure working-length accuracy.
- Root Canal Sealers:Bioceramic formulations with dimensional stability are displacing resin-based alternatives in premium segments.
- Obturation Systems:Thermal compaction devices with precise temperature control enable three-dimensional canal filling.
- Ultrasound Devices:Piezoelectric units for post removal and canal negotiation command specialized maintenance contracts.
Endodontic files handle the majority of throughput; irrigation systems are expanding most quickly on share as clinicians adopt adjunctive antimicrobial protocols.
Therapy Area:
Reimbursement intensity correlates with procedural complexity, with apical periodontitis and periapical abscess commanding premium fee schedules while cracked tooth interventions face coverage variability.
- Apical Periodontitis:Inflammatory destruction of periapical tissues demands multi-visit protocols with advanced obturation techniques. Public hospital networks in São Paulo state are expanding capacity for complex periapical surgery.
- Pulpitis:Reversible and irreversible pulp inflammation represents the highest-volume indication driving rotary system utilization. General dentistry practices in India are upgrading from manual to engine-driven instrumentation for routine pulpitis cases.
- Dental Trauma:Time-sensitive interventions for luxation and avulsion injuries require specialized immobilization devices.
- Periapical Abscess:Purulent infections necessitate drainage protocols combined with systemic antibiotic coordination.
- Root Resorption:Internal and external resorptive defects demand microscopic surgical approaches.
- Cracked Tooth:Incomplete fracture diagnosis relies on transillumination and bite-testing adjuncts.
Pulpitis generates the highest procedure count; apical periodontitis commands the steepest expansion trajectory as aging populations retain natural dentition longer.
End User:
Procurement authority is concentrating in consolidated buying groups, with multi-clinic dental networks in the United States unbundling instrument procurement from legacy distributor arrangements.
- Specialty Dental Clinics:Precision-engineered rotary systems reduce procedural chair time while meeting EU MDR biocompatibility mandates. These entities anchor demand for premium nickel-titanium formulations across Germany, the United States, and China.
- Academic & Research Institutes:Single-file reciprocating systems are undergoing systematic clinical validation for fatigue resistance and fracture risk reduction. Provincial health authorities in China are equipping teaching hospitals with advanced endodontic suites.
- General Dentistry Practices:Cost-optimized manual instrument portfolios serve high-volume routine cases.
- Hospitals:Emergency departments require rapid-access kits for dental trauma management.
- Dental Laboratories:Custom-fabricated post-and-core systems support complex restorative reconstruction.
Specialty dental clinics dominate absolute spend; academic and research institutes are gaining procurement influence fastest through validation partnerships with technology developers.
Delivery Mode:
Capital expenditure thresholds separate automated system adopters from manual instrument users, with reciprocating technologies commanding intermediate positioning on total cost of ownership curves.
- Rotary Systems:Continuous rotation nickel-titanium files with taper designs of 0.04–0.12 deliver instrument longevity and reduced chair time. Dentsply Sirona leverages integrated CAD/CAM workflows to dominate high-value segments in the United States and Germany.
- Reciprocating Systems:Alternating motion reduces cyclic fatigue and enables single-file protocols. Envista sustains R&D intensity across nickel-titanium alloy formulations to capture this expanding category.
- Manual Instruments:Stainless steel hand files retain volume in cost-constrained municipal networks.
- Thermal Techniques:Warm vertical compaction and continuous wave obturation methods require specialized heating devices.
Rotary systems capture the largest installed base; reciprocating systems are climbing the fastest on new purchase decisions as clinical validation accumulates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States commands premium multiples over Brazil, where public procurement programs compress margins for instrument suppliers. This asymmetry shapes capital allocation toward regulatory-heavy markets while volume manufacturers target cost-optimized municipal networks.
United States
Consolidated dental service organizations now control procurement for thousands of practices, negotiating direct supply contracts that bypass legacy distributors. FDA 510(k) clearance pathways for nickel-titanium rotary files impose biocompatibility documentation burdens that favor established suppliers with regulatory infrastructure. The Greater Boston corridor hosts specialized metallurgical research facilities advancing heat-treated alloy formulations.
Germany
Specialty dental clinics in Bavaria and Baden-Württemberg are replacing conventional superelastic nitinol files at eighteen-to-twenty-four-month cycles, driving demand for next-generation rotary systems. EU MDR post-market surveillance mandates systematic clinical follow-up data collection, extending compliance timelines for reusable device portfolios. The Stuttgart industrial cluster concentrates precision instrument manufacturing for export markets.
China
Provincial health authorities in Jiangsu and Guangdong are equipping teaching hospitals with advanced endodontic suites as practitioner training programs expand. NMPA registration requirements for Class II medical devices are harmonizing with international standards, accelerating market entry for multinational suppliers. The Yangtze River Delta anchors domestic manufacturing capacity for precision surgical instruments under PLI scheme incentives.
Brazil
Public oral health programs in São Paulo and Minas Gerais states present volume procurement channels for cost-optimized manual instrument portfolios. ANVISA medical device registration processes are streamlining for low-risk instrument categories, reducing administrative barriers for regional suppliers. The Campinas technology corridor is developing assembly operations to serve municipal network demand.
India
General dentistry practices in Maharashtra and Gujarat are upgrading from manual to engine-driven instrumentation for routine pulpitis cases. CDSCO medical device rules are implementing risk-based classification aligned with global harmonization initiatives. The Gujarat pharmaceutical and medical device manufacturing zone is attracting precision instrument assembly under production-linked incentive frameworks.
Global Endodontics Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated CAD/CAM workflow specialists commanding premium positioning while regional fabricators capture municipal procurement volumes. The vendor base organizes into three strategic tiers: multinational platform providers with regulatory infrastructure, mid-cap alloy specialists with metallurgical differentiation, and regional manual instrument suppliers with price-competitive portfolios. Dominant competitive moves include backward integration into nickel-titanium wire production and strategic partnerships with academic institutes for clinical validation.
Within the multinational platform tier, Dentsply Sirona and Envista occupy positions defined by integrated digital workflows and sustained R&D intensity across alloy formulations. Ultradent Products exemplifies the chemistry-specialist archetype, anchoring defensible positioning in irrigant delivery segments. These three entities collectively represent the competitive frontier where regulatory compliance capability and metallurgical innovation converge.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Envista |
| Ultradent Products |
| Ivoclar Vivadent |
| Coltene Group |
| Septodont Holding |
| Brasseler USA |
| FKG Dentaire |
| Henry Schein |
| Others |
Supply & Pricing Matrix
EU MDR biocompatibility certification gates both supplier qualification and price tier separation, forcing manufacturers to absorb validation costs that stratify offerings across premium heat-treated alloys, standard superelastic formulations, and economy-grade stainless steel alternatives. This regulatory threshold simultaneously constrains who can supply nickel-titanium instruments and how pricing power distributes across buyer segments.
Pricing Analysis
Configured-to-order pricing for heat-treated nickel-titanium rotary files commands a substantial premium over standard catalog offerings. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 3630-1 certification grade, volume scale, and after-sales service bundling. Cost compression in the economy tier is intensifying because Brazilian and Indian municipal procurement programs prioritize landed cost over instrument longevity. General dentistry practices in India exhibit the highest price sensitivity, while specialty dental clinics in Germany and the United States prioritize fatigue resistance over unit cost.
Supply Chain Analysis
Inventory lead times for premium-grade nitinol wire stretch to sixteen weeks during metallurgical facility maintenance cycles. Production gravity centers on Germany, the United States, and China, with the Stuttgart industrial cluster and Yangtze River Delta anchoring precision instrument manufacturing. Raw material dependencies include nickel-titanium alloy feedstock, precision grinding abrasives, and biocompatible sterilization packaging. Single-source vulnerability concentrates in specialized nitinol wire suppliers, exposing instrument manufacturers to input volatility. Distribution runs through consolidated dental service organizations in the United States and regional distributor networks in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CAD/CAM workflow interoperability is redefining competitive moats in endodontics, as integrated digital ecosystems displace standalone instrument sales. Platform economics now reward suppliers who control data exchange standards between cone-beam computed tomography, apex locators, and practice management systems.
For Market Incumbents: Fortify backward integration into nickel-titanium wire production to secure supply continuity amid metallurgical facility concentration. Deepen regulatory infrastructure investments for EU MDR post-market surveillance compliance, as clinical evidence requirements extend timelines for mid-tier competitors. Prioritize R&D intensity across heat-treated alloy formulations to maintain performance differentiation against emerging metallurgical specialists.
For New Entrants and Emerging Players: After-sales service gaps in ultrasonic device maintenance contracts present white-space opportunities for regional service specialists. Brazil's underserved municipal networks in São Paulo and Minas Gerais states offer the most penetrable geography for cost-optimized manual instrument portfolios. Pursue direct procurement relationships with public oral health programs, bypassing legacy distributor markups through volume contract structures.
For Investors and Strategic Acquirers: EU MDR implementation reshapes the acquisition landscape by elevating regulatory infrastructure above product innovation as a valuation driver. Five-to-ten-year viability hinges on capturing platform economics through integrated digital workflow control rather than standalone instrument market share. Target acquisition archetypes include mid-cap alloy specialists with established notified body relationships and captive nitinol wire supply. The signal to monitor is consolidation velocity among dental service organizations, as procurement authority concentration accelerates channel compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitinol Wire Production | Captive supply of premium-grade alloy feedstock insulates against metallurgical facility concentration risk. |
| EU MDR Notified Body Partnership Expansion | Accelerated clinical evidence pathways compress regulatory timelines for reusable device portfolios. |
| CAD/CAM Workflow Interoperability Investment | Platform control over data exchange standards locks in specialty dental clinic procurement decisions. |
| Single-File Reciprocating System Validation | Academic institute partnerships generate clinical outcome data for fatigue resistance claims. |
| Dental Service Organization Direct Contracting | Bypassing legacy distributors captures margin compression from consolidated buying group authority. |
Research Methodology
Desk research of FDA 510(k) clearance databases, EU MDR notified body guidance documents, and ISO 3630-1 technical standards preceded structured interviews with endodontic instrument product managers, biomedical engineers at specialty dental clinics, GPO contracts managers, and metallurgical research directors. Secondary validation drew from customs trade data, SEC 10-K filings of listed dental device manufacturers, and hospital procurement database extracts. Bottom-up demand modeling triangulated against top-down market sizing across instrument replacement cycles and clinic equipment upgrade frequencies.
Variance decomposition across product type, delivery mode, therapy area, and end-user segment isolates growth contribution by category throughout the forecast period. The analytical framework models adoption curves for reciprocating motion technologies, heat-treated alloy replacement cycles, and irrigation system adjunctive protocol penetration. CAGRs derive from instrument longevity improvements, chair-time reduction economics, and reimbursement code evolution across national health frameworks. Forecast inputs include provincial health authority capital expenditure plans in China and dental service organization consolidation trajectories in the United States.
Forecasts assume regulatory continuity in FDA 510(k) clearance pathways and EU MDR post-market surveillance regimes; material policy shifts in biocompatibility testing mandates or reciprocating system reimbursement decisions would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Global Professional Teeth Whitening and Power Toothbrushes Market
Dental Devices
Dental Aligners Market
Dental Devices
US Orthodontics Market
Dental Devices
Netherlands Dental Devices Market
Dental Devices
Titanium Dental Implants Market
Dental Devices
Plaque Disclosing Aids Market
Dental Devices
Dental Dam Market
Dental Devices
North America Dental Implants and Prosthetics Market
Dental Devices
Dental Laboratory Handpiece Market
Dental Devices
United States Dental Implants Market
Dental Devices
Asia Pacific Dental Market
Dental Devices
Root Canal Market
Dental Devices
Electric Dental Handpieces Market
Dental Devices
North America Dental Aligners Market
Dental Devices
Subperiosteal Dental Implants Market
Dental Devices
Dental Implants and Abutment Systems Market