
 Skin Replacement Market | 2026-2036
Skin Replacement Market Size, Share, and Industry Trends Forecast 2026-2036
Skin Replacement Market Outlook
Hospital procurement groups are bifurcating from traditional autograft sourcing toward engineered alternatives. Integra LifeSciences Corporation leverages its Matriderm platform to anchor burn center contracts across North America. Organogenesis Inc. specializes in living cell therapies, sustaining manufacturing scale that competitors struggle to replicate. Smith+Nephew competes through geographic dominance in European trauma networks, where its distribution controls shelf space in major wound care centers.
Skin replacement encompasses biologically active or acellular constructs designed to restore epidermal and dermal integrity, typically incorporating collagen matrices seeded with keratinocytes or fibroblasts and achieving 70-90% engraftment rates in partial-thickness wounds. These products serve primarily to accelerate wound closure, reduce scarring, and eliminate donor site morbidity in patients with extensive thermal injuries or chronic ulcers. Synthetic grafts occupy the fastest-growing product tier as polyurethane and silicone bilayer designs improve moisture vapor transmission rates, while allografts retain the largest revenue pool due to established reimbursement in surgical wound care. Bioprinting leads technology investment intensity, though cell culturing dominates current commercial throughput because regulatory pathways for autologous cell expansion remain more predictable than 3D bioprinted vascularization protocols.
The FDA enforces 21 CFR Part 1271 human cell and tissue regulations alongside premarket approval requirements for combination skin substitute devices, creating compliance barriers that filter smaller entrants. The EMA's Advanced Therapy Medicinal Products framework and Japan's PMDA regenerative medicine guidelines add parallel approval complexity for companies seeking multi-region presence. Stakeholders must monitor evolving CMS coverage determinations for bioengineered skin substitutes, as reimbursement category shifts will determine which manufacturing platforms achieve sustainable commercial scale.
Market Dynamics
Hospital burn centers are consolidating procurement authority under centralized supply chains, forcing engineered skin substitute manufacturers to restructure contract terms around engraftment performance guarantees rather than unit pricing.
Growth Catalysts
- CMS coverage expansion:Medicare reimbursement codes for bioengineered skin substitutes now encompass outpatient wound care settings, extending addressable patient populations beyond inpatient burn centers.
- Chronic wound prevalence:Diabetic foot ulcer incidence in the United States creates sustained demand for dermal regeneration products that autografts cannot supply at required volumes.
- Bioprinting maturation:Layered deposition of keratinocyte-laden hydrogels is approaching clinical-grade reproducibility, enabling patient-specific graft geometry without donor site harvesting.
Market Restraints
- Collagen raw material concentration:Bovine and porcine dermal sourcing depends on concentrated North American and European abattoir networks, exposing manufacturers to livestock disease outbreak disruptions.
- FDA 21 CFR Part 1271 compliance burden:Human cell and tissue regulations impose facility validation requirements that consume 18-24 months for new manufacturing site approvals.
- Autograft persistence:Split-thickness autografts retain preference in full-thickness burn cases where immunologic rejection risks outweigh engineered substitute convenience.
Strategic Opportunities
- Japan PMDA regenerative medicine fast-track:Conditional approval pathways for cell-based therapies enable earlier revenue generation from living skin substitutes than FDA PMA timelines permit.
- Outpatient wound center channel:Standalone chronic wound clinics bypass hospital purchasing committee gatekeeping, offering direct contracting relationships with substitute manufacturers.
- Silicone-polyurethane hybrid platforms:Synthetic bilayer designs incorporating antimicrobial silver ion release address infection-prone diabetic ulcers without allograft immunogenicity concerns.
Industry Challenges
- Cell culture technician scarcity:GMP-compliant aseptic processing expertise for autologous keratinocyte expansion remains concentrated among legacy tissue engineering specialists, constraining manufacturing scale-up.
- Engraftment variability documentation:Payer reimbursement increasingly requires real-world evidence portfolios spanning 12-month wound closure rates, demanding post-market surveillance infrastructure that mid-tier manufacturers lack capital to build.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skin Replacement Market |
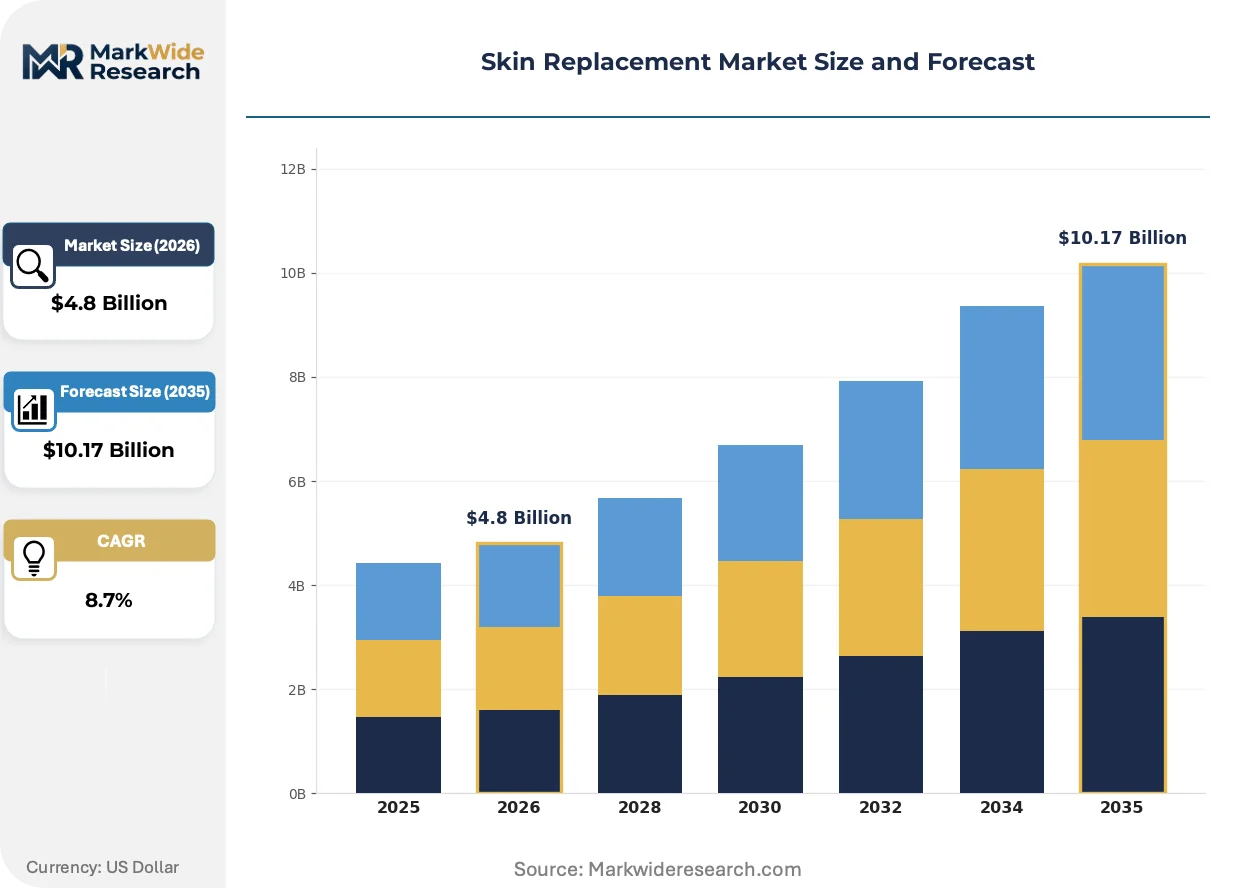
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Allografts, Xenografts, Synthetic Grafts, Autografts Application: Burn Treatment, Surgical Wound Care, Chronic Wound Management, Cosmetology End User: Hospitals, Clinics, Specialty Centers, Home Care Technology: Bioprinting, Regenerative Medicine, Cell Culturing, Tissue Engineering |
| Companies Covered | Integra LifeSciences Corporation, Organogenesis Inc., Smith+Nephew, Avita Medical, MiMedx Group, PolyNovo, Stratatech Corporation, 3M, Convatec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skin Replacement Market Strategic Shifts
Manufacturing platforms are diverging between centralized bioreactor production and point-of-care cell isolation systems, with each pathway demanding incompatible regulatory and supply chain architectures.
Decellularized extracellular matrix scaffolds derived from porcine intestinal submucosa are fragmenting the allograft segment by offering acellular alternatives that bypass human donor tissue screening bottlenecks. Burn centers in Texas and Arizona have adopted these matrices for partial-thickness coverage at volumes exceeding cadaveric allograft utilization. The shift is compressing revenue per procedure while expanding total addressable procedures by eliminating tissue bank distribution constraints.
EMA's Advanced Therapy Medicinal Products framework is recategorizing living cell therapies as medicinal products rather than medical devices, triggering manufacturing facility upgrades that favor Organogenesis-scale producers over emerging competitors. The reclassification mandates batch release testing protocols previously unnecessary under medical device directives. German and French wound care centers are consolidating supplier relationships to vendors with established ATMP compliance infrastructure.
Academic medical centers are unbundling skin substitute procurement from bundled payment contracts, creating standalone product evaluation committees that benchmark engraftment rates against total cost of care. The University of Washington Medical Center and Massachusetts General Hospital have established independent value analysis frameworks that override traditional GPO contract terms. This behavioral shift concentrates purchasing influence among institutions with sufficient case volume to generate statistically meaningful outcome comparisons.
Skin Replacement Market Segmentation
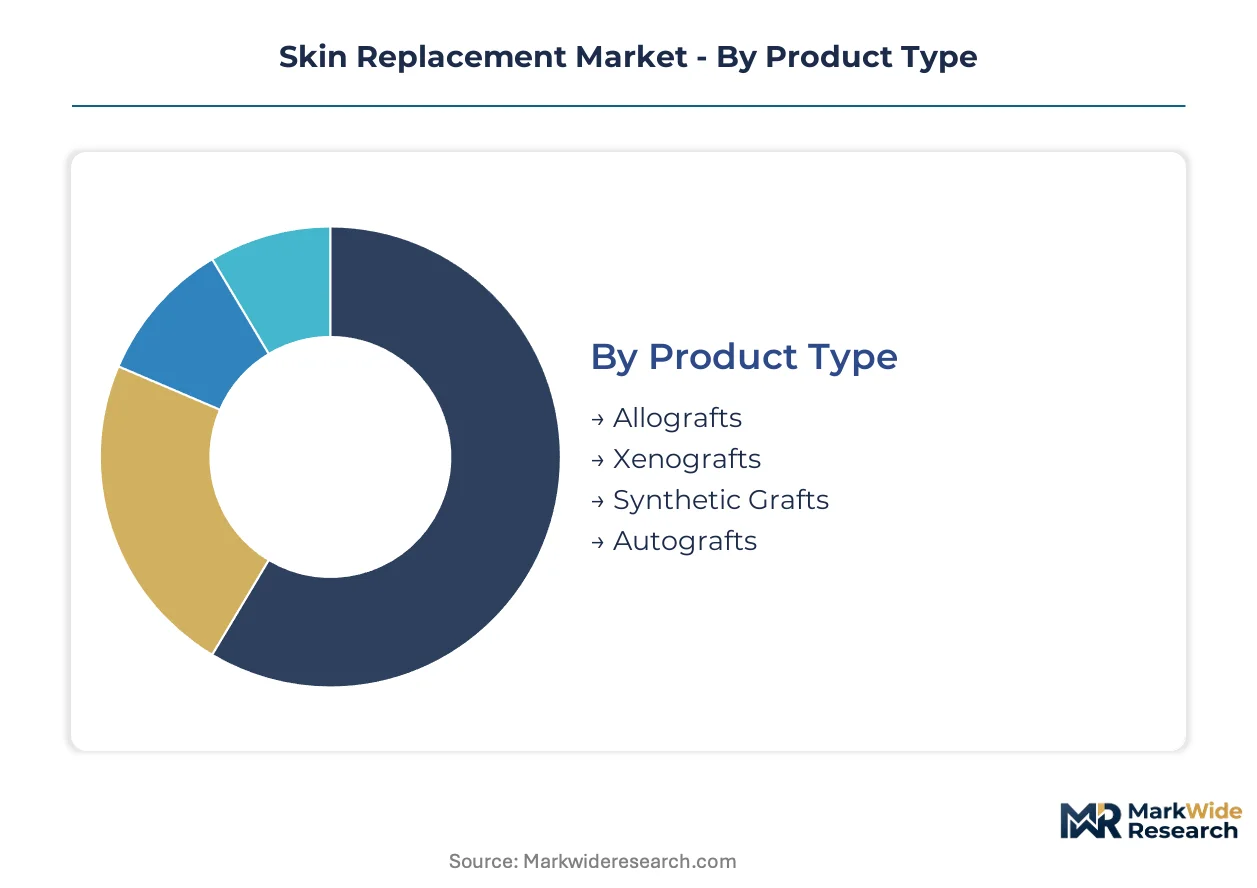
Product architecture in skin replacement determines reimbursement pathways, manufacturing scale requirements, and competitive moats. Segmentation clarity enables manufacturers to align R&D spend with addressable procedure volumes and payer coverage categories.
Product Type:
Synthetic grafts face the most intense substitution pressure from decellularized matrices that replicate barrier function without polymer degradation risks.
- Allografts:Cadaveric human skin processed through cryopreservation or lyophilization retains native extracellular matrix architecture. Burn centers in Texas and Arizona source these from concentrated tissue bank networks, though supply constraints periodically force procedure delays.
- Synthetic Grafts:Polyurethane-silicone bilayer constructs with controlled moisture vapor transmission rates. Demand concentrates in outpatient diabetic ulcer clinics where immunogenicity concerns disqualify biological alternatives and silver-ion doping addresses infection risk.
- Xenografts:Porcine or bovine dermal scaffolds after antigen removal.
- Autografts:Split-thickness harvests from patient donor sites.
Allografts anchor the volume base while synthetic grafts gain share at the steepest rate.
Application:
Cost tier differentiation separates acute surgical applications reimbursed under DRG bundles from chronic wound episodes paid per procedure.
- Burn Treatment:Full-thickness thermal injuries requiring immediate temporary or permanent coverage. Academic medical centers with level-1 trauma designation drive procurement volume for engineered substitutes that reduce donor site morbidity in extensive surface area cases.
- Chronic Wound Management:Diabetic foot ulcers and venous stasis wounds with failure-to-heal profiles. Medicare Advantage plans in Florida and Arizona now mandate bioengineered substitute documentation before authorizing amputation alternatives.
- Surgical Wound Care:Reconstructive procedures and excisional closures.
- Cosmetology:Aesthetic resurfacing and scar revision applications.
Burn treatment commands the highest unit economics while chronic wound management expands addressable procedure counts most aggressively.
End User:
Customer type determines contract structure complexity, with hospital purchasing committees demanding performance guarantees that clinics cannot enforce.
- Hospitals:Integrated delivery networks with centralized supply chain authority. The University of Washington Medical Center and Massachusetts General Hospital have established independent value analysis frameworks that benchmark engraftment rates against total cost of care, overriding traditional GPO terms.
- Specialty Centers:Dedicated burn institutes and wound care facilities. These bypass hospital purchasing committee gatekeeping, enabling direct manufacturer relationships and faster product evaluation cycles for novel constructs.
- Clinics:Outpatient settings with simpler procurement authority.
- Home Care:Emerging channel for advanced dressing maintenance.
Hospitals concentrate absolute spending power while specialty centers adopt innovative platforms earliest.
Technology:
Manufacturing maturity stratifies sharply between commercialized cell expansion and preclinical bioprinting platforms.
- Cell Culturing:Autologous or allogeneic keratinocyte and fibroblast expansion under GMP conditions. Organogenesis sustains manufacturing scale that competitors struggle to replicate, with FDA premarket notification pathways for human cells and tissues providing more predictable timelines than device PMA routes.
- Bioprinting:Layered deposition of cell-laden hydrogels for patient-specific geometry. German and French wound care centers are consolidating supplier relationships to vendors with established EMA ATMP compliance infrastructure as this technology approaches clinical-grade reproducibility.
- Regenerative Medicine:Living cell therapies with biological activity.
- Tissue Engineering:Scaffold-based construct development.
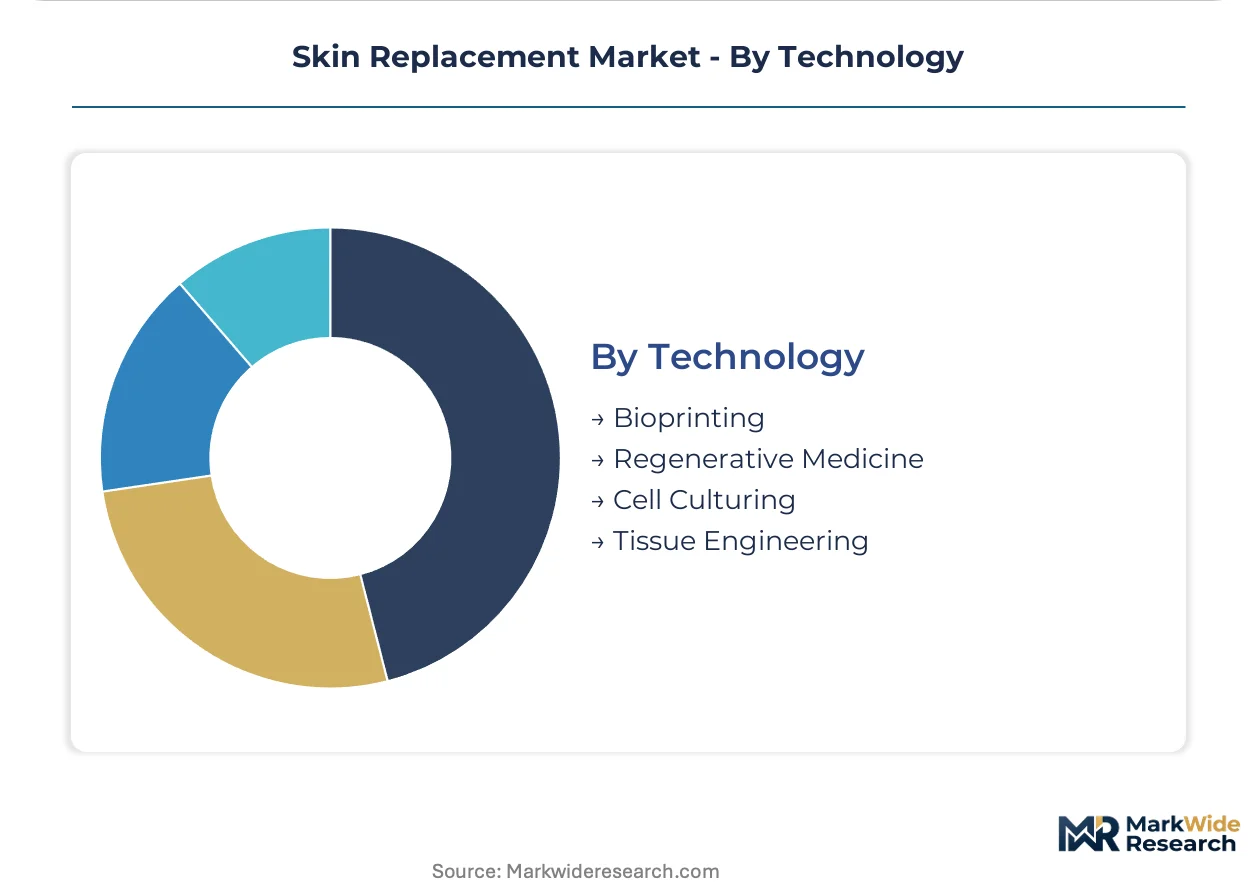
Cell culturing dominates current commercial throughput while bioprinting attracts the steepest investment intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold chain infrastructure underwrites European distribution efficiency for temperature-sensitive biologics, while the I-35 corridor's logistics density anchors North American supply chain velocity for engineered tissue products.
United States
Level-1 trauma centers in Texas and Arizona drive procurement volume for engineered skin substitutes in extensive burn cases. The FDA's 21 CFR Part 1271 framework shapes commercialization timelines through facility validation requirements that consume 18-24 months for new manufacturing approvals. Boston's academic medical cluster, including Massachusetts General Hospital, has established independent value analysis frameworks that benchmark engraftment rates against total cost of care.
Germany
Specialized burn institutes in North Rhine-Westphalia and Bavaria consolidate supplier relationships around vendors with established EMA ATMP compliance infrastructure. The EMA's Advanced Therapy Medicinal Products framework recategorizes living cell therapies as medicinal products rather than medical devices, triggering mandatory batch release testing protocols. Frankfurt's wound care centers are adopting decellularized extracellular matrix scaffolds at volumes exceeding cadaveric allograft utilization.
Japan
Academic medical centers in Tokyo and Osaka drive demand for patient-specific graft geometries through bioprinting investment. The PMDA's regenerative medicine fast-track pathway enables conditional approval for cell-based therapies, permitting earlier revenue generation than FDA PMA timelines allow. Nagoya's tissue engineering cluster concentrates manufacturing expertise for autologous keratinocyte expansion under GMP conditions.
United Kingdom
London's integrated delivery networks centralize procurement authority under supply chains demanding performance guarantees rather than unit pricing. The MHRA's alignment with EMA ATMP frameworks post-Brexit maintains regulatory continuity for advanced therapy medicinal products. Manchester's specialty wound clinics bypass hospital purchasing committee gatekeeping, enabling direct manufacturer relationships for novel constructs.
Australia
Outpatient wound centers in New South Wales and Victoria expand addressable patient populations beyond inpatient burn centers through Medicare reimbursement expansion. The TGA's biologicals framework imposes parallel approval complexity for multi-region presence seekers. Melbourne's medical device cluster concentrates polyurethane-silicone bilayer manufacturing for diabetic ulcer applications where immunogenicity concerns disqualify biological alternatives.
Skin Replacement Market Competitive Environment
Concentration sits with diversified medical technology conglomerates and specialized regenerative medicine firms. The vendor base stratifies sharply between legacy wound care multinationals with distribution scale and emerging cell therapy specialists with manufacturing depth. Two archetypes dominate: platform technology licensors with scaffold intellectual property portfolios, and vertically integrated cell culture operators with GMP-compliant bioreactor capacity. Competitive moves center on geographic expansion into Japan's PMDA fast-track jurisdiction and backward integration into collagen raw material sourcing.
Among North American specialists, Integra LifeSciences Corporation and Organogenesis Inc. exemplify contrasting scale strategies. Integra occupies a position within the diversified medical technology tier, its corporate structure suggesting platform technology breadth. Organogenesis represents the cell therapy manufacturing archetype, its name indicating biological process specialization. Smith+Nephew anchors the European geographic dominance tier, its Anglo-Swiss corporate heritage reflecting transatlantic distribution architecture. These three entities collectively illustrate the market's segmentation between scaffold-based and living cell therapeutic approaches.
| Leading Market Players |
|---|
| Integra LifeSciences Corporation |
| Organogenesis Inc. |
| Smith+Nephew |
| Avita Medical |
| MiMedx Group |
| PolyNovo |
| Stratatech Corporation |
| 3M |
| Convatec |
| Others |
Value Chain & Pricing Dynamics
Decellularized porcine intestinal submucosa displacing cadaveric allografts is redistributing manufacturing capacity toward North American abattoir networks while compressing per-procedure revenue and eliminating tissue bank distribution markups.
Pricing Analysis
Volume-discount tiering separates burn center GPO contracts from specialty clinic spot purchases, with academic medical centers extracting steepest concessions through engraftment performance guarantees. Price differentiation hinges on FDA 21 CFR Part 1271 compliance certification and autologous cell expansion capability. Cost compression in the allograft segment intensifies as decellularized matrices bypass human donor screening overhead. Outpatient wound clinics exhibit highest price sensitivity, while level-1 trauma centers prioritize clinical outcomes over unit economics.
Supply Chain Analysis
Inbound logistics costs from Rotterdam pharmaceutical cold chain congestion ripple through temperature-sensitive biologics distribution, elevating landed costs for European wound care centers. Raw material sourcing draws from concentrated North American and European abattoir networks for bovine and porcine collagen, with German and Dutch pharmaceutical hubs anchoring secondary processing. Single-source vulnerability concentrates in GMP-certified cell culture technician pools. Distribution runs through hospital integrated delivery networks and direct specialty center channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement unbundling from bundled payment contracts fragments purchasing authority, creating entry niches for manufacturers with targeted outcome documentation.
For Market Incumbents: Fortify GPO contract positions by embedding engraftment performance guarantees that emerging competitors cannot underwrite. Deepen backward integration into collagen raw material sourcing to insulate margins from livestock disease outbreak disruptions. Expand manufacturing footprint into Japan's PMDA fast-track jurisdiction to accelerate revenue generation timelines.
For New Entrants and Emerging Players: Lead with outpatient wound center direct contracting, bypassing hospital purchasing committee gatekeeping that incumbents dominate. Target silicone-polyurethane hybrid platforms for diabetic ulcer applications where immunogenicity concerns disqualify biological alternatives. Emphasize antimicrobial silver ion release as differentiated value proposition in infection-prone chronic wounds.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed cell therapy specialists possessing GMP-compliant bioreactor capacity but lacking ATMP compliance infrastructure. Long-term viability in this market requires sustained post-market surveillance investment for 12-month wound closure documentation. Monitor CMS coverage determination shifts as inflection indicator for platform scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA ATMP Compliance Investment | Batch release testing protocols recategorize living cell therapies as medicinal products across German and French wound care centers. |
| Hospital System Partnership | Independent value analysis frameworks at Massachusetts General Hospital and University of Washington Medical Center override traditional GPO terms. |
| Reimbursement Strategy | Medicare Advantage plans in Florida and Arizona mandate bioengineered substitute documentation before authorizing amputation alternatives. |
| Manufacturing Scale-Up | GMP-compliant aseptic processing expertise for autologous keratinocyte expansion remains concentrated among legacy tissue engineering specialists. |
| Geographic Expansion | PMDA regenerative medicine fast-track enables conditional approval timelines shorter than FDA PMA routes for Tokyo and Osaka academic centers. |
Study Parameters
Operator-level perspectives from burn center procurement directors, GPO contracts managers, biomedical engineers, and CMS reimbursement specialists anchored the qualitative base. Primary interview data combined with secondary validation from FDA 510(k) filings, EMA ATMP submissions, hospital procurement databases, and CMS Medicare coverage determinations. Bottom-up procedure volume estimates triangulated against top-down manufacturer capacity disclosures.
Sensitivity analysis stress-tested projections across product type, application, end user, and technology segmentation dimensions over the projection horizon. CAGRs derived from logarithmic trend fitting of historical revenue trajectories adjusted for regulatory approval lag effects. Modeling incorporated bioprinting maturation curves and chronic wound epidemiology forecasts as industry-specific inputs.
Forecasts assume regulatory continuity in FDA 21 CFR Part 1271, EMA ATMP, and PMDA regenerative medicine frameworks; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
India Skin Care Products Market
Skincare
Biocellulose Mask Market
Skincare
Global Skin Rejuvenation Market
Skincare
Asia Pacific Traditional Chinese Herbal Medicine for Face-Care Market
Skincare
Tinted Sunscreen Market
Skincare
Facial Skincare Market
Skincare
Skin Bioactive Market
Skincare
Germany Skincare Product Market
Skincare
Exfoliators and Scrubs Market
Skincare
Global Cosmetic Skin Care Market
Skincare
Cosmeceuticals Market
Skincare
Vitamin C Serum Market
Skincare
DNA-Based Skin Care Products Market
Skincare
Body Scrub Market
Skincare
South Korea Anti-Acne Dermal Patch Market
Skincare
Europe Functional Cosmetics Market